
 Asia-Pacific Seed Coating Materials Market | 2026-2036
Asia-Pacific Seed Coating Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Seed Coating Materials Market Outlook
Vegetable seed demand is decoupling from commodity grain coating volumes across the Asia-Pacific region. Bayer Crop Science dominates vegetable seed treatment formulations through its R&D intensity in biological coatings. BASF SE anchors polymer coating supply for major rice-producing territories with its manufacturing scale in the region. Croda International Plc differentiates through lipid-based additive technologies that improve seed germination under saline conditions.
Asia-Pacific seed coating materials encompass polymer films, colorants, binders, and active ingredients applied to seed surfaces to enhance planting precision, pest resistance, and germination rates. Polymer coatings typically range from 1-5% of total seed weight and function as controlled-release matrices for pesticides and micronutrients. Polymer coatings command the largest value share due to their essential role in active ingredient delivery systems. Colorants represent the fastest-growing product category as traceability mandates expand across export-oriented agricultural economies. Agricultural seeds absorb the majority of coating material volumes, though vegetable seeds generate higher per-unit margins due to specialized formulation requirements.
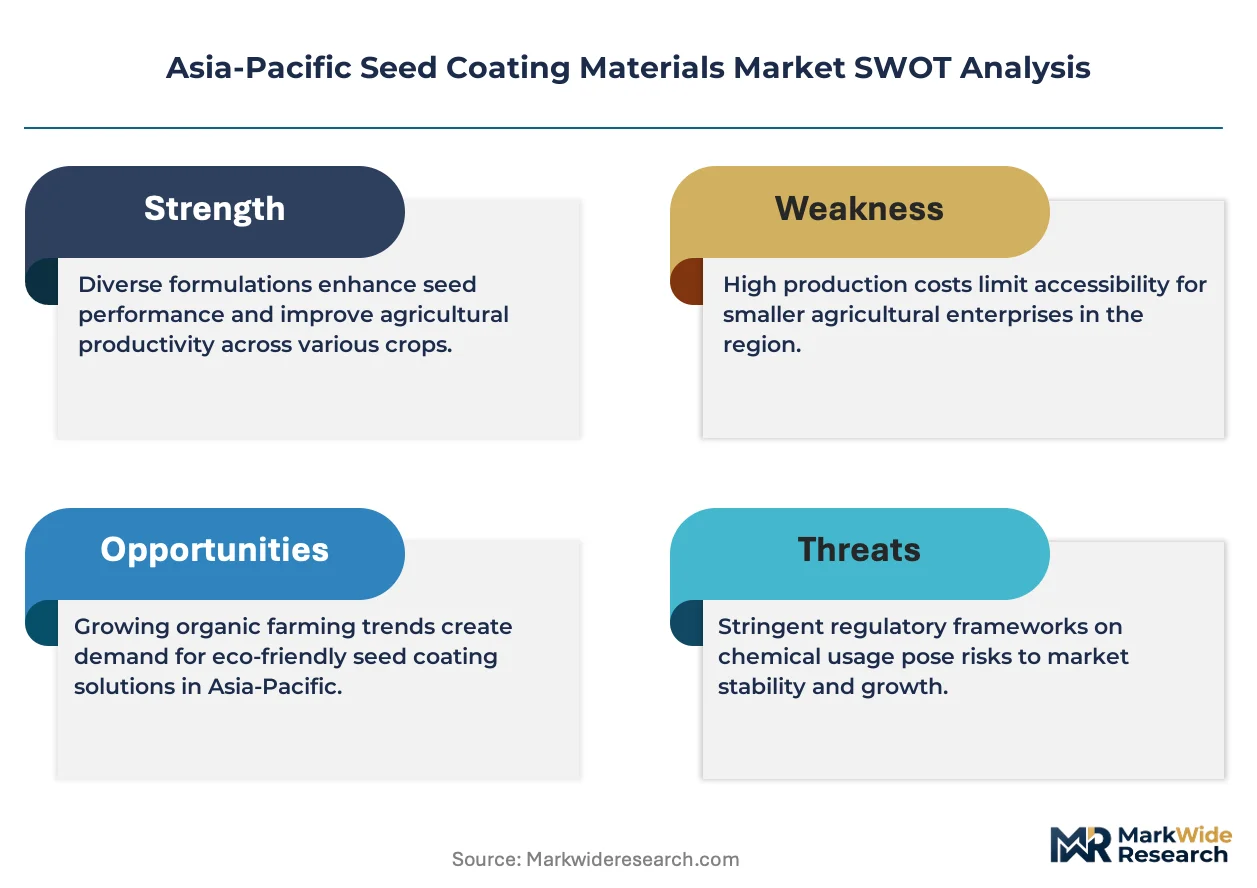
Australia's APVMA, India's CIBRC, and China's MEE collectively govern seed treatment chemical registrations and environmental release standards across the region. These regulators shape market access through residue limit harmonization and coating ingredient disclosure protocols. Stakeholders must monitor evolving biopesticide approval pathways as sustainability criteria tighten in major export corridors.
Market Dynamics
India's PLI scheme for agrochemicals is restructuring polymer coating supply chains by incentivizing domestic production capacity expansion. Rice farmers across Southeast Asia are abandoning untreated seed practices in favor of precision-coated varieties that enable mechanized planting.
Growth Catalysts
- Biological coating formulations:Rice producers in Vietnam and Thailand are adopting microbial seed treatments to reduce synthetic pesticide dependency. These formulations improve germination rates in flooded paddy conditions.
- Traceability mandates:Australia's APVMA residue limit harmonization is accelerating colorant adoption for export wheat certification. Coated seeds enable lot-level tracking through the supply chain.
- Drought-resistant treatments:Australia's wheat belt is driving premium demand for polymer coatings with controlled-release micronutrients. These formulations buffer crop stress during extended dry spells.
Market Restraints
- Petrochemical input volatility:Polymer coatings depend on acrylic and polyurethane feedstocks subject to crude oil price swings. Margin compression hits smaller formulators hardest.
- Registration timeline friction:China's MEE environmental release standards extend approval cycles for novel active ingredients. Commercialization delays stretch 18-36 months for biological entrants.
- Untreated seed substitution:Subsistence farmers in Indonesia and the Philippines continue planting bare seeds for cost reasons. Price sensitivity limits coating penetration in smallholder segments.
Strategic Opportunities
- Vegetable seed specialization:Protected cultivation expansion in South Korea and Japan creates demand for high-value coating formulations. Per-unit margins exceed commodity grain applications by multiples.
- Biopesticide pathway acceleration:India's CIBRC is streamlining microbial product registrations under sustainability directives. Domestic innovators gain first-mover positioning.
- Direct-to-farm distribution:E-commerce platforms are bypassing traditional agrochemical dealer networks. Coating manufacturers can capture margin previously lost to intermediaries.
Industry Challenges
- Formulation chemistry expertise scarcity:Polymer-active ingredient compatibility requires specialized knowledge concentrated among veteran R&D teams. Talent migration to biotechnology sectors intensifies recruitment pressure.
- Legacy equipment retrofit costs:Existing seed treatment facilities require capital investment to handle biological coating viscosity profiles. Smaller cooperatives defer upgrades amid uncertain payback periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Seed Coating Materials Market |
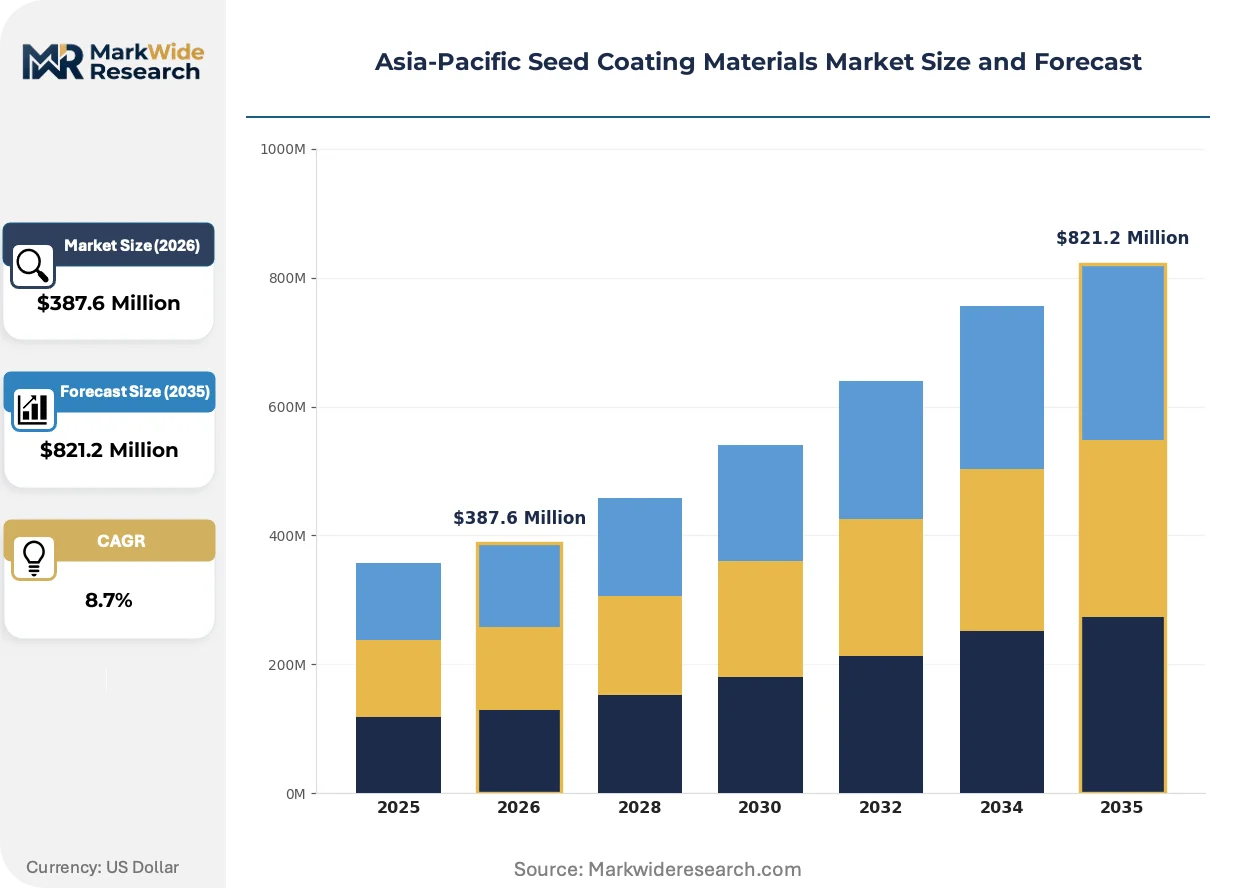
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $821.2 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polymer Coatings, Colorants, Additives, Microencapsulation Application: Agricultural Seeds, Vegetable Seeds, Flower Seeds, Turf Seeds End User: Farmers, Agricultural Cooperatives, Seed Manufacturers, Garden Centers Distribution Channel: Direct Sales, Online Retail, Wholesalers, Distributors |
| Companies Covered | BASF SE, Bayer Crop Science, Croda International Plc, Clariant, Solvay, Incotec Group BV, Brettyoung, DSM, Chromatech Incorporated, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Seed Coating Materials Market Strategic Shifts
Active ingredient delivery systems are converging with digital agriculture platforms. Coating formulations now embed tracer compounds compatible with drone-based emergence monitoring.
Biostimulant-infused polymer matrices are integrating trace mineral complexes and seaweed-derived compounds into rice seed coatings. Vietnamese commercial farms are piloting these formulations at scale. The technology is integrating precision agriculture data layers with germination performance metrics.
China's MEE dual carbon goals are tightening volatile organic compound limits on solvent-based coating processes. Manufacturers are reformulating with waterborne polymer systems to maintain registration compliance. Rice coating facilities in Jiangsu and Hunan provinces face the most acute compliance deadlines.
Consolidated procurement by large-scale farming cooperatives is compressing supplier negotiation cycles. Australian wheat belt aggregators now contract coating services directly, bypassing regional seed distributors. This pattern is most pronounced in New South Wales and Victoria where farm sizes exceed ten thousand hectares.
Asia-Pacific Seed Coating Materials Market Segmentation
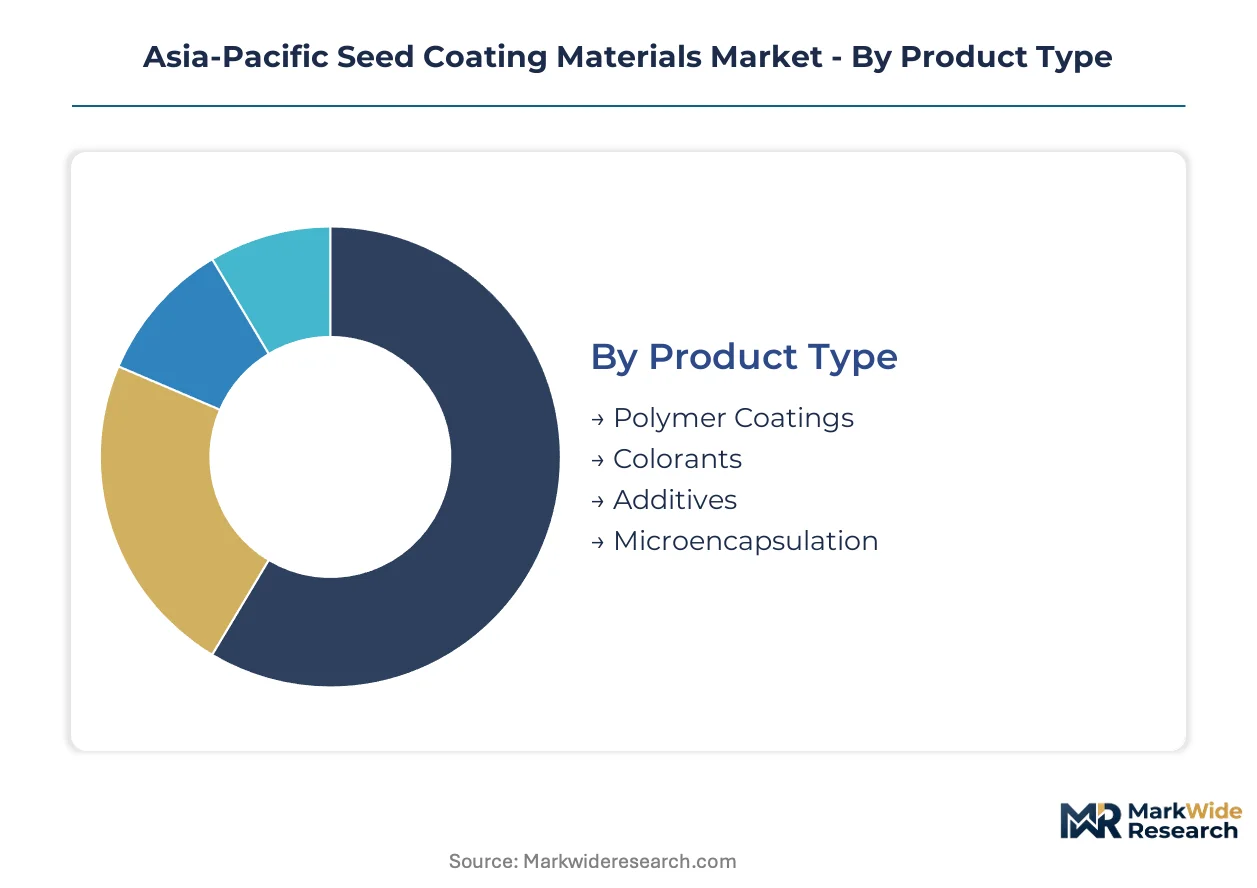
Seed coating material selection in Asia-Pacific follows distinct upgrade cycles across product categories, with polymer formulations and colorants advancing on separate innovation trajectories. End-use specialization now determines formulation complexity more than geographic origin.
Product Type:
Polymer coatings and colorants sit at opposite ends of the replacement cycle spectrum, with additive systems occupying a middle ground of incremental refinement.
- Polymer Coatings:Acrylic and polyurethane matrices constitute the functional backbone of controlled-release systems, typically comprising 1-5% of total seed weight. Australian wheat producers in New South Wales and Victoria specify drought-resistant polymer grades that buffer micronutrient release during extended dry spells. China's MEE volatile organic compound limits are forcing waterborne reformulations across Jiangsu and Hunan coating facilities.
- Colorants:Pigment and dye systems enable lot-level traceability through supply chains. Australia's APVMA residue limit harmonization accelerates colorant adoption for export wheat certification requirements. Traceability mandates across export-oriented agricultural economies position colorants as the category gaining share fastest.
- Additives:Binders, surfactants, and stabilizers optimize coating adhesion and flow characteristics.
- Microencapsulation:Shell-based delivery systems protect active ingredients from environmental degradation prior to germination.
Volume placements concentrate in polymer coatings; the faster expansion belongs to colorants.
Application:
Margin structure separates commodity grain applications from protected cultivation specialties, with per-unit economics diverging sharply across seed categories.
- Agricultural Seeds:Rice, wheat, and maize coatings absorb the majority of regional material volumes through mechanized planting adoption. Southeast Asian rice farmers in Vietnam and Thailand are abandoning untreated seed practices for precision-coated varieties that enable direct seeding in flooded paddy conditions.
- Vegetable Seeds:High-value formulations for protected cultivation command multiples of commodity grain margins. South Korean and Japanese greenhouse expansion creates concentrated demand for specialized coating systems with biostimulant integration.
- Flower Seeds:Ornamental applications require aesthetic colorant specifications alongside functional performance.
- Turf Seeds:Sports field and landscaping specifications emphasize rapid establishment and uniform emergence.
Revenue concentration sits with vegetable seeds; agricultural seeds dominate tonnage throughput.
End User:
Customer scale determines whether coating procurement flows through integrated seed manufacturers or direct-to-farm channels.
- Farmers:Australian wheat belt aggregators in New South Wales and Victoria now contract coating services directly, bypassing regional seed distributors. Consolidated procurement by large-scale farming cooperatives compresses supplier negotiation cycles.
- Agricultural Cooperatives:Member-owned enterprises pool coating demand to secure volume pricing on polymer formulations.
- Seed Manufacturers:Integrated coating operations at origin capture margin through captive supply of treatment services.
- Garden Centers:Retail channels serve hobbyist and small-scale ornamental seed demand.
Procurement authority is shifting toward agricultural cooperatives; farmer direct contracting is climbing the fastest.
Distribution Channel:
Channel selection reflects customer technical sophistication and order scale, with digital platforms disrupting traditional agrochemical dealer networks.
- Direct Sales:Manufacturer-to-farm relationships eliminate intermediary margins for large-volume accounts. E-commerce platforms enable coating manufacturers to capture value previously lost to regional distributors.
- Online Retail:Digital marketplaces aggregate smallholder demand across Indonesia and the Philippines.
- Wholesalers:Bulk distribution networks serve seed manufacturers and cooperative procurement functions.
- Distributors:Traditional agrochemical dealer networks retain relevance for technical support requirements.
Transaction volume flows through wholesalers; channel expansion is steepest in online retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's PLI scheme for agrochemicals is concentrating polymer coating production within designated manufacturing zones. Southeast Asian rice belts are decoupling from untreated seed traditions through mechanization mandates.
China
Jiangsu and Hunan provinces host the densest concentration of rice coating facilities facing MEE volatile organic compound compliance deadlines. The country's dual carbon goals are forcing waterborne polymer reformulations across solvent-dependent operations. Yangtze River Delta manufacturers are retrofitting coating lines ahead of 2025 emissions enforcement windows.
India
The PLI scheme for agrochemicals is accelerating domestic polymer coating capacity expansion across Maharashtra and Gujarat. CIBRC biopesticide registration streamlining under sustainability directives is shortening microbial product approval timelines. Telangana and Karnataka seed clusters are integrating captive coating operations to capture margin from treatment services.
Australia
New South Wales and Victoria wheat belt aggregators are contracting coating services directly, bypassing regional seed distributors. APVMA residue limit harmonization is accelerating colorant adoption for export certification requirements. Farm cooperatives exceeding ten thousand hectares are consolidating procurement authority to compress supplier negotiation cycles.
Vietnam
Mekong Delta commercial farms are piloting biostimulant-infused polymer matrices for flooded paddy germination improvement. Government mechanization directives are displacing manual transplanting with direct-seeded coated varieties. Dong Thap and An Giang provinces are leading untreated seed abandonment rates across Southeast Asia.
Japan
Protected cultivation expansion in Chiba and Ibaraki prefectures is generating concentrated demand for high-value vegetable seed formulations. METI agricultural technology adoption incentives are subsidizing precision coating equipment for greenhouse operators. Per-unit margins on specialty formulations exceed commodity grain applications by significant multiples.
Asia-Pacific Seed Coating Materials Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated seed manufacturers capturing captive value from treatment services. The vendor base organizes around three strategic archetypes: multinational chemical conglomerates with polymer R&D depth, regional coating specialists serving commodity grain volumes, and biological formulation innovators targeting sustainability premiums. Competitive moves concentrate on backward integration into polymer feedstock production and geographic expansion through distributor network acquisition.
Among European-headquartered conglomerates, BASF SE and Bayer Crop Science exemplify the integrated chemical-player archetype with regional manufacturing scale. Croda International Plc represents the specialty-additive positioning within the competitive set. These three entities anchor the premium formulation tier through differentiated technology portfolios.
| Leading Market Players |
|---|
| BASF SE |
| Bayer Crop Science |
| Croda International Plc |
| Clariant |
| Solvay |
| Incotec Group BV |
| Brettyoung |
| DSM |
| Chromatech Incorporated |
| Others |
Value Chain & Pricing Dynamics
Sovereign-backed producers across China and India anchor polymer coating supply through state-subsidized manufacturing zones, concentrating volume leverage that disciplines pricing across smaller private formulators. This ownership pattern concentrates feedstock procurement power while fragmenting downstream negotiation positions for regional coating specialists.
Pricing Analysis
Short lead-time premiums apply to biological coating formulations where China's MEE registration bottlenecks create supply scarcity. Contract-based long-term offtake dominates polymer coating procurement, with price differentiation driven by certification grade under APVMA residue protocols and volume scale across Australian wheat belt aggregators. Cost compression in commodity acrylic coatings is intensifying because petrochemical input volatility squeezes smaller formulators. Subsistence farmers in Indonesia and the Philippines exhibit highest price sensitivity, while Japanese greenhouse operators show least sensitivity due to METI subsidy coverage.
Supply Chain Analysis
Freight cost escalation across intra-Asia container routes is reshaping regional sourcing patterns for Australian and Japanese buyers. Supply concentrates in China, India, and Australia, with acrylic resins, polyurethane feedstocks, and microbial active ingredients as critical dependencies. Single-source vulnerability runs through Chinese waterborne polymer production where MEE compliance deadlines cluster. Distribution runs through agricultural cooperatives and direct manufacturer-to-farm channels, bypassing traditional dealer networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where China's MEE volatile organic compound limits and India's PLI scheme create barrier-to-entry moats for players with certified waterborne polymer capacity.
For Market Incumbents: Deepen backward integration into acrylic feedstock production to buffer petrochemical margin volatility. BASF SE and Bayer Crop Science should expand captive coating operations at Telangana and Karnataka seed clusters before CIBRC biopesticide registration streamlining attracts microbial formulation entrants. Certification investment under APVMA residue harmonization secures Australian wheat belt pricing power.
For New Entrants and Emerging Players: E-commerce platforms aggregating smallholder demand across Indonesia and the Philippines represent the most penetrable channel entry. Biological coating specialization for Vietnamese Mekong Delta flooded paddy conditions offers white-space positioning. Direct-to-farm distribution partnerships bypass entrenched agrochemical dealer networks.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap coating specialists with stranded solvent-based capacity in Jiangsu and Hunan provinces facing MEE retrofit deadlines. Long-term viability centers on waterborne polymer formulation expertise transfer. Watch CIBRC microbial product approval velocity as inflection signal for biological coating premium sustainability.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Feedstock | Captive acrylic supply insulates BASF SE from crude oil volatility in Australian coating contracts. |
| Waterborne Polymer Reformulation | MEE compliance in Jiangsu and Hunan facilities preserves registration access for Yangtze River Delta manufacturers. |
| Direct-to-Farm Channel Development | E-commerce platforms capture margin from Indonesian smallholder segments previously served by dealer networks. |
| Biological Coating R&D Partnership | Microbial formulation alliances with Vietnamese Mekong Delta pilots accelerate CIBRC approval pathways. |
| Certification Investment under APVMA Protocols | Residue limit harmonization secures export wheat colorant premiums for New South Wales aggregators. |
Study Parameters
Multi-period observation of seed treatment adoption rates, regulatory approval timelines, and polymer feedstock price movements anchored the trend analysis, supplemented by interviews with coating plant managers, procurement leads at Australian wheat cooperatives, CIBRC registration consultants, and distribution channel partners. Secondary validation drew from customs/trade data, MEE emissions enforcement notices, APVMA residue limit publications, and SEC filings of multinational chemical conglomerates. Bottom-up coating volume estimates triangulated against top-down agricultural seed market sizing.
Input-output matrices modeled polymer coating demand against rice mechanization indices, wheat export certification requirements, and greenhouse expansion rates across segmentation dimensions including product type, application category, and end-user scale. CAGRs derived from regression analysis of historical coating penetration rates projected across the analysis window, incorporating PLI scheme capacity addition schedules and MEE compliance deadline clustering as industry-specific forecast inputs.
Caveats apply where MEE enforcement intensity, crude oil price volatility, or CIBRC registration timeline revisions could materially shift the outlook. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seed Technology
China Seed Treatment Market
Seed Technology
Asia-Pacific Tomato Seed Market
Seed Technology
Protein Content Optimizing Cereal Fertility Program Market
Seed Technology
North America Cotton Seed Treatment Market
Seed Technology
Seed Coating Ingredients Market
Seed Technology
Germany Seed Treatment Market
Seed Technology
France Seed Treatment Market
Seed Technology
Seed Storage Systems Market
Seed Technology
Seed Coating Materials Market
Seed Technology
Canada Seed Treatment Market
Seed Technology
Chitosan-based Seed Coatings Market
Seed Technology
India Seed Treatment Market
Seed Technology
Europe Seed Coating Materials Market
Seed Technology
Global Wheat Seed Treatment Market
Seed Technology
Mexico Seed Treatment Market
Seed Technology
North America Seed Coating Materials Market