
 Chitosan-based Seed Coatings Market | 2026-2036
Chitosan-based Seed Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Chitosan-based Seed Coatings Market Insights
REACH compliance is consolidating the cost-of-entry calculus for chitosan seed coating suppliers seeking European market access. KitoZyme leverages its Belgian biopolymer heritage to sustain premium positioning across EU member states. Corteva Agriscience anchors its portfolio through integrated seed treatment platforms that incorporate biological coatings at scale. ChitoLytic specializes in enzymatic chitosan extraction, differentiating on molecular weight consistency for precision agriculture applications.
Chitosan-based seed coatings comprise deacetylated chitin biopolymer formulations applied to seed surfaces, typically at 0.5-2% by weight, to enhance germination rates and suppress soil-borne pathogens through induced systemic resistance. The primary commercial purpose centers on reducing synthetic fungicide dependency while improving stand establishment under abiotic stress conditions. Liquid formulations dominate volume throughput in commercial seed treatment facilities, while powder variants command margin premiums among organic farming ventures seeking dry-handling compatibility. Cereal crops absorb the largest absolute tonnage of coated seeds, though horticultural seeds generate superior per-unit value given smaller batch sizes and higher technical service requirements.
The EPA regulates chitosan seed treatments under biochemical pesticide guidelines, while the USDA National Organic Program governs certification eligibility for organic farming ventures. China's MEE enforces discharge standards on chitosan production facilities, constraining supply expansion from coastal processing clusters. Stakeholders must monitor evolving residue tolerance thresholds across import jurisdictions to preempt market access disruptions.
Market Dynamics
EU Fertilizing Products Regulation tightening on synthetic inputs is accelerating farmer migration toward biological seed treatments, compressing the window for chitosan coating suppliers to capture displaced conventional fungicide demand.
Growth Catalysts
- REACH compliance pathways:The EU's chemical registration framework creates preferential market access for chitosan producers with established dossiers, channeling procurement toward pre-certified Belgian and Dutch suppliers.
- Row crop biological transition:Brazilian soybean growers are substituting neonicotinoid seed treatments with chitosan formulations to maintain EU export eligibility for residue-sensitive markets.
- Induced systemic resistance mechanisms:Advances in molecular weight targeting enable precision activation of plant defense pathways, differentiating chitosan from broad-spectrum biocontrol alternatives.
Market Restraints
- Chitin feedstock concentration:Coastal Chinese processing clusters dominate shrimp shell supply, exposing formulation costs to MEE discharge enforcement volatility and seasonal aquaculture fluctuations.
- Performance inconsistency under abiotic stress:Chitosan efficacy degrades in high-salinity or drought-prone soils, limiting addressable acreage in Australian wheat belts and North African cereal zones.
- Synthetic fungicide residual preference:Corn seed treatment facilities in the American Midwest retain equipment calibrated for chemical actives, creating switching friction for biological coating lines.
Strategic Opportunities
- Indian organic vegetable export corridors:APEDA certification requirements for European supermarket chains are mandating residue-free seed treatments, opening premium positioning for chitosan suppliers in Punjab and Maharashtra.
- Enzymatic extraction convergence:Integration of chitinase bioprocessing with precision fermentation platforms is reducing molecular weight variance, enabling contract manufacturing for multinational seed companies.
- Direct-to-grower digital channels:E-commerce platforms serving mid-scale organic operations are bypassing traditional agrochemical distributor markups, capturing margin in specialty horticulture segments.
Industry Challenges
- Formulation chemist scarcity:Cross-disciplinary expertise spanning polymer science, plant pathology, and seed physiology remains concentrated in Belgian and Brazilian research clusters, constraining R&D expansion.
- USDA Organic Program certification timelines:Multi-year approval processes for novel chitosan derivatives delay commercialization, forcing suppliers to rely on existing OMRI-listed formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chitosan-based Seed Coatings Market |
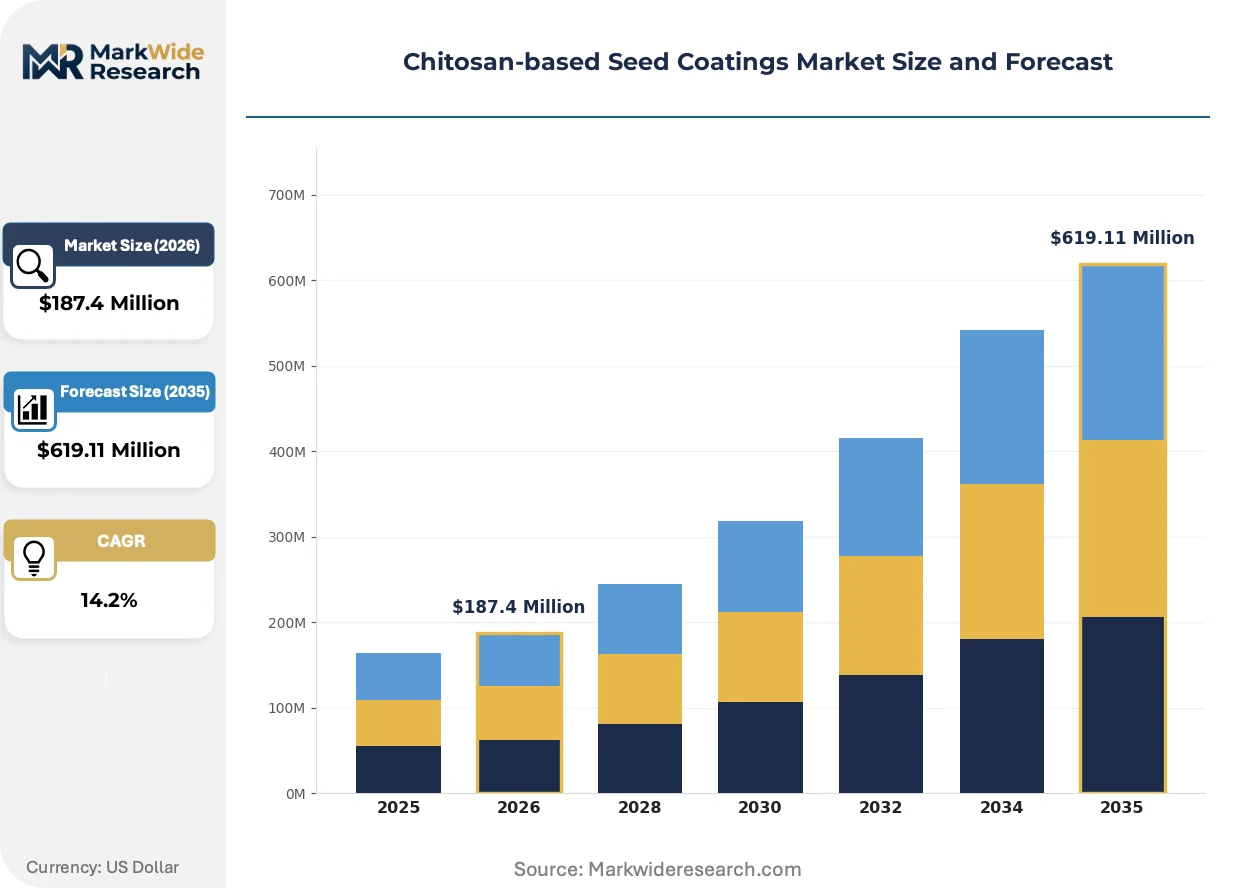
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $619.11 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Liquid, Granule, Emulsion, Film Application: Cereal Crops, Vegetable Seeds, Pulses, Oilseeds, Horticultural Seeds End Use Industry: Agricultural Farms, Seed Treatment Companies, Agrochemical Manufacturers, Organic Farming Ventures Packaging Type: Bag, Bottle, Sachet, Drum |
| Companies Covered | KitoZyme, ChitoLytic, Tidal Vision, Chitosan USA, Corteva Agriscience, Bayer Crop Science, BASF, Syngenta Group, Germains Seed Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chitosan-based Seed Coatings Market Trends and Innovations
Active ingredient delivery systems are converging with digital agriculture platforms, reshaping how seed treatment performance is measured, priced, and guaranteed to risk-averse growers.
Nano-encapsulated chitosan complexes are expanding into precision agriculture workflows through controlled-release coatings that synchronize antimicrobial activity with germination timing. Large-scale commodity operations in Iowa and Illinois are piloting these formulations to reduce re-treatment frequency. The technology is expanding into subscription-based seed treatment service models where per-acre guarantees replace traditional product sales.
EPA biochemical pesticide guidelines are tightening data requirements for plant-incorporated protectants, forcing chitosan suppliers to generate additional field efficacy dossiers for row crop registrations. The agency's 2023 guidance on semiochemicals has created classification ambiguity for oligosaccharide signaling compounds. Western European suppliers with existing BPR-compliant submissions are capturing first-mover advantage in reregistration windows.
Certification-driven procurement is consolidating buyer preference around OMRI-listed and EU Organic-compliant coating variants, displacing uncertified biological alternatives in premium vegetable seed segments. Dutch glasshouse operations and California specialty crop growers are requiring batch-traceable chitosan documentation. This shift is most visible in tomato and pepper seed supply chains where supermarket audit requirements cascade backward to propagation facilities.
Chitosan-based Seed Coatings Market Segmentation
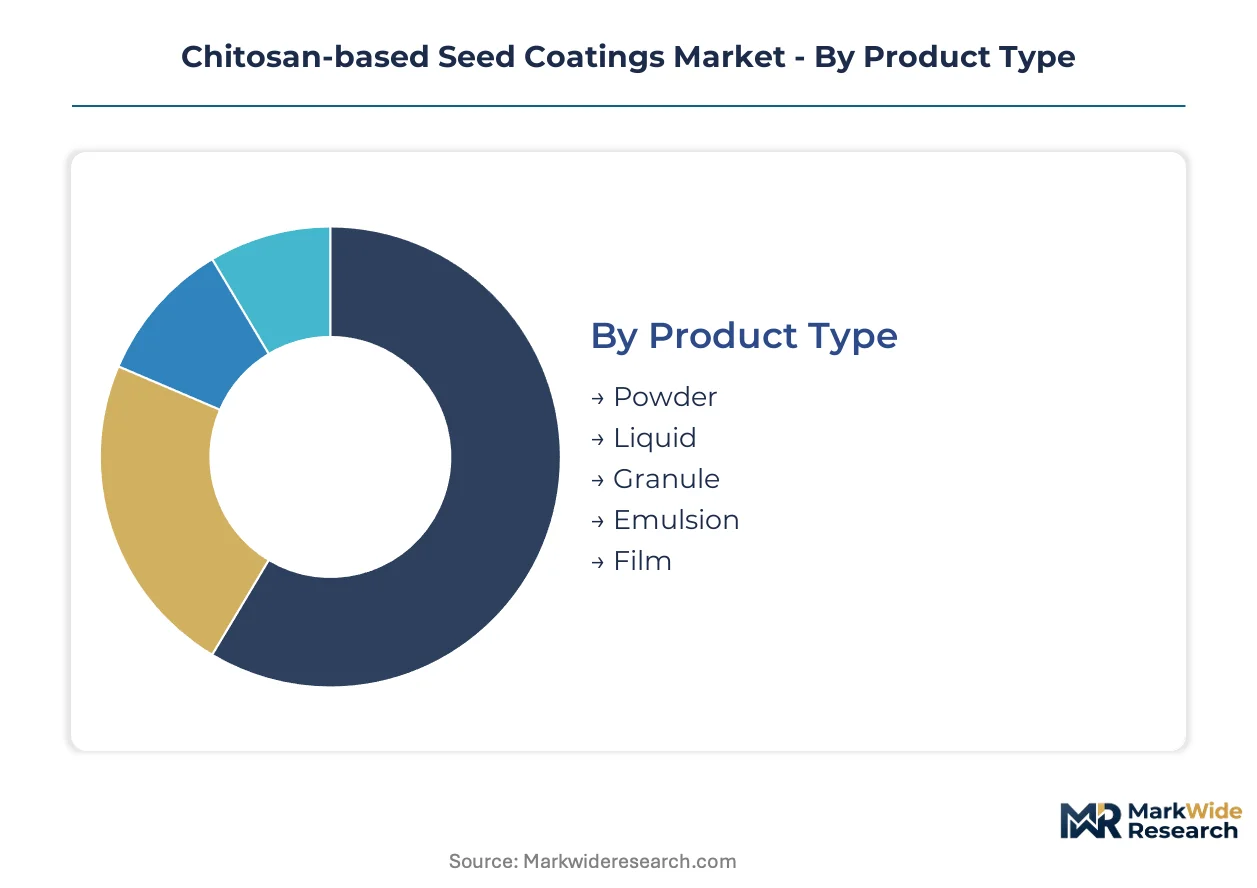
Segmentation in chitosan-based seed coatings reveals how formulation physics and downstream handling requirements split procurement decisions across commodity agriculture and precision horticulture. Each dimension exposes distinct margin structures and certification barriers that suppliers must navigate.
Product Type:
Liquid formulations embed directly into commercial seed treatment infrastructure, while powder and granule variants demand standalone handling systems that organic operators often prefer.
- Liquid:Dominates throughput at commercial seed treatment facilities calibrated for aqueous delivery systems. Demand concentrates in Iowa and Illinois corn seed operations where Corteva and Bayer treatment lines require pump-compatible viscosity grades to maintain line speeds.
- Powder:Dry-flowing chitosan salts enable on-farm seed dressing without liquid handling infrastructure. Organic farming ventures in California's Central Valley and the Netherlands' glasshouse corridors favor powder for compatibility with small-batch seeders and reduced spoilage risk.
- Granule:Compressed chitosan-carrier matrices for slow-release applications in no-till soybean systems.
- Emulsion:Oil-in-water dispersions improving adhesion to oily seed surfaces like sunflower and canola.
- Film:Pre-formed chitosan sheets for high-value horticultural seed pelleting in Dutch propagation facilities.
Volume placements concentrate in Liquid; the faster expansion belongs to Powder.
Application:
Crop-specific physiology dictates molecular weight targeting and application rates, separating commodity tonnage plays from premium horticulture service models.
- Cereal Crops:Wheat and corn seeds absorb the largest absolute tonnage of chitosan coatings, driven by Brazilian and American Midwest farmers substituting neonicotinoid treatments to maintain EU export eligibility. High-volume, low-margin contracts dominate this segment.
- Vegetable Seeds:Tomato, pepper, and lettuce seeds command superior per-unit value through smaller batch sizes and technical service intensity. Punjab and Maharashtra organic export operations are mandating residue-free treatments for APEDA certification to European supermarket chains.
- Pulses:Chickpea and lentil coating demand rising in Canadian prairie provinces for rhizobia compatibility.
- Oilseeds:Soybean and canola applications concentrated in Brazil's Mato Grosso for Asian market access.
- Horticultural Seeds:Ornamental and turf grass segments requiring specialized pelleting aesthetics.
Revenue concentration sits with Cereal Crops; margin expansion is steepest in Vegetable Seeds.
End Use Industry:
Customer type determines whether chitosan coatings enter through integrated seed company platforms or direct-to-grower channels with diverging certification requirements.
- Seed Treatment Companies:Commercial facilities operated by Corteva, Syngenta, and regional processors handle 70%+ of coated seed volume. These operations require OMRI-listed and REACH-compliant formulations to service both conventional and organic seed lines from single treatment suites.
- Organic Farming Ventures:Direct procurement of certified chitosan for on-farm seed dressing, bypassing distributor markups through e-commerce platforms. California specialty crop growers and Dutch glasshouse operators demand batch-traceable documentation for supermarket audit compliance.
- Agricultural Farms:Mid-scale row crop operations in Brazil and the American Midwest purchasing treated seed as finished product.
- Agrochemical Manufacturers:Biological division expansions integrating chitosan into broader biocontrol portfolios.
Procurement volume flows through Seed Treatment Companies; the direct channel is climbing fastest among Organic Farming Ventures.
Packaging Type:
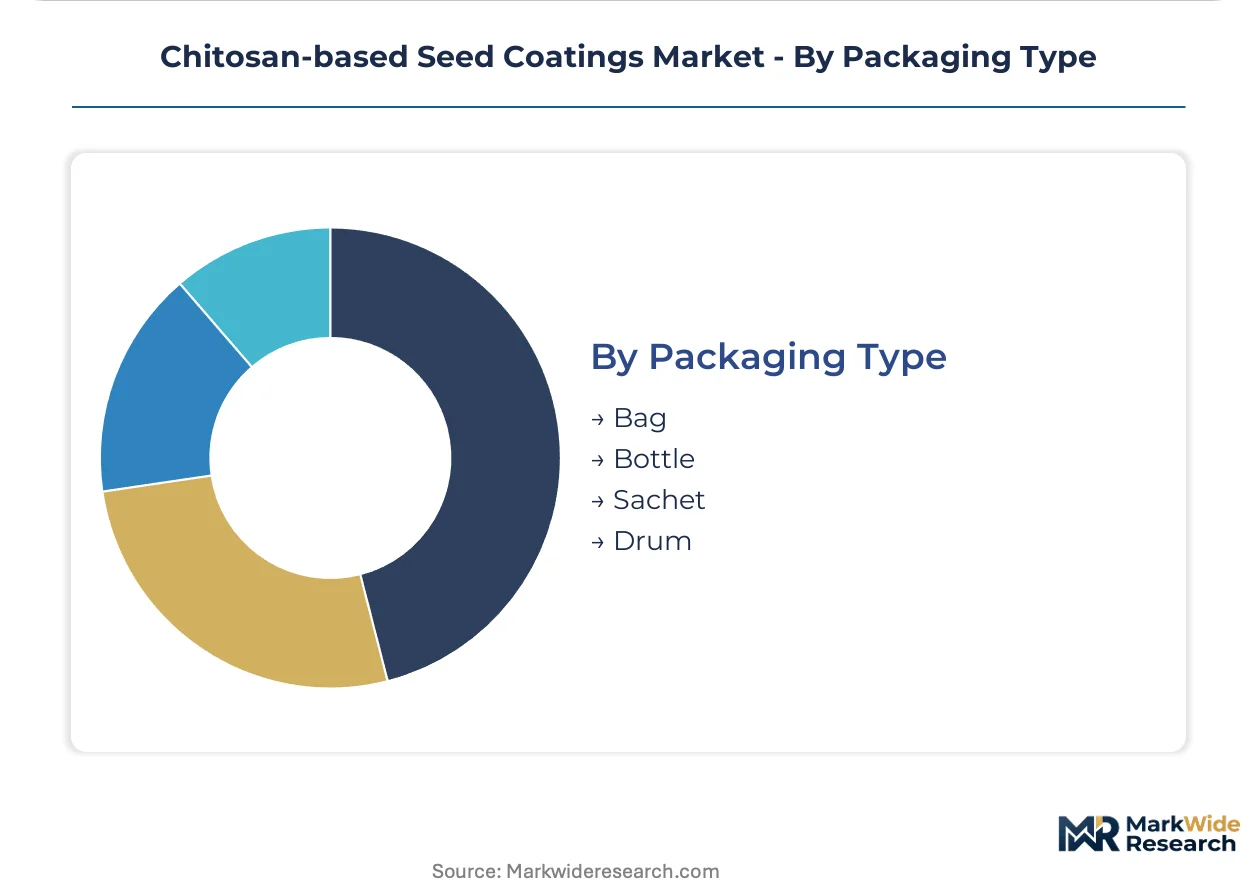
Packaging selection tracks batch size economics and shelf stability requirements across industrial-scale and artisanal use cases.
- Drum:Industrial bulk containers for seed treatment facility feed systems, dominating liquid formulation logistics.
- Bag:Multi-layer polymer sacks for powder and granule variants in 25kg agricultural standard sizing.
- Bottle:Liter-scale containers for laboratory and small-batch horticultural applications.
- Sachet:Single-use packets enabling precise dosing for on-farm seed dressing without measurement equipment.
Shipment tonnage clusters in Drum and Bag formats; sachet configurations are gaining share fastest in emerging market smallholder segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's Manaus Free Trade Zone and China's Hainan Free Trade Port concentrate chitosan processing capacity through tax-advantaged feedstock import regimes. Coastal processing clusters in both jurisdictions leverage duty exemptions on crustacean shell imports to anchor regional supply.
United States
Iowa and Illinois corn seed treatment facilities drive demand for liquid chitosan formulations compatible with existing chemical infrastructure. EPA biochemical pesticide guidelines govern registration pathways for biological seed treatments. The American Midwest's integrated seed company platforms process the largest absolute tonnage of coated cereal seeds.
Brazil
Mato Grosso soybean growers substitute neonicotinoid treatments with chitosan coatings to preserve EU export eligibility for residue-sensitive markets. ANVISA regulates biological seed treatment registrations alongside conventional agrochemical frameworks. The country's coastal processing clusters near Fortaleza handle shrimp shell feedstock conversion for domestic formulation supply.
Belgium
KitoZyme leverages established REACH dossiers to supply EU member states with premium-grade chitosan biopolymers. ECHA registration requirements channel procurement toward pre-certified suppliers with complete toxicological data packages. The Flanders biopolymer research corridor concentrates enzymatic extraction expertise and polymer science R&D capacity.
China
Shandong and Zhejiang coastal provinces dominate chitin feedstock processing from aquaculture waste streams. MEE discharge standards constrain capacity expansion and expose formulation costs to environmental enforcement volatility. Qingdao processing clusters face seasonal supply fluctuations tied to shrimp harvest cycles.
India
Punjab and Maharashtra organic vegetable export operations mandate residue-free seed treatments for APEDA certification to European supermarket chains. FSSAI and DGFT frameworks govern import and domestic production standards for biological agricultural inputs. The country's enzymatic extraction capabilities remain concentrated in research partnerships with Belgian technology licensors.
Chitosan-based Seed Coatings Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across formulation chemistry and feedstock processing tiers. The market structure splits between integrated agrochemical platforms with biological divisions and standalone chitosan suppliers with polymer science specialization. Three archetypes dominate: multinational seed treatment integrators, enzymatic extraction specialists, and regional feedstock processors. Capacity expansion and REACH dossier completion represent the dominant competitive moves as suppliers race to secure EU market access ahead of reregistration windows.
Among Belgian biopolymer specialists, KitoZyme occupies a position exemplifying premium-tier REACH compliance, while ChitoLytic represents the enzymatic extraction archetype with molecular weight consistency positioning. Corteva Agriscience anchors the integrated seed treatment platform tier, leveraging existing commercial infrastructure to incorporate biological coatings at scale.
| Leading Market Players |
|---|
| KitoZyme |
| ChitoLytic |
| Tidal Vision |
| Chitosan USA |
| Corteva Agriscience |
| Bayer Crop Science |
| BASF |
| Syngenta Group |
| Germains Seed Technology |
| Others |
Pricing and Supply Chain Analysis
Captive control over enzymatic extraction capacity anchors supply positions for Belgian specialists while compressing margin capture for formulation-dependent distributors. KitoZyme's in-house chitinase bioprocessing insulates against shrimp shell feedstock volatility, translating upstream integration into premium-tier pricing power across EU member states.
Pricing Analysis
Short lead-time premiums command substantial markups in European vegetable seed supply chains where Dutch glasshouse operators require batch-traceable chitosan within 72-hour windows. Three-tier pricing structure across premium, standard, and economy levels separates REACH-certified enzymatic grades from acid-extracted alternatives and uncertified commodity powders. Pricing pressure stems from MEE discharge enforcement volatility in Shandong processing clusters, eroding margins for acid-extracted supply. Organic farming ventures in California exhibit lowest price sensitivity, while Brazilian soybean cooperatives negotiate aggressively on volume contracts.
Supply Chain Analysis
Workforce availability constraints in Belgian biopolymer research corridors and Brazilian enzymatic processing hubs limit expansion of precision fermentation capacity. Supply concentrates in China's coastal provinces, Belgium's Flanders corridor, and Brazil's Fortaleza cluster, each drawing from distinct shrimp aquaculture waste streams. Raw material dependencies span crustacean shell feedstock, chitinase enzyme supply, and precision fermentation nutrients. Single-source vulnerability concentrates in Shandong's seasonal harvest exposure. Distribution runs through integrated seed company platforms and direct-to-grower e-commerce channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards backward integration into enzymatic extraction as the decisive competitive lever, with KitoZyme and ChitoLytic demonstrating how captive bioprocessing capacity translates into REACH dossier completion and premium positioning.
For Market Incumbents: Acquire enzymatic extraction specialists to secure molecular weight consistency capabilities before EU reregistration windows close. Corteva Agriscience should deepen captive biopolymer production to reduce formulation cost exposure. Defend against pure-play specialists by accelerating OMRI-listed derivative pipelines through USDA Organic Program pre-submission.
For New Entrants and Emerging Players: Enter via APEDA-certified organic vegetable export corridors in Punjab and Maharashtra, where residue-free mandates create procurement urgency without entrenched supplier relationships. Target powder formulation segments for dry-handling compatibility in small-batch horticulture. Pursue digital channel partnerships with mid-scale organic e-commerce platforms to bypass distributor markups.
For Investors and Strategic Acquirers: Exit pathways concentrate in multinational agrochemical platform absorption, with biological division expansions seeking proven REACH compliance. Long-term viability favors enzymatic extraction specialists with completed ECHA dossiers over acid-extracted commodity processors. Watch for EPA biochemical pesticide guideline tightening as inflection signal for reregistration cost spikes.
| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Extraction Capacity Buildout | KitoZyme's Belgian biopolymer heritage enables premium-tier molecular weight consistency for precision agriculture. |
| REACH Dossier Completion | ECHA registration requirements channel procurement toward pre-certified suppliers with complete toxicological data packages. |
| Direct-to-Grower Digital Channel | E-commerce platforms serving California specialty crop growers bypass traditional agrochemical distributor markups. |
| OMRI-Listed Formulation Pipeline | USDA Organic Program certification timelines force reliance on existing approved derivatives for commercial launch. |
| Backward Integration into Feedstock Processing | Captive shrimp shell conversion in Brazil's Fortaleza cluster reduces exposure to MEE discharge enforcement volatility. |
Research Methodology
Trade databases, ECHA registration filings, and aquaculture processing records formed the secondary backbone for supply-side calibration. Primary interviews with seed treatment facility managers, enzymatic extraction R&D directors, organic certification officers, and APEDA export coordinators validated demand assumptions. Bottom-up and top-down triangulation cross-checked volume estimates against customs data and seed company procurement disclosures.
Bottom-up modeling anchored projections in treatment line throughput at Corteva and Bayer facilities, while top-down validation referenced EU Fertilizing Products Regulation compliance cost trajectories. Segmentation dimensions spanned formulation physics, crop physiology, customer type, and certification tier across the analysis window. CAGRs derived from S-curve adoption modeling for biological seed treatments, incorporating EPA biochemical pesticide registration timelines and EU organic farming conversion rates as industry-specific inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under MEE enforcement intensification or neonicotinoid regulatory reversal scenarios. Forecasts reflect documented assumptions regarding enzymatic extraction scale-up economics and shrimp shell feedstock seasonality. Material deviation in EPA classification rulings for oligosaccharide signaling compounds warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seed Technology
China Seed Treatment Market
Seed Technology
Seed Coating Ingredients Market
Seed Technology
Seed Treatment Market
Seed Technology
Germany Seed Treatment Market
Seed Technology
Asia-Pacific Seed Coating Materials Market
Seed Technology
Mexico Seed Treatment Market
Seed Technology
Protein Content Optimizing Cereal Fertility Program Market
Seed Technology
North America Cotton Seed Treatment Market
Seed Technology
Global Wheat Seed Treatment Market
Seed Technology
Europe Seed Coating Materials Market
Seed Technology
Seed Quality Imaging and Germination Prediction Test Systems Market
Seed Technology
North America Seed Coating Materials Market
Seed Technology
Seed Storage Systems Market
Seed Technology
Asia-Pacific Tomato Seed Market
Seed Technology
India Seed Treatment Market
Seed Technology
Seed Coating Materials Market