
 North America Savory Snacks Market | 2026-2036
North America Savory Snacks Market Size, Share, and Industry Trends Forecast 2026-2036
North America Savory Snacks Market Intelligence
The fragmentation of consumer demand toward niche flavor profiles and healthier ingredients is repositioning the competitive landscape in North America. This shift creates openings for both large incumbents and smaller challengers. PepsiCo leverages its vast distribution network to command share in core chip segments. Concurrently, Utz Brands specializes in regional brand strength, while Mondelēz International competes by innovating within the cracker and savory biscuit space.
Savory snacks encompass a category of processed, non-sweet food items designed for immediate consumption. These products, typically based on potato, corn, or wheat, are manufactured through processes like frying, baking, or extrusion to achieve distinct textures and ensure shelf stability. While potato chips remain the largest product type by volume, the nuts and popcorn categories are expanding due to perceived health benefits. Sales through online distribution channels and convenience stores are growing quickly, challenging the long-held dominance of supermarkets.
The regulatory environment is shaped by the U.S. Food and Drug Administration (FDA) and Health Canada, which oversee food safety, ingredients, and labeling. Mandates concerning sodium content limits, clear allergen declarations, and potential front-of-package nutritional symbols directly impact product formulation. These rules also govern marketing claims related to health benefits. Successfully balancing consumer demand for indulgence with these evolving health-focused regulations is a critical strategic consideration for all brands.
Market Dynamics
The central dynamic in the North America savory snacks market is the tension between consumer demand for indulgent, complex flavors and mounting regulatory pressure for healthier product profiles, a force directly influencing formulation and marketing strategies.
Growth Catalysts
- Convenience Channel Expansion:The growing number of convenience stores and gas stations across the United States and Canada provides an expanding footprint for single-serve and impulse-purchase snack products, driving volume growth.
- Premium Flavor Demand:Consumer appetite for sophisticated and spicy flavor profiles, particularly in major urban centers, supports premiumization and higher price points for niche and artisanal snack categories.
- Health-Perception Shift:Products in the nuts, seeds, and popcorn categories are benefiting from a consumer perception of being healthier alternatives to traditional fried snacks, spurring category growth.
Market Restraints
- Input Cost Volatility:Fluctuations in the prices of key agricultural commodities, including potatoes, corn, and cooking oils, create margin pressure and introduce uncertainty into production cost structures for manufacturers.
- Regulatory Sodium Limits:Mandates and guidance from Health Canada and the U.S. FDA regarding sodium reduction targets present significant technical challenges in reformulation without compromising taste and shelf stability.
- Substitution from Other Categories:The savory snacks market faces competition from other convenient food categories, such as snack bars, yogurt, and fruit snacks, which are also positioned for on-the-go consumption.
Strategic Opportunities
- Plant-Based Innovation:There is a significant opportunity in developing snacks from alternative plant-based sources like chickpeas, lentils, and other pulses, appealing to health-conscious and environmentally aware consumers.
- Direct-to-Consumer Models:Building direct-to-consumer (DTC) e-commerce platforms allows brands to cultivate direct relationships with consumers, test niche products, and capture valuable data on purchasing behavior.
- Functional Ingredients:Incorporating functional ingredients, such as probiotics, fiber, and plant-based proteins, into savory snacks can create new value propositions that align with wellness trends.
Industry Challenges
- Labeling Compliance Costs:Adhering to evolving labeling regulations, such as the FDA’s proposed front-of-pack nutrition symbols, requires significant investment in packaging redesign, product reformulation, and compliance management.
- Shelf-Life Management:The shift toward cleaner labels and natural ingredients with fewer preservatives complicates supply chain logistics, increasing the risk of spoilage and requiring more stringent inventory control.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Savory Snacks Market |
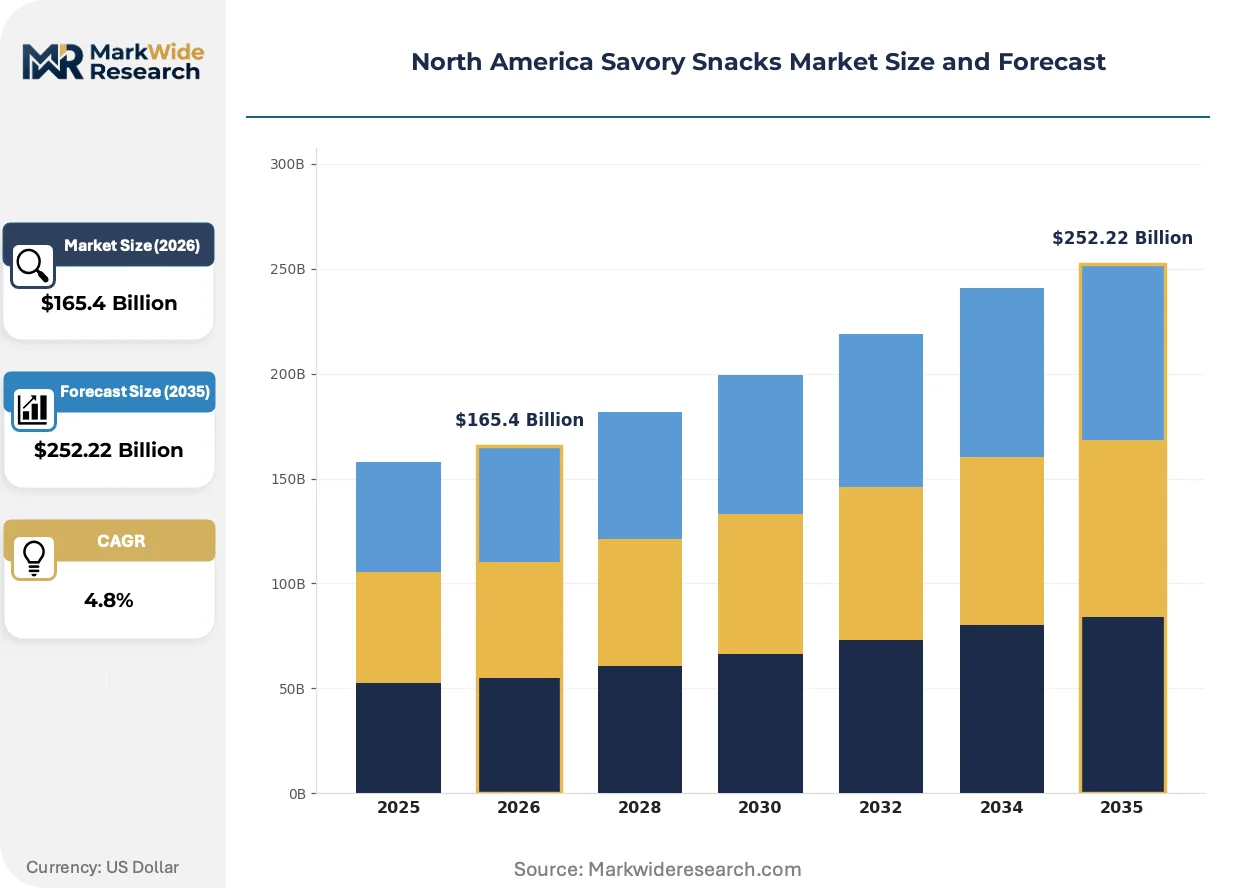
| Market Size in 2026 | $165.4 Billion |
| Market Size in 2035 | $252.22 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chips, Pretzels, Popcorn, Nuts Flavor Profile: Spicy, Cheesy, Savory, Sweet Packaging Type: Bags, Boxes, Tubs, Pouches Distribution Channel: Supermarkets, Convenience Stores, Online, Specialty Stores |
| Companies Covered | The Kraft Heinz Company, Kellanov, PepsiCo, Conagra Brands, Utz Brands, Mondelēz International, General Mills, WISE, The Hershey Company, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Savory Snacks Market Strategic Shifts & Innovations
The intersection of food science, regulatory mandates, and shifting consumer ethics around health and wellness is defining the primary innovation pathways. Product development now focuses on balancing sensory appeal with transparent, "clean-label" ingredient lists to meet new market expectations.
Advanced extrusion technology provides precise control over texture, density, and the incorporation of non-traditional flours. Snack food producers are adopting these systems to create products from bases like lentil, quinoa, and pea protein. This technology is modularizing the new product development cycle, enabling brands to rapidly iterate and launch items for specific dietary niches without overhauling entire manufacturing lines.
The U.S. FDA's proposed rule for front-of-pack (FOP) nutritional symbols is a pivotal regulatory shift. This initiative would require clear, standardized graphics on packaging that highlight high levels of sodium, added sugars, and saturated fat. Categories like potato chips and extruded cheese snacks are most exposed, prompting widespread reformulation efforts to mitigate negative consumer perceptions at the point of sale.
A consumer shift toward "permissible indulgence" is altering purchasing decisions. This behavior involves seeking products that deliver a satisfying, rich taste experience but are perceived as healthier due to factors like being baked instead of fried, having lower sodium, or containing recognizable ingredients. This trend is especially visible within the cracker and savory biscuit segments across major US and Canadian metropolitan markets.
North America Savory Snacks Market Segmentation
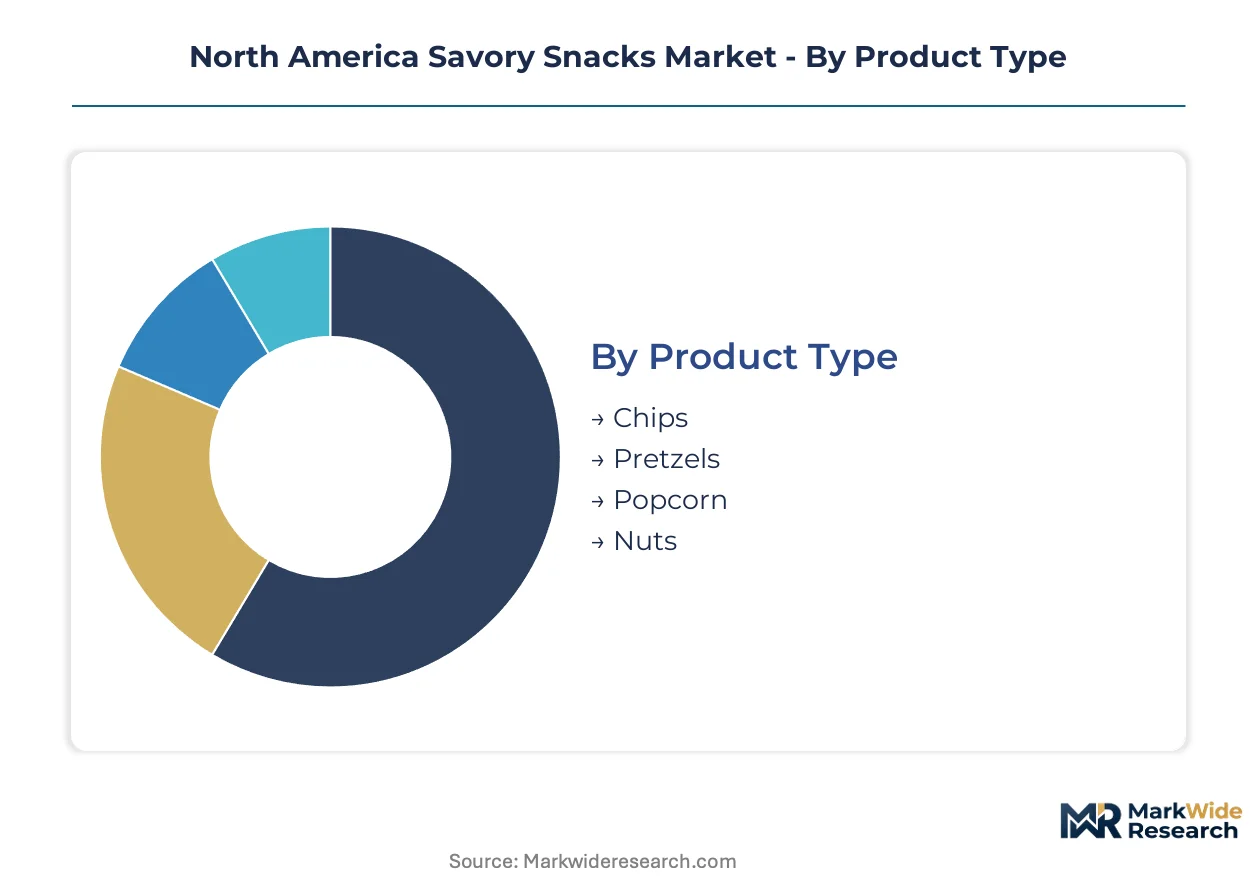
The North America savory snacks market segmentation reflects diverse consumer preferences and evolving retail strategies. Understanding these distinct segments allows brands to tailor product development, marketing efforts, and distribution networks effectively across the United States and Canada.
Product Type:
Buyer choices in this category are differentiated by the primary ingredient and manufacturing process, influencing texture and perceived health benefits.
- Chips:These thin slices of potato, corn, or other vegetables are typically fried or baked, representing the largest volume segment in North America. Demand for potato chips remains strong, particularly for traditional and ridged varieties, despite increasing competition from perceived healthier alternatives.
- Nuts:Comprising almonds, peanuts, cashews, and other varieties, this segment benefits from a consumer perception of being a healthier, protein-rich snack option. Consumption of nuts is expanding due to their natural ingredient profile and growing popularity in wellness-focused diets across urban centers.
- Pretzels:These baked, often salted, dough products offer a distinct crunchy texture and are a staple in the North American savory snack landscape. Pretzel consumption is stable, with innovation focused on new shapes and flavor coatings.
- Popcorn:Air-popped or oil-popped corn kernels provide a light, whole-grain snack, experiencing growth due to its natural and customizable nature. Ready-to-eat popcorn and microwaveable varieties continue to expand their market presence.
Volume sits with Chips; growth tilts toward Nuts.
Flavor Profile:
Consumer preferences for savory snacks are highly influenced by the desired taste experience, ranging from traditional to adventurous profiles.
- Spicy:This profile includes snacks infused with chili, jalapeño, and other capsaicin-rich ingredients, catering to a growing demand for intense and bold flavors. The spicy segment experiences significant traction in major metropolitan areas throughout the United States and Canada.
- Savory:Encompassing a broad range of umami-rich tastes like onion, garlic, and BBQ, this profile represents the foundational and most widely accepted flavor category. Savory snacks maintain broad appeal across all demographics, driving consistent sales.
- Cheesy:Snacks featuring cheese powders or cheese-flavored seasonings appeal to a wide audience seeking indulgent and familiar taste sensations. This profile is particularly popular in extruded snacks and crackers.
- Sweet:This profile integrates elements like honey, caramel, or cinnamon with savory bases, offering a contrasting and often indulgent taste experience. Sweet and savory combinations are gaining popularity, especially in pretzel and popcorn categories.
Consumer preference for Savory drives current sales, while Spicy expands most quickly.
Packaging Type:
The choice of packaging directly impacts product preservation, portability, and consumer convenience, influencing purchasing decisions.
- Bags:Flexible film bags represent the most common and cost-effective packaging for savory snacks, offering versatility for various portion sizes. This format dominates the market due to its widespread use for chips and other single-serve or family-sized options.
- Pouches:Stand-up or re-sealable pouches provide enhanced convenience and portion control, appealing to on-the-go consumption trends. The use of pouches is expanding, particularly for premium and healthier snack offerings, due to their portability and modern aesthetic.
- Boxes:Used primarily for crackers, savory biscuits, and multi-pack assortments, boxes offer structural integrity and brand visibility on shelves. This packaging type supports bulk purchases and product protection.
- Tubs:Larger plastic tubs are typically employed for bulk quantities of pretzels, cheese balls, or nuts, catering to household consumption or party-sized needs. Tubs emphasize value and extended freshness for larger portions.
The primary format remains Bags, but Pouches are gaining share due to evolving consumption patterns.
Distribution Channel:
The accessibility and retail environment where savory snacks are sold significantly influence market reach and consumer purchasing habits.
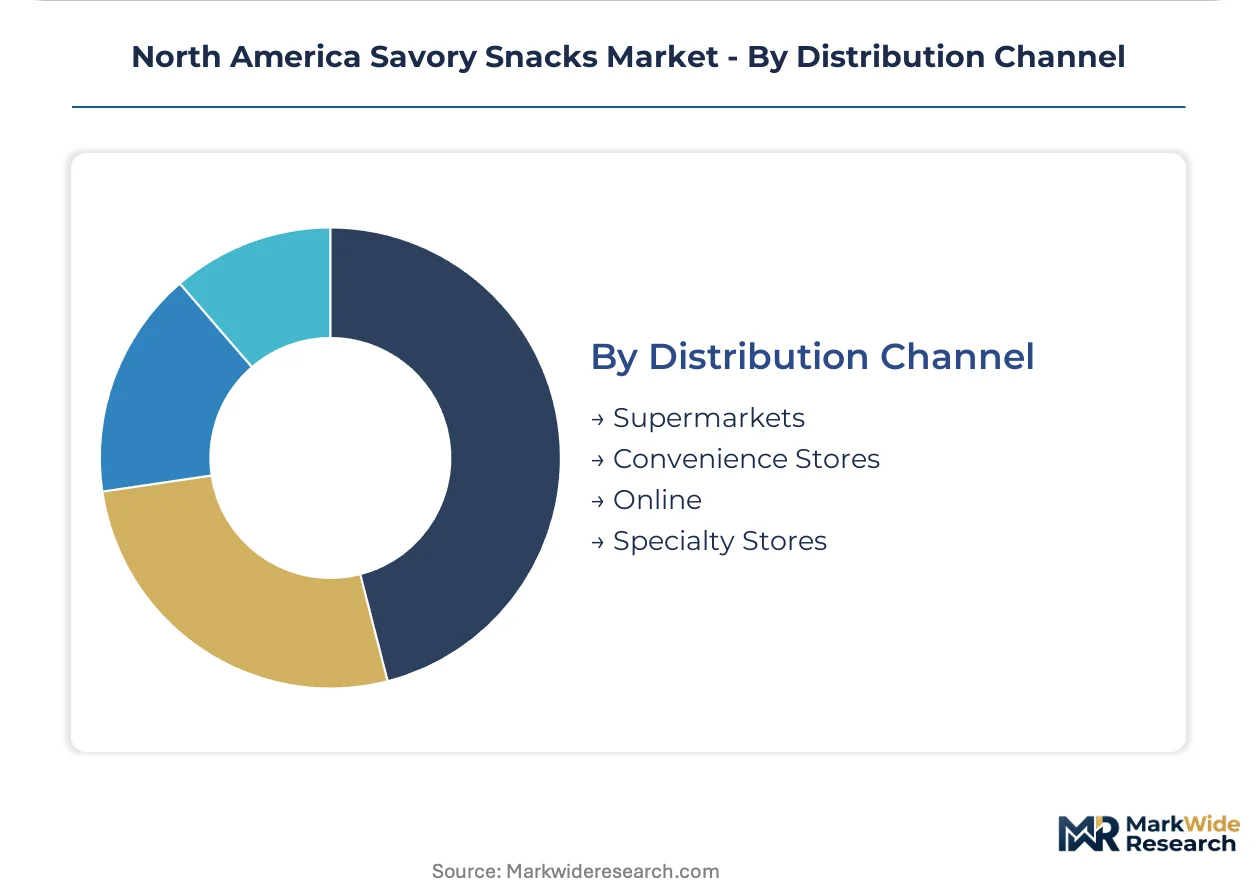
- Supermarkets:These large retail outlets remain the primary channel for savory snack sales, offering extensive product assortments and competitive pricing. Supermarkets cater to planned grocery shopping and bulk purchases for households across North America.
- Convenience Stores:Characterized by smaller footprints and extended hours, convenience stores are critical for impulse purchases and single-serve snack options. The expanding network of convenience stores across the United States and Canada is a significant growth catalyst for the market.
- Online:E-commerce platforms facilitate direct-to-consumer sales and broad product availability, allowing consumers to purchase snacks for home delivery. Online sales are experiencing rapid expansion, driven by convenience and curated selections.
- Specialty Stores:These outlets include natural food stores, gourmet shops, and independent retailers, often stocking premium, artisanal, or niche savory snack brands. Specialty stores cater to consumers seeking unique flavors and ingredient-conscious products.
Traditional retail continues to lead through Supermarkets, yet digital platforms like Online are seeing accelerated adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumer demand for savory snacks concentrates in North America, driven by convenience and evolving flavor preferences. The market, valued at $165.4 Billion in 2026, is projected to reach $252.22 Billion by 2035. This expansion reflects a dynamic interplay between indulgence and health-focused innovations.
United States
Demand for traditional potato chips remains robust across the broader United States market. The U.S. FDA’s proposed front-of-pack labeling rules are driving widespread reformulation efforts for many snack categories. Major urban centers like New York and Chicago exhibit strong demand for premium, spicy flavor profiles.
Canada
Canadian consumers show a rising preference for healthier snack options, including nuts and popcorn varieties. Health Canada mandates concerning sodium content limits influence product development significantly across the country. Toronto and Vancouver metropolitan areas lead in the adoption of artisanal and niche snack categories.
Mexico
Mexican snack consumption is increasing, particularly for bold and spicy flavors, driven by a young demographic. The country's food safety regulations ensure product quality and ingredient transparency for local and imported goods. Mexico City represents a key hub for new product introductions and distribution within the region.
California
California consumers prioritize plant-based and functional snack options, influencing national trends. State-level health initiatives often complement federal guidelines on nutritional transparency. Los Angeles and San Francisco metropolitan areas are focal points for plant-based snack innovation and direct-to-consumer models.
North America Savory Snacks Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue niche flavor profiles and healthier ingredients. The North America savory snacks market exhibits a tiered structure, with large incumbents dominating core segments while smaller challengers innovate rapidly. Strategic archetypes include diversified food conglomerates, regional specialists, and health-focused startups. Companies primarily engage in portfolio diversification and geographic expansion, alongside targeted M&A, to secure and expand market share.
At the scale-driven end, PepsiCo exemplifies a diversified food conglomerate, leveraging its vast distribution network to command significant share in core chip segments across North America. Utz Brands represents a regional specialist, focusing on strong local brand presence and cultivating brand loyalty within specific geographies through targeted product offerings. Mondelēz International occupies a position as an innovator within the cracker and savory biscuit space, continually introducing new products that align with evolving consumer preferences for permissible indulgence and diverse flavor profiles. These players highlight the varied strategies employed to capture market segments.
| Leading Market Players |
|---|
| The Kraft Heinz Company |
| Kellanov |
| PepsiCo |
| Conagra Brands |
| Utz Brands |
| Mondelēz International |
| General Mills |
| WISE |
| The Hershey Company |
| Others |
Cost & Logistics Intelligence
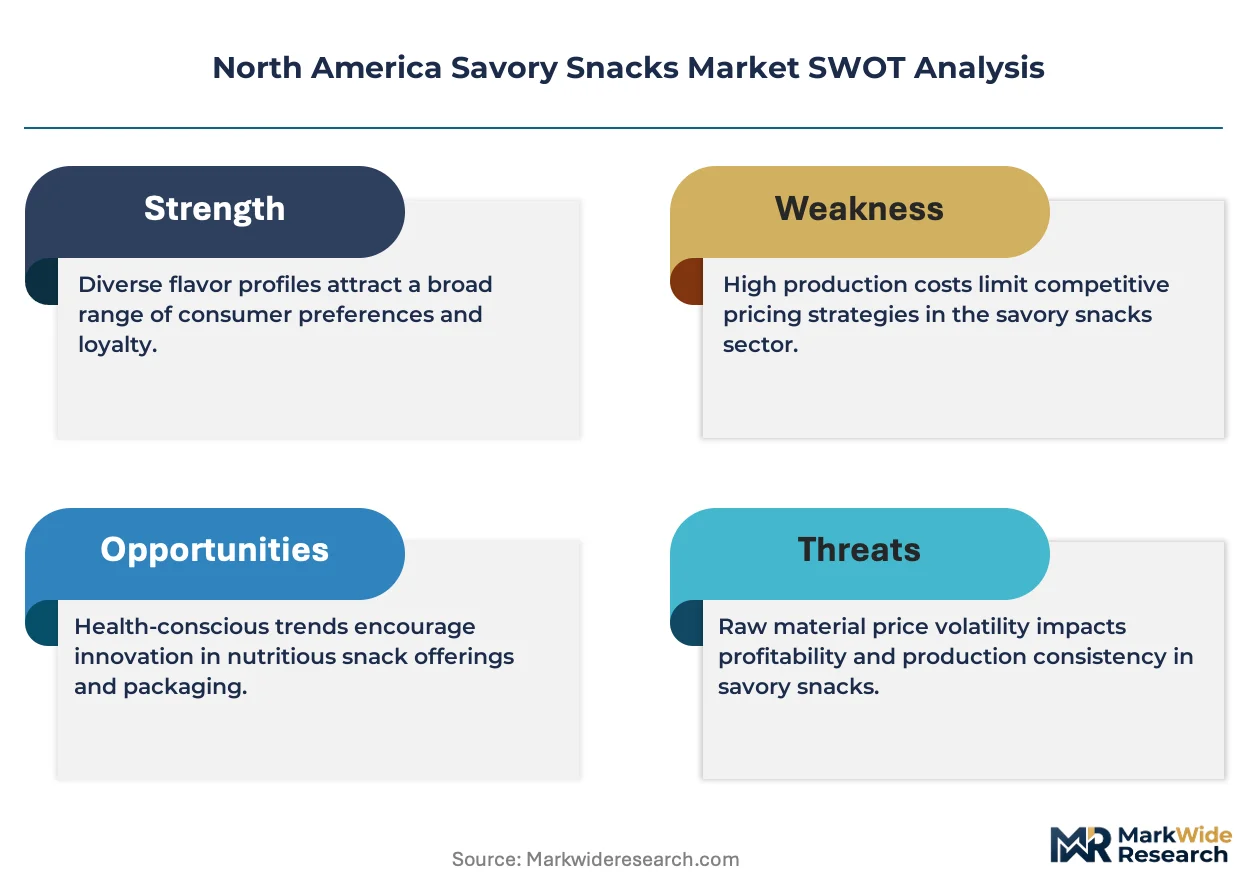
Health Canada mandates concerning sodium content limits gate both qualified savory snack supply and premium-tier pricing access for healthier product formulations. These regulations drive reformulation costs, impacting final product pricing.
Pricing Analysis
Volume-driven segments like traditional chips experience tighter margins, while niche categories command higher prices. Per-unit transactional pricing dominates the market, with price differentiation stemming from brand premium and ingredient quality. Input cost volatility, particularly for agricultural commodities, creates pricing pressure across all segments. Consumers in urban centers exhibit lower price sensitivity for premium, spicy, and functional snack options, allowing for higher price points.
Supply Chain Analysis
Potato, corn, and wheat supply rests heavily on agricultural production in the United States and Canada, forming the core ingredient base for savory snacks. Key inputs also include cooking oils and specialized packaging materials sourced across North America. Commodity price volatility presents a structural risk to manufacturer margins, demanding robust hedging strategies. Distribution runs through established retail networks, primarily supermarkets and convenience stores.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America savory snacks market is a supply-constrained story, with specialized ingredient sourcing for plant-based and functional snacks propping pricing for innovative products. This scarcity creates opportunities for focused investment.
For Market Incumbents:Acquire specialized extrusion technology to diversify product offerings beyond traditional fried snacks. This defends against emerging entrants leveraging plant-based innovation and mitigates the threat of evolving FDA front-of-pack labeling rules. Investing in advanced R&D for natural preservatives is a critical lever to manage shelf-life challenges.
For New Entrants and Emerging Players:Enter via direct-to-consumer models, targeting health-conscious consumers in major metropolitan areas like Los Angeles and Toronto. Focus on plant-based snacks made from chickpeas or lentils, leveraging transparent, clean-label ingredient lists. An effective go-to-market angle involves subscription boxes offering curated, functional snack assortments.
For Investors and Strategic Acquirers:Widespread adoption of FDA front-of-pack nutritional symbols is the leading indicator that will reshape market valuations long-term. Acquisition targets should be agile, mid-sized brands specializing in baked, non-potato snack alternatives with strong regional distribution. Watch for sustained shifts in consumer purchasing behavior away from traditional fried options.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Plant-Based Ingredient Sourcing | Secures supply of alternative proteins like lentils and chickpeas for health-focused product lines. |
| Expand Direct-to-Consumer (DTC) Channels | Cultivates direct customer relationships and gathers valuable data on niche consumer preferences. |
| Reformulate for Sodium Reduction | Ensures compliance with Health Canada and U.S. FDA mandates, avoiding potential market restrictions. |
| Acquire Regional Specialty Brands | Expands geographic footprint and gains access to established distribution networks in specific markets. |
| Implement Advanced Extrusion Technology | Enables rapid development of diverse textures and non-traditional flour bases for new snack products. |
Research Approach
Multi-period observation of consumer purchasing patterns and regulatory shifts anchored the trend analysis, supplemented by interviews with industry stakeholders. Primary research engaged brand managers, R&D directors, retail buyers, and supply chain leads across North America. Secondary data sources included government food safety reports, trade association publications, and company financial filings. Bottom-up market sizing was triangulated with top-down validation.
An input-output matrix structured the quantitative model, projecting market evolution across the analysis window. Segmentation dimensions modeled included product type, flavor profile, packaging type, and distribution channel, alongside ingredient innovation. Compound annual growth rates were derived from historical trends and anticipated shifts in consumer demand. Key forecast inputs included commodity price projections and regulatory compliance timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under significant shifts in commodity prices or unforeseen regulatory changes. The forecasts reflect assumptions documented regarding market dynamics and technological adoption. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Vegan Snacks Market
Snacks
Nuts and Seeds (Savory Snacks) Market
Snacks
Fat Free Snacks Market
Snacks
Seafood Snacks Market
Snacks
Low Calorie Granola Market
Snacks
Better for You Snacks Market
Snacks
Europe Snacks Food Market
Snacks
South America Snack Bar Market
Snacks
North America Baked Savory Snacks Market
Snacks
Tortilla Mix Market
Snacks
Dried Fruit Snacks Market
Snacks
Low-Fat Tortillas Market
Snacks
Italy Energy Bar Market
Snacks
Forti Flakes Market
Snacks
Pretzels (Savory Snacks) Market
Snacks
Snack Bar Market