
 North America Baked Savory Snacks Market | 2026-2036
North America Baked Savory Snacks Market Size, Share, and Industry Trends Forecast 2026-2036
North America Baked Savory Snacks Market Analytics
Canada is reshaping competitive dynamics through expanded baked snack manufacturing capacity in Ontario and Quebec. PepsiCo leverages its direct-store-delivery network to dominate convenience channel placement. General Mills sustains R&D intensity around whole-grain formulations for its cracker portfolio. Kellanova anchors North American pretzel production with specialized baking infrastructure.
Baked savory snacks encompass flour-based or extruded products subjected to oven-based thermal processing rather than oil frying, typically achieving moisture content below four percent for shelf stability and crispy texture; their primary commercial purpose is delivering portable, ready-to-eat flavor experiences in retail and foodservice channels. Crackers occupy the largest volume position due to household pantry penetration and multipack formats, while gluten-free ingredient formulations capture the fastest expansion as celiac awareness and wheat-avoidance diets proliferate across health-conscious consumer segments. Supermarkets retain the dominant distribution share, though online retail channels are accelerating as subscription snack boxes and direct-to-consumer fulfillment reshape repurchase behavior.
The FDA governs nutrition labeling and health claims, while the USDA oversees grain-based ingredient standards and organic certification pathways for baked savory products. Canada's CFIA enforces bilingual labeling and allergen management rules that shape cross-border product specifications. Stakeholders must monitor evolving sodium reduction targets and front-of-package labeling mandates that will determine which formulations maintain retail access.
Market Dynamics
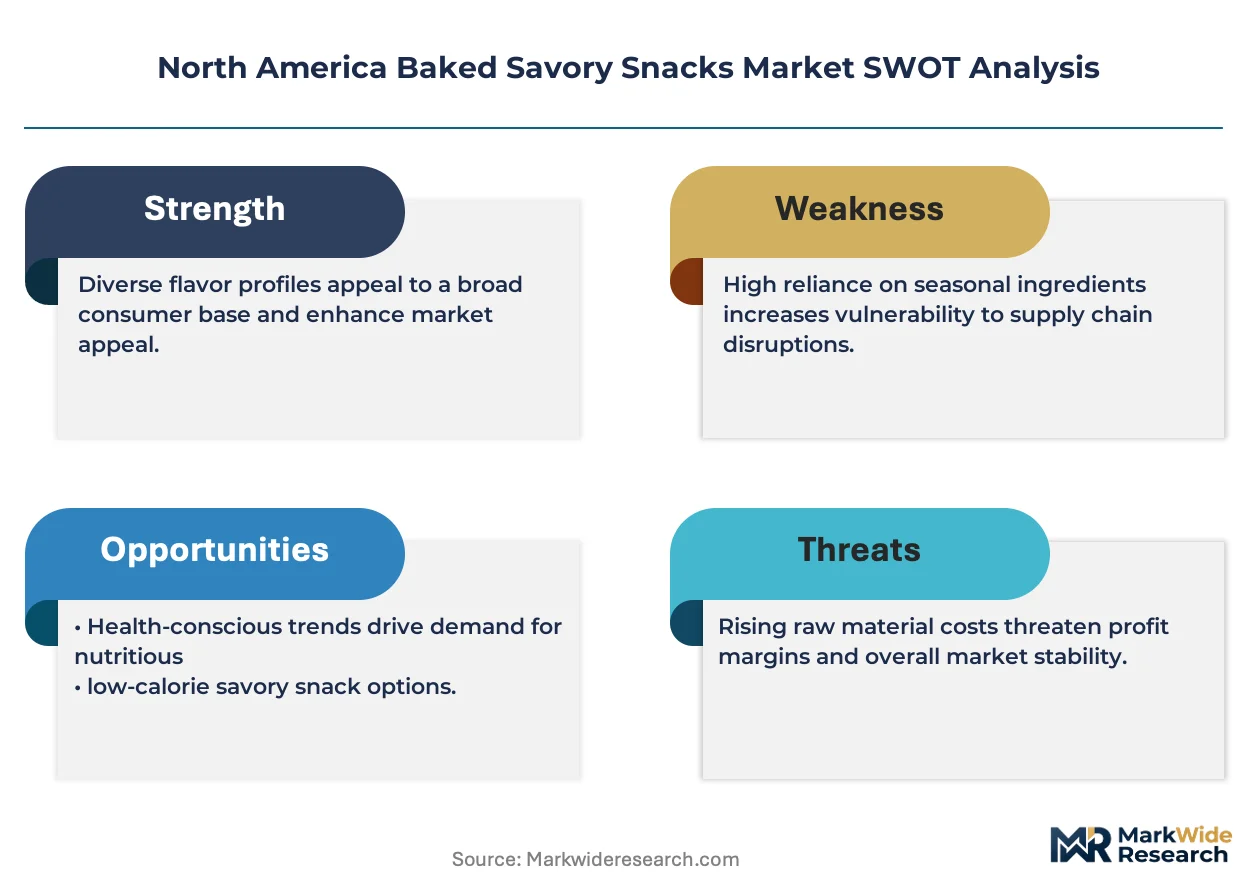
The FDA's updated Nutrition Facts labeling rules and sodium reduction mandates are forcing baked savory snack manufacturers toward reformulation investments, compressing margins while opening shelf space for compliant products.
Growth Catalysts
- Clean-label reformulation:Consumer demand for shorter ingredient lists drives adoption of natural preservatives and whole-grain bases. The USDA organic certification pathway accelerates product development pipelines.
- Convenience channel expansion:Urban millennial households in coastal US metros generate pull-through for portable, single-serve formats. Convenience stores allocate incremental shelf space to better-for-you options.
- Gluten-free ingredient innovation:Celiac awareness and wheat-avoidance diets expand addressable demand. Alternative flour suppliers in Canada scale capacity to meet North American formulation requirements.
Market Restraints
- Input cost volatility:Wheat and alternative grain prices fluctuate with climate-driven harvest variability. The Great Plains drought cycles compress ingredient sourcing margins.
- Supply concentration risk:Specialized baking infrastructure for extruded snacks clusters in Ontario and Quebec. Cross-border logistics dependencies create vulnerability to CFIA inspection delays.
- Technical shelf-life limitations:Reduced-sodium formulations face moisture retention challenges below four percent target. Clean-label preservatives extend stability less predictably than synthetic alternatives.
Strategic Opportunities
- Subscription snack box penetration:Direct-to-consumer fulfillment bypasses traditional retail slotting fees. Urban coastal markets show highest repurchase velocity for curated savory assortments.
- Front-of-package labeling readiness:Anticipated FDA mandates create first-mover advantage for compliant portfolios. Early reformulation investments secure preferred placement as rules finalize.
- Foodservice portion-pack expansion:Office and hospitality channels underutilize baked savory formats relative to fried alternatives. Single-serve multipacks align with institutional procurement specifications.
Industry Challenges
- Reformulation R&D timeline compression:Sodium reduction targets outpace sensory science capabilities. Product developers balance taste parity against clean-label requirements.
- Allergen management complexity:CFIA bilingual labeling rules and FDA disclosure standards diverge on precautionary statements. Dual-compliance packaging increases production changeover costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Baked Savory Snacks Market |
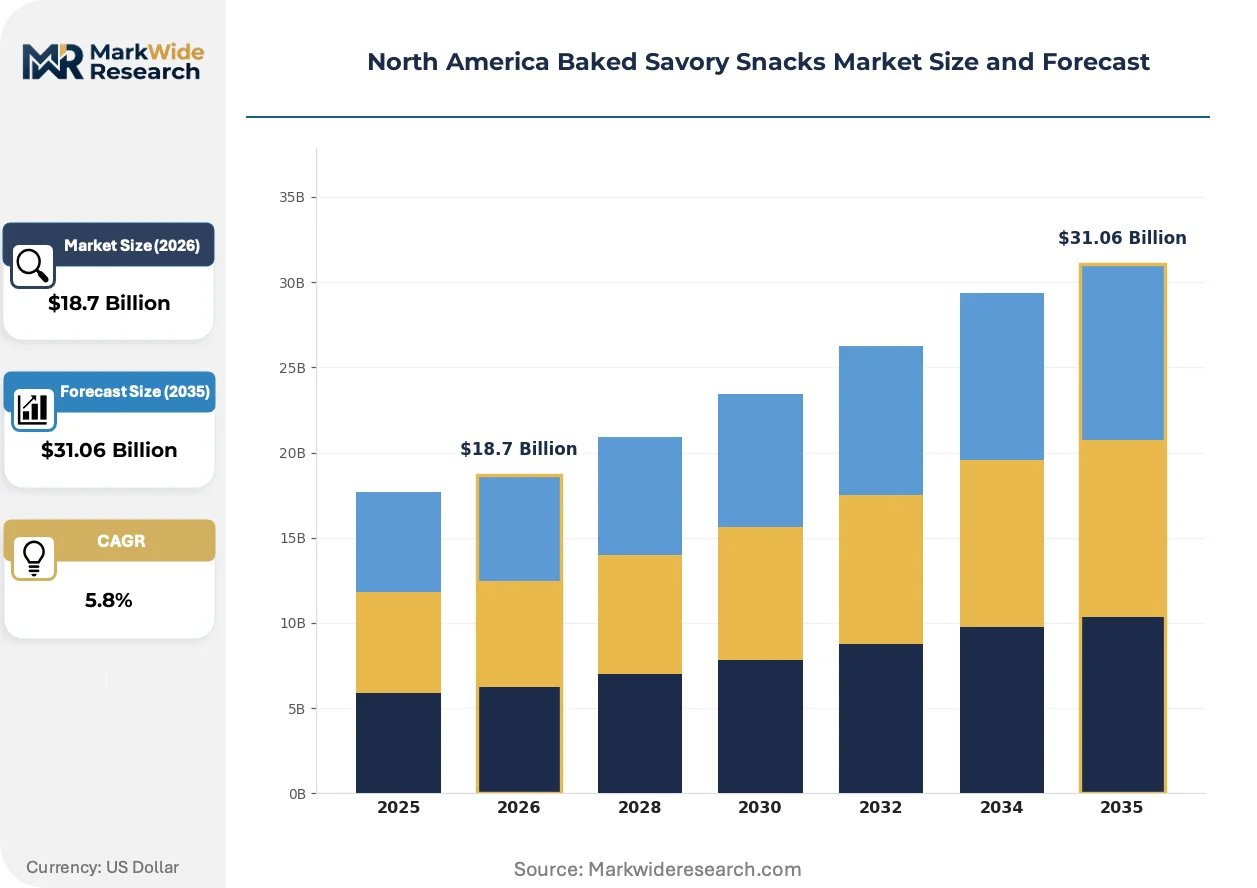
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Crackers, Chips, Pretzels, Cheese Snacks Ingredient: Whole Grain, Gluten-Free, Cheese, Spices Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Specialty Stores Customer Type: Health-Conscious Consumers, Families, Students, Professionals |
| Companies Covered | General Mills, Campbell Soup Company, PepsiCo, The Kraft Heinz Company, Utz Brands, Mondelez International, Conagra Brands, Calbee, Kellanova, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Baked Savory Snacks Market Evolving Landscape
Reformulation science and distribution technology are converging to reshape how baked savory snacks reach health-conscious consumers. Three developments dominate strategic planning.
Hybrid thermal processing is hybridizing conventional oven baking with infrared and microwave finishing stages. Mid-tier manufacturers adopt these systems to achieve fried-like texture without oil immersion. The technology is hybridizing equipment investment decisions, compressing the performance gap between established baking lines and emerging hybrid configurations.
The FDA's updated Nutrition Facts panel mandates disclosure of added sugars and revised serving sizes. Reformulation teams prioritize sodium reduction to maintain permissible health claims. Cracker portfolios face the steepest compliance burden given their household pantry penetration and multipack consumption patterns.
Millennial buyers in US urban coastal markets now source repeat purchases through subscription snack boxes rather than supermarket restocking trips. Direct-to-consumer fulfillment platforms displace traditional distributor relationships for niche and premium formulations. This channel rotation concentrates in California, New York, and Pacific Northwest metropolitan corridors where delivery density supports unit economics.
North America Baked Savory Snacks Market Segmentation
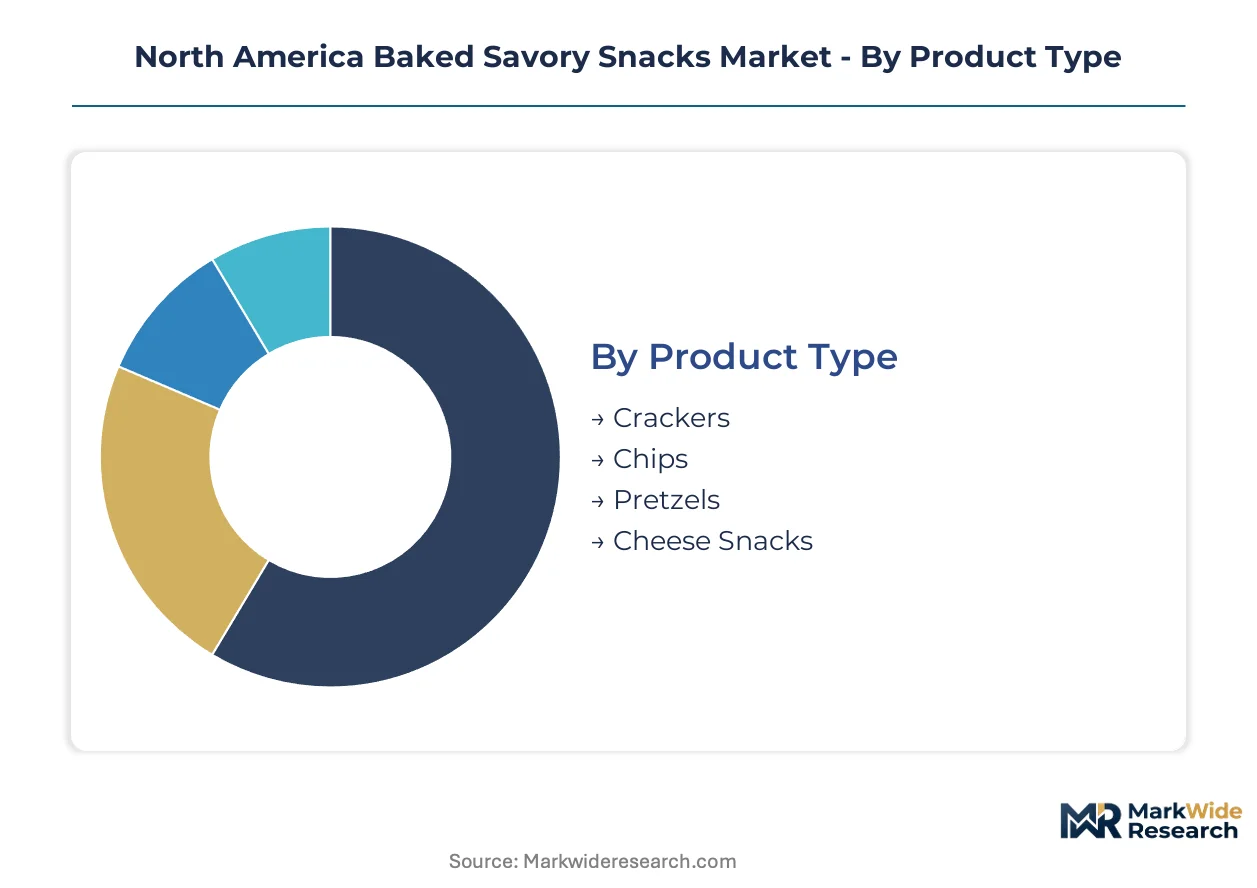
Segmentation in baked savory snacks reveals how formulation choices, channel access, and buyer priorities fragment demand across distinct commercial battlegrounds. Manufacturers must align R&D pipelines and distribution investments with the specific technical and behavioral requirements of each slice.
Product Type:
Volume concentration across product formats reflects household penetration rates and consumption occasion patterns.
- Crackers:Flour-based, sheeted or rotary-molded products achieving moisture content below four percent through controlled oven thermal processing. Demand concentrates in US urban coastal households where pantry stocking and multipack formats dominate repeat purchase behavior; sodium reduction mandates from the FDA drive reformulation complexity.
- Chips:Extruded or sheeted products subjected to oven baking rather than oil frying, delivering crispy texture through controlled moisture removal. Health-conscious millennials in California and New York metro areas generate pull-through for better-for-you positioning against fried alternatives.
- Pretzels:Dough-based products formed through extrusion or twisting before alkali treatment and baking.
- Cheese Snacks:Baked products incorporating cheese as primary flavor carrier or structural component.
Crackers hold installed capacity. Chips are rotating up the share rankings.
Ingredient:
Formulation architecture determines margin structure and regulatory exposure across the category.
- Whole Grain:Products incorporating USDA-compliant whole-grain flour bases delivering dietary fiber claims and clean-label positioning. Families in Midwest US markets sustain volume through household pantry penetration; General Mills maintains R&D intensity around cracker portfolio reformulation.
- Gluten-Free:Alternative flour formulations using rice, tapioca, or legume bases to address celiac and wheat-avoidance diets. Celiac awareness expansion across health-conscious consumer segments drives steepest expansion trajectory; Canadian suppliers in Ontario and Quebec scale alternative flour capacity to meet North American demand.
- Cheese:Dairy-based flavor systems and inclusions providing umami profiles and protein content.
- Spices:Botanical and seasoning blends delivering regional flavor profiles and heat levels.
Whole Grain maintains formulation share leadership. Gluten-Free is climbing the fastest.
Distribution Channel:
Channel selection dictates packaging formats, margin structures, and buyer relationship economics.
- Supermarkets:Traditional grocery retail with dominant shelf space allocation and promotional velocity requirements. PepsiCo leverages direct-store-delivery network to secure placement; multipack and family formats align with household restocking trips.
- Online Retail:Direct-to-consumer and third-party marketplace fulfillment bypassing traditional distributor relationships. Subscription snack boxes concentrate repurchase velocity in urban coastal corridors where delivery density supports unit economics.
- Convenience Stores:Small-format retail with single-serve and immediate consumption positioning.
- Specialty Stores:Premium and natural channel retail with curated assortment and higher price points.
Supermarkets retain volume concentration. Online Retail is gaining share fastest.
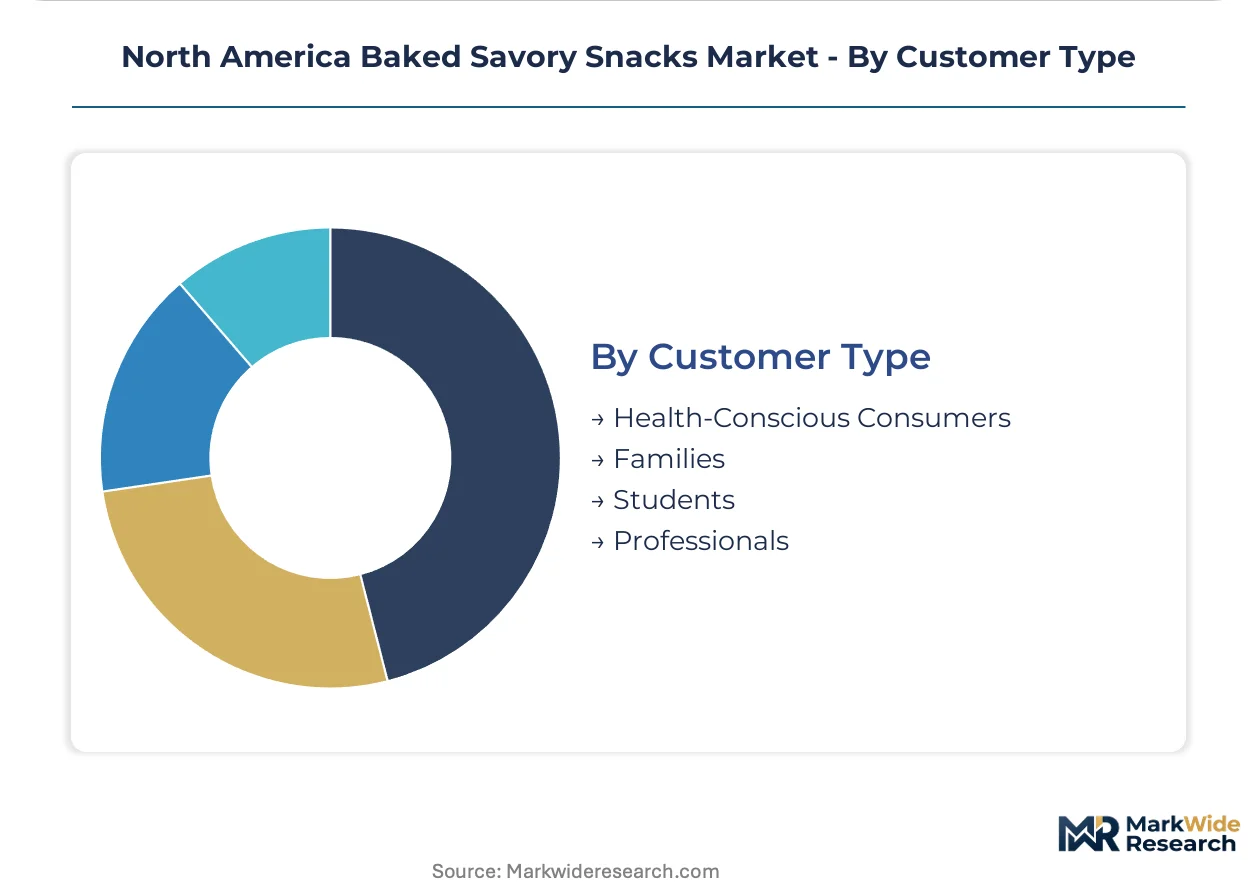
Customer Type:
Buyer identity shapes flavor preference, price sensitivity, and channel selection patterns.
- Health-Conscious Consumers:Buyers prioritizing clean labels, reduced sodium, and functional ingredient claims. Urban coastal millennials drive demand for better-for-you options; FDA sodium reduction targets and front-of-package labeling mandates determine accessible formulations.
- Families:Multi-person households purchasing multipack formats for pantry stocking and lunchbox inclusion.
- Students:Younger buyers seeking portable, affordable single-serve options for on-campus consumption.
- Professionals:Time-constrained workers purchasing convenience formats for office and commuting occasions.
Health-Conscious Consumers anchor premium tier development. Families sustain volume base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized baking infrastructure for extruded snacks clusters in Ontario and Quebec, creating cross-border dependencies that shape North American supply patterns. The FDA's sodium reduction mandates and CFIA's bilingual labeling requirements generate divergent compliance burdens across the region. Urban coastal corridors concentrate demand pull for better-for-you formulations.
United States
Health-conscious millennials in California and New York metro areas drive premium-tier demand for clean-label crackers and chips. The FDA's updated Nutrition Facts labeling rules force reformulation investments across cracker portfolios. PepsiCo leverages its direct-store-delivery network to dominate convenience channel placement in coastal urban markets.
Canada
Alternative flour suppliers in Ontario and Quebec scale capacity to meet North American gluten-free formulation requirements. CFIA enforces bilingual labeling and allergen management rules that shape cross-border product specifications. Kellanova anchors North American pretzel production with specialized baking infrastructure concentrated in the Quebec corridor.
Mexico
Expanding middle-class households in Mexico City and Monterrey generate incremental demand for portable snack formats. The country's national food safety regulator aligns labeling standards with US export requirements for integrated North American supply chains. Grupo Bimbo's manufacturing footprint in Nuevo León supports regional baked goods diversification into savory categories.
North America Baked Savory Snacks Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in ingredient and equipment supply. The North American baked savory snacks market consolidates around diversified food conglomerates with cross-category brand portfolios. Three strategic archetypes dominate: direct-store-delivery network operators, whole-grain formulation specialists, and gluten-free ingredient innovators. Competitive moves center on front-of-package labeling readiness investments and subscription channel partnerships.
Among US-based diversified food manufacturers, General Mills, PepsiCo, and Kellanova occupy distinct archetype positions. General Mills exemplifies the whole-grain formulation specialist through sustained R&D intensity around cracker portfolio development. PepsiCo represents the platform integrator leveraging distribution infrastructure for channel control. Kellanova anchors the specialized baking infrastructure archetype with pretzel-focused production capabilities.
| Leading Market Players |
|---|
| General Mills |
| Campbell Soup Company |
| PepsiCo |
| The Kraft Heinz Company |
| Utz Brands |
| Mondelez International |
| Conagra Brands |
| Calbee |
| Kellanova |
| Others |
Value Network & Pricing Analysis
Ontario and Quebec's specialized baking infrastructure for extruded snacks generates downstream pricing leverage for manufacturers controlling cross-border distribution corridors. Capacity concentration in these provinces tightens ingredient procurement economics for US buyers while amplifying margin capture for integrated operators with captive Quebec production assets.
Pricing Analysis
FDA sodium reduction mandates dictate the pricing tier structure across cracker and chip portfolios, separating reformulation-compliant premium lines from legacy standard formulations facing shelf-space compression. Price differentiation centers on clean-label certification tiers and whole-grain USDA endorsements versus conventional ingredient bases. Cost compression in mid-tier products is intensifying as wheat and alternative grain input volatility from Great Plains drought cycles squeezes formulation margins. Health-conscious millennials in coastal urban markets exhibit lowest price sensitivity, while family pantry buyers in Midwest markets drive volume through promotional responsiveness.
Supply Chain Analysis
CFIA bilingual labeling and allergen management rules function as de facto export controls limiting unidirectional product flows from US facilities into Canadian retail channels. Geographic supply concentration centers on Canada for alternative flour milling, the United States for cracker sheeting and rotary-molded production, and Mexico for regional baked goods diversification. Raw material dependencies draw from North American wheat belts, Canadian legume and rice flour processors, and domestic dairy supply chains for cheese-flavor systems. Single-source vulnerability clusters in Quebec pretzel extrusion infrastructure. Distribution runs through PepsiCo's direct-store-delivery network for convenience channel dominance, supplemented by third-party logistics for subscription box fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against fresh and refrigerated snack alternatives capturing immediate-consumption occasions. Incumbents must navigate the threat of perimeter-store competition eroding center-store baked savory velocity.
For Market Incumbents: Harden formulation moats through accelerated sodium reduction R&D ahead of anticipated FDA front-of-package labeling finalization. Secure backward integration into Ontario alternative flour milling to reduce cross-border procurement exposure. Anchor shelf position by locking multi-year convenience channel contracts before regulatory compliance deadlines reshape available facings.
For New Entrants and Emerging Players: Establish a beachhead in gluten-free subscription snack boxes serving California and Pacific Northwest metro corridors where delivery density supports unit economics. Target white-space in foodservice portion-pack specifications for office and hospitality channels currently underutilizing baked formats. Lead with clean-label positioning and direct-to-consumer fulfillment to bypass traditional retail slotting fee barriers.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified food conglomerates with undermonetized cracker brands lacking reformulation investment. Long-term viability favors operators with Quebec baking infrastructure and USDA organic certification pipelines. Watch CFIA inspection delay frequencies as inflection indicator for cross-border supply chain stress.
| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Reformulation Acceleration | FDA sodium targets and front-of-package mandates favor early movers with compliant portfolios securing preferred retail placement. |
| Direct-to-Consumer Channel Expansion | Subscription snack boxes bypass traditional distributor relationships and concentrate repurchase velocity in urban coastal markets. |
| Alternative Flour Supply Integration | Backward integration into Ontario and Quebec milling capacity reduces cross-border logistics dependencies and input cost volatility. |
| Foodservice Portion-Pack Development | Single-serve multipacks align with institutional procurement specifications in underpenetrated office and hospitality channels. |
| Hybrid Thermal Processing Adoption | Infrared and microwave finishing stages compress the texture gap between baked and fried alternatives without oil immersion. |
Research Methodology
Initial hypotheses were tested against primary input from brand managers, category buyers at supermarkets and convenience chains, supply planners at baked goods manufacturers, and channel sales heads; these were refined through secondary validation against Nielsen retail audit data, FDA labeling guidance documents, USDA grain standards, CFIA regulatory bulletins, and customs trade flow records. Bottom-up volume modeling from SKU-level consumption data was triangulated against top-down category expenditure estimates.
Demand-supply balance dynamics anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, ingredient formulation, distribution channel, and customer archetype. CAGRs were derived from regression analysis of historical volume trends adjusted for regulatory phase-in schedules and channel migration patterns. Forecast inputs incorporated FDA rulemaking timelines, convenience store shelf-space reallocation announcements, and subscription box subscriber growth trajectories.
Stress conditions across wheat price volatility bands, CFIA inspection throughput rates, and sodium reduction compliance cost scenarios were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory implementation pacing and consumer clean-label preference persistence. Material shifts in FDA front-of-package labeling finalization timing or CFIA cross-border inspection protocols would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Refrigerated Snacks Market
Snacks
Organic Snack Food Market
Snacks
Superfoods-Based Packaged Snacks Market
Snacks
Marshmallow Market
Snacks
Mushroom Based Jerky Market
Snacks
Asia Pacific Frozen Snacks Market
Snacks
Seafood Snacks Market
Snacks
United Kingdom Snack Bar Market
Snacks
Austria Snack Bar Market
Snacks
South Africa Snack Bar Market
Snacks
Roasted Snacks Market
Snacks
Asia Pacific Tortilla Market
Snacks
Granola Bars Market
Snacks
Pretzel Salts Market
Snacks
Europe Snacks Market
Snacks
Baked Savoury Snacks Market