
 North America Sweet Biscuits Market | 2026-2036
North America Sweet Biscuits Market Size, Share, and Industry Trends Forecast 2026-2036
North America Sweet Biscuits Market Analytics
Premium clean-label ingredient specifications is reorganizing competitive dynamics in North America sweet biscuits. Mondelez International leverages its integrated supply chain to secure consistent cocoa and wheat sourcing across Mexico and the United States. Pepperidge Farm differentiates through heritage positioning and controlled distribution in specialty retail channels. Grupo Bimbo anchors production scale with continental bakery networks that compress unit economics in core cookie segments.
North America sweet biscuits comprise flour-based baked goods containing added sugars, fats, and flavoring agents, typically achieving moisture content below 5% through controlled oven drying to ensure shelf stability and crisp texture. These products serve as convenience snacking items, dessert accompaniments, and portable energy sources for consumer and foodservice channels. Cookies maintains the largest revenue footprint across product type segments, while online retail distribution is expanding fastest as fulfillment infrastructure penetrates secondary metropolitan areas. Wafer biscuits concentrates margin pools in gift and seasonal packaging formats where premiumization tolerates higher price points.
The FDA governs nutrition labeling and health claims for sweet biscuits sold in the United States, while Health Canada and PMRA administer parallel standards for products entering Canadian provinces. Both frameworks are tightening scrutiny on added-sugar disclosures and front-of-pack labeling, compelling manufacturers to reformulate recipes or absorb compliance costs. Stakeholders must monitor whether state-level sugar tax proposals in the United States gain legislative traction, as these would fragment pricing power across sub-regional markets and force channel-specific portfolio adjustments.
Market Dynamics
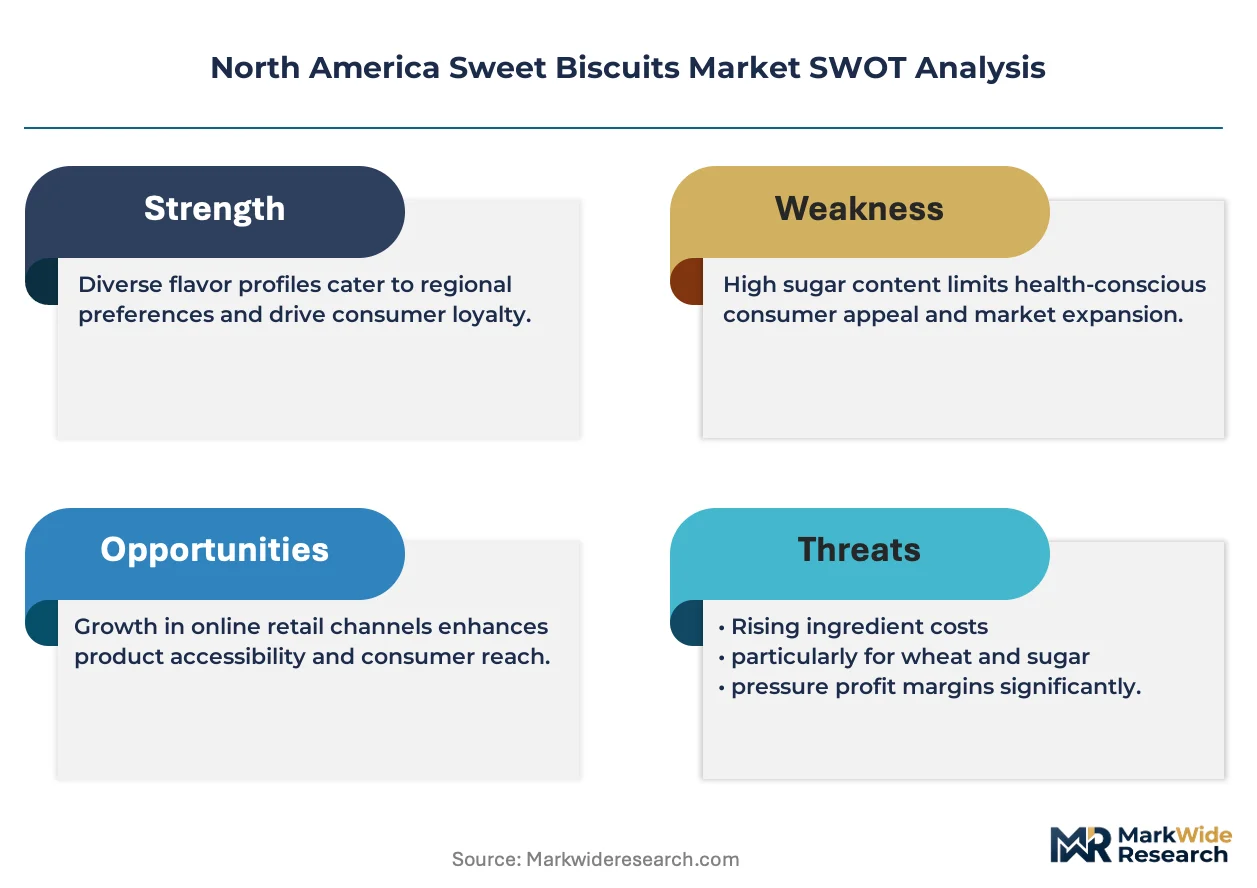
The FDA's updated Nutrition Facts labeling rules for added sugars are forcing manufacturers to reformulate recipes or absorb compliance costs, fundamentally altering product development priorities and competitive positioning across the United States and Canada.
Growth Catalysts
- Snacking normalization in working-age households:Dual-income families across the United States and Canada prioritize portable convenience foods, creating sustained pull-through demand for single-serve sweet biscuit formats.
- Health Canada's front-of-pack labeling modernization:Regulatory clarity on added-sugar thresholds enables manufacturers to develop compliant product lines with marketing advantages in Canadian provinces.
- E-commerce fulfillment infrastructure:Amazon and regional grocery delivery platforms are penetrating secondary metropolitan areas, unlocking distribution reach previously constrained by traditional retail shelf space.
Market Restraints
- Cocoa price volatility:West African supply concentration and climate variability compress margins for chocolate-coated biscuit segments, forcing hedging costs or recipe adjustments.
- Wheat protein quality divergence:North American milling wheat specifications vary across the Great Plains and Canadian prairies, creating batch consistency challenges for standardized production lines.
- Substitution by fresh bakery:In-store bakery programs at Kroger, Loblaws, and Walmart capture occasion-based purchases with perceived freshness advantages over packaged alternatives.
Strategic Opportunities
- Mexico manufacturing expansion:Lower input costs and USMCA tariff advantages position Mexican production hubs for export into the United States Southeast and Southwest corridors.
- Functional ingredient integration:Collagen, adaptogens, and protein fortification create premium positioning in Pacific Coast wellness-oriented consumer segments.
- Direct-to-consumer subscription models:Curated seasonal assortments bypass retail margin stacking while capturing consumer data for personalization algorithms.
Industry Challenges
- Reformulation R&D timeline compression:FDA compliance deadlines for added-sugar disclosure force accelerated testing cycles that strain quality assurance protocols.
- Legacy ERP integration with e-commerce stacks:Real-time inventory synchronization between manufacturing execution systems and multi-channel fulfillment platforms demands capital-intensive middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Sweet Biscuits Market |
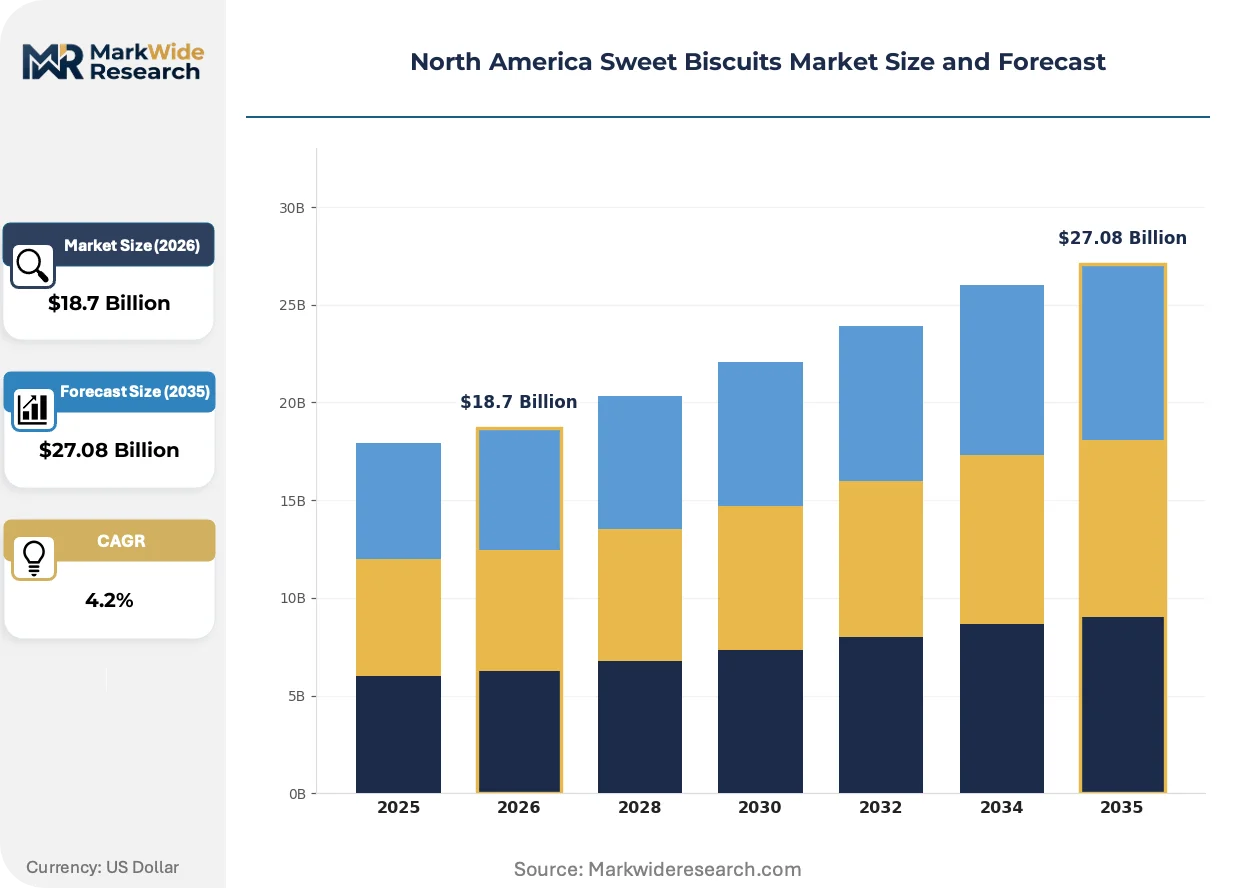
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $27.08 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cookies, Cream-filled, Wafer Biscuits, Shortbread Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Specialty Shops End User: Households, Food Service, Bakeries, Cafés Flavor: Chocolate, Vanilla, Fruit, Nut |
| Companies Covered | Mondelez International, Ferrero Group, Nestlé, Grupo Bimbo, PepsiCo, Kellogg Company, Campbell Soup Company, Pepperidge Farm, Nabisco, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Sweet Biscuits Market Evolving Landscape
Clean-label ingredient specifications and digital commerce infrastructure are fragmenting traditional competitive moats, enabling smaller players to challenge established shelf presence while forcing incumbents to accelerate innovation cycles.
Precision fermentation-derived dairy alternatives are fragmenting the conventional butter and cream inputs that historically anchored premium cookie texture profiles. Artisanal bakeries in Portland, Austin, and Toronto are adopting these ingredients at pilot scale. The technology is fragmenting supply chain relationships as manufacturers bypass traditional dairy cooperatives for direct biotechnology partnerships.
The FDA's updated Nutrition Facts labeling rules mandate added-sugar disclosure with specific gram quantities and percent daily value calculations. Manufacturers must reformulate or accept front-of-pack transparency that disadvantages legacy recipes. Wafer biscuits and sandwich cookies with high sugar-to-flour ratios face the steepest compliance pressure in United States distribution.
Working-age households are consolidating snacking occasions into fewer, higher-quality purchases rather than volume-based stockpiling. Club channels and bulk formats are losing share to premium single-serve packaging in specialty retail and online subscriptions. This behavioral rotation is most pronounced in the United States Pacific Coast corridor where wellness positioning commands price premiums.
North America Sweet Biscuits Market Segmentation
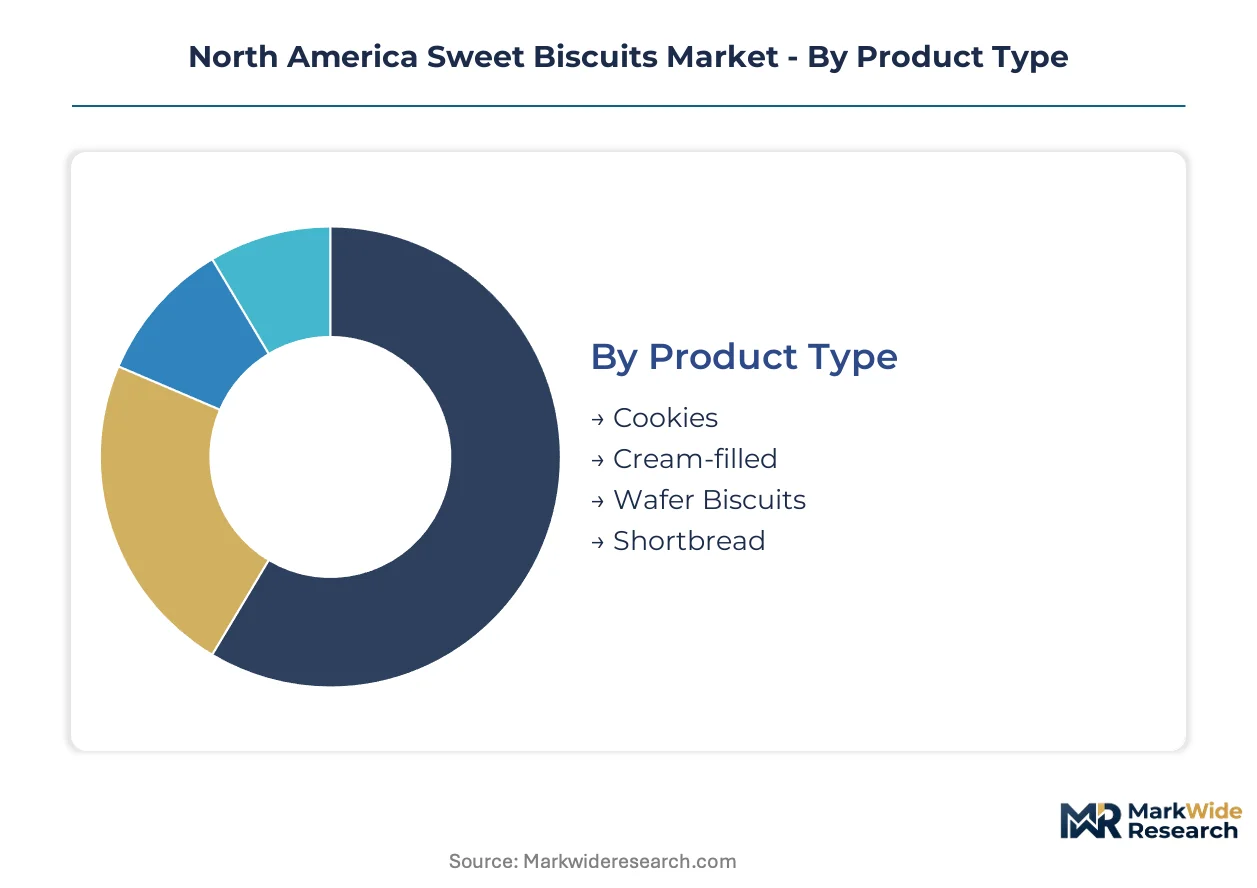
Segmentation in North America sweet biscuits reveals how substitution pressures from fresh bakery and wellness-oriented snacks concentrate differently across product formats. Understanding these fault lines enables manufacturers to allocate reformulation investments toward segments with defensible positioning.
Product Type:
Fresh in-store bakery programs at Kroger and Loblaws exert the strongest substitution pressure on shelf-stable formats, with vulnerability varying sharply by moisture content and occasion positioning.
- Cookies:Flour-based formulations with moisture content below 5% achieve extended shelf stability through controlled oven drying. Demand concentrates in United States Southeast corridor households where convenience snacking dominates daily routines despite front-of-pack labeling scrutiny from FDA added-sugar disclosure rules.
- Wafer Biscuits:Layered constructions with cream or chocolate interleaving depend on precise humidity control during cooling tunnels. Pacific Coast wellness-oriented consumers drive premiumization in gift and seasonal formats where higher price points absorb cocoa volatility from West African supply concentration.
- Cream-filled:Sandwich constructions with fat-based fillings face accelerated reformulation timelines under FDA compliance deadlines for added-sugar transparency.
- Shortbread:High butter-to-flour ratios create tender, crumbly textures vulnerable to precision fermentation dairy alternatives disrupting traditional supply relationships.
Cookies anchors the volume base while Wafer Biscuits gains share at the steepest rate.
Distribution Channel:
Cost tier stratification separates capital-intensive fulfillment infrastructure from legacy shelf-space economics, with margin compression accelerating in mid-tier retail formats.
- Supermarkets:Traditional shelf-space allocation through category management programs faces erosion from in-store bakery expansion at Walmart and Kroger. United States Midwest and Southeast corridors maintain the highest household penetration for planned stock-up purchases.
- Online Retail:Amazon and regional grocery delivery platforms penetrate secondary metropolitan areas with subscription models that bypass retail margin stacking. Real-time inventory synchronization demands strain legacy ERP integration with multi-channel fulfillment stacks.
- Convenience Stores:Impulse-oriented single-serve formats capture working-age household snacking consolidation into fewer, higher-quality purchases.
- Specialty Shops:Curated assortments in Portland, Austin, and Toronto pilot clean-label and functional ingredient integrations at premium price points.
Supermarkets retains the largest transaction volume while Online Retail climbs the fastest.
End User:
Application-based demand fragmentation splits between at-home consumption stability and foodservice recovery patterns, with channel-specific formulation requirements diverging.
- Households:Dual-income families across United States and Canada prioritize portable single-serve formats for consolidated snacking occasions. Health Canada front-of-pack labeling modernization creates marketing advantages for compliant product lines in Canadian provinces.
- Food Service:Portion-controlled dessert accompaniments for institutional catering require batch consistency despite North American milling wheat specification divergence across Great Plains and Canadian prairies.
- Bakeries:Ingredient inputs for downstream processing face competition from captive in-house production at integrated retail chains.
- Cafés:Premium positioning alongside beverage programs tolerates higher price points for artisanal and heritage-positioned offerings.
Households commands the revenue base while Food Service rebounds most sharply.
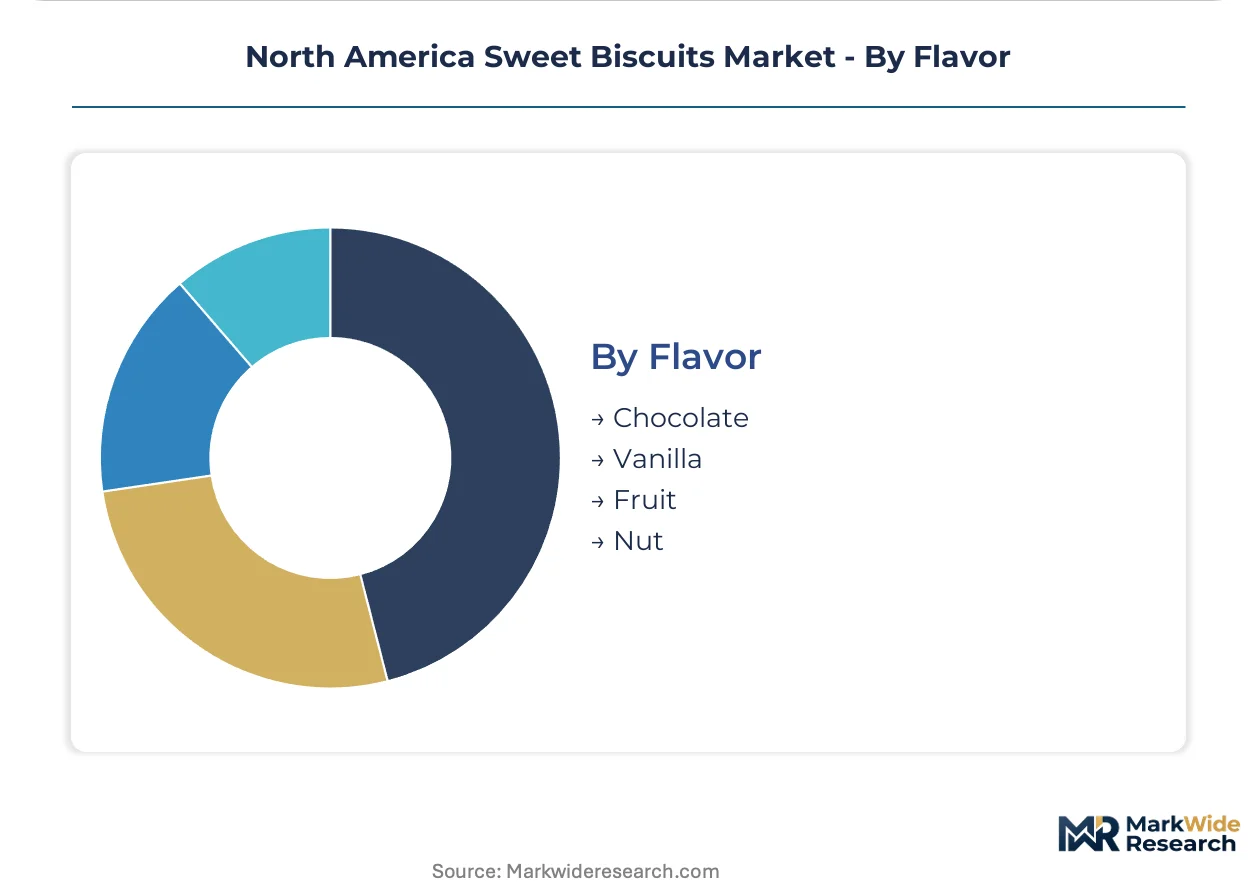
Flavor:
Maturity gradients separate established comfort preferences from emerging wellness-positioned alternatives, with cocoa-dependent segments carrying concentrated margin risk.
- Chocolate:Cocoa mass and butter formulations face the steepest compliance pressure under FDA added-sugar disclosure rules for sandwich cookies and coated varieties. West African supply concentration and climate variability force hedging costs or recipe adjustments.
- Vanilla:Synthetic and natural extract specifications vary by regulatory threshold between United States and Canadian frameworks.
- Fruit:Filled and topped varieties leverage perceived natural positioning for front-of-pack marketing advantages.
- Nut:Almond and hazelnut inclusions command premium tier pricing in Pacific Coast wellness corridors.
Chocolate dominates absolute volume while Nut expands most quickly in premium positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cross-border trade flows within the USMCA zone are intensifying as Mexican production hubs leverage tariff advantages to serve United States distribution networks. Canadian ingredient quality standards create export opportunities for prairie wheat suppliers. Regional demand patterns diverge sharply between convenience-oriented southern corridors and wellness-focused Pacific markets.
United States
The Southeast corridor sustains the highest per-capita consumption of single-serve sweet biscuit formats among working-age households. FDA added-sugar disclosure rules compel reformulation investments ahead of compliance deadlines. Chicago and Atlanta anchor manufacturing clusters where Mondelez International and Pepperidge Farm maintain integrated production and distribution networks.
Canada
Dual-income families in Ontario and Quebec consolidate snacking occasions into premium single-serve purchases. Health Canada front-of-pack labeling modernization creates marketing advantages for compliant product lines entering retail channels. Toronto and Montreal serve as test markets for clean-label ingredient specifications before United States rollout.
Mexico
Lower input costs and USMCA tariff positioning attract capacity expansion for export-oriented production. Mexican food safety regulations under COFEPRIS align with FDA import requirements for seamless cross-border shipment. Monterrey and Mexico City Metro host Grupo Bimbo continental bakery networks supplying the United States Southwest corridor.
North America Sweet Biscuits Market Competitive Landscape
Concentration sits with multinational packaged food conglomerates controlling shelf-stable bakery categories across North American retail channels. The vendor base clusters around three strategic archetypes: integrated snack conglomerates with cocoa and wheat sourcing advantages, heritage-positioned specialty brands commanding premium price points, and continental-scale bakery operators compressing unit economics through production density. Dominant competitive moves include backward integration into ingredient supply chains and geographic expansion into Mexican manufacturing hubs.
Among integrated snack conglomerates, Mondelez International and Nestlé occupy positions defined by cross-border supply chain control and brand portfolio breadth. Pepperidge Farm exemplifies the heritage-positioned specialty archetype with controlled distribution in premium retail channels. Grupo Bimbo anchors the continental-scale bakery operator tier with production networks spanning Mexico, the United States, and Canada.
| Leading Market Players |
|---|
| Mondelez International |
| Ferrero Group |
| Nestlé |
| Grupo Bimbo |
| PepsiCo |
| Kellogg Company |
| Campbell Soup Company |
| Pepperidge Farm |
| Nabisco |
| Others |
Value Network & Pricing Analysis
Ninety-day cocoa inventory cycles at North American processors now determine margin buffers across chocolate-coated biscuit segments, binding pricing power to West African harvest timing and futures market liquidity. This inventory-to-pricing linkage concentrates cost volatility in sandwich cookie and wafer formats where cocoa butter ratios exceed formulation thresholds.
Pricing Analysis
Industrial foodservice buyers anchor contract pricing across institutional channels, while retail pricing stratifies across premium heritage-positioned, standard mass-market, and economy private-label tiers. Price differentiation hinges on clean-label certification status and controlled distribution in specialty retail channels. Pricing pressure intensifies in mid-tier supermarket formats as in-store bakery programs at Kroger and Walmart capture occasion-based purchases with perceived freshness premiums. Private-label buyers at club channels exhibit highest price sensitivity, whereas Pacific Coast wellness-oriented consumers tolerate steep premiums for functional ingredient fortification.
Supply Chain Analysis
West African cocoa belt concentration—Côte d'Ivoire, Ghana, and Nigeria—underwrites raw material vulnerability for chocolate-dependent biscuit segments, with single-source dependency amplifying climate and political risk exposure. Wheat sourcing draws from Great Plains and Canadian prairies milling networks, with protein specification divergence creating batch consistency challenges. Tariff exposure through USMCA renegotiation risk threatens cross-border manufacturing economics at Mexican export hubs. Distribution runs through integrated retail replenishment systems and Amazon fulfillment centers penetrating secondary metropolitan corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North America sweet biscuits sits in early-cycle expansion as e-commerce fulfillment infrastructure penetrates secondary metropolitan areas and unlocks distribution reach previously constrained by traditional retail shelf economics.
For Market Incumbents: Fortify backward integration into prairie wheat sourcing networks and Mexican manufacturing capacity to compress unit economics against Grupo Bimbo continental scale. Accelerate ERP middleware development for real-time inventory synchronization with multi-channel fulfillment platforms. Prioritize clean-label certification investment ahead of FDA compliance deadlines to defend shelf positioning against private-label encroachment.
For New Entrants and Emerging Players: Anchor in Pacific Coast wellness corridors where functional ingredient integration commands premium price tolerance and brand loyalty remains unsettled. Target direct-to-consumer subscription models for curated seasonal assortments that bypass retail margin stacking. Exploit white-space in precision fermentation-derived dairy alternatives disrupting traditional butter supply relationships for shortbread and premium cookie formats.
For Investors and Strategic Acquirers: Carve-out targets emerge from multinational packaged food conglomerates seeking portfolio rationalization of regional biscuit brands with heritage positioning but underutilized distribution infrastructure. Five-to-ten year viability favors operators with integrated Mexican production capacity and USMCA tariff positioning. Monitor state-level sugar tax legislative traction as inflection signal for channel-specific portfolio restructuring urgency.
| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Reformulation | FDA added-sugar disclosure rules force recipe transparency that disadvantages legacy formulations. |
| Mexico Manufacturing Expansion | USMCA tariff advantages position Monterrey hubs for Southeast and Southwest corridor supply. |
| Direct-to-Consumer Subscription | Amazon and regional grocery delivery platforms unlock secondary metropolitan penetration. |
| Functional Ingredient Integration | Collagen and adaptogen fortification captures Pacific Coast wellness premium pricing. |
| ERP-E-Commerce Integration | Real-time inventory synchronization demands capital-intensive middleware development. |
Research Methodology
Initial hypotheses were tested against primary input from brand managers at multinational conglomerates, category buyers at Kroger and Loblaws, supply planners at integrated bakery networks, and channel sales heads at specialty retail distributors, then refined through secondary validation against Nielsen retail audit data, FDA labeling guidance documents, USMCA customs records, and SEC 10-K filings from packaged food operators. Bottom-up volume builds triangulated with top-down macroeconomic anchors across the analysis window.
Variance decomposition across product type, distribution channel, and regional demand clusters shaped the analytical framework, with CAGRs derived from segment-level growth rate reconciliation against aggregate market expansion. Modeled inputs included cocoa futures price trajectories, wheat protein specification divergence across North American milling regions, and e-commerce penetration curves in secondary metropolitan statistical areas.
Decision-makers should treat outputs as directional under stable USMCA tariff assumptions and FDA compliance timeline adherence; material deviation would warrant model refresh. Practitioners should keep alternative scenarios live as state-level sugar tax proposals and West African supply disruptions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
Dough Whitener Market
Bakery Products
Qatar Bakery Product Market
Bakery Products
Healthy Biscuits Market
Bakery Products
South America Ice Cream Market
Bakery Products
Europe Bakery Products Market
Bakery Products
Low-Gluten Emmer and Einkorn Flour Blends Market
Bakery Products
GCC Frozen Bakery Products Market
Bakery Products
Global Baked Food and Cereals Market
Bakery Products
Gluten-Free Bakery Market
Bakery Products
Lentil Bread Market
Bakery Products
Southeast Asia Bakery Products Market
Bakery Products
Pastry Dough Market
Bakery Products
Asia-Pacific Baked Food and Cereals Market
Bakery Products
Baked Foods Market
Bakery Products
Low Calorie Muffins Market
Bakery Products
India Cake Market