
 Snack Bar Market | 2026-2036
Snack Bar Market Size, Share, and Industry Trends Forecast 2026-2036
Snack Bar Market Intelligence
Convenience store shelf resets is reconfiguring how impulse snack bar purchases convert at checkout. Clif Bar & Company leverages its organic ingredient sourcing to sustain premium positioning in natural retail. Mars Incorporated anchors its portfolio through mass-market chocolate-coated formats that dominate c-store coolers. General Mills competes via cereal-bar heritage brands that extend manufacturing scale into co-manufactured protein lines.
A snack bar is a shelf-stable, individually wrapped food item typically comprising cereals, nuts, dried fruits, protein isolates, and binding syrups extruded or cold-pressed into a cohesive bar form, designed for portable consumption between meals. Protein Bars occupy the highest-margin tier as functional fortification commands price premiums, while Granola Bars represent the mature volume base with compressed margins and private-label encroachment. Nutritional Bars targeted at meal-replacement occasions are gaining velocity in Online Retail and Health Food Stores where ingredient transparency drives conversion.
FDA nutrition labeling rules and the USDA organic certification program shape permissible health claims and ingredient sourcing standards in the United States. The EU Green Deal packaging directives and REACH chemical safety frameworks constrain wrapper composition and additive use across European supply chains. Stakeholders must monitor evolving front-of-package warning label regimes and bio-based material certifications to preserve market access and margin structure.
Market Dynamics
Clean-label reformulation pressure is fragmenting manufacturing scale advantages as co-manufacturers absorb capital-intensive extrusion capacity from branded players seeking asset-light flexibility.
Growth Catalysts
- EU Green Deal packaging mandates:Bio-based wrapper material requirements are accelerating supplier R&D partnerships with cellulose innovators and compostable film specialists across European supply chains.
- Protein fortification technology:Cold-pressed protein binding systems are enabling cleaner ingredient decks that convert health-conscious buyers in natural retail channels.
- United States:Club channel shelf resets favoring functional nutrition are pulling incremental volume into protein-fortified and low-sugar formats at checkout.
Market Restraints
- Almond and whey protein input volatility:California drought cycles and dairy commodity swings compress margin predictability for nut-based and dairy-protein formulations.
- Co-manufacturer concentration:North American extrusion capacity clusters with three contract manufacturers, creating bottleneck risk for mid-tier brands scaling distribution.
- Front-of-package warning regimes:Latin American sugar threshold labeling is forcing reformulation or market exit for legacy high-syrup granola formats.
Strategic Opportunities
- Meal-replacement positioning:Nutritional bars targeting intermittent fasting protocols are gaining velocity in online retail where subscription models lock recurring revenue.
- USDA organic certification tailwinds:Premium shelf placement incentives in natural retail are pulling conventional brands into certified supply chain investments.
- Convenience channel cooler expansion:Refrigerated protein bar sets are displacing ambient displays in c-store chains, creating new impulse purchase occasions.
Industry Challenges
- Clean-label R&D talent scarcity:Formulation chemists skilled in natural binding systems without synthetic additives command premium compensation and extended recruitment timelines.
- Organic certification compliance duration:Three-year transition requirements for ingredient suppliers delay product launches and tie up working capital.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Snack Bar Market |
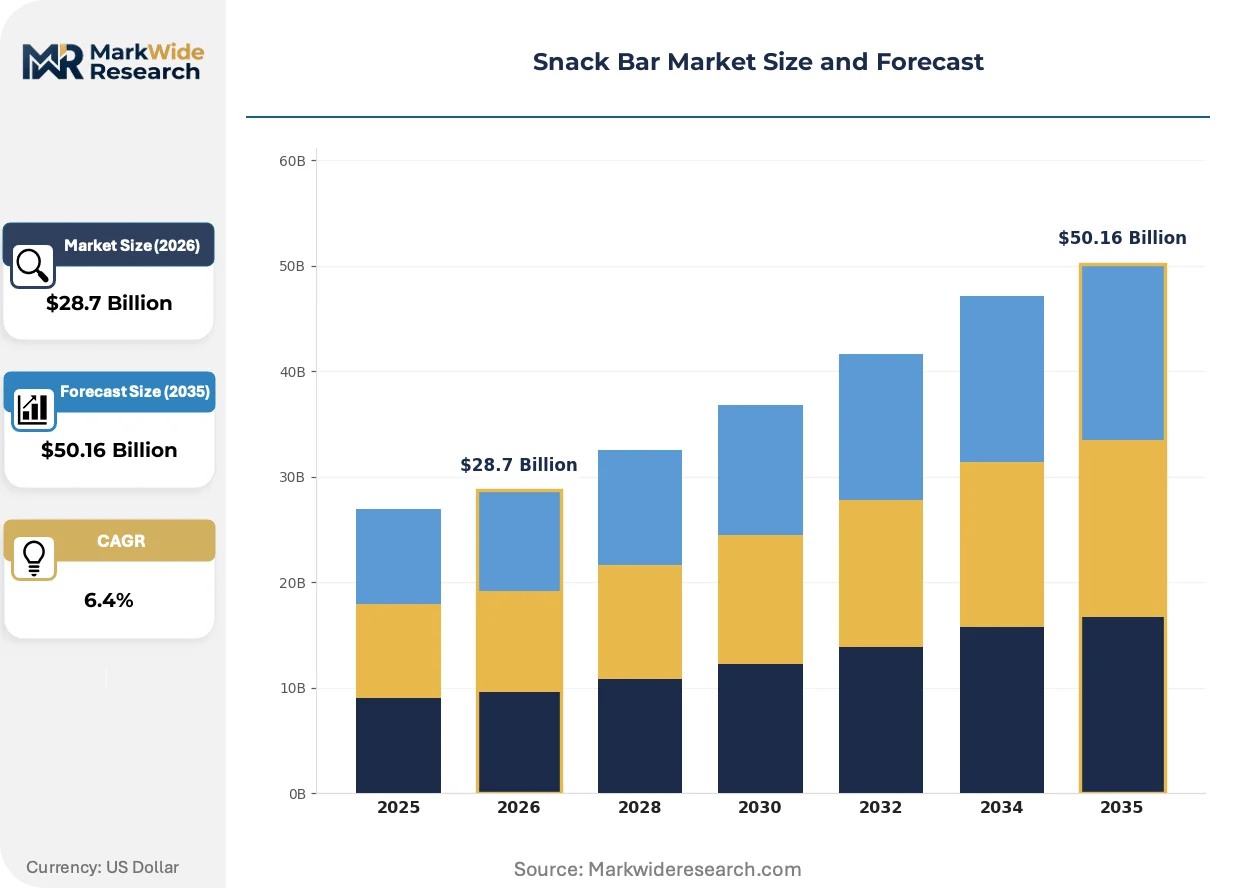
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $50.16 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Protein Bars, Granola Bars, Trail Mix Bars, Nutritional Bars Packaging Type: Boxed, Pouch, Wrapper, Bulk Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Health Food Stores Customer Type: Fitness Enthusiasts, Busy Professionals, Students, Health-Conscious Consumers |
| Companies Covered | PepsiCo, Clif Bar & Company, General Mills, The Nature's Bounty Company, Quest Nutrition, Kellogg Company, Mars Incorporated, Kind LLC, Mondelez International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Snack Bar Market Strategic Shifts & Innovations
Active packaging material transitions and binding technology advances are compressing traditional formulation advantages while regulatory compliance costs reshape competitive capital allocation.
Plant-protein extrusion technology is migrating from batch thermal processing to continuous cold-press systems that preserve amino acid integrity without denaturation. Natural retail buyers and performance-oriented consumers are adopting these formats at accelerating rates. This migration from heat-processed isolates is enabling cleaner label claims that command shelf price premiums in club and specialty channels.
EU Green Deal packaging directives are mandating recyclable or compostable wrapper substrates by specified compliance windows. European supply chains are absorbing reformulation costs and passing through price adjustments to preserve margin structure. Protein bar segments with higher price elasticity are responding fastest through bio-based film partnerships.
Subscription-based replenishment models are displacing single-unit impulse purchases in direct-to-consumer channels. Online retail and health food store operators are building auto-ship infrastructure that locks buyer loyalty and reduces customer acquisition costs. United States metropolitan markets with dense fitness culture penetration show the highest subscription attach rates for functional nutrition bars.
Snack Bar Market Segmentation
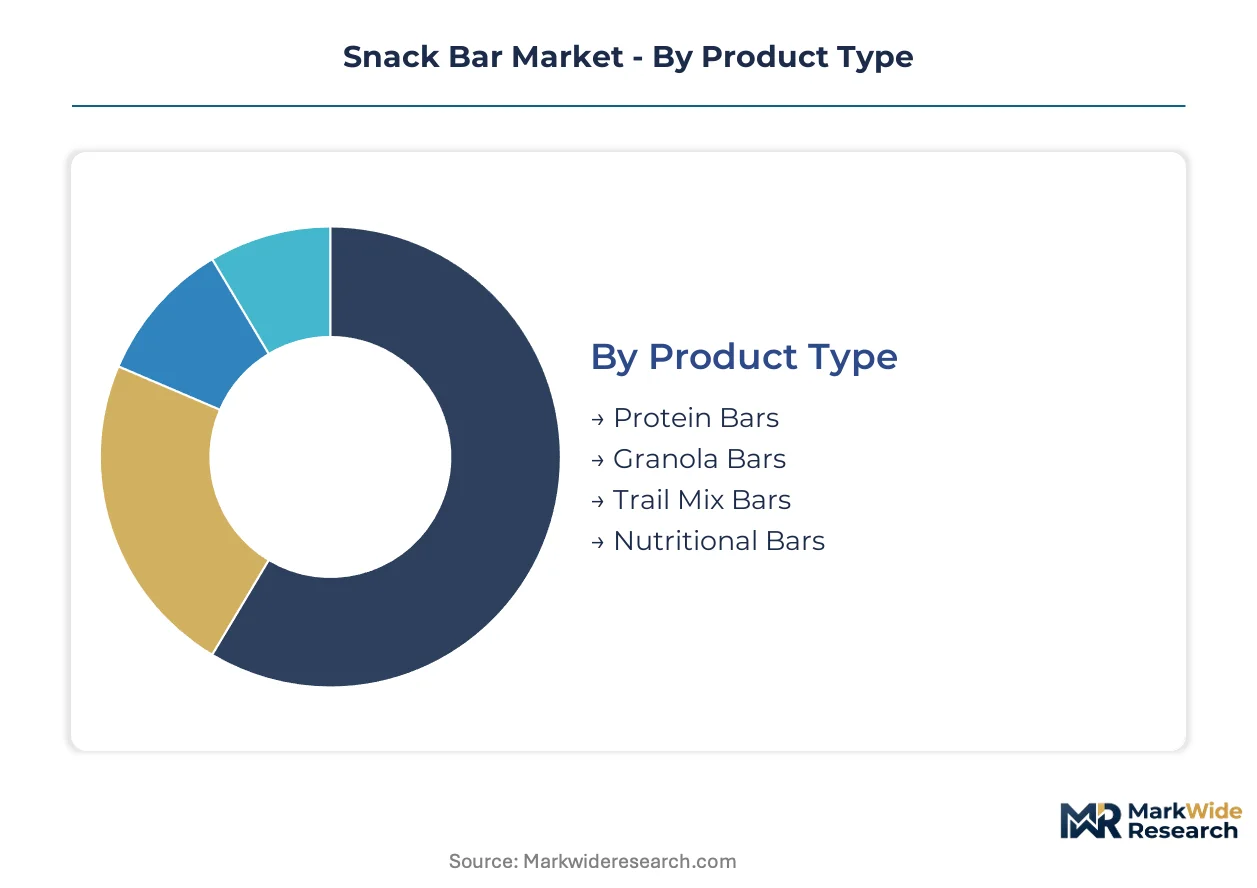
Segmentation in the snack bar market determines where margin pools concentrate and which reformulation investments yield shelf access. Cycle times vary dramatically across product formats, with protein-fortified lines turning inventory faster than legacy granola while packaging regulations force wrapper material transitions at uneven speeds.
Product Type:
Protein Bars turn inventory fastest in club and fitness channels, while Granola Bars rotate slowest as private-label compression extends replacement cycles.
- Protein Bars:Cold-pressed or extruded formulations combining whey, plant isolates, or collagen with binding syrups, targeting 15-30g protein per serving. Demand concentrates in United States metropolitan fitness corridors where subscription models lock recurring revenue.
- Granola Bars:Baked oat and honey clusters with dried fruit inclusions, the mature volume base facing compressed margins. Private-label encroachment in United States supermarkets is forcing branded players toward premium ingredient differentiation or exit.
- Trail Mix Bars:Whole nut and dried fruit combinations with minimal processing, appealing to outdoor recreation segments.
- Nutritional Bars:Meal-replacement formulations with micronutrient fortification, gaining velocity in intermittent fasting protocols through online retail auto-ship infrastructure.
Granola Bars dominate installed base volume. Protein Bars are where expansion concentrates.
Packaging Type:
Cost tiers separate premium bio-based wrappers from commodity films, with compliance deadlines driving divergence in European supply chains versus United States flexibility.
- Wrapper:Individual flow-wrap films in polyethylene or emerging cellulose substrates, the standard for impulse channels. EU Green Deal mandates are accelerating supplier partnerships with compostable film specialists across Germany, France, and Netherlands supply chains.
- Boxed:Multi-unit cardboard cartons for club channel bulk purchase, carrying lower per-unit packaging cost but higher shelf space requirements.
- Pouch:Resealable flexible bags for multi-bar formats, common in online retail fulfillment.
- Bulk:Unwrapped or minimal-packaging formats for foodservice and institutional channels, bypassing retail labeling requirements.
Wrapper formats command the highest unit volume. Boxed formats are climbing the fastest as club channel resets favor multi-unit purchase.
Distribution Channel:
Customer type concentration varies sharply by channel, with Health Food Stores indexing highest on ingredient transparency while Convenience Stores prioritize cooler placement and checkout visibility.
- Online Retail:Direct-to-consumer and third-party marketplace fulfillment, where subscription auto-ship models reduce customer acquisition costs. United States metropolitan markets with dense fitness culture penetration show highest attach rates for functional nutrition bars.
- Convenience Stores:Impulse-oriented cooler and checkout placement, where refrigerated protein bar sets are displacing ambient displays in c-store chains.
- Supermarkets:Center-store and natural foods aisle placement, facing private-label pressure in standard granola formats.
- Health Food Stores:Curated premium assortments where USDA organic certification and clean-label claims drive conversion.
Supermarkets dominate installed base. Online Retail is where expansion concentrates.
Customer Type:
Application occasion separates meal-replacement buyers from snack occasion users, with intermittent fasting protocols creating new usage windows that cut across traditional demographic boundaries.
- Health-Conscious Consumers:Clean-label seekers prioritizing organic certification and ingredient transparency, the fastest-expanding buyer segment reshaping purchasing patterns across all channels.
- Fitness Enthusiasts:Performance-oriented buyers targeting specific macronutrient ratios, concentrated in protein bar subscriptions and specialty retail.
- Busy Professionals:Meal-replacement and desk-snack occasions favoring portability and minimal mess.
- Students:Price-sensitive convenience seekers driving volume in granola and trail mix formats.
Health-Conscious Consumers represent the fastest-growing trajectory. Fitness Enthusiasts anchor premium tier pricing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Long Beach anchors North American distribution for protein isolate imports, while Rotterdam's container terminals handle European flows of bio-based packaging films. These maritime gateways determine where formulation and packaging investments concentrate.
United States
FDA nutrition labeling rules and USDA organic certification programs govern permissible health claims and ingredient sourcing standards. Club channel shelf resets in Texas and Florida metros favor functional nutrition formats at checkout. Cold-pressed protein binding systems from California suppliers enable cleaner label claims commanding premium placement.
Germany
EU Green Deal packaging directives and REACH chemical safety frameworks constrain wrapper composition across Bavarian and North Rhine-Westphalia manufacturing clusters. ECHA compliance deadlines accelerate supplier partnerships with cellulose innovators in Hamburg port zones. German extrusion specialists are absorbing reformulation costs for compostable film transitions.
China
NMPA food safety standards and GB labeling requirements shape import conditions for foreign protein bar brands. Yangtze River Delta manufacturing bases around Shanghai produce binding syrups and oat clusters for regional markets. Cold-chain infrastructure investments in Guangdong province enable refrigerated protein format trials.
United Kingdom
FSA front-of-pack labeling guidelines and post-Brexit divergence from EU food law create compliance complexity for cross-channel suppliers. London metropolitan fitness culture drives subscription model adoption for meal-replacement bars. Midlands co-manufacturing clusters handle extrusion capacity for mid-tier brands scaling distribution.
Brazil
ANVISA nutritional labeling regulations and Mercosur trade protocols govern regional market access. São Paulo state concentrates demand for protein-fortified formats among metropolitan fitness consumers. Sugar threshold warning labels under Latin American regimes force reformulation for legacy granola formats in Rio Grande do Sul production zones.
Snack Bar Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in binding technology and protein isolate supply. The market structures around three tiers: multinational CPG conglomerates with extrusion assets, mid-tier organic specialists leveraging co-manufacturing flexibility, and private-label suppliers compressing margins in mature granola segments. Strategic moves concentrate on portfolio diversification into functional nutrition and backward integration into organic ingredient sourcing.
Within the multinational tier, PepsiCo and General Mills occupy positions anchored by cereal-bar heritage and mass-market distribution scale. Mars Incorporated exemplifies the chocolate-coated format dominance that secures c-store cooler placement. Clif Bar & Company represents the organic specialist archetype sustaining premium positioning through certified supply chain investments.
| Leading Market Players |
|---|
| PepsiCo |
| Clif Bar & Company |
| General Mills |
| The Nature's Bounty Company |
| Quest Nutrition |
| Kellogg Company |
| Mars Incorporated |
| Kind LLC |
| Mondelez International |
| Others |
Cost & Logistics Intelligence
Overcapacity in North American extrusion facilities is pressuring contract manufacturers to absorb reformulation costs and extend payment terms, compressing margin structures for mid-tier brands while concentrating pricing power with three dominant co-manufacturers.
Pricing Analysis
Volume-discount tiering structures separate club-channel bulk purchasers from convenience-store single-unit buyers, with protein-fortified formats commanding shelf price premiums in natural retail channels. Price differentiation rests on USDA organic certification status and cold-pressed processing claims that justify elevated positioning. Cost compression in granola segments is intensifying because private-label encroachment in United States supermarkets forces branded players toward premium ingredient differentiation or exit. Students represent the most price-sensitive segment, while Fitness Enthusiasts anchor premium tier pricing with minimal elasticity.
Supply Chain Analysis
Extended payment terms from European retailers are forcing bio-based wrapper suppliers to absorb working capital strain while scaling cellulose film capacity. Raw material dependencies draw from California almond orchards, Wisconsin dairy processing clusters, and Yangtze River Delta syrup refineries. Supply chain risk centers on California drought cycles that compress margin predictability for nut-based formulations. Distribution runs through Port of Long Beach for protein isolate imports and Rotterdam terminals for compostable film flows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as health-conscious buyer segments reshape purchasing patterns across all channels, with intermittent fasting protocols creating new meal-replacement occasions that cut across traditional demographic boundaries.
For Market Incumbents: Pre-empt co-manufacturer consolidation by securing captive extrusion capacity in Texas and Florida corridor zones before bottleneck risks materialize. Accelerate USDA organic certification investments to defend shelf placement incentives in natural retail channels against emerging certified entrants. Cold-pressed protein binding R&D represents the priority capability lock-up. For New Entrants and Emerging Players: Build out intermittent fasting subscription infrastructure in United States metropolitan fitness corridors where auto-ship models reduce customer acquisition costs. The nutritional bar segment targeting meal-replacement occasions offers the most penetrable white space with minimal incumbent subscription lock-in. Direct-to-consumer launch with influencer partnerships in Los Angeles and Miami metros provides the cleanest go-to-market angle. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across co-manufactured protein lines as branded players shed extrusion assets for asset-light flexibility. Long-term viability favors mid-tier organic specialists with certified supply chain investments and established natural retail relationships. Watch for co-manufacturer M&A activity as the signal indicating consolidation phase entry.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organic Ingredient Sourcing | Captive almond and oat supply from California Central Valley growers locks input cost stability. |
| Cold-Pressed Protein Binding R&D Investment | Preserved amino acid integrity commands premium shelf placement in club channel resets. |
| EU Green Deal Packaging Compliance Partnership | Cellulose film partnerships with Hamburg port zone suppliers preserve European market access. |
| Subscription Auto-Ship Infrastructure Buildout | Recurring revenue models reduce customer acquisition costs in metropolitan fitness corridors. |
| Refrigerated Protein Bar Cooler Expansion | C-store chain cooler placement creates new impulse purchase occasions displacing ambient displays. |
Research Approach
Findings reconcile primary fieldwork against secondary review of FDA nutrition labeling guidance, USDA organic certification databases, EU Green Deal packaging directives, and Nielsen retail audit data. Category buyers at club and convenience channels, co-manufacturing operations directors, protein isolate procurement leads, and natural retail merchandising heads contributed structured input. Bottom-up SKU-level volume builds triangulate against top-down category spend estimates.
Forecast inputs include protein fortification technology adoption curves, EU packaging compliance deadlines, and intermittent fasting protocol penetration rates across metropolitan fitness corridors. Segmentation dimensions span product type, packaging format, distribution channel, and customer application occasion. CAGRs derive from regression against historical volume trajectories and forward projection of regulatory catalysts.
The forecast holds incumbent behavior within observed patterns; aggressive moves by private-label suppliers or co-manufacturer consolidators would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Packaged Rice Snacks Market
Snacks
Salty Puffed Snacks Market
Snacks
Savory Snack Products Market
Snacks
Corn Chips Market
Snacks
Roasted Corn Market
Snacks
Granola Bars Market
Snacks
Oat-Based Snacks Market
Snacks
Healthy Fat-Free Snacks Market
Snacks
Seaweed Snacks Market
Snacks
RTE Popcorn Market
Snacks
Premium Snacks Market
Snacks
North America Potato Chips Market
Snacks
Europe Cereal Bar Market
Snacks
Healthy Snacks Market
Snacks
Saudi Arabia French Fries Market
Snacks
Europe Energy Bar Market