
 Seafood Snacks Market | 2026-2036
Seafood Snacks Market Size, Share, and Industry Trends Forecast 2026-2036
Seafood Snacks Market Insights
Subscription-based replenishment models for resealable bag formats is decoupling volume sales from traditional retail velocity metrics. Taokaenoi Food and Marketing Public Company Limited leverages its Thai manufacturing base to dominate Southeast Asian distribution channels. Gimme Seaweed anchors North American shelf presence through certified organic positioning and broad retail penetration. CJ CheilJedang Corp. extends its Korean food conglomerate infrastructure into premium dried seafood exports across Asian and Western markets.
Seafood snacks encompass processed marine-derived consumables—dried, cured, extruded, or preserved—that typically deliver protein densities exceeding 15 grams per serving and shelf stability through moisture reduction or hermetic sealing. These products serve commercial purposes ranging from impulse retail capture to functional nutrition delivery in on-the-go consumption contexts. Dried fish and fish jerky segments carry mature margin structures rooted in established supply chains across East Asian processing hubs. Seafood chips represent the fastest-growing product type, capitalizing on texture innovation and vegetable-chip crossover appeal among health-conscious consumers. Resealable bag packaging concentrates investment as brands chase repeat-purchase loyalty and pantry-stock positioning in supermarkets and online retailers.
FDA seafood HACCP regulations govern US import safety protocols, while EFSA and REACH frameworks shape European additive and packaging material compliance. South Korea's MFDS maintains strict sodium-labeling and marine-sourcing disclosure requirements that influence formulation decisions for export-oriented manufacturers. Stakeholders must monitor evolving extended producer responsibility mandates for flexible plastic packaging, as these rules will determine which regional production configurations retain cost-competitive market access.
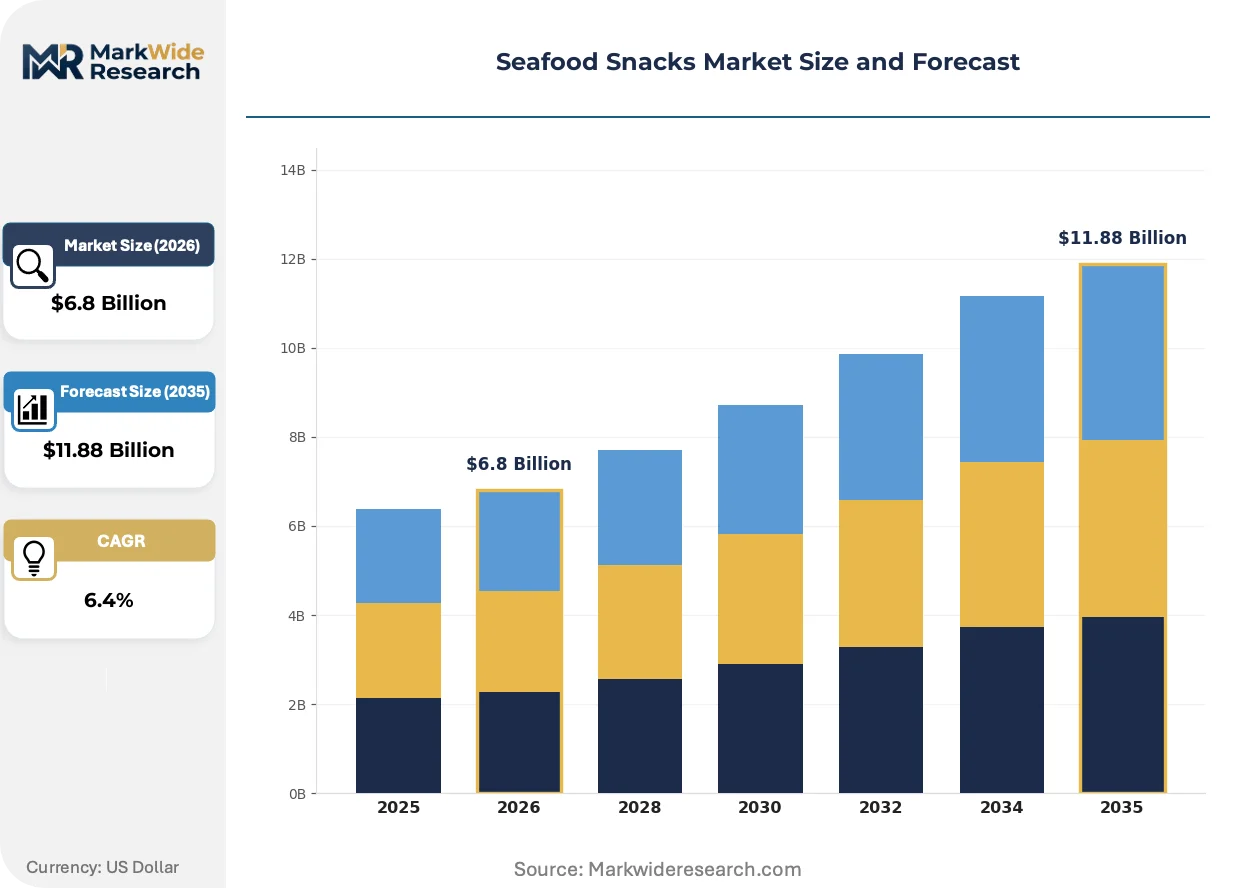
Market Dynamics
Subscription replenishment models are decoupling seafood snack volume sales from traditional retail velocity metrics, forcing manufacturers to redesign packaging formats and loyalty programs around pantry-stock positioning rather than impulse capture.
Growth Catalysts
- EU Packaging Waste Directives:Extended producer responsibility mandates for flexible plastics are accelerating investment in recyclable mono-material films and compostable barrier layers across European manufacturing lines.
- Convenience Store Channel Expansion:High-protein portable formats are capturing expanded shelf space in South Korean and Thai retail networks, anchoring domestic consumption growth and export manufacturing scale.
- Extrusion Technology Advancement:Precision-controlled thermal processing is enabling seafood chip textures that crossover with vegetable-chip appeal, broadening the addressable consumer base beyond traditional dried fish buyers.
Market Restraints
- Wild-Catch Input Volatility:Fluctuating anchovy and mackerel landings in Southeast Asian waters create raw material cost instability that compresses margin structures for dried fish processors.
- Sodium Disclosure Friction:South Korea's MFDS strict labeling requirements for marine-sourcing and sodium content impose formulation constraints that limit product standardization across export markets.
- Plant-Based Protein Substitution:Pea and soy protein isolates in savory snack formats are capturing shelf space and consumer trial among flexitarian demographics seeking alternative protein sources.
Strategic Opportunities
- Resealable Bag Innovation:Hermetic sealing technology combined with subscription-based replenishment models creates repeat-purchase loyalty and direct-to-consumer channel expansion in North American markets.
- Organic Certification Tailwind:USDA and EU organic standards for aquaculture feed and processing are enabling premium positioning that commands price differentiation in supermarket and online retail.
- Thailand Export Manufacturing:Established seaweed and dried fish processing infrastructure positions Thai producers to scale private-label supply for European and North American retail chains seeking Asian-origin authenticity.
Industry Challenges
- HACCP Compliance Timeline:FDA seafood safety protocols for US import certification require 12-18 month validation cycles that delay market entry for new processing facilities and product line extensions.
- Moisture Barrier R&D Gap:Shortage of food scientists specializing in marine protein stabilization and lipid oxidation prevention constrains innovation pipelines for shelf-stable premium formats.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Seafood Snacks Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.88 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dried Fish, Fish Jerky, Seafood Chips, Canned Seafood Packaging Type: Single Serve, Multipack, Resealable Bags, Cans Distribution Channel: Supermarkets, Convenience Stores, Online Retailers, Specialty Stores Customer Type: Health-Conscious Consumers, Busy Professionals, Fitness Enthusiasts, Families |
| Companies Covered | Roland Foods LLC, Annie Chun's Inc., CJ CheilJedang Corp., Sewha Seafood Co. Ltd., Seamore BV, Taokaenoi Food and Marketing Public Company Limited, Gimme Seaweed, Blue Evolution Inc., Eden Foods Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Seafood Snacks Market Trends and Innovations
Texture innovation and packaging sustainability are converging to reshape competitive positioning, with brands racing to deliver sensory differentiation while preempting regulatory compliance deadlines for single-use plastics.
Advanced extrusion systems are absorbing seafood proteins into porous chip matrices that replicate the crunch profile of root vegetable alternatives. Health-conscious millennial and Gen Z buyers in North American supermarkets are adopting these formats at rates outpacing traditional jerky segments. This absorption is compressing the historical dominance of dried whole-fish products by expanding the category's relevance beyond ethnic and heritage consumer bases.
REACH framework restrictions on per- and polyfluoroalkyl substances in food contact materials are forcing European manufacturers to abandon legacy grease-resistant coatings. Industrial consequence includes accelerated R&D spending on bio-based barrier films and pressure-sensitive adhesive alternatives. Premium resealable bag segments in Germany and France are responding fastest, with several mid-cap processors already achieving commercial-scale mono-material validation.
Pantry-stock buying patterns are displacing single-serve impulse purchases as subscription models capture household replenishment routines. Direct-to-consumer channels and Amazon Subscribe and Save are disrupting conventional supermarket velocity metrics that historically determined shelf allocation. This behavioral pivot is most visible in South Korea and urban US coastal markets, where delivery-app integration and micro-fulfillment centers enable same-day restocking of high-rotation SKUs.
Seafood Snacks Market Segmentation
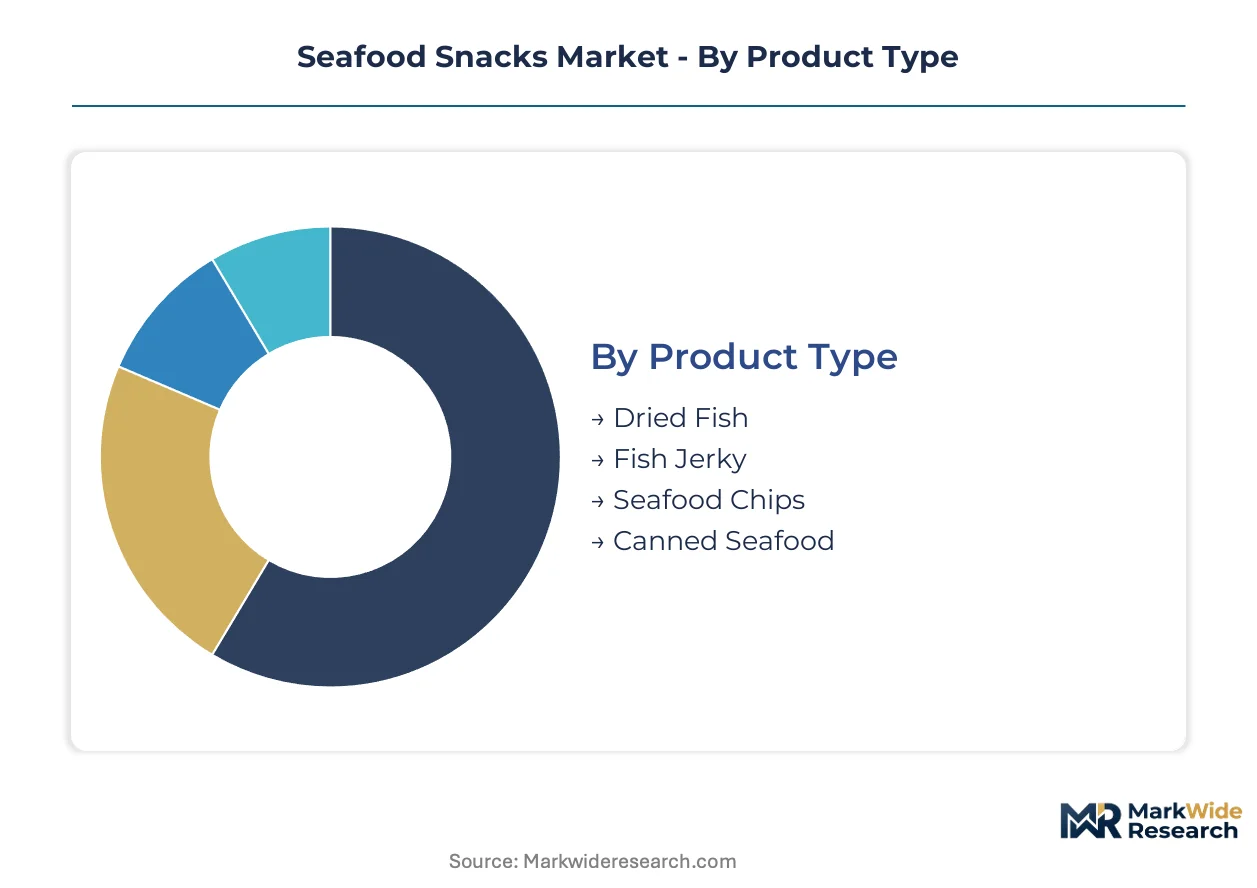
Segmentation in seafood snacks reveals divergent capital requirements and margin profiles across processing technologies and distribution configurations. Manufacturers must align production investments with the specific shelf-stability demands and channel economics of each product and packaging format.
Product Type:
Capital intensity peaks in extrusion-based manufacturing where thermal processing equipment and protein stabilization R&D consume the largest upfront outlays.
- Dried Fish:Traditional moisture-reduction processing through sun-drying or mechanical dehydration yields shelf-stable products with minimal additive requirements. South Korean and Thai coastal processors dominate volume, anchored by heritage consumption patterns and established export infrastructure for anchovy and mackerel variants.
- Seafood Chips:Advanced extrusion systems absorb marine proteins into porous matrices that replicate vegetable-chip crunch profiles. North American supermarket demand is climbing fastest among millennial and Gen Z buyers seeking crossover texture innovation beyond traditional jerky formats.
- Fish Jerky:Cured and smoked whole-muscle preparations require controlled-environment aging facilities and precision humidity management.
- Canned Seafood:Retort processing and hermetic sealing operations demand substantial canning line investment and compliance with FDA low-acid canned food regulations.
Most installed capacity flows through Dried Fish. Expansion is steepest in Seafood Chips.
Packaging Type:
Cost tier separation is sharpest here, with premium barrier materials commanding multiples over commodity formats.
- Resealable Bags:Hermetic sealing technology and mono-material film development absorb the highest packaging R&D budgets as brands chase pantry-stock positioning. Subscription replenishment models in North American direct-to-consumer channels are decoupling volume metrics from traditional retail velocity.
- Single Serve:Individual portion formats dominate impulse capture in convenience stores and vending networks. South Korean and Thai retail expansion is concentrating shelf space allocation for high-protein portable units.
- Multipack:Bundled configurations target household stocking behaviors with per-unit cost advantages.
- Cans:Metal packaging retains dominance in shelf-stable seafood with longest demonstrated durability.
Volume concentrates in Single Serve. Value capture is climbing fastest in Resealable Bags.
Distribution Channel:
Customer acquisition economics vary dramatically between high-frequency convenience formats and loyalty-driven subscription channels.
- Convenience Stores:High-rotation shelf positioning in South Korean and Thai networks is capturing expanded space for protein-forward portable snacks. Channel growth is tethered to urban density and delivery-app integration in coastal US and Asian metro markets.
- Online Retailers:Amazon Subscribe and Save and direct-to-consumer platforms are displacing traditional supermarket velocity metrics with replenishment-based purchasing patterns. Pantry-stock positioning here demands resealable formats and subscription-enabled logistics.
- Supermarkets:Mass retail remains the primary trial channel for new texture innovations.
- Specialty Stores:Curated assortments in natural and organic retailers command premium positioning for certified aquaculture products.
Transaction volume flows heaviest through Supermarkets. Customer lifetime value is expanding fastest in Online Retailers.
Customer Type:
Application urgency separates occasional purchasers from habitual replenishment buyers with distinct formulation priorities.
- Fitness Enthusiasts:Protein density exceeding 15 grams per serving drives formulation specifications and portion architecture. Sodium disclosure requirements under South Korea's MFDS framework constrain standardization for export-oriented manufacturers targeting this segment.
- Health-Conscious Consumers:Organic certification and clean-label positioning command price premiums in North American supermarkets and European retail chains. USDA and EU organic standards for aquaculture feed enable differentiated shelf placement.
- Busy Professionals:On-the-go consumption contexts favor single-serve portability and minimal preparation.
- Families:Multipack configurations and mild flavor profiles target household stocking behaviors.
Current spending concentrates in Health-Conscious Consumers. Purchase frequency is climbing fastest among Fitness Enthusiasts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korea and Thailand command distinct consumption patterns, with Seoul's subscription-driven households outpacing Bangkok's convenience-store velocity in per-capita protein snack spend.
United States
Fitness enthusiasts and pantry-stock subscription buyers drive demand for resealable bag formats. FDA seafood HACCP regulations govern import safety protocols for Asian-origin processors. Seattle and Los Angeles coastal metros anchor direct-to-consumer fulfillment networks for same-day replenishment services.
South Korea
Heritage dried fish consumption and delivery-app integration sustain high-rotation convenience channel growth. MFDS maintains strict sodium-labeling and marine-sourcing disclosure requirements that constrain export formulation standardization. Busan-Ulsan processing clusters dominate anchovy and mackerel dehydration capacity for domestic and export markets.
Thailand
Seaweed and dried fish traditions anchor both domestic consumption and private-label manufacturing for Western retail chains. Extended producer responsibility mandates for flexible plastics are accelerating investment in recyclable mono-material films across European-facing production lines. Bangkok-based processors leverage established infrastructure to scale certified organic output for North American supermarkets.
Germany
REACH framework restrictions on per- and polyfluoroalkyl substances in food contact materials force abandonment of legacy grease-resistant coatings. EFSA additive compliance shapes formulation decisions for marine-protein snack imports. Hamburg and Bremen port logistics clusters facilitate distribution of Asian-origin premium formats into Central European retail networks.
Japan
Traditional surimi and dried seafood consumption patterns persist alongside emerging demand for extruded chip textures among younger demographics. METI industrial standards influence equipment specifications for thermal processing technology imports. Nagoya and Osaka manufacturing belts concentrate precision-controlled extrusion system deployment for domestic and regional export markets.
Seafood Snacks Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with private-label suppliers capturing volume in European supermarket chains while certified organic specialists command premium positioning in North American direct-to-consumer channels. The vendor base organizes into three tiers: multinational food conglomerates with captive seafood processing infrastructure, mid-cap regional specialists leveraging heritage processing knowledge, and emerging extrusion-technology entrants targeting texture innovation. Consolidation pressure is accelerating through strategic partnerships between Asian processors and Western distribution platforms, alongside vertical integration moves into captive aquaculture feed sourcing.
Within the heritage-processing tier, Taokaenoi Food and Marketing Public Company Limited and Sewha Seafood Co. Ltd. exemplify regional specialists that anchor Southeast Asian and Korean supply capacity respectively. Gimme Seaweed occupies a position representing North American organic certification specialists. CJ CheilJedang Corp. sits within the multinational conglomerate archetype, extending Korean food infrastructure into premium export channels across Asian and Western markets.
| Leading Market Players |
|---|
| Roland Foods LLC |
| Annie Chun's Inc. |
| CJ CheilJedang Corp. |
| Sewha Seafood Co. Ltd. |
| Seamore BV |
| Taokaenoi Food and Marketing Public Company Limited |
| Gimme Seaweed |
| Blue Evolution Inc. |
| Eden Foods Inc. |
| Others |
Pricing and Supply Chain Analysis
The EU's extended producer responsibility mandates for flexible plastic packaging gate qualified supply access and premium-tier pricing power, forcing processors to absorb mono-material R&D costs or surrender shelf placement in European retail chains. Buyers with certified organic positioning and hermetic sealing capabilities capture price premiums while commodity dried fish processors face margin compression from compliance-driven input cost inflation.
Pricing Analysis
Capacity additions in Thailand are reshaping price floors for seaweed and extruded chip formats, intensifying competition in private-label supply contracts. Three-tier pricing structure across premium, standard, and economy levels separates USDA-certified organic SKUs from conventional heritage processors and commodity anchovy exporters. Cost compression in standard-tier dried fish is intensifying because wild-catch input volatility in Southeast Asian waters compresses processor margins. Fitness enthusiasts demonstrate lowest price sensitivity for protein-density claims, while family-oriented multipack buyers in supermarket channels exhibit highest elasticity.
Supply Chain Analysis
Dual-sourcing requirements from European retail chains mandate Thai and South Korean processor qualification alongside domestic EU canning capacity, fragmenting volume allocation across heritage and extrusion-based manufacturing hubs. Raw material flows draw from Indonesian seaweed cultivation, Peruvian anchovy landings, and Korean mackerel dehydration clusters. Single-source vulnerability concentrates in Busan-Ulsan anchovy processing infrastructure, where typhoon disruption risks export supply continuity. Distribution runs through Amazon Subscribe and Save direct-to-consumer channels and South Korean convenience store networks with delivery-app integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Seafood snacks constitute a late-cycle quality story as pantry-stock subscription models displace impulse velocity and concentrate purchasing power among certified organic specialists with resealable format capabilities.
For Market Incumbents: Cement shelf-stable format leadership through backward integration into captive aquaculture feed sourcing that secures organic certification compliance. Lock in resealable bag substrate supply agreements with European mono-material film developers before REACH-mandated coating transitions accelerate. Plant-based protein substitution in savory snacks threatens trial capture among flexitarian demographics, demanding texture innovation investment in extrusion R&D to defend protein-density positioning. For New Entrants and Emerging Players: Enter via private-label supply contracts for North American supermarket chains seeking Asian-origin authenticity without captive processing infrastructure. White-space concentrates in certified organic seafood chips with vegetable-chip crossover texture profiles, where millennial and Gen Z adoption outpaces incumbent capacity expansion. Direct-to-consumer replenishment models with micro-fulfillment center partnerships offer the most penetrable go-to-market angle against established retail velocity gatekeepers. For Investors and Strategic Acquirers: Roll-up economics work for mid-cap Thai and South Korean processors with heritage dehydration infrastructure because EU packaging compliance mandates are forcing distressed asset valuations among non-compliant competitors. Five-to-ten year viability hinges on subscription channel penetration rates and organic certification attach rates. Watch for FDA HACCP validation timeline compression as the inflection signal indicating new processing facility entry barriers are tightening.| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Packaging Transition | REACH compliance deadlines force abandonment of legacy PFAS coatings in European-facing production lines. |
| Subscription Channel Integration | Amazon Subscribe and Save displaces supermarket velocity metrics with pantry-stock replenishment economics. |
| Organic Certification Investment | USDA and EU aquaculture feed standards enable premium positioning in North American supermarket chains. |
| Extrusion Technology Deployment | Precision thermal processing replicates vegetable-chip crunch profiles for millennial and Gen Z adoption. |
| Dual-Sourcing Processor Qualification | European retail mandates split volume between Thai heritage processors and domestic canning capacity. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with seafood processing plant managers, retail category buyers at convenience store chains, supply planners at subscription logistics platforms, and regulatory affairs leads at export-oriented manufacturers. Secondary validation drew from MFDS sodium-labeling disclosures, FDA HACCP import certification records, EU packaging waste directive implementation timelines, and Nielsen retail audit data for protein snack velocity metrics. Bottom-up processor capacity assessments and top-down retail channel spend estimates were triangulated to anchor volume and value outputs.
Historical reference periods spanning heritage dried fish consumption trends and emerging extruded chip adoption curves anchored the projection horizon across the analysis window. Segmentation dimensions modeled include product type, packaging format, distribution channel, and customer application urgency. CAGRs were derived from trend-line extrapolation of subscription penetration rates and organic certification attach rates, cross-referenced with regulatory compliance cost trajectories and wild-catch biomass fluctuation patterns.
Inputs from retail scanner databases and customs trade records were available through the study window; gaps in real-time subscription cancellation rate data introduce uncertainty bands around direct-to-consumer channel forecasts. Deviation in EU extended producer responsibility enforcement timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Superfoods-Based Packaged Snacks Market
Snacks
Low Calorie Biscuits Market
Snacks
Saudi Arabia Snack Bar Market
Snacks
Low Calorie Snack Foods Market
Snacks
Asia Pacific Snack Food Market
Snacks
UAE Snack Bar Market
Snacks
Salty Puffed Snacks Market
Snacks
Kids Snacks Market
Snacks
South Africa Snack Bar Market
Snacks
Healthy Fat-Free Snacks Market
Snacks
Vegan Snacks Market
Snacks
South America Frozen Snacks Market
Snacks
United Kingdom Snack Bar Market
Snacks
Low-Fat Tortillas Market
Snacks
Cheese Snacks Market
Snacks
Packaged Rice Snacks Market