
 Low-Fat Tortillas Market | 2026-2036
Low-Fat Tortillas Market Size, Share, and Industry Trends Forecast 2026-2036
Low-Fat Tortillas Market Analytics
US flour mill capacity dedicated to reduced-fat formulations is realigning toward health-positioned tortilla production. Mission Foods leverages vertical integration from grain sourcing to retail distribution across North American markets. La Tortilla Factory differentiates through specialized whole wheat and alternative-flour recipes targeting wellness consumers. Guerrero anchors its position in foodservice channels where low-fat specifications now appear in chain restaurant tenders.
Low-fat tortillas are flatbread products manufactured with reduced lipid content, typically achieved through modified dough formulations, enzyme treatments, or fiber enrichment that maintains pliability while cutting fat to under three grams per serving. These products serve food manufacturers and foodservice operators seeking menu items compliant with health-positioned consumer segments. Flour tortillas occupy the largest volume position due to universal application in wraps and burrito formats, while whole wheat variants capture the fastest expansion as clean-label preferences intensify. Shelf-stable forms dominate retail logistics economics, though fresh formats command premium placement in health food stores where turnover justifies shorter codedating.
The FDA governs nutrition fact panel declarations and health claims on packaged low-fat tortillas sold in US commerce, while the USDA oversees grain standards and organic certification pathways that influence ingredient sourcing. Mexico's national health regulator sets parallel guidelines for products manufactured and distributed within its territory, creating dual compliance obligations for cross-border producers. Stakeholders must monitor evolving front-of-package labeling mandates and grain origin documentation requirements that will determine market access thresholds without explicit timeline commitments.
Market Dynamics
Quick-service restaurant procurement contracts now mandate reduced-fat specifications, forcing tortilla manufacturers to reconfigure milling operations and reformulate dough chemistry at scale.
Growth Catalysts
- Quick-service restaurant mandates:Chain operators in the southwestern United States now embed low-fat requirements into supplier tenders, pulling reformulated products through foodservice channels.
- FDA nutrition labeling updates:Revised declaration standards for packaged foods accelerate manufacturer transitions toward reduced-fat profiles to maintain retail shelf positioning.
- Enzyme treatment advances:Novel lipase applications enable fat reduction below three grams per serving without compromising tortilla pliability or freeze-thaw stability.
Market Restraints
- Wheat gluten volatility:Protein concentrate prices fluctuate with drought cycles in the North American plains, compressing margins on whole wheat formulations.
- Fresh format logistics:Shorter codedating requirements for refrigerated distribution limit geographic radius from production facilities.
- Alternative-carbohydrate substitution:Lettuce wraps and cauliflower-based flatbreads capture calorie-conscious consumers in premium urban markets.
Strategic Opportunities
- Foodservice channel expansion:Institutional feeding programs in Mexico present untapped volume for reduced-fat corn and flour variants.
- Clean-label convergence:Pairing low-fat claims with organic certification captures dual-preference wellness segments in California and Texas retail.
- Direct-to-foodservice platforms:Digital procurement portals enable tortilla manufacturers to bypass distributor markups and capture chain restaurant accounts directly.
Industry Challenges
- Grain milling expertise scarcity:Operators capable of calibrating reduced-fat dough rheology remain concentrated among legacy tortilla specialists.
- Dual compliance complexity:Manufacturers supplying both US and Mexican markets must reconcile FDA nutrition panels with Mexico's national health regulator labeling requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low-Fat Tortillas Market |
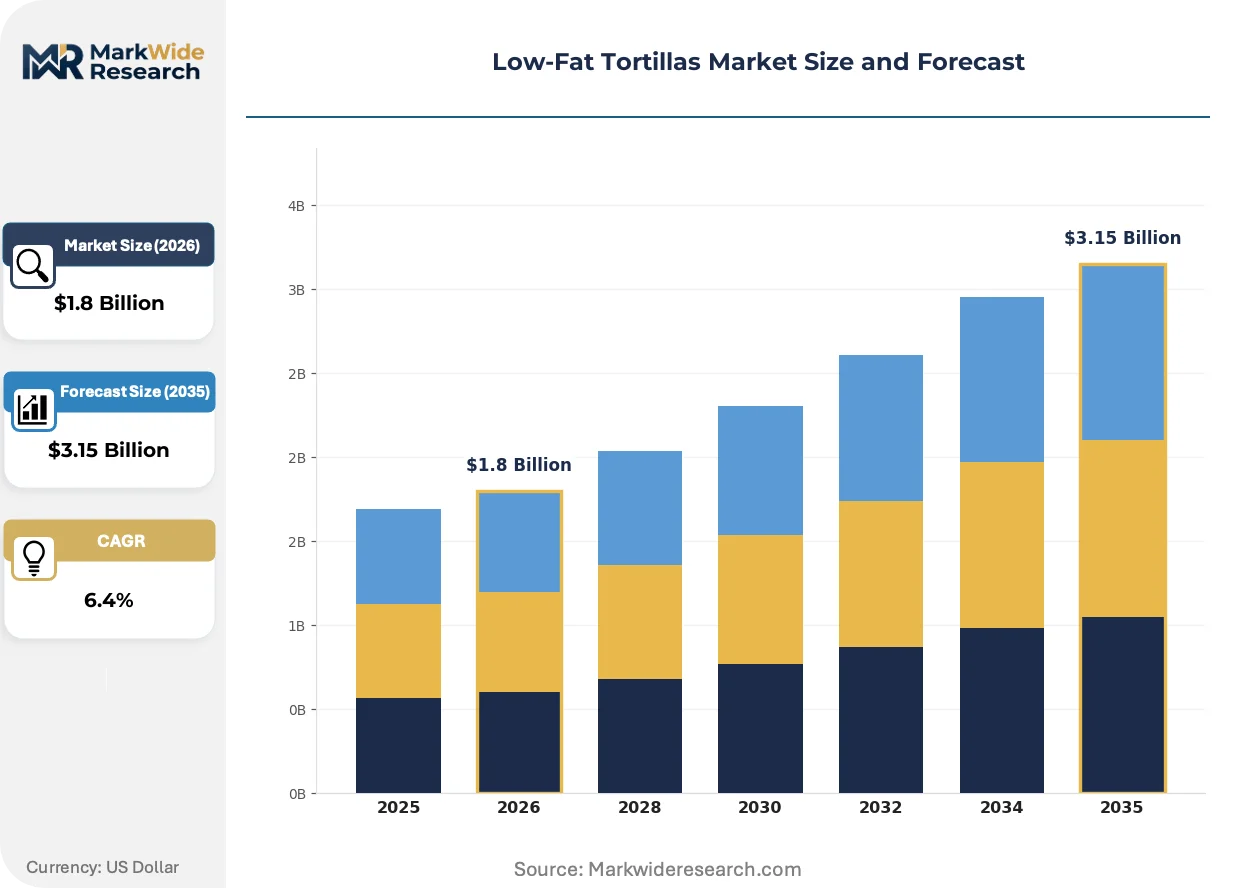
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Corn Tortillas, Flour Tortillas, Whole Wheat Tortillas, Spinach Tortillas Distribution Channel: Supermarkets, Online Retail, Health Food Stores, Convenience Stores End User: Restaurants, Households, Catering Services, Food Trucks Form: Ready-to-Eat, Frozen, Shelf-Stable, Fresh |
| Companies Covered | Mission Foods, La Tortilla Factory, Guerrero, La Banderita, Trader Joe's, Mr. Tortilla, Siete Foods, Tumaro's, Mama Lupe's, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low-Fat Tortillas Market Evolving Landscape
Active enzyme engineering and front-of-package labeling mandates are compressing formulation cycles while reshaping how tortilla manufacturers compete on health claims rather than price alone.
Modified lipase and transglutaminase systems are electrifying low-fat tortilla production by enabling fat reduction without structural collapse during rolling and heating. Foodservice distributors in Texas and Arizona are adopting these enzyme-treated formats at accelerating pace to meet chain restaurant specifications. The technology is electrifying competitive positioning by separating enzyme-capable manufacturers from commodity flour tortilla operations unable to achieve equivalent texture profiles.
The FDA's updated nutrition fact panel requirements are forcing packaged tortilla producers to consolidate multiple health claims into single reformulation efforts rather than sequential product line extensions. Manufacturers must now simultaneously address fat reduction, sodium limits, and fiber enhancement to retain retail placement. Flour tortilla SKUs sold through US grocery channels face the steepest compliance timelines and are responding with accelerated R&D cycles.
Chain restaurant procurement departments are consolidating supplier rosters around tortilla manufacturers capable of delivering documented nutritional compliance with batch-level traceability. Distributor intermediaries lose leverage as buyers demand direct relationships with milling operations that control ingredient sourcing. This concentration is most visible in the southwestern United States where quick-service operators source tortillas for regional menu rollouts.
Low-Fat Tortillas Market Segmentation
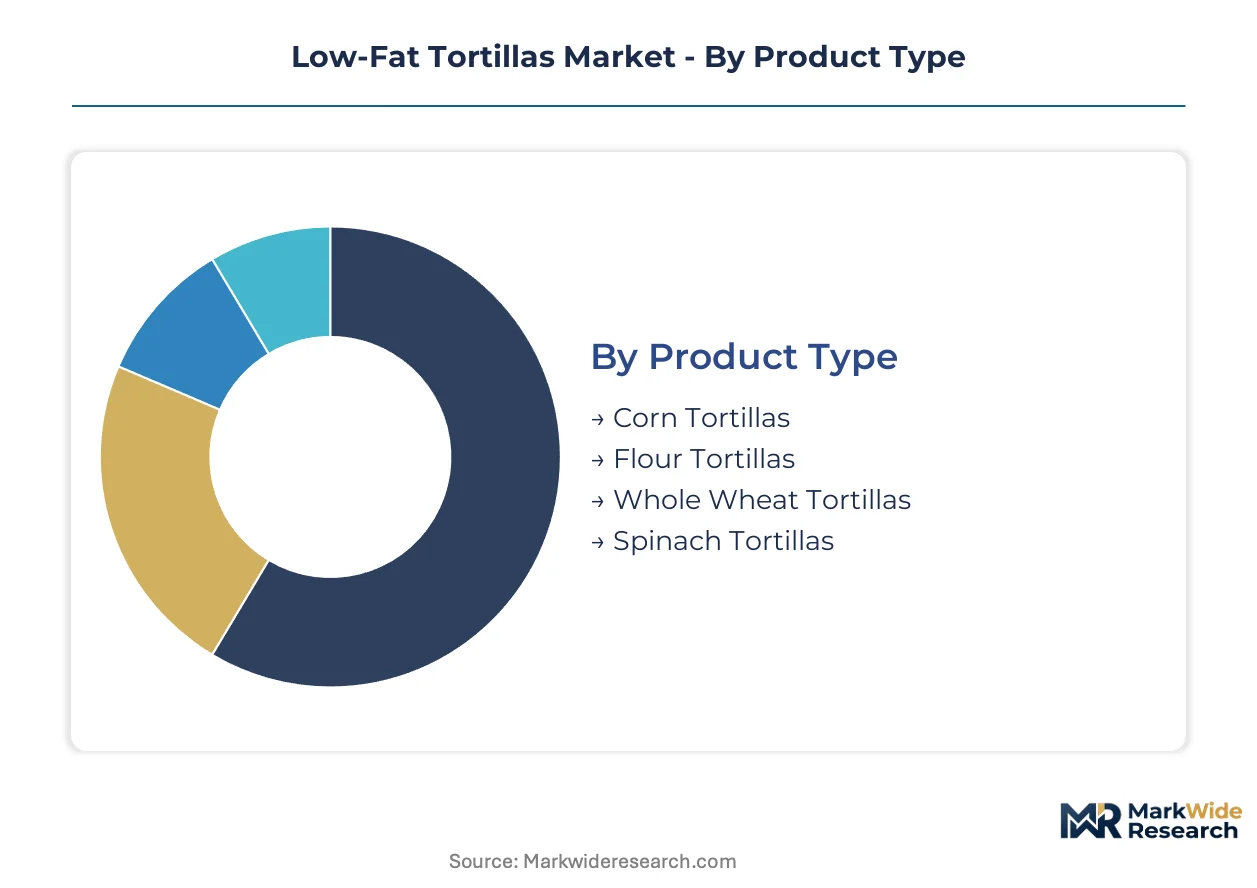
Low-fat tortilla manufacturers calibrate production lines around distinct product specifications, distribution economics, and end-use requirements. Each segmentation dimension reveals divergent margin structures and reformulation priorities that determine competitive positioning across retail and foodservice channels.
Product Type:
Reformulation cycles accelerate as enzyme technologies mature, pushing manufacturers to upgrade dough systems toward reduced-fat profiles without sacrificing pliability.
- Flour Tortillas:Standard wheat-based formulations dominate foodservice procurement volumes, with modified lipase treatments now enabling sub-three-gram fat content while maintaining freeze-thaw stability for chain restaurant distribution.
- Whole Wheat Tortillas:Fiber-enriched alternatives capture wellness-positioned retail placement in California and Texas, where clean-label preferences intensify demand for visible grain texture combined with reduced-fat claims.
- Corn Tortillas:Traditional masa-based products serve authentic Mexican cuisine applications with naturally lower fat content.
- Spinach Tortillas:Vegetable-infused variants target premium health food store placement with color differentiation.
Volume placements concentrate in flour tortillas; the faster expansion belongs to whole wheat.
Distribution Channel:
Channel economics dictate packaging formats and codedating requirements, with margin structures varying sharply between high-velocity retail and specialized health food placement.
- Supermarkets:High-velocity retail chains in the southwestern United States drive standardized packaging and front-of-package labeling compliance, with shelf-stable formats dominating logistics economics.
- Health Food Stores:Premium independent retailers in California command fresh-format tortillas with shorter codedating, justifying higher unit economics through turnover rates that support refrigerated distribution.
- Online Retail:Direct-to-consumer platforms enable subscription models for specialized whole wheat and alternative-flour variants.
- Convenience Stores:Grab-and-go placement favors individually wrapped shelf-stable formats with extended shelf life.
Supermarkets anchor current volume; health food stores are climbing the fastest.
End User:
Customer procurement specifications diverge sharply between institutional foodservice tenders and household consumption patterns.
- Restaurants:Quick-service chain operators embed low-fat mandates into supplier contracts, requiring batch-level nutritional documentation and direct milling relationships that bypass distributor markups.
- Households:Retail consumers in Mexico and the southwestern United States prioritize familiarity and price accessibility for daily meal preparation.
- Catering Services:Event-based volume demands consistent sizing and pliability for buffet service applications.
- Food Trucks:Mobile operators require durable wraps that withstand holding temperatures without structural breakdown.
Restaurants command the largest procurement volumes; households represent the most stable recurring demand base.
Form:
Preservation technology investments separate manufacturers capable of multi-format production from single-capability specialists.
- Shelf-Stable:Modified atmosphere packaging extends retail distribution radius, with enzyme-treated formulations maintaining texture profiles through ambient temperature logistics.
- Fresh:Refrigerated distribution captures premium placement in health-focused retail, constrained by geographic radius from production facilities.
- Frozen:Extended shelf life serves foodservice inventory management and institutional feeding programs.
- Ready-to-Eat:Pre-cooked formats target convenience consumption with minimal preparation requirements.
Shelf-stable formats dominate retail logistics; fresh formats gain share fastest in premium urban markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hard red winter wheat from the Kansas-Oklahoma corridor supplies the primary feedstock for North American low-fat tortilla production, anchoring milling infrastructure across the southern plains.
United States
Quick-service restaurant chains in Texas and California embed low-fat specifications into procurement contracts, pulling reformulated products through foodservice channels. The FDA governs nutrition fact panel declarations and health claims on packaged tortillas sold in interstate commerce. Mission Foods operates integrated milling and production facilities in Irving, Texas, supplying retail and institutional accounts across the southwestern corridor.
Mexico
Traditional tortilla consumption patterns in Mexico City and Guadalajara create stable household demand for reduced-fat corn and flour variants. Mexico's national health regulator sets parallel labeling guidelines for products manufactured and distributed within its territory, creating dual compliance obligations for cross-border producers. Gruma anchors industrial production in Nuevo León, serving both domestic retail and export markets to the United States.
Canada
Health-conscious consumers in Toronto and Vancouver drive retail placement of whole wheat low-fat tortillas through supermarket channels. Health Canada oversees packaged food labeling requirements and organic certification pathways that influence ingredient sourcing decisions. Industrial baking clusters in southern Ontario process imported wheat into tortilla formulations for distribution across the Prairie Provinces.
Germany
Expatriate communities and wellness-oriented consumers in Berlin and Munich generate niche demand for low-fat wraps as alternatives to traditional bread. EFSA guidelines on nutrition and health claims shape permissible front-of-package declarations for imported and domestically produced flatbreads. Specialized distributors in Hamburg manage cold-chain logistics for fresh-format tortillas targeting premium urban retail.
United Kingdom
Foodservice operators in London and Manchester specify low-fat tortillas for health-positioned menu items in casual dining and fast-casual segments. The Food Standards Agency enforces labeling requirements for prepacked foods sold in England, Wales, and Northern Ireland. Ethnic food manufacturers in the West Midlands produce reformulated flatbreads for supermarket private-label programs.
Low-Fat Tortillas Market Competitive Landscape
Global majors compete with regional champions across procurement channels, with multinational food corporations holding foodservice contracts while specialized mills capture premium retail placement. The vendor base separates into three tiers: integrated grain-to-retail operators, specialized health-positioned brands, and private-label suppliers serving supermarket chains. Strategic archetypes include enzyme-technology specialists, clean-label organic certifiers, and scale-driven commodity producers. Competitive moves concentrate on direct-to-foodservice platform development and backward integration into grain sourcing to control input costs.
Within the integrated multinational tier, Mission Foods exemplifies vertical control from wheat procurement through retail distribution, while Guerrero anchors foodservice channel penetration. Among specialized health-positioned operators, La Tortilla Factory occupies a position targeting wellness consumers through whole wheat and alternative-flour formulations. These three companies represent distinct competitive vectors: scale-driven supply chain control, institutional channel dominance, and premium health-positioning.
| Leading Market Players |
|---|
| Mission Foods |
| La Tortilla Factory |
| Guerrero |
| La Banderita |
| Trader Joe's |
| Mr. Tortilla |
| Siete Foods |
| Tumaro's |
| Mama Lupe's |
| Others |
Value Network & Pricing Analysis
Backward integration into hard red winter wheat sourcing anchors both supply security and margin control for leading tortilla manufacturers across the southern plains. This upstream control over grain procurement enables Mission Foods and Guerrero to buffer against protein concentrate price swings while commanding preferential terms in quick-service restaurant negotiations.
Pricing Analysis
Service unbundling separates technical formulation support from base product supply, with enzyme-treated variants commanding premiums for documented freeze-thaw stability. Three-tier pricing structure across premium organic, standard clean-label, and economy flour tiers reflects certification grade and volume scale differentiation. Pricing pressure stems from cauliflower-based flatbread substitutes capturing calorie-conscious urban consumers. Foodservice buyers exhibit lowest price sensitivity due to mandated low-fat specifications, while retail households prioritize unit accessibility.
Supply Chain Analysis
Domestic-content rules in Mexican procurement tenders reshape sourcing patterns, compelling cross-border producers to maintain parallel milling capacity in Nuevo León. Hard red winter wheat from Kansas and Oklahoma feeds primary production, with supplemental grain drawn from Canadian prairie provinces. Single-source vulnerability concentrates in enzyme lipase suppliers, where proprietary formulations create captive dependencies. Distribution runs through foodservice distributor networks in Texas and Arizona, with direct-to-chain portals eroding intermediary leverage.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The low-fat tortilla sector is transitioning from commodity flour production to enzyme-engineered specialty formats, with modified lipase systems displacing traditional dough chemistry as the baseline competitive capability.
For Market Incumbents: Deepen captive enzyme development partnerships to lock in proprietary texture profiles that commodity mills cannot replicate. Secure dedicated hard red winter wheat offtake agreements before drought cycles compress protein concentrate availability. The priority lever sits in foodservice channel control, where direct procurement relationships insulate against distributor disintermediation.
For New Entrants and Emerging Players: Capture institutional feeding program volume in Mexico City and Guadalajara, where reduced-fat specifications remain underpenetrated relative to US quick-service saturation. Target health food store placement in California premium corridors, where fresh-format turnover justifies refrigerated distribution investments. A subscription-based direct-to-consumer platform for whole wheat and alternative-flour variants bypasses retail slotting barriers.
For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by integrated grain processors seeking downstream brand assets. Long-term viability hinges on enzyme capability ownership rather than toll-milled commodity production. The acquisition target archetype combines proprietary lipase formulations with established foodservice contracts. Watch for FDA front-of-package labeling enforcement as the inflection signal separating compliant reformulators from stranded legacy SKUs.
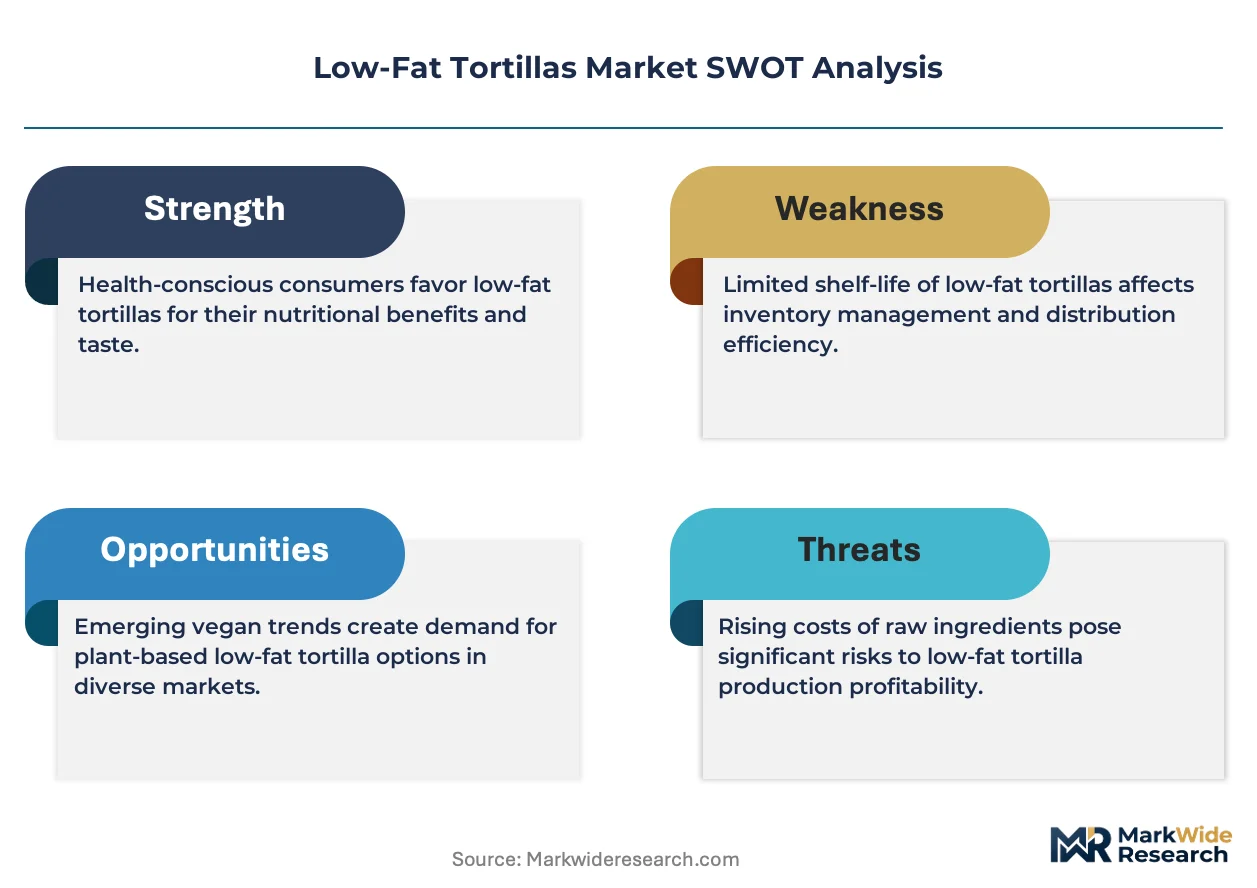
| Strategic Initiative | Industry Significance |
|---|---|
| Enzyme Technology Licensing | Proprietary lipase systems from Novozymes or DuPont enable sub-three-gram fat content without texture collapse. |
| Backward Integration into Grain Sourcing | Captive wheat procurement from Kansas-Oklahoma corridor insulates margin against protein concentrate volatility. |
| Direct-to-Foodservice Platform Launch | Digital procurement portals bypass Sysco and US Foods markups while capturing chain restaurant batch-traceability requirements. |
| Dual Certification Investment | Simultaneous USDA organic and FDA low-fat claim compliance captures wellness-premium positioning in California retail. |
| Cross-Border Production Footprint | Parallel milling capacity in Nuevo León satisfies Mexican domestic-content rules while serving US export demand. |
Research Methodology
Independent corroboration across milling operations executives, quick-service restaurant procurement directors, and enzyme technology suppliers underwrites the qualitative findings. Primary fieldwork encompassed tortilla plant managers, foodservice distributor category leads, and regulatory affairs specialists at cross-border manufacturers. Secondary validation drew from FDA nutrition labeling guidance documents, USDA grain standard reports, SEC filings of integrated food corporations, and Mexican health regulator compliance circulars. Bottom-up volume modeling triangulated against top-down category spend estimates.
Rate-of-change decomposition separated volume growth from price-mix effects across the projection horizon. The analytical framework modeled product type segments, distribution channel economics, end-user procurement specifications, and preservation format logistics. CAGRs derived from iterative convergence between historical consumption elasticities and forward scenario weightings. Key inputs included enzyme adoption curves in foodservice channels and front-of-package labeling compliance timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to drought-induced wheat protein volatility and alternative-carbohydrate substitution rates. Assumptions reflect documented procurement mandate trajectories and regulator enforcement patterns. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Spain Energy Bar Market
Snacks
Europe Energy Bar Market
Snacks
Europe Snacks Market
Snacks
Oat-Based Snacks Market
Snacks
Low Sodium Snacks Market
Snacks
Corn Chips Market
Snacks
Dried Fruit Snacks Market
Snacks
Crispy Fruit Chips Market
Snacks
Nuts and Seeds (Savory Snacks) Market
Snacks
Spicy Sticks (Chinese Snack) Market
Snacks
Low Fat Protein Snacks Market
Snacks
Dairy Protein Crisps Market
Snacks
UK Snack Market
Snacks
North America Snack Bar Market
Snacks
Candy and Snack Food Pouches Market
Snacks
Asia Pacific Frozen Snacks Market