
 Nuts and Seeds (Savory Snacks) Market | 2026-2036
Nuts and Seeds (Savory Snacks) Market Size, Share, and Industry Trends Forecast 2026-2036
Nuts and Seeds (Savory Snacks) Market Insights
Vietnam is rewriting capacity dynamics for cashew processing and export-oriented savory nut production. Blue Diamond Growers leverages its California almond orchards and processing infrastructure to dominate North American supply. The Wonderful Company sustains vertical integration across pistachio cultivation and branded snack distribution. Intersnack Group competes through its European manufacturing footprint and private-label capabilities.
Nuts and Seeds (Savory Snacks) comprise oilseed and tree nut products that undergo dry-roasting, oil-roasting, or seasoning to achieve shelf-stable flavor profiles with moisture content typically below four percent. These products serve as protein-dense alternatives to carbohydrate-heavy snack categories in both impulse and planned purchase occasions. Roasted Nuts anchors the value pool due to premium pricing and established household penetration across retail channels. Seasoned Seeds represents the fastest-expanding form factor, driven by portability and alignment with portion-controlled consumption. Mixed Nuts occupies a mature position where margin compression from commodity almond and peanut costs limits pricing flexibility.
The FDA enforces allergen labeling through FALCPA and nutrition fact standards that determine shelf placement and consumer trust for packaged nut products. EFSA evaluates novel food applications and contaminant thresholds that constrain import flows into European retail. India's FSSAI mandates fortification and hygiene benchmarks for domestic savory snack manufacturing. Stakeholders must monitor how divergent sodium and saturated fat caps across jurisdictions reshape permissible seasoning formulations and export eligibility.
Market Dynamics
Clean-label mandates from the FDA and EFSA are forcing reformulation across the savory nut supply chain, compressing permissible ingredient sets while elevating transparency requirements as a competitive differentiator.
Growth Catalysts
- EFSA contaminant thresholds:Stricter aflatoxin and pesticide residue limits are accelerating investment in controlled-environment processing infrastructure across European import gateways.
- Urban commuter convenience retail:Grab-and-go channel expansion in transit hubs and workplace micro-markets is pulling single-serve and resealable formats into higher velocity rotation.
- Dry-roasting automation:Precision thermal control systems are reducing energy intensity and enabling real-time moisture monitoring that satisfies export certification requirements.
Market Restraints
- Almond and peanut commodity volatility:California water allocation uncertainty and Argentine peanut harvest variability transmit directly into margin pressure for roasted nut portfolios.
- Cashew processing concentration:Vietnam and India collectively control over seventy percent of shelling capacity, creating bottleneck risk during peak harvest windows.
- Sodium reduction technical ceiling:Current salt replacer technologies fail to replicate flavor kinetics in oil-roasted applications, limiting compliance with emerging health claims standards.
Strategic Opportunities
- Germany clean-label retail:Discounter chains in this market are expanding dedicated natural snack aisles with explicit exclusion of artificial flavor enhancers and modified starches.
- Precision fermentation-derived seasonings:Biotech-enabled flavor compounds are opening pathways to sodium reduction without sensory compromise in savory coatings.
- Subscription direct-to-consumer channels:Curated nut assortments with origin storytelling and portion customization are capturing pantry replenishment occasions previously held by conventional retail.
Industry Challenges
- FSSAI fortification compliance timelines:India's mandatory micronutrient addition requirements demand capital-intensive blending equipment retrofits with compressed implementation windows.
- Legacy ERP integration with traceability platforms:Lot-level blockchain documentation for allergen management is colliding with decades-old inventory management architectures at mid-tier processors.
- Roaster operator skill scarcity:Artisanal thermal profile expertise is aging out faster than automated control interfaces can replicate nuanced browning judgment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nuts and Seeds (Savory Snacks) Market |
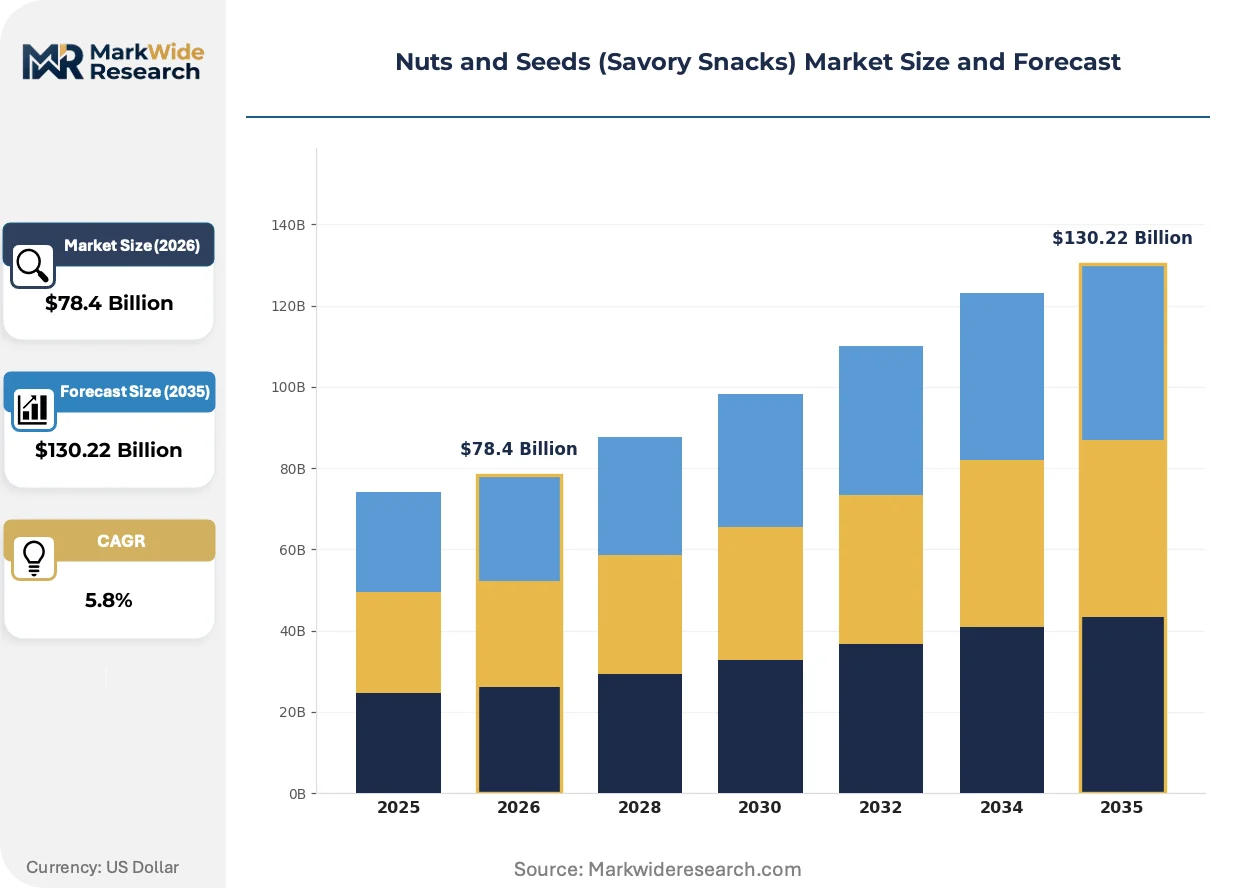
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $130.22 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Roasted Nuts, Seasoned Seeds, Spicy Nuts, Mixed Nuts Form: Whole, Chopped, Sliced, Powdered Packaging Type: Bags, Canisters, Bulk Bins, Pouches Distribution Channel: Supermarkets, Health Food Stores, Online Retailers, Convenience Stores |
| Companies Covered | Blue Diamond Growers, Link Snacks Inc., The Wonderful Company, Hormel Foods Corporation, Diamond Foods, Intersnack Group, Waterford Nut Company, Royal Nut Company, Tong Garden, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nuts and Seeds (Savory Snacks) Market Trends and Innovations
Processing technology and regulatory disclosure requirements are converging to redefine what constitutes a premium savory snack, with transparency mechanisms now competing directly with flavor innovation for shelf positioning.
Infrared roasting systems with spectral feedback loops are rendering obsolete conventional time-temperature batch protocols that relied on operator intuition. Premium private-label suppliers in Germany and the United States are deploying these systems to achieve lot-to-lot consistency that satisfies EFSA contaminant documentation requirements. The capital barrier is compressing the supplier base toward processors with captive equipment financing relationships.
REACH registration requirements for novel flavor compounds are extending development timelines for seasoned seed launches into European retail. ECHA evaluation backlogs are forcing reformulators toward GRAS-certified alternatives already present on the Union list. Seed specialists are responding by consolidating seasoning development within existing approved substance portfolios rather than pursuing novel molecule pathways.
Buyers in workplace and transit channels are compressing purchase decision windows to under fifteen seconds, privileging front-of-pack certification marks over ingredient list scrutiny. This behavioral pivot is displacing legacy nutrition claim hierarchies with single-icon systems such as Non-GMO Project or organic seals. China and the United States exhibit the most pronounced divergence in which certification marks command price premiums.
Nuts and Seeds (Savory Snacks) Market Segmentation
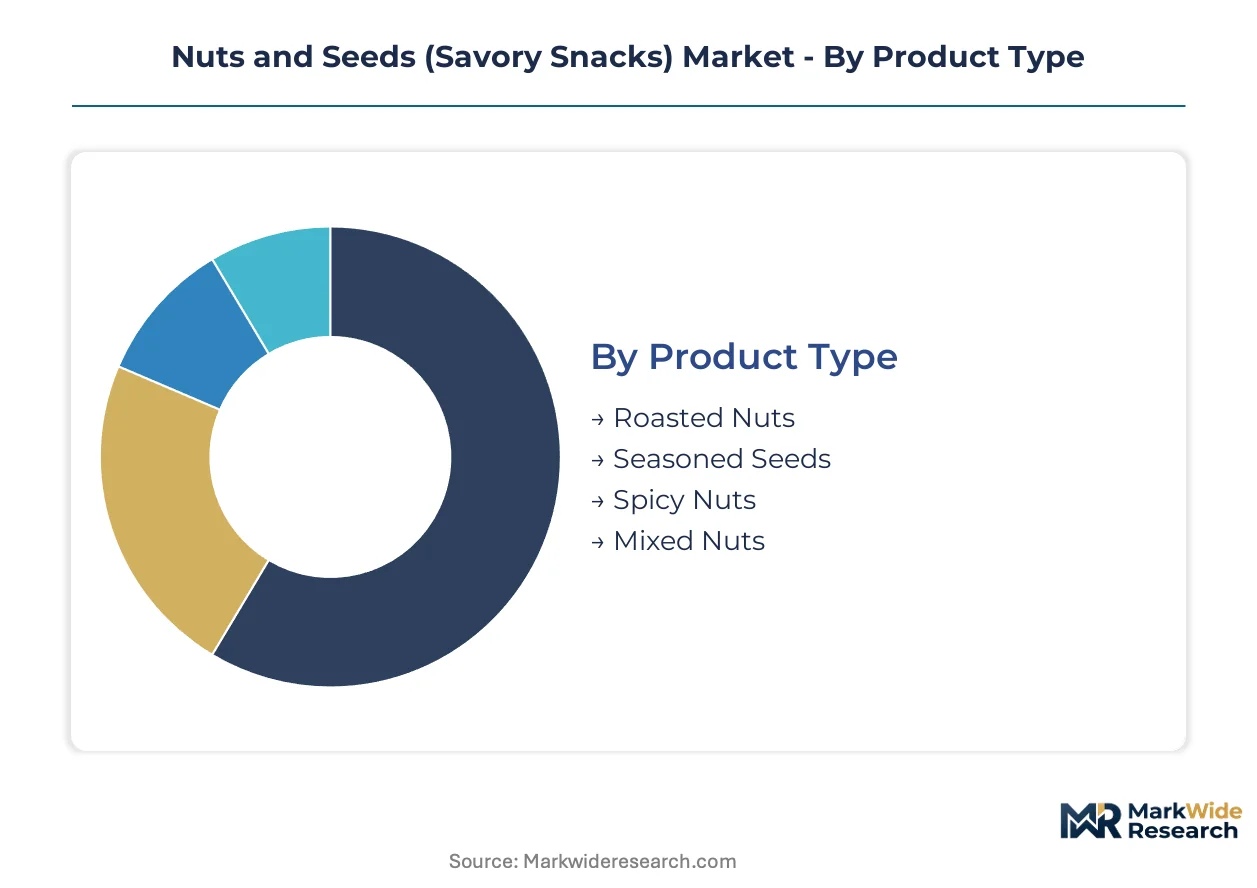
Segmentation in savory nuts and seeds reflects divergent consumption rituals. Product type captures flavor intensity and protein density preferences. Form and packaging address portability demands across commuter, pantry, and foodservice occasions. Distribution channels reveal where impulse versus planned purchasing concentrates.
Product Type:
The use-case spectrum spans protein-centric meal supplements to impulse flavor experiences, with moisture content and seasoning intensity determining shelf positioning and price tier.
- Roasted Nuts:Dry-roasted or oil-roasted tree nuts and peanuts with moisture content below four percent, achieving Maillard browning for shelf-stable flavor. Household penetration in the United States and Germany sustains velocity in conventional retail, though California almond cost volatility compresses margin flexibility.
- Seasoned Seeds:Sunflower, pumpkin, and watermelon seeds coated with savory or umami flavor systems, offering portion-controlled protein density. Transit hubs in China and workplace micro-markets in Germany are pulling single-serve formats into higher rotation due to grab-and-go convenience.
- Spicy Nuts:Oil-roasted nuts with capsaicin-forward seasoning profiles targeting heat-seeking snackers.
- Mixed Nuts:Blended almond, cashew, pecan, and macadamia assortments positioned for premium gifting and pantry replenishment.
Established volume favors Roasted Nuts; emerging adoption favors Seasoned Seeds.
Form:
Processing intensity correlates with application specificity, from whole kernel snacking to ingredient integration in food manufacturing.
- Whole:Intact kernels retaining natural oil encapsulation and textural integrity, commanding premium positioning in health food channels. Clean-label requirements from the FDA and EFSA privilege minimal processing for shelf placement in natural snack aisles.
- Chopped:Mechanically fractured pieces standardized for baking and salad topping applications. Foodservice procurement in Germany and industrial buyers in the United States are consolidating specifications around uniform particle size for recipe consistency.
- Sliced:Thin lamina produced for confectionery and granola integration.
- Powdered:Finely milled flour and butter bases for alternative protein formulations.
Whole kernels dominate household snacking; chopped forms are climbing fastest in foodservice ingredient procurement.
Packaging Type:
Barrier properties and resealability determine shelf life extension and consumption occasion targeting across retail formats.
- Bags:Flexible film structures with nitrogen flush and oxygen scavengers, balancing cost and shelf stability. Discounter chains in Germany are expanding private-label bagged offerings with explicit exclusion of artificial preservatives.
- Canisters:Rigid containers with threaded closures for pantry storage and portion control. Premium positioning in the United States leverages transparency windows and stackability for club store distribution.
- Bulk Bins:Gravity-fed dispensers for zero-waste retail and foodservice volume purchasing.
- Pouches:Stand-up flexible formats with press-to-close zippers for commuter channels.
Bags sustain mass-market volume; pouches are gaining share fastest in convenience retail expansion.
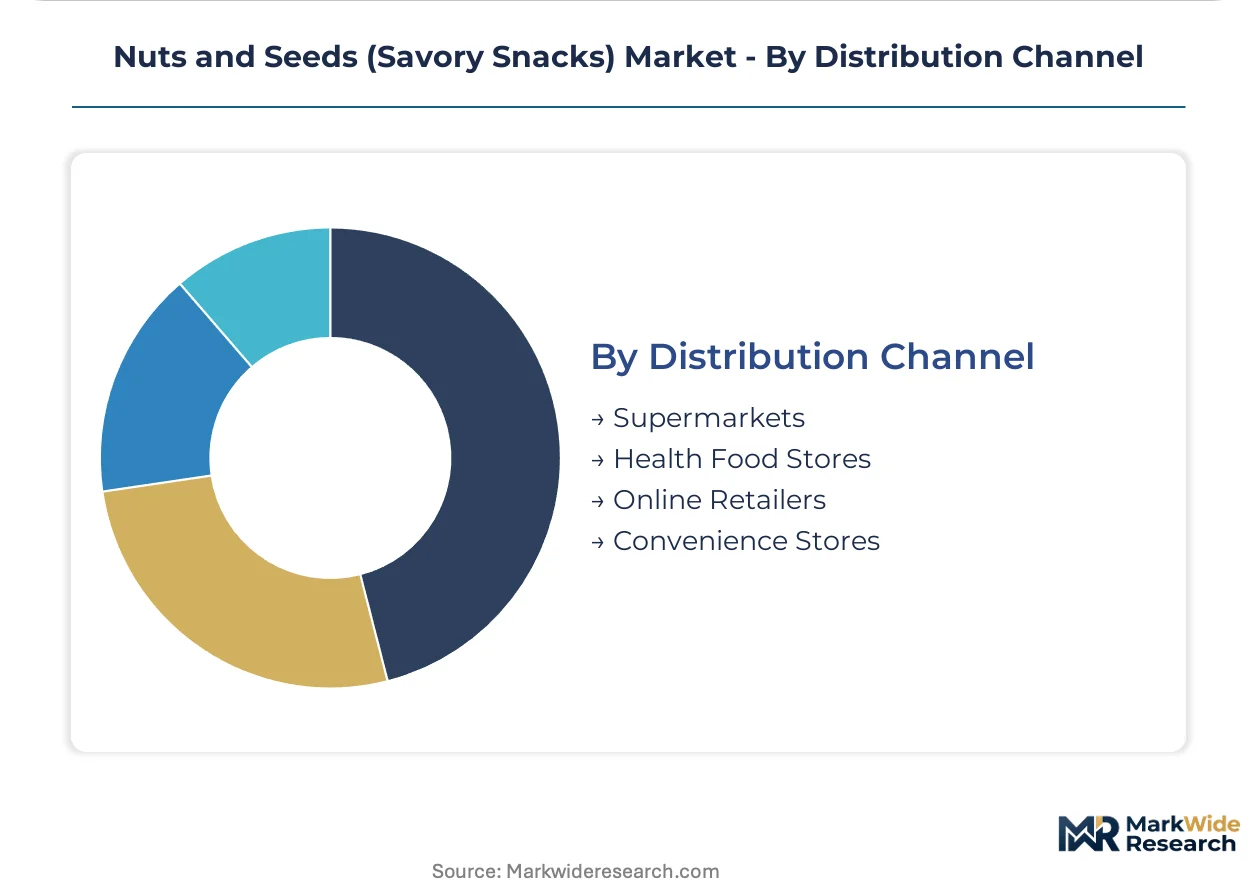
Distribution Channel:
Channel selection dictates pricing architecture, certification requirements, and promotional cadence for brand versus private-label positioning.
- Supermarkets:Full-line retailers with dedicated snack aisles and seasonal promotional calendars. FALCPA allergen labeling compliance from the FDA determines shelf eligibility and consumer trust for packaged nut products in the United States.
- Health Food Stores:Specialty retailers privileging organic, Non-GMO Project, and clean-label certification marks. EFSA novel food evaluations and contaminant thresholds constrain import flows into European health food channels.
- Online Retailers:Direct-to-consumer platforms enabling subscription replenishment and origin storytelling.
- Convenience Stores:Transit-adjacent and workplace formats compressing purchase decisions to under fifteen seconds.
Supermarkets anchor volume concentration; online retailers are expanding most quickly in curated subscription formats.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shelling capacity clusters in Vietnam and India constrain global cashew flows, while California almond orchards and European processing gateways shape trade patterns for roasted nut exports.
United States
Workplace micro-markets and transit-hub convenience retail pull single-serve formats into higher velocity rotation. FDA allergen labeling through FALCPA determines shelf eligibility for packaged nut products. California's Central Valley anchors almond cultivation and dry-roasting infrastructure serving North American supply.
Germany
Discounter chains expand dedicated natural snack aisles with explicit exclusion of artificial flavor enhancers. EFSA contaminant thresholds for aflatoxin and pesticide residues constrain import flows into European retail. Hamburg and Bremen host processing gateways with controlled-environment infrastructure for export certification.
China
Urban commuter demand concentrates in grab-and-go channels where purchase decisions compress to under fifteen seconds. SAMR nutrition labeling and GB standards for food safety determine permissible seasoning formulations. Yangtze River Delta processing clusters scale seasoned seed production for domestic distribution.
Vietnam
Export-oriented savory nut production rewrites capacity dynamics for cashew processing. The country's national food safety regulator mandates hygiene benchmarks for shelling operations. Binh Phuoc and Dong Nai provinces concentrate mechanized cracking facilities serving international traders.
India
Domestic savory snack manufacturing scales under fortification mandates for micronutrient addition. FSSAI compliance timelines demand capital-intensive blending equipment retrofits. Gujarat and Maharashtra host roasting and seasoning infrastructure for both local consumption and export.
Nuts and Seeds (Savory Snacks) Market Competitive Landscape
Vertically integrated orchard operators and European manufacturing specialists split the market into distinct capability tiers. Orchard-based processors control upstream supply through captive cultivation, while contract manufacturers compete on private-label flexibility and regional distribution density. Three archetypes dominate: captive-source processors with in-house nut cultivation, multi-site European manufacturers with private-label scale, and Asia-Pacific export specialists with shelling concentration. Competitive moves center on backward integration into cultivation assets and automation investment for contaminant-compliant processing.
Within the captive-source tier, Blue Diamond Growers and The Wonderful Company exemplify orchard-to-shelf control over almond and pistachio supply chains. European manufacturing scale concentrates with Intersnack Group, which occupies a position across private-label and branded distribution through its multi-country production footprint. These three anchors represent divergent strategic paths: California-based vertical integration, diversified European processing, and Asia-Pacific export specialization.
| Leading Market Players |
|---|
| Blue Diamond Growers |
| Link Snacks Inc. |
| The Wonderful Company |
| Hormel Foods Corporation |
| Diamond Foods |
| Intersnack Group |
| Waterford Nut Company |
| Royal Nut Company |
| Tong Garden |
| Others |
Pricing and Supply Chain Analysis
Trans-Pacific container rates from Ho Chi Minh City to Los Angeles transmit directly into landed cost spreads for Vietnamese cashew exporters, compressing margin buffers for mid-tier processors while amplifying price differentiation between commodity shellers and integrated roasters serving FDA-compliant retail channels.
Pricing Analysis
FALCPA allergen labeling mandates from the FDA dictate the pricing tier structure across North American retail, separating premium clean-label SKUs with full traceability documentation from economy-tier private-label bags with minimal origin disclosure. Pricing stratifies across premium organic certification, standard conventional grade, and economy bulk repack tiers, with California almond cost volatility intensifying compression in the standard tier. Buyers in German discounter channels exhibit highest price sensitivity, while health food store procurement in the United States tolerates significant premiums for Non-GMO Project verification.
Supply Chain Analysis
Extended payment terms through supply-chain finance facilities at Vietnamese shelling cooperatives are concentrating working capital risk among export traders dependent on Binh Phuoc and Dong Nai processing clusters. Raw material flows draw from West African cashew orchards, California almond groves, and Argentine peanut farms, with single-source vulnerability in Vietnamese shelling capacity exceeding seventy percent of global throughput. Distribution runs through Hamburg and Bremen gateway infrastructure for European retail compliance, with direct-to-consumer subscription channels bypassing traditional wholesale markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in clean-label certification gaps, as commuter-channel buyers compress decision windows below fifteen seconds and privilege single-icon trust marks over ingredient scrutiny.
For Market Incumbents: Build regulatory compliance moats through captive EFSA contaminant testing infrastructure at European import gateways, defending against emerging private-label entrants with faster certification turnaround. Backward integration into California almond cultivation or Vietnamese shelling assets locks in supply security against harvest volatility. Channel control through exclusive workplace micro-market placement agreements preserves velocity against direct-to-consumer disruption. For New Entrants and Emerging Players: Build out precision fermentation-derived seasoning capabilities targeting sodium reduction without sensory compromise, penetrating the white space between legacy salt replacers and clean-label mandates. German discounter natural snack aisles offer most penetrable retail geography, with explicit exclusion of artificial flavor enhancers creating entry barriers for incumbent reformulators. Go-to-market leverage rests on subscription direct-to-consumer origin storytelling with portion customization. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified food conglomerates with underperforming savory snack divisions lacking clean-label certification infrastructure or commuter-channel distribution density. Long-term viability favors processors with captive equipment financing for infrared roasting systems and blockchain traceability platforms. Watch for inflection in EFSA novel food evaluation backlogs forcing reformulators toward GRAS-certified alternatives already Union-listed.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cultivation Assets | Blue Diamond Growers and The Wonderful Company demonstrate orchard-to-shelf control over almond and pistachio supply security. |
| Precision Fermentation Seasoning Development | Biotech-enabled flavor compounds unlock sodium reduction pathways without sensory compromise in oil-roasted applications. |
| Blockchain Traceability Platform Deployment | Lot-level documentation satisfies EFSA contaminant thresholds and FALCPA allergen management for retail shelf eligibility. |
| Subscription Direct-to-Consumer Launch | Curated assortments with origin storytelling capture pantry replenishment occasions from conventional retail channels. |
| Controlled-Environment Processing Infrastructure | Investment at Hamburg and Bremen gateways accelerates export certification compliance for European retail access. |
Research Methodology
Desk research of trade flow databases, regulatory filing repositories, and food safety authority guidance documents preceded structured interviews with roasting plant managers, retail category buyers, import compliance officers, and seasoning formulation specialists. Primary fieldwork across California processing facilities, Vietnamese shelling cooperatives, and German discounter headquarters was cross-validated against customs records, EFSA contaminant monitoring reports, and FDA inspection classifications. Bottom-up volume modeling from facility throughput data was triangulated with top-down expenditure analysis from retail audit channels.
Base-case assumptions held EFSA novel food evaluation timelines and FSSAI fortification compliance deadlines fixed across the projection horizon, with sensitivity scenarios varying California water allocation uncertainty and Argentine peanut harvest variability. Segmentation dimensions modeled included product type, form, packaging configuration, and distribution channel, with additional granularity on clean-label certification tier. CAGRs were derived from trend extrapolation of historical volume shifts adjusted for channel migration patterns and regulatory implementation schedules.
Stress conditions across trans-Pacific freight rates, almond commodity spot prices, and sodium reduction technology maturation were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory timeline adherence and infrastructure investment continuity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Spain Energy Bar Market
Snacks
Flexible Plastic Snack Food Packaging Market
Snacks
Southeast Asia Savory Snacks Market
Snacks
Packaged Rice Snacks Market
Snacks
Europe Snack Pellets Market
Snacks
No Fat Snacks Market
Snacks
Meat Snacks Market
Snacks
Candy and Snack Food Pouches Market
Snacks
Baked Savoury Snacks Market
Snacks
Snack Bar Market
Snacks
South America Protein Bar Market
Snacks
Snack Subscription Market
Snacks
South America Snack Bar Market
Snacks
China Snack Bar Market
Snacks
North America Potato Chips Market
Snacks
Cereal Bars Market