
 Pretzels (Savory Snacks) Market | 2026-2036
Pretzels (Savory Snacks) Market Size, Share, and Industry Trends Forecast 2026-2036
Pretzels (Savory Snacks) Market Insights
Aftermarket service revenue from in-store pretzel warming and topping stations is reshaping how snack brands capture margin beyond the factory gate. PepsiCo leverages its Frito-Lay distribution network to dominate multiplex and stadium channels. Utz Brands anchors its position through direct-store delivery density across the Mid-Atlantic and Southeast. Auntie Anne's specializes in captive-audience locations, sustaining premium pricing through made-to-view production in transit hubs.
Pretzels (savory snacks) comprise wheat-flour dough products shaped into twisted or stick forms, baked or fried to moisture levels below 10 percent, and seasoned with salt, cheese powders, or spice blends for shelf-stable consumption. Their primary commercial purpose centers on portion-controlled, impulse-purchase snacking across retail and foodservice channels. Hard pretzels occupy the mature volume base, while pretzel chips capture the fastest growth as cracker-substitute usage expands. Flavor profiles skew heavily toward sea salt in conventional retail, though spicy variants are gaining velocity through specialty shops and online retailers where experimentation tolerance runs higher.
FDA sodium reduction targets and USDA Smart Snacks in School standards are tightening formulation parameters, pushing manufacturers toward potassium chloride blends and yeast-extract flavor enhancers. The EPA and state-level packaging regulations in California and New York are accelerating shifts from multilayer foil bags to recyclable plastic tubs and paper-based boxed formats. Stakeholders must monitor how dual compliance with nutrition labeling and extended producer responsibility laws reshapes both ingredient costs and packaging capital allocation without eroding the convenience-driven price points that define impulse purchases.
Market Dynamics
Clean-label reformulations driven by FDA sodium reduction guidance are compressing formulation timelines and forcing ingredient sourcing shifts across wheat-milling and seasoning supply tiers.
Growth Catalysts
- Airport and transit hub expansion:Captive-audience locations in Dallas-Fort Worth International Airport and Denver International Airport sustain premium pricing through made-to-view production models. Traveler foot traffic recovery post-2023 is accelerating kiosk deployment.
- USDA Smart Snacks in School standards:Compliance requirements for sodium limits and whole-grain content are creating institutional procurement pathways for reformulated pretzel products in K-12 foodservice channels.
- Potassium chloride blending technology:Advanced masking systems from flavor houses are enabling sodium reduction without sensory trade-offs, opening reformulation contracts with regional bakery operations.
Market Restraints
- Wheat price volatility:Hard red winter wheat futures from Kansas City Board of Trade expose margin compression for mid-sized pretzel manufacturers lacking forward-contract coverage.
- Multilayer packaging supply concentration:California and New York extended producer responsibility laws are stranding foil-laminate inventory while recyclable tub conversion requires capital outlays.
- Cracker and puffed snack substitution:Pretzel chips face displacement from seeded crispbreads and vegetable-based puffed products in health-positioned retail sets.
Strategic Opportunities
- India urban convenience retail:Modern trade expansion in Mumbai and Bangalore creates shelf-space allocation for imported savory snack formats targeting premium consumers.
- Yeast-extract flavor enhancement:Convergence of fermentation-derived umami systems with clean-label positioning enables sodium reduction without potassium chloride aftertaste.
- Direct-to-office subscription channels:Corporate pantry services bypass traditional retail slotting fees while capturing recurring revenue from hybrid-workplace snacking occasions.
Industry Challenges
- Flavor chemist talent scarcity:Reformulation expertise for salt-replacement systems is concentrating at specialized ingredient houses, inflating R&D contractor rates.
- Dual compliance capex burden:Simultaneous investment in nutrition-labeling software and packaging-line retooling strains working capital for regional producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pretzels (Savory Snacks) Market |
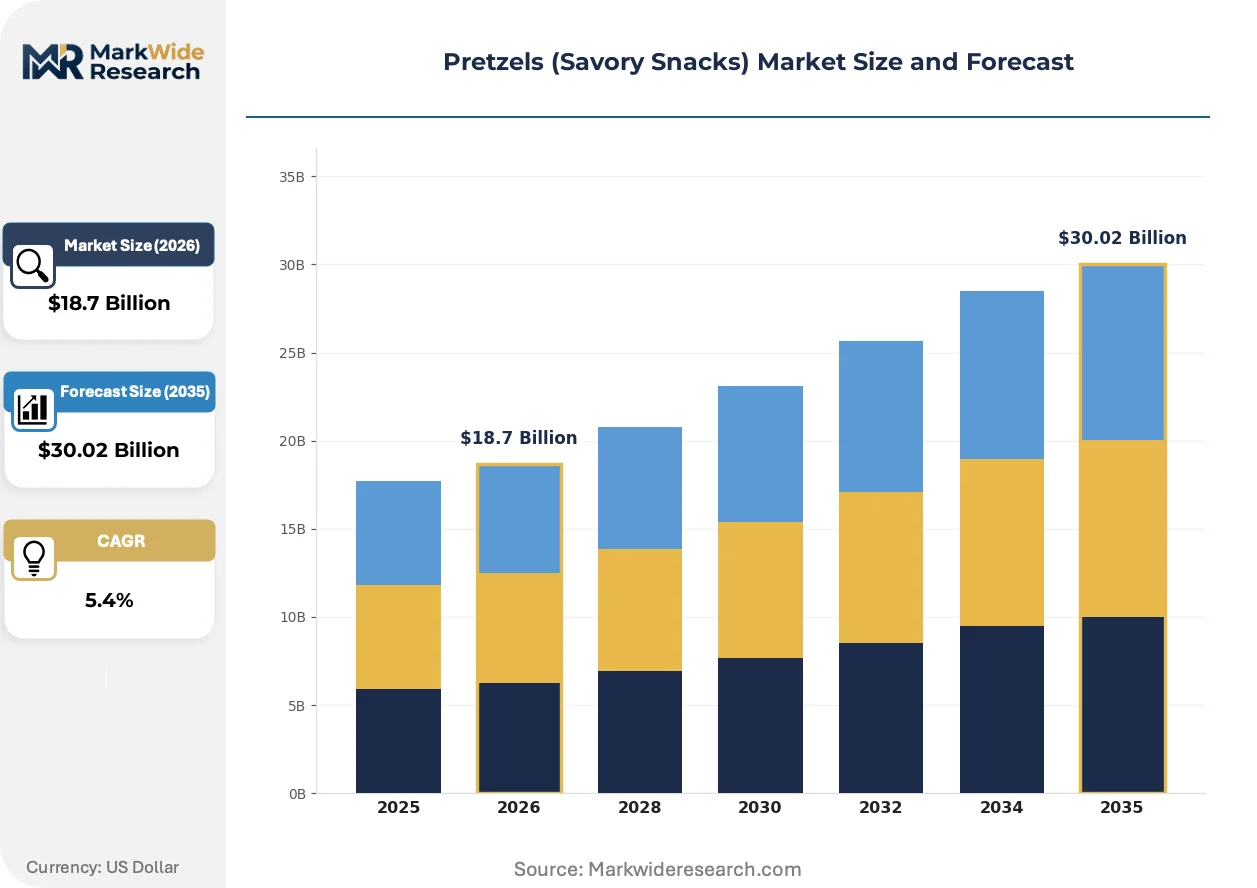
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $30.02 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Baked Pretzels, Hard Pretzels, Soft Pretzels, Pretzel Chips Flavor Profile: Sea Salt, Cheese, Honey Mustard, Spicy Packaging Type: Foil Bags, Plastic Tubs, Bulk Packaging, Boxed Sales Channel: Supermarkets, Online Retailers, Convenience Stores, Specialty Shops |
| Companies Covered | J&J Snack Foods, ConAgra Brands, PepsiCo, Campbell Soup Company, General Mills, Intersnack Group, Pretzels Inc., Utz Brands, Auntie Anne's, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pretzels (Savory Snacks) Market Trends and Innovations
Digital twin modeling of extrusion and baking parameters is compressing new product development cycles while regulatory pressure on sodium and packaging intensifies formulation and material science investments.
Sensory mapping software paired with AI-driven flavor prediction is virtualizing the traditional benchtop tasting panel. Mid-sized pretzel manufacturers in the Mid-Atlantic region are adopting these platforms to accelerate clean-label reformulation timelines. The technology is virtualizing quality assurance workflows that previously required weeks of human sensory evaluation.
California's extended producer responsibility regulations for flexible packaging are forcing accelerated shifts from metallized films to mono-material polyethylene tubs. Pretzel chip segments face the steepest compliance costs due to higher barrier requirements. Manufacturers are responding with paperboard box formats for club-store multipacks.
Grab-and-go snacking occasions are consolidating purchase decisions into convenience store and airport kiosk channels. Traditional grocery center-store placement is losing velocity to refrigerated perimeter locations and foodservice warming stations. This rotation is most visible in United States metropolitan markets where commute patterns favor impulse purchases at transit-adjacent retail.
Pretzels (Savory Snacks) Market Segmentation
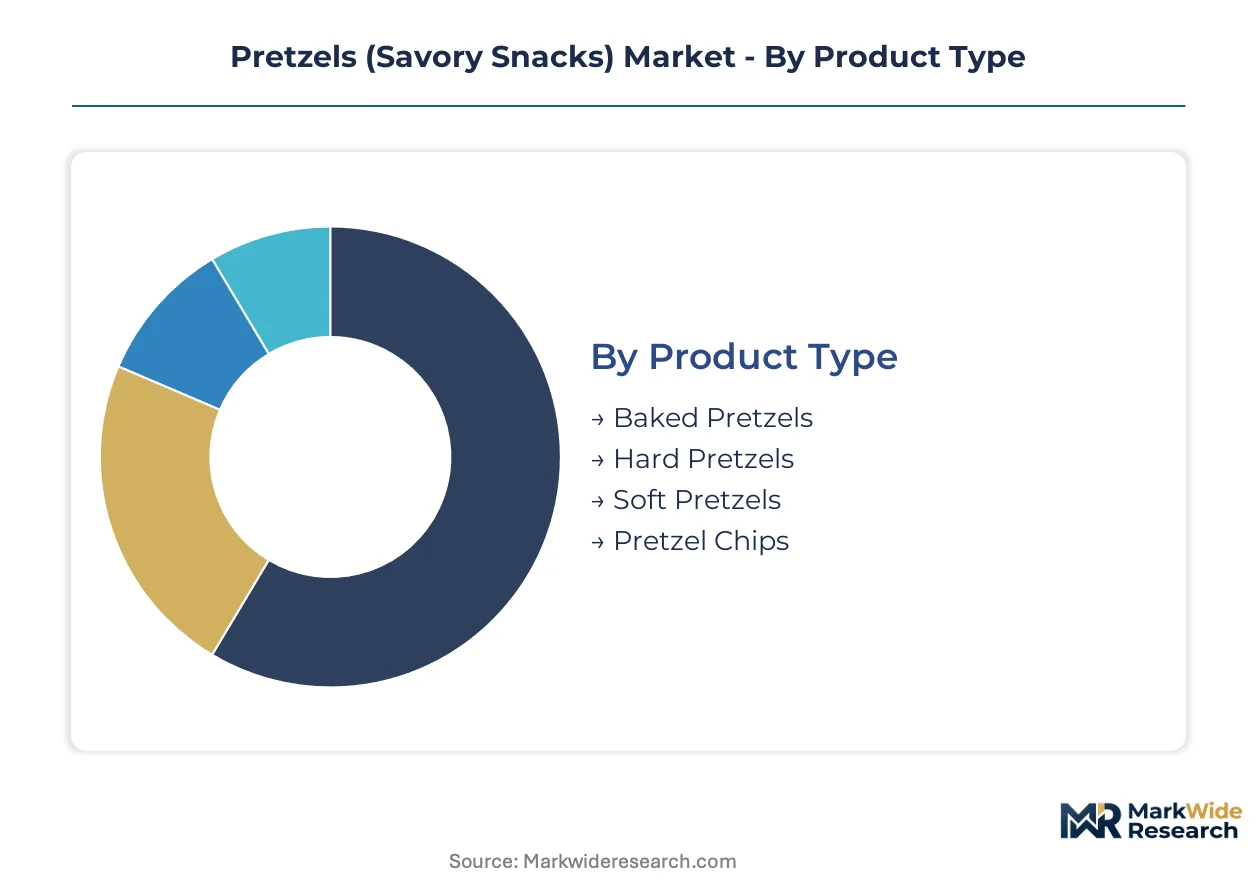
Pretzel manufacturers calibrate production assets and distribution investments around segment-specific margin profiles. Product format and packaging decisions cascade through wheat-milling specifications, barrier-film sourcing, and channel slotting fee structures.
Product Type:
After-sales service intensity varies sharply across product formats, with soft pretzel operators maintaining on-site warming equipment while hard pretzel brands focus on shelf-life technical support.
- Hard Pretzels:Dense, low-moisture baked products with extended ambient shelf stability above twelve months. Demand concentrates in United States grocery center-store aisles where Utz Brands and Snyder's-Lance anchor the mature volume base through direct-store delivery density.
- Pretzel Chips:Thin, flat-cut baked pieces positioned as cracker substitutes with higher surface-area-to-volume ratios for seasoning adhesion. United States club-store channels and specialty retailers are driving velocity as health-positioned consumers displace conventional fried snacks.
- Baked Pretzels:Standard twisted or stick formats produced through extrusion and baking rather than frying, achieving moisture levels below 10 percent.
- Soft Pretzels:Higher-moisture products requiring frozen distribution or on-premise production, common in foodservice and captive-audience retail locations.
Hard pretzels hold the largest share; momentum sits with pretzel chips.
Flavor Profile:
Cost tier stratification in seasoning inputs separates commodity sea salt formulations from premium spice blends carrying higher raw material and clean-label certification burdens.
- Sea Salt:Standard sodium chloride applications dominating conventional retail with minimal formulation complexity and lowest per-unit seasoning cost.
- Spicy:Capsicum-derived heat profiles gaining velocity through United States specialty shops and online retailers where experimentation tolerance runs higher and premium pricing sustains margin.
- Cheese:Dehydrated dairy and yeast-extract powder coatings common in mass-market multipacks and institutional foodservice channels.
- Honey Mustard:Sweet-heat hybrid profiles targeting regional taste preferences in Mid-Atlantic and Southeast United States markets.
Sea salt dominates volume; spicy variants are expanding most quickly.
Packaging Type:
Application requirements for barrier properties and shelf visibility drive divergent capital allocation between flexible film lines and rigid tub injection molding.
- Foil Bags:Metallized multilayer laminates providing oxygen and moisture barriers for hard pretzel shelf stability, now facing regulatory pressure under California and New York extended producer responsibility laws.
- Plastic Tubs:Mono-material polyethylene containers accelerating as foil-laminate replacements, with higher capital requirements but simplified recycling streams and club-store visibility.
- Boxed:Paperboard formats for multipack club-store configurations, gaining share as retailers prioritize shelf-ready display efficiency.
- Bulk Packaging:Foodservice-oriented formats for institutional and commercial baking operations with minimal retail branding requirements.
Foil bags retain the largest installed base; plastic tubs are climbing the fastest.
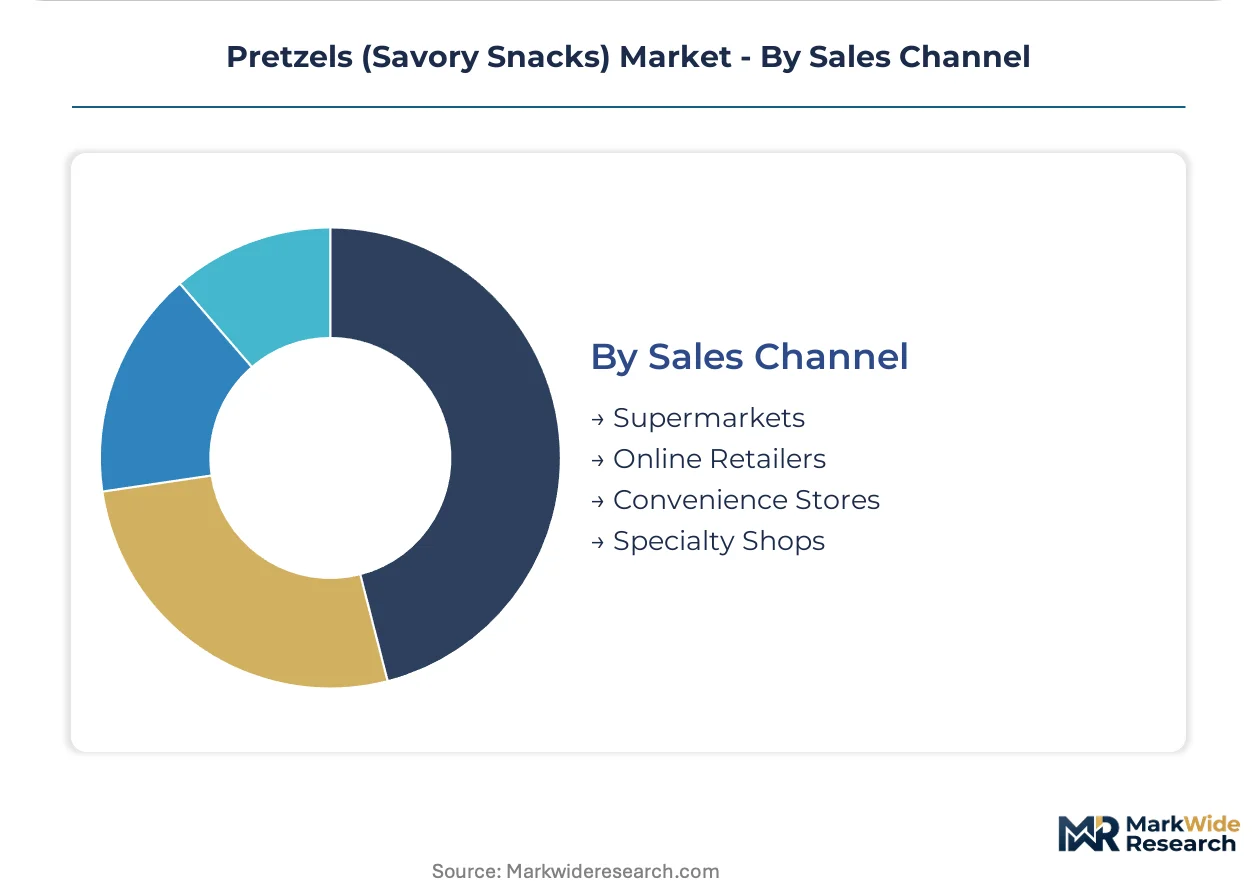
Sales Channel:
Customer type differentiation separates impulse-driven convenience purchasers from planned grocery buyers and subscription-based corporate pantry services.
- Convenience Stores:Grab-and-go focused locations with refrigerated perimeter placement and warming station investments, expanding pretzel placements as commuter traffic patterns favor transit-adjacent impulse purchases in United States metropolitan markets.
- Specialty Shops:Curated assortments with higher experimentation tolerance for novel flavors and regional craft brands, concentrated in United States coastal urban centers.
- Supermarkets:Traditional center-store and perimeter retail with slotting fee structures favoring established brands with direct-store delivery scale.
- Online Retailers:E-commerce platforms enabling flavor variety discovery and subscription recurrence without physical shelf-space constraints.
Supermarkets hold the largest share; specialty shops are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity diverges sharply across geographies. United States consumers absorb premium positioning at airport kiosks, while Indian buyers gravitate toward economy formats in modern trade. European purchasers split between discounter private-label and craft-positioned regional brands.
United States
Mall-based foodservice and stadium concession channels sustain impulse pricing power. FDA sodium reduction guidance is compressing formulation timelines for national brands. Philadelphia and Baltimore corridor anchor direct-store delivery density for hard pretzel distribution.
Germany
Bakery tradition supports artisan-positioned savory snack acceptance in retail. ECHA REACH compliance is elevating packaging material documentation burdens for imported seasonings. Munich and Stuttgart metropolitan clusters concentrate pretzel chip manufacturing for private-label export.
India
Urban convenience retail expansion in Mumbai and Bangalore creates shelf-space for imported formats. FSSAI labeling mandates are tightening ingredient declaration requirements for wheat-flour products. Gujarat industrial belt hosts contract manufacturing for regional savory snack brands.
Japan
Premium gifting culture sustains higher per-unit pricing for packaged snacks. METI plastic resource circulation guidelines are accelerating mono-material packaging transitions. Nagoya-Chubu corridor concentrates automated baking equipment suppliers serving regional producers.
United Kingdom
Discounter channel growth is compressing branded shelf-stable snack margins. UK Plastic Packaging Tax is forcing rapid transitions from metallized films to paper-based formats. West Midlands manufacturing cluster hosts co-packing operations for European brand entrants.
Pretzels (Savory Snacks) Market Competitive Landscape
Capability concentration sits with specialized flavor houses and regional bakery operations; scale advantage sits with diversified snack conglomerates with direct-store delivery infrastructure. The market structures around three archetypes: mass-market packaged brands, captive-audience foodservice operators, and contract manufacturing specialists. Dominant competitive moves include portfolio diversification into adjacent cracker and puffed snack categories, and geographic expansion through acquisition of regional bakery assets.
Within the diversified-snack tier, PepsiCo and ConAgra Brands occupy positions defined by distribution network breadth, while Utz Brands exemplifies the regional-scale specialist archetype through Mid-Atlantic and Southeast market density. Auntie Anne's represents the captive-audience foodservice model with transit-hub production visibility. These three anchors illustrate how scale, specialization, and channel focus segment competitive positioning across the category.
| Leading Market Players |
|---|
| J&J Snack Foods |
| ConAgra Brands |
| PepsiCo |
| Campbell Soup Company |
| General Mills |
| Intersnack Group |
| Pretzels Inc. |
| Utz Brands |
| Auntie Anne's |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in hard pretzel manufacturing across the Mid-Atlantic corridor is compressing spot-market wheat flour pricing while forcing regional producers toward long-term offtake contracts with Kansas City Board of Trade suppliers to lock in margin stability.
Pricing Analysis
Contract-based long-term offtake agreements dominate wheat flour procurement, with spot purchases reserved for demand surges. Three-tier pricing structure across premium, standard, and economy levels separates Auntie Anne's airport kiosk positioning from Utz Brands' grocery multipacks and private-label discounter offerings. Pricing pressure stems from wheat futures volatility and California packaging compliance costs. Discounter channel buyers exhibit highest price sensitivity; captive-audience transit hub consumers absorb premium positioning with minimal elasticity.
Supply Chain Analysis
Export-control regimes on potassium chloride blending technology from German and Japanese flavor houses are constraining sodium-reduction formulation access for mid-sized regional bakeries. Wheat milling concentrates in the United States, Germany, and India; seasoning inputs draw from Chinese capsicum processors and European yeast-extract suppliers. Single-source vulnerability runs through specialized multilayer film converters facing California extended producer responsibility stranding. Distribution runs through direct-store delivery networks anchored by Frito-Lay infrastructure and regional bakery fleet density.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pretzel market expansion sits in early-cycle positioning as airport kiosk deployment accelerates traveler foot traffic recovery and clean-label reformulation opens institutional procurement pathways under USDA Smart Snacks standards.
For Market Incumbents: Build direct-store delivery density as the defensive moat against PepsiCo's multiplex and stadium channel dominance. Anchor regional bakery acquisition strategies in Southeast metropolitan corridors to preempt Utz Brands' expansion. Deepen backward integration into wheat milling to offset Kansas City Board of Trade futures exposure. Prioritize potassium chloride blending technology licensing from specialized flavor houses before R&D contractor rates inflate further. For New Entrants and Emerging Players: India's urban convenience retail underpenetration offers white-space shelf allocation in Mumbai and Bangalore modern trade formats. Target corporate pantry subscription channels bypassing traditional grocery slotting fees through direct-to-office recurring revenue models. Lead with yeast-extract flavor enhancement positioning to differentiate from potassium chloride aftertaste limitations in clean-label reformulation segments. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across pretzel chip manufacturing as California and New York packaging compliance forces foil-laminate line retooling toward mono-material tub injection molding. Long-term viability favors contract manufacturing specialists with co-packing flexibility across hard pretzel, pretzel chip, and soft pretzel formats. Monitor FDA sodium reduction guidance enforcement intensity as the primary inflection signal for reformulation investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Reformulation Partnership | Yeast-extract flavor house collaborations enable FDA sodium compliance without sensory trade-offs. |
| Airport Kiosk Network Expansion | Captive-audience locations in Dallas-Fort Worth and Denver sustain premium pricing through made-to-view production. |
| Mono-Material Packaging Conversion | Polyethylene tub transitions address California extended producer responsibility stranding of metallized films. |
| Direct-to-Office Subscription Launch | Corporate pantry services capture hybrid-workplace snacking occasions without retail slotting fee burdens. |
| Regional Bakery Acquisition | Mid-Atlantic and Southeast direct-store delivery density anchors grocery channel shelf stability. |
Research Methodology
Operator-level perspectives from pretzel manufacturing plant managers, Frito-Lay distribution channel partners, grocery category buyers, and airport foodservice concession operators anchored the qualitative base. Primary fieldwork combined with secondary validation from FDA sodium guidance documentation, USDA Smart Snacks compliance databases, Kansas City Board of Trade wheat futures records, and California extended producer responsibility regulatory filings. Bottom-up facility capacity assessments triangulated against top-down retail velocity data from Nielsen and Circana audit sources.
Scenario-bracketing framed volume and value outputs across the projection horizon, with segmentation dimensions spanning product format, flavor profile, packaging type, and sales channel. CAGRs derived from wheat input cost trajectories, packaging capital expenditure cycles, and traveler foot traffic recovery patterns. Forecast inputs incorporated potassium chloride blending technology adoption curves and extended producer responsibility compliance timelines.
Practitioners should monitor FDA enforcement intensity on sodium reduction targets and California packaging regulation implementation pace for early signals. Forecasts reflect assumptions on wheat price stability and traveler traffic normalization. Material shifts in wheat futures volatility or extended producer responsibility law expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
North America Snack Bar Market
Snacks
Cheese Snacks Market
Snacks
No Fat Snacks Market
Snacks
North America Energy Bar Market
Snacks
Latin America Extruded Snack Food Market
Snacks
Candy and Snack Food Pouches Market
Snacks
Saudi Arabia French Fries Market
Snacks
North America Pretzel Market
Snacks
Europe Snacks Food Market
Snacks
Low Calorie Snacks Market
Snacks
South Africa Snack Bar Market
Snacks
United Kingdom Snack Bar Market
Snacks
Snacks Market
Snacks
North America Snack Pellets Market
Snacks
On-The-Go Healthy Snacks Market
Snacks
Asia Pacific Snack Food Market