
 South America Snack Bar Market | 2026-2036
South America Snack Bar Market Size, Share, and Industry Trends Forecast 2026-2036
South America Snack Bar Market Analytics
The South America snack bar category is recalibrating around a widening gap between premium clean-label offerings and commodity-priced standard bars. Kellogg Company leverages its regional manufacturing footprint to sustain volume leadership in granola bars across Brazilian retail channels. Nestle S.A. differentiates through specialized protein formulations targeting athlete segments in Argentina and Chile. Mondelez International competes by extending its chocolate-flavored portfolio into convenience-store impulse locations.
A snack bar denotes a molded, shelf-stable food product combining cereals, proteins, fruits, or nuts with binding agents, typically achieving moisture content below 15% for ambient stability and serving as a portable meal replacement or energy supplement. Granola bars occupy the mature volume core of the South American market, while protein bars capture expanding margin pools among health-conscious consumers and athletes. Supermarkets dominate distribution throughput, though online retailers represent the fastest-growing channel as urban professionals shift toward subscription-based replenishment.
ANVISA enforces front-of-package warning labels and sodium caps that reshape formulation requirements for manufacturers operating in Brazil. Argentina's national food code and Chile's Law 20.606 on nutritional composition impose parallel restrictions on sugar content and advertising claims across the Andean markets. Stakeholders must monitor evolving Mercosur harmonization talks and decide whether to standardize recipes regionally or maintain country-specific product lines.
Market Dynamics
ANVISA's front-of-package warning label mandate is compressing formulation flexibility for manufacturers serving Brazil, forcing simultaneous reformulation across sodium, sugar, and saturated fat dimensions while competitors race to maintain sensory appeal under tighter compositional constraints.
Growth Catalysts
- Protein fortification technology:Microencapsulation and extrusion advances enable stable incorporation of whey and plant isolates into ambient-stable bars without textural degradation, expanding addressable demand among athlete and fitness segments in São Paulo and Buenos Aires.
- Chile's Law 20.606:Nutritional composition standards and advertising restrictions on high-sugar products have normalized cleaner-label expectations, creating regulatory pull-through that premium manufacturers leverage for margin expansion across Andean markets.
- Southeastern Brazil urban corridor:Concentrated purchasing power across São Paulo, Rio de Janeiro, and Belo Horizonte generates sufficient volume density to justify dedicated production lines and localized flavor development for regional palate preferences.
Market Restraints
- Input cost volatility:Global whey protein concentrate and specialty nut prices fluctuate with dairy futures and harvest cycles, compressing gross margins for protein-focused SKUs when commodity markets tighten.
- Supply concentration risk:Binding syrup and hydrocolloid suppliers cluster in southern Brazil and Argentina's Pampas region, exposing manufacturers to localized logistics disruptions and currency-driven import cost spikes.
- Moisture-barrier limitation:Current biodegradable film technologies fail to match synthetic multilayer films for oxygen and vapor transmission rates, constraining shelf-life extension for clean-label positioning.
Strategic Opportunities
- Colombian market penetration:Per capita snack bar consumption trails Brazil by a significant multiple, with Bogotá and Medellín showing early adoption signals among urban professionals that warrant dedicated market development investment.
- Subscription channel innovation:Direct-to-consumer replenishment platforms bypass traditional retail slotting fees and enable first-party data capture for personalized flavor and nutrition recommendations.
- Mercosur harmonization tailwind:Converging technical regulations across member states would reduce SKU proliferation costs and enable centralized production with streamlined cross-border distribution.
Industry Challenges
- Formulation talent scarcity:Food technologists with dual expertise in protein chemistry and extrusion processing command premium compensation, constraining R&D throughput for mid-tier manufacturers.
- Compliance timeline compression:ANVISA's phased implementation of updated nutrition labeling creates overlapping reformulation deadlines with Argentina's national food code revisions, straining analytical laboratory capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Snack Bar Market |
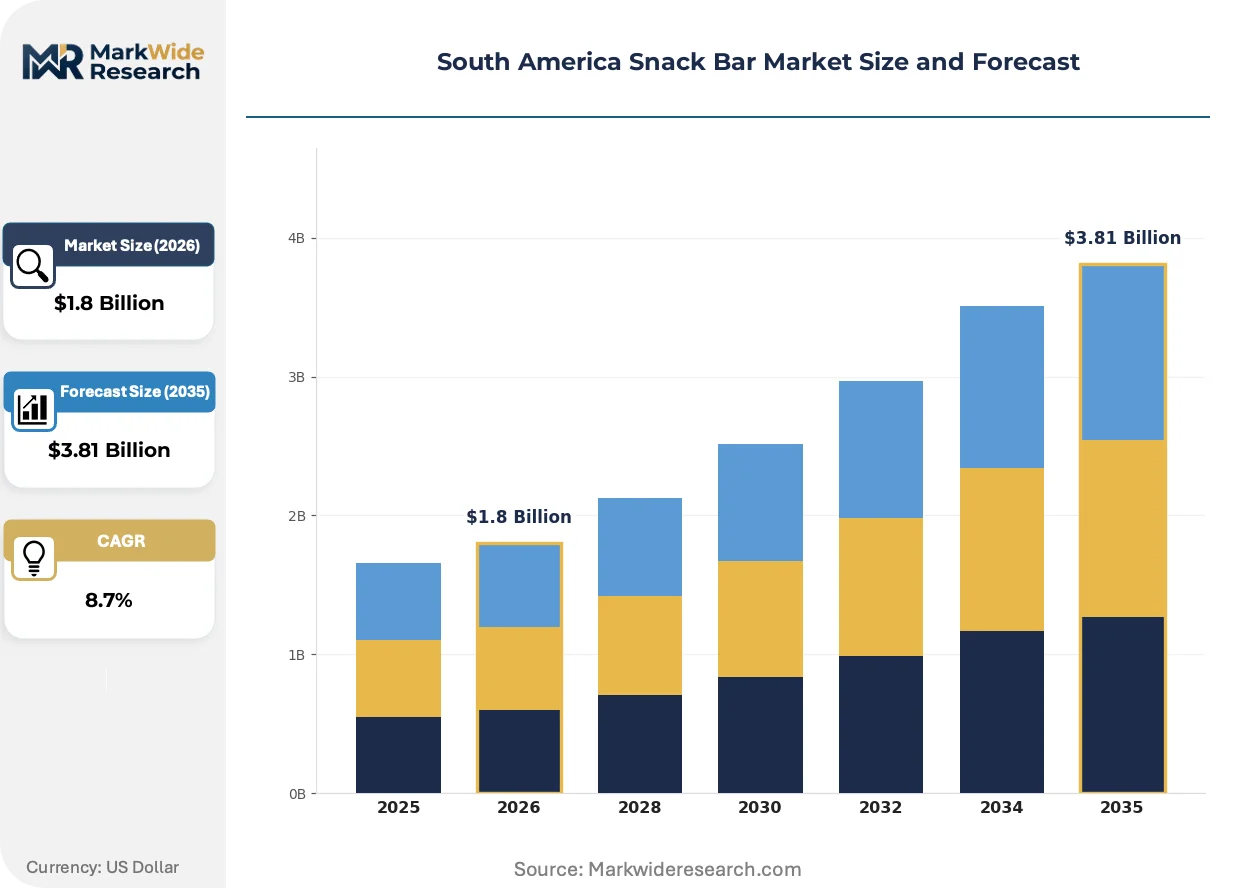
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granola Bars, Protein Bars, Energy Bars, Fruit Bars Distribution Channel: Supermarkets, Convenience Stores, Online Retailers, Specialty Stores Consumer Type: Health-Conscious Consumers, Athletes, Students, Busy Professionals Flavor Profile: Chocolate, Nutty, Fruity, Savory |
| Companies Covered | Kellogg Company, General Mills Inc., Nestle S.A., PepsiCo Inc., Post Holdings, Mars Inc., Mondelez International, Natural Balance Foods, The Hain Celestial Group, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Snack Bar Market Evolving Landscape
Clean-label binding systems and precision fermentation-derived proteins are displacing conventional ingredient palettes, while digital traceability platforms reshape how manufacturers demonstrate provenance claims to skeptical urban consumers.
Pea and fava protein isolates are integrating into high-inclusion formulations previously dominated by dairy proteins, achieving functional parity through enzymatic hydrolysis and lipid coating technologies. Brazilian sports nutrition brands and Argentine wellness retailers are adopting these alternatives at accelerating rates to capture flexitarian and lactose-intolerant demand segments. This ingredient pivot is integrating new supply chain partnerships with domestic pulse processors and compressing reliance on imported whey concentrates.
ANVISA's updated nutrition labeling rules enforce front-of-package octagonal warning symbols for products exceeding sodium, sugar, or saturated fat thresholds, compelling reformulation across mass-market portfolios. Manufacturers must now reconcile sensory benchmarks with hard compositional ceilings or accept visibility penalties in Brazilian retail environments. Protein bar and granola categories face disproportionate impact given their historical reliance on honey, chocolate coatings, and binding syrups for palatability.
Urban professionals in São Paulo and Santiago are consolidating purchases through subscription-based replenishment models that displace intermittent convenience-store buying. These platforms capture predictable demand while offering customization interfaces for macronutrient targets and flavor rotation preferences. Digital-native challenger brands exploit this channel most aggressively, bypassing traditional retail gatekeepers that favor established multinationals with slotting fee capacity.
South America Snack Bar Market Segmentation
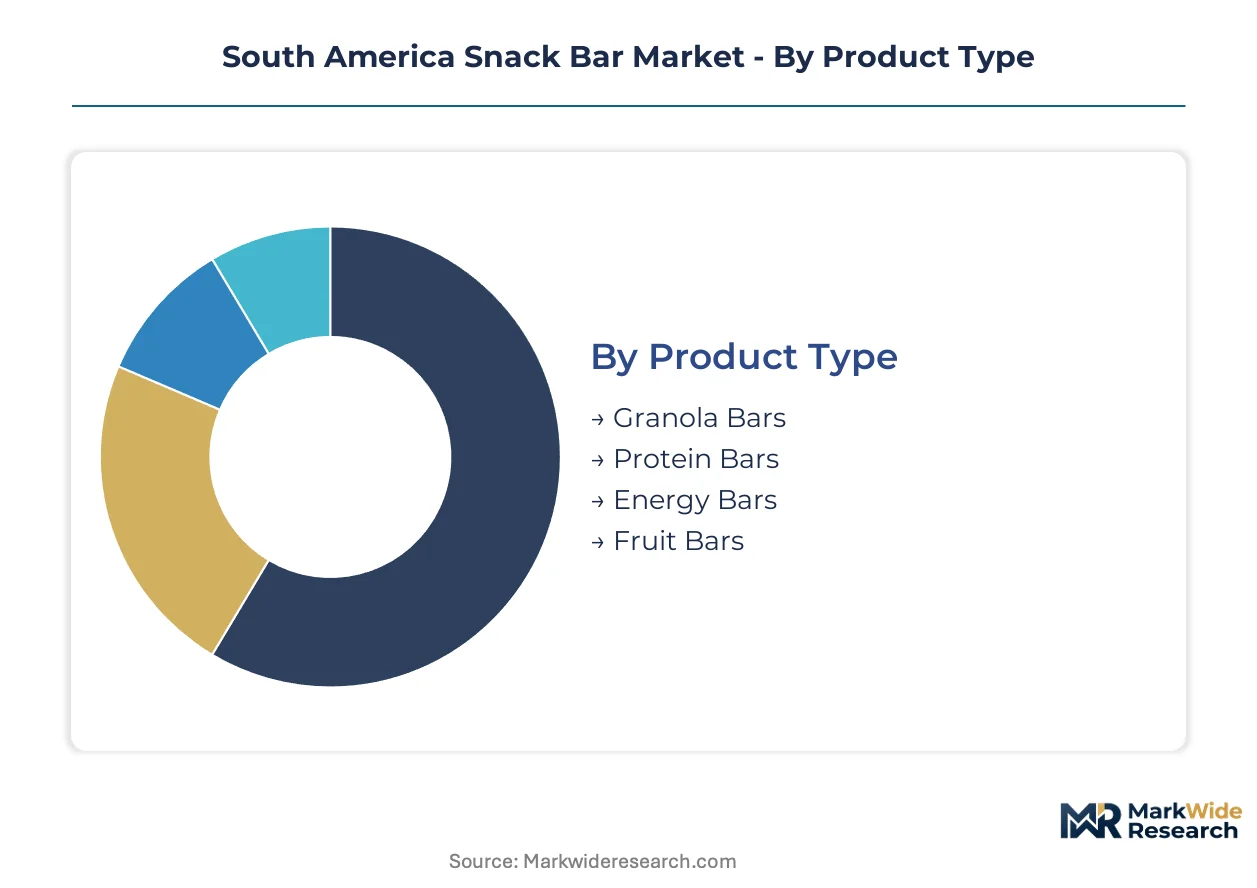
Snack bar manufacturers in South America must balance standardized formulations for regulatory compliance against localized variants that capture regional palate preferences. Segmentation reveals where volume concentrates versus where margins expand.
Product Type:
Standardization pressure from ANVISA's warning label thresholds compresses recipe flexibility, yet premium positioning demands differentiated formats.
- Granola Bars:Oat-based formulations with honey or syrup binding achieve moisture content below 15% for ambient shelf stability. São Paulo and Rio de Janeiro supermarkets move the highest throughput, though ANVISA's sugar caps are forcing binding agent substitutions.
- Protein Bars:Whey or plant-isolate fortification targets 15-25g protein per serving through extrusion or cold-press processing. Buenos Aires and Santiago athlete segments drive premium pricing, with microencapsulation advances solving texture degradation in ambient storage.
- Energy Bars:Carbohydrate-dense formats emphasizing rapid glycemic response for endurance activities.
- Fruit Bars:Compressed dried fruit matrices with minimal added sweeteners, popular in Chile's clean-label retail environment.
Most installed capacity flows through Granola Bars. Expansion is steepest in Protein Bars.
Distribution Channel:
Cost-to-serve economics and slotting fee structures determine which channels manufacturers prioritize for margin defense versus volume acquisition.
- Supermarkets:Hypermarket and supermarket chains in Brazil's southeastern corridor command the dominant throughput share, with centralized distribution reducing logistics overhead. Shelf-space competition intensifies as ANVISA-compliant reformulations multiply SKU counts.
- Convenience Stores:Impulse-oriented placement captures grab-and-go demand from urban commuters in Santiago and Buenos Aires. Chocolate-coated and single-serve formats outperform here, though price sensitivity limits premium protein positioning.
- Online Retailers:Subscription replenishment models bypass traditional slotting fees and enable direct consumer data capture.
- Specialty Stores:Sports nutrition and organic retailers in São Paulo's Pinheiros district and Buenos Aires' Palermo neighborhood curate premium assortments.
Volume concentrates in Supermarkets. Online Retailers are climbing the fastest.
Consumer Type:
Application-driven segmentation separates sustained daily consumption from occasion-based purchasing with divergent price elasticity profiles.
- Health-Conscious Consumers:Flexitarian and clean-label seekers prioritize ingredient transparency and low processing indicators. Chile's Law 20.606 has normalized their expectations across Andean markets, compressing acceptance of artificial additives.
- Athletes:Competitive and recreational sports participants demand precise macronutrient ratios with batch-tested protein claims. São Paulo's CrossFit and cycling communities sustain dedicated brand loyalty for verified formulations.
- Students:Price-sensitive convenience seekers in university corridors of Bogotá and Medellín.
- Busy Professionals:Time-constrained urban workers in São Paulo and Santiago consolidating purchases through subscription platforms.
The largest consumer base sits with Health-Conscious Consumers. Athletes deliver the steepest expansion trajectory.
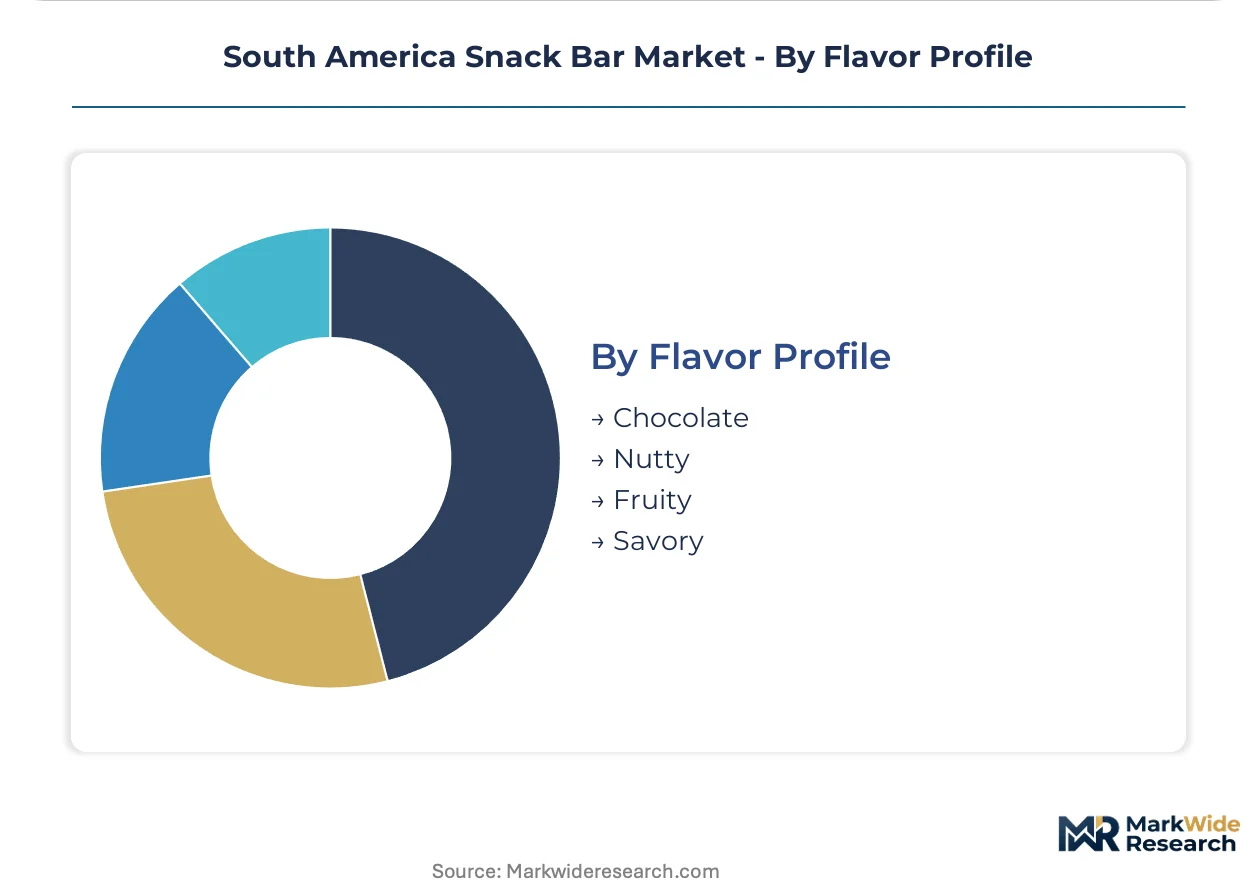
Flavor Profile:
Palate localization requirements vary sharply across South American markets, complicating regional recipe standardization efforts.
- Chocolate:Cocoa-based coatings and inclusions dominate Brazilian mass-market preferences, though ANVISA's sugar thresholds are forcing dark chocolate substitutions and reduced-syrup binding systems that alter mouthfeel profiles.
- Nutty:Peanut, almond, and Brazil nut combinations resonate in Argentina's traditional confectionery culture. Local Pampas-region nut processors supply raw materials, though harvest volatility introduces margin pressure.
- Fruity:Acai, guava, and passionfruit variants capture Brazilian regional identity positioning.
- Savory:Emerging cheese and seed-based formats testing acceptance in Chile's experimental urban retail.
Chocolate commands the highest installed capacity. Nutty formats are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil commands the dominant volume position while Argentina concentrates premium protein bar innovation, creating divergent growth profiles across the southern cone. Chile's regulatory environment pulls through clean-label expectations that reshape competitive positioning in Andean markets. Colombia's underpenetrated urban corridors now attract dedicated market development investment.
Brazil
São Paulo's metropolitan corridor generates sufficient demand density to justify dedicated production lines for regional palate preferences. ANVISA's front-of-package warning label mandate forces simultaneous reformulation across sodium, sugar, and saturated fat dimensions. Rio de Janeiro and Belo Horizonte supermarkets move the highest granola bar throughput as health-conscious consumers expand purchases of protein-fortified formats.
Argentina
Buenos Aires athlete segments sustain premium pricing for specialized protein formulations targeting competitive and recreational sports participants. The national food code imposes parallel restrictions on sugar content and advertising claims that compress recipe flexibility. Pampas-region nut processors supply raw materials for traditional confectionery-influenced bar formats, though harvest volatility introduces margin pressure.
Chile
Santiago urban professionals consolidate purchases through subscription-based replenishment models that displace intermittent convenience-store buying. Law 20.606 on nutritional composition normalizes cleaner-label expectations across Andean markets, creating regulatory pull-through for premium manufacturers. The city's experimental urban retail tests emerging savory cheese and seed-based formats.
Colombia
Bogotá and Medellín show early adoption signals among university corridor students and time-constrained professionals that warrant dedicated market development investment. The country's national food regulator enforces evolving disclosure requirements that parallel Mercosur harmonization talks. Per capita snack bar consumption trails Brazil by a significant multiple, indicating expansion headroom.
South America Snack Bar Market Competitive Landscape
Top-tier vendors anchor mass-market volume through established retail slotting relationships, while mid-tier specialists and digital-native challengers compete on formulation differentiation and direct channel access. The market structure reflects moderate consolidation around multinational packaged food conglomerates with regional manufacturing footprints. Three strategic archetypes dominate: scale-driven mass-market suppliers, premium protein formulation specialists, and subscription-platform digital natives. Competitive moves center on portfolio diversification into clean-label variants and geographic expansion into underpenetrated Andean corridors.
Within the multinational conglomerate tier, Kellogg Company and Nestle S.A. exemplify divergent strategic positioning—Kellogg leveraging regional manufacturing infrastructure for volume leadership in Brazilian retail channels, Nestle differentiating through specialized protein formulations. Mondelez International occupies a position emphasizing chocolate-flavored portfolio extension into convenience-store impulse locations. These three anchors represent the spectrum from manufacturing-scale defense to premium segmentation capture.
| Leading Market Players |
|---|
| Kellogg Company |
| General Mills Inc. |
| Nestle S.A. |
| PepsiCo Inc. |
| Post Holdings |
| Mars Inc. |
| Mondelez International |
| Natural Balance Foods |
| The Hain Celestial Group |
| Others |
Value Network & Pricing Analysis
ANVISA's front-of-package warning label mandate is compressing formulation flexibility for manufacturers serving Brazil, forcing simultaneous reformulation across sodium, sugar, and saturated fat dimensions while competitors race to maintain sensory appeal under tighter compositional constraints.
Pricing Analysis
Capacity additions in Brazil's southeastern corridor are reshaping price floors for mass-market granola bars as regional manufacturers absorb fixed costs across higher throughput. Three-tier pricing structure across premium, standard, and economy levels stratifies by protein inclusion rate and certification tier, with ANVISA-compliant clean-label variants commanding measurable premiums. Price differentiation stems from binding agent substitution costs and localized flavor development investments. Students in Colombian university corridors exhibit highest price sensitivity, while Argentine athlete segments accept premium positioning for batch-tested formulations.
Supply Chain Analysis
Single-source vulnerability sits with hydrocolloid and binding syrup suppliers clustered in southern Brazil and Argentina's Pampas region. Manufacturing capacity concentrates in Brazil, Argentina, and Chile, with raw material dependencies spanning whey protein concentrates from dairy futures markets, specialty nuts from Pampas-region harvests, and pea protein isolates from domestic pulse processors. Supply chain risk centers on currency-driven import cost spikes for dairy-derived inputs. Distribution runs through hypermarket and supermarket chains with centralized logistics networks, though direct-to-consumer subscription platforms are gaining downstream share.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
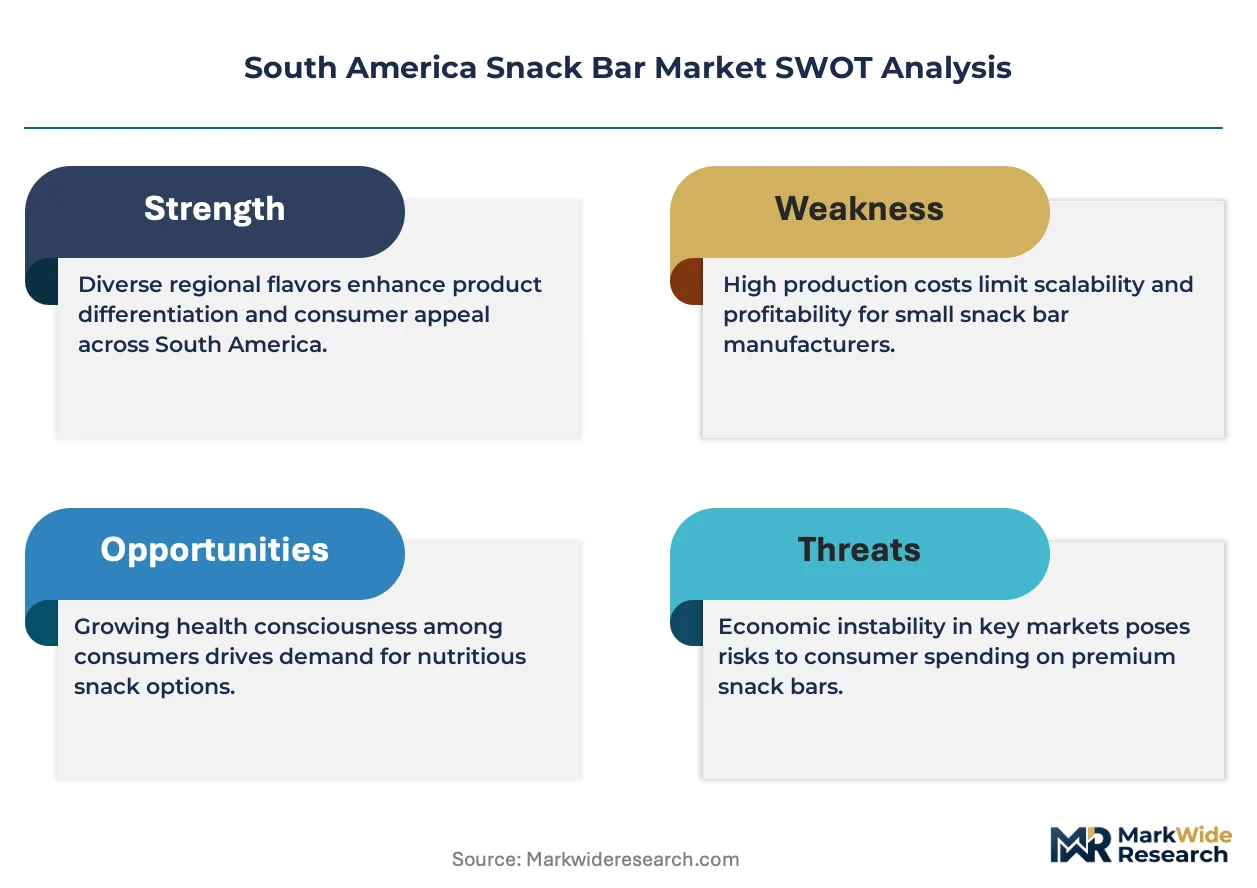
The South America snack bar market functions as a geographic-arbitrage play where manufacturers can exploit regulatory timing gaps between ANVISA's phased implementation in Brazil and Argentina's overlapping national food code revisions to optimize production location and margin capture.
For Market Incumbents: To counter digital-native challengers exploiting subscription channel bypass, incumbents must secure exclusive shelf-space agreements with Brazilian supermarket chains in the southeastern corridor while investing in microencapsulation R&D to defend protein bar texture benchmarks under ANVISA's sugar caps. For New Entrants and Emerging Players: Precision fermentation-derived protein technologies offer a technology-first wedge for entrants targeting Chile's clean-label retail environment and Colombia's underpenetrated urban corridors. White-space opportunities concentrate in Bogotá professional segments and Santiago savory format experimentation, with direct-to-consumer launch as the optimal go-to-market angle. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-tier Brazilian manufacturers possessing ANVISA-compliant reformulation capabilities and established Pampas-region nut supply relationships. Long-term viability hinges on Mercosur harmonization execution, with regulatory convergence timeline serving as the critical inflection indicator for cross-border scale economics.| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Reformulation | ANVISA compliance enables shelf-space retention in Brazilian retail. |
| Direct-to-Consumer Launch | Subscription platforms bypass slotting fees and capture first-party data. |
| Regional Production Footprint | Southeastern Brazil capacity serves density of São Paulo demand. |
| Alternative Protein Integration | Pea and fava isolates reduce whey import dependency. |
| Mercosur Harmonization Readiness | Standardized recipes enable centralized production across member states. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with brand managers, category buyers at Brazilian and Argentine retailers, supply planners, and food technology R&D directors with secondary validation through ANVISA regulatory filings, customs records, and Nielsen retail audit data. Bottom-up SKU-level volume builds triangulated against top-down category spend estimates.
Historical reference periods anchored the projection horizon to established growth trajectories, with segmentation modeling across product type, distribution channel, consumer archetype, and flavor profile dimensions. CAGRs derived from curve-fitting approaches incorporating protein fortification adoption rates, regulatory implementation timelines, and urban professional subscription penetration patterns.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Mercosur harmonization progress, currency volatility in Argentine Pampas nut pricing, and biodegradable packaging technology maturation. Forecasts reflect documented assumptions regarding regulatory phase-in schedules and consumer clean-label acceptance curves. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
United Kingdom Snack Bar Market
Snacks
Fruit and Vegetable Chips Market
Snacks
Low Sugar Fruit Snacks Market
Snacks
Packaged Rice Snacks Market
Snacks
High Fiber Snack Foods Market
Snacks
United Kingdom Energy Bar Market
Snacks
Middle-East and Africa Cereal Bar Market
Snacks
Crispy Fruit Chips Market
Snacks
Fried Potato Chips Market
Snacks
Europe Popcorn Market
Snacks
Asia-Pacific Popcorn Market
Snacks
North America Potato Chips Market
Snacks
South Africa Savory Snacks Market
Snacks
Crackers Market
Snacks
Protein Bars Market
Snacks
Brazil Snack Bar Market