
 Italy Energy Bar Market | 2026-2036
Italy Energy Bar Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Energy Bar Market Foresight
Amateur endurance sports participation is hardening as the dominant demand vertical in Italy, displacing casual snacking as the primary consumption occasion. Enervit S.p.A. leverages its heritage in cycling and triathlon nutrition to anchor premium positioning among serious athletes. Ferrero International SpA competes through its established Italian confectionery infrastructure and retail relationships. Mondelēz International, Inc. extends its European snack distribution network to occupy shelf space in convenience channels where impulse purchases concentrate.
Italy energy bars are formulated food products combining carbohydrates, proteins, and fats in shelf-stable formats, typically manufactured through cold-press extrusion or baked slab-and-cut processes, designed to deliver rapid glycemic response and sustained energy release during physical exertion. Protein bars command the deepest margin pools as consumers trade up for whey and plant-isolate formulations with verified amino acid profiles. Vegan bars represent the fastest-expanding product type as Italian consumers shift toward legume-derived proteins and away from dairy-based formulations. Supermarkets sustain volume leadership through promotional bundling and private-label placement, though online retail captures the highest growth rate in subscription and direct-to-athlete models.
Italy's Ministry of Health enforces EU Regulation 1924/2006 on nutrition and health claims, restricting how energy bars market performance benefits without EFSA-approved substantiation. The EU F-Gas Regulation indirectly shapes cold-chain logistics costs for temperature-sensitive ingredient imports. Stakeholders must monitor whether Italy's national pharmaceutical regulator, AIFA, extends oversight into sports-nutrition border categories that currently fall under standard food law.
Market Dynamics
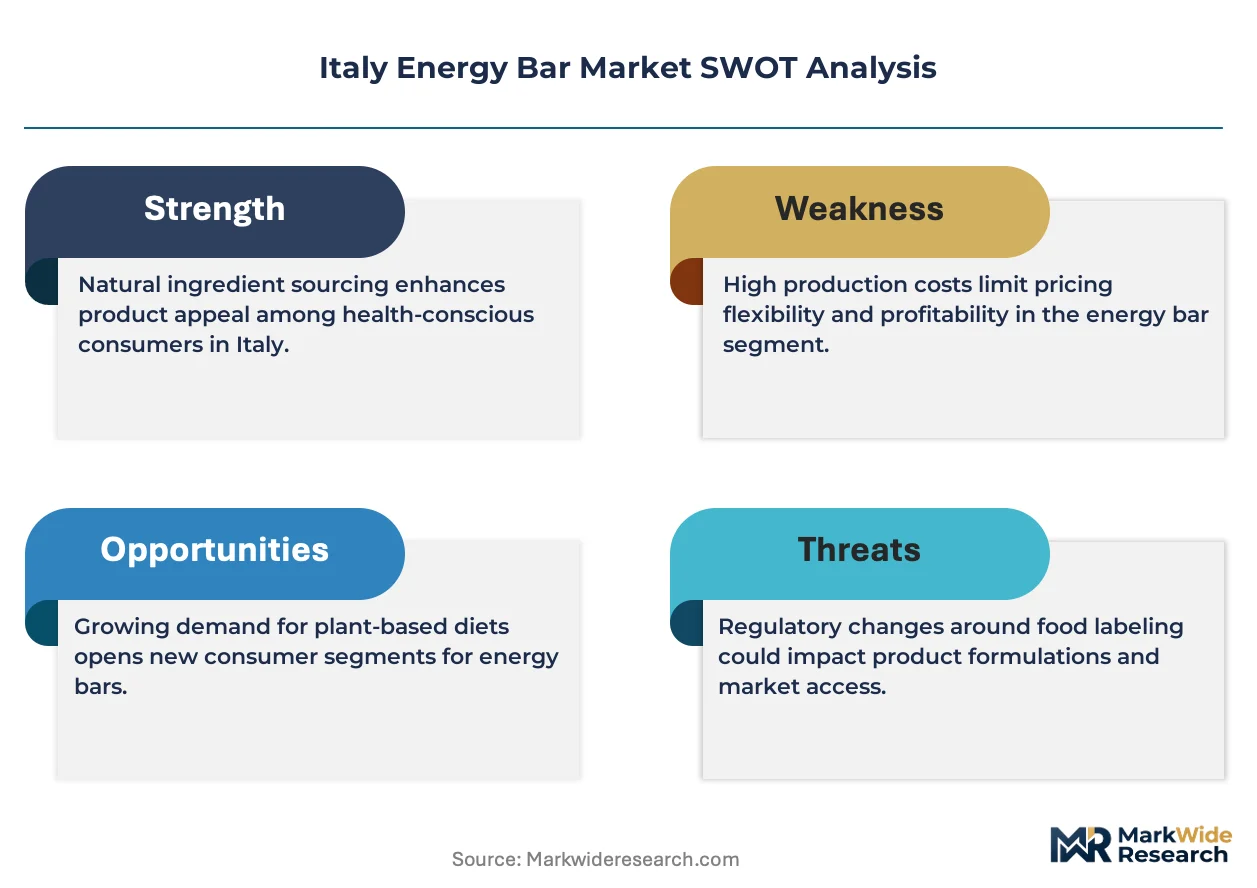
Italy's energy bar market is hardening around endurance-sport nutrition as amateur athletes displace casual snackers as the core demand base. Cold-press extrusion equipment and EU health-claim enforcement are concentrating competitive advantage among manufacturers with verified formulation science.
Growth Catalysts
- EU Nutrition and Health Claims Regulation:EFSA-approved substantiation requirements are filtering out unsubstantiated performance claims, rewarding compliant Italian manufacturers with shelf-space security in pharmacy and sports-retail channels.
- Milan-Turin corporate wellness infrastructure:Northern Italy's dense network of employer-sponsored fitness programs is institutionalizing energy-bar consumption as standard pre-workout protocol among white-collar professionals.
- Plant-protein extraction technology:Advances in legume-isolate processing are enabling cost-competitive vegan formulations that match whey amino-acid completeness, accelerating category expansion beyond dairy-dependent SKUs.
Market Restraints
- Whey protein import dependency:Italian manufacturers rely on northern European dairy processors for high-grade isolates, exposing margin compression when euro-denominated input costs fluctuate against domestic pricing power.
- EFSA substantiation timelines:The 12-18 month approval cycle for novel health claims freezes marketing innovation and locks smaller players into generic positioning without differentiation leverage.
- Fresh snack substitution:Italian consumers retain strong preference for unprocessed alternatives—fresh fruit, nuts, bakery items—limiting energy-bar penetration in convenience and impulse channels outside gym environments.
Strategic Opportunities
- Southern Italy underpenetration:Naples, Bari, and Palermo exhibit sub-40% gym penetration versus northern benchmarks, presenting whitespace for regional distribution partnerships and localized flavor development.
- Direct-to-athlete subscription models:Triathlon and cycling clubs are consolidating purchasing power through team-level procurement, bypassing traditional retail markup structures and capturing recurring revenue streams.
- EU Green Deal packaging mandates:Accelerated biodegradable-film requirements favor domestic Italian converters with compostable-lamination expertise, creating first-mover advantage in sustainable SKU positioning.
Industry Challenges
- Food-technologist talent scarcity:Formulation expertise combining sports-nutrition science with Italian taste-profile preferences concentrates in Emilia-Romagna's food-tech corridor, forcing national brands into wage competition with Parma's cured-meat and dairy conglomerates.
- Cold-chain reconfiguration for temperature-sensitive isolates:F-Gas Regulation phase-downs are obsoleting existing refrigeration assets, requiring capital deployment into CO2-based systems for peptide and probiotic ingredient integrity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Energy Bar Market |
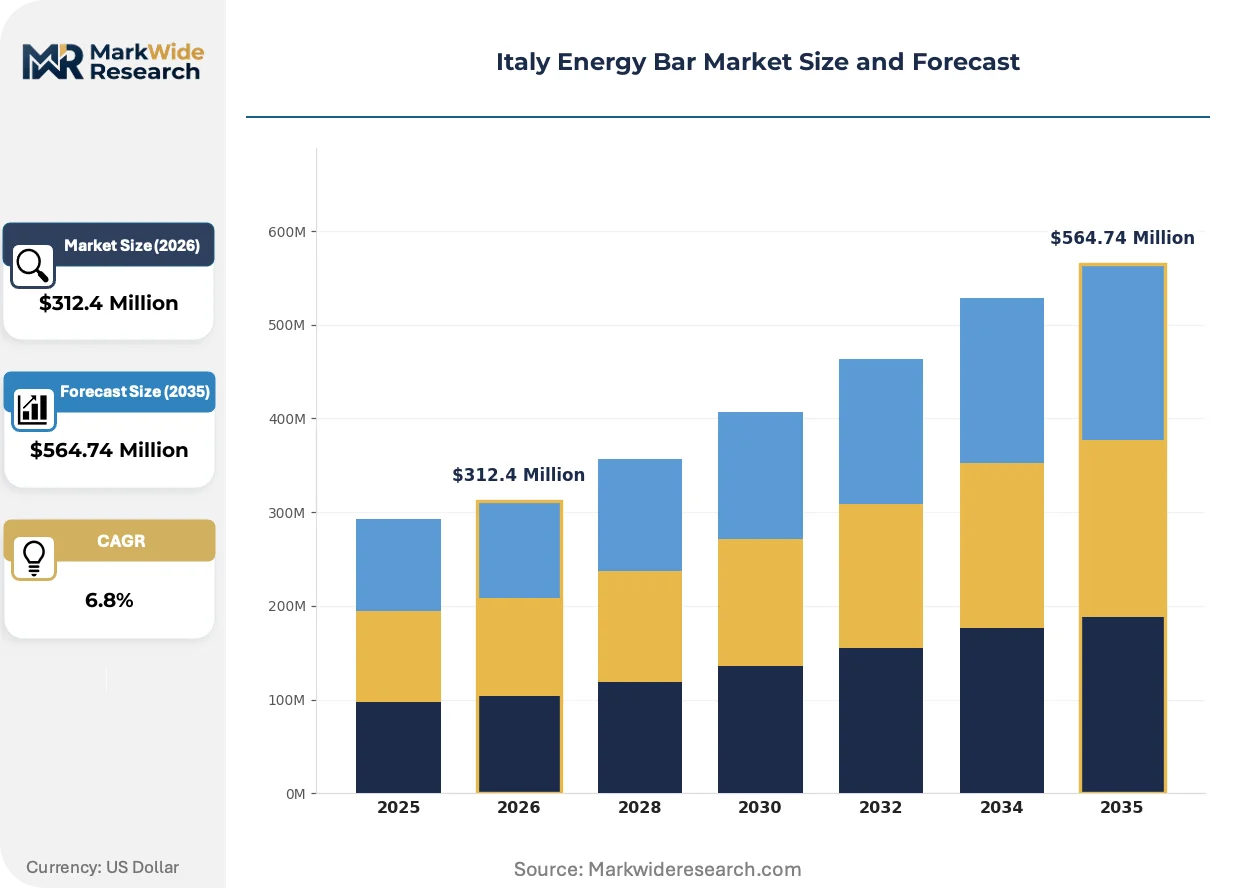
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nut-Based, Protein Bars, Granola Bars, Vegan Bars Distribution Channel: Supermarkets, Online Retail, Health Stores, Convenience Stores Target Consumer: Fitness Enthusiasts, Athletes, Busy Professionals, Health-Conscious Individuals Flavor Profile: Chocolate, Vanilla, Berry, Caramel |
| Companies Covered | Enervit S.p.A., Ferrero International SpA, Mondelēz International, Inc., Post Holdings, Inc., Abbott Laboratories, Nestlé S.A., Kellogg Company, General Mills Inc., Mars Incorporated, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Energy Bar Market Shifts & Advancements
Formulation transparency and supply-chain digitization are compressing traditional competitive moats in Italian energy-bar manufacturing. Three developments are restructuring how value is created and captured.
Pea-protein isolate is absorbing the functional role previously occupied by whey concentrates in mid-tier Italian energy bars. Amateur cyclists and trail runners in the Dolomites are adopting plant-based SKUs at rates that now match dairy formulations in Milan's specialty retailers. This absorption is compressing whey suppliers' volume premiums and forcing dairy-dependent brands to diversify their protein sourcing or surrender price-sensitive segments.
Italy's Ministry of Health is intensifying enforcement of EU Regulation 1924/2006 through randomized shelf audits and substantiation document requests. Manufacturers lacking EFSA-approved dossiers face delisting from pharmacy channels where margin structures exceed supermarket benchmarks by 15-20 percentage points. Premium-positioned domestic brands are responding by pre-submission investment in clinical glycemic-response studies to secure exclusive "sustained energy" claim permissions.
Corporate procurement officers in Turin's automotive and fashion headquarters are consolidating energy-bar purchasing through centralized wellness budgets rather than individual employee reimbursement. This concentration is displacing convenience-store impulse buying as the dominant volume channel for weekday consumption, privileging manufacturers with direct B2B sales infrastructure and private-label co-manufacturing capability.
Italy Energy Bar Market Segmentation
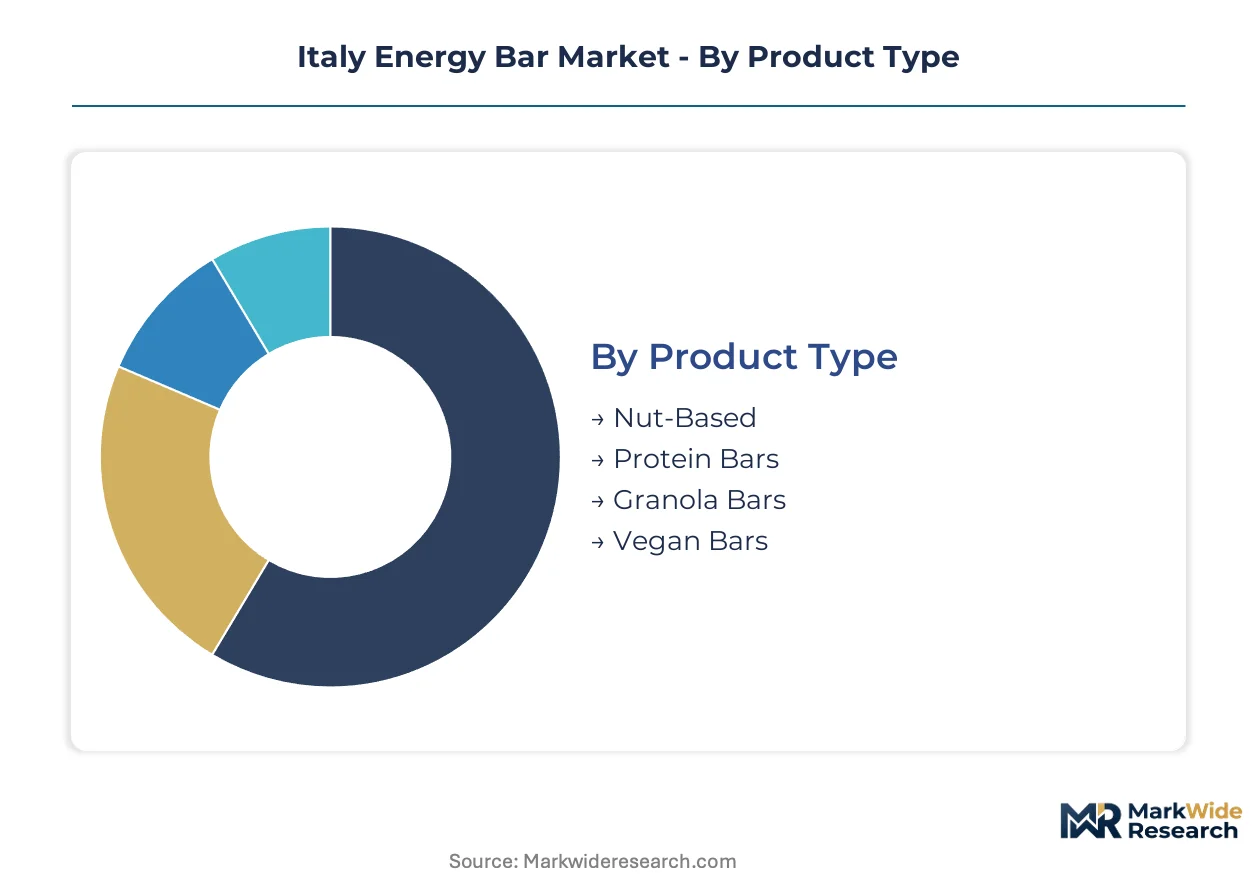
Italian energy bar manufacturers navigate four intersecting segmentation dimensions that determine formulation priorities, channel economics, and regulatory exposure. Product type and distribution channel configurations shape margin structures, while target consumer and flavor profile selections dictate R&D investment and shelf positioning strategies.
Product Type:
Integration depth varies sharply across product types, with protein bars functioning as standalone performance nutrition while granola bars embed within broader breakfast and snacking occasions.
- Protein Bars:Formulations combine whey isolates or plant proteins with controlled glycemic carbohydrates, delivering 15-25g protein per serving. Demand concentrates among amateur triathletes and cyclists in Milan and Turin, where gym penetration and corporate wellness programs institutionalize pre-workout consumption. EFSA substantiation requirements for performance claims create regulatory moats favoring manufacturers with clinical dossiers.
- Vegan Bars:Legume-derived protein isolates from pea and fava bean sources replace dairy bases, matching whey amino acid completeness through advanced extraction technology. Adoption accelerates in northern Italy's specialty retail channels as sustainability-conscious consumers trade up from conventional formulations. EU Green Deal packaging mandates favor domestic converters with compostable-lamination expertise.
- Nut-Based:Almond, hazelnut, and pistachio formulations leverage Italy's domestic orchard infrastructure, with Piedmont's hazelnut cooperatives supplying premium raw material.
- Granola Bars:Oat and honey-based formats occupy impulse and breakfast occasions, competing directly with fresh bakery alternatives in southern Italian markets.
Protein bars lead volumes today; vegan bars are gaining share fastest.
Distribution Channel:
Channel selection determines pricing power and consumer relationship depth, with direct models capturing recurring revenue while retail partnerships drive trial and scale.
- Supermarkets:Promotional bundling and private-label placement sustain volume leadership, though margin compression from retailer negotiation limits premium positioning.
- Online Retail:Subscription and direct-to-athlete models capture the steepest expansion trajectory, bypassing traditional markup structures through team-level procurement consolidation.
- Health Stores:Pharmacy-adjacent channels command 15-20 percentage point margin premiums over supermarkets, contingent on EFSA-compliant health claim substantiation.
- Convenience Stores:Impulse purchasing concentrates in urban corridors and transport hubs, though fresh snack substitution limits penetration outside gym-proximate locations.
Supermarkets dominate transaction volume; online retail expands most quickly.
Target Consumer:
Consumer archetype segmentation aligns product development with distinct usage occasions, from structured athletic protocols to unstructured workplace snacking.
- Athletes:Amateur endurance sports participants in the Dolomites and Alpine regions drive premium formulation demand, with glycemic response and electrolyte balance specifications.
- Fitness Enthusiasts:Gym members across northern Italy's corporate wellness programs consume energy bars as standardized pre-workout protocol.
- Busy Professionals:Turin's automotive and fashion headquarters consolidate purchasing through centralized wellness budgets, displacing individual convenience-store buying.
- Health-Conscious Individuals:Clean-label seekers prioritize ingredient transparency and supply-chain digitization, compressing competitive moats for legacy brands.
Athletes anchor premium revenue; busy professionals drive weekday volume concentration.
Flavor Profile:
Flavor development balances international palatability with regional taste heritage, as southern Italian markets resist standardized northern European profiles.
- Chocolate:Cocoa-based formulations dominate export-oriented production, with Ferrero's regional confectionery infrastructure influencing local expectations.
- Berry:Bilberry and raspberry variants align with Alpine foraging associations and antioxidant marketing permissible under EU health claim frameworks.
- Vanilla:Neutral profiles serve as base carriers for protein fortification, minimizing taste fatigue in high-frequency athletic consumption.
- Caramel:Indulgence-positioned SKUs compete with traditional Italian confectionery, requiring precise sweetness calibration to avoid cloying perception.
Chocolate sustains mass-market leadership; berry variants climb fastest in specialty channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage in sports-nutrition compliance is concentrating production investment in Italian regions where EFSA substantiation costs align with local R&D infrastructure. Northern industrial zones absorb disproportionate capacity expansion as southern markets remain underpenetrated.
Lombardy
Milan's corporate wellness programs and dense gym networks institutionalize energy-bar consumption among white-collar professionals. The region's food-tech corridor leverages proximity to EFSA's Parma headquarters for streamlined health-claim dossier preparation. Bergamo and Brescia host cold-press extrusion facilities serving pan-European distribution.
Piedmont
Turin's automotive and fashion headquarters consolidate procurement through centralized wellness budgets, displacing individual convenience-store purchasing. The region's hazelnut cooperatives supply premium raw material for nut-based formulations. Novara's logistics hub anchors temperature-controlled distribution for peptide ingredients.
Emilia-Romagna
Parma's food-science cluster concentrates formulation expertise combining sports-nutrition science with Italian taste-profile preferences. The region's cured-meat and dairy conglomerates compete aggressively for food-technologist talent. Bologna's packaging converters develop compostable-lamination solutions under EU Green Deal mandates.
Veneto
Verona and Vicenza exhibit expanding triathlon and cycling club density, driving team-level subscription procurement. The region's alpine proximity supports glycemic-response testing protocols for performance-claim substantiation. Padua's university research centers collaborate on plant-protein extraction technology.
Lazio
Rome's pharmacy channel commands margin premiums contingent on EFSA-compliant health claims, rewarding manufacturers with clinical dossiers. The region's bureaucratic concentration shapes AIFA regulatory monitoring for sports-nutrition border categories. Fiumicino's import infrastructure handles northern European whey isolate shipments.
Italy Energy Bar Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with premium athletic nutrition consolidating around heritage sports-nutrition houses while mass-market snacking fragments across confectionery conglomerates. The competitive terrain exhibits tiered concentration: established Italian specialists anchor pharmacy and specialty retail channels, multinational snack corporations dominate supermarket impulse placement, and private-label co-manufacturers capture corporate wellness procurement. Dominant competitive moves include portfolio diversification into plant-protein formulations and geographic expansion through direct-to-athlete subscription infrastructure.
Within the heritage sports-nutrition tier, Enervit S.p.A. and Ferrero International SpA occupy positions shaped by radically different legacy assets—one rooted in cycling and triathlon performance protocols, the other in confectionery retail relationships and domestic orchard supply chains. Mondelēz International, Inc. represents the multinational snack-network archetype, leveraging European distribution density for convenience-channel shelf presence.
| Leading Market Players |
|---|
| Enervit S.p.A. |
| Ferrero International SpA |
| Mondelēz International, Inc. |
| Post Holdings, Inc. |
| Abbott Laboratories |
| Nestlé S.A. |
| Kellogg Company |
| General Mills Inc. |
| Mars Incorporated |
| Others |
Supply & Pricing Matrix
Whey protein isolate spot prices from northern European dairy processors cascade through Italian energy bar manufacturing into three distinct pricing tiers. Premium pharmacy-channel SKUs absorb euro-denominated input volatility through brand equity buffers, while private-label supermarket offerings compress margins when commodity costs spike against fixed retail negotiation terms.
Pricing Analysis
Retailer markup structures absorb 35-50 percentage points of shelf price in supermarket channels, forcing manufacturers to claw back margin through direct-to-athlete subscription discounts that bypass wholesale layers. Three-tier pricing structure across premium pharmacy, standard retail, and economy private-label levels stratifies by EFSA claim certification and protein source grade. Cost compression in mid-tier vegan formulations is intensifying because pea-protein isolate supply expansion outpaces whey concentrate scarcity. Corporate wellness buyers in Milan and Turin exhibit lowest price sensitivity due to centralized procurement budgets, while southern Italian convenience-store shoppers remain most elastic.
Supply Chain Analysis
Direct-to-athlete channels handle consolidated team-level demand from triathlon and cycling clubs, displacing traditional distributor networks in high-frequency consumption segments. Manufacturing draws from Dutch and German whey processors, Spanish and French pea-protein isolators, and domestic Piedmont hazelnut cooperatives for nut-based formulations. Single-source vulnerability concentrates in high-grade whey isolate procurement from northern European dairy processors, exposing Italian brands to euro-commodity mismatch risk. Distribution runs through temperature-controlled logistics hubs in Novara and Bergamo serving pharmacy, supermarket, and online fulfillment channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Italy energy bar market reads as a late-cycle quality story where amateur endurance athletes trade up for EFSA-substantiated performance claims. This demand-shift toward premium specifications rewards manufacturers with clinical dossiers and pharmacy-channel access.
For Market Incumbents: Cement pharmacy-channel positioning through pre-submission investment in glycemic-response clinical studies that secure exclusive "sustained energy" claim permissions. Deepen backward integration into Piedmont hazelnut cooperatives and Emilia-Romagna packaging converters to defend margin position against plant-protein commoditization. Control team-level subscription procurement infrastructure before emerging direct-to-athlete platforms consolidate purchasing power.
For New Entrants and Emerging Players: Enter via southern Italy's underpenetrated wellness markets in Naples, Bari, and Palermo where gym penetration trails northern benchmarks by 20-plus percentage points. Target corporate wellness procurement officers in Turin's automotive and fashion headquarters through B2B sales infrastructure that displaces individual convenience-store purchasing. Launch with localized flavor development leveraging regional taste heritage distinct from standardized northern European profiles.
For Investors and Strategic Acquirers: Asymmetric upside sits with domestic contract manufacturers possessing compostable-lamination expertise under EU Green Deal packaging mandates. Long-term viability hinges on formulation science capabilities combining sports-nutrition research with Italian taste-profile preferences, not brand marketing spend. Watch AIFA regulatory monitoring signals for potential extension of pharmaceutical oversight into sports-nutrition border categories currently governed by standard food law.
| Strategic Initiative | Industry Significance |
|---|---|
| EFSA Health Claim Dossier Investment | Clinical glycemic-response studies secure 15-20 point pharmacy margin premiums over supermarkets. |
| Plant-Protein Formulation Diversification | Pea and fava bean isolates match whey amino acid completeness while hedging euro-denominated dairy import exposure. |
| Direct-to-Athlete Subscription Launch | Team-level procurement consolidation in Verona and Vicenza cycling clubs bypasses traditional retail markup structures. |
| Compostable Packaging Conversion | Bologna-based converters with biodegradable-lamination expertise capture EU Green Deal first-mover positioning. |
| Southern Italy Distribution Partnership | Regional alliances in Naples and Palermo exploit sub-40% gym penetration versus Milan-Turin benchmarks. |
Research Methodology
Coverage spans Lombardy, Piedmont, Emilia-Romagna, Veneto, and Lazio, with primary inputs from each region's food-technology corridor. The analysis combines structured interviews with sports-nutrition formulators, pharmacy category managers, corporate wellness procurement officers, and cold-chain logistics operators with secondary validation through EFSA health claim registers, EU customs trade data, Nielsen retail audit figures, and Italian Ministry of Health enforcement records. Bottom-up demand modeling from gym penetration rates and triathlon club membership rolls triangulates against top-down value estimates from manufacturer revenue disclosures.
Rate-of-change decomposition separates volume expansion from price-mix effects across the projection horizon. The analytical framework models product type, distribution channel, target consumer archetype, and regional regulatory cluster dimensions throughout the forecast period. CAGRs derive from segment-level growth rate blending weighted by base-year revenue shares. Forecast inputs incorporate EFSA substantiation timeline probabilities and EU F-Gas Regulation phase-down schedules for cold-chain asset replacement cycles.
The model holds under stable euro-dairy commodity parity and continued AIFA non-intervention in sports-nutrition classification; deviation in whey isolate supply shocks or pharmaceutical regulator scope expansion would shift volume trajectories. Forecasts reflect documented assumptions about amateur endurance sports participation growth and corporate wellness budget institutionalization. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Refrigerated Snacks Market
Snacks
Savoury Biscuits Market
Snacks
Baked Savoury Snacks Market
Snacks
Nuts and Seeds (Savory Snacks) Market
Snacks
Fat Free Meals and Snacks Market
Snacks
North America Fruit Snacks Market
Snacks
Snack Food Packaging Market
Snacks
Low Fat Sweet Snacks Market
Snacks
RTE Popcorn Market
Snacks
United Kingdom Energy Bar Market
Snacks
Roasted Corn Market
Snacks
Middle East and Africa Frozen Snacks Market
Snacks
Potato Chips Market
Snacks
Seafood Snacks Market
Snacks
Snacks Market
Snacks
Cheese Snacks Market