
 North America Cheese Market | 2026-2036
North America Cheese Market Size, Share, and Industry Trends Forecast 2026-2036
North America Cheese Market Intelligence
Canadian dairy cooperatives is restructuring milk procurement to secure consistent whey and curd flows for specialty cheese operations. Lactalis American Group leverages its Wisconsin production footprint to dominate commodity cheddar supply chains. Saputo Inc. anchors its competitiveness through backward integration into fluid milk collection networks across the Upper Midwest. BelGioioso Cheese Inc. differentiates via artisan-scale parmesan and fresh mozzarella production.
Cheese comprises milk proteins coagulated through enzymatic or acid precipitation, aged under controlled temperature and humidity to develop flavor profiles and textural properties measured by moisture content and fat-in-dry-matter ratios. Cheddar occupies the largest production volume position due to its melting functionality in prepared foods and extended shelf stability under refrigeration. Mozzarella commands premium placement in food service channels where pizza and Italian-style applications drive procurement. Shredded packaging formats capture disproportionate growth velocity as commercial kitchens prioritize labor efficiency and portion consistency.
The USDA grades cheese quality through its Agricultural Marketing Service, while the FDA enforces pasteurization standards and pathogen controls under the Pasteurized Milk Ordinance. Health Canada and the CFIA administer parallel safety protocols that govern cross-border dairy trade and ingredient disclosure requirements. Stakeholders must monitor evolving plant-based labeling disputes and state-level dairy compacts that could fragment procurement rules across provincial and federal jurisdictions.
Market Dynamics
Food service operators are accelerating cheese-forward menu development while the FDA's updated nutrition labeling requirements force reformulation trade-offs between clean-label positioning and functional performance in melted applications.
Growth Catalysts
- Quick-service restaurant expansion:Pizza chains and burger operators are adding premium cheese SKUs to limited-time offers, driving procurement volume through centralized distribution contracts.
- USDA grading standardization:The Agricultural Marketing Service's quality tiers create price transparency that reduces buyer search costs and enables premium positioning for Grade AA cheddar blocks.
- Enzymatic coagulation advances:Microbial rennet alternatives reduce production variability and extend kosher/halal certification reach into institutional food service channels.
Market Restraints
- Fluid milk price volatility:Federal Milk Marketing Order pricing swings compress processor margins, particularly for aged cheese varieties with 12-24 month inventory cycles.
- Wisconsin production concentration:Commodity cheddar supply chains cluster in a three-county radius, creating weather and logistics vulnerability for national distributors.
- Plant-based substitution:Fermented casein alternatives from precision fermentation startups capture trial among flexitarian consumers in coastal urban markets.
Strategic Opportunities
- Mexican market underpenetration:Specialty cheese imports remain below per-capita potential in Monterrey and Guadalajara metro corridors, creating white space for aged gouda and manchego-style production.
- Direct-to-foodservice distribution:Shredded and diced formats shipped in food-service pack sizes bypass traditional retail wholesale layers, capturing margin and freshness advantages.
- Canada-US dairy compact harmonization:Revised cross-border ingredient disclosure protocols under Health Canada and FDA coordination reduce compliance duplication for integrated North American operations.
Industry Challenges
- Affineur skill scarcity:Master cheesemakers with cave-aging expertise command premium wages, construring expansion of artisan parmesan and blue cheese operations.
- Pathogen testing throughput:FDA's Pasteurized Milk Ordinance enforcement requires 24-hour hold periods forListeria screening, compressing cash conversion cycles for small-batch producers.
- Legacy ERP integration:Batch tracking systems from the 1990s resist interoperability with modern cold-chain monitoring platforms, delaying real-time inventory visibility.
Report Scope
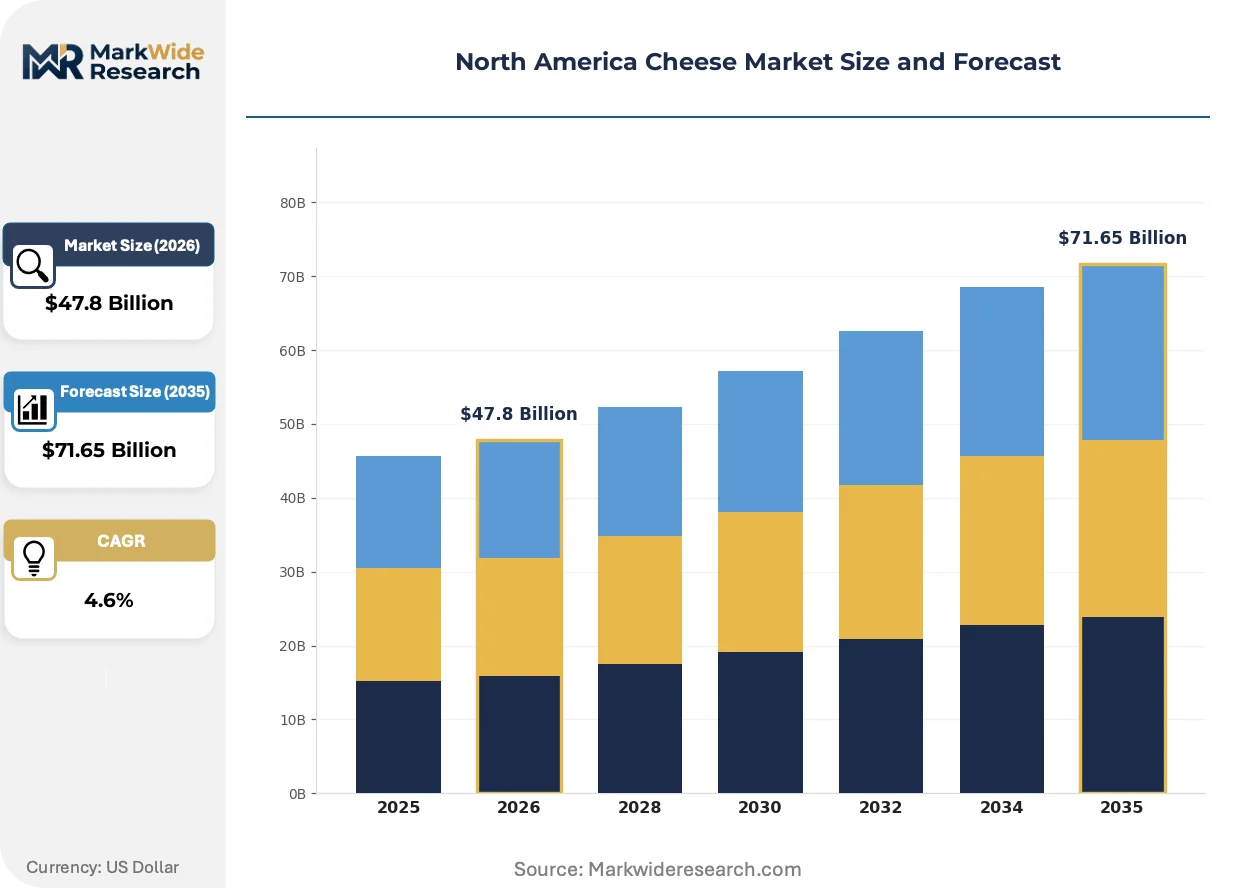
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Cheese Market |
| Market Size in 2026 | $47.8 Billion |
| Market Size in 2035 | $71.65 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cheddar, Mozzarella, Parmesan, Gouda End User: Households, Food Services, Retailers, Manufacturers Distribution Channel: Online, Supermarkets, Wholesale, Specialty Stores Packaging Type: Block, Sliced, Shredded, Grated |
| Companies Covered | Sargento Foods Inc., Lactalis American Group, The Kraft Heinz Company, Bel Brands USA Inc., Schreiber Foods, Saputo Inc., Dairy Farmers of America Inc., BelGioioso Cheese Inc., Agropur Cooperative, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Cheese Market Strategic Shifts & Innovations
Cheese production and distribution are undergoing simultaneous transformation across biological processing, regulatory disclosure, and procurement logistics. These shifts are compressing traditional supply chain layers.
Precision fermentation-derived enzymes are integrating into industrial mozzarella production, replacing animal-derived rennet with consistent microbial alternatives. Major pizza chains have approved these inputs for their supplier qualification programs over the past eighteen months. This biological substitution is integrating clean-label positioning with scale economics previously reserved for commodity production.
The FDA's updated Nutrition Facts label requirements for dairy products mandate added sugar disclosure and revised serving size calculations. Processors must reformulate flavored cheese varieties or accept degraded nutritional panel positioning. Aged natural cheese categories with minimal carbohydrate content gain relative advantage in retail planogram negotiations.
Food service buyers are consolidating purchase decisions through group purchasing organizations, displacing independent distributor relationships with contracted pricing tiers. Regional restaurant chains in the Upper Midwest and Texas metro areas have shifted 40% of their cheese procurement to GPO-administered contracts. This concentration is visible most acutely in the quick-service pizza segment, where procurement directors now negotiate directly with processor national accounts teams.
North America Cheese Market Segmentation
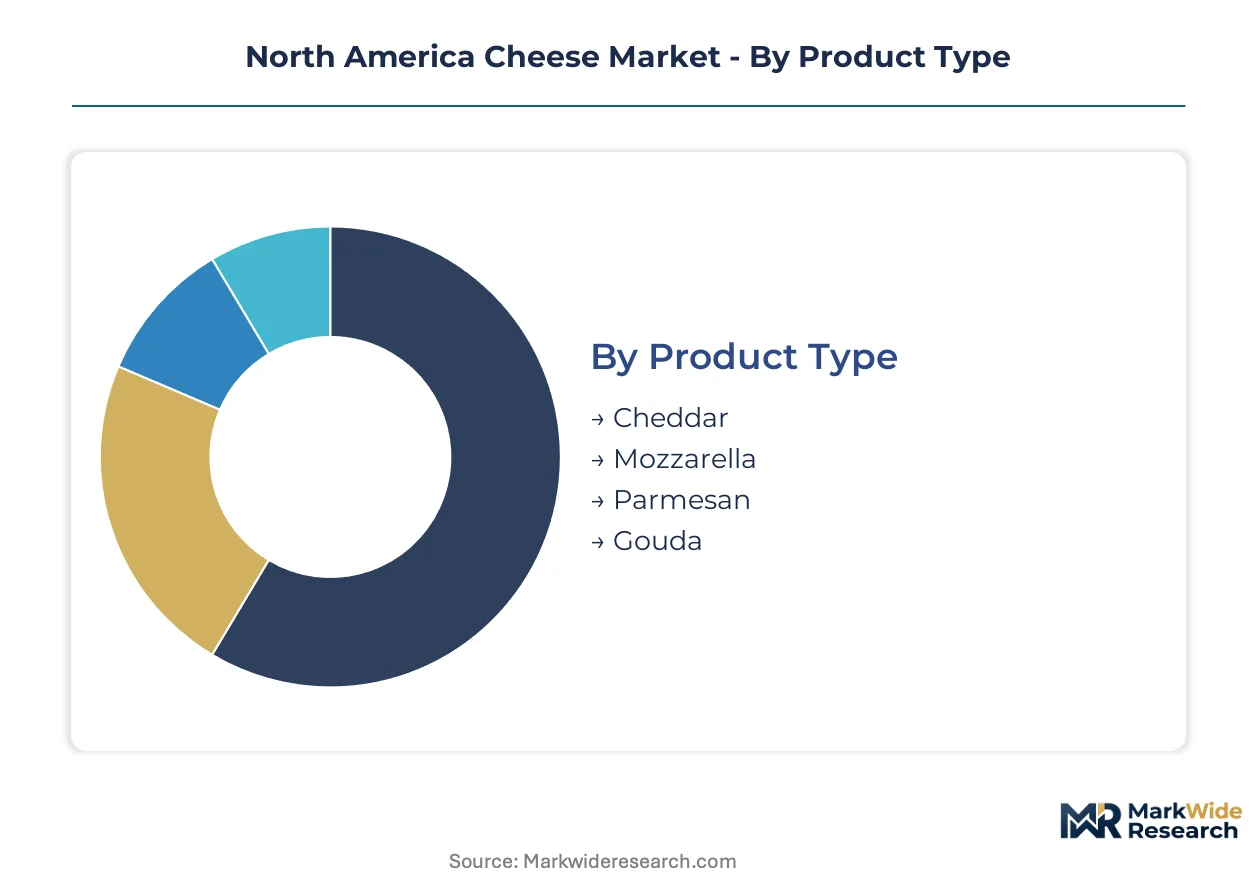
Cheese processors configure production lines around melting performance, aging requirements, and portion-control economics. Segmentation choices determine margin capture, cold-chain investment, and regulatory compliance pathways across the United States, Canada, and Mexico.
Product Type:
Standardization dominates commodity grades while specialty varieties command affineur expertise and extended inventory cycles.
- Cheddar:Aged under controlled humidity to develop sharp flavor profiles and crystalline texture. Quick-service restaurants in the Upper Midwest and Texas metro corridors drive block and shredded procurement through centralized distribution contracts. Federal Milk Marketing Order pricing volatility compresses margins for aged varieties with 12-24 month holding periods.
- Mozzarella:High-moisture fresh varieties deliver stretch functionality for pizza applications; low-moisture part-skim extends shelf stability for food service distribution. Pizza chains negotiate directly with processor national accounts teams, displacing traditional wholesale layers. Microbial rennet alternatives have gained supplier qualification approval across major chain programs.
- Parmesan:Hard grating cheese requiring 10-24 month aging under FDA Pasteurized Milk Ordinance pathogen controls.
- Gouda:Semi-hard Dutch-style variety with smoked and aged variants capturing specialty retail placement.
Most installed capacity flows through Cheddar. Expansion is steepest in Mozzarella.
End User:
Volume concentration separates institutional procurement from fragmented household purchasing patterns.
- Food Services:Quick-service restaurants and pizza chains consolidate purchases through group purchasing organizations, with regional chains shifting 40% of cheese procurement to GPO-administered contracts. Labor efficiency priorities drive shredded and diced format adoption.
- Manufacturers:Processed cheese and prepared food producers require consistent melt profiles and extended shelf stability for ingredient applications. USDA Agricultural Marketing Service grading tiers reduce supplier search costs for Grade AA cheddar blocks.
- Households:Retail consumers selecting natural cheese varieties for snacking and cooking applications.
- Retailers:Supermarket deli and specialty cheese counters curating artisan and imported selections.
Food Services commands the largest volume throughput. Manufacturers are gaining share fastest through ingredient supply contracts.
Distribution Channel:
Cold-chain reliability requirements stratify channel economics and geographic reach.
- Wholesale:Food service distributors operating temperature-controlled warehouses deliver to restaurant chains and institutional accounts. Wisconsin production concentration within a three-county radius creates logistics vulnerability for national coverage.
- Supermarkets:Retail grocery dominates household purchasing with deli counter and pre-packaged cheese sections. FDA updated Nutrition Facts label requirements for added sugar disclosure reshape flavored variety planogram positioning.
- Specialty Stores:Artisan cheese mongers and gourmet retailers curating aged and imported selections.
- Online:Direct-to-consumer platforms and grocery delivery services expanding refrigerated last-mile capabilities.
Wholesale channels move the highest tonnage. Online is climbing the fastest as refrigerated logistics mature.
Packaging Type:
Labor substitution economics and portion consistency requirements differentiate format adoption.
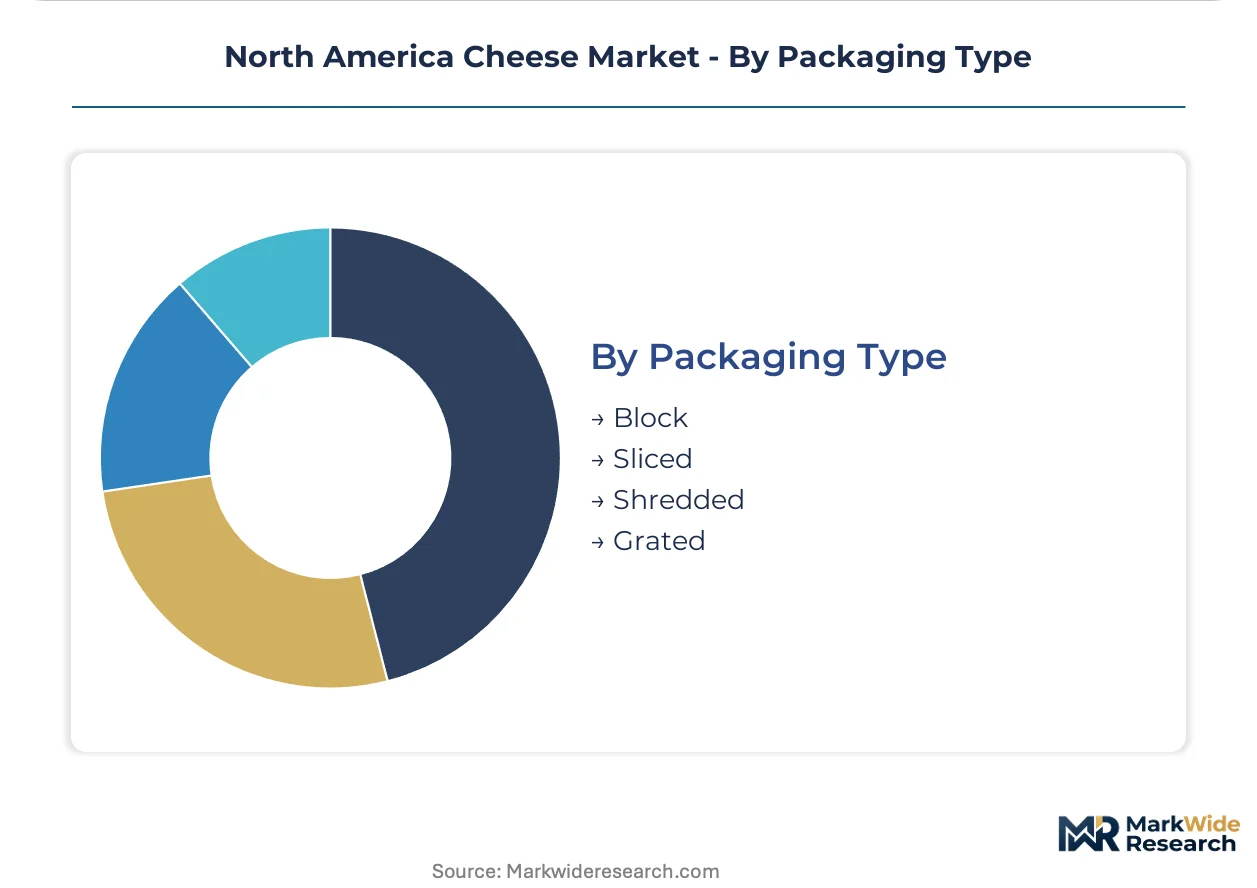
- Shredded:Pre-cut cheese reduces kitchen labor and delivers consistent portion weights for food service operators. Commercial kitchens across quick-service pizza and burger chains prioritize this format for speed of service.
- Block:Unprocessed cheese requiring in-house cutting; preferred by deli operations and artisan food service accounts for freshness control. Wisconsin cheddar blocks anchor commodity supply chains.
- Sliced:Deli-counter and pre-packaged sandwich applications.
- Grated:Fine-cut parmesan and hard cheese for finishing applications.
Block packaging retains the largest production base. Shredded is gaining share fastest as labor costs rise across food service operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States generates substantially higher per-capita cheese consumption than Canada, though Mexican demand is accelerating fastest among the three markets. Canada maintains tighter supply management through its quota system, while Mexico's import dependency creates different competitive dynamics. Regulatory divergence across FDA, Health Canada, and COFEPRIS shapes formulation and labeling requirements.
United States
Wisconsin's three-county cheddar production cluster anchors national commodity supply, while California's Central Valley drives mozzarella output for pizza chains. The FDA enforces pasteurized milk standards under the Pasteurized Milk Ordinance, with updated Nutrition Facts label requirements mandating added sugar disclosure. Quick-service restaurant procurement directors in Texas and Upper Midwest metro corridors now negotiate directly with processor national accounts teams, bypassing traditional wholesale layers.
Canada
Quebec and Ontario dairy cooperatives restructure milk procurement to secure consistent whey flows for specialty cheese operations. Health Canada and the CFIA administer cross-border safety protocols governing ingredient disclosure and pathogen controls. The Upper Midwest fluid milk collection networks extend into Canadian border regions, creating integrated supply basin economics for integrated North American operations.
Mexico
Monterrey and Guadalajara metro corridors show underpenetrated per-capita consumption relative to GDP-adjusted benchmarks, creating white space for aged gouda and manchego-style production. COFEPRIS administers dairy safety standards with increasing harmonization to FDA protocols for cross-border trade. Northern border states concentrate import-dependent processing capacity, while central Mexico develops domestic production infrastructure.
North America Cheese Market Key Industry Players
Wisconsin-based producers anchor one tier; Canadian cooperative specialists hold procurement-adjacent positions through backward integration into fluid milk networks. The market structures around three archetypes: scale-driven commodity processors with national distribution contracts, artisan-scale affineurs commanding premium positioning through cave-aging expertise, and cooperative-backed regional players leveraging captive milk supply. Dominant competitive moves include direct-to-foodservice distribution bypassing wholesale layers and enzymatic coagulation technology licensing for kosher and halal certification expansion.
Among scale-driven processors, Lactalis American Group, Saputo Inc., and BelGioioso Cheese Inc. occupy representative positions within their respective strategic tiers. Lactalis exemplifies the Wisconsin-anchored commodity specialist leveraging production footprint dominance. Saputo represents the cooperative-integrated model with upstream control over fluid milk collection networks. BelGioioso occupies the artisan-scale differentiation vector through specialized parmesan and fresh mozzarella production.
| Leading Market Players |
|---|
| Sargento Foods Inc. |
| Lactalis American Group |
| The Kraft Heinz Company |
| Bel Brands USA Inc. |
| Schreiber Foods |
| Saputo Inc. |
| Dairy Farmers of America Inc. |
| BelGioioso Cheese Inc. |
| Agropur Cooperative |
| Others |
Cost & Logistics Intelligence
Grade AA cheddar blocks and commodity shredded formats diverge sharply in margin capture, with the former commanding premium positioning through USDA Agricultural Marketing Service quality tiers while the latter competes on volume scale through direct-to-foodservice contracts. This bifurcation manifests in procurement patterns: premium aged varieties tie capital to 12-24 month inventory cycles vulnerable to Federal Milk Marketing Order price swings, whereas commodity formats prioritize logistics velocity over margin depth.
Pricing Analysis
Distributor margin layers compress as pizza chains and quick-service operators negotiate directly with processor national accounts teams, bypassing traditional wholesale markups. Three-tier pricing structure across premium artisan, standard commodity, and economy private-label levels separates affineur-aged parmesan from block cheddar and shredded mozzarella. Pricing pressure stems from fluid milk input volatility, with aged cheese processors least able to pass through cost spikes. Food service buyers show highest price sensitivity due to GPO-administered contract concentration, while specialty retailers absorb premiums for cave-aged varieties.
Supply Chain Analysis
Master cheesemaker scarcity in Wisconsin's three-county cheddar cluster and California's Central Valley mozzarella corridor constrains expansion of artisan-scale operations. Supply concentrates in the United States, with Canadian dairy cooperatives and northern Mexican import-dependent processors completing the North American footprint. Raw material flows draw from Upper Midwest fluid milk collection networks, microbial rennet alternatives, and precision fermentation-derived enzymes. Single-source vulnerability runs through Wisconsin's weather-exposed production cluster. Distribution runs through temperature-controlled wholesale warehouses serving restaurant chains, with direct-to-foodservice formats bypassing retail layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cheese processors arbitrage cost differentials between Canada's supply-managed quota system and the United States' Federal Milk Marketing Order pricing, exploiting regulatory divergence to optimize milk procurement basins.
For Market Incumbents: Anchor competitiveness through backward integration into fluid milk collection networks across the Upper Midwest, securing captive whey and curd flows for specialty operations. Defend against precision fermentation substitutes by accelerating microbial rennet qualification across kosher and halal certification tiers. Prioritize direct-to-foodservice distribution contracts in Texas and Upper Midwest metro corridors where GPO concentration is displacing wholesale relationships. For New Entrants and Emerging Players: Precision fermentation-derived casein alternatives offer technology-first entry into flexitarian consumer segments in coastal urban markets. White space exists in Monterrey and Guadalajara metro corridors for aged gouda and manchego-style production, where per-capita consumption trails GDP-adjusted benchmarks. Target direct-to-foodservice shredded and diced formats, leveraging labor efficiency priorities in quick-service pizza procurement. For Investors and Strategic Acquirers: Consolidation pressure builds where artisan-scale affineurs with cave-aging expertise command unsustainable wage premiums relative to output scale. Long-term viability favors processors with integrated milk supply and enzymatic coagulation technology licensing. Watch for FDA plant-based labeling dispute resolution as inflection indicator for competitive positioning between dairy and fermented alternatives.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fluid Milk Networks | Captive whey and curd flows secure specialty cheese margin capture against commodity volatility. |
| Microbial Rennet Supplier Qualification | Kosher and halal certification expansion opens institutional food service procurement channels. |
| Direct-to-Foodservice Distribution Buildout | Bypassing wholesale layers captures margin and freshness advantages in GPO-administered contracts. |
| Precision Fermentation Partnership | Enzyme alternatives reduce production variability while positioning for clean-label consumer segments. |
| Mexican Market Production Footprint | Monterrey and Guadalajara corridors offer underpenetrated white space for aged variety production. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with dairy cooperative procurement directors, quick-service restaurant supply chain managers, FDA regulatory affairs specialists, and artisan cheesemaker affineurs with secondary validation. USDA Agricultural Marketing Service grading databases, FDA Pasteurized Milk Ordinance enforcement records, Health Canada cross-border trade filings, and Canadian Dairy Commission quota reports anchored supply-side modeling. Bottom-up processor capacity assessments and top-down consumption elasticity models were triangulated against trade flow data.
Segment-weighting approaches applied product type, end user, distribution channel, and packaging format dimensions across the projection horizon. Cheddar, mozzarella, parmesan, and gouda varieties were modeled separately against food service, manufacturer, household, and retail buyer archetypes. CAGRs derived from elasticity-adjusted volume projections incorporating Federal Milk Marketing Order price volatility, enzymatic coagulation technology adoption curves, and GPO procurement concentration trends.
The model holds under stable FDA-Health Canada regulatory harmonization and intact Federal Milk Marketing Order structures; deviation in plant-based labeling litigation outcomes or Wisconsin production disruption would shift forecast trajectories. Forecasts reflect documented assumptions about milk input pricing and food service labor cost trends. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Dairy Protein Market
Dairy Products
Global Butter Market
Dairy Products
South America Dairy Protein Market
Dairy Products
Africa Yogurt Market
Dairy Products
Middle East and Africa Whey Protein Market
Dairy Products
A2 Fresh Milk Market
Dairy Products
Condensed Whey Market
Dairy Products
Goat Milk Market
Dairy Products
Dairy Concentrates Market
Dairy Products
Latin America Cheese Market
Dairy Products
United Kingdom Milk Protein Market
Dairy Products
Organic Dairy Market
Dairy Products
Russia Whey Protein Market
Dairy Products
White Cheese Market
Dairy Products
Mexico Lactose-Free Dairy Market
Dairy Products
Ricotta Market