
 Biscuit Mixes Market | 2026-2036
Biscuit Mixes Market Size, Share, and Industry Trends Forecast 2026-2036
Biscuit Mixes Market Outlook
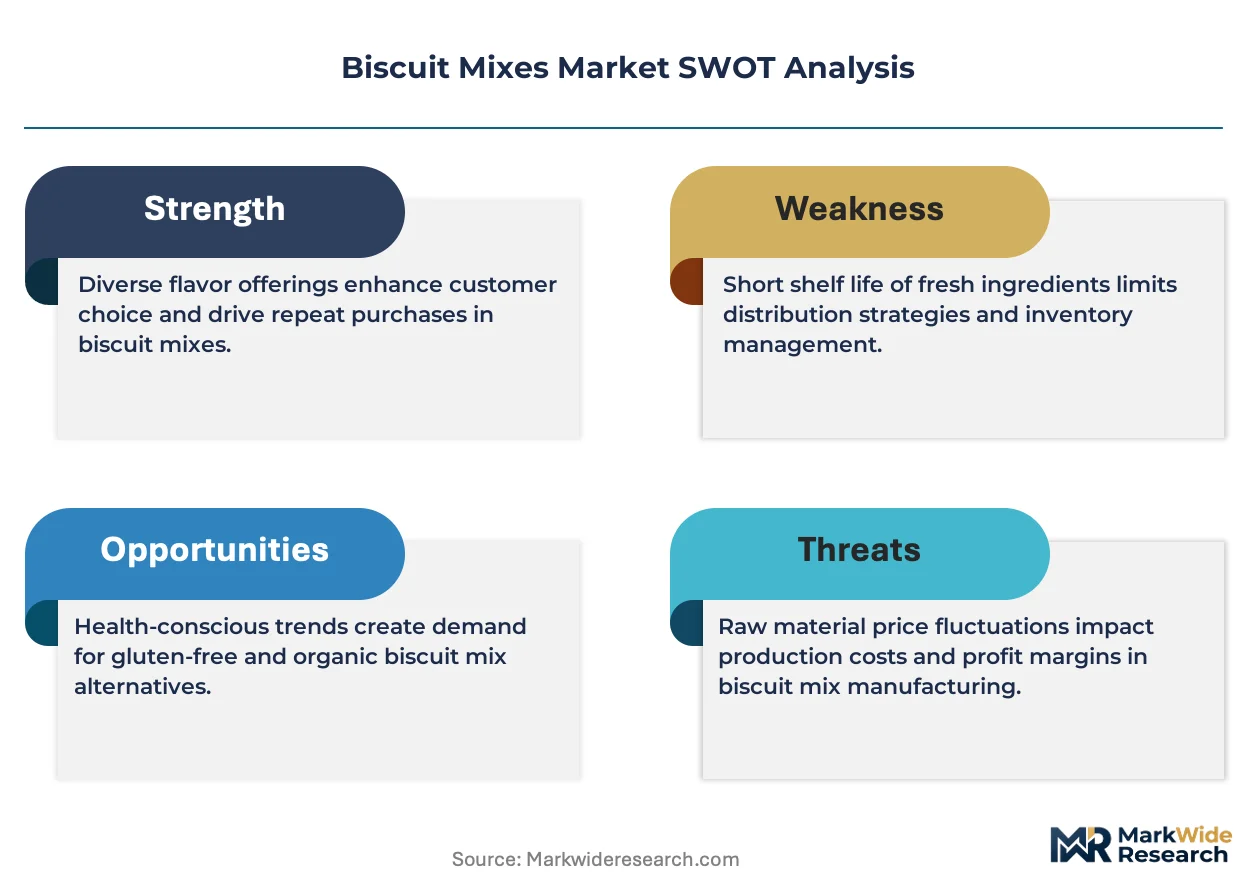
Premium clean-label tiering is rotating the biscuit mixes category toward higher-margin positioning. General Mills leverages its manufacturing scale to dominate mainstream retail distribution across North America. Bob's Red Mill differentiates through heritage grain sourcing and gluten-free certification depth. C. H. Guenther & Son anchors foodservice supply chains with institutional-format production capabilities.
Biscuit mixes comprise pre-measured dry ingredient blends—typically wheat flour, leavening agents, shortening, and salt—requiring only liquid addition before baking, with specifications ranging from 8-16% protein content depending on intended rise and crumb structure. These formulations serve commercial bakeries, restaurants, and home consumers seeking consistent, labor-reduced preparation. The sweet biscuit mix segment leads volume due to breakfast and dessert application breadth, while gluten-free biscuit mix captures the fastest expansion as celiac awareness and non-celiac sensitivity broaden addressable demand. Organic biscuit mix occupies a concentrated premium tier where margin pools exceed conventional equivalents through certified supply chain premiums and smaller-batch positioning.
The FDA governs allergen labeling and fortification standards for U.S.-distributed mixes, while EFSA evaluates novel ingredient safety claims across European markets, and the USDA Organic seal shapes premium shelf placement through certified ingredient traceability requirements. These frameworks elevate compliance costs for new entrants but reinforce incumbent advantages through established certification infrastructure. Stakeholders must monitor evolving clean-label definitions and emerging market registration pathways to sustain competitive positioning as regulatory granularity intensifies.
Market Dynamics
Clean-label reformulation pressure from FDA and EFSA is compressing formulation flexibility while simultaneously opening premium shelf space for certified alternatives. This regulatory bifurcation is forcing manufacturers to maintain parallel production lines or abandon conventional positioning entirely.
Growth Catalysts
- Home Baking Resurgence:Post-pandemic household baking retention is sustaining demand for convenience-oriented scratch alternatives. Residential kitchens now represent the dominant consumption node.
- EFSA Gluten-Free Certification:Standardized safety thresholds across European markets are reducing cross-border formulation friction. This harmonization accelerates pan-European product launches.
- Heritage Grain Sourcing:Red fife, einkorn, and spelt varietals are commanding ingredient premiums through provenance storytelling. Specialty millers are securing long-term contracts with regional grain cooperatives.
Market Restraints
- Wheat Price Volatility:Input cost swings from Black Sea supply disruptions are compressing margin stability. Formulators lack hedging instruments at their scale.
- Leavening Agent Concentration:Sodium aluminum phosphate and monocalcium phosphate supply concentrates among three domestic chemical processors. Any production interruption cascades immediately.
- Clean-Label Technical Ceiling:Removing phosphate-based leavening degrades rise consistency and shelf stability. Alternative acid-base systems remain inferior for high-altitude distribution.
Strategic Opportunities
- Japanese Convenience Store Channel:Seven-Eleven Japan and Lawson are expanding fresh-baked private-label programs. Single-serve pouch formats align with their operational model.
- USDA Organic Certification Tailwind:The 2023 organic livestock feed rule expansion is tightening ingredient traceability requirements. Early certifiers capture shelf placement advantages.
- Precision Fermentation Convergence:Lab-cultured butterfat and whey proteins are approaching cost parity with conventional dairy. Hybrid formulations can claim animal-free status without sacrificing mouthfeel.
Industry Challenges
- Clean-Label Reformulation Talent Scarcity:Food scientists capable of replacing synthetic emulsifiers with natural alternatives command premium compensation. Mid-tier manufacturers struggle to recruit.
- Dual Certification Timeline Compression:Simultaneous FDA allergen review and USDA Organic audit cycles extend time-to-market by 8-14 months. Working capital requirements escalate proportionally.
- Legacy Equipment Retrofit Costs:Dedicated gluten-free production demands segregated milling and packaging lines. Capital expenditure thresholds exclude smaller regional players.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biscuit Mixes Market |
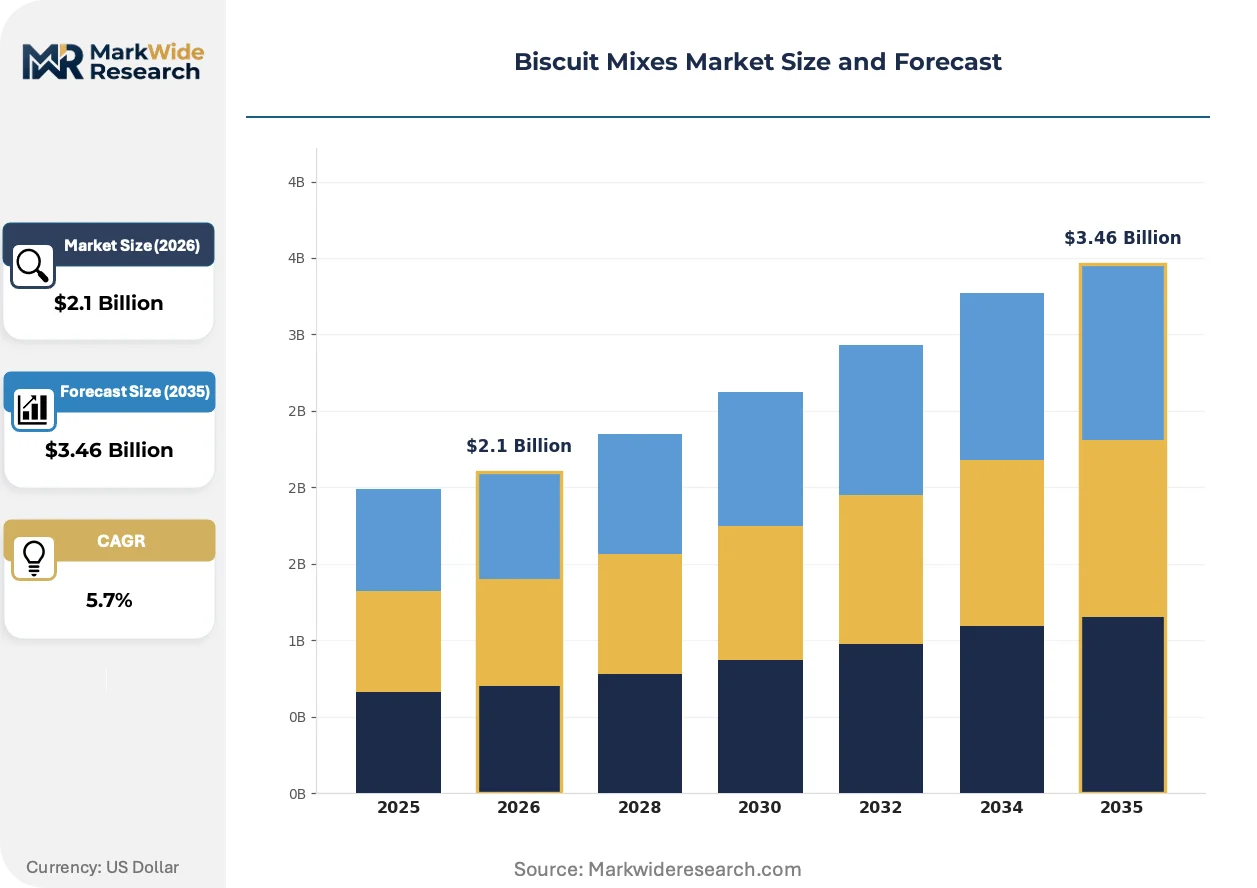
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.46 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sweet Biscuit Mix, Savory Biscuit Mix, Gluten-Free Biscuit Mix, Organic Biscuit Mix Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Wholesale End User: Households, Bakeries, Food Industry, Restaurants Packaging Type: Bag, Box, Pouch, Canister |
| Companies Covered | General Mills, C. H. Guenther & Son, Belle Biscuit Company, Atkinson Milling, Miss Roben's Baking Mixes, Southern Belle Biscuit Company, Chelsea Milling, Bob's Red Mill, Krusteaz, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biscuit Mixes Market Strategic Shifts
Formulation science is migrating from bench-scale substitution toward systematic ingredient architecture redesign. This shift is compressing traditional R&D cycles while elevating the technical bar for competitive entry.
Spray-dried fat encapsulation technology is decomposing the historical trade-off between shelf stability and clean-label positioning. Commercial bakeries in the United States are adopting these systems at accelerated rates to maintain extended distribution reach without synthetic preservatives. The structural consequence is margin compression for conventional shortening-based formulations that cannot match performance claims.
EFSA's 2023 updated guidance on novel food ingredients is tightening safety dossier requirements for emerging protein sources. European manufacturers must now submit extended toxicology data for fermentation-derived ingredients. The gluten-free biscuit mix segment faces the steepest compliance burden as it most aggressively pursues alternative protein integration.
Direct-to-consumer subscription models are displacing conventional grocery replenishment cycles for specialty mix categories. Millennial households in Germany and Japan are consolidating purchases through curated delivery services that emphasize limited-batch releases. This channel rotation is most visible in organic and heritage-grain positioned products where provenance transparency commands subscription premiums.
Biscuit Mixes Market Segmentation
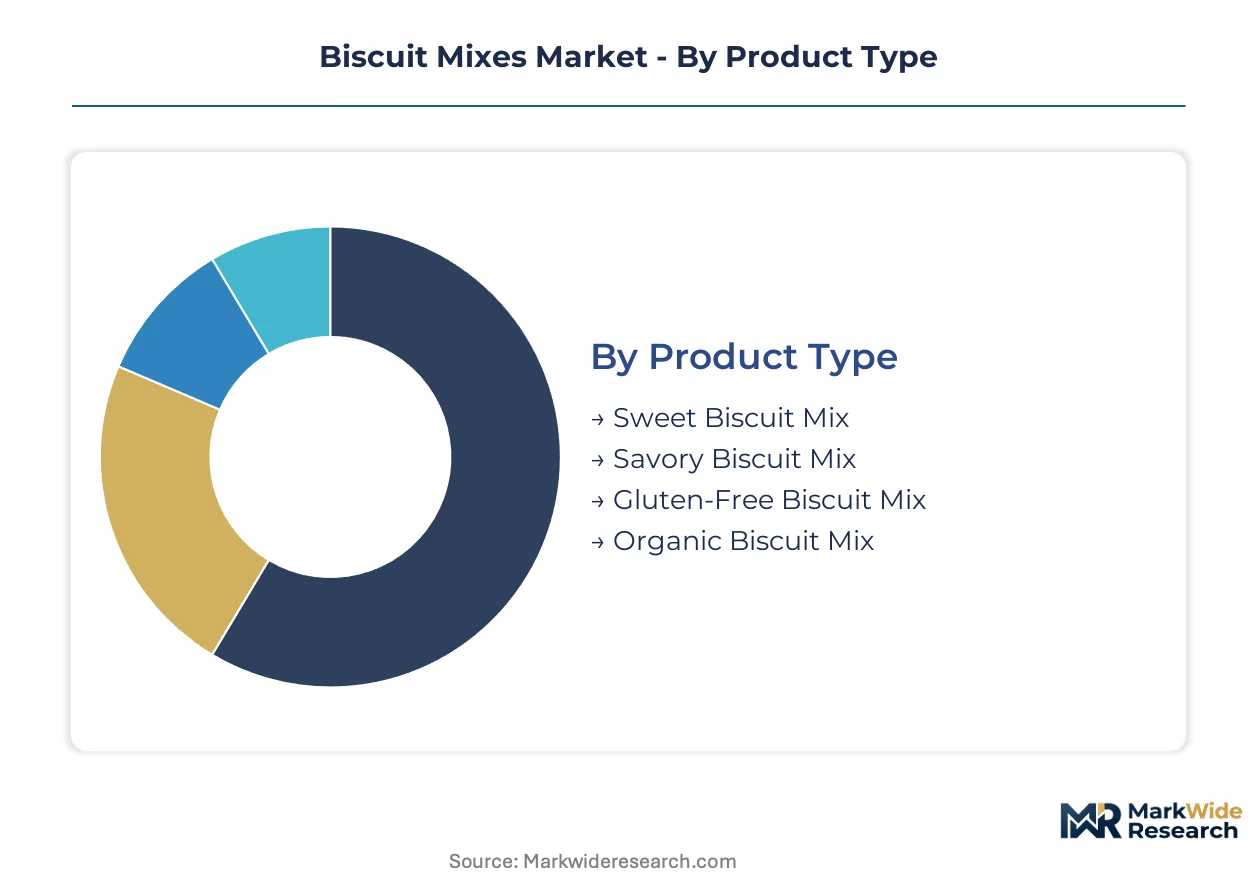
Biscuit mix segmentation reveals how formulation architecture and channel access determine margin capture. Manufacturers must align production capabilities with the specific technical and regulatory requirements of each segment tier.
Product Type:
Margin pools concentrate in certified specialty tiers where supply chain premiums justify price architecture elevation above commodity benchmarks.
- Sweet Biscuit Mix:Formulations incorporate 12-16% sugar content with vanilla or cinnamon flavor profiles, optimized for breakfast and dessert applications. Demand concentrates in United States households where convenience-oriented scratch baking sustains replenishment cycles. The segment anchors volume throughput for major millers.
- Gluten-Free Biscuit Mix:Rice flour and tapioca starch bases replace wheat, with xanthan gum providing structural integrity. Celiac awareness in Germany and Japan is broadening addressable demand beyond diagnosed populations. FDA and EFSA certification requirements elevate compliance costs but open premium shelf placement.
- Savory Biscuit Mix:Reduced sugar formulations with herb inclusions target dinner roll and breadstick applications.
- Organic Biscuit Mix:USDA-certified ingredient traceability commands supply chain premiums through smaller-batch positioning.
Sweet biscuit mix holds installed capacity. Gluten-free biscuit mix is rotating up the share rankings.
Distribution Channel:
Channel selection determines working capital intensity and price realization, with direct-to-consumer formats compressing margin leakage.
- Supermarkets:Mass merchandisers dominate volume throughput with slotting fee structures that favor scaled suppliers. United States retail consolidation around Kroger and Albertsons squeezes regional brand access.
- Online Retail:Subscription models in Germany capture recurring revenue through curated heritage-grain releases. Direct fulfillment eliminates distributor margin capture.
- Specialty Stores:Natural food retailers emphasize certified organic and gluten-free assortments.
- Wholesale:Institutional foodservice supply demands bulk format consistency.
Supermarkets hold installed capacity. Online retail is rotating up the share rankings.
End User:
Application-specific formulation requirements separate household convenience from commercial performance specifications.
- Households:Single-batch pouch formats with minimal ingredient addition dominate residential kitchens. Post-pandemic baking retention in Japan sustains demand for portion-controlled packaging.
- Bakeries:High-volume commercial operations require 50-pound bulk bags with extended mixing tolerance and consistent hydration response.
- Food Industry:Co-manufacturers demand custom formulation flexibility for private-label programs.
- Restaurants:Quick-service operators prioritize speed-scratch solutions with frozen dough compatibility.
Households hold installed capacity. Bakeries is rotating up the share rankings.
Packaging Type:
Format engineering balances shelf stability, portion control, and sustainability positioning across consumption occasions.
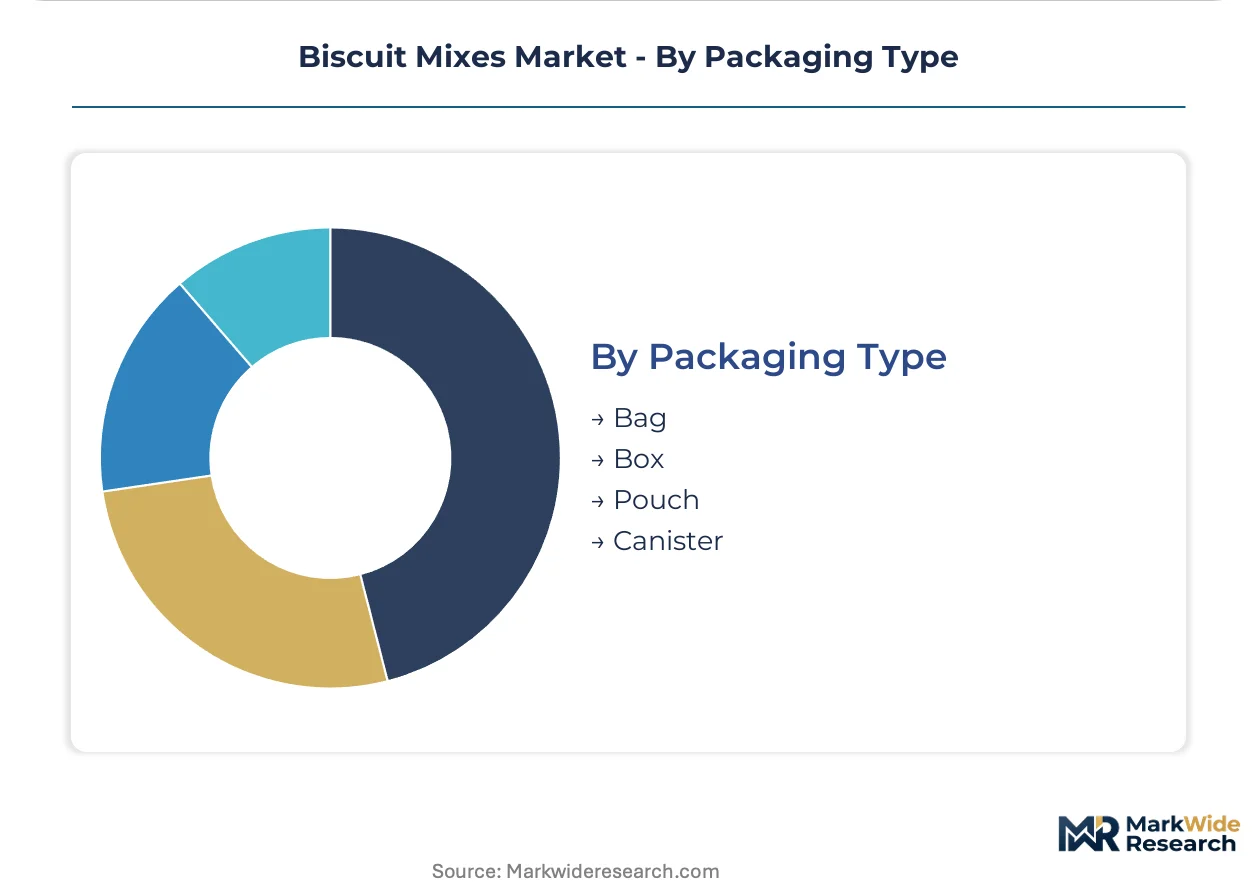
- Pouch:Multi-layer barrier films with nitrogen flush extend shelf life without synthetic preservatives. Single-serve formats align with Japanese convenience store operational models.
- Box:Secondary packaging provides retail billboard space for certification callouts and recipe suggestions.
- Bag:Flexible packaging reduces shipping cube for wholesale distribution.
- Canister:Rigid containers support repeated dispensing in high-frequency household use.
Pouch holds installed capacity. Box is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in biscuit mixes tilt toward deficit positions in premium-importing economies while surplus-generating regions leverage grain milling infrastructure. Currency fluctuations and certification harmonization efforts are reshaping cross-border shipment patterns.
United States
Convenience-oriented scratch baking sustains household replenishment cycles across suburban and rural markets. FDA allergen labeling mandates and fortification standards elevate compliance costs for imported formulations. Kansas and Minnesota anchor domestic milling capacity where heritage grain cooperatives supply regional blenders.
Germany
EFSA gluten-free certification harmonization accelerates pan-European product launches from German manufacturing bases. Clean-label reformulation pressures compress formulation flexibility for conventional positioning. Bavaria concentrates specialty milling operations where smaller-batch organic certifiers secure long-term supply contracts.
Japan
Seven-Eleven Japan and Lawson convenience store channels expand fresh-baked private-label programs requiring single-serve pouch formats. METI standards on food additive thresholds shape import acceptance criteria. Tokyo-Osaka corridor dominates distribution infrastructure where direct-to-consumer subscription models capture millennial household consolidation.
United Kingdom
Post-Brexit regulatory divergence from EFSA frameworks creates parallel certification requirements for EU-destined versus domestic formulations. Heritage grain provenance storytelling commands ingredient premiums through regional grain cooperative relationships. Midlands industrial baking clusters supply foodservice operators with institutional-format production.
Canada
Health Canada fortification and allergen disclosure requirements align closely with FDA frameworks, easing U.S. exporter market entry. Prairie province grain cooperatives supply wheat flour inputs to cross-border blenders. Ontario and Quebec concentrate retail distribution negotiations where slotting fee structures favor scaled North American suppliers.
Biscuit Mixes Market Competitive Environment
Listed leaders compete with private specialists across certification depth and channel access dimensions. The vendor base stratifies between scaled mass-market suppliers and heritage-positioned regional millers. Three archetypes dominate: diversified consumer packaged goods conglomerates, specialty grain-focused independents, and foodservice-dedicated institutional suppliers. Capacity expansion and clean-label portfolio diversification represent the dominant competitive moves as manufacturers respond to regulatory bifurcation pressures.
Within the heritage-grain specialist tier, Bob's Red Mill and Belle Biscuit Company exemplify certification-forward positioning through organic and gluten-free supply chain depth. General Mills occupies a scale-driven position representing diversified conglomerate manufacturing advantages across mainstream retail distribution. C. H. Guenther & Son anchors the foodservice-dedicated archetype with institutional-format production capabilities. These three company types collectively illustrate how competitive positioning fragments across certification tier, production scale, and channel specialization vectors.
| Leading Market Players |
|---|
| General Mills |
| C. H. Guenther & Son |
| Belle Biscuit Company |
| Atkinson Milling |
| Miss Roben's Baking Mixes |
| Southern Belle Biscuit Company |
| Chelsea Milling |
| Bob's Red Mill |
| Krusteaz |
| Others |
Value Chain & Pricing Dynamics
Mill-scale utilization rates above 85% in Kansas and Minnesota milling clusters compress unit economics for heritage grain inputs while simultaneously elevating price floors for smaller-batch organic certifiers who lack comparable throughput leverage. This scale asymmetry bifurcates the biscuit mixes market into volume-driven commodity tiers and premium-positioned specialty tiers where supply chain traceability commands measurable price premiums.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across foodservice channels, while household consumers encounter per-unit transactional pricing with pronounced quality-grade differentiation. Certification tier—USDA Organic versus conventional—drives the widest price spreads, followed by volume scale discounts for institutional procurement. Pricing pressure stems from wheat price volatility originating in Black Sea supply corridors, compressing margins most acutely for mid-tier manufacturers lacking hedging instruments. Quick-service restaurant operators exhibit highest price sensitivity due to cost-plus contract structures, whereas direct-to-consumer subscription households demonstrate lowest sensitivity where provenance storytelling justifies premium acceptance.
Supply Chain Analysis
Leavening agent production concentrates among three domestic chemical processors in the United States, creating single-source vulnerability for sodium aluminum phosphate and monocalcium phosphate inputs. Wheat flour draws from Kansas and Minnesota milling clusters, while heritage grain varietals source from regional cooperatives in the Prairie provinces. Supply chain risk centers on phosphate-based leavening concentration, where any production interruption cascades immediately across formulation pipelines. Distribution runs through mass merchandiser consolidation around Kroger and Albertsons, with direct-to-consumer fulfillment emerging as an alternative channel for specialty certifiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The biscuit mixes market operates as a regulatory entrenchment story where FDA allergen labeling infrastructure and USDA Organic certification depth create switching costs that disadvantage unqualified entrants. Established certification pipelines function as defensive moats.
For Market Incumbents: Secure dual certification timelines by front-loading FDA allergen review and USDA Organic audit cycles to compress time-to-market gaps. Defend margin position through backward integration into heritage grain milling capacity in Kansas and Minnesota, neutralizing input cost volatility from Black Sea supply disruptions. Channel control through direct-to-consumer subscription infrastructure insulates against mass merchandiser slotting fee compression. For New Entrants and Emerging Players: EFSA gluten-free certification fast-tracks pan-European market access from German manufacturing bases, bypassing fragmented national approval pathways. White-space concentrates in Japanese convenience store single-serve pouch formats where Seven-Eleven Japan and Lawson expansion creates immediate demand pull. Target German millennial households through curated heritage-grain subscription releases with provenance transparency as the core go-to-market angle. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors spray-dried fat encapsulation specialists who decompose the shelf-stability-versus-clean-label trade-off. Long-term viability over the next decade hinges on precision fermentation convergence for lab-cultured butterfat integration. Acquisition targets should exhibit established certification infrastructure with USDA Organic pipeline depth. The signal to watch is EFSA novel food ingredient guidance tightening, which would accelerate compliance cost escalation and consolidation pressure.| Strategic Initiative | Industry Significance |
|---|---|
| Heritage Grain Sourcing Contracts | Red fife and einkorn varietals from regional cooperatives secure ingredient premiums through provenance storytelling. |
| Dual Certification Investment | Simultaneous FDA and USDA Organic pipelines compress competitive entry timelines for premium shelf placement. |
| Direct-to-Consumer Launch | Subscription models in Germany and Japan capture recurring revenue without distributor margin leakage. |
| Precision Fermentation Partnership | Lab-cultured butterfat integration enables animal-free claims without sacrificing mouthfeel performance. |
| Japanese Convenience Channel Expansion | Single-serve pouch formats align with Seven-Eleven Japan and Lawson operational requirements. |
Study Parameters
Initial hypotheses were tested against primary input from brand managers at diversified consumer packaged goods conglomerates, category buyers at Kroger and Albertsons, supply planners at regional grain cooperatives, and technical R&D directors at specialty millers, then refined against secondary validation from FDA allergen labeling databases, USDA Organic certification registries, EFSA novel food ingredient guidance documents, and Nielsen retail audit data. Bottom-up demand modeling across household, bakery, and foodservice end-use segments was triangulated with top-down capacity assessments at Kansas and Minnesota milling clusters.
Variance decomposition across the projection horizon isolates volume drivers by product type—sweet, gluten-free, savory, and organic—while cross-referencing distribution channel dynamics and end-user application requirements. CAGRs were derived from segment-level growth trajectory synthesis rather than single-point extrapolation. Forecast inputs incorporated wheat price volatility indices from Black Sea supply corridors and EFSA certification harmonization timelines for pan-European product launch feasibility.
Decision-makers should treat outputs as directional under assumptions of sustained home baking retention and stable regulatory certification frameworks; material deviation in wheat input costs or EFSA guidance tightening would warrant model refresh. Practitioners should keep alternative scenarios live as precision fermentation cost parity timelines and Japanese convenience store channel expansion rates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
Asia-Pacific Frozen Bakery Market
Bakery Products
Premix Bread Flour Market
Bakery Products
Pizza Crust Market
Bakery Products
Bread Market
Bakery Products
Bread Improver Market
Bakery Products
Baking Mix, Base and Concentrate Market
Bakery Products
Bake Stable Pastry Fillings Market
Bakery Products
Bread Premix Market
Bakery Products
Cakes and Pastries Market
Bakery Products
South America Ice Cream Market
Bakery Products
Global Wafer Biscuits Market
Bakery Products
Organic Frozen Bakery Market
Bakery Products
Cakes, Pastries, and Sweet Pies Market
Bakery Products
Multigrain Bread Mix Market
Bakery Products
Asia-Pacific Bakery Products Market
Bakery Products
Doughnuts Market