
 Tortilla Mix Market | 2026-2036
Tortilla Mix Market Size, Share, and Industry Trends Forecast 2026-2036
Tortilla Mix Market Analytics
Ingredient value capture is tilting from commodity grain trading toward proprietary blend formulation and premix customization. Gruma Corporation dominates fresh masa and nixtamalized corn flour technology through captive supply of heritage corn varieties. Archer Daniels Midland Company leverages its North American grain origination network to anchor industrial-scale wheat flour mix production for foodservice distributors. Bob's Red Mill Natural Foods differentiates through stone-ground processing credentials and organic certification that commands shelf-space premiums in specialty retail.
Tortilla mix comprises dry, pre-measured combinations of nixtamalized corn flour, wheat flour, or alternative grains with leavening agents, salt, and functional additives, requiring hydration and sheeting to produce flatbread with specified thickness, moisture content, and fold integrity for wrapping or frying applications. Corn flour formulations sustain the largest volume position due to entrenched preference in Mexican and Tex-Mex cuisine, while gluten-free mixes represent the fastest-expanding category as celiac-safe protocols and rice-almond-cassava blends penetrate restaurant and retail channels. Bulk bags occupy the dominant packaging format in commercial foodservice procurement, though resealable pouches are gaining traction among home cooks seeking portion control and extended freshness.
The FDA enforces Current Good Manufacturing Practices and allergen labeling for flour-based mixes, while the USDA Organic seal and Non-GMO Project verification shape premium positioning and retail access. Mexico's Secretariat of Economy maintains NOM standards for nixtamalized corn products that govern import quality and traditional process claims. Stakeholders must monitor evolving clean-label demands and regional grain price volatility to calibrate formulation costs against positioning strategies.
Market Dynamics
Restaurant chains across the United States are consolidating fresh tortilla programs under central commissary models, compressing procurement timelines and forcing mix suppliers to certify nixtamalization protocols at scale.
Growth Catalysts
- FSMA Preventive Controls:The FDA's updated flour milling requirements are accelerating supplier consolidation toward certified facilities with documented hazard analysis plans.
- Heritage corn varieties:Premium positioning through landrace sourcing from Mexico's central plateau is commanding price premiums in specialty retail channels.
- Quick-service restaurant expansion:Chipotle and similar chains are rolling out made-fresh-daily tortilla programs that require bulk nixtamalized corn flour procurement.
Market Restraints
- Input cost volatility:White corn futures on the Chicago Board of Trade expose margins to weather-driven price swings in Iowa and Illinois growing regions.
- Supply concentration risk:Nixtamalization expertise concentrates in Mexico's Estado de México and Tlaxcala regions, creating single-source dependencies for authentic process claims.
- Substitution threat:Pre-formed frozen tortillas from industrial bakeries are displacing mix-based fresh production in cost-sensitive institutional foodservice accounts.
Strategic Opportunities
- Gluten-free formulation:Rice-almond-cassava blends certified through the Gluten-Free Certification Organization are penetrating restaurant chains seeking celiac-safe menu items.
- Direct-to-restaurant distribution:Bypassing broadline distributors through proprietary delivery fleets is capturing margin in Texas and California metro markets.
- Organic certification:The USDA Organic seal is unlocking shelf placement in Whole Foods Market and Sprouts Farmers Market regional expansions.
Industry Challenges
- Nixtamalization skill scarcity:Traditional lime-cooking expertise is aging out of the workforce in Mexican processing facilities, threatening quality consistency.
- Clean-label reformulation timelines:Removing potassium bromate and DATEM emulsifiers requires 18-24 month stability testing cycles that delay product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tortilla Mix Market |
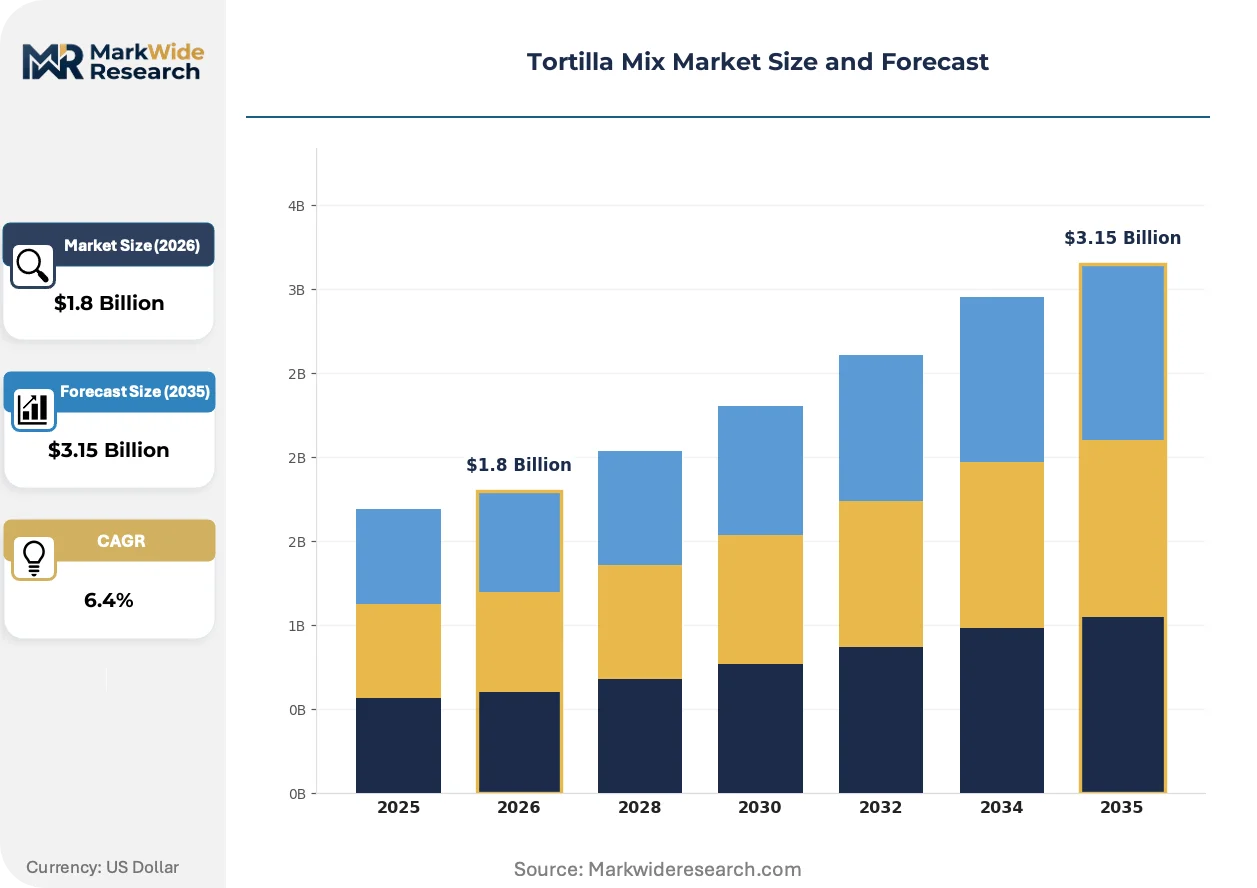
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Corn Flour, Wheat Flour, Organic Mix, Gluten-Free Mix End User: Restaurants, Food Trucks, Retail Chains, Home Cooks Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale Packaging Type: Bulk Bags, Single-Serve Packs, Family Packs, Resealable Pouches |
| Companies Covered | Gruma Corporation, Archer Daniels Midland Company, General Mills Inc., Cargill Inc., Bob’s Red Mill Natural Foods, Ingredion Incorporated, Tate & Lyle PLC, Bunge Limited, MGP Ingredients Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tortilla Mix Market Evolving Landscape
Automation is penetrating tortilla production at the commissary level, collapsing the labor intensity that previously justified centralized manufacturing. Equipment suppliers are retrofitting sheeting lines with vision systems that adjust thickness in real time.
Extrusion technology is collapsing the traditional nixtamalization timeline from 12 hours to 45 minutes through high-pressure steam injection systems. Restaurant commissaries in Texas and Arizona are piloting these units to support same-day production models. The compression of processing time is collapsing the capital requirements for in-house tortilla programs.
The FDA's Food Safety Modernization Act preventive controls rule is mandating environmental monitoring programs for dry mix facilities. Flour mills are installing automated sampling systems to document pathogen controls. Small and mid-sized suppliers in the Midwest are absorbing six-figure compliance costs or exiting the foodservice channel.
Home cooks are migrating toward resealable pouch formats that extend freshness windows beyond bulk bag alternatives. Specialty retailers are allocating incremental shelf space to single-pound packages with recipe instructions. This channel rotation is most visible in California and Colorado markets where meal-kit crossover demand concentrates.
Tortilla Mix Market Segmentation
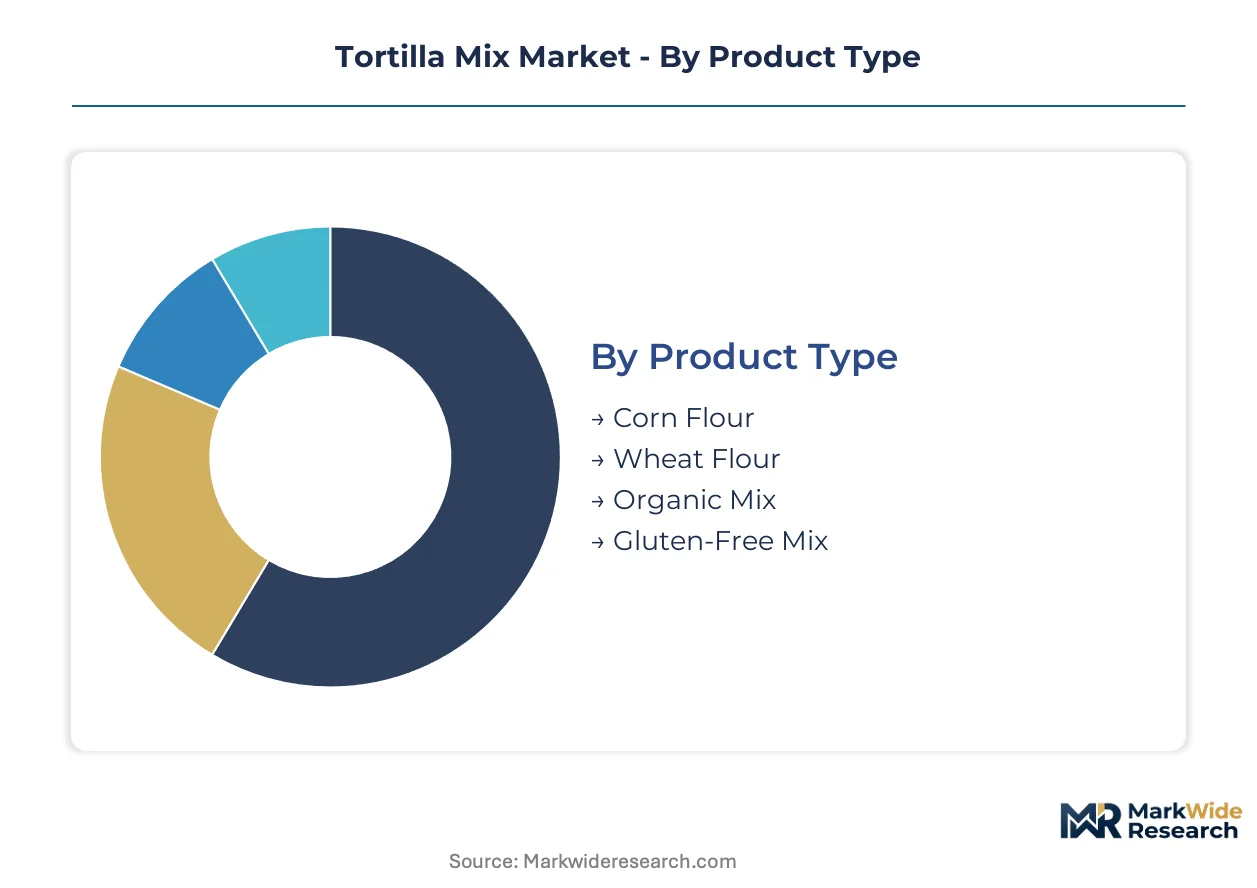
Segmentation in the tortilla mix market reflects divergent supply chain requirements between industrial-scale foodservice procurement and specialty retail positioning. Each dimension carries distinct margin structures and technical specifications that shape formulation priorities.
Product Type:
After-sales service intensity varies sharply across product types, with nixtamalized corn flour demanding technical support for hydration protocols while commodity wheat flour requires minimal intervention.
- Corn Flour:Nixtamalized formulations require precise lime-cooking expertise and hydration calibration to achieve specified pH and moisture targets. Restaurant chains in Texas and Arizona concentrate procurement here, driven by made-fresh-daily programs at Chipotle and similar concepts that mandate authentic process claims.
- Gluten-Free Mix:Rice-almond-cassava blends certified through the Gluten-Free Certification Organization command formulation precision and allergen-segregated production lines. Demand concentrates in California and Colorado retail channels where celiac-safe menu items penetrate both restaurants and home kitchens.
- Wheat Flour:Industrial-scale production for foodservice distributors leverages established milling infrastructure with minimal technical support requirements.
- Organic Mix:USDA Organic certification unlocks placement in Whole Foods Market and Sprouts Farmers Market expansions with documented supply chain traceability.
Corn flour holds the largest share; momentum sits with gluten-free mixes climbing the fastest as celiac protocols expand.
End User:
Cost tier stratification separates premium-positioned restaurant commissaries from price-sensitive institutional accounts, with each tier demanding distinct formulation and packaging economics.
- Restaurants:Central commissary models compress procurement timelines and mandate certified nixtamalization protocols at scale. Quick-service chains rolling out fresh tortilla programs drive bulk nixtamalized corn flour procurement with documented hazard analysis plans.
- Retail Chains:Shelf placement negotiations require organic certification and clean-label positioning that commands slotting fee premiums in specialty grocery expansions.
- Food Trucks:Mobile operations prioritize compact packaging and rapid hydration formulations with minimal equipment requirements.
- Home Cooks:Recipe-included packaging and portion control formats dominate this fragmented channel with high brand switching rates.
Restaurants command the largest volume position; retail chains are gaining share fastest through organic certification requirements.
Distribution Channel:
Volume concentration in wholesale channels contrasts with margin capture in specialty retail, creating divergent pricing architectures across the network.
- Wholesale:Broadline distributors anchor industrial-scale procurement for restaurant chains with palletized bulk delivery and extended payment terms.
- Supermarkets:Mainstream retail placement demands promotional slotting and family-pack formats with competitive unit economics.
- Specialty Stores:Stone-ground credentials and heritage corn sourcing command price premiums in curated assortments with educated staff.
- Online Retail:Direct-to-consumer shipping of resealable pouches extends freshness windows and captures meal-kit crossover demand in California and Colorado markets.
Wholesale holds the dominant volume position; online retail shows the steepest expansion trajectory through pouch format adoption.
Packaging Type:
Customer type stratification separates commercial foodservice procurement from home kitchen convenience requirements, with each segment driving distinct material and format specifications.
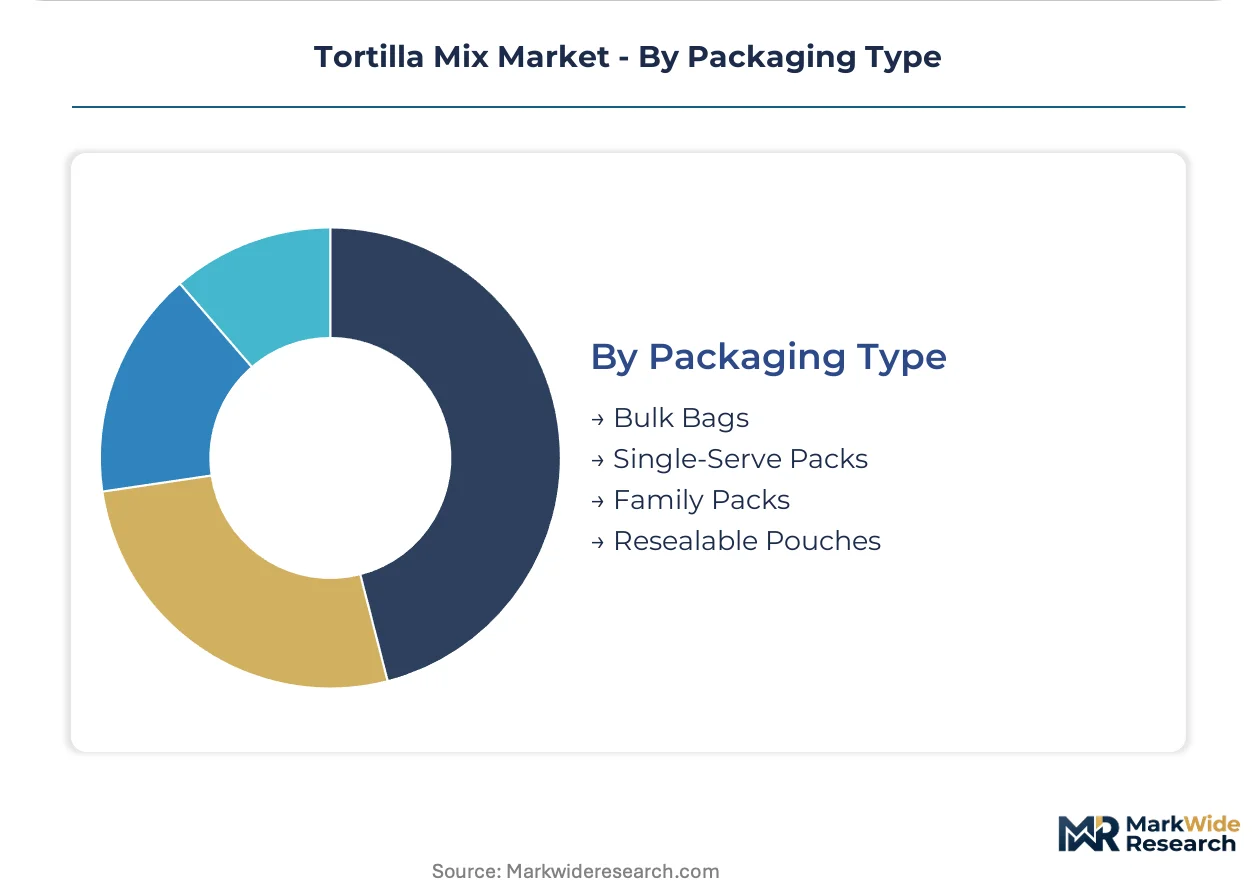
- Bulk Bags:Multi-hundred-pound formats dominate commercial foodservice procurement with minimal unit costs and established logistics infrastructure.
- Resealable Pouches:Zip-lock closures extend freshness windows beyond bulk alternatives and capture meal-kit crossover demand with recipe integration.
- Family Packs:Mid-size formats balance value positioning with manageable storage requirements for regular home consumption.
- Single-Serve Packs:Portion-controlled units target trial purchases and occasional users with premium per-unit pricing.
Bulk bags maintain the largest share; resealable pouches are expanding most quickly through freshness positioning and channel rotation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mexico consumes tortilla mix through traditional nixtamalization channels that emphasize heritage process claims, while the United States channels demand through quick-service restaurant commissaries seeking bulk efficiency. This consumption-mix differential shapes divergent supply chain configurations across the two largest markets.
Mexico
Central plateau states of Estado de México and Tlaxcala anchor nixtamalization expertise for premium corn flour exports. Mexico's Secretariat of Economy enforces NOM standards governing import quality and traditional process authentication. Mexico City Metro concentration supports artisanal milling clusters that supply heritage landrace varieties to specialty retail channels in California and Texas.
United States
Texas and Arizona restaurant commissaries pilot extrusion systems compressing nixtamalization from 12 hours to 45 minutes for same-day production. The FDA's Food Safety Modernization Act preventive controls rule mandates environmental monitoring programs for dry mix facilities. California retail channels drive resealable pouch adoption through meal-kit crossover demand concentrated in Los Angeles and San Francisco metro areas.
Canada
Ontario and Quebec foodservice distributors import bulk nixtamalized corn flour under Health Canada flour safety guidelines. The Canadian Food Inspection Agency enforces allergen labeling and preventive control requirements parallel to FDA frameworks. Toronto and Montreal restaurant clusters are expanding fresh tortilla programs through central commissary models.
Spain
Catalonia and Madrid tapas restaurant chains are adopting fresh tortilla production for menu differentiation. The European Food Safety Authority governs additive permissions and clean-label claims across wheat and alternative grain formulations. Barcelona industrial zones host pilot facilities testing rice-almond blends for gluten-free positioning in European retail.
United Kingdom
London and Southeast England specialty retailers allocate shelf space to stone-ground and organic-certified mixes. The UK Food Standards Agency enforces allergen controls and organic certification integrity through Soil Association accreditation. Manchester and Birmingham foodservice distributors are expanding Tex-Mex restaurant supply contracts.
Tortilla Mix Market Competitive Landscape
Capability concentration sits with heritage process specialists; scale advantage sits with grain origination networks. The market structures around three tiers: captive corn variety controllers, industrial milling conglomerates, and specialty organic certifiers. Consolidation pressures are accelerating as FSMA compliance costs force mid-scale suppliers toward acquisition or exit. Dominant competitive moves include backward integration into heritage seed sourcing and geographic expansion through direct-to-restaurant distribution fleets.
Within the heritage process tier, Gruma Corporation exemplifies captive supply chain control through nixtamalization technology concentration. Archer Daniels Midland Company anchors the industrial-scale vector through North American grain origination infrastructure. Bob's Red Mill Natural Foods occupies the specialty certification position through stone-ground processing credentials and organic verification that commands retail slotting premiums.
| Leading Market Players |
|---|
| Gruma Corporation |
| Archer Daniels Midland Company |
| General Mills Inc. |
| Cargill Inc. |
| Bob's Red Mill Natural Foods |
| Ingredion Incorporated |
| Tate & Lyle PLC |
| Bunge Limited |
| MGP Ingredients Inc. |
| Others |
Value Network & Pricing Analysis
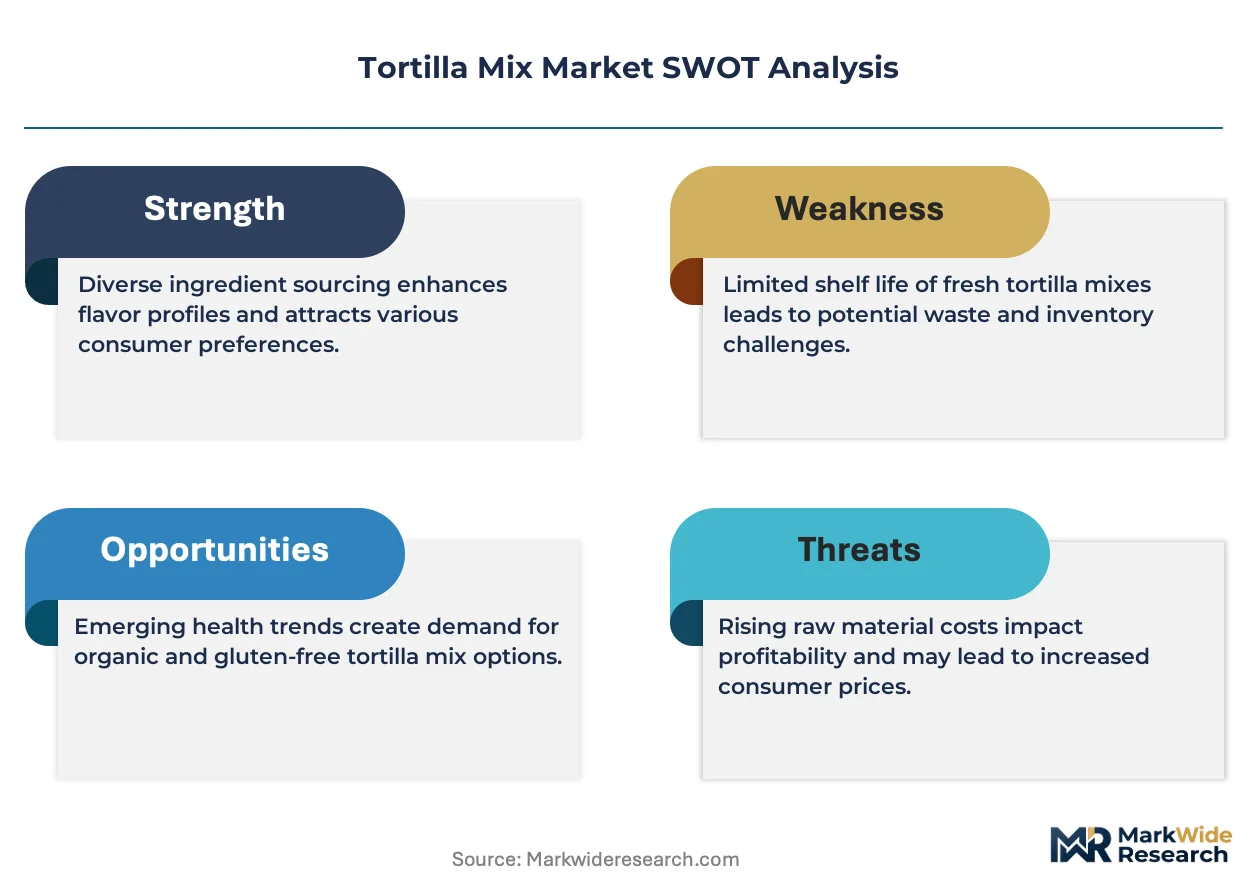
The Laredo-Nuevo Laredo freight corridor's cross-border logistics costs cascade through tortilla mix supply chains, amplifying price differentiation between heritage nixtamalized corn flour and commodity wheat alternatives while concentrating procurement power among distributors with bonded warehouse capacity.
Pricing Analysis
Long-term offtake contracts dominate procurement between restaurant chains and nixtamalized corn flour suppliers, insulating volume buyers from white corn futures volatility while spot purchases in retail channels absorb commodity price swings. Three-tier pricing structure across premium, standard, and economy levels separates USDA Organic certified heritage blends from conventional nixtamalized formulations and bulk wheat flour alternatives. Cost compression in the economy tier is intensifying because pre-formed frozen tortillas are capturing institutional foodservice accounts. Quick-service restaurant commissaries exhibit lowest price sensitivity due to brand differentiation requirements; home cooks in specialty retail show highest sensitivity to per-unit costs.
Supply Chain Analysis
Contract manufacturing concentration rests with Gruma Corporation's captive nixtamalization facilities in Mexico's Estado de México and Tlaxcala regions, supplemented by Archer Daniels Midland Company's industrial wheat milling network across Iowa and Illinois. Raw material dependencies center on white corn from Illinois and Iowa growing regions, lime for nixtamalization sourced from Veracruz quarries, and heritage landrace seed stock from Puebla plateau communities. Single-source vulnerability concentrates in traditional lime-cooking expertise aging out of Mexican processing facilities. Distribution runs through broadline foodservice distributors with palletized bulk delivery to restaurant commissaries, bypassed by direct-to-restaurant fleets in Texas and California metro markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Tortilla mix penetration sits at early-cycle expansion, propelled by quick-service restaurant chains consolidating fresh production programs under central commissary models that displace frozen alternatives.
For Market Incumbents: Build captive heritage corn variety moats through backward integration into landrace seed sourcing from Mexico's central plateau, securing nixtamalization process claims against extrusion technology substitutes. Expand FSMA-certified capacity in Texas and Arizona to capture Chipotle-scale fresh program rollouts before mid-scale competitors absorb compliance costs. Channel control through proprietary delivery fleets defends margin position against broadline distributor consolidation. For New Entrants and Emerging Players: Spain and the United Kingdom's nascent fresh tortilla adoption in tapas and Tex-Mex restaurant clusters offers white-space expansion with minimal incumbent nixtamalization presence. Gluten-free rice-almond-cassava blends certified through the Gluten-Free Certification Organization represent the most penetrable segment, as celiac-safe protocols outpace incumbent reformulation timelines. Direct-to-restaurant distribution bypassing established broadline networks captures margin in underserved European metro markets. For Investors and Strategic Acquirers: Mid-scale organic certifiers with stone-ground processing credentials and established Sprouts Farmers Market shelf placement represent prime acquisition targets for portfolio diversification into specialty retail growth. Long-term viability across the projection horizon hinges on clean-label reformulation completion and nixtamalization automation adoption. Watch extrusion technology pilot outcomes in Texas commissaries as inflection signal for traditional process displacement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Heritage Corn Backward Integration | Captive landrace sourcing from Puebla plateau secures premium positioning against commodity substitutes. |
| FSMA-Certified Capacity Expansion | Documented hazard analysis plans unlock Chipotle-scale procurement beyond mid-scale competitor reach. |
| Direct-to-Restaurant Distribution | Proprietary Texas and California fleets capture margin otherwise absorbed by broadline distributors. |
| Gluten-Free Certification Investment | GFCO-certified rice-almond-cassava blends penetrate celiac-safe menu expansions ahead of incumbent timelines. |
| Extrusion Technology Piloting | High-pressure steam injection systems collapse nixtamalization from 12 hours to 45 minutes for same-day production. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with restaurant commissary procurement directors, nixtamalization facility plant managers, specialty retail category buyers, and FDA compliance officers at flour milling operations. Secondary validation drew from USDA Organic certification databases, FDA FSMA inspection records, Mexico's Secretariat of Economy NOM standards filings, and white corn futures data from the Chicago Board of Trade. Bottom-up volume estimates from individual facility throughput combined with top-down market sizing from grain origination networks to produce triangulated figures.
Calibration against historical adoption curves for fresh tortilla programs in quick-service restaurants anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, end-user category, distribution channel, and packaging format, with nixtamalization process type as an industry-specific overlay. CAGRs were derived from regression analysis of procurement volume trends against restaurant chain expansion announcements and retail shelf-space allocation data. Forecast inputs incorporated FSMA compliance cost absorption rates and extrusion technology pilot adoption signals from Texas and Arizona commissaries.
The forecast holds incumbent behavior within observed patterns; aggressive moves by industrial baking conglomerates into frozen tortilla substitutes would shift outcomes toward mix-based displacement. Quarterly review of white corn futures volatility, FSMA enforcement intensity, and extrusion pilot scale-up announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Roasted Corn Market
Snacks
Snack Products Market
Snacks
North America Snack Food Market
Snacks
Low-Calorie Savoury Snacks Market
Snacks
Southeast Asia Savory Snacks Market
Snacks
Cereal Bars Market
Snacks
Granola Market
Snacks
Europe Frozen Snacks Market
Snacks
North America Cereal Bar Market
Snacks
No-Fat Peanut Butter Market
Snacks
Middle-East and Africa Cereal Bar Market
Snacks
South America Cereal Bar Market
Snacks
Allergy-Free Snacks Market
Snacks
Saudi Arabia French Fries Market
Snacks
Latin America Extruded Snack Food Market
Snacks
Veggie Chips Market