
 Fat Free Snacks Market | 2026-2036
Fat Free Snacks Market Size, Share, and Industry Trends Forecast 2026-2036
Fat Free Snacks Market Analytics
Single-serve and portion-controlled bundling is shifting how buyers evaluate fat-free snack options, moving value away from bulk packaging toward grab-and-go configurations. PepsiCo leverages its direct-store-delivery network to dominate convenience channel placement. Mondelez International differentiates through baked-chip technology leadership and reduced-fat cookie platforms. General Mills anchors the popcorn segment with air-popped production scale that sustains price competitiveness across mass retail.
Fat-free snacks are formulated products with less than 0.5 grams fat per serving, typically achieved through baking, air-popping, or extrusion rather than frying, serving the dual purpose of taste satisfaction within controlled caloric budgets. The chips segment leads volume but faces margin compression from commodity potato and corn input volatility, while the nuts ingredient category commands premium positioning due to inherent protein density and clean-label alignment. Health food stores represent the fastest-growing distribution channel as consumers trade up for certified organic and non-GMO fat-free alternatives.
FDA nutrition labeling requirements and EFSA health claim regulations shape permissible fat-free and reduced-fat marketing assertions, directly influencing product positioning and packaging communication. USDA school nutrition standards create institutional demand for compliant snack formats in federally supported meal programs. Stakeholders must monitor evolving front-of-package warning systems and sodium reduction mandates that could force reformulation investments ahead of enforcement timelines.
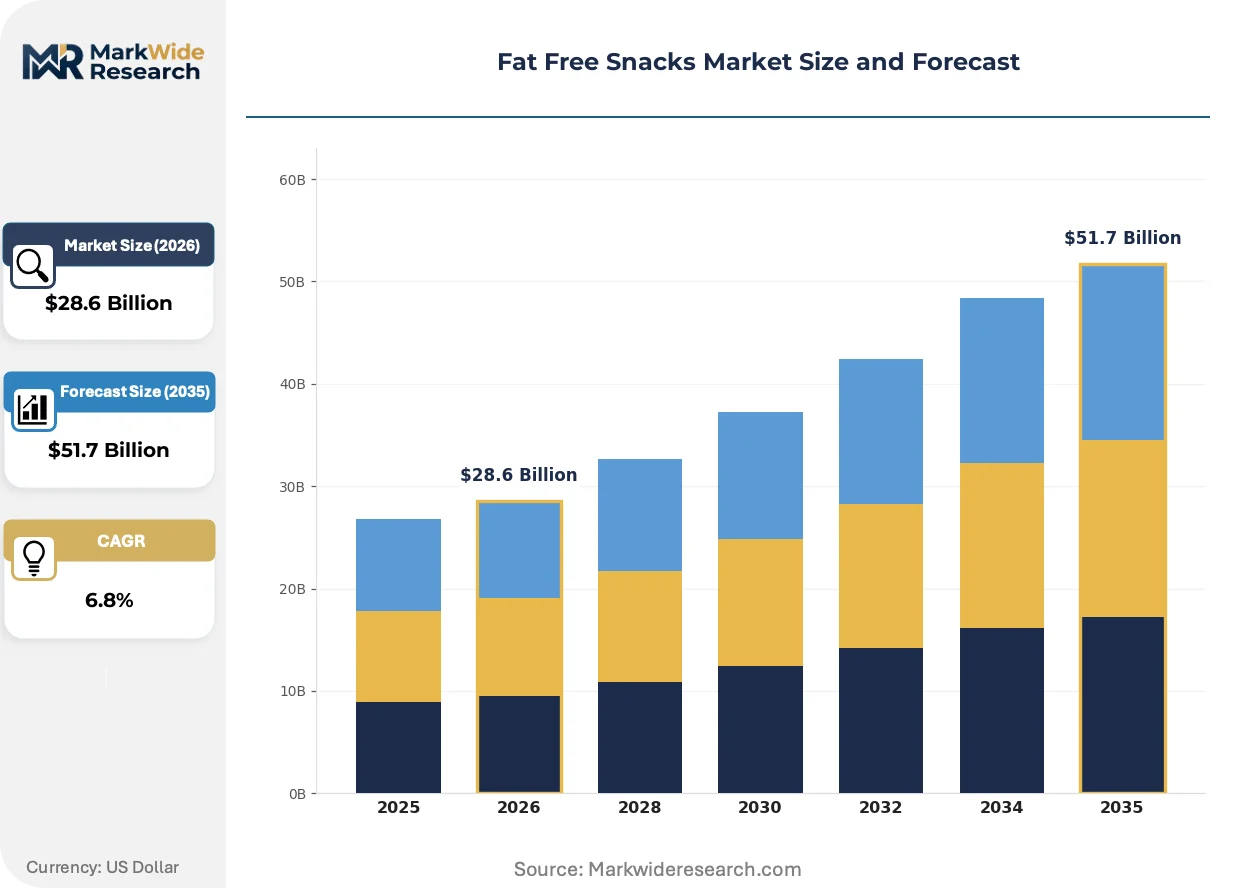
Market Dynamics
Clean-label reformulation mandates from FDA and EFSA are forcing manufacturers to eliminate trans fats and reduce saturated fat content while preserving shelf stability and mouthfeel in baked and extruded snack formats.
Growth Catalysts
- USDA School Nutrition Standards:Federally supported meal programs create institutional procurement pipelines for compliant fat-free snack formats in K-12 cafeterias, locking in multi-year volume commitments.
- Air-popping technology:Continuous flow hot-air expansion systems enable fat-free popcorn production at industrial scale, cutting oil input costs and simplifying ingredient declarations for clean-label positioning.
- Germany:Bundesinstitut für Risikobewertung guidance on acrylamide reduction drives investment in low-temperature baking alternatives to frying, accelerating fat-free chip adoption in Central European retail.
Market Restraints
- Potato and corn commodity volatility:Input cost swings for starchy substrates compress margins on volume chip SKUs, forcing trade-offs between price competitiveness and formulation quality.
- Flavor delivery limitations:Lipid-soluble flavor compounds require reformulation or encapsulation in fat-free matrices, raising R&D costs and extending development timelines.
- Single-source extrusion equipment:Concentrated supply of high-shear twin-screw extruders from Italian and German OEMs creates bottleneck risk for capacity expansion.
Strategic Opportunities
- Direct-to-consumer subscription models:Portion-controlled monthly boxes bypass slotting fee barriers in consolidated retail, capturing lifetime value from fitness-focused cohorts.
- India:FSSAI enforcement of packaged food labeling rules creates first-mover advantage for brands with established fat-free claims ahead of local competitor adaptation.
- Pulse flour extrusion:Convergence of air-popping and lentil-protein extrusion enables savory snack formats with complete amino acid profiles, opening sports nutrition adjacencies.
Industry Challenges
- Clean-label preservative substitution:Removing fat as a natural oxidation barrier forces rapid adoption of high-pressure processing or modified atmosphere packaging, requiring capex-heavy line retrofits.
- Sensory panel calibration:Fat-mimetic mouthfeel engineering demands specialized food rheology expertise scarce in conventional snack R&D departments, inflating recruitment costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fat Free Snacks Market |
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chips, Cookies, Crackers, Popcorn Ingredient Type: Fruits, Nuts, Vegetables, Grains Distribution Channel: Online Retail, Supermarkets, Convenience Stores, Health Food Stores End User: Health Conscious Consumers, Fitness Enthusiasts, Weight Watchers, Families |
| Companies Covered | General Mills, Mondelez International, PepsiCo, Nestlé, Kellogg Company, Kraft Heinz, Hain Celestial Group, Dole Food Company, ITC Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fat Free Snacks Market Evolving Landscape
Reformulation science is converging with packaging engineering to solve the shelf-life and sensory gaps that have historically limited fat-free snack penetration beyond dietetic niches.
Microencapsulation of lipid-based flavor systems is modularizing how fat-free matrices deliver taste impact without fat content. Health-conscious millennials and Gen Z buyers in US coastal metros are adopting these products at rates outpacing traditional reduced-fat alternatives. The technology is compressing the sensory quality gap between baked and fried formats, eroding a core barrier to premium positioning.
EFSA's updated guidance on nutrition and health claims regulates how "fat-free" and "low-fat" assertions appear on packaging across EU member states. Manufacturers must substantiate claims with validated analytical methods, reshaping label design and marketing communication budgets. Baked chip categories in France and Benelux markets are responding fastest, reformulating to meet claim thresholds ahead of enforcement audits.
Subscription-based replenishment is displacing impulse purchases in convenience retail for core snack buyers. Fitness enthusiasts and remote workers are migrating toward auto-ship models that guarantee portion discipline, bypassing supermarket end-cap competition. This pattern concentrates in US metropolitan corridors with high gym density and premium grocery saturation.
Fat Free Snacks Market Segmentation
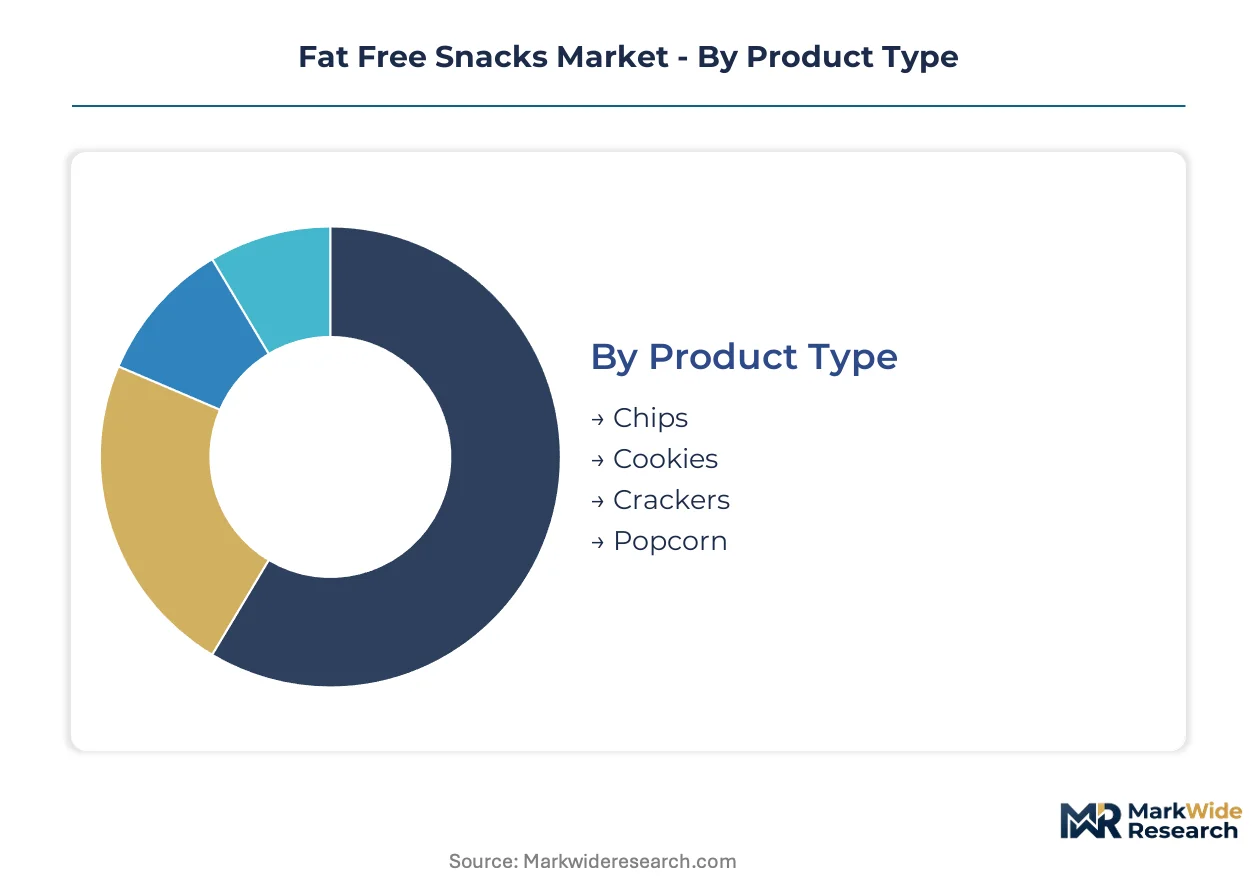
Segmentation in fat-free snacks reveals how formulation constraints and channel economics split manufacturing investment across incompatible production technologies. Each dimension—product format, ingredient sourcing, distribution logistics, and buyer motivation—creates distinct margin profiles that reshape competitive positioning.
Product Type:
Supply concentration in extrusion and air-popping equipment tilts capacity allocation toward formats that minimize oil dependency while preserving throughput economics.
- Chips:Baked or extruded potato and corn matrices achieve fat-free status through high-shear processing rather than frying. Demand clusters in US convenience retail where grab-and-go packaging commands shelf placement premiums.
- Popcorn:Continuous-flow hot-air expansion systems enable industrial-scale production with zero oil input, cutting both ingredient costs and clean-label complexity. Air-popped formats absorb the fastest volume growth from fitness-oriented subscription channels.
- Cookies:Fat-free formulations rely on modified starches and hydrocolloid binders to replace shortening functionality.
- Crackers:Low-moisture baking preserves shelf stability without lipid oxidation barriers.
Chips absorb the bulk of installed capacity; popcorn is expanding most quickly.
Ingredient Type:
Input cost volatility and protein density premiums split procurement strategies between commodity starches and value-added alternatives.
- Grains:Corn, rice, and wheat flours dominate extrusion feedstocks due to neutral flavor profiles and established supply infrastructure. US heartland sourcing corridors anchor cost-competitive chip and cracker production.
- Nuts:Inherently fat-dense ingredients require defatted flour processing or portion-controlled inclusion to meet regulatory thresholds. Defatted peanut and almond proteins command premium positioning in sports nutrition adjacent formats.
- Fruits:Freeze-dried and air-dried formats leverage natural sugar content for flavor delivery without fat carriers.
- Vegetables:Root vegetable crisps and legume-based extrusions appeal to clean-label positioning.
Grains anchor volume throughput; nuts capture the steepest margin expansion.
Distribution Channel:
Slotting fee structures and inventory velocity requirements filter which product formats reach specific buyer contexts.
- Supermarkets:Mass retail placement demands case-stack efficiency and promotional calendar coordination. US national chains concentrate volume for core chip and popcorn SKUs with household penetration above category averages.
- Health Food Stores:Certified organic and non-GMO verification requirements create barrier-to-entry for conventional manufacturers. Coastal US metros with premium grocery saturation show the fastest same-store growth for fat-free alternatives.
- Online Retail:Direct-to-consumer subscription models bypass slotting economics.
- Convenience Stores:Single-serve packaging formats dominate impulse purchase occasions.
Supermarkets absorb the bulk of case volume; health food stores are gaining share fastest.
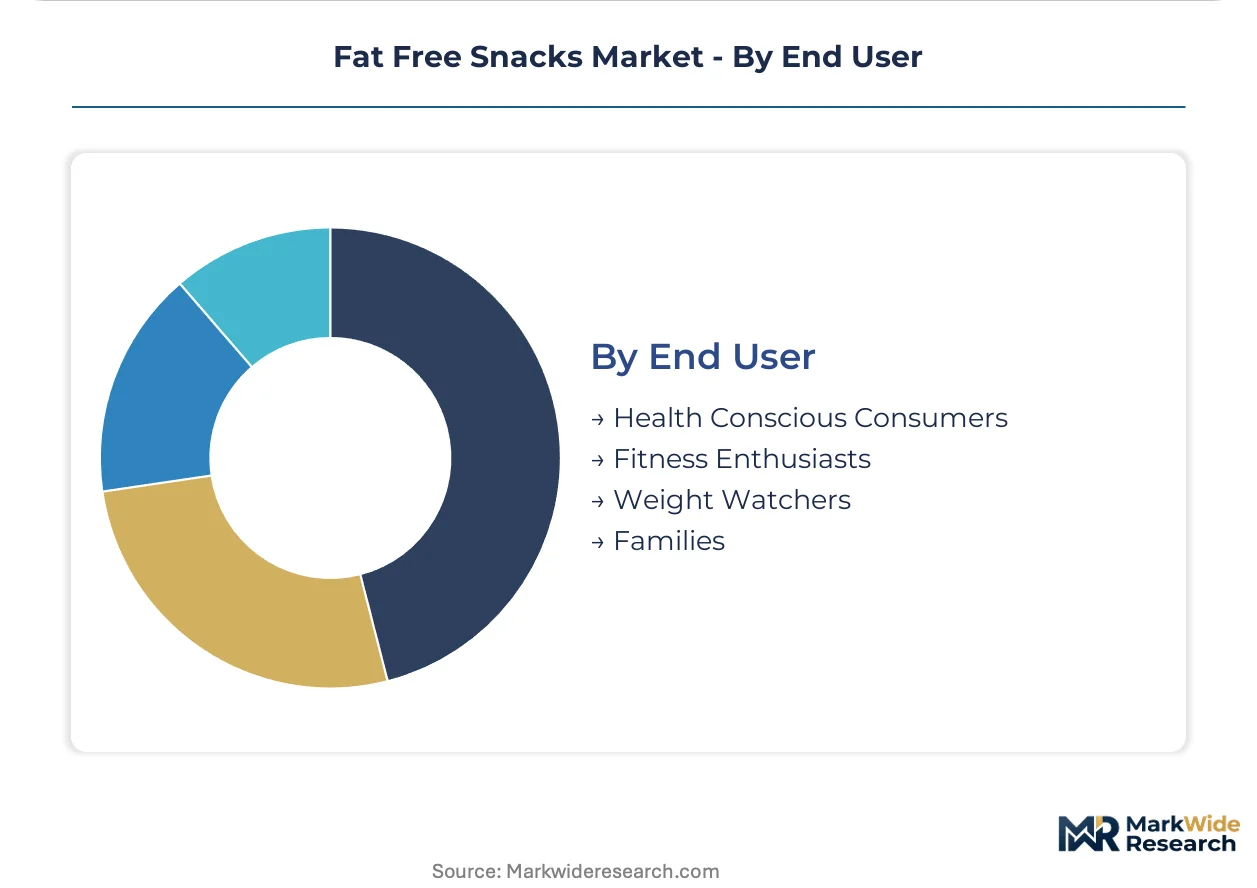
End User:
Usage occasion specificity and nutritional literacy levels determine willingness to trade taste compromise for label claims.
- Fitness Enthusiasts:Macro-tracking precision demands drive acceptance of texture trade-offs in exchange for verified fat-free certification. Gym-adjacent retail and sports nutrition e-commerce concentrate demand for high-protein, fat-free formats.
- Health Conscious Consumers:Clean-label scanning behavior prioritizes ingredient list brevity over absolute fat reduction. US coastal urban markets show highest penetration of baked and air-popped alternatives.
- Weight Watchers:Portion-controlled packaging aligns with behavioral compliance frameworks.
- Families:Multi-serve formats and child-friendly flavor profiles dominate household purchasing.
Fitness enthusiasts absorb the bulk of premium pricing; health conscious consumers are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity clusters in North American and European extrusion technology corridors while consumption concentrates in urban centers with high health-conscious population density. This geographic split creates distinct supply chain configurations across major national markets.
United States
FDA nutrition labeling requirements and USDA school nutrition standards institutionalize demand for compliant fat-free snack formats across K-12 and retail channels. Private-label expansion accelerates category penetration in mass retail. Chicago and Minneapolis-St. Paul anchor Midwest production clusters for extruded and air-popped formats.
Germany
Bundesinstitut für Risikobewertung guidance on acrylamide reduction drives low-temperature baking investment ahead of frying alternatives. EFSA health claim regulations shape permissible fat-free marketing assertions across EU member states. The Munich-Stuttgart corridor concentrates clean-label reformulation R&D for Central European distribution.
India
FSSAI enforcement of packaged food labeling rules creates first-mover advantage for brands with established fat-free claims. Rising gym culture and fitness tracking adoption expand demand for portion-controlled formats. Mumbai and Bangalore lead e-commerce subscription penetration for health-conscious urban professionals.
United Kingdom
EFSA-aligned UK nutrition claims regulation governs permissible fat-free and reduced-fat packaging assertions. Premium grocery saturation in London and Southeast England drives fastest same-store growth for certified organic alternatives. The East Midlands hosts concentrated extrusion equipment manufacturing serving domestic and export markets.
Japan
METI industrial standards and consumer preference for portion discipline sustain demand for single-serve fat-free formats. Aging demographics and metabolic health awareness expand the weight management consumer base. The Osaka-Kobe manufacturing belt specializes in precision extrusion for savory snack exports.
Fat Free Snacks Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Consolidated multinational food corporations anchor mass retail placement through direct-store-delivery networks and promotional scale. Three strategic archetypes dominate: integrated snack conglomerates with extrusion technology ownership, health-focused pure-plays with clean-label certification depth, and private-label manufacturers serving retailer captive brands. Capacity expansion and portfolio diversification represent the dominant competitive moves as players respond to clean-label reformulation mandates.
Among North American integrated food corporations, General Mills, Mondelez International, and PepsiCo occupy positions spanning mass retail and convenience channel dominance. General Mills exemplifies scale-driven air-popped production, Mondelez International represents baked-chip technology leadership, and PepsiCo anchors direct-store-delivery network coverage. These three corporations collectively illustrate how diversified snack portfolios compete against emerging pure-play specialists in the fat-free segment.
| Leading Market Players |
|---|
| General Mills |
| Mondelez International |
| PepsiCo |
| Nestlé |
| Kellogg Company |
| Kraft Heinz |
| Hain Celestial Group |
| Dole Food Company |
| ITC Limited |
| Others |
Value Network & Pricing Analysis
Clean-label reformulation mandates from FDA and EFSA gate qualified supply access and premium-tier pricing power, forcing manufacturers to absorb capex-heavy line retrofits or surrender shelf placement to certified competitors. This regulatory filter concentrates margin capture among players with verified fat-free claims and validated analytical methods.
Pricing Analysis
Margin tightening in standard-tier chips reflects potato and corn commodity volatility compressing case-stack economics for mass retail SKUs. Three-tier pricing structure across premium, standard, and economy levels separates certified organic air-popped formats from conventional baked alternatives and private-label economy lines. Price differentiation hinges on clean-label certification depth and direct-store-delivery network coverage. Fitness enthusiasts demonstrate lowest price sensitivity, while family household buyers drive volume through promotional calendar responsiveness.
Supply Chain Analysis
Workforce availability constraints in Chicago and Minneapolis-St. Paul extrusion corridors limit capacity expansion for air-popped and high-shear baked formats. Supply concentrates in the United States, Germany, and Italy, with starchy substrates drawn from US heartland sourcing corridors and precision extrusion equipment anchored in Italian and German OEM manufacturing. Single-source equipment dependency creates bottleneck risk for capacity scaling. Distribution runs through direct-store-delivery networks for mass retail and subscription bypass models for fitness-focused cohorts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around clean-label certification depth as smaller manufacturers face insurmountable reformulation capex and validation timelines. EFSA enforcement audits and FDA guidance updates accelerate attrition among undifferentiated players.
For Market Incumbents: Acquire extrusion technology ownership and captive air-popping capacity to defend against commodity input volatility and emerging pure-play specialists with certified organic positioning. Lock in multi-year USDA school nutrition program commitments before competitive bidding intensifies. Prioritize backward integration into defatted nut protein processing for sports nutrition adjacency expansion.
For New Entrants and Emerging Players: Remote workers seeking portion discipline represent the most penetrable buyer archetype underserved by incumbent impulse-retail dominance. Target direct-to-consumer subscription channels in US metropolitan corridors with high gym density, bypassing slotting fee barriers that protect established supermarket placement. Lead with pulse flour extrusion formats delivering complete amino acid profiles to differentiate from commodity starch competitors.
For Investors and Strategic Acquirers: FSSAI enforcement of packaged food labeling rules in India is the leading indicator that regulatory convergence will reward first-mover certification investments across emerging markets. Five-to-ten year viability favors pure-play specialists with clean-label certification depth and subscription channel infrastructure over diversified conglomerates with legacy fried-format exposure. Watch for Bundesinstitut für Risikobewertung acrylamide guidance expansion as signal for low-temperature baking technology acquisition premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Certification Investment | FDA and EFSA validated analytical methods unlock premium shelf placement and health claim eligibility. |
| Air-Popping Capacity Expansion | Continuous flow hot-air systems cut oil input costs and simplify ingredient declarations for fitness channels. |
| Direct-to-Consumer Subscription Launch | Auto-ship models capture lifetime value from macro-tracking enthusiasts bypassing supermarket competition. |
| Pulse Flour Extrusion Development | Lentil-protein savory formats open sports nutrition adjacencies with complete amino acid profiles. |
| Backward Integration into Defatted Protein Processing | In-house defatted peanut and almond flour production secures margin capture in premium positioning tiers. |
Research Methodology
Document review covered FDA guidance documents, EFSA health claim registers, USDA school nutrition standards, and Bundesinstitut für Risikobewertung acrylamide assessments, complemented by interviews with snack category buyers at national retail chains, extrusion equipment procurement directors, clean-label R&D formulators, and sports nutrition e-commerce operators. Secondary validation drew from Nielsen retail audit data, customs trade records for starchy substrate flows, and SEC filings of diversified food conglomerates. Bottom-up SKU-level volume builds triangulated against top-down category expenditure models.
Historical volume trajectories cross-referenced against panel input from manufacturing capacity planners and ingredient procurement specialists shaped the analytical framework. Segmentation dimensions modeled include product format, ingredient sourcing strategy, distribution channel economics, and buyer motivation archetype across the projection horizon. CAGRs derived from trend extrapolation adjusted for regulatory enforcement timelines and technology adoption S-curves, with specific inputs from air-popping equipment installation backlogs and subscription channel customer acquisition cost trends.
Revisions become necessary when EFSA enforcement audit schedules accelerate, FSSAI labeling rule implementation tightens, or commodity potato and corn price volatility exceeds historical bands. Material deviation in named triggers warrants pause and re-evaluation of volume and value assumptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Healthy Fruit and Vegetable Chips Market
Snacks
Middle East Snack Bar Market
Snacks
Healthy Fat-Free Snacks Market
Snacks
Veggie Chips Market
Snacks
Low Calorie Granola Market
Snacks
Low Sodium Snacks Market
Snacks
Europe Energy Bar Market
Snacks
Asia Pacific Snack Food Market
Snacks
Fruit and Vegetable Chips Market
Snacks
North America Pretzel Market
Snacks
United Kingdom Snack Bar Market
Snacks
South Africa Snack Bar Market
Snacks
Snack Products Market
Snacks
Edible Flakes Market
Snacks
Austria Snack Bar Market
Snacks
South America Energy Bar Market