
 Europe Snacks Food Market | 2026-2036
Europe Snacks Food Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Snacks Food Market Foresight
Premium clean-label tiering is unwinding across the European snacks landscape as retailers and consumers trade up from standard formulations. Intersnack Group GmbH leverages its German manufacturing footprint to dominate private-label and branded savory lines across Central Europe. Nestlé S.A. anchors its position through R&D intensity in portion-controlled and nutritionally modified snack formats. Mondelez International competes aggressively on chocolate-coated and biscuit-based snack hybrids, sustaining brand strength in Southern European impulse channels.
Europe snacks food encompasses ready-to-eat products manufactured through baking, frying, extrusion, or air-popping of cereal, tuber, nut, or legume bases, typically packaged in moisture-barrier films with shelf lives ranging from three to twelve months for retail distribution. These products serve commercial purposes spanning impulse convenience, planned pantry stocking, and out-of-home consumption occasions across supermarkets, petrol stations, and foodservice outlets. Chips retains the largest revenue pool within product type segmentation, though extruded snacks represents the fastest-growing category as manufacturers deploy twin-screw extrusion to achieve texture and protein-fortification targets. Health-conscious customer segmentation commands disproportionate margin contribution, while on-the-go consumers drive pouch-format innovation in packaging type.
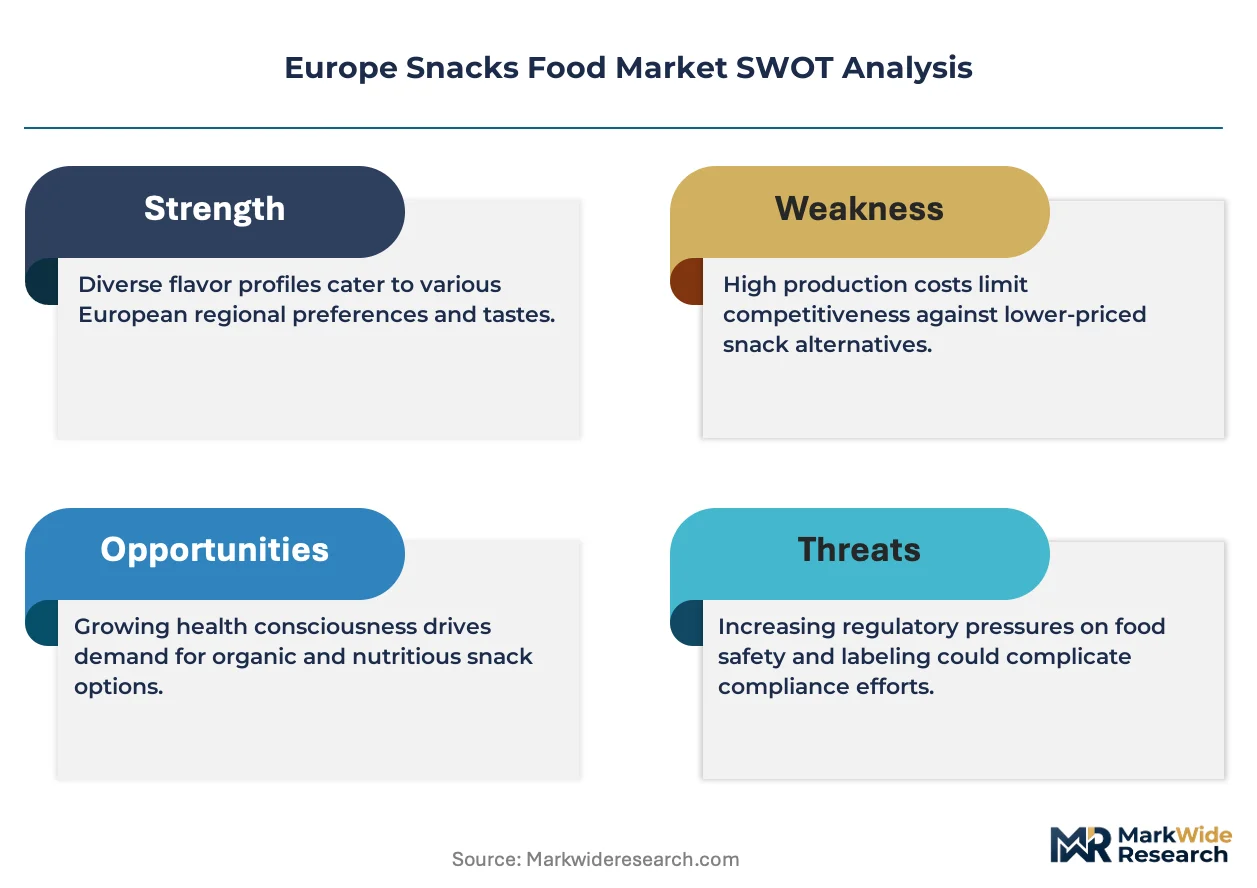
EFSA governs nutrition and health claims verification, compelling manufacturers to substantiate protein, fiber, or reduced-fat positioning with clinical evidence or reformulation compliance. EU Green Deal packaging directives and national extended producer responsibility schemes in France, Germany, and Italy are redirecting capital toward mono-material recyclable films and paper-based alternatives. REACH chemical safety standards further constrain additive and coating selections across flavor profile development. Stakeholders must monitor regulatory acceleration on front-of-pack labeling and plastic taxation schedules to calibrate portfolio renovation timelines against compliance cost curves.
Market Dynamics
EFSA's tightened substantiation requirements for nutrition claims are forcing simultaneous reformulation across sodium reduction, clean-label ingredient sourcing, and front-of-pack disclosure protocols. This regulatory compression is accelerating capital deployment toward extrusion technology upgrades and mono-material packaging conversion.
Growth Catalysts
- Clean-label protein fortification:Twin-screw extrusion technology enables chickpea and lentil flour integration into savory matrices. German and French retailers are expanding shelf space for these positioned lines.
- EU Green Deal packaging mandates:Extended producer responsibility schemes in France, Germany, and Italy are creating compliant-first procurement preferences. Mono-material films and paper-based barriers gain volume commitments.
- Metropolitan convenience density:Petrol station and transit-hub retail formats in London, Paris, and Milan are absorbing higher-margin pouch formats. Impulse occasion expansion drives premium tier absorption.
Market Restraints
- Sunflower oil input volatility:Black Sea supply disruptions and EU biofuel diversion mandates are compressing margin structures for fried snack categories. Reformulation to alternative oils requires sensory validation cycles.
- EFSA claim substantiation costs:Clinical evidence requirements for protein, fiber, or reduced-fat positioning demand six-figure validation investments. Mid-tier manufacturers face portfolio narrowing.
- Flexible packaging supply concentration:Mono-material film capacity concentrates among German and Austrian converters. Lead times for compliant substrates extend procurement risk.
Strategic Opportunities
- Eastern European penetration gaps:Poland, Romania, and Bulgaria exhibit underdeveloped premium savory snack distribution. Modern trade expansion in Warsaw and Bucharest creates first-mover positioning.
- Air-popped texture convergence:Hot-air expansion technology married to seasoning encapsulation is displacing oil-fried alternatives in health-positioned segments. Equipment suppliers in northern Italy are scaling capacity.
- Digital direct-to-pantry channels:Subscription snack boxes and rapid-delivery apps in Amsterdam, Berlin, and Barcelona are bypassing traditional retail slotting fees. Data capture enables flavor personalization.
Industry Challenges
- Extrusion engineering talent scarcity:Process engineers capable of optimizing screw profiles for protein-fortified matrices command premium compensation. Technical universities in the Netherlands and Belgium are expanding food engineering pipelines.
- Legacy equipment retrofit complexity:Existing fryer and seasoning lines require substantial modification to handle clean-label oil alternatives and reduced-sodium coatings. Downtime during conversion compresses quarterly output.
- REACH additive approval timelines:Novel flavor encapsulants and natural preservative systems face eighteen-month safety dossier reviews. Product launch schedules must accommodate regulatory lag.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Snacks Food Market |
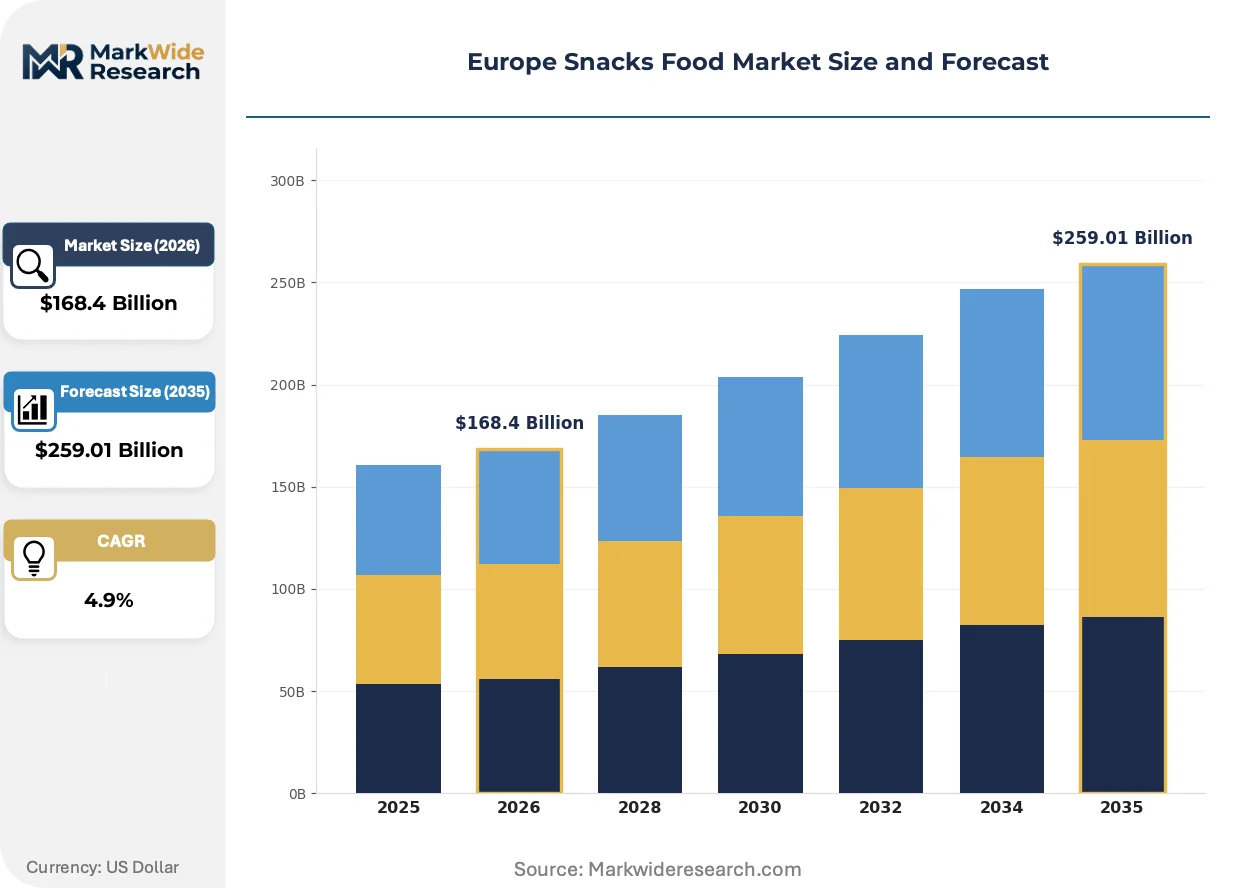
| Market Size in 2026 | $168.4 Billion |
| Market Size in 2035 | $259.01 Billion |
| CAGR (2026 – 2036) | 4.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chips, Extruded Snacks, Popcorn, Nuts Flavor Profile: Sweet, Savory, Spicy, Sour Packaging Type: Bags, Boxes, Trays, Pouches Customer Type: Adults, Children, Health-Conscious, On-the-Go Consumers |
| Companies Covered | Intersnack Group GmbH, The Kraft Heinz Company, PepsiCo Inc., Mars Inc., Kellogg Company, Nestlé S.A., General Mills Inc., Unilever PLC, Mondelez International, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Snacks Food Market Shifts & Advancements
Processing technology and regulatory disclosure requirements are actively fragmenting competitive advantage sources across the European snacks landscape. Manufacturers must now synchronize equipment capability, ingredient provenance transparency, and packaging compliance in integrated development cycles.
Twin-screw extrusion technology is bifurcating the savory snacks category between protein-fortified premium tiers and conventional starch-based economy lines. Health-conscious consumers in metropolitan France and northern Italy are absorbing these positioned products at accelerated rates. The technology is compressing traditional frying equipment demand while expanding R&D intensity around texture modulation and off-flavor masking.
EFSA's updated guidance on nutrition and health claims verification is tightening evidentiary standards for protein, fiber, and reduced-fat positioning. Manufacturers must now submit clinical or compositional data prior to market entry, extending development timelines. Southern European impulse channels and private-label suppliers face disproportionate compliance burden relative to branded players with captive research infrastructure.
Consumer pantry-stocking behavior is rotating toward transparent ingredient sourcing and front-of-pack interpretive labels. Retailers in Germany and the United Kingdom are responding with clean-label aisle segmentation and Nutri-Score integration. This preference shift is most visible in family-household segments, where purchase decisions increasingly hinge on additive-free positioning and recognizable ingredient lists rather than price-point optimization alone.
Europe Snacks Food Market Segmentation
Channel fragmentation across European retail formats demands precise segment-channel matching. Supermarket chains, petrol stations, and rapid-delivery apps each absorb distinct product configurations, packaging formats, and flavor positioning.
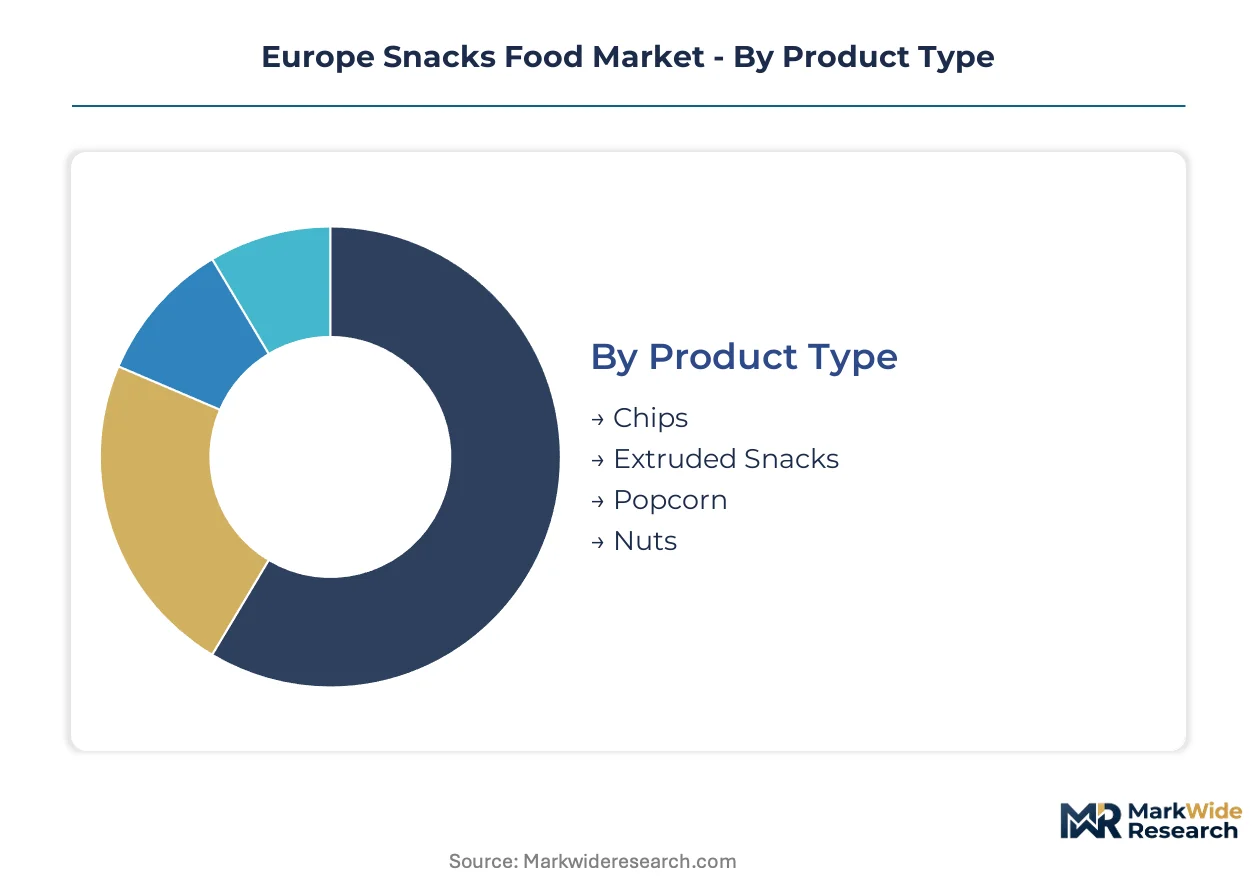
Product Type:
Channel placement varies sharply by processing method and margin structure. Fried and extruded lines dominate impulse formats, while air-popped and raw nut offerings concentrate in health-positioned supermarket aisles.
- Chips:Thin-sliced potato or root vegetable bases fried in sunflower or rapeseed oil, seasoned post-fry. German and UK petrol station networks absorb the highest volumes of single-serve bags, though Black Sea oil supply disruptions are compressing manufacturer margins. Shelf-stable formats sustain planned pantry stocking in French and Italian supermarkets.
- Extruded Snacks:Twin-screw extrusion of cereal, legume, or tuber flours into puffed or textured matrices, enabling protein fortification and sodium reduction. Northern Italian and metropolitan French retailers are expanding dedicated shelf space for chickpea and lentil-based positioned lines. EFSA claim substantiation requirements extend development timelines for protein-forward positioning.
- Popcorn:Hot-air expansion or kettle-popped maize kernels with oil and seasoning encapsulation. Dutch and Belgian rapid-delivery apps are absorbing premium pouch formats for home consumption occasions.
- Nuts:Roasted, raw, or seasoned tree nuts and legumes, often positioned as protein-forward alternatives to carbohydrate-heavy snacks. German clean-label aisle segmentation favors additive-free dry-roasted varieties.
Chips dominates installed base. Extruded snacks is where expansion concentrates.
Flavor Profile:
Regional palate variation drives formulation complexity. Southern European consumers tolerate higher sodium and spice intensity, while northern markets prioritize reduced-salt positioning and front-of-pack transparency.
- Savory:Cheese, onion, barbecue, and meat-simulated profiles relying on yeast extracts, hydrolyzed proteins, and natural flavor precursors. UK and German supermarkets maintain the broadest savory SKU breadth, though EFSA sodium reduction pressure is forcing reformulation toward potassium chloride and umami enhancer systems.
- Sweet:Honey, caramel, chocolate, and fruit-based coatings on puffed or nut bases. French and Belgian impulse channels absorb chocolate-hybrid snack formats at premium price points. Sugar taxation schedules in the UK and Ireland are redirecting R&D toward polyol and fiber-based sweetening systems.
- Spicy:Chili, pepper, and pungent spice blends calibrated to Scoville-equivalent intensity tiers. Spanish and Portuguese metropolitan convenience stores show highest tolerance for heat-forward positioning.
- Sour:Vinegar, citrus, and fermented flavor profiles leveraging acidulants and natural fermentation derivatives. Eastern European markets exhibit distinct preference for pickled and sour cream-adjacent snack coatings.
Savory commands volume leadership. Sweet is climbing the fastest as chocolate-nut hybrids penetrate premium tiers.
Packaging Type:
EU Green Deal mandates are redirecting procurement toward mono-material and paper-based barrier systems. Extended producer responsibility schemes in France, Germany, and Italy penalize multi-layer flexible films.
- Bags:Vertical form-fill-seal flexible films with moisture and oxygen barriers, historically multi-layer but converting to mono-material polypropylene or polyethylene. German converters are scaling compliant substrate capacity with extended lead times.
- Pouches:Stand-up or flat pouches with reseal features, absorbing premium positioning and on-the-go consumption. Amsterdam and Berlin rapid-delivery apps are standardizing pouch formats for subscription snack box fulfillment.
- Boxes:Paperboard cartons with inner barrier linings, common for multipack and gift-oriented snack assortments. UK retailers are expanding paper-primary packaging aisles in response to consumer plastic aversion.
- Trays:Rigid or semi-rigid thermoformed containers, typically for deli-counter or foodservice snack presentation. Italian petrol station foodservice formats favor tray-based nut and dried fruit combinations.
Bags retain installed base dominance. Pouches is where format innovation and margin expansion concentrate.
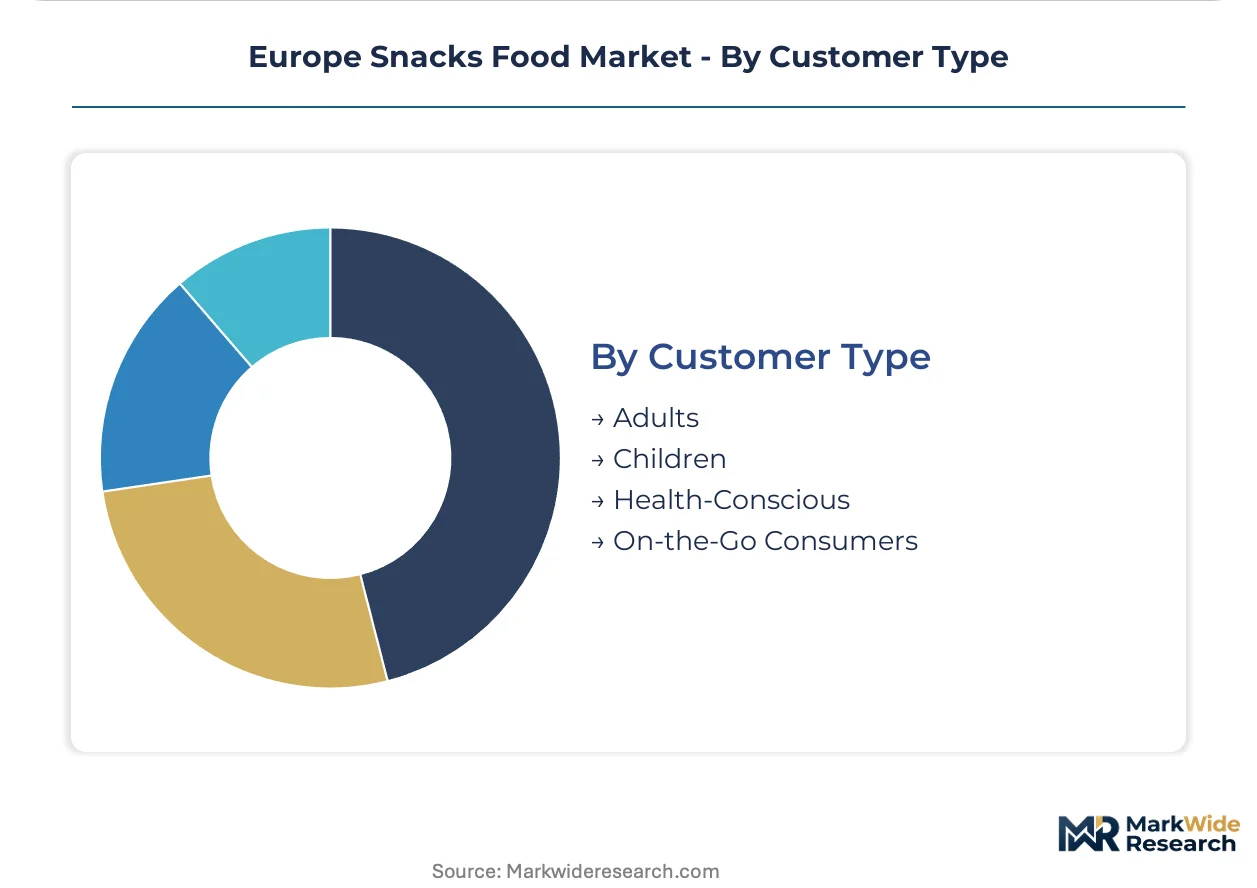
Customer Type:
Purchase occasion and decision criteria fragment sharply across demographic and behavioral segments. Health-conscious and on-the-go consumers command disproportionate margin contribution despite smaller volume shares.
- Health-Conscious:Consumers prioritizing protein content, additive-free positioning, and front-of-pack interpretive labels. French Nutri-Score integration and UK traffic-light labeling are standardizing purchase criteria. Clean-label aisle segmentation in German supermarkets concentrates demand for recognizable ingredient lists and reduced sodium.
- On-the-Go Consumers:Transit-hub and workplace consumption occasions demanding single-serve portability and reseal functionality. London, Paris, and Milan metropolitan rail networks are absorbing the highest volumes of premium pouch formats.
- Adults:Planned pantry stocking and social occasion consumption, with price sensitivity varying by household income tier. Family-household segments in suburban UK and German markets favor multipack value formats.
- Children:Pester-power driven impulse purchases, increasingly constrained by school nutrition policies and parental sugar awareness. Portion-controlled and nutritionally modified formats from branded players are displacing conventional confectionery-adjacent snacks.
Adults represent volume concentration. Health-conscious is where margin expansion and R&D intensity concentrate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European snack food trade flows reveal Germany and the Netherlands as net exporters of extruded and packaged formats, while Mediterranean markets import premium positioning inputs and specialty oils. Import dependency for sunflower and rapeseed oil concentrates Black Sea supply risk in Central European frying operations.
Germany
Petrol station networks and discount supermarket chains absorb the highest volumes of private-label savory lines across Europe. Extended producer responsibility schemes under the EU Green Deal are accelerating mono-material packaging conversion among converters in North Rhine-Westphalia. The Rhine-Ruhr industrial corridor hosts twin-screw extrusion equipment suppliers scaling capacity for protein-fortified matrices.
United Kingdom
Transit-hub retail formats in London and rapid-delivery apps in Manchester are driving premium pouch format absorption. Sugar taxation schedules and front-of-pack traffic-light labeling are redirecting R&D toward polyol-based sweetening systems. The Midlands manufacturing belt concentrates clean-label reformulation facilities serving both domestic and Irish export markets.
France
Metropolitan Paris and Lyon exhibit accelerated uptake of chickpea and lentil-based extruded snacks in health-positioned supermarket aisles. Nutri-Score integration and EFSA claim substantiation requirements are extending development timelines for protein-forward positioning. The Hauts-de-France region anchors roasting and seasoning operations for nut-based premium tiers.
Italy
Northern Italian consumers in Milan and Turin demonstrate disproportionate absorption of air-popped and protein-fortified savory alternatives. REACH chemical safety standards constrain novel flavor encapsulant approval timelines for seasoning houses in Emilia-Romagna. Bologna-based equipment manufacturers are scaling hot-air expansion technology for oil-displacement applications.
Netherlands
Amsterdam and Rotterdam rapid-delivery channels are standardizing subscription snack box fulfillment for digital-native brands. Port infrastructure concentrates edible oil import flows from Black Sea and South American origins. Dutch flexible film converters in the Randstad are expanding mono-material polypropylene capacity with extended lead times for compliant substrates.
Europe Snacks Food Market Competitive Landscape
Concentration sits with branded multinationals and private-label specialists operating across tiered price positioning. The vendor base separates into three strategic archetypes: diversified FMCG conglomerates with captive R&D infrastructure, regional private-label manufacturers leveraging extrusion scale, and niche protein-forward challengers deploying direct-to-pantry channels. Competitive moves center on portfolio renovation for EFSA compliance and backward integration into oilseed processing to defend margin structures against input volatility.
Among diversified FMCG conglomerates, Nestlé S.A. and Mondelez International exemplify the R&D-intensive archetype, while Intersnack Group GmbH occupies the private-label manufacturing tier. These entities represent contrasting strategic positions—multinationals anchoring nutritionally modified and portion-controlled formats against German-based specialists dominating Central European savory distribution through manufacturing footprint scale.
| Leading Market Players |
|---|
| Intersnack Group GmbH |
| The Kraft Heinz Company |
| PepsiCo Inc. |
| Mars Inc. |
| Kellogg Company |
| Nestlé S.A. |
| General Mills Inc. |
| Unilever PLC |
| Mondelez International |
| Others |
Supply & Pricing Matrix
Sixteen-week lead times for mono-material flexible films from German and Austrian converters concentrate procurement risk and amplify pricing leverage among compliant substrate suppliers. EFSA reformulation mandates and EU Green Deal packaging directives compress margin structures as manufacturers absorb certification and equipment conversion costs simultaneously.
Pricing Analysis
Retail category buyers anchor three-tier pricing structure across premium, standard, and economy levels in the European snacks market. Price differentiation rests on clean-label certification tier and volume scale commitments to extrusion equipment suppliers. Pricing pressure stems from Black Sea sunflower oil supply disruptions forcing reformulation to alternative oils with sensory validation overhead. Discount supermarket chains in Germany exhibit highest price sensitivity, while metropolitan convenience formats in Paris and London absorb premium positioning with minimal elasticity.
Supply Chain Analysis
Germany and the Netherlands anchor extruded snack manufacturing and flexible film conversion capacity across the European supply base. Raw material dependencies center on Black Sea sunflower oil, Ukrainian and Russian origin, plus chickpea and lentil flour from North American and Mediterranean suppliers. Single-source vulnerability in mono-material film substrates concentrates risk among three dominant converters. Distribution runs through supermarket central warehouses, petrol station supply networks, and rapid-delivery app fulfillment centers in Amsterdam, Berlin, and Barcelona.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent snack manufacturers face substitution pressure from fresh prepared food and meal-kit services capturing pantry-stocking occasions. Defense requires portfolio renovation velocity that matches regulatory acceleration.
For Market Incumbents: Consolidate extrusion engineering capability through captive hiring pipelines at Dutch and Belgian technical universities. Secure backward integration into oilseed processing to defend margin structures against Black Sea supply volatility. Prioritize mono-material packaging conversion ahead of EPR scheme enforcement timelines in France and Germany. For New Entrants and Emerging Players: Direct-to-pantry subscription gaps in Eastern European capitals expose under-served premium savory demand. Target Warsaw and Bucharest modern trade expansion with protein-forward extruded lines. Leverage rapid-delivery app partnerships to bypass traditional retail slotting fees and capture consumption data for flavor personalization. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because EFSA compliance costs and equipment retrofit complexity favor scaled manufacturers with captive R&D infrastructure. Target mid-tier private-label specialists with extrusion scale but limited branded portfolio depth. Monitor REACH additive approval timelines as inflection signal for product launch velocity differentials.| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Reformulation | EFSA sodium reduction mandates force yeast extract and potassium chloride substitution in savory coatings. |
| Mono-Material Packaging Conversion | Extended producer responsibility schemes in France and Germany penalize multi-layer flexible films. |
| Protein Fortification R&D | Twin-screw extrusion enables chickpea and lentil integration for metropolitan French and Italian health positioning. |
| Eastern European Distribution Expansion | Warsaw and Bucharest modern trade growth creates first-mover premium savory positioning. |
| Digital Direct-to-Consumer Launch | Amsterdam and Berlin rapid-delivery apps bypass retail slotting fees for data-capture advantage. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with snack category buyers, extrusion equipment engineers, and flexible film procurement managers; and secondary validation through EFSA guidance documents, EU Green Deal packaging directives, and Nielsen retail audit data. Triangulation across bottom-up volume modeling and top-down macroeconomic anchoring refined segment-level estimates.
Across the analysis window, the forecasting framework modeled product type, flavor profile, packaging format, and customer type segmentation dimensions. CAGRs derived from historical volume trajectories adjusted for regulatory acceleration and technology substitution curves. Key inputs included Black Sea oil supply scenarios and mono-material film capacity expansion timelines from German and Austrian converters.
Forecasts assume regulatory continuity in EFSA nutrition claims verification and EU Green Deal packaging mandates; material policy shifts on front-of-pack labeling or plastic taxation would require re-modeling. Recalibration cycles align with material shifts in input commodity volatility and REACH additive approval timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
UAE Snack Bar Market
Snacks
Allergy-Free Snacks Market
Snacks
North America Snack Bar Market
Snacks
North America Frozen Snacks Market
Snacks
Roasted Snacks Market
Snacks
United Arab Emirates Energy Bar Market
Snacks
Italy Snack Bar Market
Snacks
Europe Popcorn Market
Snacks
Middle East and Africa Snack Food Market
Snacks
Vegan Snacks Market
Snacks
Corn Chips Market
Snacks
Savory Snack Products Market
Snacks
Cheese Snacks Market
Snacks
Middle East and North Africa Extruded Snack Food Market
Snacks
Spicy Sticks (Chinese Snack) Market
Snacks
Low Calorie Granola Market