
 North America Residential Heat Pump Market | 2026-2036
North America Residential Heat Pump Market Size, Share, and Industry Trends Forecast 2026-2036
North America Residential Heat Pump Market Analysis
Certified HVAC technician availability is collapsing across Ontario and the northeastern United States, forcing distributors to extend lead times and contractors to raise installation bids. Carrier Corporation leverages its factory-trained dealer network to sustain service coverage in constrained labor markets. Daikin Industries anchors its North American position through vertical integration into inverter compressor manufacturing. Trane Technologies competes on cold-climate performance ratings that exceed federal minimums.
A residential heat pump is a vapor-compression refrigeration system that transfers thermal energy between indoor and outdoor environments, typically operating at coefficients of performance between two and five depending on ambient temperature and refrigerant type. The equipment serves as the primary heating and cooling appliance in electrified homes, displacing fossil-fuel furnaces through ambient energy extraction. Air source systems dominate installed base owing to lower first cost and minimal site disruption, while ground source configurations command premium positioning where geothermal loop installation proves feasible. Variable speed technology leads new sales growth as utilities and regulators reward load-shaping capabilities that flatten peak demand curves.
The US Department of Energy administers efficiency standards under the Energy Policy and Conservation Act, while the EPA governs refrigerant transitions through phasedown rules under the AIM Act. Canada's Natural Resources Office enforces parallel efficiency regulations through the EnerGuide program, creating a harmonized but not identical compliance landscape. State-level building codes in California, New York, and Washington are mandating heat-pump-ready construction or outright fossil-fuel bans in new housing. Stakeholders must monitor refrigerant supply chain readiness for low-global-warming-potential alternatives and assess whether contractor training investments can outpace code adoption timelines.
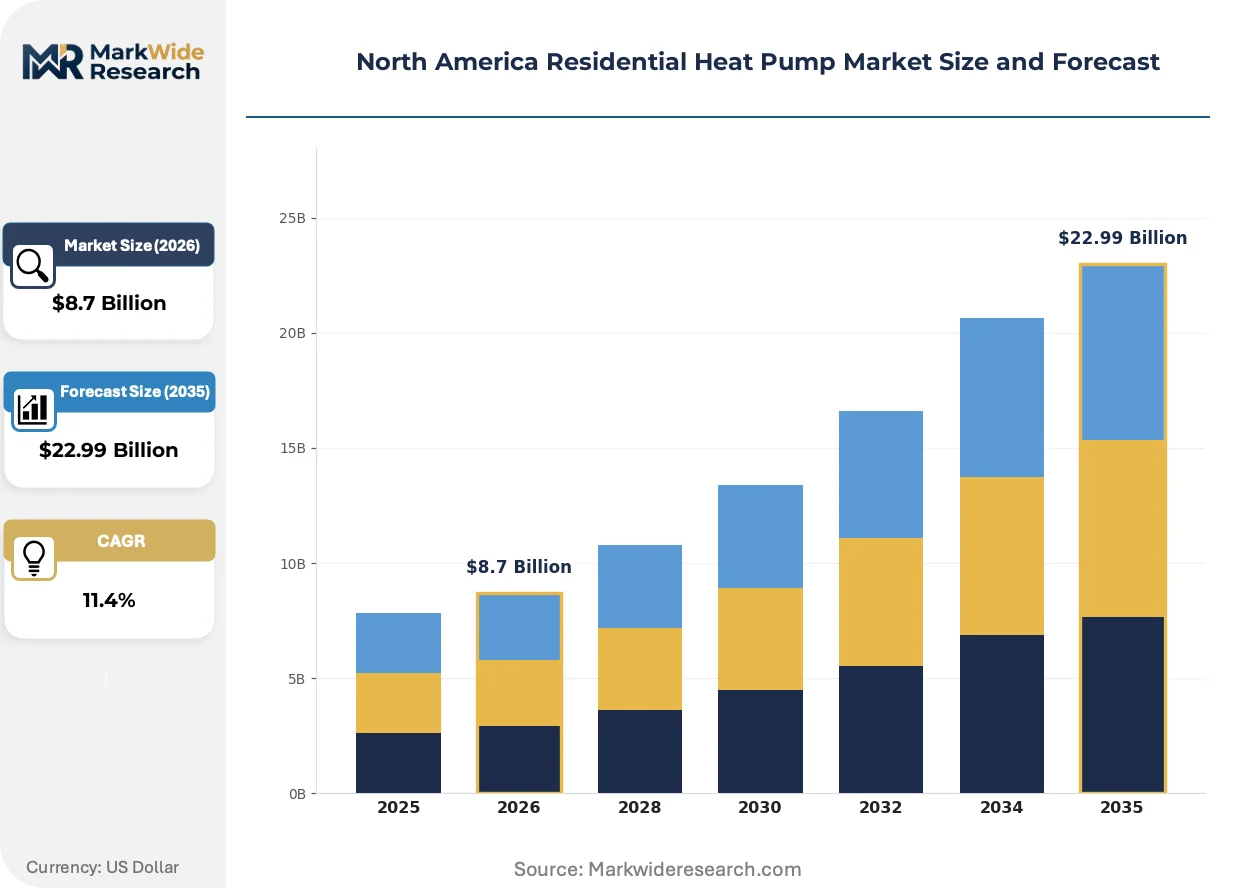
Market Dynamics
Electrification mandates across US states and Canadian provinces are compressing installation timelines while refrigerant phase-down rules under the AIM Act force equipment redesigns before contractor workforces can adapt. This regulatory velocity mismatch creates the defining structural tension in North American heat pump deployment.
Growth Catalysts
- Inflation Reduction Act tax credits:The IRA's rebates and credits are restructuring household economics for electrification retrofits across the United States, accelerating replacement cycles for fossil-fuel furnaces.
- Cold-climate performance standards:Northeastern states are tightening minimum operating temperature requirements, expanding addressable market geography for air-source systems into historically marginal heating zones.
- Single-family electrification:New construction codes in California, New York, and Washington are mandating heat-pump-ready infrastructure or outright fossil-fuel bans, embedding demand into building stock for decades.
Market Restraints
- Copper and aluminum input volatility:Heat exchanger materials face commodity price swings that compress manufacturer margins and destabilize distributor inventory planning.
- Compressor supply concentration:Inverter compressor production clusters in Asian manufacturing hubs, exposing North American OEMs to trans-Pacific logistics disruptions and tariff exposure.
- Cold-climate performance degradation:Air-source coefficient of performance collapses below minus 15 degrees Celsius, requiring supplemental resistance heating that undermines operating cost advantages in Upper Midwest and Prairie provinces.
Strategic Opportunities
- Ground-source geothermal loops:Vertical bore installation techniques are reducing site disruption costs, opening suburban retrofit markets previously blocked by horizontal loop space requirements.
- Variable-speed load shaping:Utilities in Ontario and Pacific Northwest states are designing rate structures that reward thermal battery behavior, creating service revenue streams beyond equipment sales.
- Refrigerant transition timing:Early certification in R-454B and R-32 systems positions distributors to capture replacement demand during the AIM Act phase-down window.
Industry Challenges
- Certified technician scarcity:EPA Section 608 certification programs cannot graduate technicians fast enough to match code adoption timelines in Massachusetts and British Columbia.
- Legacy electrical panel capacity:Pre-1990s single-family housing stock requires service upgrades that add cost and scheduling complexity to heat pump conversions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Residential Heat Pump Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Air Source, Ground Source, Hybrid, Exhaust Air Technology: Variable Speed, Inverter Driven, Dual Fuel, Gas Heat Pump End User: Single-Family Homes, Multi-Family Units, Retirement Communities, New Constructions Distribution Channel: Contractors, Wholesalers, Online Retailers, Direct Sales |
| Companies Covered | Carrier Corporation, Daikin Industries, Trane Technologies, Lennox International, Johnson Controls International, Rheem Manufacturing Company, Mitsubishi Electric Corporation, Emerson Electric Co., Gree Electric Appliances, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Residential Heat Pump Market Emerging Trajectories
Refrigerant chemistry and compressor control algorithms are converging to expand operating envelopes while digital distribution platforms compress information asymmetries between contractors and homeowners. These shifts are reconfiguring how equipment is specified, sold, and serviced.
Variable-refrigerant-flow indoor units are miniaturizing to fit closets and mechanical chases in dense urban housing stock. Multi-family developers in Vancouver and Toronto are specifying these systems to avoid rooftop equipment penalties. The technology is miniaturizing installation footprints enough to penetrate segments previously reserved for PTAC and window units.
The EPA's AIM Act refrigerant phasedown is forcing OEMs to redesign systems around A2L mildly flammable alternatives before technician training infrastructure matures. This regulatory compression is accelerating equipment replacement cycles as older R-410A inventory faces obsolescence. Cold-climate product lines are experiencing the fastest redesign velocity as manufacturers race to maintain performance ratings with lower-global-warming-potential chemistries.
Homeowner specification behavior is fragmenting across digital channels that bypass traditional contractor gatekeepers. Online load calculators and utility rebate portals in California and New York are enabling self-directed equipment research before contractor contact. This channel shift is compressing the traditional sales cycle and forcing distributors to support direct-to-consumer technical consultation models they previously avoided.
North America Residential Heat Pump Market Segmentation
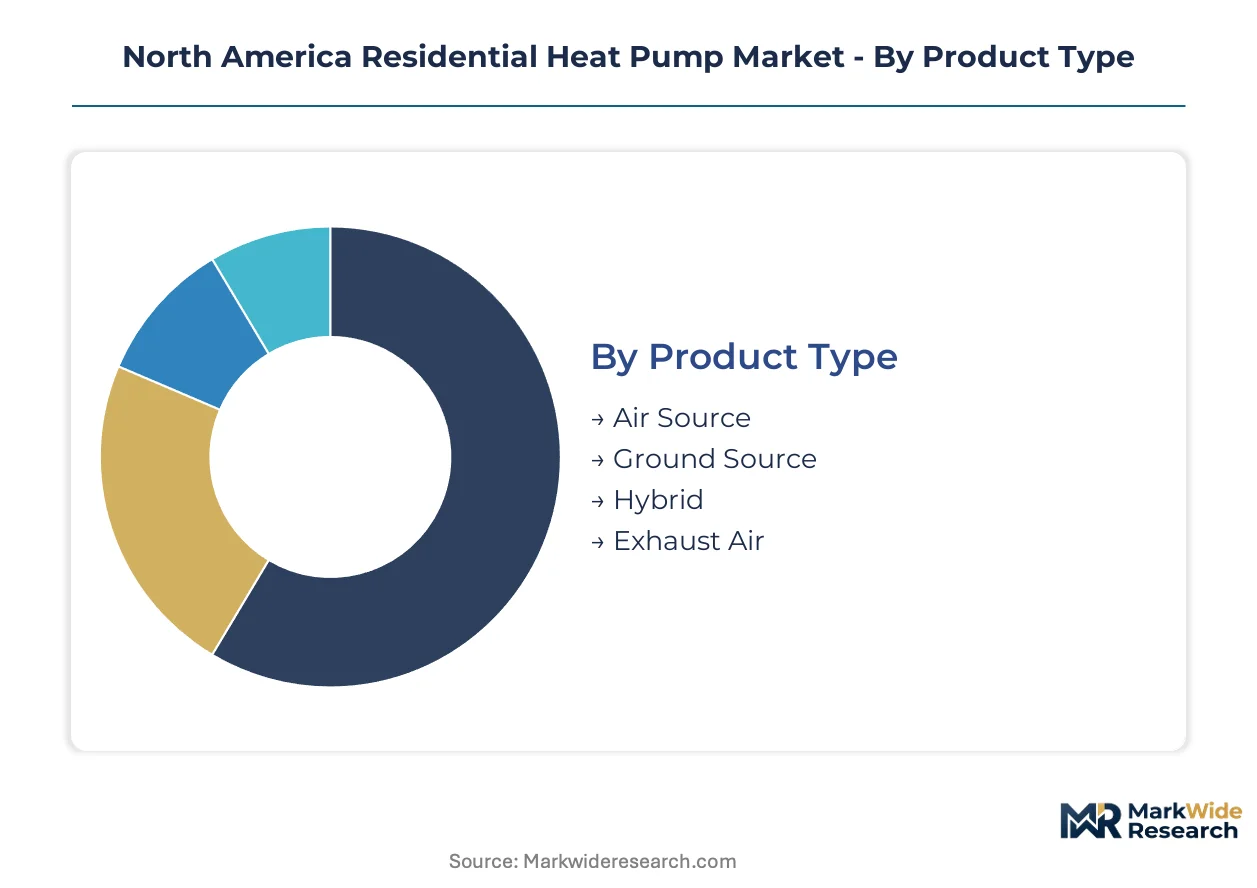
Heat pump market segmentation reveals divergent channel economics and technical requirements across installation contexts. Product type and technology choices cascade through distribution networks with distinct margin profiles and service intensity. Understanding these segment boundaries enables targeted positioning as electrification mandates reshape addressable demand.
Product Type:
Channel flows differ sharply by product type, with air source systems dominating contractor-led retrofits while ground source configurations route through specialized geothermal dealers with engineering capabilities.
- Air Source:Vapor-compression units extract ambient thermal energy from outdoor air through finned-tube heat exchangers and aluminum microchannel coils. Demand concentrates in the Northeast and Pacific Northwest where cold-climate performance standards are tightening and IRA incentives compress payback periods. By volume, Air Source leads. By growth pace, Hybrid is ahead.
- Ground Source:Geothermal heat pumps utilize vertical or horizontal ground loops to access stable subsurface temperatures, achieving coefficients of performance exceeding five even in extreme cold. Suburban retrofit markets in Ontario and Minnesota are expanding as directional drilling reduces loop installation disruption.
- Hybrid:Dual-fuel configurations pair electric heat pumps with fossil-fuel backup, bridging electrification transitions in regions with severe cold snaps. These systems appeal to risk-averse homeowners in Upper Midwest states facing minus 25 degree Celsius design temperatures.
- Exhaust Air:Heat recovery units capture thermal energy from ventilation exhaust streams, serving tight-envelope new construction in British Columbia and Washington state building code jurisdictions.
Cost tiering separates air source mass market penetration from ground source premium positioning where installation complexity limits addressable households.
Technology:
Application context drives technology selection, with variable speed and inverter systems commanding new construction specifications while dual fuel dominates retrofit replacements of aging furnaces.
- Variable Speed:Electronically commutated motors and multi-stage compressors modulate capacity across 25-100% range, enabling load-shaping that utilities in Ontario and California reward through time-of-use rate structures. New construction pipelines in Seattle and Vancouver mandate this capability for grid-interactive water heating.
- Inverter Driven:Variable-frequency drives adjust compressor motor speed to match thermal loads precisely, eliminating on-off cycling losses. Cold-climate product lines from Daikin and Carrier leverage this architecture to maintain heating output at minus 25 degrees Celsius ambient.
- Dual Fuel:Control systems switch between electric heat pump and gas furnace based on outdoor temperature and utility rates. These configurations satisfy building code compliance in jurisdictions where full electrification faces political resistance.
- Gas Heat Pump:Absorption-cycle systems utilize natural gas or propane to drive refrigeration cycles, serving rural properties with limited electrical service capacity across Prairie provinces and Mountain West states.
Volume concentration favors inverter-driven systems in new construction, while retrofit markets show stronger dual fuel attachment rates where electrical panel upgrades prove cost-prohibitive.
End User:
Customer type segmentation aligns with construction cycle timing and procurement authority structures, from homeowner-driven single-family decisions to developer-specified multi-family installations.
- Single-Family Homes:Detached and semi-detached dwellings represent the core retrofit opportunity as IRA tax credits and state rebates restructure replacement economics. Massachusetts and New York programs target this segment with point-of-sale rebates up to several thousand dollars.
- Multi-Family Units:Apartment and condominium buildings require centralized or individual mini-split configurations depending on ownership structure. Developers in Toronto and Vancouver are specifying variable-refrigerant-flow systems to avoid rooftop equipment penalties.
- Retirement Communities:Age-restricted housing with predictable occupancy patterns suits thermal storage and demand response programs. Arizona and Florida operators are piloting utility-controlled thermal batteries.
- New Constructions:California, New York, and Washington building codes are mandating heat-pump-ready infrastructure or fossil-fuel bans, embedding demand into building stock for decades.
Maturity varies across end user segments, with new construction showing highest technology adoption rates while single-family retrofits face legacy electrical infrastructure constraints.
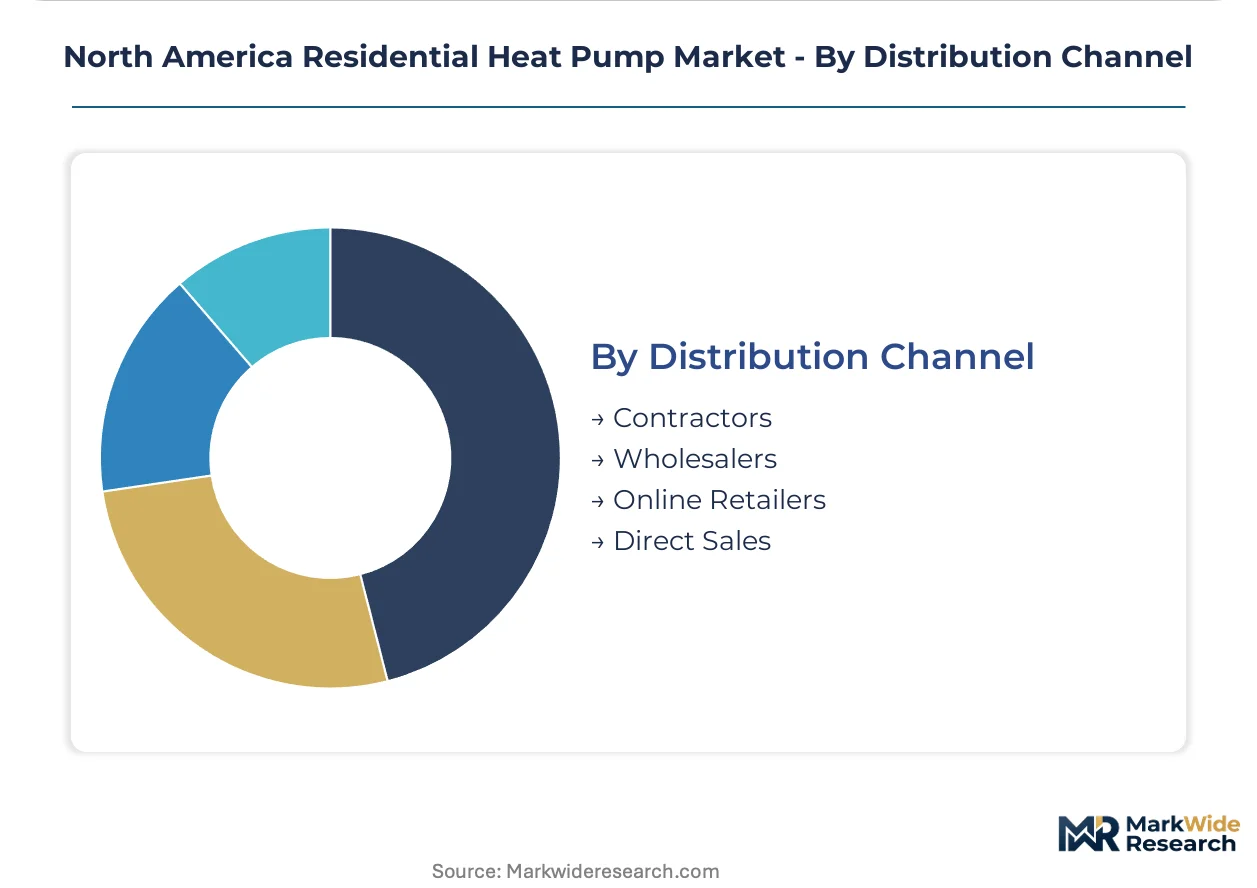
Distribution Channel:
Supply concentration patterns shape channel power, with compressor manufacturing clustering in Asian hubs while final assembly and distribution maintain regional footprints.
- Contractors:EPA Section 608 certified HVAC installers dominate equipment specification and installation, capturing margin through labor and markup. Technician scarcity in Ontario and the Northeast is extending lead times and raising bid prices.
- Wholesalers:Regional distributors like Watsco and Ferguson maintain inventory positions and credit relationships with contractor bases. These intermediaries are investing in R-454B refrigerant training ahead of AIM Act phase-down deadlines.
- Online Retailers:Digital platforms are enabling homeowner self-education and equipment research before contractor contact, compressing traditional sales cycles. California and New York utility rebate portals accelerate this channel shift.
- Direct Sales:Manufacturer-direct channels serve large multi-family developers and institutional buyers with volume pricing and extended warranty terms. Daikin and Carrier leverage factory-trained dealer networks for service coverage.
Margin structures favor contractor channels for complex installations, while online and direct channels gain traction in standardized replacement scenarios.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States and Canada deploy residential heat pumps at divergent intensities, with American adoption concentrated in retrofit replacements and Canadian deployment weighted toward new construction compliance. Mexico represents nascent electrification infrastructure with minimal policy scaffolding.
United States
Single-family retrofits dominate volume as Inflation Reduction Act tax credits restructure household economics. The EPA's AIM Act refrigerant phasedown is compressing equipment redesign timelines ahead of contractor training readiness. Northeastern states including Massachusetts and New York are tightening cold-climate performance standards that expand addressable market geography.
Canada
New construction codes in British Columbia and Ontario mandate heat-pump-ready infrastructure, embedding demand into building stock. Natural Resources Canada enforces parallel efficiency regulations through the EnerGuide program. Ontario faces acute certified technician scarcity that extends installation lead times and raises contractor bids.
Mexico
Electrification infrastructure remains underdeveloped with minimal federal heat pump incentives or building code mandates. The national utility CFE has not deployed time-of-use rate structures that reward load-shaping behavior. Northern border states show scattered adoption driven by cross-border contractor capacity rather than domestic policy.
North America Residential Heat Pump Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with factory-trained dealer networks separating premium positioning from price-driven commoditization. Carrier Corporation and Daikin Industries anchor the upper tier through captive distribution control, while regional assemblers compete on installation speed. Two dominant competitive moves are emerging: backward integration into inverter compressor manufacturing to secure supply, and pre-positioning R-454B refrigerant certification ahead of EPA phase-down deadlines.
Among North American HVAC incumbents, Carrier Corporation exemplifies the integrated leader archetype through its factory-trained dealer network, while Daikin Industries occupies a position as a vertically structured Japanese multinational with North American assembly presence. Trane Technologies represents the cold-climate performance specialist tier, competing on ratings that exceed federal minimums.
| Leading Market Players |
|---|
| Carrier Corporation |
| Daikin Industries |
| Trane Technologies |
| Lennox International |
| Johnson Controls International |
| Rheem Manufacturing Company |
| Mitsubishi Electric Corporation |
| Emerson Electric Co. |
| Gree Electric Appliances |
| Others |
Supply Flow & Price Mechanics
EPA Section 608 certification requirements gate both contractor qualification and installation pricing tiers simultaneously, compressing margins for uncertified installers while rewarding factory-trained dealer networks with premium positioning. The Inflation Reduction Act's point-of-sale rebates restructure household willingness-to-pay, creating divergent effective price floors across Massachusetts, New York, and federal incentive zones.
Pricing Analysis
Project-based contracting dominates residential heat pump transactions, with bids bundling equipment, labor, and electrical upgrades into single-price proposals. Three-tier pricing structure across premium cold-climate systems, standard mid-efficiency units, and economy single-stage equipment reflects certification grade and after-sales service bundling. Cost compression in the economy tier is intensifying because aluminum microchannel coil volatility feeds through to distributor inventory carrying costs. Single-family retrofits in pre-1990s housing stock show highest price sensitivity due to mandatory electrical panel upgrades, while new construction developers exhibit lowest sensitivity through volume procurement.
Supply Chain Analysis
Port congestion across the trans-Pacific trade lane elevates inbound logistics costs for inverter compressors sourced from Japanese and South Korean manufacturing hubs. North American OEMs draw from Thailand, China, and Mexico for aluminum fin stock, copper tubing, and electronic control modules. Single-source vulnerability concentrates in variable-frequency drive production clustered in East Asian facilities. Distribution runs through regional wholesalers like Watsco and Ferguson who maintain contractor credit relationships and R-454B refrigerant training programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The acute shortage of EPA-certified technicians capable of handling A2L refrigerant transitions constitutes the binding constraint on market expansion, privileging players with captive training infrastructure over price-competitive assemblers lacking service depth.
For Market Incumbents: Fortify factory-trained dealer networks against independent contractor attrition by embedding R-454B certification into warranty eligibility requirements. Deepen backward integration into inverter compressor sourcing to offset trans-Pacific logistics exposure from Japanese and South Korean supply clusters. Cold-climate performance ratings exceeding federal minimums defend positioning against emerging low-cost entrants. For New Entrants and Emerging Players: Anchor in ground-source geothermal loop installation services where directional drilling techniques reduce site disruption costs and specialized engineering capabilities limit price competition. Target suburban retrofit markets in Ontario and Minnesota where horizontal loop space constraints previously blocked adoption. Partner with electrical contractors on service upgrade bundling to bypass established HVAC distributor relationships. For Investors and Strategic Acquirers: The EPA AIM Act refrigerant phasedown reshapes the acquisition landscape toward early R-454B certified distributors with captive technician training pipelines. Long-term viability hinges on installation capacity scaling faster than electrification mandate adoption curves. Monitor Massachusetts and British Columbia code enforcement timelines as the critical signal for technician demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Technician Certification Pipeline Investment | EPA Section 608 and A2L readiness programs secure installation capacity ahead of code adoption in Massachusetts and British Columbia. |
| Backward Integration into Inverter Compressor Sourcing | Captive supply from Thai or Mexican assembly reduces tariff exposure and trans-Pacific logistics vulnerability for North American OEMs. |
| R-454B Refrigerant Pre-Positioning | Early distributor certification captures replacement demand during the AIM Act phase-down window before competitor inventory turnover. |
| Ground-Source Loop Installation Capability | Vertical bore expertise opens suburban retrofit markets in Ontario and Minnesota previously blocked by horizontal loop space constraints. |
| Utility Rate Structure Partnership | Time-of-use and demand-response program alignment with Ontario IESO or California IOUs creates service revenue beyond equipment margins. |
Methodological Framework
Operator-level perspectives from HVAC contractors, regional distributor procurement managers, utility demand-side management officers, and EPA certification program administrators anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation through DOE efficiency standard filings, EPA AIM Act rulemaking dockets, Natural Resources Canada EnerGuide databases, and utility rebate program disclosures. Bottom-up equipment shipment analysis triangulated against top-down construction permit and electrification mandate adoption curves.
Sensitivity analysis tested forecast robustness across commodity price volatility scenarios for copper and aluminum inputs, trans-Pacific logistics disruption severity, and technician graduation rate variations. Segmentation modeling spanned product type, technology architecture, end-user construction cycle timing, and distribution channel structure. CAGRs derived from installed base turnover dynamics, new construction code compliance trajectories, and IRA incentive program participation elasticity. Cold-climate performance standard tightening velocity and refrigerant transition timing constituted industry-specific forecast inputs.
Material uncertainties — commodity price spikes, certification program graduation shortfalls, and electrical grid upgrade delays — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding policy continuity and supply chain normalization. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
Ventilation Equipment Market
HVAC Equipment
Air Conditioner Quilt Market
HVAC Equipment
North America Heat Exchanger Market
HVAC Equipment
India Chillers Market
HVAC Equipment
Industrial Condensing Units Market
HVAC Equipment
Water Chiller Market
HVAC Equipment
Canada HVAC Equipment Market
HVAC Equipment
Global Split Systems Market
HVAC Equipment
Tubular Heater Market
HVAC Equipment
Fume Extraction System Market
HVAC Equipment
Warm Air Furnaces Market
HVAC Equipment
China Commercial HVAC Market
HVAC Equipment
Wall Fan Coil Market
HVAC Equipment
Global Modular Chillers Market
HVAC Equipment
Industrial Insulation Testers Market
HVAC Equipment
Global Fan Coil Unit Market