
 Ventilation Equipment Market | 2026-2036
Ventilation Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Ventilation Equipment Market Outlook
The capital-intensity divergence between foundry-dependent and modular-assembly players is reorganizing competitive tiers in the ventilation equipment sector. Daikin Industries leverages captive compressor manufacturing to sustain margin control across heat recovery product lines. Johnson Controls anchors its position through building-automation integration, while Greenheck Fan Corporation specializes in heavy-duty industrial exhaust systems where custom engineering commands premium positioning.
Ventilation equipment encompasses mechanical systems designed to control indoor air quality through air exchange, filtration, and thermal conditioning, typically operating at pressures between 0.5 and 2.5 inches water gauge in commercial applications. These systems serve critical functions in moisture control, contaminant dilution, and thermal comfort across enclosed structures. Heat recovery ventilators capture the fastest expansion trajectory as energy codes tighten, while ducted systems retain the largest installed base despite longer replacement cycles. Commercial buildings generate the deepest margin pools due to specification-driven procurement and lifecycle service contracts, whereas residential homes drive unit volume through new construction and retrofit programs.
The US Environmental Protection Agency and Department of Energy jointly shape demand through efficiency mandates and ENERGY STAR qualification thresholds, while the EU F-Gas Regulation and Ecodesign Directive progressively restrict refrigerant choices and fan power limits. China's GB standards and dual carbon goals impose parallel efficiency floors on imported and domestic equipment alike. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory and certification gaps.
Market Dynamics
The ventilation equipment sector is undergoing a structural compression as building energy codes tighten across developed economies, forcing equipment replacement cycles to accelerate while simultaneously raising technical barriers for market entry.
Growth Catalysts
- EU F-Gas Regulation:Phasedown schedules for hydrofluorocarbon refrigerants are compelling commercial building owners to replace aging rooftop units with compliant heat recovery systems ahead of failure.
- Healthcare infrastructure:Hospital renovation programs in Germany and France are specifying demand-controlled ventilation with HEPA filtration to meet infection control protocols.
- Electrification mandates:Natural gas heating bans in new construction across multiple jurisdictions are redirecting capital toward all-electric heat pump ventilation packages.
Market Restraints
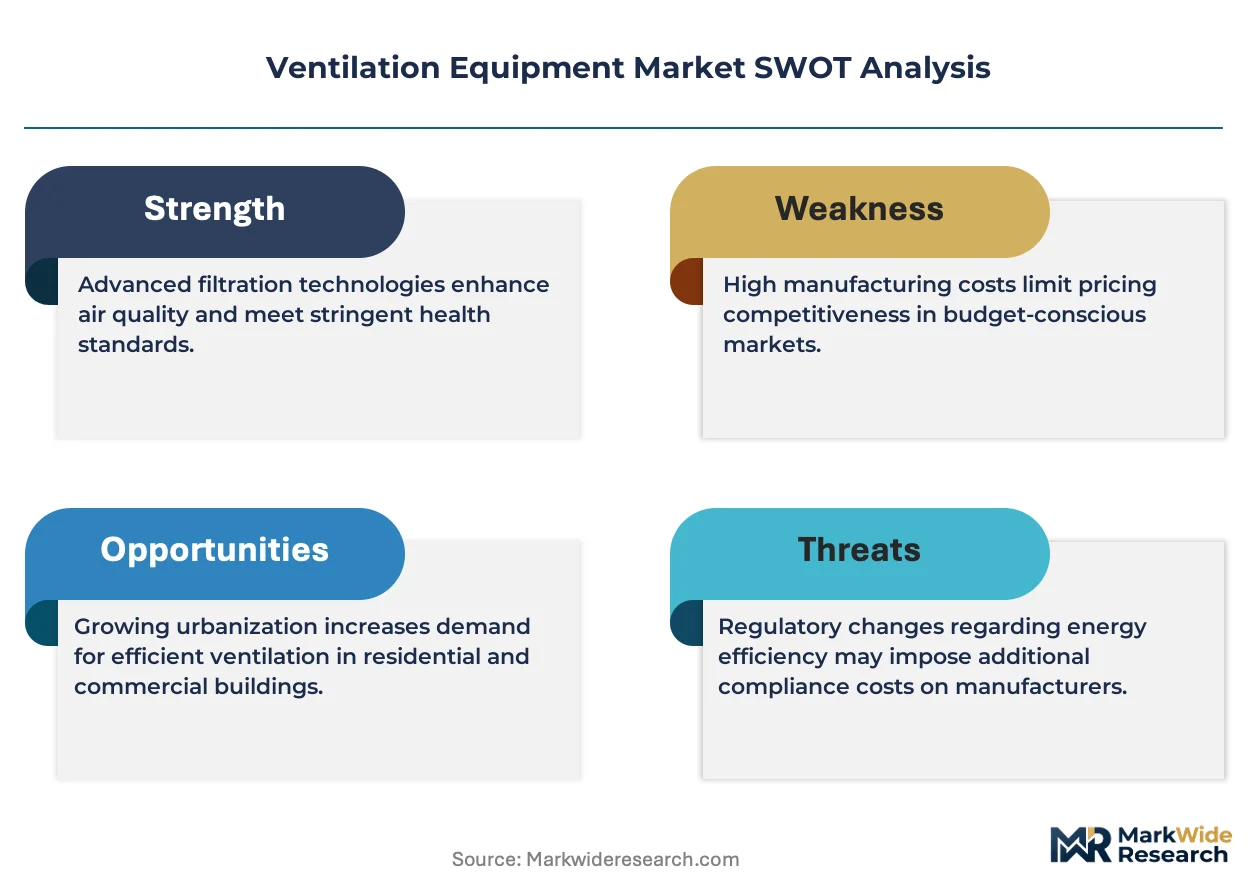
- Copper and aluminum price volatility:Heat exchanger manufacturing faces margin pressure from commodity swings, with coil fabrication representing 35-40% of variable production costs.
- Foundry capacity concentration:Precision casting for high-efficiency fan housings depends on a limited supplier base in Germany and Japan, creating bottleneck risk during demand surges.
- Refrigerant transition friction:The shift from R-410A to lower-GWP alternatives requires equipment redesign and technician retraining, slowing replacement timelines.
Strategic Opportunities
- Data center cooling:Hyperscale facilities are adopting liquid-cooled heat recovery ventilation to capture waste heat for adjacent district heating networks.
- Retrofit-as-a-service:Energy service companies are bundling ventilation upgrades with performance guarantees, reducing upfront capital barriers for building owners.
- GB standards alignment:China's efficiency certification requirements for imported equipment create first-mover advantage for manufacturers achieving dual EU-China compliance.
Industry Challenges
- Controls integration complexity:BACnet and Modbus protocol fragmentation between HVAC and building automation systems extends commissioning timelines and escalates field service costs.
- Certification timeline compression:The EU Ecodesign Directive's tightening fan power limits require retesting entire product lines, straining engineering resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ventilation Equipment Market |
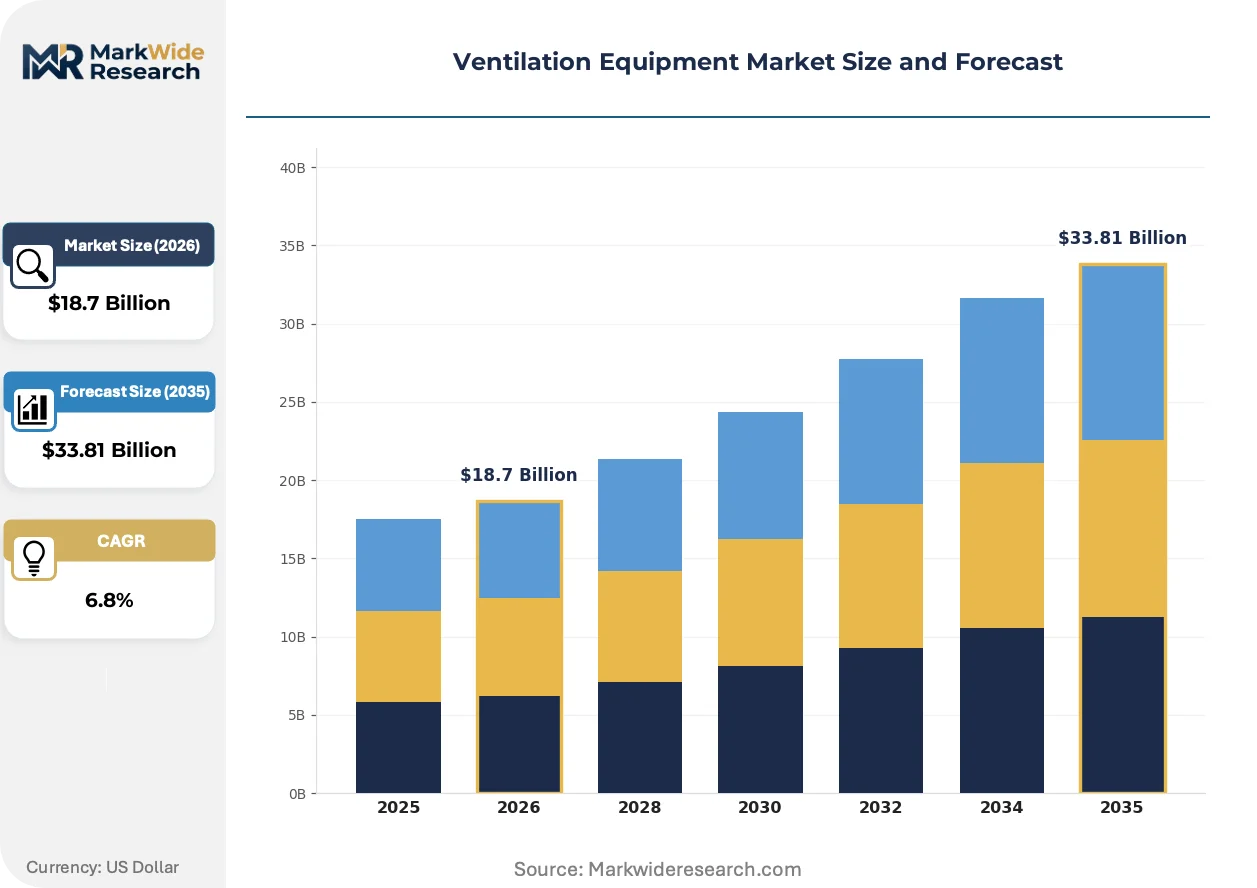
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Exhaust Fans, Air Purifiers, Ducted Systems, Heat Recovery Ventilators End User: Commercial Buildings, Residential Homes, Industrial Facilities, Hospitals Technology: Natural Ventilation, Mechanical Ventilation, Hybrid Systems, Energy Recovery Installation Type: Ceiling-Mounted, Wall-Mounted, Portable, Integrated |
| Companies Covered | Daikin Industries, Johnson Controls, Honeywell International, Lennox International, Trane Technologies, Carrier Global, Systemair, Greenheck Fan Corporation, Mitsubishi Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ventilation Equipment Market Strategic Shifts
Equipment intelligence and thermal recovery efficiency are converging to redefine competitive differentiation, with software-enabled performance optimization now matching hardware specifications as a procurement criterion.
Heat recovery ventilator technology is bifurcating the market between enthalpy wheel and fixed-plate exchanger architectures. Enthalpy wheels dominate humid climate installations for latent heat capture, while fixed-plate designs gain share in cold-dry regions for frost resistance and reduced maintenance. This technical divergence is compressing mid-range product positioning and forcing manufacturers to commit to single-architecture specialization.
The EU Green Deal's building renovation targets are mandating minimum heat recovery efficiency thresholds in commercial retrofits. Member states must transpose these requirements into national building codes by fixed deadlines, triggering specification updates. Germany's federal building energy ordinance is tightening fastest, driving demand for certified equipment with test data traceable to accredited laboratories.
Building owners are unbundling lifecycle service contracts from initial equipment purchase, separating maintenance from capital expenditure decisions. This procurement fragmentation is compressing manufacturer margins on hardware while expanding recurring revenue pools for service specialists. The shift is most visible in Nordic countries where energy performance contracting has mature legal frameworks.
Ventilation Equipment Market Segmentation
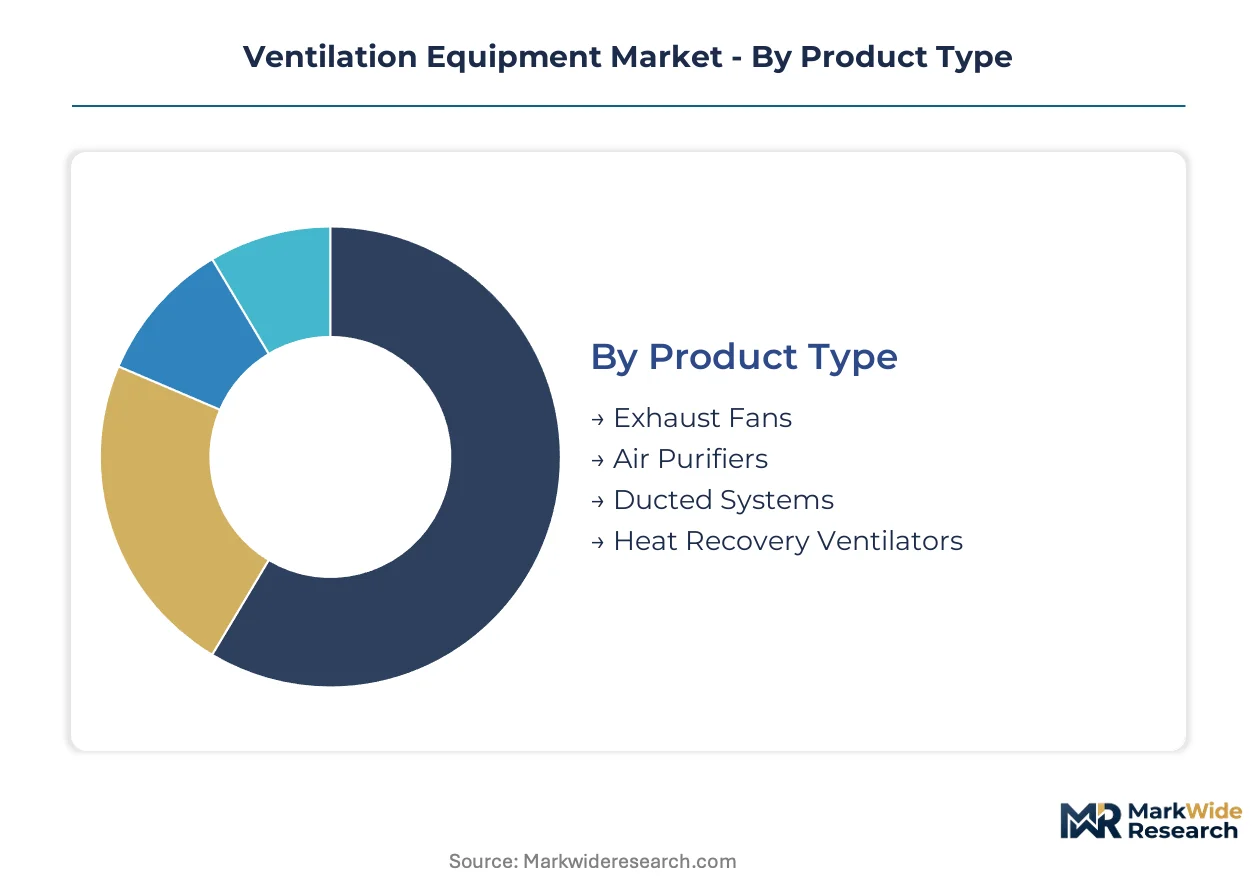
Segmentation in ventilation equipment reveals distinct procurement patterns between specification-driven commercial retrofits and price-sensitive residential new construction. Understanding these divides allows manufacturers to align product development with margin architecture rather than chasing volume indiscriminately.
Product Type:
Heat recovery ventilators face the strongest substitution pressure from simpler exhaust-only systems in cost-constrained residential segments, while commercial codes increasingly mandate their inclusion.
- Exhaust Fans:Basic air extraction devices operating at low static pressure for moisture and odor control. Demand concentrates in residential kitchens and bathrooms across Spain and Italy where natural ventilation traditions persist despite tightening codes.
- Air Purifiers:Standalone filtration units with HEPA or activated carbon stages targeting particulate and VOC reduction. Post-pandemic healthcare specifications in France and Germany now integrate these into centralized ventilation rather than treating them as peripheral equipment.
- Ducted Systems:Networked distribution infrastructure with terminal units and central air handling. Commercial building stock in Germany retains the largest installed base, though replacement cycles extend to 20-25 years due to infrastructure embeddedness.
- Heat Recovery Ventilators:Enthalpy wheel or fixed-plate exchangers capturing thermal energy from exhaust air streams. The EU Ecodesign Directive's tightening efficiency thresholds are accelerating displacement of non-recuperative systems in Nordic and German commercial retrofits.
Ducted systems anchor the volume base while heat recovery ventilators gain share at the steepest rate.
End User:
Cost tier separation dominates this dimension, with hospitals and data centers accepting 3-4x hardware premiums for redundancy and filtration performance that residential builders reject.
- Commercial Buildings:Offices, retail, and hospitality requiring demand-controlled ventilation with BACnet integration. Germany's federal building energy ordinance is forcing equipment replacement ahead of failure in structures exceeding specific energy consumption thresholds.
- Residential Homes:Single-family and multi-family units where builder-grade specifications dominate new construction. France's RE2020 environmental regulation is mandating mechanical ventilation with heat recovery in all new residential builds, compressing natural ventilation's remaining share.
- Industrial Facilities:Manufacturing and process environments with fume extraction and explosion-proof requirements. Chemical processing clusters in Belgium's Port of Antwerp generate sustained demand for corrosion-resistant exhaust systems.
- Hospitals:Infection-controlled environments requiring HEPA filtration, pressure cascades, and redundancy. Renovation programs at Paris and Berlin university hospitals are specifying room-level ventilation monitoring with centralized fault alerting.
Residential homes anchor the volume base while hospitals expand most quickly on a value-per-unit basis.
Technology:
Application context determines technology selection more than performance optimization, with natural ventilation persisting in mild climates despite mechanical alternatives achieving superior air quality outcomes.
- Natural Ventilation:Buoyancy and wind-driven air exchange without mechanical assistance. Mediterranean commercial architecture in Spain and southern France retains this approach where code minimums still permit operable window strategies.
- Mechanical Ventilation:Fan-forced air distribution with filtration and conditioning stages. Germany's building codes now effectively mandate mechanical systems in all new commercial construction, eliminating natural ventilation from permitted compliance paths.
- Hybrid Systems:Switching between natural and mechanical modes based on outdoor conditions and occupancy. Dutch office developments are pioneering these configurations to minimize fan energy while maintaining indoor air quality during peak occupancy.
- Energy Recovery:Sensible and latent heat exchange between exhaust and supply air streams. The EU F-Gas Regulation's refrigerant restrictions are redirecting specification toward these non-refrigerant thermal recovery approaches in rooftop unit replacements.
Mechanical ventilation anchors the volume base while energy recovery climbs the fastest as building codes tighten.
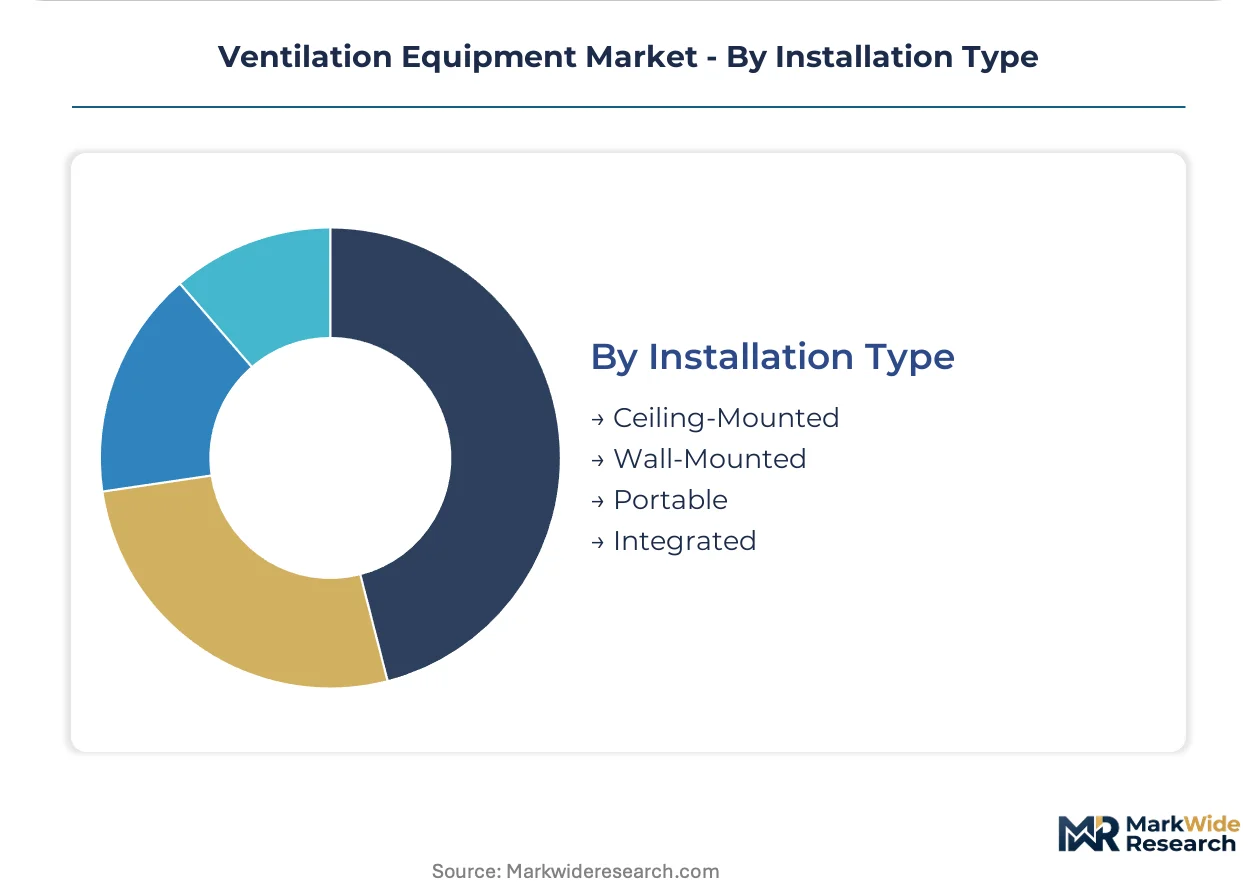
Installation Type:
Supply concentration differs sharply between integrated systems requiring coordinated trades and portable units distributed through retail channels with minimal installation support.
- Ceiling-Mounted:Recessed or surface-mounted units integrated with suspended ceiling grids. Commercial fit-outs in Frankfurt and Munich specify these for space efficiency and aesthetic integration with lighting systems.
- Wall-Mounted:Through-wall or surface-mounted units common in residential and light commercial retrofits. French multi-family renovation programs favor these for minimal envelope disruption and resident-in-place installation.
- Portable:Plug-in units requiring no permanent installation. Residential consumer markets in Italy and Spain absorb these as interim solutions where permanent ventilation upgrades face capital constraints.
- Integrated:Factory-assembled packages combining ventilation with heating, cooling, and controls. German industrial construction is standardizing on these for commissioning speed and single-point warranty coverage.
Ceiling-mounted systems anchor the volume base while integrated packages gain share at the steepest rate in new construction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German commercial retrofits command 40% pricing premiums over Italian residential equivalents, reflecting code stringency divergence rather than manufacturing cost differences.
Germany
Federal building energy ordinance revisions are accelerating rooftop unit replacements in Frankfurt and Munich office districts. The EU F-Gas Regulation's phasedown schedules force refrigerant transitions ahead of equipment failure. Bavaria's industrial corridor around Nuremberg concentrates heat recovery ventilator demand from automotive supplier facilities undergoing deep renovation.
France
RE2020 environmental regulations now mandate mechanical ventilation with heat recovery in all new residential construction. ANSM infection control protocols drive hospital renovation specifications in Paris university hospitals. The Île-de-France region's commercial building stock generates sustained demand for demand-controlled ventilation with BACnet integration.
United States
EPA and DOJ joint efficiency mandates reshape procurement criteria for commercial building retrofits in Chicago and New York. ENERGY STAR qualification thresholds filter specification lists for federal building upgrades. Texas data center clusters around Dallas-Fort Worth are adopting liquid-cooled heat recovery systems for waste heat capture.
China
GB standards and dual carbon goals impose parallel efficiency floors on imported and domestic ventilation equipment. Yangtze River Delta manufacturing hubs in Shanghai and Suzhou drive specification-grade demand from semiconductor fabrication facilities. NMPA-aligned certification requirements create compliance barriers for non-domestic suppliers.
Japan
METI efficiency standards and JIS certification requirements structure premium-tier procurement in Tokyo commercial districts. Osaka-Kansai industrial corridors generate demand for corrosion-resistant exhaust systems from chemical processing clusters. Precision casting supply constraints from Nagoya-area foundries bottleneck high-efficiency fan housing production during demand surges.
Ventilation Equipment Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, with captive manufacturing assets separating margin-sustainable positions from assembly-dependent competitors. The market structures around three tiers: integrated system houses with building automation portfolios, component-specialized fabricators with foundry relationships, and modular-assembly distributors serving price-sensitive residential segments. Scale advantages concentrate in heat recovery product lines where test data traceability to accredited laboratories commands specification access. Competitive moves center on backward integration into compressor and heat exchanger production, plus geographic licensing arrangements to bypass certification timeline compression.
Within the integrated system tier, Daikin Industries and Johnson Controls occupy positions where building automation integration and captive compressor manufacturing anchor margin control. Greenheck Fan Corporation exemplifies the specialized fabricator archetype, with heavy-duty industrial exhaust positioning that commands premium engineering fees. These three companies represent the structural divergence between specification-driven commercial retrofits and price-sensitive volume segments.
| Leading Market Players |
|---|
| Daikin Industries |
| Johnson Controls |
| Honeywell International |
| Lennox International |
| Trane Technologies |
| Carrier Global |
| Systemair |
| Greenheck Fan Corporation |
| Mitsubishi Electric |
| Others |
Value Chain & Pricing Dynamics
Foundry utilization rates in Germany and Japan determine minimum viable production thresholds for high-efficiency fan housings, concentrating supply-side leverage among precision casting specialists who simultaneously set price floors for specification-grade equipment and squeeze modular assemblers competing on standard product lines.
Pricing Analysis
Configured-to-order pricing commands 40-60% premiums over standard catalog pricing in commercial retrofit segments where building codes mandate certified test data traceability. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade divergence and after-sales bundling intensity. Cost compression in residential new construction intensifies as builder-grade procurement consolidates volume around fewer suppliers. Hospitals and data centers exhibit lowest price sensitivity, accepting hardware premiums for redundancy guarantees and HEPA filtration performance that residential builders reject outright.
Supply Chain Analysis
Germany and Japan anchor precision casting capacity for high-efficiency fan housings, while China dominates coil fabrication and aluminum extrusion for heat exchanger cores. Copper and aluminum draw from Chilean mining clusters and Australian smelters, with coil fabrication representing the largest variable cost component. Single-source vulnerability concentrates in Nagoya-area foundries where capacity constraints bottleneck production during demand surges. Distribution runs through specification-driven engineering consultants in commercial segments and HVAC wholesale distributors in residential replacement markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of accredited laboratory test data traceability separates specification-accessible suppliers from price-commoditized competitors, with EU Ecodesign Directive compliance timelines compressing the window for capability acquisition.
For Market Incumbents: Consolidate backward integration into compressor and heat exchanger production to defend margin control against modular-assembly entrants. Lock in foundry capacity agreements in Germany and Japan before precision casting bottlenecks intensify. Prioritize certification investment for dual EU-China compliance to capture first-mover positioning in Yangtze River Delta manufacturing hubs. For New Entrants and Emerging Players: Certification fast-track through ENERGY STAR qualification offers specification access in US federal building upgrade programs. Target French residential new construction under RE2020 mandates where mechanical ventilation with heat recovery is newly compulsory and incumbent capacity lags demand ramp. Pursue retrofit-as-a-service bundling to bypass upfront capital barriers that favor established financing relationships. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors component-specialized fabricators with captive foundry relationships over assembly-dependent distributors. Five-to-ten year viability hinges on heat recovery efficiency threshold compliance rather than hardware cost minimization. Watch EU member state transposition deadlines for building renovation targets as demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Heat Exchanger Production | Captive coil fabrication insulates margins from copper and aluminum price volatility affecting 35-40% of variable costs. |
| Dual EU-China Certification Investment | GB standards alignment creates specification access in Shanghai and Suzhou semiconductor fabrication facility upgrades. |
| Foundry Capacity Lock-in Agreements | Precision casting commitments in Bavaria and Nagoya secure supply continuity during EU F-Gas Regulation-driven replacement surges. |
| Retrofit-as-a-Service Platform Launch | Performance contracting bundles reduce upfront capital barriers in Nordic markets with mature energy service legal frameworks. |
| Building Automation Integration Partnership | BACnet protocol harmonization with Johnson Controls and Daikin systems shortens commissioning timelines in Frankfurt commercial fit-outs. |
Study Parameters
Cross-validation between primary interviews with plant engineers, OEM procurement teams, aftermarket service heads, and building automation integration specialists anchors the qualitative findings, supplemented by secondary validation against SEC 10-K filings, EU Ecodesign Directive compliance databases, customs and trade data, and hospital procurement contract registries. Bottom-up equipment shipment analysis triangulates against top-down construction spending allocation models.
Sensitivity analysis around copper and aluminum price trajectories, foundry capacity utilization thresholds, and EU member state transposition timeline variance shapes the analytical framework across the analysis window. Segmentation dimensions span product architecture, end-use application, technology type, and installation configuration, with CAGRs derived from replacement cycle acceleration rates and code mandate enforcement intensity. Heat recovery efficiency threshold compliance and refrigerant transition friction serve as industry-specific forecast inputs.
Underlying assumptions cover regulatory enforcement continuity, commodity price band stability, and foundry capacity expansion schedules, with deviation risk concentrated in EU F-Gas Regulation phasedown acceleration and China GB standards alignment timing. Recalibration cycles align with material shifts in building code revision announcements and accredited laboratory capacity expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
HVAC Air Quality Monitoring Market
HVAC Equipment
Steam Boiler Systems Market
HVAC Equipment
Global Snow Making System Market
HVAC Equipment
Global Industrial Fans and Blowers Market
HVAC Equipment
United States Air Conditioning Equipment Market
HVAC Equipment
HVAC Services Market
HVAC Equipment
HVAC Louvers Market
HVAC Equipment
Europe HVAC Market
HVAC Equipment
Reciprocating Chiller Market
HVAC Equipment
Hydro Chillers Market
HVAC Equipment
Heating Equipment Market
HVAC Equipment
Global Heat Exchangers Market
HVAC Equipment
Electric Underfloor Heating Market
HVAC Equipment
Europe Heating Radiator Market
HVAC Equipment
Blowers Market
HVAC Equipment
Hybrid Air Conditioner Market