
 US Residential Heat Pump Market | 2026-2036
US Residential Heat Pump Market Size, Share, and Industry Trends Forecast 2026-2036
US Residential Heat Pump Market Analysis
R-410A refrigerant is repositioning product economics as manufacturers phase down this hydrofluorocarbon ahead of EPA mandates under the AIM Act, forcing redesigns around lower-global-warming-potential alternatives like R-32 and R-454B. Rheem leverages its water heating heritage to cross-sell integrated heat pump water heater and HVAC packages through contractor channels. Carrier anchors its position through extensive distributor relationships that control shelf space in the replacement segment. Daikin differentiates via inverter-driven compressor technology developed for its mini-split platforms.
A residential heat pump is a vapor-compression refrigeration system engineered to transfer thermal energy between indoor and outdoor environments, typically operating with coefficient of performance ratings between two and five depending on ambient temperature conditions. The device serves the primary commercial purpose of space conditioning and domestic water heating using electricity rather than on-site fossil fuel combustion. Air source systems dominate installed base owing to lower loop installation costs, while ground source configurations command premium pricing in new construction where horizontal or vertical borefield work can be coordinated with foundation excavation. Inverter technology leads growth trajectories as variable-speed compressors deliver part-load efficiency gains that traditional single-stage units cannot match.
EPA refrigerant transition rules under the AIM Act, DOE minimum efficiency standards enforced through the Appliance and Equipment Standards Program, and state-level building electrification codes in California, New York, and Washington shape product design cycles and market access timelines. The Inflation Reduction Act's 25C tax credits and HOMES rebate programs direct consumer purchasing toward cold-climate-qualified models above specified SEER2 and HSPF2 thresholds. Stakeholders must monitor state utility commission rate case outcomes that determine whether time-of-use electricity pricing rewards or penalizes heat pump operation patterns.
Market Dynamics
The US residential heat pump market is being fundamentally restructured by the EPA's phasedown of R-410A refrigerant under the AIM Act, forcing manufacturers to redesign compressor systems around lower-GWP alternatives while managing inventory transitions across distributor networks.
Growth Catalysts
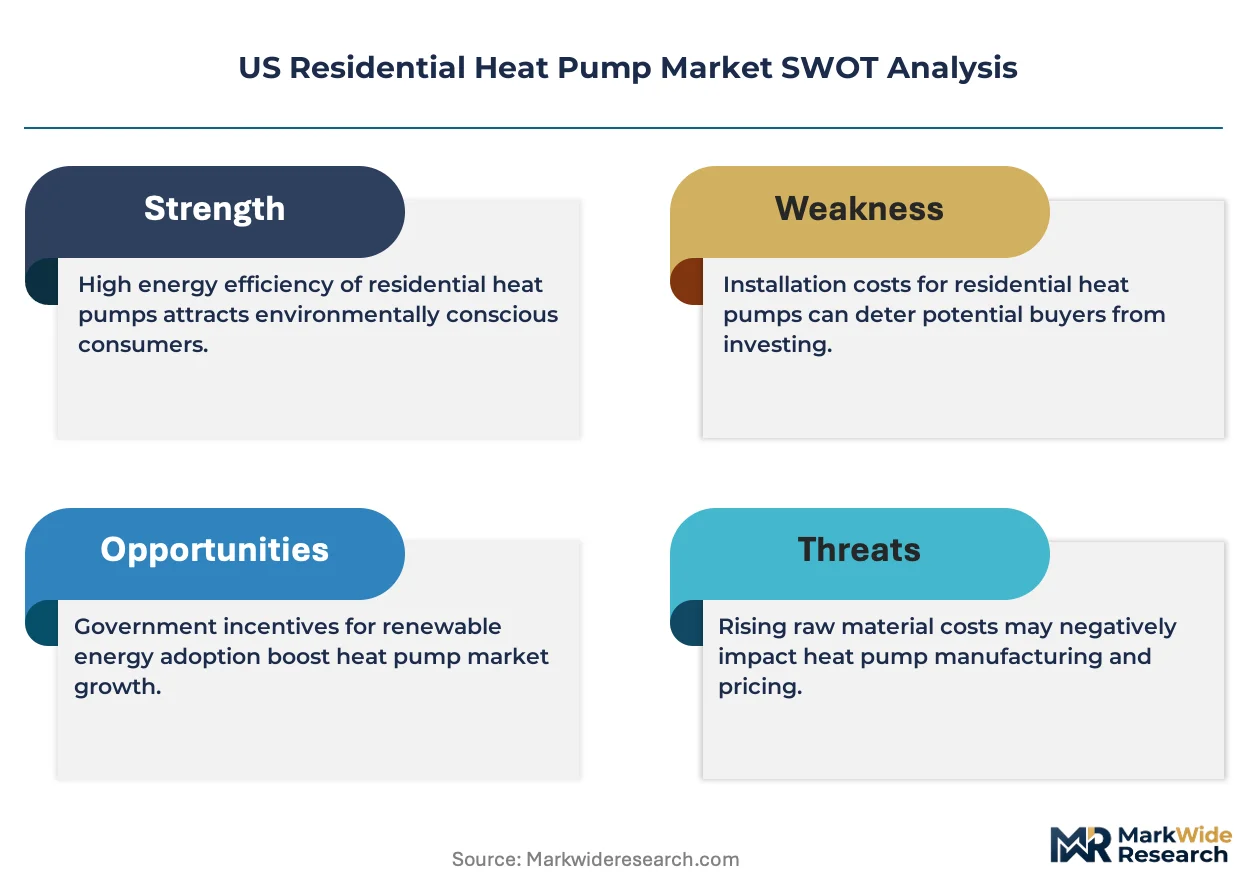
- Inflation Reduction Act incentives:The 25C tax credit and HOMES rebate program reduce upfront installation costs for cold-climate-qualified systems, accelerating replacement cycles in northern states where electrification mandates are tightening.
- Cold-climate optimization:Variable-speed inverter compressors with enhanced vapor injection are extending operational efficiency to sub-zero temperatures, opening addressable demand in Minnesota, Wisconsin, and Michigan heating markets.
- Contractor channel expansion:HVAC installers are cross-selling heat pump water heaters alongside space conditioning systems, leveraging existing customer relationships to capture whole-home electrification projects.
Market Restraints
- Copper and aluminum input volatility:Compressor and coil manufacturing faces margin pressure from base metal price swings, with raw materials representing 35-40% of system bill-of-materials.
- Refrigerant supply concentration:Domestic production capacity for R-32 and R-454B remains limited, creating dependency on imported chemical feedstocks subject to trade policy uncertainty.
- Electrical infrastructure gaps:Rural and older urban service territories lack sufficient panel capacity and transformer sizing to support cold-climate heat pump loads without costly upgrades.
Strategic Opportunities
- Midwestern retrofit penetration:Ohio, Indiana, and Illinois single-family housing stock remains underpenetrated relative to the Southeast, presenting white space for cold-climate system deployment.
- Utility demand response integration:Smart thermostat and compressor controls enabling grid-interactive water heating create recurring revenue streams through utility-managed load flexibility programs.
- Heat pump water heater bundling:Integrated system packages combining space conditioning and domestic hot water capture higher ticket values while simplifying installation logistics for contractor networks.
Industry Challenges
- Refrigerant handling certification gaps:The transition to mildly flammable A2L refrigerants requires technician retraining on safety protocols and recovery equipment, compressing available installation labor.
- Legacy furnace replacement complexity:Existing ductwork sizing and distribution patterns optimized for fossil fuel heating often require modification to deliver adequate airflow for heat pump operation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Residential Heat Pump Market |
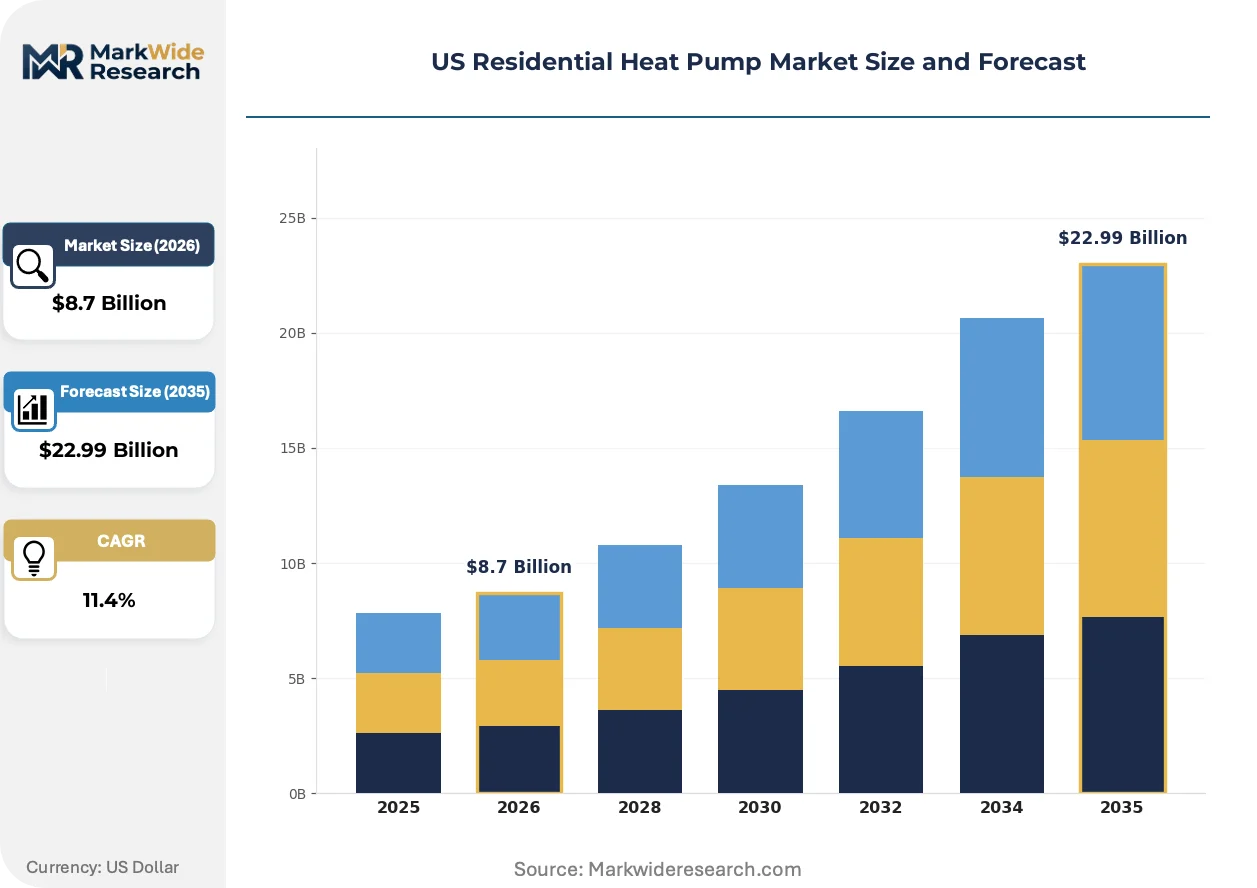
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Air Source, Ground Source, Hybrid, Water Source Technology: Inverter, Traditional, Ductless, Smart Systems End User: Homeowners, Contractors, Builders, Property Managers Installation Type: New Construction, Retrofit, Replacement, Seasonal |
| Companies Covered | Rheem, Lennox, Carrier, Bryant, American Standard, Daikin, Mitsubishi Electric, The Whalen Company, Trane, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Residential Heat Pump Market Emerging Trajectories
Product architecture is fragmenting into configurable subsystems as manufacturers adapt to refrigerant transitions, efficiency mandates, and installation labor constraints. Three developments are compressing traditional equipment categories.
Variable-refrigerant-flow heat pump technology is modularizing residential system design. Daikin and Mitsubishi Electric are transferring commercial VRF architectures into split-ductless platforms, enabling zoned conditioning without central air handlers. Southeast and Southwest installers are adopting these configurations for additions and retrofits where duct extension proves cost-prohibitive.
EPA's Technology Transitions rule under the AIM Act is prohibiting R-410A in new equipment beginning 2025, forcing compressor redesigns around R-32 and R-454B. The regulation compresses product development cycles as manufacturers must certify new platforms while managing legacy inventory clearance. Cold-climate product lines face the steepest redesign burden given their higher refrigerant charges and operating pressures.
Utility-managed installation programs are displacing traditional retail channels in key states. California's TECH Clean California initiative and New York's Clean Heat program are directing consumer demand through vetted contractor networks with standardized pricing, bypassing distributor showrooms. These procurement consolidations concentrate volume with fewer installation firms while compressing margin structures for equipment-only sales.
US Residential Heat Pump Market Segmentation
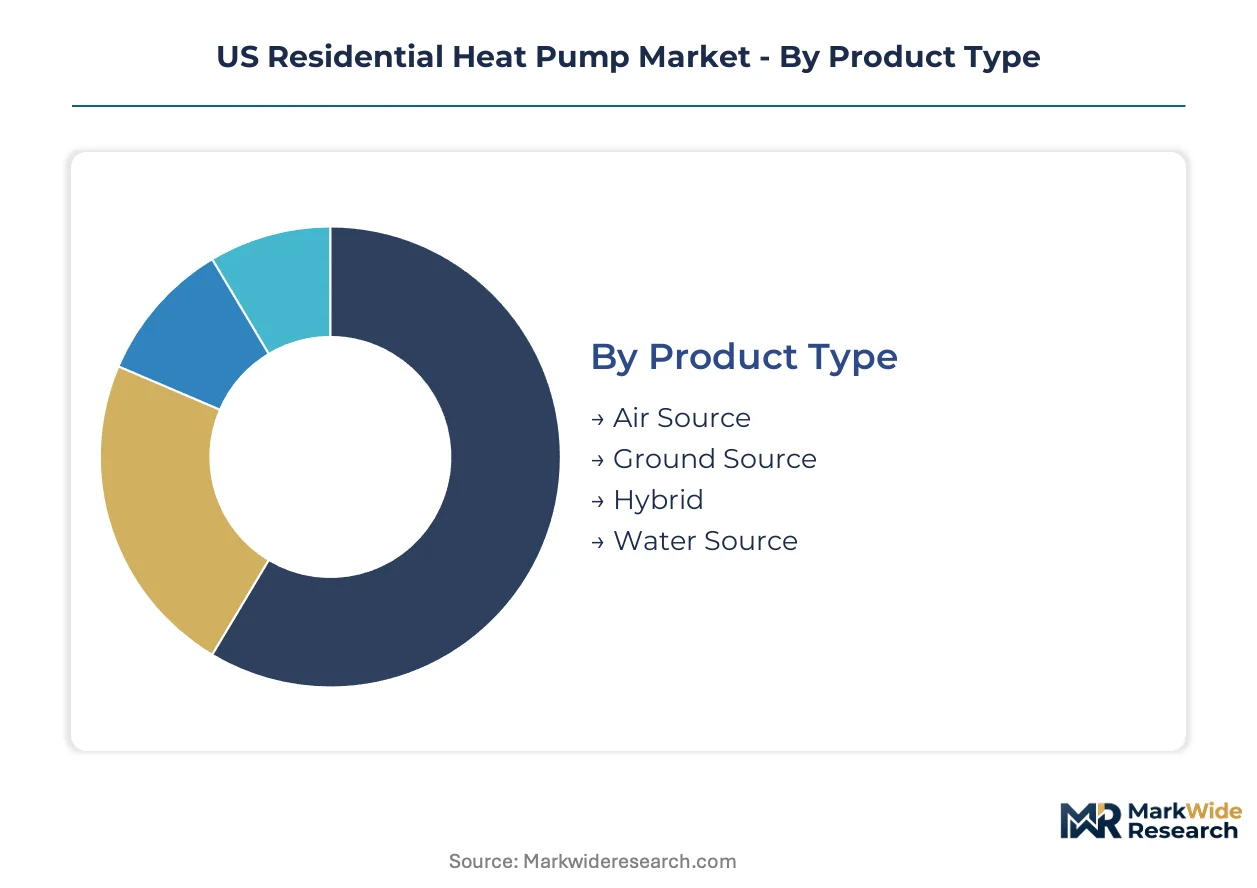
Heat pump purchasing patterns diverge sharply across installation context, technical architecture, and buyer sophistication. Segmentation reveals where equipment margins concentrate and which technology transitions face adoption friction.
Product Type:
Cost tier determines installation complexity and payback period for buyers across climate zones.
- Air Source:Vapor-compression systems exchange thermal energy with ambient air through finned coils, eliminating ground loop excavation. Demand concentrates in Southeast and Southwest single-family retrofits where moderate winters reduce supplemental heating requirements.
- Ground Source:Closed-loop geothermal systems leverage stable subsurface temperatures through vertical boreholes or horizontal trenches, delivering coefficient of performance ratings above four even in sub-zero conditions. Volume clusters in new construction developments across Minnesota, Wisconsin, and Michigan where borefield costs amortize across multiple units.
- Hybrid:Dual-fuel configurations pair electric heat pumps with fossil fuel furnaces, switching energy sources based on ambient temperature and electricity pricing. Northeast corridor installations favor this architecture for grid reliability assurance.
- Water Source:Systems extract thermal energy from lakes, ponds, or wells, requiring proximity to water bodies. Limited deployment concentrates in coastal Maine and Great Lakes shoreline properties.
Volume sits with Air Source; growth tilts toward Ground Source.
Technology:
Application requirements separate whole-home conditioning from targeted zone control.
- Inverter:Variable-speed compressors modulate refrigerant flow to match thermal loads, trimming electricity consumption during part-load operation. Cold-climate-qualified models with enhanced vapor injection are capturing replacement demand in northern utility territories.
- Traditional:Fixed-capacity compressors cycle on-off at full output, sacrificing efficiency during shoulder seasons. Budget-conscious Southeast replacements sustain residual demand despite regulatory phaseout pressures.
- Ductless:Mini-split architectures deliver zoned conditioning through wall-mounted or ceiling-cassette air handlers, eliminating ductwork losses. Sun Belt additions and accessory dwelling units drive specification.
- Smart Systems:Grid-interactive platforms integrate utility demand response signals, time-of-use rate optimization, and predictive maintenance algorithms. California and New York rebate programs accelerate adoption.
Traditional holds installed base volume; Inverter climbs the fastest.
End User:
Customer type dictates specification authority and financing mechanism.
- Homeowners:Retail purchasers responding to equipment failure or energy cost pressure, typically sourcing through contractor referrals. IRA tax credit awareness is shortening decision cycles for qualified cold-climate systems.
- Contractors:Installation firms controlling equipment selection for replacement and retrofit projects, influenced by distributor credit terms and manufacturer rebate programs. Cross-selling heat pump water heaters expands ticket values.
- Builders:Production and custom home developers specifying systems for new construction, prioritizing first-cost containment and code compliance over operating efficiency.
- Property Managers:Multifamily portfolio operators standardizing equipment across rental units, emphasizing warranty coverage and service network density.
Contractors command replacement volume; Builders represent the steepest expansion trajectory.
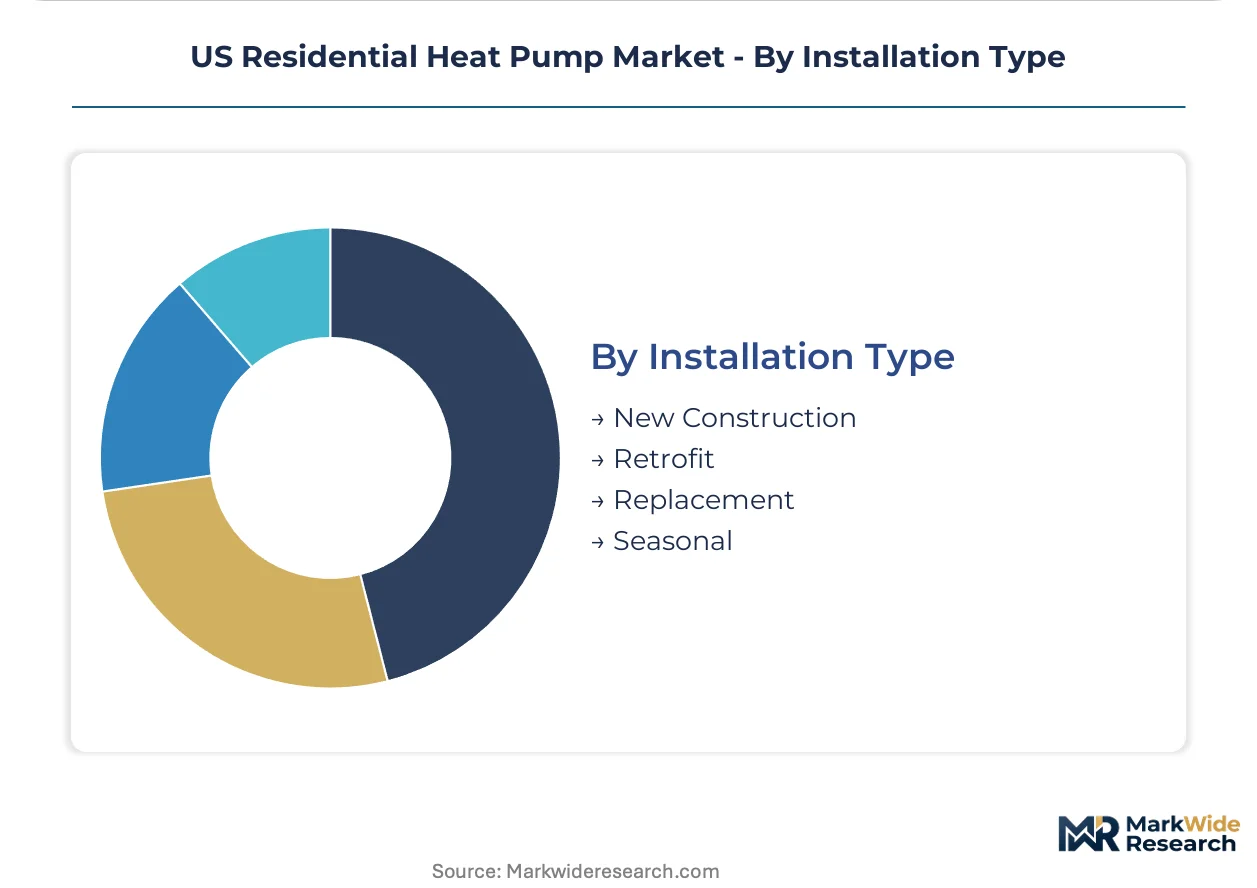
Installation Type:
Maturity of existing infrastructure shapes labor requirements and equipment selection.
- New Construction:Systems installed during initial building, enabling optimized duct sizing and electrical panel specification. Electrification mandates in California, New York, and Washington are converting this segment to heat-pump-only specification.
- Retrofit:Conversions of existing fossil fuel heating systems, often requiring duct modification and electrical service upgrades. Midwest single-family housing stock presents substantial white space.
- Replacement:Like-for-like equipment swaps at end-of-life, representing the largest volume channel but facing refrigerant transition complexity.
- Seasonal:Temporary or supplemental installations, minimal market presence.
Replacement dominates current volume; New Construction gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Single-family retrofits in the Southeast and Midwest concentrate current demand, while state electrification mandates in the Northeast and Pacific Coast are accelerating new construction specification shifts.
Southeast
Florida and Georgia homeowners drive replacement volume for air-source systems given moderate winter loads and high cooling-degree-day profiles. The Inflation Reduction Act's 25C tax credits shorten payback periods for SEER2-qualified equipment. Atlanta and Charlotte contractor networks are cross-selling heat pump water heaters alongside space conditioning upgrades.
Midwest
Ohio, Indiana, and Illinois housing stock remains underpenetrated relative to the Southeast, presenting white space for cold-climate system deployment. State utility commission rate cases in Michigan and Wisconsin determine whether time-of-use pricing rewards heat pump operation. Minneapolis-St. Paul distributors are expanding inventory for enhanced vapor injection models.
Northeast
New York and Massachusetts electrification mandates are prohibiting fossil fuel heating in new construction, converting builder specification to heat-pump-only. The HOMES rebate program directs consumer demand through vetted contractor networks. Boston and New York City installation firms are consolidating volume under utility-managed procurement programs.
Pacific Coast
California's TECH Clean California initiative standardizes pricing and contractor qualification, bypassing traditional distributor channels. Washington state building codes are tightening electrification requirements for residential construction. Los Angeles and Seattle metro areas are seeing grid-interactive smart system adoption through utility demand response integration.
Southwest
Arizona and Nevada cooling-dominated markets favor ductless mini-split architectures for additions and accessory dwelling units. Desert climate conditions reduce heating load requirements, simplifying system sizing. Phoenix and Las Vegas contractors are adopting variable-refrigerant-flow platforms transferred from commercial applications.
US Residential Heat Pump Market Vendor Landscape
Refrigerant transition redesigns dominate the current landscape as manufacturers manage R-410A phaseout inventory clearance while certifying R-32 and R-454B platforms. The vendor base spans diversified HVAC conglomerates, Japanese inverter specialists, and water heating crossover players. Three archetypes define positioning: full-line climate control providers, mini-split technology originators, and integrated water heating specialists. Competitive intensity centers on distributor shelf space control and contractor channel loyalty programs.
Among diversified HVAC providers, Carrier and Trane exemplify full-line positioning through extensive distributor relationships. Daikin and Mitsubishi Electric occupy the inverter-driven compressor technology tier, leveraging mini-split heritage for residential ductless expansion. Rheem represents the water heating crossover archetype, bundling heat pump water heaters with space conditioning systems through shared contractor networks.
| Leading Market Players |
|---|
| Rheem |
| Lennox |
| Carrier |
| Bryant |
| American Standard |
| Daikin |
| Mitsubishi Electric |
| The Whalen Company |
| Trane |
| Others |
Supply Flow & Price Mechanics
Backward integration into compressor manufacturing anchors pricing power for leading HVAC conglomerates while insulating margin structures from copper and aluminum volatility. Captive production of critical rotating components allows volume leaders to undercut distributor pricing on entry-level air-source systems without sacrificing profitability on cold-climate inverter platforms.
Pricing Analysis
Volume concentrates in replacement-grade air-source units where contractor purchasing power compresses margins, while cold-climate inverter systems with enhanced vapor injection capture premium pricing through IRA qualification thresholds. Price differentiation separates SEER2-certified models eligible for federal tax credits from legacy inventory facing accelerated obsolescence. Pricing pressure stems from raw material input volatility, with copper and aluminum representing substantial bill-of-materials exposure. Builder-specified new construction systems exhibit highest price sensitivity, whereas homeowner-driven retrofits in electrification-mandate states show willingness to absorb upfront premiums for operational savings.
Supply Chain Analysis
Workforce availability constraints in Mexico and Tennessee manufacturing corridors are compressing production schedules for rotary compressor assembly lines. Domestic supply draws from Japanese and Korean component imports for inverter drives and electronic expansion valves, creating tariff exposure on precision-machined parts. Single-source vulnerability concentrates in refrigerant chemical feedstocks, with domestic R-32 and R-454B capacity lagging EPA-mandated transition timelines. Distribution runs through authorized distributor networks controlling contractor credit terms and inventory allocation across Southeast and Midwest replacement markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as refrigerant transition costs and certification burdens force sub-scale manufacturers toward strategic exit. The EPA's AIM Act implementation timeline compresses weaker players unable to fund parallel R-410A inventory clearance and R-32 platform development.
For Market Incumbents: Acquire cold-climate testing and certification capabilities to secure IRA rebate eligibility ahead of competitor platform launches. Lock exclusive distribution agreements with top-twenty HVAC contractor networks in Ohio, Indiana, and Illinois to defend replacement volume against emerging inverter specialists. Prioritize backward integration into heat exchanger coil manufacturing to offset copper price volatility exposure. For New Entrants and Emerging Players: Grid-interactive smart thermostat integration offers a technology-first wedge for bypassing established distributor relationships through direct utility procurement channels. Target California and New York electrification-mandate territories where standardized pricing programs reduce brand-loyalty barriers. Lead with demand-response-enabled system packages that generate recurring software revenue alongside equipment sales. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by diversified HVAC conglomerates seeking cold-climate product line fill. Long-term viability favors manufacturers with certified R-32 platforms and established contractor channel relationships over pure-play water heating crossover entrants. Monitor state utility commission rate case outcomes as the inflection signal determining whether time-of-use pricing structures reward or penalize heat pump load profiles.| Strategic Initiative | Industry Significance |
|---|---|
| R-32 Platform Certification | EPA AIM Act compliance secures market access beyond legacy refrigerant phaseout deadlines. |
| Contractor Network Consolidation | Exclusive distribution agreements in Midwest retrofit markets concentrate replacement volume. |
| Cold-Climate Test Investment | Enhanced vapor injection validation unlocks IRA rebate eligibility in northern utility territories. |
| Heat Pump Water Heater Bundling | Integrated system packages raise ticket values while simplifying installation logistics. |
| Utility Demand Response Integration | Smart compressor controls create recurring revenue through grid-interactive load flexibility programs. |
Methodological Framework
Document review covered EPA regulatory filings under the AIM Act, DOE Appliance and Equipment Standards Program dockets, and state-level building code electrification mandates, complemented by interviews with HVAC distributor principals, contractor network managers, and utility demand response program administrators. Secondary validation drew from FERC rate case documentation, EIA residential energy consumption surveys, and manufacturer SEC disclosures. Bottom-up unit shipment estimates triangulated against top-down market value reconstruction.
Cross-referencing historical replacement cycle patterns with industry panel input on refrigerant transition timelines established the analytical framework across the projection horizon. Segmentation dimensions modeled include product architecture, compressor technology tier, installation context, and regional electrification policy intensity. CAGRs derived from installer capacity expansion plans, housing stock turnover rates, and incentive program budget allocations. Forecast inputs incorporated copper futures curves and state-level rebate program legislative authorization status.
Several conditions sit outside the modeled scope, including abrupt repeal of Inflation Reduction Act provisions, trade policy disruption affecting refrigerant chemical imports, and utility rate structure reforms that penalize rather than reward electrification load profiles. Forecasts reflect assumptions regarding orderly R-410A inventory clearance and technician certification completion for mildly flammable A2L refrigerant handling. Material deviation in federal incentive continuity, refrigerant supply availability, or electrical infrastructure upgrade funding warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
HVAC Actuators Market
HVAC Equipment
Global Portable Air Conditioner Market
HVAC Equipment
South Korea HVAC Market
HVAC Equipment
Germany Heat Pump Market
HVAC Equipment
Industrial Heating Equipment Market
HVAC Equipment
Heating Radiator Market
HVAC Equipment
Asia Pacific Commercial HVAC Market
HVAC Equipment
GCC Kitchen Hood Market
HVAC Equipment
Asia-Pacific Heating Equipment Market
HVAC Equipment
Swing Compressor Market
HVAC Equipment
Air Humidifier and Dehumidifier Market
HVAC Equipment
Europe Residential Fan Coil Convectors Market
HVAC Equipment
Europe Air to Water Heat Pump Market
HVAC Equipment
Fabric Ducting Market
HVAC Equipment
Water Softener Equipment Market
HVAC Equipment
Variable Refrigerant Flow (VRF) System Market