
 Global Split Systems Market | 2026-2036
Global Split Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Global Split Systems Market Foresight
Aftermarket service revenue is tilting toward refrigerant management and predictive diagnostics as margin pools migrate from hardware installation to lifecycle contracts. Daikin Industries Ltd. leverages its captive compressor production to control cost structures across Southeast Asian projects. Mitsubishi Electric Corporation anchors premium positioning through proprietary inverter algorithms that reduce part-load energy consumption. Carrier Global Corporation competes on scale, operating factory networks that supply ducted and cassette configurations to North American commercial contractors.
Split systems are self-contained air conditioning units comprising separate indoor evaporator and outdoor condenser sections linked by refrigerant piping, typically operating on R-32 or R-410A with rated capacities from 9,000 to 48,000 BTU per hour for zonal climate control. Wall-mounted units dominate residential retrofit volumes due to minimal structural modification, while variable refrigerant flow configurations capture margin in commercial complexes by enabling simultaneous heating and cooling across multiple zones. Smart thermostat integration represents the fastest-expanding technology segment as facility managers prioritize remote diagnostics and demand-response grid integration.
EPA regulations in the United States mandate phased reductions in hydrofluorocarbon refrigerants, compelling manufacturers to redesign systems for lower global warming potential alternatives. The EU F-Gas Regulation imposes similar quotas, while India's BIS certification requirements enforce minimum performance standards for imported compressor units. Stakeholders must monitor refrigerant transition timelines and regional certification divergence when configuring product portfolios for multi-country deployment.
Market Dynamics
Refrigerant phase-down mandates under the Kigali Amendment are forcing manufacturers to redesign compressor architectures and thermal exchange systems, compressing development cycles while opening premium positioning for early movers on R-32 and R-290 platforms.
Growth Catalysts
- India's PLI scheme for white goods:Production-linked incentives for air conditioning components are drawing compressor manufacturing investment to Gujarat and Tamil Nadu, reducing import dependence for coil and motor assemblies.
- Cooling degree day expansion:Vietnam's Mekong Delta and Indonesia's Java corridor are experiencing sustained temperature elevation, driving residential retrofit demand for variable-speed units that modulate output against latent loads.
- Refrigerant transition timelines:The EU F-Gas Regulation's quota reductions are accelerating R-410A obsolescence, creating replacement pull for lower-GWP alternatives in commercial refurbishment projects.
Market Restraints
- Copper and aluminum input volatility:Coil and fin stock pricing fluctuations compress margin predictability for OEMs locked into annual contractor pricing agreements.
- Compressor supply concentration:Rotary and scroll compressor production clusters in eastern China create geographic risk exposure for brands without captive motor winding or stamping capabilities.
- Installation labor scarcity:Certified refrigerant handling technicians remain undersupplied relative to retrofit volume growth in Philippines and Bangladesh urban corridors.
Strategic Opportunities
- Smart thermostat convergence:Integration of occupancy sensing and grid-responsive controls with split system hardware opens recurring software revenue streams in North American multi-family housing.
- VRF penetration in Southeast Asian commercial:Simultaneous heating-cooling configurations remain underdeployed in Indonesian hospital and hotel verticals relative to Japanese adoption benchmarks.
- Aftermarket refrigerant recovery services:EPA and EU mandates for reclaimed refrigerant use are creating certified service network expansion opportunities independent of unit sales cycles.
Industry Challenges
- BIS certification timelines:India's mandatory testing protocols for imported compressors introduce 12-16 week approval delays that disrupt just-in-time manufacturing schedules.
- Legacy building electrical infrastructure:Pre-1990s residential stock in southern Europe lacks circuit capacity for inverter startup loads, forcing costly panel upgrades or limiting addressable unit sizing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Split Systems Market |
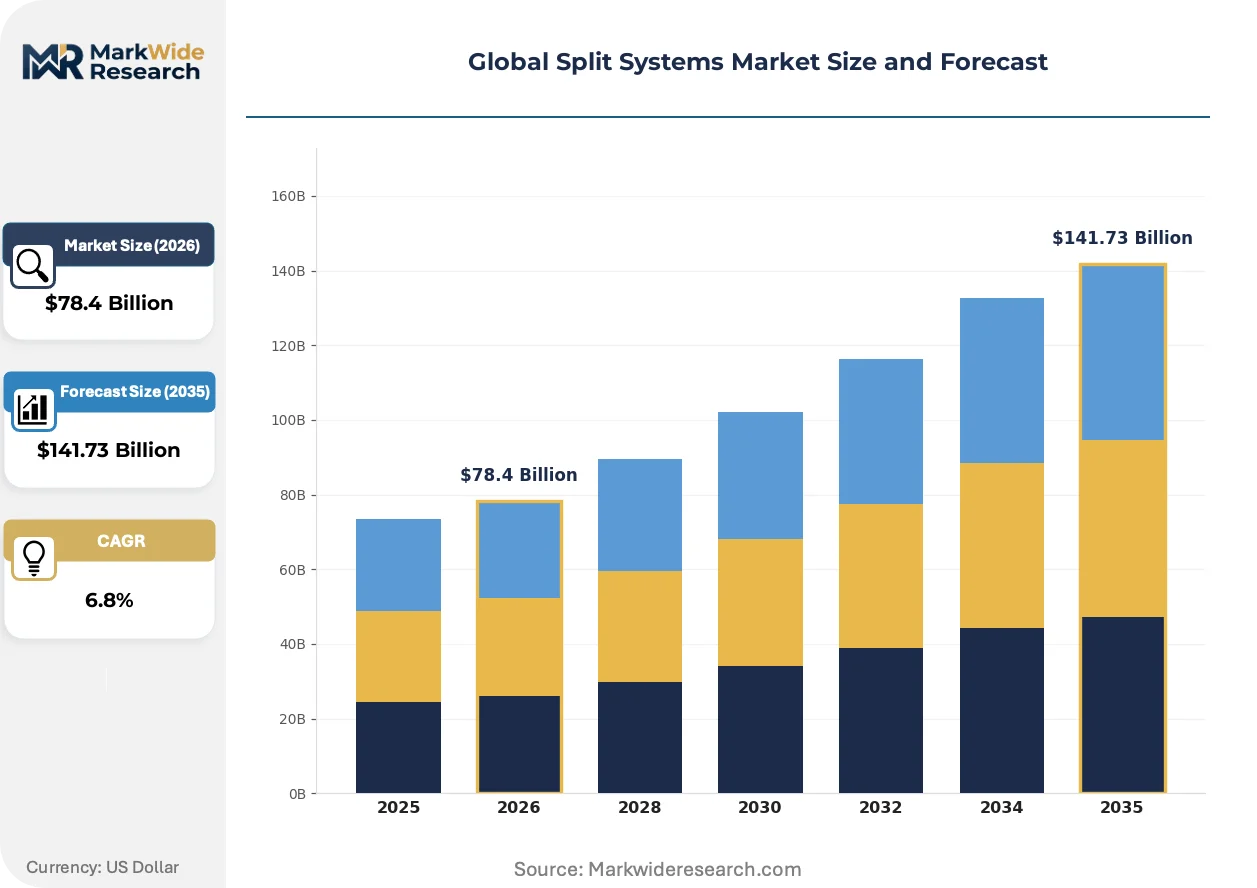
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $141.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wall-mounted, Floor-standing, Ceiling Cassette, Ducted, Ceiling Suspended Technology: Inverter, Non-Inverter, Multi-Split, Smart Thermostat, Variable Refrigerant Flow Application: Residential Complexes, Commercial Complexes, Educational Institutions, Hospitality Establishments, Data Centers End User: Property Developers, Facility Managers, Real Estate Investors, Building Automation Specialists |
| Companies Covered | Daikin Industries Ltd., Mitsubishi Electric Corporation, Carrier Global Corporation, LG Electronics Inc., Panasonic Corporation, Samsung Electronics Co., Ltd., Fujitsu General Limited, Johnson Controls International plc, Midea Group Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Split Systems Market Shifts & Advancements
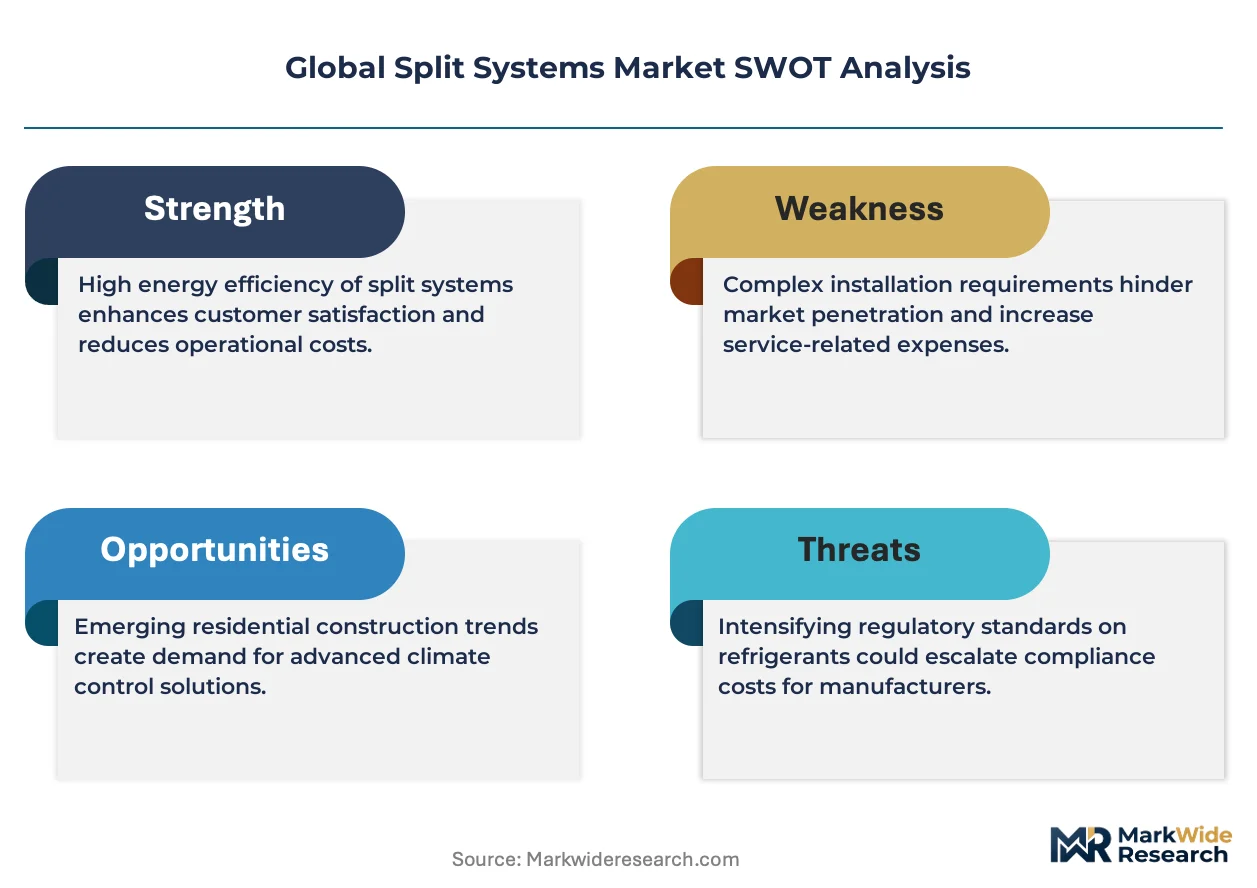
Electrification of thermal systems is intersecting with refrigerant chemistry transitions and digital building controls, compressing equipment replacement cycles while fragmenting procurement authority between HVAC contractors, energy managers, and sustainability officers.
Variable refrigerant flow technology with dedicated outdoor unit architectures is rendering obsolete fixed-capacity split systems in mid-rise commercial construction. Facility managers in Singapore and Dubai are specifying VRF for simultaneous heating-cooling zones, compressing payback periods through heat recovery operation. The technology is rendering obsolete traditional chiller-and-boiler configurations in buildings under 50,000 square feet.
The EPA's phasedown of hydrofluorocarbon production and consumption under the AIM Act is compressing R-410A availability and elevating reclaimed refrigerant prices. OEMs are accelerating R-32 and R-454B platform launches to maintain federal compliance timelines. North American residential replacement contractors are experiencing the steepest inventory reconfiguration burden as 2025-2026 production quotas tighten.
Building automation system integration is shifting specification authority from mechanical contractors to energy procurement teams. Large multi-family developers are bundling split system selection with utility demand-response program enrollment, displacing traditional contractor-driven equipment selection. This concentration of buying power is most visible in California and New York state markets where grid-interactive water heating and space conditioning incentives stack.
Global Split Systems Market Segmentation
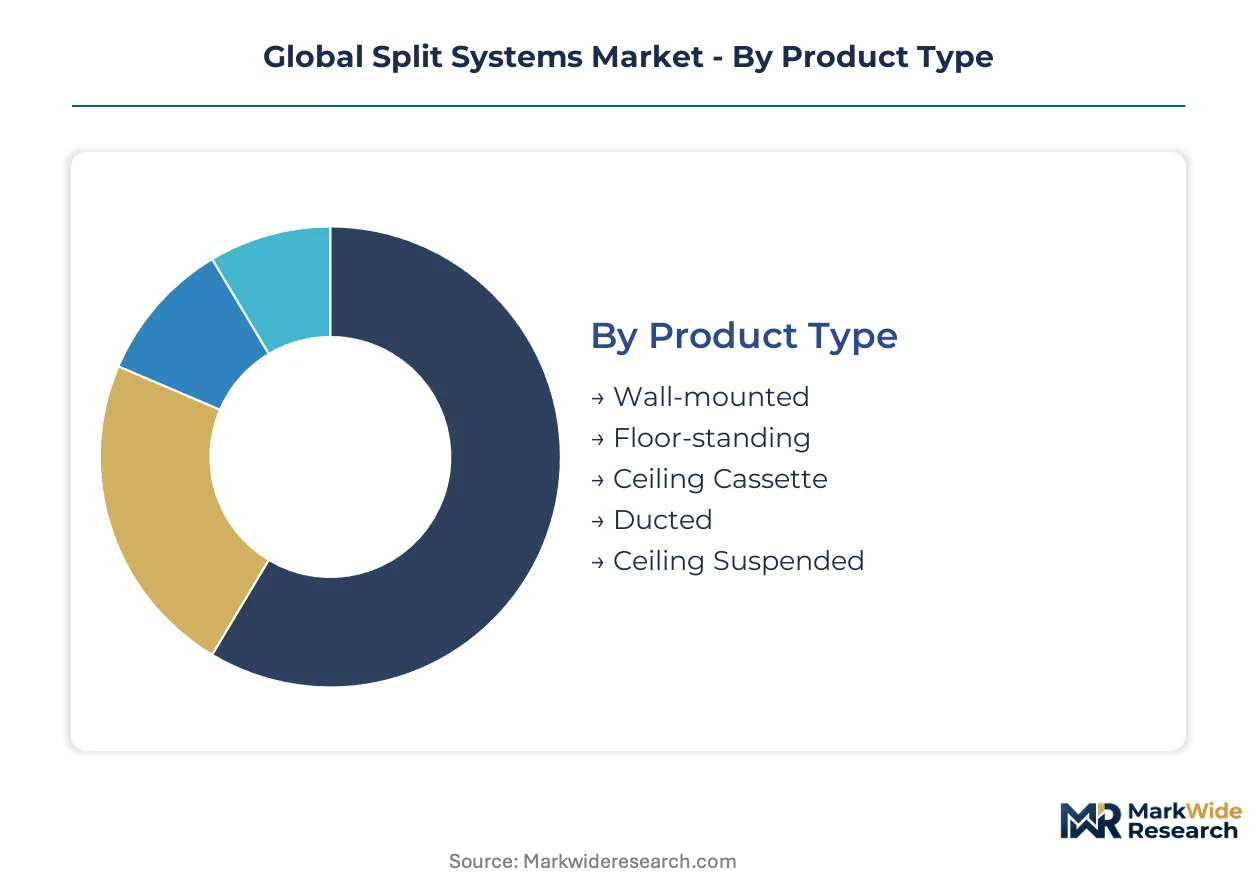
Segmentation in split systems reveals how procurement authority fragments across mechanical contractors, energy managers, and sustainability officers. Each dimension—product form, control technology, building type, and buyer profile—carries distinct margin structures and certification requirements that reshape competitive positioning.
Product Type:
Cost tier differentiation separates retrofit-friendly configurations from integrated building systems requiring structural modification.
- Wall-mounted:Compact evaporator units affix directly to vertical surfaces with minimal ductwork. Demand concentrates in Vietnam's urban residential corridors where electrification programs accelerate and installation labor remains scarce.
- Ducted:Concealed air handlers distribute conditioned air through building plenums, requiring coordinated mechanical-electrical planning. Facility managers in Singapore's commercial retrofits specify these for aesthetic integration where ceiling exposure is unacceptable.
- Floor-standing:Vertical cabinet designs serve spaces lacking wall mounting surfaces or with high glazing ratios.
- Ceiling Cassette:Four-way discharge units recess into suspended ceilings for uniform air distribution across open plans.
- Ceiling Suspended:Under-ceiling mounting preserves floor space in industrial or retail environments with limited wall availability.
Wall-mounted configurations command the established base. The steepest expansion runs through ducted systems as commercial refurbishment volumes climb.
Technology:
Application-specific control architectures determine energy performance certification tiers and utility incentive eligibility.
- Inverter:Variable-frequency drives modulate compressor speed against thermal loads rather than cycling on-off. India's BIS certification mandates minimum efficiency thresholds that inverter platforms exceed, concentrating adoption in Gujarat and Tamil Nadu residential developments.
- Variable Refrigerant Flow:Dedicated outdoor unit architectures enable simultaneous heating and cooling across zones with heat recovery. Indonesia's hospital and hotel verticals underdeploy these relative to Japanese benchmarks, creating penetration headroom.
- Non-Inverter:Fixed-capacity operation at full compressor speed persists in price-sensitive replacement cycles.
- Multi-Split:Single outdoor units serve multiple indoor evaporators, reducing external equipment footprint in dense urban fabric.
- Smart Thermostat:Occupancy sensing and grid-responsive controls integrate with building automation systems for demand-response program enrollment.
Non-Inverter systems retain volume in emerging markets. VRF configurations gain share fastest as commercial specifications prioritize heat recovery operation.
Application:
Customer type maturity separates commodity replacement demand from engineered new construction specifications.
- Residential Complexes:Individual unit climate control with minimal common infrastructure. Cooling degree day expansion across Indonesia's Java corridor drives variable-speed unit preference for latent load modulation.
- Commercial Complexes:Zonal control requirements with simultaneous heating-cooling needs and after-hours setback protocols. Singapore facility managers specify integrated controls for utility demand-response stacking.
- Educational Institutions:Intermittent occupancy patterns favoring rapid pull-down capability and centralized scheduling.
- Hospitality Establishments:Guest room individual control with central housekeeping override and energy management system integration.
- Data Centers:Precision cooling with continuous operation requirements and redundant capacity for thermal runaway protection.
Residential applications anchor unit volume. Commercial complexes exhibit the steepest technology upgrade trajectory as VRF displaces traditional chiller-and-boiler configurations.
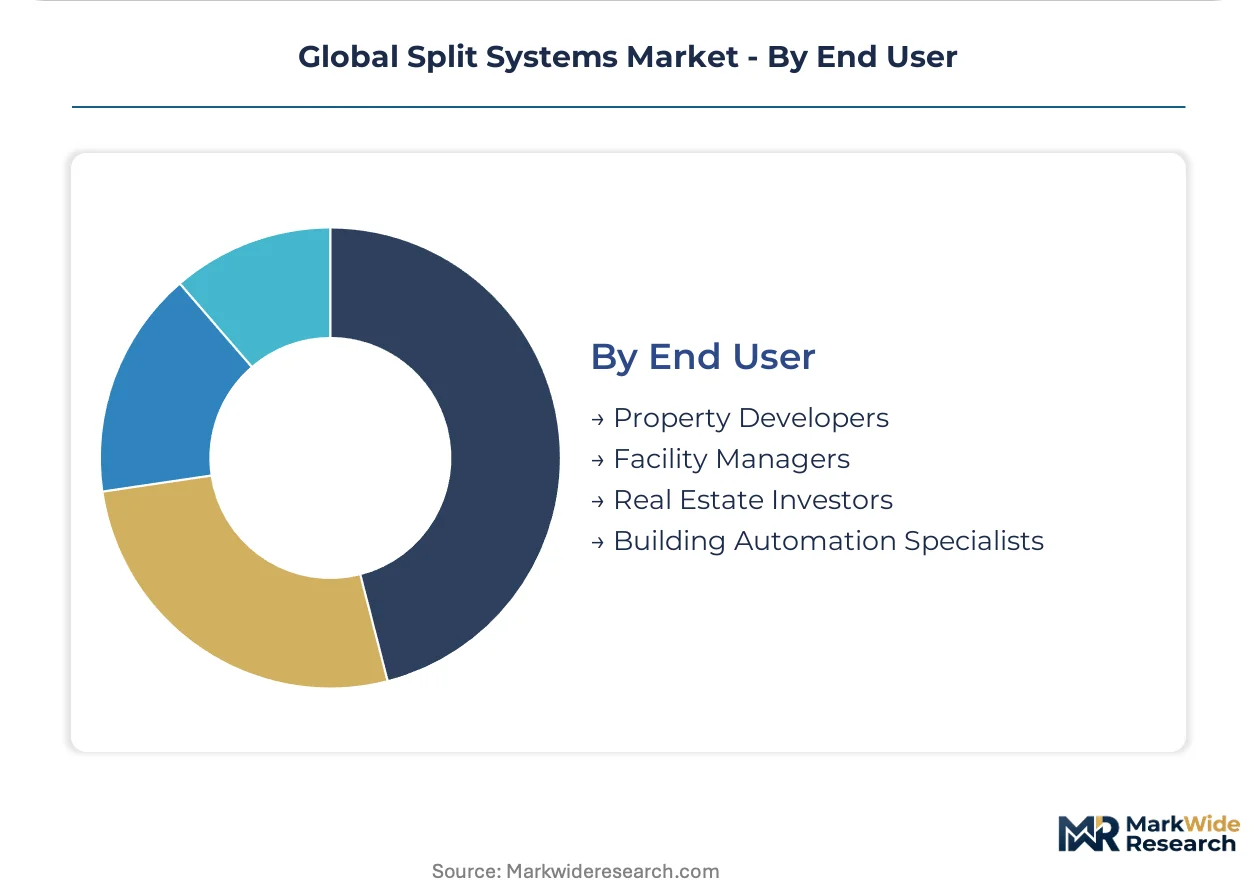
End User:
Procurement authority concentration determines whether specifications prioritize first cost, lifecycle energy, or operational flexibility.
- Facility Managers:Operating budget accountability drives predictive maintenance contracts and refrigerant recovery service bundling. North American multi-family developers are consolidating specification authority with these stakeholders for grid-interactive enrollment.
- Property Developers:Capital cost optimization with certificate of occupancy timing constraints shapes equipment selection for new construction.
- Real Estate Investors:Asset valuation metrics incorporating energy benchmarking scores and green building certification premiums.
- Building Automation Specialists:System integration responsibility for BACnet or Modbus connectivity with central energy management platforms.
Facility managers command specification influence in operational buildings. Property developers retain authority fastest in Southeast Asian greenfield construction where PLI scheme localization reduces component lead times.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Southeast Asia demonstrate acute price sensitivity to upfront equipment costs, while North American and European purchasers prioritize lifecycle energy efficiency and refrigerant compliance over first-cost minimization.
United States
Residential replacement cycles dominate unit volume as aging R-22 systems face mandatory phase-out. EPA regulations under the AIM Act compress R-410A availability, elevating reclaimed refrigerant pricing and accelerating R-454B platform adoption. Texas and Florida metropolitan corridors exhibit the steepest retrofit demand as cooling degree days climb and electrical infrastructure upgrades enable inverter startup loads.
China
Domestic cooling demand concentrates in the Yangtze River Delta and Pearl River Delta urban agglomerations where apartment density favors multi-split configurations. MIIT efficiency standards and dual carbon goals drive compressor motor redesign toward permanent magnet synchronous architectures. Guangdong province hosts the densest cluster of rotary compressor manufacturing, with captive stamping and winding capabilities insulating major brands from supply disruption.
India
PLI scheme incentives for white goods components draw compressor and coil assembly investment to Gujarat and Tamil Nadu, reducing import dependence for motor laminations. BIS certification mandates 12-16 week approval timelines for imported compressors, disrupting just-in-time schedules for brands without local testing partnerships. Delhi-NCR and Maharashtra residential complexes exhibit fastest adoption of inverter platforms as urban electrification programs accelerate.
Vietnam
The Mekong Delta corridor experiences sustained temperature elevation, driving residential retrofit demand for variable-speed units capable of latent load modulation. Cooling degree day expansion outpaces grid infrastructure upgrades in secondary cities, creating addressable market constraints for higher-capacity equipment. Ho Chi Minh City anchors commercial VRF specification activity as hospitality and healthcare verticals modernize thermal systems.
Germany
EU F-Gas Regulation quota reductions accelerate R-410A obsolescence in commercial refurbishment projects, elevating demand for R-32 and R-290 platforms. Building energy performance certificates influence real estate valuation, concentrating procurement authority with facility managers prioritizing operational carbon metrics. Bavaria and North Rhine-Westphalia exhibit densest concentration of heat pump-split hybrid installations as building codes tighten envelope standards.
Global Split Systems Market Competitive Landscape
Vertically integrated conglomerates and specialized climate-control engineering houses split the market along technology-intensity lines. Japanese and Korean industrial groups dominate inverter algorithm development and captive compressor production. North American HVAC contractors and European building automation specialists compete on system integration and lifecycle service bundling. Capacity localization and refrigerant platform transition timing represent the dominant competitive moves as manufacturers reposition for R-32 and R-290 compliance deadlines.
Within the integrated manufacturing tier, Daikin Industries Ltd. and Mitsubishi Electric Corporation exemplify archetypes combining captive compressor production with proprietary control software development. Carrier Global Corporation occupies a position bridging equipment manufacturing and multi-brand distribution network operation. These three entities represent distinct strategic postures: full vertical integration, technology-led premium positioning, and scale-driven portfolio breadth.
| Leading Market Players |
|---|
| Daikin Industries Ltd. |
| Mitsubishi Electric Corporation |
| Carrier Global Corporation |
| LG Electronics Inc. |
| Panasonic Corporation |
| Samsung Electronics Co., Ltd. |
| Fujitsu General Limited |
| Johnson Controls International plc |
| Midea Group Co., Ltd. |
| Others |
Supply & Pricing Matrix
Guangdong province's dense cluster of rotary compressor manufacturing anchors cost structures across Southeast Asian project bids, with captive stamping and winding capabilities insulating major brands from supply disruption while compressing margin pools for competitors sourcing externally. The interplay between captive production and spot-market coil pricing creates divergent cost positions that reshape bidding dynamics for Indian PLI scheme contracts.
Pricing Analysis
Aftermarket refrigerant recovery and predictive maintenance contracts now drive lifetime value capture, displacing hardware margins as the primary revenue anchor. Three-tier pricing structure across premium inverter platforms, standard fixed-speed units, and economy non-inverter configurations segments buyers by efficiency certification and control sophistication. Cost compression in entry-level residential tiers intensifies as Vietnam's electrification programs expand addressable volumes. Facility managers in Singapore commercial complexes exhibit lowest price sensitivity, prioritizing heat recovery VRF configurations with integrated building automation.
Supply Chain Analysis
Supplier-financing facilities with 90-120 day extended terms have become standard for compressor and coil procurement from Chinese manufacturing clusters. Rotary and scroll compressor production concentrates in eastern China, Thailand, and India, drawing from copper cathode, aluminum fin stock, and rare-earth permanent magnet inputs. Single-source vulnerability around Guangdong motor winding capacity creates geographic risk exposure for brands lacking alternative supplier qualification. Distribution runs through authorized dealer networks for residential retrofit, while commercial projects deploy direct contractor relationships with factory technical support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Procurement authority fragmentation between HVAC contractors, energy managers, and sustainability officers creates white-space opportunities for specialized players. Building automation integration requirements open niches for control-software specialists alongside traditional equipment manufacturers.
For Market Incumbents:Entrench specification influence through captive compressor production and proprietary inverter algorithm development. Daikin Industries Ltd. and Mitsubishi Electric Corporation demonstrate how backward integration into motor winding and stamping insulates margin structures from commodity volatility. Accelerate R-32 and R-290 platform certification to capture premium positioning ahead of EPA and EU F-Gas Regulation compliance deadlines.
For New Entrants and Emerging Players:Build out certified refrigerant recovery service networks independent of unit sales cycles, capitalizing on EPA and EU mandates for reclaimed refrigerant use. Indonesia's hospital and hotel verticals remain underpenetrated for VRF configurations relative to Japanese adoption benchmarks, offering the most accessible commercial entry point. Partner with Indian PLI scheme beneficiaries for localized coil and motor assembly to circumvent BIS certification delays.
For Investors and Strategic Acquirers:Mid-cycle technology positioning favors building automation specialists with BACnet and Modbus integration capabilities over pure hardware manufacturers. The 5-10 year viability window rewards acquisition targets combining refrigerant transition readiness with software-defined control platforms. Monitor R-410A obsolescence velocity and reclaimed refrigerant price curves as inflection indicators for portfolio rebalancing between legacy service networks and next-generation platform providers.
| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerant Platform Transition | R-32 and R-290 certification ahead of EPA and EU F-Gas Regulation deadlines captures premium positioning. |
| Backward Integration into Compressor Manufacturing | Captive motor winding and stamping capabilities insulate margin structures from Guangdong supply concentration. |
| Smart Thermostat Convergence | Grid-responsive controls with demand-response enrollment open recurring software revenue in North American multi-family housing. |
| VRF Penetration in Southeast Asian Commercial | Simultaneous heating-cooling configurations address underdeployment in Indonesian hospital and hotel verticals. |
| Aftermarket Refrigerant Recovery Network Expansion | Certified service capabilities align with EPA and EU mandates for reclaimed refrigerant use independent of sales cycles. |
Research Methodology
A spread of perspectives from HVAC contractor operations managers, facility management executives, compressor manufacturing engineers, and building automation integration specialists converged on the working assumptions shaping demand modeling. Primary field engagement combined with secondary validation against SEC filings from Carrier Global Corporation and Daikin Industries Ltd., EPA refrigerant phase-down schedules, EU F-Gas Regulation quota documentation, and Indian BIS certification timelines. Bottom-up unit shipment analysis triangulated against top-down construction spending and cooling degree day projections.
Demand-supply balance dynamics across the projection horizon anchored volume and value outputs, with segmentation modeled across product type, control technology, building application, and procurement authority concentration. CAGRs derived from fitted growth curves incorporating PLI scheme localization effects, refrigerant transition compliance timelines, and grid infrastructure upgrade pacing. Compressor manufacturing capacity utilization and inverter adoption velocity served as industry-specific forecast inputs.
Stress conditions across copper and aluminum input volatility, BIS certification approval delays, and installation labor scarcity in Philippines and Bangladesh urban corridors were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about electrification program pacing and regulatory compliance deadlines. Macroeconomic deviation, regulatory acceleration or delay, or breakthrough heat pump technology would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
Heating Equipment Market
HVAC Equipment
Steam Operated Condensate Pump Market
HVAC Equipment
Steam Boiler Systems Market
HVAC Equipment
North America Ceiling Cassette Market
HVAC Equipment
Commercial Refrigeration Equipment Market
HVAC Equipment
Europe Ventilation Equipment Market
HVAC Equipment
Field-Erected Cooling Tower Market
HVAC Equipment
Air Volume Controllers Market
HVAC Equipment
Europe Commercial HVAC Market
HVAC Equipment
HVAC Fan and Evaporator Coil Market
HVAC Equipment
HVAC Systems Market
HVAC Equipment
Air Humidifier and Dehumidifier Market
HVAC Equipment
Air Conditioning Equipment Market
HVAC Equipment
Fabric Ducting Market
HVAC Equipment
South America Compressor Market
HVAC Equipment
HVAC Louvers Market