
 Tubular Heater Market | 2026-2036
Tubular Heater Market Size, Share, and Industry Trends Forecast 2026-2036
Tubular Heater Market Analytics
Modular heater configurations with integrated temperature sensing and control electronics is broadening buyer choice beyond standalone commodity elements. Watlow leverages its vertically integrated sensor and heater architecture to capture premium positioning in precision process applications. Chromalox sustains manufacturing scale across multiple North American facilities, anchoring its presence in heavy industrial segments. Tempco Electric Heater Corporation specializes in rapid-turn custom configurations, competing on engineering responsiveness rather than volume.
A tubular heater is a resistance heating element consisting of a nickel-chromium or iron-chromium-aluminum wire coil centered within a metal sheath and compacted with magnesium oxide insulation, typically operating at sheath temperatures up to 760°C for industrial duty. Its primary purpose is to deliver controlled, uniform heat transfer to liquids, gases, metals, and air streams across process industries. Stainless steel and Incoloy material grades command the strongest margin pools due to corrosion resistance requirements in chemical and food processing environments. Immersion and flanged configurations represent the fastest-expanding product types, driven by replacement cycles in aging boiler and tank heating systems.
EPA emissions standards and OSHA thermal safety regulations shape product design requirements for US-manufactured tubular heaters, particularly in petrochemical and food processing installations. The EU Ecodesign Directive and REACH chemical compliance frameworks constrain material selection and energy efficiency thresholds for equipment sold into European industrial markets. Stakeholders must monitor evolving efficiency mandates and material certification requirements as procurement criteria shift toward lifecycle cost optimization rather than upfront capital expenditure.
Market Dynamics
Precision thermal control requirements in pharmaceutical bioprocessing and chemical synthesis are compressing replacement cycles for legacy heating infrastructure across industrial manufacturing facilities.
Growth Catalysts
- EU Ecodesign Directive compliance mandates:Industrial operators in Germany and France face retrofit deadlines for energy-intensive process equipment, accelerating replacement demand for high-efficiency tubular heater systems.
- Stainless steel sheath corrosion resistance:Food and beverage processors specify 316L and Incoloy 800 grades to meet FDA sanitation requirements, expanding premium material adoption.
- Modular immersion configurations:Tank and vessel heating applications favor flanged heater assemblies with integrated thermocouples for reduced installation complexity.
Market Restraints
- Nickel-chromium alloy supply concentration:Specialty wire coil production clusters in Chinese and German metallurgical facilities, exposing buyers to raw material availability constraints.
- Magnesium oxide insulation purity standards:REACH chemical compliance frameworks restrict low-grade MgO sourcing, elevating input costs for European-manufactured heaters.
- Infrared radiant panel substitution:Space heating applications in warehousing and commercial facilities increasingly specify quartz tube alternatives, constraining air-heating tubular element demand.
Strategic Opportunities
- India pharmaceutical manufacturing expansion:CDSCO regulatory harmonization and PLI scheme incentives attract bulk drug production investment, creating process heating equipment demand in Maharashtra and Gujarat clusters.
- Electrification of steam systems:Industrial decarbonization mandates in the Netherlands and Denmark favor direct electric immersion heaters over fossil-fired boiler retrofits.
- Integrated IoT temperature control:Convergence of resistance heating elements with wireless sensor networks enables predictive maintenance contracts for chemical processing operators.
Industry Challenges
- ASME Section VIII pressure vessel certification:Third-party inspection timelines extend 12-16 weeks for flanged heater assemblies, compressing project delivery schedules.
- Legacy 480V three-phase integration:Retrofit installations in aging US petrochemical facilities require custom terminal housing configurations to match obsolete electrical infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tubular Heater Market |
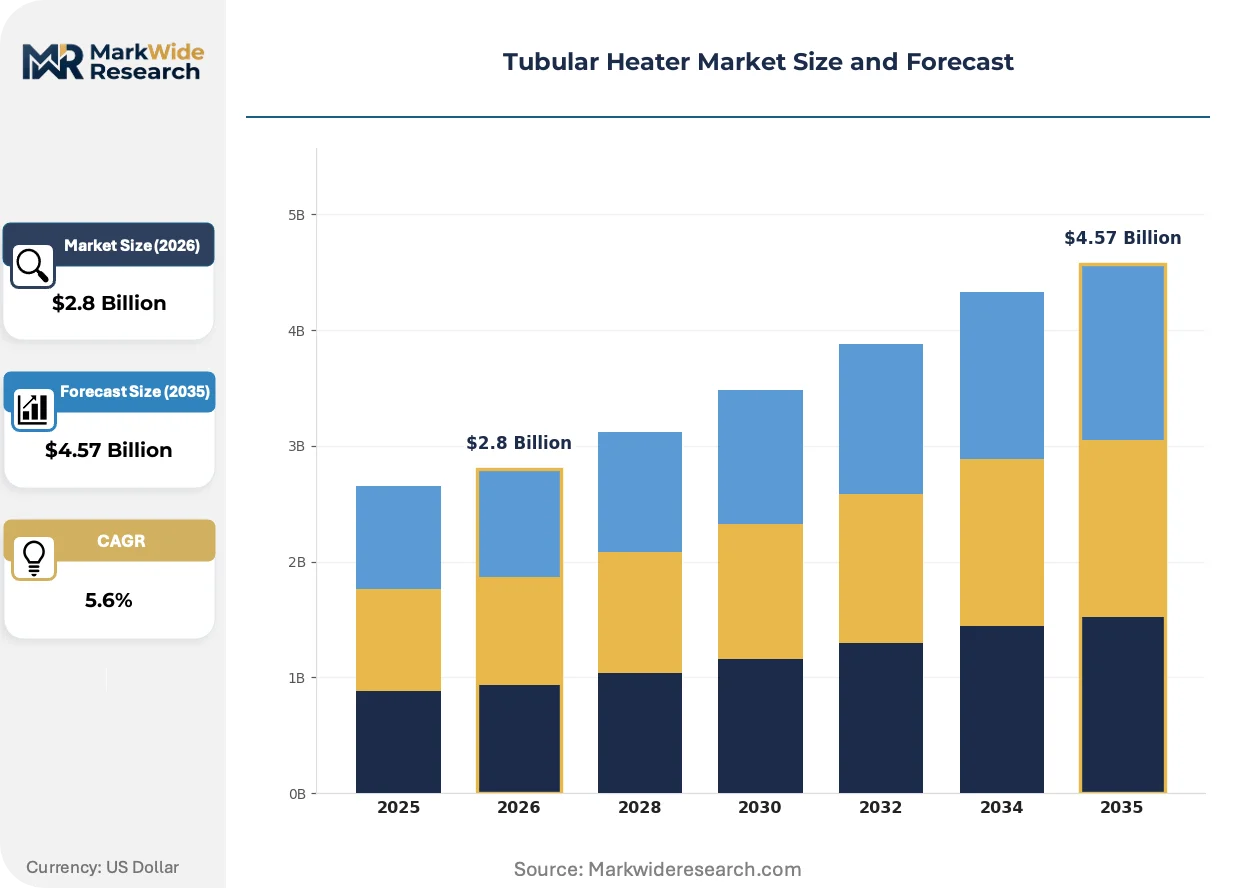
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.57 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Tubular, Immersion, Flanged, Customized Material: Stainless Steel, Copper, Incoloy, Aluminum Installation: Surface Mount, Wall Mount, Ceiling Mount, Portable Application: Industrial Heating, Food Processing, HVAC, Process Heating |
| Companies Covered | Watlow, Chromalox, Tempco Electric Heater Corporation, Omega Engineering, Backer Hotwatt, Wattco, Tutco Heating Solutions Group, Indeeco, NIBE Industrier AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tubular Heater Market Evolving Landscape
Digital thermal management architectures are displacing analog control systems across process heating applications, enabling real-time sheath temperature monitoring and automated power modulation.
Cartridge-style tubular heaters with distributed heating zones is decentralizing temperature control from centralized PLC systems to edge-mounted solid-state relays. Semiconductor fabrication facilities in South Korea and Taiwan adopt zoned immersion configurations for ultra-pure water heating. This architecture eliminates hot spots and reduces thermal cycling fatigue in high-purity process streams.
REACH SVHC candidate list expansion is tightening material disclosure requirements for magnesium oxide insulation and ceramic end seals. European chemical processors now demand full material composition documentation to avoid supply chain disruption. Stainless steel sheath suppliers in Italy and Spain are accelerating third-party toxicology assessments to maintain market access.
Lifecycle cost contracting is displacing upfront capital purchase models among multinational chemical operators. Engineering-procurement-construction firms in Germany now specify 15-year total cost of ownership guarantees for process heating systems. This shift compresses supplier margins while rewarding manufacturers with verified mean-time-between-failure data and regional service networks.
Tubular Heater Market Segmentation
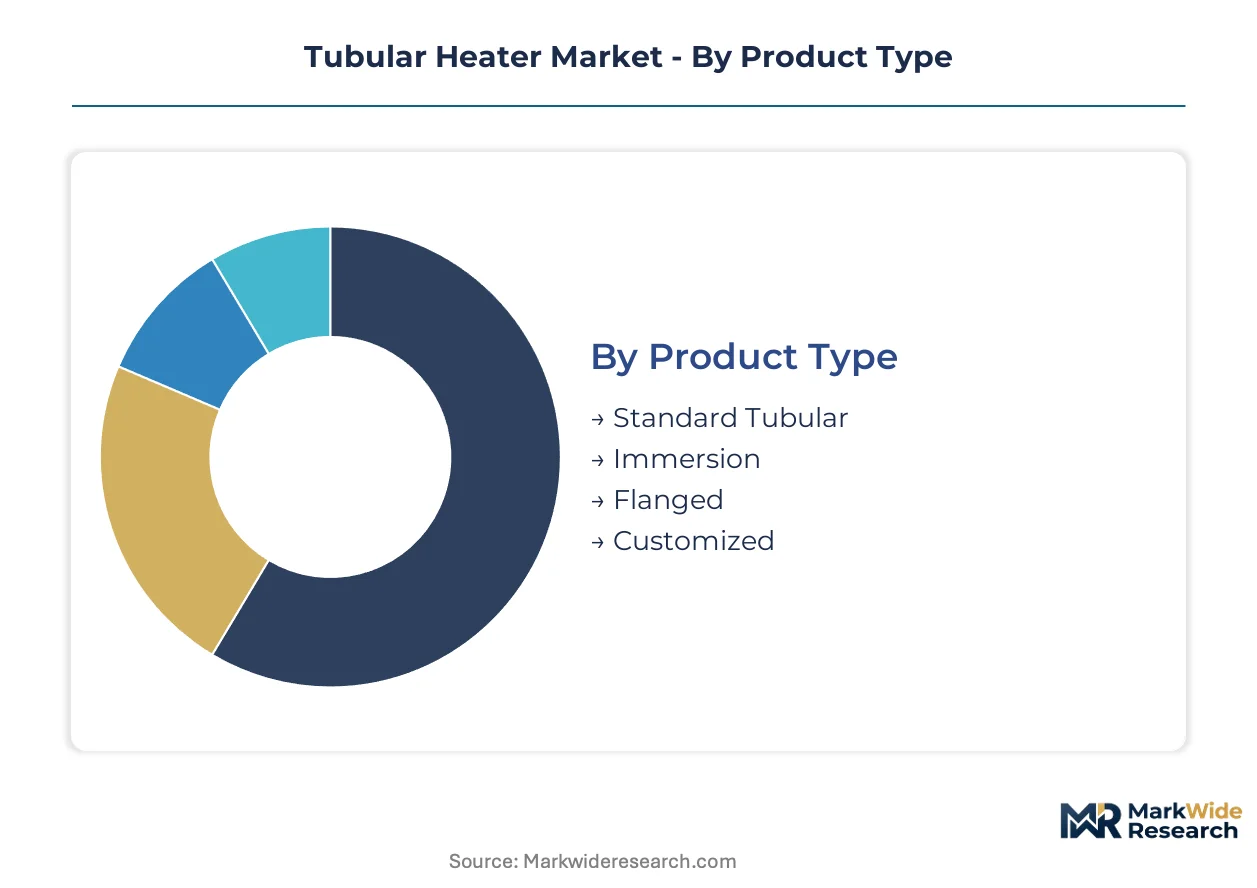
Tubular heater procurement decisions pivot on thermal load specifications, installation constraints, and regulatory compliance requirements across process industries. Segmentation reveals where engineering margins concentrate and which configurations command premium positioning.
Product Type:
Sheath geometry and terminal configuration define thermal transfer efficiency and maintenance accessibility in industrial deployments.
- Standard Tubular:Straight or bent wire-coil elements in magnesium-oxide-compacted sheaths serve general-duty air and surface heating. Chemical processors in Germany specify these for drying oven retrofits under EU Ecodesign Directive efficiency mandates.
- Immersion:Hairpin or U-bend configurations with sealed terminal housings submerge directly into tanks and vessels. Food processors specify 316L stainless immersion assemblies for clean-in-place compliance with FDA sanitation requirements.
- Flanged:Bolted mounting plates integrate multiple elements for high-kilowatt boiler and tank heating systems.
- Customized:Application-specific bend radii, terminal orientations, and sheath lengths address non-standard vessel geometries.
Standard tubular leads on scale; immersion leads on momentum.
Material:
Sheath alloy selection balances corrosion resistance against thermal conductivity and unit economics.
- Stainless Steel:304 and 316L grades dominate food, pharmaceutical, and chemical processing where chloride resistance and surface finish matter. Maharashtra pharmaceutical clusters specify 316L for US FDA-compliant bulk drug manufacturing equipment.
- Incoloy:Nickel-iron-chromium alloys (800/840 series) withstand oxidizing and carburizing atmospheres up to 870°C. Petrochemical crackers in Texas specify Incoloy 800 for process heater tubes exposed to sulfur-bearing hydrocarbons.
- Copper:High thermal conductivity suits water heating and low-temperature fluid applications.
- Aluminum:Lightweight sheathing serves air-heating and defrost applications where weight reduction matters.
Stainless steel dominates volume; Incoloy captures margin.
Installation:
Mounting topology determines heat distribution patterns and accessibility for preventive maintenance.
- Surface Mount:Clamp or bracket attachments to flat or curved metal surfaces conduct heat into platens, dies, and molds. Michigan automotive toolmakers specify surface-mounted cartridges for injection mold temperature control.
- Wall Mount:Finned or unfinned elements in protective enclosures heat commercial and industrial spaces.
- Ceiling Mount:Downward-radiating configurations serve warehousing and high-bay manufacturing facilities.
- Portable:Self-contained units with integral controls provide temporary or supplemental heating.
Surface mount anchors industrial demand; portable serves spot-market needs.
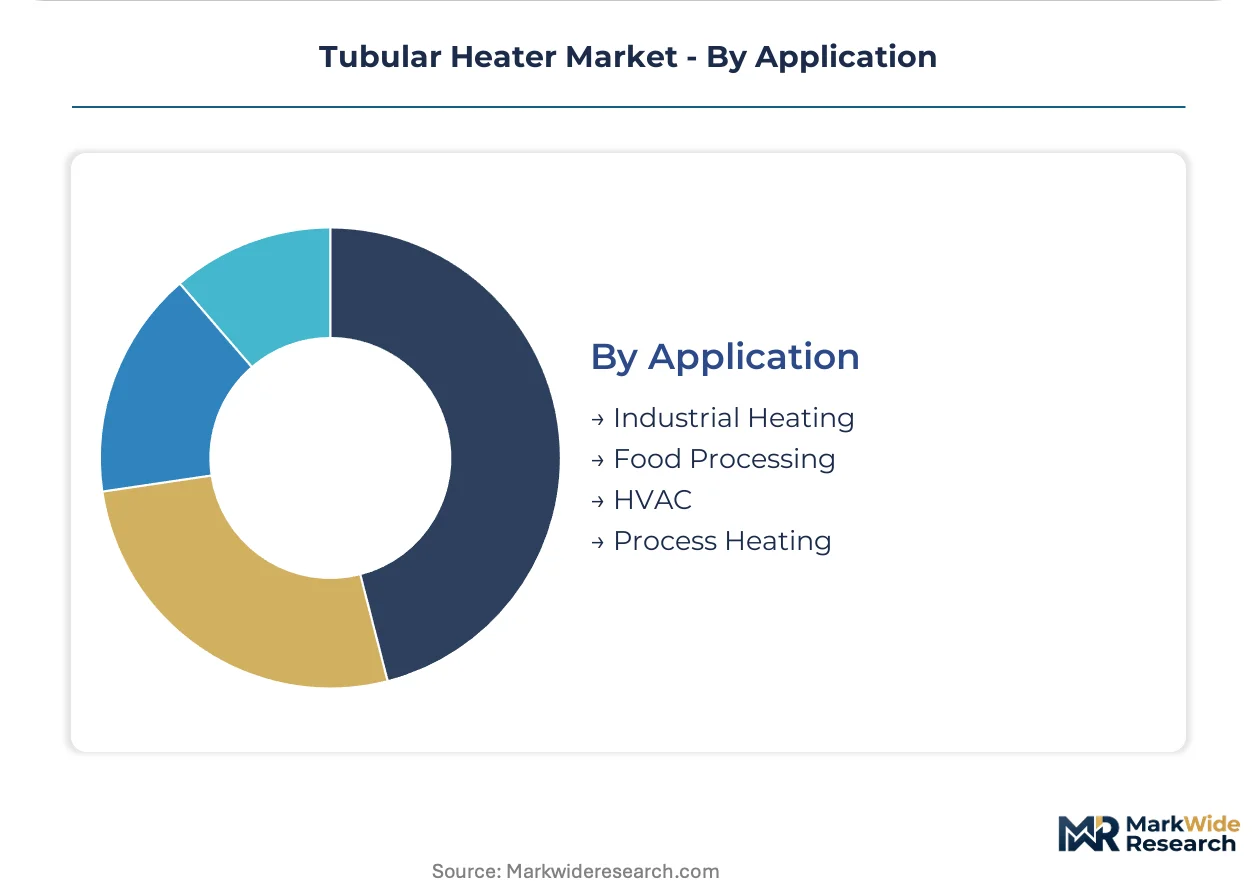
Application:
End-use thermal requirements dictate watt density, sheath material, and control architecture specifications.
- Process Heating:Chemical synthesis, distillation, and reaction vessel heating demand precision temperature control within ±1°C. Netherlands chemical operators specify direct electric immersion heaters to replace fossil-fired steam systems under national decarbonization mandates.
- Food Processing:Pasteurization, sterilization, and clean-in-place systems require FDA-compliant surface finishes and sanitary connections. Wisconsin dairy processors specify 3A-certified flanged immersion heaters for HTST pasteurization lines.
- Industrial Heating:General-purpose plant heating, freeze protection, and equipment warming applications.
- HVAC:Air duct and hydronic system heating for commercial and institutional buildings.
Process heating commands premium engineering; food processing drives replacement velocity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany pioneered precision process heating engineering during the post-war industrial reconstruction, establishing technical standards that shaped tubular heater design across European chemical and pharmaceutical manufacturing.
Germany
Mittelstand manufacturers in the Ruhr and Bavaria regions are retrofitting aging boiler systems with high-efficiency flanged immersion heaters. The EU Ecodesign Directive mandates energy-intensive equipment replacements by 2027, accelerating procurement cycles. Stuttgart-area automotive toolmakers specify surface-mounted tubular elements for injection mold temperature control systems.
United States
Petrochemical operators along the Texas Gulf Coast demand Incoloy-sheathed heaters for sulfur-bearing hydrocarbon processing. EPA emissions standards and OSHA thermal safety regulations constrain material selection and installation protocols. Houston-area engineering-procurement-construction firms now specify 15-year total cost of ownership guarantees for process heating systems.
China
Semiconductor fabrication facilities in Shanghai and Hefei are adopting zoned immersion configurations for ultra-pure water heating. The country's dual carbon goals are pressuring industrial operators to electrify steam systems previously fired by coal. Jiangsu province chemical clusters are sourcing REACH-compliant magnesium oxide insulation to maintain European export market access.
India
Pharmaceutical bulk drug manufacturers in Maharashtra and Gujarat are expanding cleanroom-grade heating infrastructure under CDSCO regulatory harmonization. The PLI scheme attracts investment into active pharmaceutical ingredient production. Mumbai and Ahmedabad clusters specify 316L stainless steel immersion assemblies for US FDA-compliant manufacturing equipment.
Netherlands
Chemical processors in Rotterdam and the Chemelot industrial park are replacing fossil-fired steam boilers with direct electric immersion heaters. National decarbonization mandates favor electrification over natural gas retrofits. Eindhoven-region engineering firms are integrating IoT temperature control architectures into modular heater configurations for predictive maintenance contracts.
Tubular Heater Market Competitive Landscape
The competitive structure tilts toward vertically integrated specialists with captive sensor and control electronics capabilities. Market concentration remains moderate, with tier-one players commanding premium positioning in precision process applications while regional fabricators compete on custom engineering responsiveness. Two strategic archetypes dominate: integrated thermal solution providers combining heater and sensor architectures, and rapid-turn custom configurators competing on engineering cycle times. Competitive moves center on backward integration into magnesium oxide insulation supply and geographic expansion through regional service network establishment.
Among North American integrated manufacturers, Watlow and Chromalox exemplify the vertically integrated archetype, with the former representing premium positioning in precision process applications and the latter anchoring heavy industrial segments through manufacturing scale. Tempco Electric Heater Corporation occupies a position within the rapid-turn custom configuration tier, competing on engineering responsiveness rather than production volume. These three players illustrate the market's bifurcation between scale-driven standardization and specialization-driven customization.
| Leading Market Players |
|---|
| Watlow |
| Chromalox |
| Tempco Electric Heater Corporation |
| Omega Engineering |
| Backer Hotwatt |
| Wattco |
| Tutco Heating Solutions Group |
| Indeeco |
| NIBE Industrier AB |
| Others |
Value Network & Pricing Analysis
German Mittelstand chemical processors concentrate procurement authority for high-efficiency flanged immersion heaters, compressing supplier margins through lifecycle cost contracting rather than transactional spot purchasing.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates Incoloy-sheathed precision systems from 316L stainless immersion assemblies and commodity-grade straight tubular elements. Price differentiation rests on REACH compliance certification and integrated IoT control architectures. Cost compression in the standard tier is intensifying because magnesium oxide insulation purity requirements elevate input costs. Food processors in Wisconsin demonstrate the highest price sensitivity due to thin margins in dairy pasteurization equipment, while semiconductor fabs in Taiwan accept premium positioning for zoned ultra-pure water heating configurations.
Supply Chain Analysis
Dual-sourcing mandates from Rotterdam chemical operators and Maharashtra pharmaceutical clusters require qualified suppliers in both Germany and China for nickel-chromium wire coil feedstock. Raw material dependencies center on Chinese magnesium oxide insulation, German specialty alloy production, and Italian stainless steel sheath fabrication. Single-source vulnerability concentrates in REACH-compliant MgO purification capacity, where European regulatory restrictions constrain qualified supplier pools. Distribution runs through engineering-procurement-construction firms in Germany and direct OEM relationships in the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between EU Ecodesign Directive compliance costs in Germany and PLI scheme manufacturing incentives in India, creating divergent landed cost structures for identical heater specifications.
For Market Incumbents: Cement regional service network density in the Netherlands and Denmark to capture electrification retrofit cycles replacing fossil-fired steam systems. Backward integration into magnesium oxide insulation supply buffers REACH SVHC disclosure requirements. Incumbent positioning faces pressure from infrared radiant panel substitution in warehousing applications. For New Entrants and Emerging Players: EU Ecodesign Directive in Germany opens a window for modular immersion configurations with integrated thermocouples targeting 2027 retrofit deadlines. White-space concentrates in India pharmaceutical bulk drug manufacturing clusters under CDSCO harmonization. A rapid-turn custom engineering model competing on specification responsiveness rather than production scale offers the most penetrable entry angle. For Investors and Strategic Acquirers: Industrial decarbonization-focused private equity is the most active acquirer in this space, consolidating regional fabricators with captive sensor capabilities. Long-term viability hinges on predictive maintenance contract attach rates and verified mean-time-between-failure databases. Watch for ASME Section VIII certification backlog duration as the inflection signal for capacity-constrained premium pricing power.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into MgO Insulation | Captive supply of REACH-compliant magnesium oxide insulation secures European market access against ECHA SVHC restrictions. |
| Regional Service Network Establishment | Localized maintenance capabilities in Rotterdam and Chemelot industrial parks enable predictive maintenance contract capture. |
| Integrated IoT Temperature Control Launch | Wireless sensor convergence with resistance heating elements creates recurring revenue streams for chemical processors. |
| Joint Venture with Indian Fabricators | PLI scheme partnerships in Maharashtra and Gujarat address CDSCO-compliant pharmaceutical equipment demand. |
| Certification Investment in ASME Section VIII | Third-party pressure vessel accreditation compresses 12-16 week inspection timelines for flanged heater assemblies. |
Research Methodology
Direct dialogue with plant engineers at chemical processing facilities, procurement leads at pharmaceutical OEMs, maintenance directors in food manufacturing, and thermal systems integrators anchored qualitative findings. Secondary validation drew from ECHA REACH registration databases, EU Ecodesign Directive implementation reports, SEC filings of listed heating equipment manufacturers, and customs trade data for nickel-chromium alloy imports. Bottom-up demand modeling across installation configurations and top-down industrial expenditure analysis were triangulated to cross-verify volume estimates.
Bottom-up segmentation modeling tracked sheath material grades, product geometries, and application verticals across the analysis window. The analytical framework incorporated watt density specifications, corrosion resistance requirements, and regulatory compliance tiers as forecast inputs. CAGRs were derived from replacement cycle compression in aging boiler infrastructure and electrification mandate adoption curves in European chemical processing.
Revisions become necessary when nickel-chromium alloy supply disruptions, REACH SVHC list expansions, or infrared substitution acceleration in commercial heating materialize. Deviation in EU Ecodesign Directive enforcement timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
Asia-Pacific Compressor Market
HVAC Equipment
GCC Kitchen Hood Market
HVAC Equipment
Foamer Pump Market
HVAC Equipment
Industrial Exhaust System Market
HVAC Equipment
Industrial Heating Equipment Market
HVAC Equipment
United Kingdom Heating Equipment Market
HVAC Equipment
United States Heat Exchanger Market
HVAC Equipment
US Residential HVAC Systems Market
HVAC Equipment
Combustion Controls, Equipments and Systems Market
HVAC Equipment
Water Chiller Market
HVAC Equipment
India Chillers Market
HVAC Equipment
ASEAN Heat Exchanger Market
HVAC Equipment
China HVAC Field Device Market
HVAC Equipment
Europe Commercial HVAC Market
HVAC Equipment
Heating and Cooling Market
HVAC Equipment
Steam Operated Condensate Pump Market