
 Warm Air Furnaces Market | 2026-2036
Warm Air Furnaces Market Size, Share, and Industry Trends Forecast 2026-2036
Warm Air Furnaces Market Analytics
A shift from single-source to multi-source component procurement is realigning supply economics for furnace OEMs. Carrier Corporation leverages captive compressor manufacturing to control input costs across its heating portfolio. Daikin Industries, Ltd. anchors its North American position through localized assembly and refrigerant-adjacent thermal expertise. Rheem Manufacturing competes aggressively on distribution density, sustaining dealer network coverage in suburban and exurban markets.
Warm air furnaces are forced-air heating appliances that combust fuel or use electric resistance to heat air distributed through ductwork, with gas-fired models typically achieving AFUE ratings from 80% to 98.5%. These systems serve as primary space heating equipment in residential, commercial, and light industrial buildings across temperate and cold climates. Gas furnaces occupy the dominant revenue position due to lower operating costs versus electric resistance in most North American utility rate environments. Smart control systems represent the fastest-expanding segment as connected thermostats and zoning controls command premium pricing and deepen aftermarket service attach rates. Dual fuel configurations are gaining traction in markets with volatile electricity pricing, blending heat pump efficiency with furnace reliability.
DOE furnace efficiency standards and EPA regulations on NOx emissions shape product design cycles and manufacturing compliance costs. NHTSA does not regulate this equipment class, but OSHA workplace safety standards influence commercial installation practices and contractor certification requirements. Stakeholders must monitor state-level building code accelerations toward electrification mandates that could constrain gas furnace addressable markets in key jurisdictions.
Market Dynamics
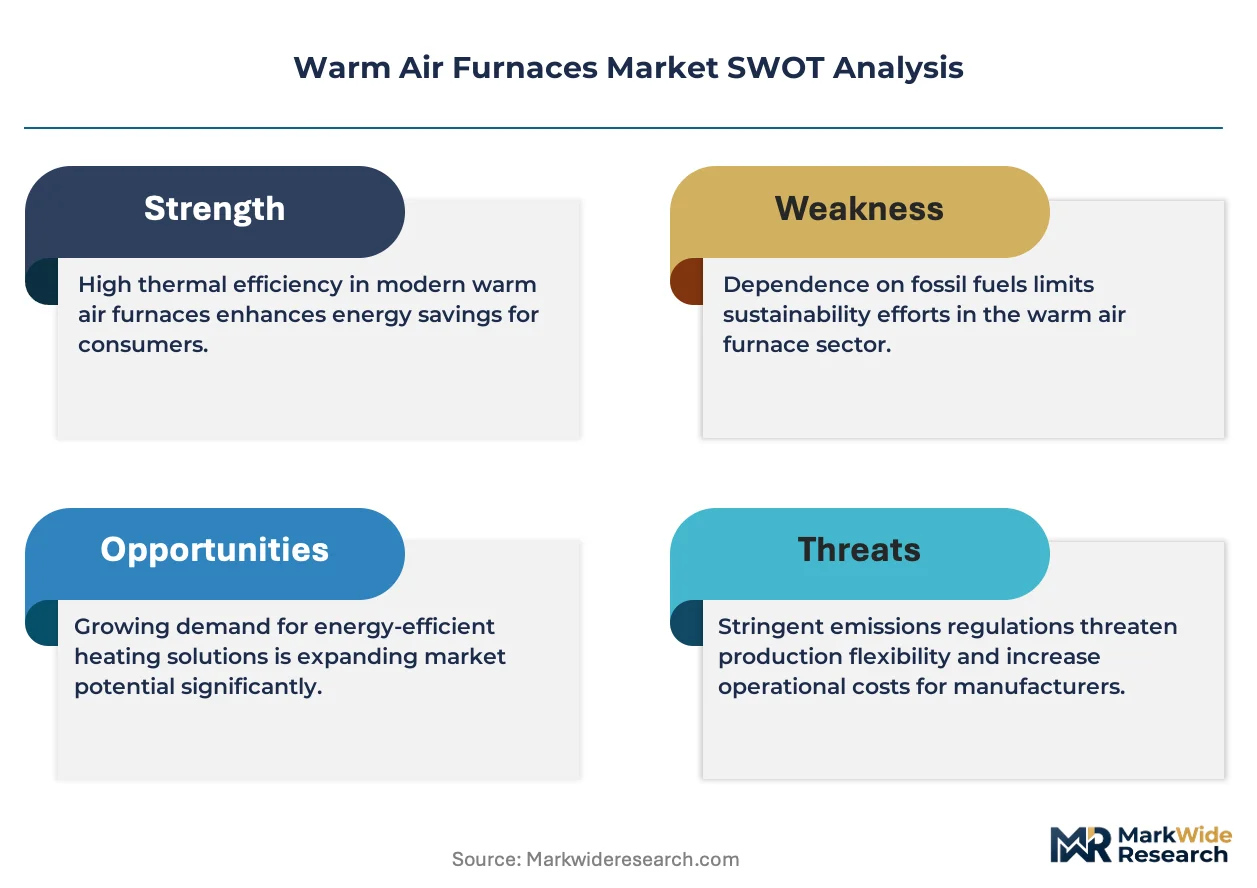
The US warm air furnace sector faces structural compression from federal efficiency mandates tightening minimum AFUE thresholds and state-level electrification codes that threaten gas-fired equipment addressable markets in California, New York, and Washington.
Growth Catalysts
- DOE Efficiency Mandates:Federal minimum AFUE standards rising to 92% in northern climates force condensing technology upgrades across replacement cycles, expanding premium product attach rates.
- Cold-Climate Housing Stock:Aging single-family homes in the Midwest and Northeast sustain replacement volume as 15-20 year equipment lifecycles expire simultaneously across installed base peaks from the 2000s construction boom.
- Smart Control Integration:Connected thermostat adoption creates service revenue expansion through remote diagnostics and predictive maintenance subscriptions tied to furnace installations.
Market Restraints
- Natural Gas Price Volatility:Henry Hub fluctuations compress operating cost advantages versus electric heat pumps, eroding the core value proposition in volatile utility rate environments.
- Electrification Code Acceleration:California Title 24 and New York Local Law 97 impose building-level carbon caps that constrain new gas furnace permitting in coastal metropolitan zones.
- Heat Pump Substitution:Cold-climate heat pumps achieving COP ratings above 2.0 at sub-zero temperatures displace dual-fuel configurations in Pacific Northwest and Northeast markets.
Strategic Opportunities
- Hydrogen-Ready Burner Development:Prototype furnaces accepting 20-100% hydrogen blends position OEMs for utility infrastructure transitions in the UK, Netherlands, and California pilot zones.
- Texas and Florida New Construction:Suburban expansion in Sun Belt states with winter heating loads sustains gas furnace penetration where heat pump defrost cycles reduce efficiency.
- IRA Tax Credit Stacking:Federal 30% efficiency tax credits combined with state rebates in Massachusetts and Colorado reduce net installed costs for 95%+ AFUE condensing units.
Industry Challenges
- HVAC Technician Shortage:EPA Section 608 certification requirements and aging installer demographics constrain service capacity during seasonal demand peaks.
- Condensate Neutralization Compliance:High-efficiency furnace drainage requirements trigger plumbing code conflicts and callback rates in jurisdictions with acidic discharge restrictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Warm Air Furnaces Market |
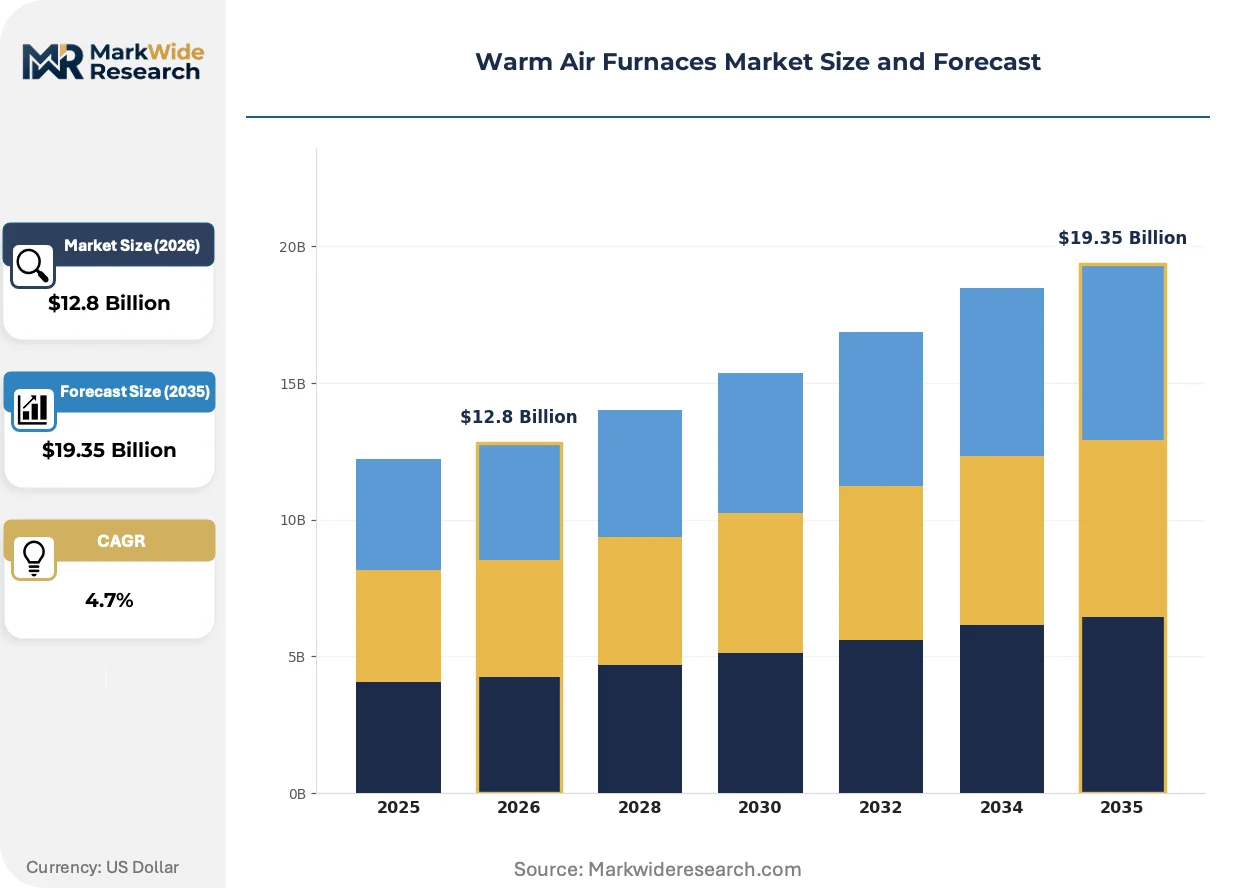
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $19.35 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gas Furnaces, Electric Furnaces, Oil Furnaces, Dual Fuel Furnaces Installation Type: Residential, Commercial, Industrial, Modular Control System: Manual, Programmable, Smart, Thermostatic Fuel Type: Natural Gas, Propane, Electricity, Oil |
| Companies Covered | Carrier Corporation, Daikin Industries, Ltd., Lennox International Inc., Ingersoll Rand, Trane Technologies, Emerson Electric Co., Johnson Controls, Inc., Rheem Manufacturing, Goodman Manufacturing, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Warm Air Furnaces Market Evolving Landscape
Modulating burner technology and connected diagnostics are compressing the performance gap between commodity 80% AFUE units and premium condensing systems, reshaping how distributors and contractors position equipment tiers.
Variable-capacity gas valves paired with ECM blower motors are overtaking single-stage furnaces in mid-market replacement segments. Multi-family developers in Minneapolis and Denver specify these units to meet utility rebate thresholds without full condensing system costs. The technology is overtaking fixed-output equipment by reducing cycling losses and enabling zoned airflow without ductwork modifications.
EPA New Source Performance Standards for residential furnaces tighten NOx emissions limits to 40 ng/J in ozone non-attainment zones. Manufacturers redesign heat exchanger geometries and flame retention heads to maintain efficiency while reducing nitrogen oxide formation. California's South Coast Air Quality Management District enforces the strictest interpretation, forcing dedicated low-NOx product lines for Los Angeles and San Diego distribution.
Contractor procurement gravitates toward distributor-managed inventory programs with guaranteed availability clauses. Independent dealers in Ohio and Pennsylvania abandon spot-market purchasing for committed volume agreements that lock input costs through heating seasons. This consolidation concentrates purchasing power among top 50 HVAC distributors, compressing margins for regional equipment wholesalers without captive installation networks.
Warm Air Furnaces Market Segmentation
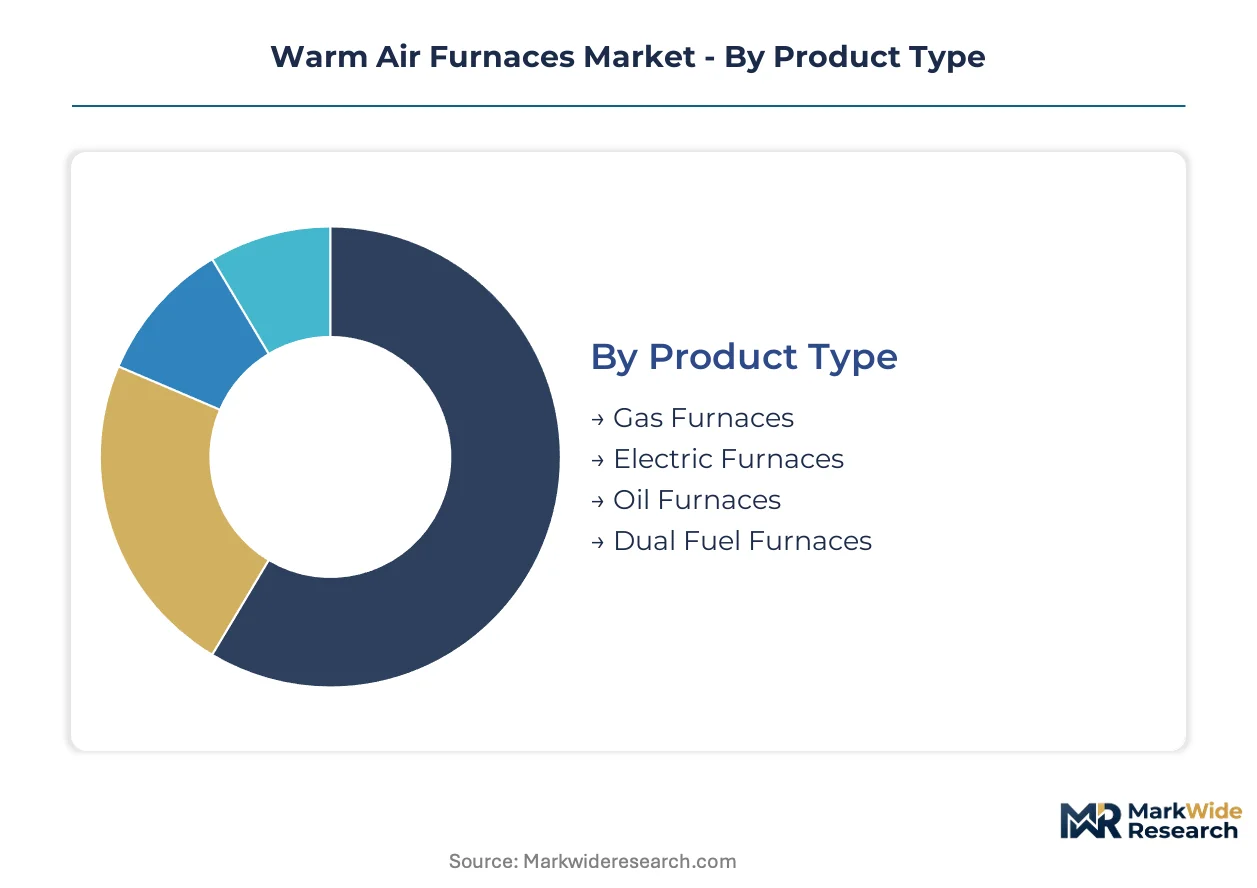
Warm air furnace segmentation reveals how equipment specifications align with distinct replacement cycles and efficiency upgrade pathways. Product type and fuel selection drive the bulk of procurement decisions, while control system tiering increasingly determines margin capture across installation channels.
Product Type:
Replacement-cycle timing varies sharply across combustion technologies, with condensing gas upgrades dominating northern climate retrofits while electric conversions accelerate in electrification-mandated jurisdictions.
- Gas Furnaces:These systems combust natural gas or propane through tubular heat exchangers, achieving AFUE ratings from 80% to 98.5% depending on condensing architecture. Demand concentrates in the United States Midwest and Northeast, where utility rate structures preserve operating cost advantages over electric resistance during 15-20 year replacement waves.
- Electric Furnaces:Resistance heating elements warm forced airflow without combustion, eliminating venting requirements and enabling simpler installation in multi-family housing. Pacific Northwest markets favor these units where hydroelectric rates compress operating penalties, though heat pump substitution now constrains growth in Washington and Oregon.
- Dual Fuel Furnaces:Hybrid configurations pair gas combustion with heat pump compressors, switching fuel sources based on ambient temperature and utility pricing.
- Oil Furnaces:Burner-atomized fuel oil serves rural markets lacking natural gas distribution infrastructure, primarily in Maine, Vermont, and eastern Canada.
Gas Furnaces sits at the top of the volume ranking, with Dual Fuel Furnaces climbing the fastest.
Installation Type:
Application scale determines equipment sizing protocols, distribution channel access, and service contract attach rates across the installed base.
- Residential:Single-family and multi-family dwellings account for the dominant share of unit volume, with replacement cycles triggered by equipment failure or efficiency upgrade incentives. Suburban construction in Texas and Florida sustains new installation demand where winter heating loads justify gas infrastructure.
- Commercial:Rooftop units and split systems serve retail, office, and hospitality applications with higher duty cycles and centralized maintenance contracts.
- Industrial:Heavy-duty heat exchangers and high-static blowers address manufacturing facilities and warehouse applications with large air volumes.
- Modular:Pre-engineered furnace modules integrate with packaged HVAC systems for rapid deployment in speculative commercial construction.
Residential commands absolute unit volume, while Modular installations are expanding most quickly in fast-track construction segments.
Control System:
Intelligence tiering now separates commodity replacements from premium installations, with connected platforms enabling recurring service revenue.
- Smart:WiFi-enabled thermostats with machine learning occupancy prediction and remote diagnostics command premium pricing. Massachusetts and Colorado rebate programs accelerate adoption by offsetting hardware costs.
- Programmable:Schedule-based temperature setbacks deliver efficiency gains without network connectivity, satisfying code requirements in cost-sensitive replacement segments.
- Manual:Basic electromechanical thermostats persist in rental housing and legacy installations where tenant turnover discourages technology investment.
- Thermostatic:Single-setpoint controls without programming capability occupy the economy tier in temporary structures and agricultural applications.
Smart controls lead value growth, with Programmable systems retaining volume leadership in mandatory-upgrade markets.
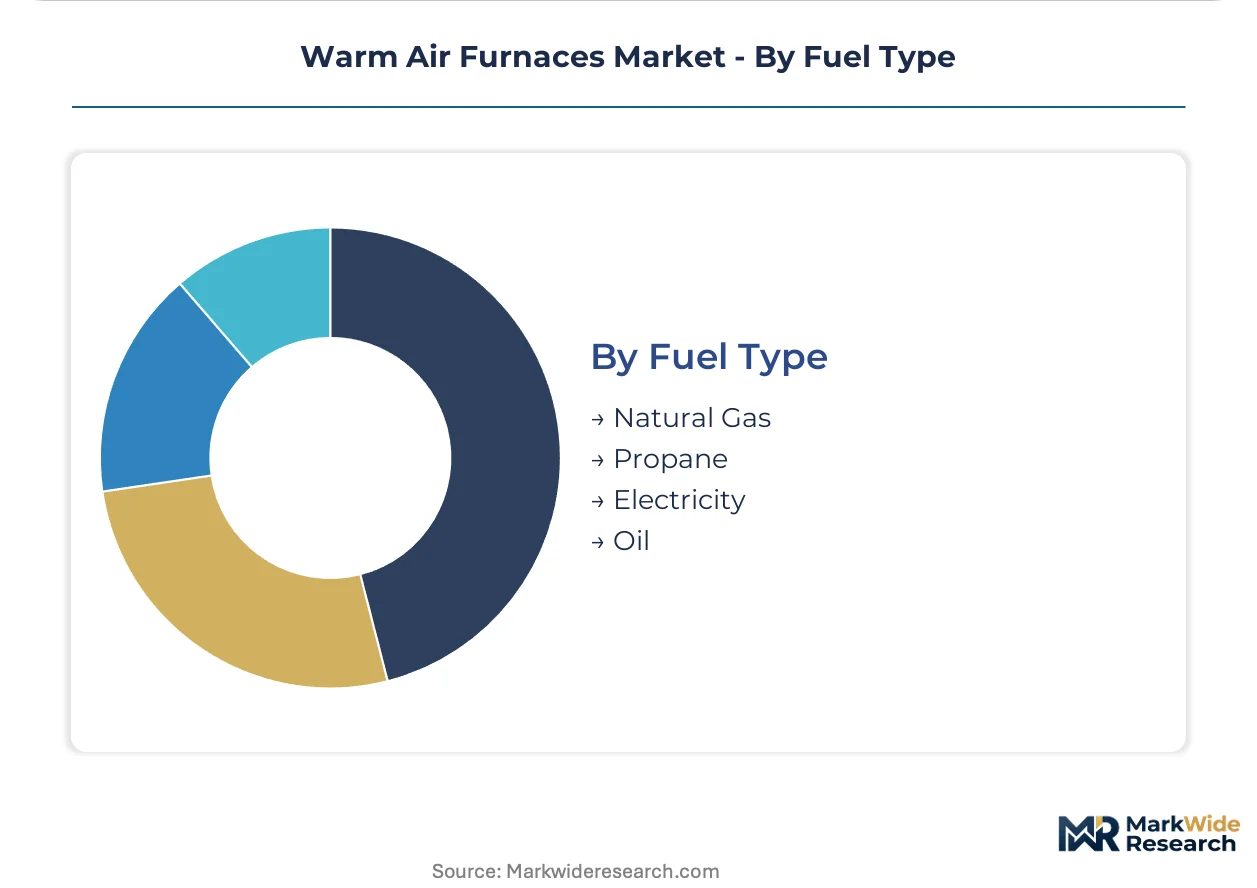
Fuel Type:
Energy source selection locks in operating economics and regulatory exposure across the equipment lifecycle.
- Natural Gas:Pipeline distribution networks in the United States deliver lowest-cost heating energy, though California Title 24 and New York Local Law 97 now constrain new permitting in coastal metropolitan zones.
- Electricity:Resistance heating faces cost disadvantages in most utility rate environments but gains traction where carbon mandates override operating economics.
- Propane:Stored fuel serves exurban and rural markets beyond gas pipeline reach, with tank ownership models affecting customer switching costs.
- Oil:Delivered fuel retains niche position in legacy heating markets, subject to price volatility and storage tank replacement regulations.
Natural Gas dominates installed capacity, though Electricity is gaining share fastest in electrification-priority jurisdictions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory cost-of-compliance gaps are redistributing furnace manufacturing capacity across jurisdictions with divergent efficiency mandates and carbon pricing regimes. OEMs migrate final assembly toward markets with deferred electrification timelines while maintaining component sourcing from established industrial clusters.
United States
Midwest and Northeast housing stock sustains replacement demand as 2000s-era furnaces expire across synchronized 15-20 year cycles. DOE minimum AFUE standards rising to 92% in northern climate zones force condensing technology upgrades. Ohio and Pennsylvania distribution networks concentrate procurement through committed volume agreements with guaranteed availability clauses.
Canada
Cold-climate heating requirements preserve gas furnace penetration despite federal carbon pricing escalation. Natural Resources Canada ENERGY STAR specifications accelerate high-efficiency adoption in Ontario and Quebec retrofit markets. Alberta and British Columbia building codes impose divergent electrification timelines, fragmenting provincial addressable markets.
Germany
Building Energy Act (GEG) amendments mandate 65% renewable heating share in new construction from 2024, compressing gas furnace new-installation windows. Hydrogen-ready burner development concentrates in industrial clusters around Cologne and Düsseldorf. Bavaria retains legacy oil-to-gas conversion demand in rural districts beyond district heating reach.
Netherlands
National Heat Act timelines require 1.5 million residential heat pump installations by 2030, constraining gas furnace market trajectory. Rotterdam and Amsterdam pilot zones test 20-100% hydrogen blend compatibility in modified condensing units. Groningen field decommissioning accelerates infrastructure transition planning for appliance OEMs.
United Kingdom
Future Homes Standard 2025 prohibition on gas boilers in new construction redirects manufacturer focus toward hybrid and hydrogen-ready portfolios. Worcester and Birmingham manufacturing clusters pivot toward export markets with deferred electrification mandates. Scotland's Heat in Buildings Strategy accelerates replacement subsidies in Glasgow and Edinburgh metropolitan zones.
Warm Air Furnaces Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue adjacent thermal management and building electrification spaces. The vendor base concentrates among diversified HVAC conglomerates with captive distribution networks and refrigerant-adjacent manufacturing expertise. Three archetypes dominate: full-system integrators controlling compressor-to-furnace value chains; component specialists supplying heat exchangers and burner assemblies; and private-label assemblers serving price-sensitive replacement segments. Competitive moves center on backward integration into heat exchanger fabrication and strategic partnerships with hydrogen infrastructure developers.
Among North American diversified manufacturers, Carrier Corporation, Daikin Industries, Ltd., and Rheem Manufacturing represent distinct strategic positioning archetypes. Carrier exemplifies captive component manufacturing with internal compressor production insulating margin pressure. Daikin anchors Asia-Pacific origin supply with localized North American assembly leveraging refrigerant system expertise. Rheem occupies the distribution density vector with suburban and exurban dealer network coverage sustaining replacement-cycle capture.
| Leading Market Players |
|---|
| Carrier Corporation |
| Daikin Industries, Ltd. |
| Lennox International Inc. |
| Ingersoll Rand |
| Trane Technologies |
| Emerson Electric Co. |
| Johnson Controls, Inc. |
| Rheem Manufacturing |
| Goodman Manufacturing |
| Others |
Value Network & Pricing Analysis
Private-equity-rolled-up HVAC distributors in the United States Midwest control inventory commitment programs that lock furnace OEMs into volume-based pricing tiers, compressing margin flexibility for independent wholesalers lacking captive installation networks. This ownership concentration tightens procurement discipline across Ohio and Pennsylvania distribution hubs while channeling replacement-cycle demand toward committed-volume agreements with guaranteed availability clauses.
Pricing Analysis
Distributor margin layers absorb 18-25 points between factory gate and contractor invoice across the North American warm air furnace channel. Three-tier pricing structure across premium condensing, standard mid-efficiency, and economy 80% AFUE levels separates equipment tiers by certification grade and smart control bundling. Cost compression in the economy tier intensifies because commodity heat exchanger sourcing from Mexico faces cross-border logistics headwinds. Multi-family developers in Minneapolis and Denver exhibit highest price sensitivity, while commercial rooftop specifiers prioritize warranty length over unit cost.
Supply Chain Analysis
Regional distribution centers in Ohio, Texas, and California anchor hub-and-spoke patterns that position finished furnaces within 48-hour delivery windows of major metropolitan construction zones. Component manufacturing concentrates in Mexico, China, and the United States for heat exchanger stampings, burner assemblies, and ECM blower motors. Supply chain risk centers on single-source vulnerability for specialized condensate neutralization kits subject to California South Coast Air Quality Management District low-NOx compliance. Distribution runs through distributor-managed inventory programs with guaranteed availability clauses rather than spot-market purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The warm air furnace market offers margin expansion through condensing technology upgrades and smart control attach rates, as DOE efficiency mandates and IRA tax credit stacking shift replacement demand toward premium-tier products with higher service revenue potential.
For Market Incumbents: Deepen backward integration into heat exchanger fabrication to offset commodity steel volatility and protect margin position against private-label assemblers. Secure EPA Section 608 certification capacity through HVAC technician training partnerships to defend service attach rates during seasonal demand peaks. Prioritize hydrogen-ready burner R&D positioning for California and Netherlands pilot zones before utility infrastructure transitions accelerate. For New Entrants and Emerging Players: Capture modular furnace assembly opportunities in fast-track commercial construction segments where pre-engineered HVAC integration commands specification influence. Target Texas and Florida suburban new construction markets where heat pump defrost cycle inefficiencies preserve gas furnace penetration. Pursue direct-to-developer sales models bypassing established distributor networks in Sun Belt expansion corridors. For Investors and Strategic Acquirers: Valuations sit cheapest among regional equipment wholesalers without captive installation networks, as distributor consolidation concentrates purchasing power among top 50 HVAC distributors. Long-term viability over the next decade hinges on hydrogen-ready technology portfolios and electrification-mandate exposure diversification. Watch California Title 24 and New York Local Law 97 enforcement timelines as inflection indicators for gas furnace addressable market compression.| Strategic Initiative | Industry Significance |
|---|---|
| Hydrogen-Ready Burner Development | Positions OEMs for utility infrastructure transitions in California and Netherlands pilot zones. |
| Smart Control Platform Integration | Enables recurring service revenue through remote diagnostics tied to Massachusetts and Colorado rebate programs. |
| Backward Integration into Heat Exchangers | Insulates margin pressure from commodity steel volatility and Mexican cross-border logistics headwinds. |
| Distributor-Managed Inventory Programs | Locks procurement commitments through Ohio and Pennsylvania networks with guaranteed availability clauses. |
| Low-NOx Product Line Diversification | Meets California South Coast Air Quality Management District strictest emissions interpretation for Los Angeles distribution. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with HVAC distributor procurement managers, OEM product planning directors, EPA-certified technician training providers, and multi-family developer specification consultants with secondary validation against DOE appliance standards filings, EPA New Source Performance Standards rulemakings, and state-level building code adoption databases. Bottom-up unit shipment modeling triangulated against top-down construction permit and replacement-cycle demographic projections.
Comparable-period anchoring tied projection assumptions to synchronized 15-20 year replacement waves from 2000s-era housing construction peaks. Segmentation dimensions spanned combustion technology tier, control system intelligence level, installation application scale, and regional regulatory framework clusters. CAGRs derived from equipment lifecycle expiration curves, efficiency mandate phase-in schedules, and electrification code adoption trajectories across the modeling period. Forecast inputs incorporated Henry Hub natural gas price volatility scenarios and cold-climate heat pump COP improvement curves.
Underlying measurement precision varies by segment; smart control and dual fuel categories carry tighter precision than legacy manual-thermostat economy tiers due to rebate program reporting requirements. Forecast outputs reflect documented assumptions regarding federal tax credit continuity and state electrification timeline enforcement. Decision-makers should treat outputs as directional within the stated assumption set, recognizing that OSHA workplace safety standard revisions or NHTSA-adjacent commercial vehicle electrification spillovers could revise technician capacity and equipment substitution patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
US HVAC Systems Market
HVAC Equipment
Refrigeration and Air Conditioning Compressors Market
HVAC Equipment
Global Smart Vent Market
HVAC Equipment
Welded Spiral Heat Exchangers Market
HVAC Equipment
Shell and Tube Heat Exchangers Market
HVAC Equipment
Heating Radiator Market
HVAC Equipment
United Kingdom Heating Equipment Market
HVAC Equipment
HVAC Actuators Market
HVAC Equipment
Residential Furnaces Market
HVAC Equipment
Steam Operated Condensate Pump Market
HVAC Equipment
Recirculating Chillers Market
HVAC Equipment
Industrial Air Blower Market
HVAC Equipment
Air-Cooled Heat Exchangers Market
HVAC Equipment
Thermo Ventilators Market
HVAC Equipment
Variable Air Volume Box Market
HVAC Equipment
Air Conditioning Compressor Market