
 Global Fan Coil Unit Market | 2026-2036
Global Fan Coil Unit Market Size, Share, and Industry Trends Forecast 2026-2036
Global Fan Coil Unit Market Analysis
Commercial property developers are rotating share from speculative office builds toward data center and life-science facilities with stringent climate loads. Daikin Industries leverages captive compressor production to tighten cost positions on water-based units. Carrier Global Corporation anchors North American service infrastructure through extensive distributor networks. Gree Electric Appliances competes on manufacturing scale out of Zhuhai, sustaining export volumes into Southeast Asia and the Middle East.
A fan coil unit is a decentralized terminal HVAC device that conditions air via heat exchange between a coil—fed by chilled or heated water, refrigerant, or electric resistance elements—and a forced-air stream driven by a centrifugal or tangential fan, typically rated between 200 and 2,000 cubic feet per minute. These units serve zonal temperature control in buildings where central air handling proves inefficient or where individual room conditioning remains operationally critical. Water fan coil systems dominate installed base across mature commercial stock, while smart control integration is expanding fastest as building automation retrofits accelerate. Ceiling-mounted configurations occupy the majority of new construction specifications, though modular formats are gaining traction in data center and cleanroom applications where layout flexibility commands premium pricing.
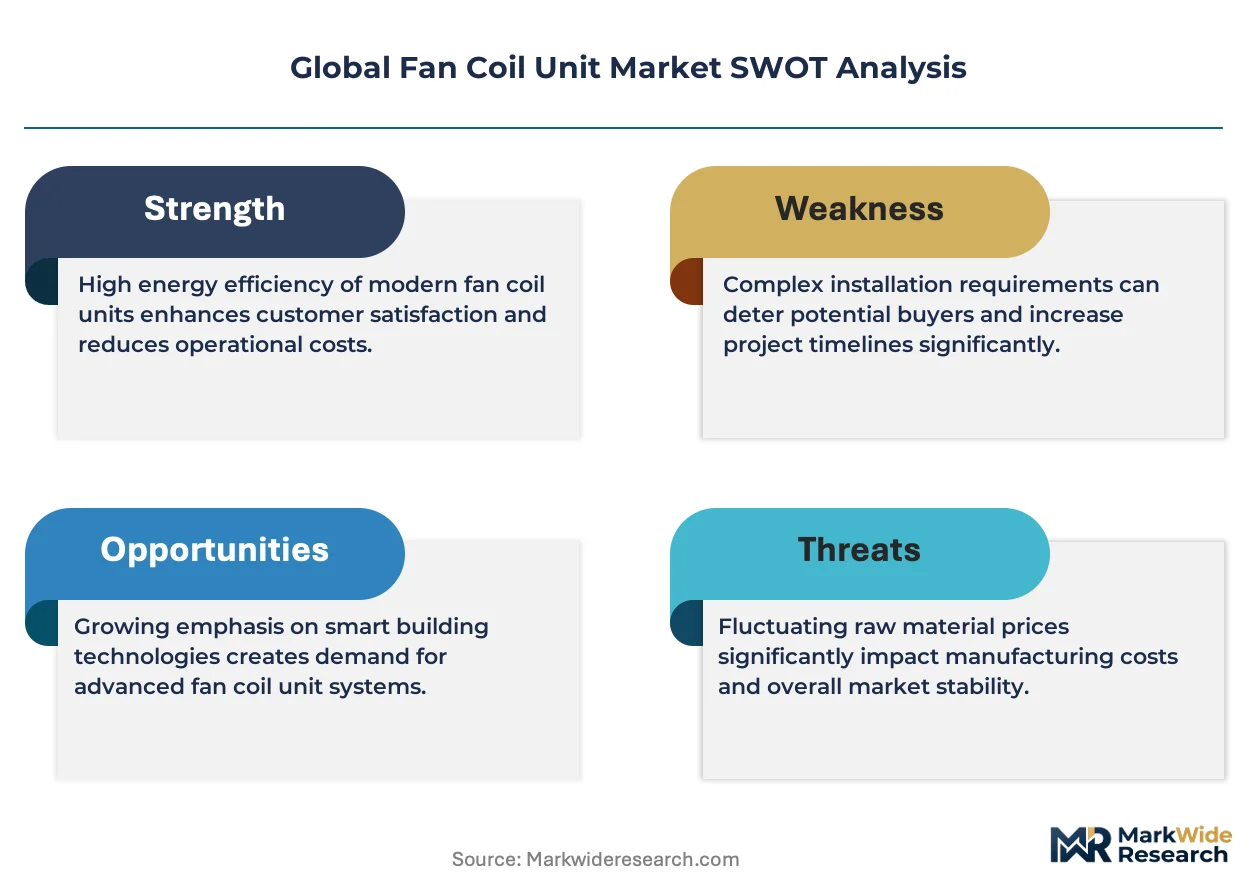
The US Department of Energy enforces minimum efficiency standards under ASHRAE 90.1 that tighten allowable fan power and coil performance coefficients, while the EU F-Gas Regulation and CE marking under the Ecodesign Directive constrain refrigerant selections and mandate recoverability disclosures. China's GB standards for unitary air conditioners, administered by SAMR, impose parallel efficiency tiers that shape export eligibility for domestic manufacturers. Stakeholders must monitor divergence between regional test procedures and certification reciprocity agreements, as misalignment threatens to fragment product platforms and inflate compliance engineering overhead.
Market Dynamics
Refrigerant-phase-down mandates across major economies are compressing replacement cycles for legacy HVAC infrastructure, forcing building owners to accelerate capital deployment toward compliant systems before regulatory deadlines lock in stranded asset risk.
Growth Catalysts
- EU F-Gas Regulation:The phasedown schedule for hydrofluorocarbons is compelling commercial property portfolios across Germany, France, and Italy to front-load equipment refresh programs ahead of 2030 reduction targets.
- Data center thermal loads:Hyperscale cloud providers in Northern Virginia and Frankfurt are specifying high-capacity chilled-water fan coil arrays to manage rack densities exceeding 50 kilowatts per cabinet.
- Smart actuator integration:BACnet and Modbus-enabled valve actuators are penetrating new construction specifications in Singapore and Dubai, enabling zone-level energy metering that satisfies green building certification requirements.
Market Restraints
- Copper coil input volatility:Raw material price swings for copper tubing and aluminum fins are compressing gross margins for original equipment manufacturers serving price-sensitive Southeast Asian markets.
- Compressor supply concentration:Captive production of rotary and scroll compressors by Japanese and Korean industrial groups limits sourcing flexibility for mid-tier European and North American assembly operations.
- Refrigerant substitution timelines:The ASHRAE 90.1 transition pathway for lower-global-warming-potential alternatives remains unresolved, freezing specification decisions for multi-year projects.
Strategic Opportunities
- India commercial construction:Office and retail stock in Mumbai, Bangalore, and Hyderabad is expanding faster than centralized chiller infrastructure, creating openings for decentralized water-based terminal units.
- Life-science facility specifications:Cleanroom and laboratory projects in Boston, Basel, and Shanghai are demanding modular fan coil configurations with HEPA filtration integration and rapid layout reconfiguration capability.
- US Inflation Reduction Act:Section 179D tax deductions for energy-efficient commercial building upgrades are improving project economics for full-system replacements in Class B office renovations.
Industry Challenges
- Controls integration complexity:Commissioning teams face interoperability failures when merging legacy pneumatic thermostats with digital building automation networks, extending project handover timelines.
- Refrigerant handling certification:EPA Section 608 technician credential requirements and parallel EU F-Gas company certification mandates are constraining available installation labor pools in multiple markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Fan Coil Unit Market |
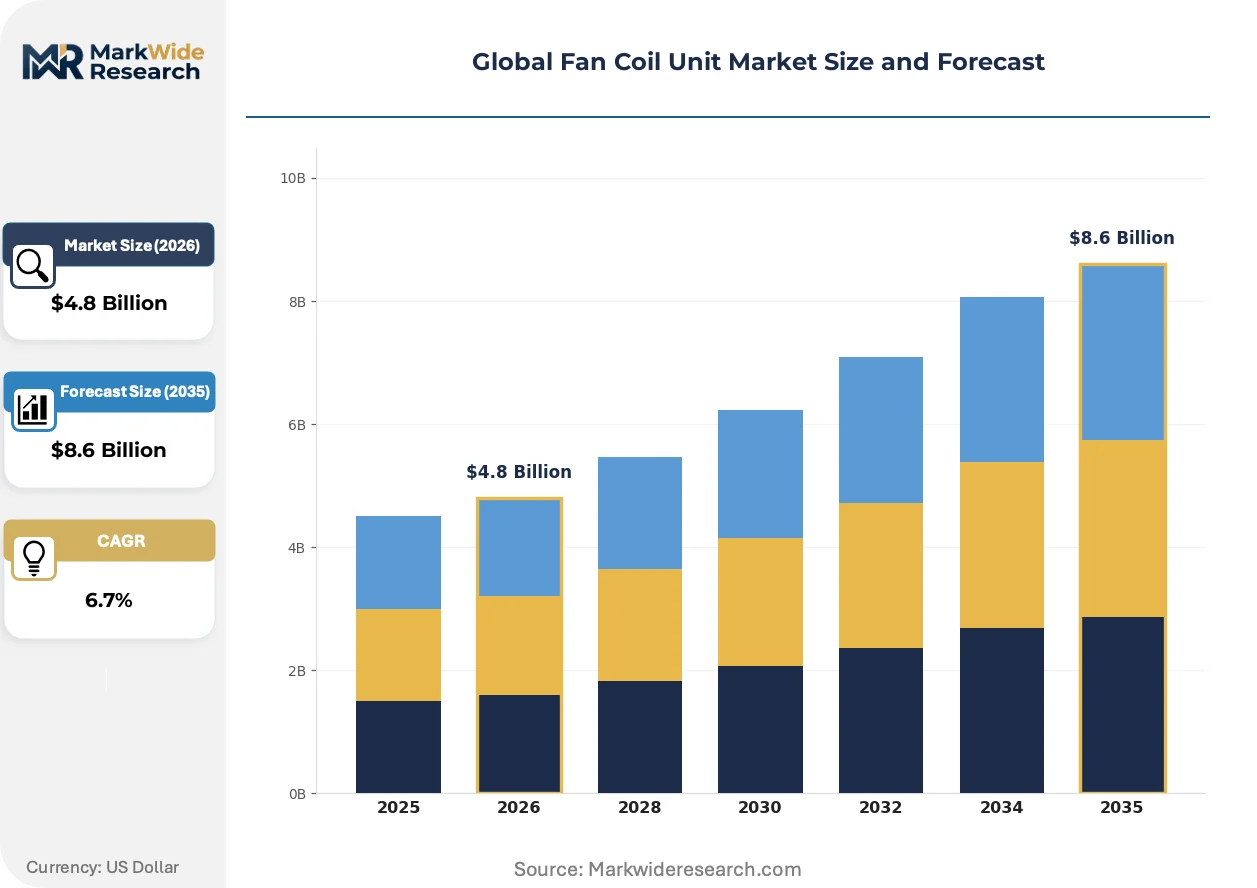
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Water Fan Coil, Electric Fan Coil, Dual Fuel Fan Coil, Air Fan Coil End User: Residential, Commercial, Industrial, Hospitality Installation Type: Wall-Mounted, Ceiling-Mounted, Floor-Mounted, Modular Control System: Manual, Digital, Smart, Centralized |
| Companies Covered | Daikin Industries, Carrier Global Corporation, Johnson Controls International, Gree Electric Appliances, Mitsubishi Electric Corporation, LG Electronics, Samsung Electronics, Trane Technologies, Lennox International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Fan Coil Unit Market Emerging Trajectories
Product architectures are splitting between premium smart-enabled systems for new construction and cost-optimized replacements for existing mechanical infrastructure, with control integration becoming the primary value differentiation vector.
Variable refrigerant flow technology is bifurcating the commercial terminal equipment landscape. VRF systems deliver simultaneous heating and cooling across zones without hydronic distribution, appealing to developers in Tokyo and Seoul pursuing reduced mechanical footprint. Large-scale hospitality and healthcare projects in these cities are specifying VRF for its piping flexibility, compressing addressable volume for traditional four-pipe fan coil configurations in premium segments.
The EU F-Gas Regulation's quota allocation mechanism is reshaping refrigerant cost structures and equipment design priorities. Manufacturers serving the European market are accelerating R&D into propane and carbon dioxide secondary loop systems to maintain product viability under tightening supply constraints. Water-based fan coil units without direct refrigerant charge are gaining specification share in German and Dutch commercial retrofits as a compliance hedge.
Service contract unbundling is altering aftermarket revenue capture for installed base operators. Building owners in London and New York are separating preventive maintenance from parts-and-labor coverage, driving OEMs to develop predictive diagnostics platforms that demonstrate measurable energy savings. This behavior is most pronounced in multi-tenant office assets where operating cost pass-through structures incentivize performance transparency.
Global Fan Coil Unit Market Segmentation
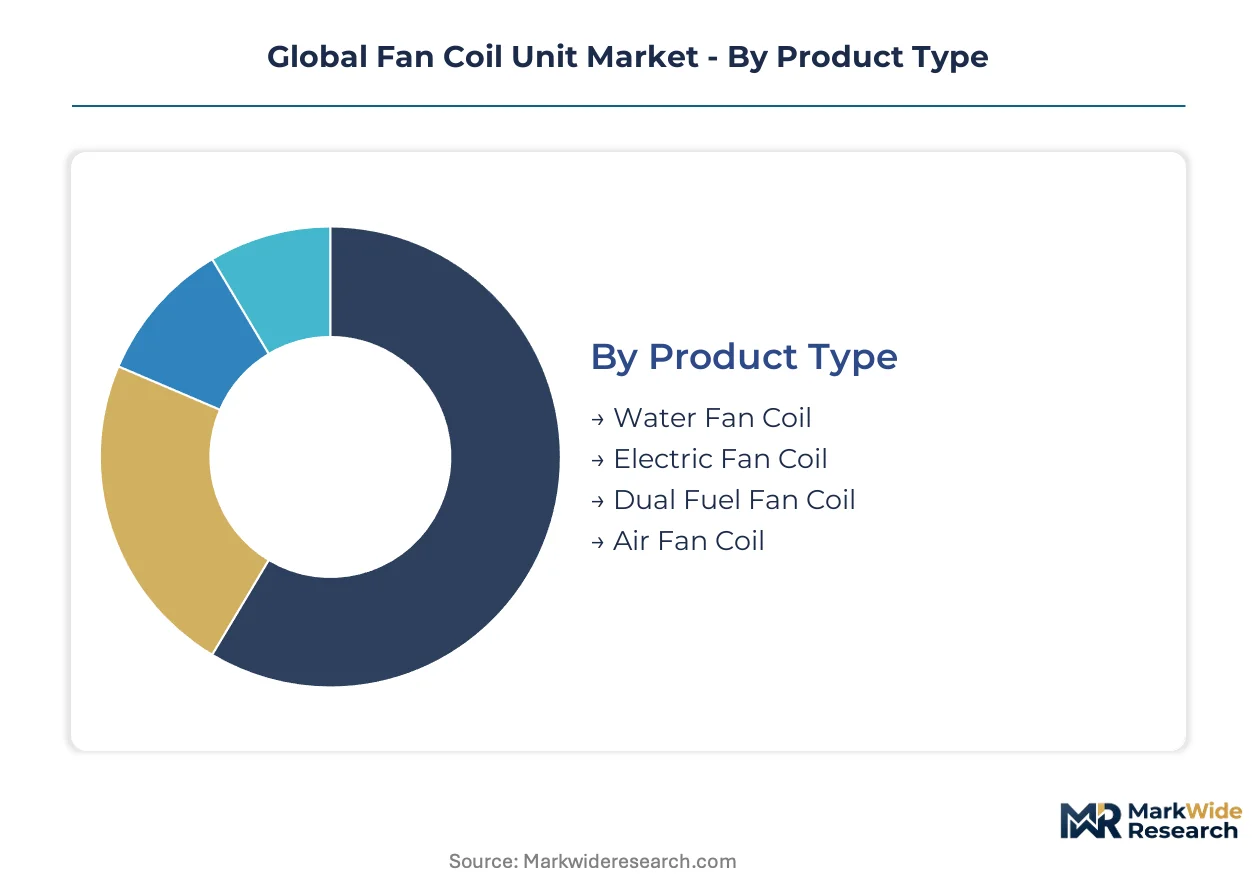
Segmentation in the fan coil unit market reveals how regulatory pressure and building automation trends fragment demand across product architectures. Specification divergence between refrigerant-based and water-based systems directly shapes procurement patterns for new construction versus retrofit projects.
Product Type:
EU F-Gas Regulation quotas and ASHRAE 90.1 efficiency standards create divergent compliance pathways for each product architecture, forcing manufacturers to maintain parallel engineering tracks.
- Water Fan Coil:These units circulate chilled or heated water through copper-aluminum coils, eliminating on-site refrigerant handling. German and Dutch commercial retrofits specify water-based systems as a hedge against tightening F-Gas quotas, with hospitality chains in Frankfurt and Amsterdam front-loading replacements.
- Electric Fan Coil:Resistance heating elements enable rapid deployment without hydronic infrastructure. Indian office developments in Bangalore and Hyderabad specify electric units where centralized chiller capacity lags construction timelines, though operating costs constrain long-term adoption.
- Dual Fuel Fan Coil:Hybrid configurations switch between electric resistance and water-based heating. These serve transitional building stock in Boston and Basel where legacy boiler infrastructure coexists with modern chiller plants.
- Air Fan Coil:Direct-expansion refrigerant systems dominate Southeast Asian residential towers in Manila and Jakarta where first-cost sensitivity outweighs efficiency premiums.
Established volume favors water fan coils; emerging adoption favors electric configurations in markets with electricity subsidy structures.
End User:
Customer procurement maturity separates price-driven residential buyers from performance-contracting commercial operators with energy transparency requirements.
- Commercial:Multi-tenant office assets in London and New York demand zone-level metering for operating cost pass-throughs. BACnet-enabled valve actuators satisfy green building certification requirements while extending project handover timelines due to controls integration complexity.
- Hospitality:Premium hotel chains accelerate renovation cycles to capture post-pandemic travel recovery. Ceiling-mounted units dominate guest room specifications, with modular formats gaining traction in back-of-house mechanical spaces requiring layout flexibility.
- Residential:High-rise developments in Mumbai and Dubai specify cost-optimized wall-mounted units where individual tenant metering remains impractical.
- Industrial:Cleanroom and laboratory projects in Shanghai and Basel demand HEPA filtration integration and rapid reconfiguration capability, commanding premium pricing for modular configurations.
Commercial contracts concentrate procurement volume; hospitality renovation cycles are climbing the fastest.
Installation Type:
Mechanical footprint constraints and ceiling plenum depth availability determine specification viability across building vintages.
- Ceiling-Mounted:Concealed ducted configurations occupy the majority of new construction specifications in Frankfurt and Northern Virginia data centers. These units integrate with suspended ceiling grids while delivering 200-2,000 CFM across zonal loads.
- Modular:Cleanroom-rated configurations with rapid layout reconfiguration capability serve life-science facilities in Boston and Basel. HEPA filtration integration commands premium pricing where contamination control is operationally critical.
- Wall-Mounted:Exposed cabinet designs dominate Southeast Asian residential retrofits where ceiling plenum access is limited.
- Floor-Mounted:Console units persist in European heritage building stock where structural constraints prohibit ceiling suspension.
Ceiling-mounted units capture new construction share; modular formats are expanding most quickly in specialized applications.
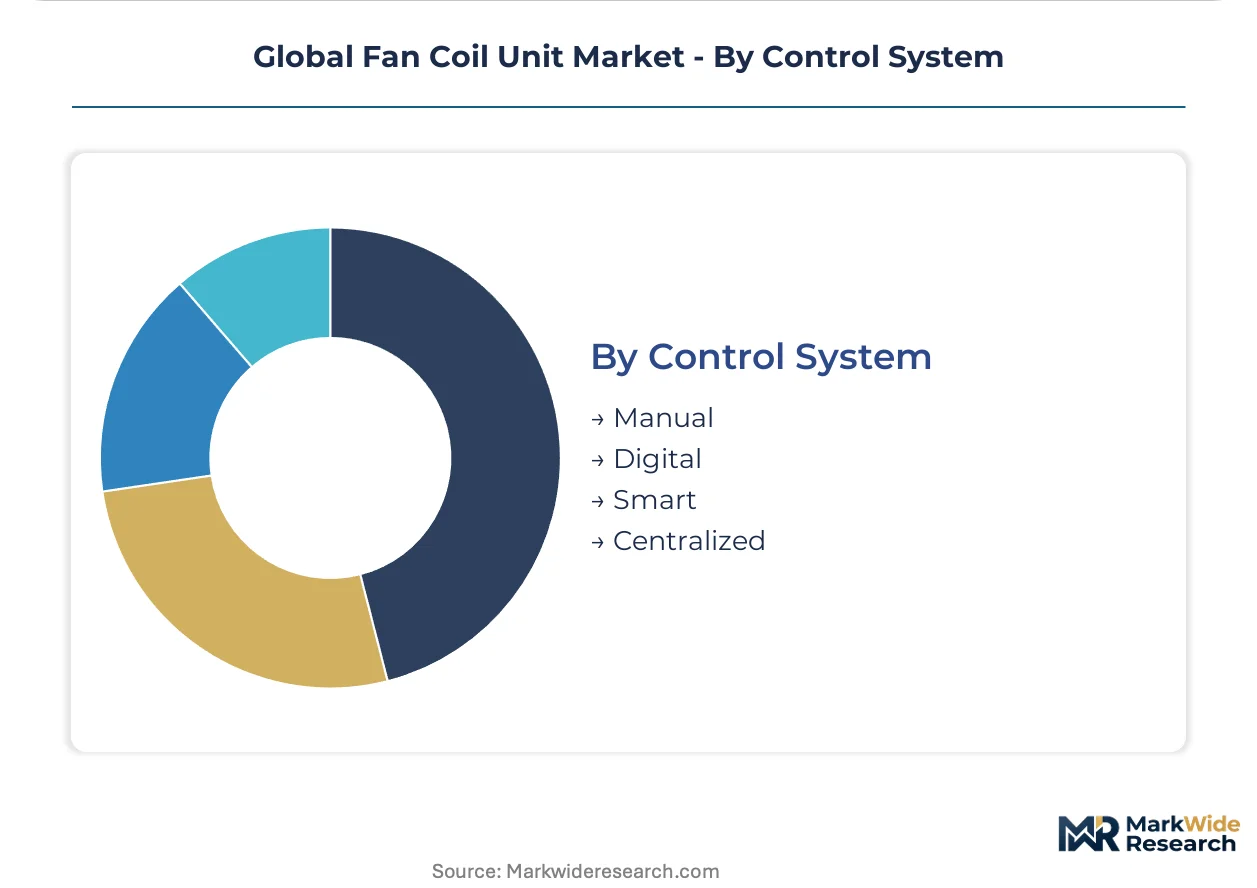
Control System:
Commissioning complexity and interoperability failures separate legacy pneumatic infrastructure from digital building automation networks.
- Smart:BACnet and Modbus-enabled actuators penetrate Singapore and Dubai new construction specifications. Zone-level energy metering satisfies green building certification requirements while demonstrating measurable savings to multi-tenant asset owners.
- Centralized:Building automation system integration enables predictive diagnostics platforms that unbundle service contracts in London and New York. OEMs capture aftermarket revenue through performance transparency rather than preventive maintenance bundling.
- Digital:Standalone electronic thermostats serve mid-market commercial retrofits where full BMS integration is cost-prohibitive.
- Manual:Pneumatic and basic electromechanical controls persist in legacy Class B office stock targeted by US Inflation Reduction Act Section 179D deductions.
Centralized controls dominate premium specifications; smart actuators are gaining share fastest as green building mandates proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese manufacturers export water-based fan coil units to Southeast Asian construction markets, while German and Dutch buyers source compliant systems ahead of tightening F-Gas quotas. Trade corridors link production clusters in Zhuhai and Shanghai to project sites in Dubai, Singapore, and Mumbai.
United States
Data center construction in Northern Virginia and hyperscale cloud expansion in Dallas-Fort Worth drive chilled-water fan coil specifications for 50-kilowatt rack densities. The Department of Energy enforces ASHRAE 90.1 efficiency standards that tighten fan power coefficients. Boston life-science clusters specify modular configurations with HEPA filtration for laboratory cleanrooms.
China
GB standards administered by SAMR impose efficiency tiers that shape export eligibility for domestic manufacturers. Yangtze River Delta production bases in Shanghai and Jiangsu supply water-based units to Indian commercial developments. Zhuhai manufacturing clusters sustain export volumes into Southeast Asia and Middle Eastern hospitality projects.
Germany
EU F-Gas Regulation quotas compel Frankfurt and Munich commercial portfolios to front-load equipment refresh programs before 2030 reduction targets. The Ecodesign Directive mandates recoverability disclosures that constrain refrigerant selections. Hospitality chains in Berlin and Hamburg accelerate renovation cycles to capture post-pandemic travel recovery.
India
Office and retail stock in Mumbai, Bangalore, and Hyderabad expands faster than centralized chiller infrastructure, creating openings for decentralized water-based terminal units. BIS certification requirements shape product eligibility for domestic procurement. Electric fan coil units serve Bangalore developments where grid infrastructure outpaces hydronic distribution timelines.
United Arab Emirates
Green building mandates in Dubai and Abu Dhabi drive BACnet-enabled smart actuator specifications for zone-level energy metering. MOHAP and local emirate-level regulators enforce performance transparency requirements for multi-tenant assets. New construction in Dubai Marina and Abu Dhabi's Al Reem Island concentrates ceiling-mounted unit demand.
Global Fan Coil Unit Market Vendor Landscape
Player mix skews toward diversified HVAC conglomerates with captive compressor production and scale-driven appliance manufacturers competing on manufacturing throughput. Structure consolidates around three tiers: premium integrated systems providers, mid-market assembly operations, and cost-optimized volume producers. Strategic moves concentrate on backward integration into compressor supply and geographic expansion through distributor network anchoring.
Among diversified Japanese industrial groups, Daikin Industries and Mitsubishi Electric Corporation represent the premium integrated tier with in-house component production. Carrier Global Corporation anchors North American service infrastructure. Gree Electric Appliances exemplifies scale-driven manufacturing from Zhuhai production bases.
| Leading Market Players |
|---|
| Daikin Industries |
| Carrier Global Corporation |
| Johnson Controls International |
| Gree Electric Appliances |
| Mitsubishi Electric Corporation |
| LG Electronics |
| Samsung Electronics |
| Trane Technologies |
| Lennox International |
| Others |
Supply Flow & Price Mechanics
Long-term offtake agreements between German hospitality chains and Zhuhai-based manufacturers lock in copper coil supply and freeze water-based unit pricing across 18-to-24-month windows. These contracts insulate procurement teams from LME copper volatility while constraining margin flexibility for mid-tier assemblers in Southeast Asia.
Pricing Analysis
Current-generation smart-enabled fan coils with BACnet integration command 35-to-50 percent premiums over prior-generation pneumatic-controlled units, while next-generation propane-loop systems remain pre-commercial. Three-tier pricing structure across premium smart-actuator, standard digital-thermostat, and economy manual-control levels stratifies procurement in Dubai green-building mandates. Cost compression in economy tiers is intensifying because Indian developers prioritize first-cost over operating efficiency. Residential buyers in Manila and Jakarta exhibit highest price sensitivity; life-science facility operators in Basel demonstrate lowest sensitivity due to contamination-control compliance requirements.
Supply Chain Analysis
China and Japan anchor global compressor and coil fabrication, with Yangtze River Delta plants feeding water-based units to Indian commercial projects and Osaka-Kobe clusters supplying rotary compressors to European assembly operations. Copper tubing from Chilean mines and aluminum fins from domestic Chinese smelters constitute primary raw material dependencies. Single-source vulnerability concentrates in Japanese captive compressor production, which limits sourcing flexibility for North American and European OEMs. Distribution runs through project-specification channels where MEP contractors in Frankfurt and Dubai control final equipment selection.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Predictive diagnostics platforms and unbundled service contracts represent a faster-expanding recurring-revenue layer than hardware shipments, as London and New York multi-tenant asset owners separate energy-performance verification from preventive maintenance coverage.
For Market Incumbents: Shield installed base relationships by embedding predictive maintenance algorithms that demonstrate measurable energy savings to building operators. Backward integration into valve actuator production reduces exposure to BACnet module supply bottlenecks. Prioritize certification investment for EU F-Gas compliance to preempt stranded asset risk in German commercial portfolios. For New Entrants and Emerging Players: Differentiate on rapid layout reconfiguration capability for life-science cleanroom applications where incumbent response times lag project schedules. Target modular fan coil specifications in Boston and Shanghai laboratory clusters where HEPA integration commands premium positioning. Pursue direct specification relationships with MEP contractors rather than distributor channel stacking. For Investors and Strategic Acquirers: Regional aftermarket service specialists with captive technician certification pools offer consolidation leverage as EPA Section 608 and EU F-Gas credential requirements constrain installation labor availability. Long-term viability hinges on software-enabled energy transparency rather than hardware manufacturing scale. Monitor divergence between ASHRAE 90.1 and EU Ecodesign test procedures as an inflection indicator for product platform fragmentation risk.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Compressor Production | Daikin Industries tightens cost positions on water-based units through captive rotary compressor supply. |
| Smart Actuator Platform Development | BACnet-enabled valve integration satisfies Dubai green building mandates for zone-level energy metering. |
| Regional Service Network Expansion | Carrier Global Corporation anchors North American aftermarket capture through extensive distributor infrastructure. |
| Propane Secondary Loop R&D Acceleration | European manufacturers hedge against EU F-Gas quota constraints with alternative refrigerant architectures. |
| Cleanroom Modular Configuration Launch | Life-science facilities in Basel and Boston command premium pricing for HEPA-integrated rapid-reconfiguration units. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of SEC 10-K HVAC segment disclosures, EU Ecodesign Directive implementation reports, and SAMR GB standard certification databases. Interviews with MEP specification engineers, commercial building maintenance directors, and HVAC distributor procurement heads informed demand-side validation. Bottom-up unit shipment estimates triangulated against top-down construction spending data across the analysis window.
Segmentation dimensions modeled include product architecture, installation type, control system sophistication, and end-use sector across the projection horizon. CAGRs derive from regression analysis of historical replacement cycles, regulatory deadline impacts, and construction pipeline data. Hyperscale data center thermal load specifications and hospitality renovation cycle acceleration served as industry-specific forecast inputs.
Material uncertainties — copper price volatility, refrigerant substitution timeline delays, and controls integration commissioning failures — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory enforcement consistency and construction permit issuance velocity. Recalibration cycles align with material shifts in EU F-Gas quota allocations and ASHRAE 90.1 standard revision schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
Underfloor Heating Market
HVAC Equipment
Variable Refrigerant Flow (VRF) System Market
HVAC Equipment
Air-Conditioning Natural Convection Refrigerator Market
HVAC Equipment
Water Softener Equipment Market
HVAC Equipment
Duct Fans Market
HVAC Equipment
North America HVAC Filter Change Service Market
HVAC Equipment
Global Snow Making System Market
HVAC Equipment
United Kingdom Commercial HVAC Market
HVAC Equipment
Middle East and Africa Commercial HVAC Market
HVAC Equipment
North America Air to Water Heat Pump Market
HVAC Equipment
Heating Radiator Market
HVAC Equipment
HVAC Centrifugal Compressors Market
HVAC Equipment
Centrifugal Chillers Market
HVAC Equipment
Warm Air Heater Market
HVAC Equipment
Hydro Chillers Market
HVAC Equipment
Water Chiller Market