
 Air Conditioner Quilt Market | 2026-2036
Air Conditioner Quilt Market Size, Share, and Industry Trends Forecast 2026-2036
Air Conditioner Quilt Market Insights
A capital-intensity divergence between integrated textile manufacturers and assembly-only vendors is bifurcating competitive returns in the air conditioner quilt supply chain. Daikin Industries leverages captive cooling technology partnerships to anchor premium positioning in climate-responsive bedding. Gree Electric Appliances sustains vertical control over compressor-to-textile coordination, reducing thermal calibration costs. Midea Group competes through modular platform designs that span multiple material grades without retooling.
An air conditioner quilt is a thermoregulated bedding product engineered with phase-change materials, moisture-wicking fibers, or conductive layers to maintain optimal skin temperature during mechanical cooling, typically specified with thermal resistance values between 0.5 and 2.0 tog for summer conditions. Cooling quilts dominate residential volume due to seasonal replacement cycles in subtropical climates, while insulating covers command margin pools from commercial buyers seeking HVAC load reduction. Microfiber and polyester blends lead material adoption for their wash durability and cost scalability, though wool variants occupy a defensible niche among hospitality buyers prioritizing natural fiber claims.
China's SAMR enforces GB standards on textile flammability and labeling that filter subscale exporters from domestic distribution, while the EU's REACH framework restricts chemical finishes on imports sold through European online retail channels. Japan's METI energy-efficiency labeling program extends to climate-control bedding, creating compliance costs that favor mid-tier producers with testing laboratory relationships. Stakeholders must monitor how dual carbon goals in China's manufacturing provinces reshape energy pricing for textile dyeing and finishing operations.
Market Dynamics
China's SAMR enforcement of updated GB textile standards is compressing manufacturing capacity toward integrated producers capable of in-house thermal calibration and phase-change material certification, eliminating assembly-only vendors from premium distribution channels.
Growth Catalysts
- Hospitality sector expansion across East Asia:Hotel chains in subtropical zones specify cooling quilts with thermal resistance ratings between 0.5 and 1.5 tog for HVAC load reduction, creating recurring replacement demand from commercial buyers.
- Phase-change material maturation:Bio-based paraffin microcapsules and salt hydrate formulations now achieve temperature regulation without petroleum-derived inputs, satisfying procurement criteria from sustainability-focused institutional buyers.
- Yangtze River Delta manufacturing concentration:OEM capacity for cooling quilts has scaled dramatically in Shaoxing and Nantong, where textile dyeing clusters benefit from captive chemical supply and shared testing infrastructure.
Market Restraints
- Petrochemical input volatility:Polyester staple fiber and polyethylene glycol prices fluctuate with crude oil benchmarks, compressing margin stability for producers lacking backward integration into polymer supply.
- Single-region supply concentration:Over 70% of phase-change material finishing capacity sits in Zhejiang province, exposing buyers to weather-related disruption and provincial energy rationing under dual carbon targets.
- REACH chemical restrictions:The EU's ECHA enforcement against certain flame retardant and antimicrobial finishes blocks direct-to-consumer exports through European online retail channels unless reformulation occurs.
Strategic Opportunities
- India's underserved commercial hospitality segment:Mid-tier hotel construction in Bengaluru and Hyderabad lacks domestic cooling quilt suppliers, creating import substitution potential for manufacturers with BIS textile labeling compliance.
- Modular platform convergence:Midea Group's approach—spanning multiple material grades without retooling—demonstrates how digital cutting and automated quilting can serve both economy and premium tiers from shared production lines.
- Japan's METI energy-efficiency labeling extension:Climate-control bedding now falls under mandatory disclosure rules, favoring mid-tier producers with established testing laboratory relationships over unverified imports.
Industry Challenges
- Thermal calibration expertise scarcity:Engineers capable of integrating phase-change material loading rates with fabric breathability specifications command premium wages, constraining R&D throughput at smaller manufacturers.
- GB standard certification timelines:SAMR textile flammability testing queues extend 4-6 months for new product submissions, delaying seasonal launch windows and inventory positioning.
- Legacy ERP integration with smart textile tracking:Batch-level traceability requirements for phase-change material sourcing strain accounting systems designed for commodity bedding production.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Air Conditioner Quilt Market |
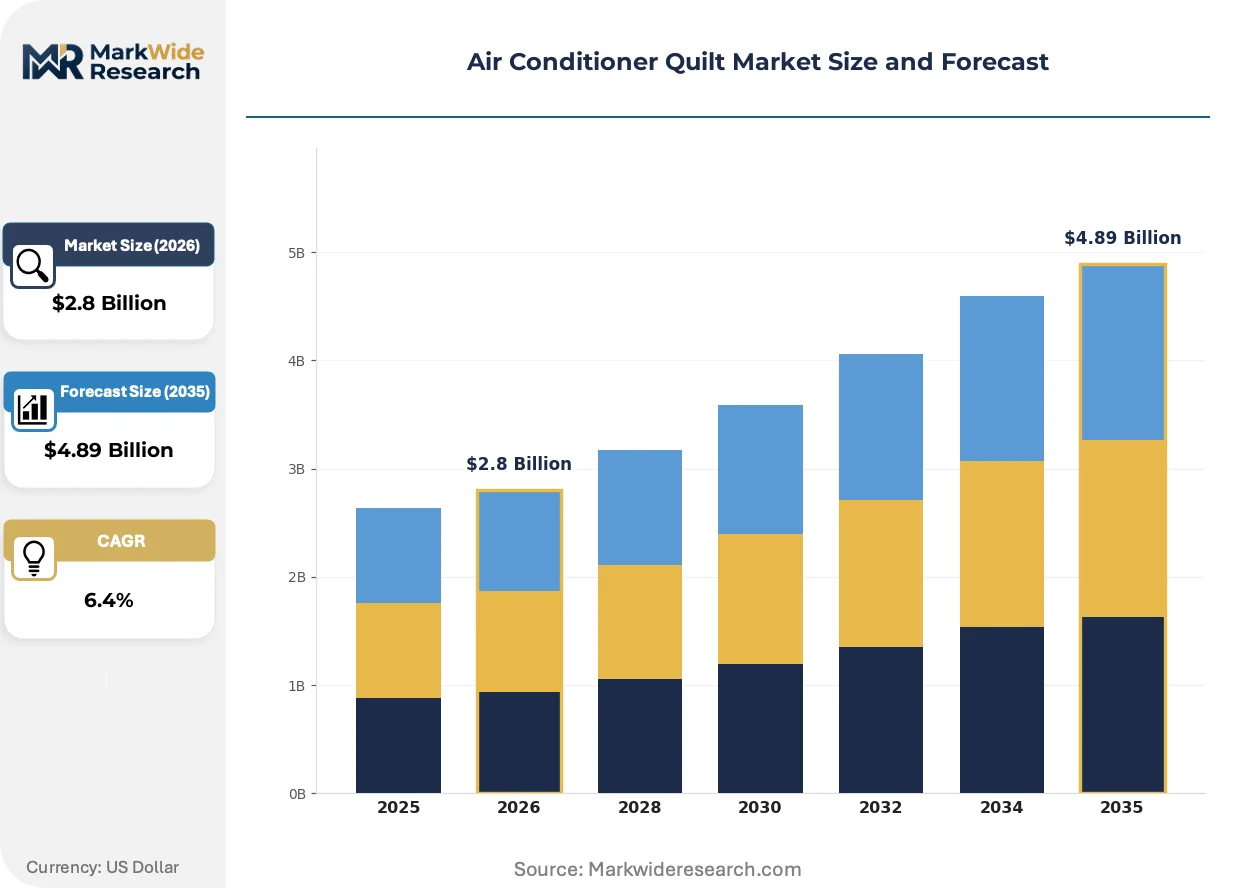
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cooling Quilts, Thermal Blankets, Insulating Covers, Weighted Quilts Material: Cotton, Polyester, Microfiber, Wool End User: Residential, Commercial, Hospitality, Institutions Distribution Channel: Online Retail, Offline Retail, Wholesale, Direct Sales |
| Companies Covered | Daikin Industries, Gree Electric Appliances, Midea Group, Carrier Global, Trane Technologies, Johnson Controls, LG Electronics, Haier Group, Mitsubishi Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Air Conditioner Quilt Market Trends and Innovations
Active cooling mechanisms and bio-responsive materials are displacing passive thermal mass approaches, while regulatory frameworks in major economies harden chemical disclosure and energy-efficiency requirements for climate-control bedding.
Conductive yarn integration—embedding silver-coated nylon or carbon fiber filaments into quilt batting—is displacing conventional moisture-wicking polyester blends in premium residential segments. Japanese and South Korean apartment dwellers with mini-split air conditioning systems adopt these products for precise temperature targeting. The technology is displacing traditional tog-rated insulation by enabling real-time thermal adjustment rather than static resistance values.
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances (PFAS) are forcing reformulation of water-repellent quilt finishes across European distribution channels. Manufacturers serving EU online retail must eliminate C6 fluorocarbon treatments or risk customs detention at Rotterdam and Hamburg. German and French buyers now prioritize OEKO-TEX Standard 100 certification over price in hospitality procurement tenders.
Direct-to-hotel procurement platforms are consolidating purchasing authority previously fragmented across property-level housekeepers and regional linen suppliers. Marriott and Hilton's centralized sustainability scorecards now specify thermal performance verification and carbon footprint disclosure for climate-control bedding. This concentration is most visible in Singapore and Dubai, where flagship properties source cooling quilts through global framework agreements rather than local textile distributors.
Air Conditioner Quilt Market Segmentation
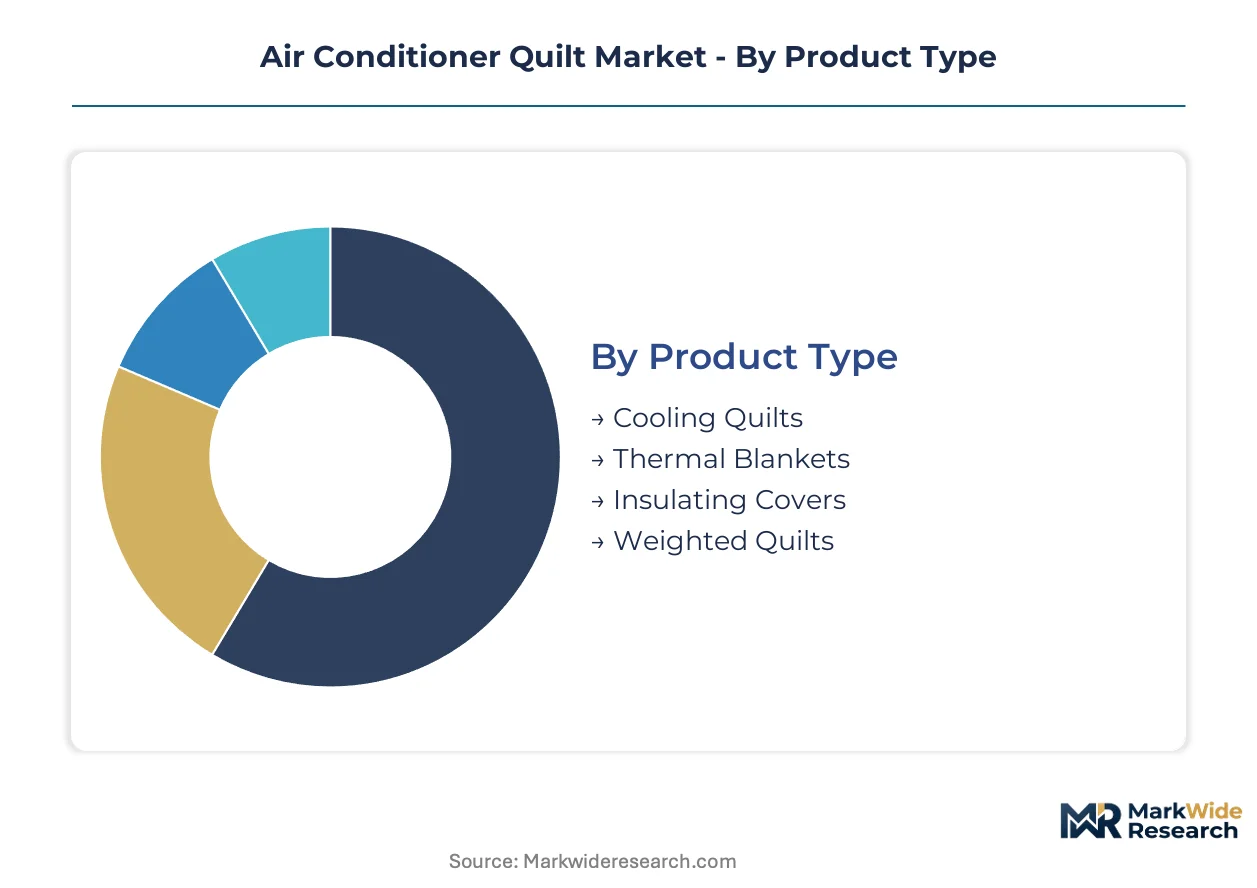
Segmentation in the air conditioner quilt market reveals how thermal performance specifications diverge across use cases, with material chemistry and distribution access determining margin capture. Buyers sort products by static thermal resistance versus active temperature modulation, creating distinct competitive arenas.
Product Type:
Substitution pressure from HVAC efficiency upgrades and smart home climate systems threatens passive thermal products most severely, while active cooling mechanisms defend niche positions.
- Cooling Quilts:Engineered with phase-change material microcapsules or moisture-wicking synthetic batting to maintain skin temperature between 28-32°C during mechanical cooling. Residential replacement cycles in subtropical East Asian climates concentrate demand, though mini-split air conditioner penetration in Japanese apartments accelerates adoption of conductive yarn variants.
- Thermal Blankets:Static insulation products relying on lofted synthetic or natural fiber batting without active temperature regulation. Hospitality procurement in Southeast Asia favors these for cost scalability, yet they face displacement from energy-efficient building codes that reduce overnight HVAC loads.
- Insulating Covers:High-loft barrier layers designed for HVAC load reduction in commercial buildings.
- Weighted Quilts:Glass bead or plastic pellet-filled bedding with incidental thermal mass properties.
Cooling quilts retain volume leadership; insulating covers hold the steepest expansion curve.
Material:
Cost tier stratification separates premium natural fiber claims from mass-market synthetic scalability, with mid-tier blends capturing hospitality contract volume.
- Polyester:Petroleum-derived staple fiber dominating mass production for wash durability and dye consistency. Yangtze River Delta dyeing clusters in Shaoxing and Nantong concentrate supply, though crude oil price volatility compresses margin stability for non-integrated producers.
- Microfiber:Denier-split synthetic filaments achieving superior moisture transport through capillary action. South Korean apartment dwellers with mini-split systems drive premium residential adoption, displacing cotton in climate-responsive bedding specifications.
- Cotton:Cellulosic staple fiber with natural breathability but higher water absorption.
- Wool:Keratin fiber retaining defensible positioning among hospitality buyers prioritizing natural fiber claims and flame resistance without chemical finishes.
Polyester retains volume leadership; microfiber holds the steepest expansion curve.
End User:
Application-specific thermal calibration requirements separate commercial buyers seeking HVAC load reduction from residential seasonal replacement patterns.
- Residential:Individual consumers purchasing through seasonal replacement cycles, with subtropical climate zones showing concentrated adoption. China's updated GB standards for textile energy efficiency reshape product specifications for domestic distribution.
- Hospitality:Hotel chains specifying thermal resistance ratings between 0.5 and 1.5 tog for HVAC load reduction, creating recurring replacement demand. Marriott and Hilton centralized sustainability scorecards now mandate thermal performance verification.
- Commercial:Office and retail space operators purchasing climate-control bedding for employee rest facilities.
- Institutions:Healthcare and educational facilities with standardized procurement protocols.
Residential retains volume leadership; hospitality holds the steepest expansion curve.
Distribution Channel:
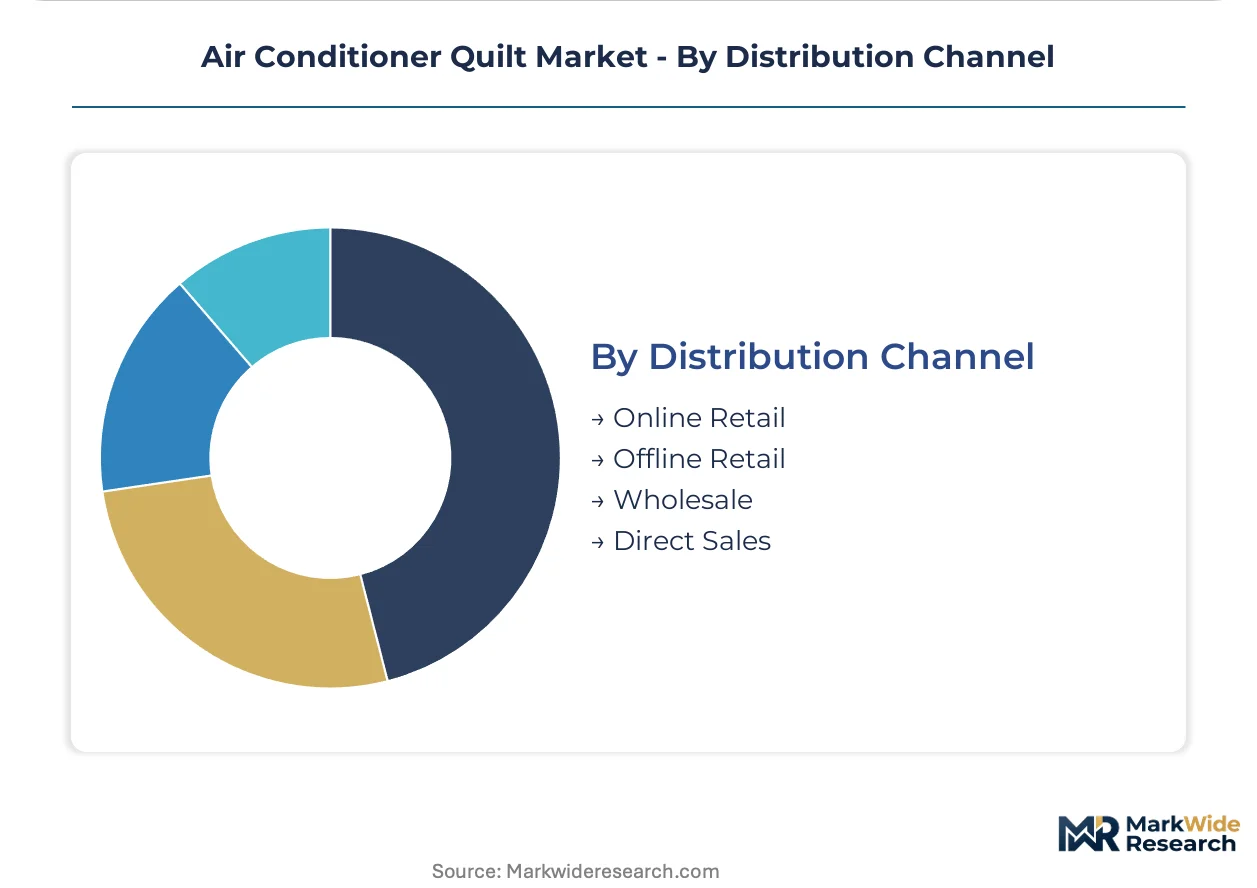
Customer type and purchase scale determine channel selection, with direct procurement consolidating previously fragmented authority.
- Online Retail:Direct-to-consumer platforms serving EU markets face REACH Annex XVII restrictions on PFAS finishes, forcing reformulation or customs detention risk at Rotterdam and Hamburg. German and French buyers prioritize OEKO-TEX Standard 100 certification.
- Direct Sales:Framework agreements with hotel chains consolidating purchasing authority previously fragmented across property-level housekeepers. Singapore and Dubai flagship properties source through global agreements rather than local textile distributors.
- Offline Retail:Department store and specialty bedding storefronts with tactile evaluation requirements.
- Wholesale:Regional linen suppliers serving fragmented property-level procurement in developing markets.
Online retail retains volume leadership; direct sales holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Japan's METI-certified premium segment while Chinese manufacturers compete on volume through Yangtze River Delta production clusters. This asymmetry shapes competitive returns across East Asian supply chains.
China
Domestic demand concentrates in subtropical provinces where mini-split air conditioner penetration drives seasonal replacement cycles. SAMR enforces updated GB textile standards that filter subscale exporters from premium distribution channels. Shaoxing and Nantong textile clusters scale OEM capacity through shared dyeing infrastructure and captive chemical supply.
Japan
Apartment dwellers in Tokyo and Osaka adopt conductive yarn variants for precise temperature targeting with mini-split systems. METI energy-efficiency labeling extends to climate-control bedding, creating compliance costs that favor mid-tier producers with testing laboratory relationships. Kanto and Kansai manufacturing regions anchor premium positioning through thermal calibration expertise.
South Korea
Seoul Capital Area residents drive microfiber adoption for moisture transport in climate-responsive bedding specifications. The country's national standards body maintains textile performance disclosure requirements that parallel Japanese METI frameworks. Busan-Ulsan industrial corridors supply synthetic filament capacity to regional quilt manufacturers.
Germany
Hospitality procurement in Berlin and Munich prioritizes OEKO-TEX Standard 100 certification over price following REACH Annex XVII restrictions on PFAS finishes. ECHA enforcement blocks direct-to-consumer exports through European online retail channels unless reformulation occurs. Bavaria and North Rhine-Westphalia distribute imported cooling quilts through centralized hotel framework agreements.
India
Mid-tier hotel construction in Bengaluru and Hyderabad lacks domestic cooling quilt suppliers, creating import substitution potential. BIS textile labeling compliance requirements filter subscale domestic manufacturers from commercial procurement. Maharashtra and Gujarat textile clusters concentrate on conventional bedding production without phase-change material finishing capacity.
Air Conditioner Quilt Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated HVAC-to-textile manufacturers commanding premium positioning while assembly-only vendors compete on volume. The vendor base splits between captive cooling technology partnerships and modular platform designers. Three archetypes dominate: vertically integrated appliance manufacturers, specialized textile producers with thermal calibration expertise, and OEM assemblers serving private-label retail. Capacity expansion and strategic partnerships represent the dominant competitive moves, with producers securing phase-change material supply agreements and testing laboratory relationships.
Among East Asian appliance manufacturers, Daikin Industries, Gree Electric Appliances, and Midea Group exemplify divergent strategic positioning. Daikin occupies a position anchored in captive cooling technology partnerships. Gree represents upstream control over compressor-to-textile coordination. Midea sits within the modular platform tier, serving multiple material grades through shared production infrastructure.
| Leading Market Players |
|---|
| Daikin Industries |
| Gree Electric Appliances |
| Midea Group |
| Carrier Global |
| Trane Technologies |
| Johnson Controls |
| LG Electronics |
| Haier Group |
| Mitsubishi Electric |
| Others |
Pricing and Supply Chain Analysis
OEM capacity utilization above 80% in Shaoxing and Nantong dyeing clusters compresses margin buffers for non-integrated assemblers while elevating price floors for phase-change material finished goods. China's SAMR GB standard enforcement concentrates compliant capacity among thermal-calibration-capable producers, bifurcating the market between certified premium supply and gray-channel economy products.
Pricing Analysis
The customization-premium spread separates configured-to-order conductive yarn quilts from standard polyester cooling quilts by a factor of three to five. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with OEKO-TEX Standard 100 and METI energy-efficiency labels commanding substantial premiums in Japanese and European channels. Price erosion runs through the economy tier as Zhejiang assembly-only vendors compete on undifferentiated polyester volume. Hospitality procurement teams exhibit lowest price sensitivity, prioritizing thermal verification and carbon disclosure over unit cost.
Supply Chain Analysis
Qiantang River basin dyeing capacity acts as a chokepoint, with over 70% of phase-change material finishing concentrated in Zhejiang province under dual carbon energy rationing protocols. Raw material feeds draw from Saudi petrochemical complexes for polyethylene glycol, Korean synthetic filament plants for microfiber, and Australian wool brokers for hospitality-grade natural fiber claims. Single-region concentration exposes buyers to provincial energy quotas and weather-related disruption. Distribution runs through direct-to-hotel framework agreements consolidating previously fragmented property-level procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment through GB standard certification and METI energy-efficiency labeling creates switching costs that lock in hospitality procurement relationships.
For Market Incumbents: Consolidate thermal calibration expertise through captive laboratory relationships and backward integration into phase-change material supply. Eliminate assembly-only competitors by accelerating SAMR compliance timelines that strain smaller manufacturers' working capital. Priority lever rests on securing Shaoxing dyeing cluster capacity under long-term offtake arrangements before dual carbon rationing intensifies. For New Entrants and Emerging Players: Differentiate on bio-based paraffin microcapsule formulations that satisfy sustainability scorecards from Marriott and Hilton centralized procurement. Target India's underserved commercial hospitality segment in Bengaluru and Hyderabad where BIS textile labeling compliance filters domestic competition. Go-to-market angle emphasizes import substitution for mid-tier hotel construction lacking local phase-change material finishing capacity. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated textile manufacturers with hospitality framework agreements and testing laboratory relationships. Long-term viability favors producers with backward integration into polymer supply and captive dyeing infrastructure. Acquisition target archetype: mid-tier Chinese manufacturers with SAMR certification but lacking phase-change material R&D depth. Signal to watch: METI labeling expansion to additional climate-control bedding categories.| Strategic Initiative | Industry Significance |
|---|---|
| Phase-Change Material Supply Agreement | Secures bio-based paraffin microcapsule feedstock from Zhejiang chemical clusters under dual carbon constraints. |
| Testing Laboratory Partnership | Accelerates SAMR GB standard certification timelines and METI energy-efficiency labeling for seasonal product launches. |
| Direct-to-Hotel Framework Agreement | Consolidates procurement authority from fragmented property-level housekeepers into centralized sustainability scorecards. |
| Conductive Yarn Integration Investment | Enables real-time thermal adjustment for Japanese mini-split air conditioner penetration in premium residential segments. |
| India Market Entry with BIS Compliance | Captures import substitution opportunity in Bengaluru and Hyderabad mid-tier hotel construction. |
Research Methodology
Desk research of customs trade records, SAMR regulatory filings, and hospitality procurement databases preceded structured interviews with textile plant managers, phase-change material R&D directors, hotel sustainability officers, and GB standard testing laboratory heads. Primary fieldwork validated secondary data on Yangtze River Delta capacity expansion and REACH Annex XVII reformulation costs. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across the analysis window.
Variance decomposition separates volume drivers from price-mix effects across product type, material chemistry, end-use application, and distribution channel dimensions. CAGRs were derived from segment-level growth rate reconciliation with aggregate market expansion. Forecast inputs incorporated mini-split air conditioner penetration curves, hospitality construction pipelines in subtropical zones, and petrochemical feedstock price elasticity assumptions.
The analysis sits within stated boundaries; outcomes outside sustained SAMR enforcement intensity, dual carbon policy continuity, or REACH chemical restriction scope would require recalibration. Forecasts reflect documented assumptions regarding phase-change material cost curves and hospitality procurement centralization trajectories. Practitioners should keep alternative scenarios live as energy rationing protocols and PFAS regulatory expansion evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
Warm Air Furnaces Market
HVAC Equipment
Europe Commercial HVAC Market
HVAC Equipment
HVAC Pumps Market
HVAC Equipment
Global Portable Air Conditioner Market
HVAC Equipment
Heating Equipment Market
HVAC Equipment
North America Bus HVAC Market
HVAC Equipment
Positive Displacement Blowers Market
HVAC Equipment
United Kingdom Heating Equipment Market
HVAC Equipment
Industrial Condensing Units Market
HVAC Equipment
Dedicated Outdoor Air System Market
HVAC Equipment
Steam Heat Exchanger Market
HVAC Equipment
South America Screw Compressor Market
HVAC Equipment
Scrubber Dryer Market
HVAC Equipment
Air Conditioning Systems Market
HVAC Equipment
Fabric Ducting Market
HVAC Equipment
Industrial Boiler Market