
 Horizontal Directional Drilling Market | 2026-2036
Horizontal Directional Drilling Market Size, Share, and Industry Trends Forecast 2026-2036
Horizontal Directional Drilling Market Analysis
Equipment rental networks is rewriting how contractors access horizontal directional drilling capability across North American infrastructure corridors. Vermeer Corporation leverages its captive dealer footprint to control aftermarket parts flow and technician training density. Herrenknecht AG anchors European demand through specialized large-diameter river crossing systems. XCMG Group competes on manufacturing scale, pushing standardized rig configurations into Asian and African markets at compressed capital cycles.
Horizontal directional drilling employs steerable drill strings with mud motors and electronic guidance packages to install pipelines, conduits, and cables beneath obstacles without surface trenching, typically achieving accuracies within centimeters over kilometer-scale bore paths. The process relies on bentonite drilling fluids to stabilize bore walls and evacuate cuttings while downhole sensors transmit inclination and azimuth data to surface operators in real time. Among applications, telecommunications has emerged as the fastest-expanding segment as 5G fiber backhaul and subsea cable landings multiply, while natural gas maintains the deepest margin pools given pipeline diameter requirements and pressure-class certification. Equipment type segmentation shows drilling rigs capturing the majority of capital expenditure, though locator technology is displacing older magnetic systems as GPS-integrated walkover and wireline guidance becomes standard for urban utility work.
The US Department of Transportation's Pipeline and Hazardous Materials Safety Administration mandates integrity management protocols that favor trenchless construction in high-consequence areas, while EPA wetland crossing permits increasingly require minimal surface disturbance methods. In Europe, the EU Green Deal's methane reduction targets and national renewable gas injection standards are redirecting distribution network investments toward HDD-based pipeline replacement. Stakeholders must monitor evolving carbon accounting frameworks for construction equipment and assess how embedded emissions reporting reshapes fleet procurement criteria across municipal and private project pipelines.
Market Dynamics
Telecommunications fiber deployments are rewriting demand patterns for horizontal directional drilling, as 5G backhaul and data center interconnects force carriers to bore beneath dense urban infrastructure without surface disruption.
Growth Catalysts
- US Pipeline Safety Regulations:The Department of Transportation's PHMSA mandates trenchless construction in high-consequence areas, directing capital toward HDD methods for wetland and river crossings.
- EU Green Deal Methane Targets:National renewable gas injection standards across Europe are accelerating distribution network replacement programs that favor minimal-surface-disturbance pipeline installation.
- Permian Basin Extended-Reach Laterals:Oil and gas operators in West Texas and southeastern New Mexico require kilometer-scale bore paths with centimeter-level accuracy to access reserves beneath developed land.
Market Restraints
- Bentonite Supply Concentration:Drilling fluid formulations depend on Wyoming sodium bentonite deposits, creating input cost volatility when mining output fluctuates.
- GPS-Integrated Locator Equipment Costs:Walkover and wireline guidance systems capable of urban utility work require capital outlays that exclude smaller municipal contractors from project bidding.
- Steel Drill Pipe Lead Times:Specialized high-torque tubular manufacturing concentrates in limited North American and European foundries, extending equipment procurement cycles.
Strategic Opportunities
- Subsea Cable Landings:Coastal fiber landing stations in Florida, California, and Virginia present untapped demand for HDD-based shore approaches that avoid beach nourishment zones.
- Carbon Accounting Frameworks:Embedded emissions reporting requirements under the EU CSRD are reshaping fleet procurement criteria toward lower-carbon rig configurations.
- Equipment-as-a-Service Models:Rental networks with embedded technician certification are opening access for mid-tier contractors previously excluded by ownership economics.
Industry Challenges
- Downhole Sensor Calibration Expertise:Real-time inclination and azimuth data interpretation requires specialized mud logging skills that outpace vocational training program output.
- Multi-Agency Permitting Coordination:Projects crossing EPA wetlands, Coast Guard navigable waters, and state utility corridors face sequential review timelines that compress construction windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Horizontal Directional Drilling Market |
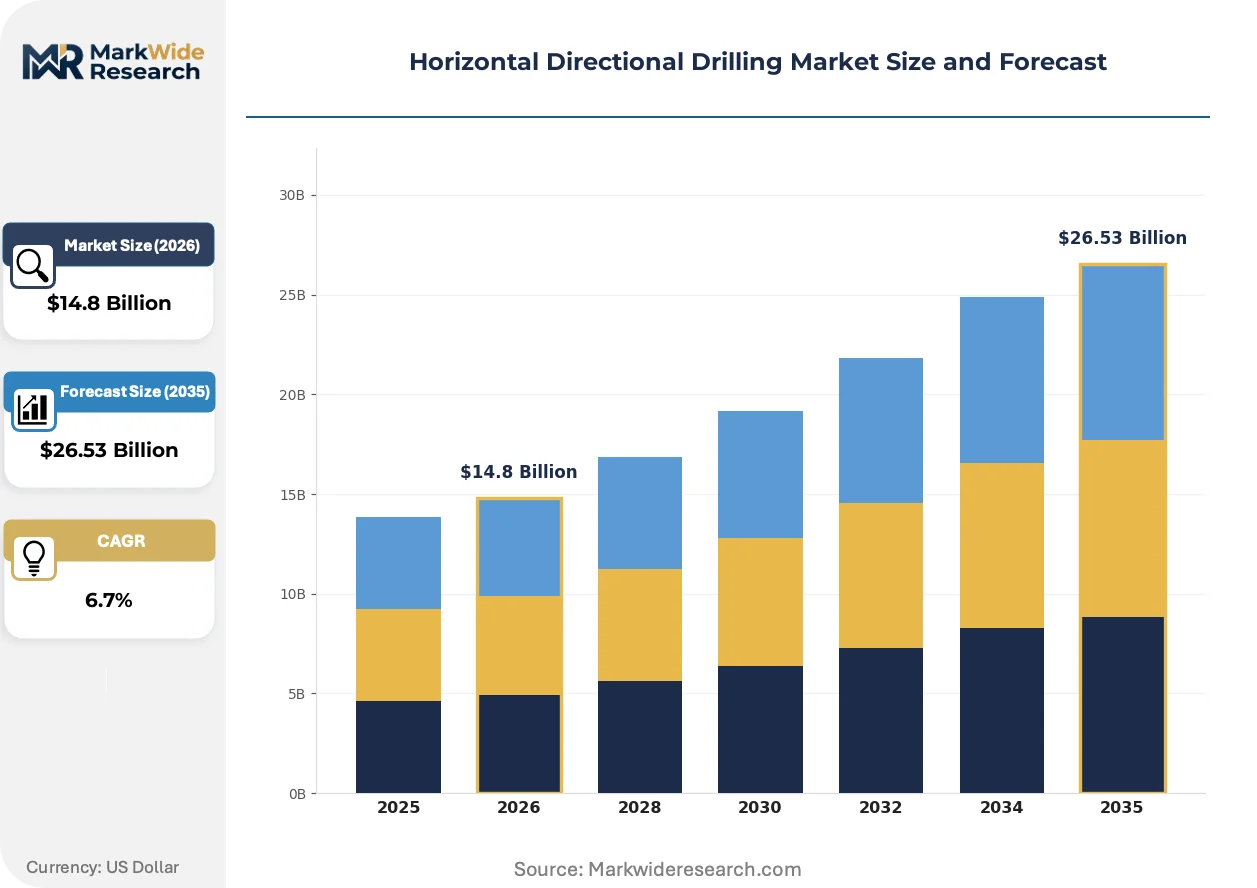
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $26.53 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Telecommunications, Water Supply, Electric Utility, Natural Gas Equipment Type: Drilling Rigs, Drill Bits, Locators, Reamers End User: Construction Companies, Municipalities, Oil & Gas Operators, Infrastructure Developers Installation Type: Onshore, Offshore, Urban, Rural |
| Companies Covered | Vermeer Corporation, Herrenknecht AG, XCMG Group, Barbco Inc., The Charles Machine Works Inc. (Ditch Witch), Halliburton Company, Baker Hughes Company, The Toro Company, Nabors Industries Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Horizontal Directional Drilling Market Emerging Trajectories
Downhole telemetry and surface automation are compressing the skill gap between experienced drillers and field crews, while regulatory pressure on methane emissions redirects capital toward replacement infrastructure.
Electromagnetic telemetry systems are digitizing how inclination and azimuth data transmits from mud motor assemblies to surface operators without conductive drill string requirements. Fiber and 5G carriers in Germany, the United Kingdom, and Japan are adopting these packages for urban utility corridors where magnetic interference from existing infrastructure degrades conventional guidance. The technology is digitizing project staffing models, enabling single-operator monitoring of multiple rig locations from centralized control rooms.
The EU F-Gas Regulation and national methane reduction frameworks are mandating leak detection and repair protocols that favor trenchless pipeline replacement over open-cut methods. Distribution network operators in the Netherlands, Denmark, and Italy face accelerated biogas injection timelines that require parallel pipeline integrity upgrades. Steel and composite pipe manufacturers are responding with pressure-class certifications optimized for HDD pull-through installation.
Outcome-based drilling contracts are displacing traditional day-rate arrangements in North American shale plays and European utility markets. EPC firms and midstream operators now specify total installed cost guarantees that transfer geological risk to drilling contractors. This restructuring concentrates most visibly in the Permian Basin and Appalachian shale corridors, where operators bundle multiple lateral bores under single-performance contracts with penalty clauses for surface release incidents.
Horizontal Directional Drilling Market Segmentation
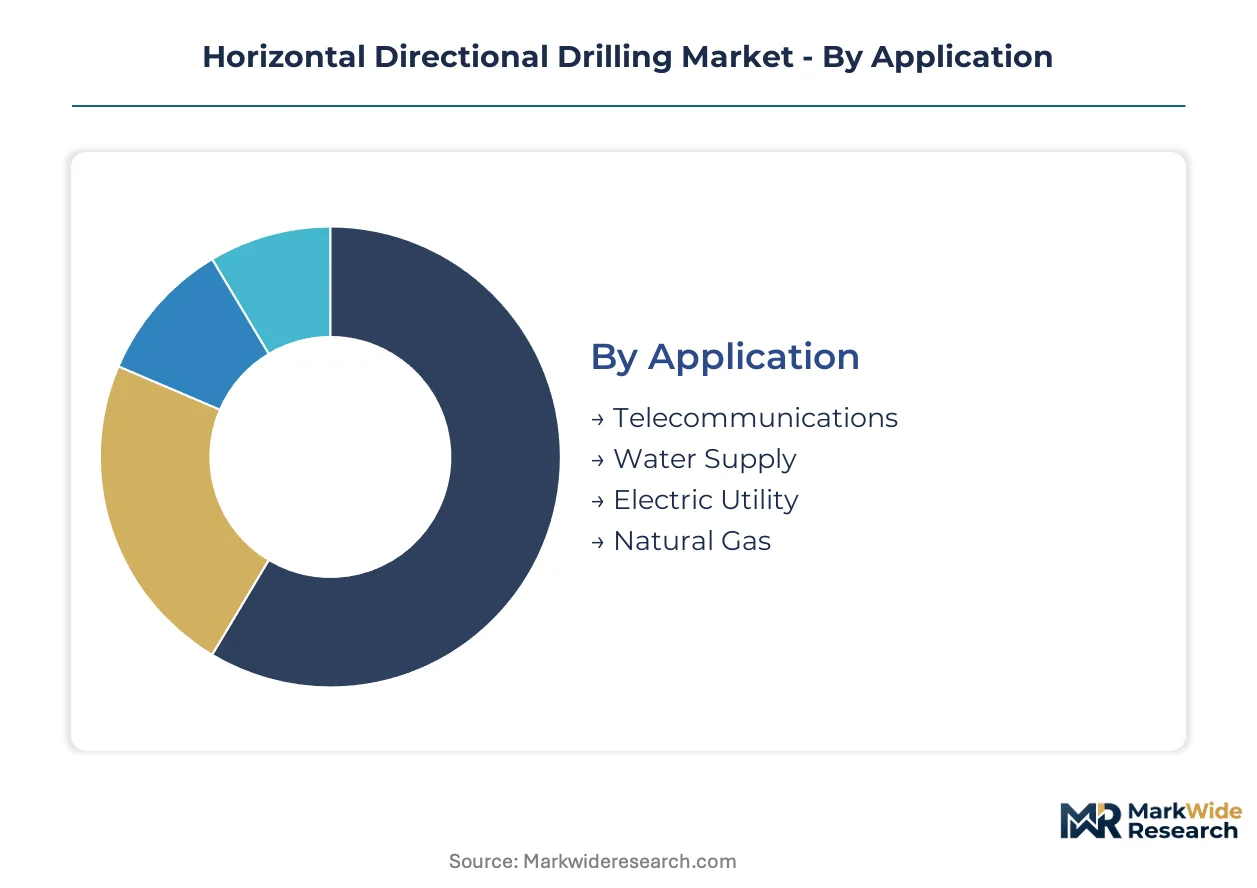
Horizontal directional drilling equipment and services fragment across four distinct dimensions that shape procurement patterns and margin structures. Application requirements dictate bore diameter and pressure-class specifications. Equipment type determines capital intensity and rental versus ownership economics.
Application:
Application segmentation separates projects by the infrastructure being installed and the regulatory environment governing each vertical.
- Telecommunications:Fiber and 5G backhaul installations demand sub-30cm bore diameters with centimeter-level accuracy beneath dense urban infrastructure. Carriers in Germany, Japan, and the United States are accelerating deployments to avoid surface disruption in established rights-of-way.
- Natural Gas:High-pressure steel pipeline installations require large-diameter reaming sequences and pressure-class certifications from regulators including PHMSA and national gas safety bodies. Distribution network operators face replacement timelines driven by methane reduction frameworks.
- Water Supply:Municipal water main replacements favor medium-diameter bores with corrosion-resistant pipe pull-through.
- Electric Utility:Underground transmission and distribution cable installations concentrate in coastal load centers facing storm-hardening mandates.
Natural Gas holds installed capacity. Telecommunications is rotating up the share rankings.
Equipment Type:
Equipment type segmentation captures the capital stack and technology intensity of HDD project execution.
- Drilling Rigs:Self-propelled crawler and trailer-mounted units deliver rotary torque and thrust force through hydraulic power systems. Demand clusters in the Permian Basin and Appalachian shale corridors where extended-reach laterals require 100,000+ ft-lb torque ratings.
- Locators:GPS-integrated walkover and wireline guidance systems transmit real-time inclination and azimuth data from mud motor assemblies to surface operators. European and Japanese carriers are displacing magnetic systems in urban utility corridors where electromagnetic interference degrades conventional accuracy.
- Drill Bits:Tricone and PDC cutting structures face replacement cycles tied to formation abrasiveness and bore length.
- Reamers:Hole-opening tools expand pilot bores to final diameter in multi-pass sequences.
Drilling Rigs dominate capital deployed. Locators are climbing the fastest as guidance technology displaces legacy systems.
End User:
End user segmentation reflects the contracting structure and risk allocation of HDD projects.
- Oil & Gas Operators:Midstream and upstream firms specify extended-reach laterals beneath developed land in West Texas and southeastern New Mexico. Outcome-based contracts with total installed cost guarantees are displacing traditional day-rate arrangements in these corridors.
- Construction Companies:General and specialty contractors bid municipal and private infrastructure projects with equipment rental networks reducing capital barriers to entry.
- Municipalities:City and county agencies procure water, sewer, and electric distribution upgrades through public bidding processes.
- Infrastructure Developers:Private equity-backed firms aggregate fiber and pipeline projects across multiple jurisdictions.
Oil & Gas Operators anchor high-specification demand. Construction Companies are expanding fastest as rental models democratize access.
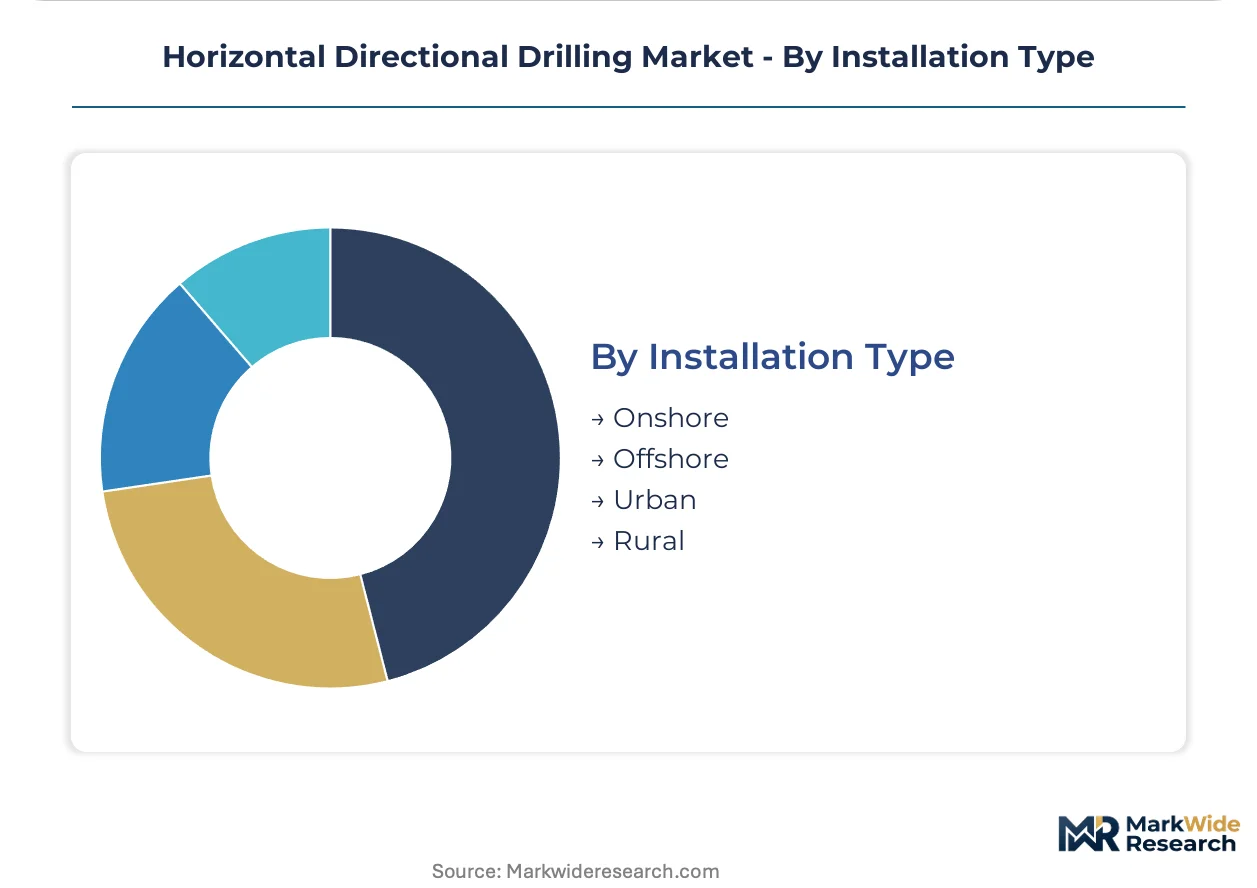
Installation Type:
Installation type segmentation distinguishes projects by surface environment and permitting complexity.
- Urban:Dense infrastructure corridors require GPS-integrated locators and bentonite fluid management to avoid utility strikes and surface heave. EPA wetland permits and Coast Guard navigable water crossings impose sequential review timelines.
- Onshore:Rural and suburban projects across the continental United States constitute the volume base for standard rig configurations and conventional magnetic guidance.
- Offshore:Subsea cable landings at coastal fiber stations in Florida, California, and Virginia present specialized shore approach requirements.
- Rural:Agricultural and undeveloped land crossings minimize permitting layers but extend mobilization distances.
Onshore commands project volume. Urban is gaining share fastest as 5G and fiber densification accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US Department of Transportation anchors regulatory momentum through PHMSA mandates that favor trenchless construction in environmentally sensitive corridors. Demand concentrates where pipeline safety rules intersect with fiber densification and shale field development.
United States
Telecommunications carriers and oil and gas operators drive parallel demand streams for extended-reach laterals and urban fiber backhaul. PHMSA integrity management protocols mandate trenchless methods in high-consequence areas including wetland and river crossings. The Permian Basin spanning West Texas and southeastern New Mexico hosts kilometer-scale bore projects beneath developed land.
Germany
Distribution network operators face compressed timelines for biogas injection infrastructure and methane reduction compliance. The EU F-Gas Regulation and national renewable gas standards redirect capital toward HDD-based pipeline replacement. Industrial clusters in North Rhine-Westphalia and Bavaria concentrate utility contracting capacity for urban utility corridors.
Japan
5G fiber backhaul and data center interconnects force carriers to bore beneath dense metropolitan infrastructure without surface disruption. METI guidelines on underground utility coordination streamline permitting for trenchless methods in Tokyo and Osaka corridors. The Kanto and Kansai regions host specialized contracting networks for electromagnetic telemetry deployments.
China
Municipal water main replacement and natural gas distribution expansion drive standardized rig demand across provincial infrastructure programs. National standards on minimal surface disturbance construction align with urban renewal timelines in the Yangtze River Delta and Pearl River Delta. State-backed pipeline operators in Sichuan-Chongqing and Shandong Peninsula regions specify extended-reach capabilities for river crossings.
Netherlands
Distribution network operators accelerate biogas injection timelines that require parallel pipeline integrity upgrades. The EU Green Deal methane reduction targets and CSRD embedded emissions reporting reshape procurement criteria toward lower-carbon rig configurations. The Randstad corridor concentrates specialized contracting for urban utility work beneath dense infrastructure.
Horizontal Directional Drilling Market Vendor Landscape
Integrated equipment manufacturers and specialized drilling contractors split the market based on capital intensity and technical specification requirements. Equipment ownership concentrates among firms with captive dealer networks and aftermarket parts control. Three archetypes dominate: full-line rig builders with rental distribution, specialized large-diameter system providers, and scale-driven manufacturers pushing standardized configurations. Competitive moves center on technician certification density and embedded emissions reporting compliance.
Among North American equipment manufacturers, Vermeer Corporation and The Charles Machine Works Inc. (Ditch Witch) exemplify the full-line archetype with integrated dealer footprints. Herrenknecht AG anchors the specialized tier for large-diameter river crossing systems. These named entities represent strategic positioning around rental network density, aftermarket control, and geographic specialization rather than product-specific claims.
| Leading Market Players |
|---|
| Vermeer Corporation |
| Herrenknecht AG |
| XCMG Group |
| Barbco Inc. |
| The Charles Machine Works Inc. (Ditch Witch) |
| Halliburton Company |
| Baker Hughes Company |
| The Toro Company |
| Nabors Industries Ltd. |
| Others |
Supply Flow & Price Mechanics
Wyoming sodium bentonite deposit concentration determines both pricing tier spreads and supply chain shape across horizontal directional drilling markets. Single-source dependency on Powder River Basin mining output creates input cost volatility that compresses margins for fluid-dependent contractors while rewarding integrated operators with captive bentonite supply.
Pricing Analysis
Configured-to-order pricing for extended-reach rigs with 100,000+ ft-lb torque ratings commands substantial premiums over standardized trailer-mounted units. Price differentiation rests on GPS-integrated locator certification tiers and PHMSA pressure-class compliance levels. Cost compression in economy-tier rental equipment is intensifying because Asian manufacturers are pushing standardized configurations at compressed capital cycles. Municipal contractors exhibit highest price sensitivity due to public bidding constraints, while Permian Basin operators prioritize performance guarantees over unit economics.
Supply Chain Analysis
Tariff exposure between China and North America dominates supply chain risk calculations for steel drill pipe and hydraulic power system components. Manufacturing gravity centers on Germany for specialized large-diameter river crossing systems, the United States for high-torque tubular production, and China for standardized rig assemblies. Raw material dependencies include Wyoming sodium bentonite for drilling fluids, specialized alloy steel for drill pipe, and rare-earth magnets for electromagnetic telemetry. Distribution runs through captive dealer networks controlled by full-line manufacturers with embedded technician certification programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Horizontal directional drilling markets sit at a platform-economics inflection where equipment-as-a-service rental networks are displacing ownership models. Interoperability between GPS-integrated locators and multi-manufacturer rig fleets is consolidating contractor procurement around certified technician density rather than capital access.
For Market Incumbents: Harden aftermarket parts control through captive dealer footprint expansion in the Permian Basin and Appalachian shale corridors. Lock in technician certification density to prevent rental network disintermediation by third-party equipment aggregators. Prioritize embedded emissions reporting compliance ahead of EU CSRD procurement mandate expansion.
For New Entrants and Emerging Players: Build out electromagnetic telemetry specialization for urban utility corridors in Germany, Japan, and coastal US fiber landing markets. Target subsea cable shore approach contracting where incumbent density remains thin and PHMSA wetland crossing expertise creates qualification barriers. Pursue outcome-based contract capabilities to access Permian Basin bundled lateral projects.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors technician-certification-dense rental networks over pure manufacturing assets. Long-term viability hinges on carbon-accounting-compliant fleet configurations and software-integrated guidance technology. Watch for EU methane reduction enforcement intensity as the signal indicating accelerated distribution network replacement capital deployment.
| Strategic Initiative | Industry Significance |
|---|---|
| Technician Certification Network Expansion | Captive dealer density locks in aftermarket revenue streams and excludes rental competitors. |
| Electromagnetic Telemetry Integration | GPS-integrated walkover systems displace magnetic guidance in urban utility corridors. |
| Carbon Accounting Compliance Investment | EU CSRD embedded emissions reporting reshapes fleet procurement criteria for municipal buyers. |
| Outcome-Based Contract Capability | Total installed cost guarantees transfer geological risk and consolidate Permian Basin market share. |
| Bentonite Supply Integration | Backward integration into Wyoming mining operations insulates margins from input cost volatility. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with drilling contractors, equipment rental network managers, PHMSA compliance officers, and municipal procurement directors. Secondary validation drew from EPA wetland permit databases, FERC pipeline filings, EU Green Deal implementation trackers, and customs records for drilling fluid component trade flows. Bottom-up project pipeline aggregation triangulated against top-down equipment shipment data from North American and European manufacturers.
Calibration against historical rig deployment patterns and telecommunications fiber densification timelines anchored projection models across the analysis window. Segmentation dimensions modeled include application vertical, equipment torque class, end-user contracting structure, and installation environment complexity. CAGRs derived from equipment replacement cycles, regulatory mandate phase-in schedules, and carrier capital expenditure commitments. Forecast inputs incorporated shale field development intensity and subsea cable landing station permitting velocity.
Stress conditions across bentonite supply disruptions, steel tariff escalations, and PHMSA regulatory tightening were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding methane reduction framework enforcement and 5G backhaul deployment cadence. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialized Building Services
Portable Ramps Market
Specialized Building Services
Automatic Industrial Doors Market
Specialized Building Services
Private Bunker Market
Specialized Building Services
Portable Toilet Market
Specialized Building Services
Building Inspection Services Market
Specialized Building Services
US and Europe Cleanrooms Market
Specialized Building Services
Global Automated Industrial Door Market
Specialized Building Services
Europe Stair Lift Market
Specialized Building Services
Clean Room Pass Box Market
Specialized Building Services
Industrial Access Platform Market
Specialized Building Services
Global Prefabricated Bathroom Pods Market
Specialized Building Services
Construction Drone Market
Specialized Building Services
Portable Toilet Rental Market
Specialized Building Services
Street Furniture Market