
 Movable Scaffolding System Market | 2026-2036
Movable Scaffolding System Market Size, Share, and Industry Trends Forecast 2026-2036
Movable Scaffolding System Market Insights
Modular aluminum frame technology is reshaping how contractors deploy temporary access platforms across complex geometries. PERI Group leverages its German engineering base to sustain premium positioning in system scaffold configurations. BrandSafway anchors North American infrastructure projects through extensive rental fleet coverage. ULMA Construction differentiates via integrated formwork and shoring solutions that extend beyond pure scaffolding supply.
A movable scaffolding system comprises engineered temporary access platforms mounted on wheels, tracks, or cantilever arms, typically fabricated from aluminum alloy 6061-T6 or S355 structural steel with load ratings spanning 75 to 500 kg/m², designed to transport workers, tools, and materials along horizontal or vertical work faces during construction, maintenance, or renovation operations. System scaffold configurations dominate commercial applications where rapid assembly cycles reduce labor hours, while cantilever designs command specialized margins in bridge soffit and stadium roof access where ground support proves impractical. Aluminum frame technology leads unit volume given corrosion resistance and manual handling advantages, though steel frame variants retain share in heavy industrial settings such as power plant maintenance where static load requirements exceed aluminum thresholds.
OSHA scaffold standards in the United States, the EU Machinery Directive enforced through national notified bodies in Germany and France, and China's GB 51210 technical code for scaffolding safety collectively dictate load testing protocols, guardrail specifications, and documentation requirements that filter non-compliant suppliers from project bids. The EU's Construction Products Regulation and CE marking obligations further segment market access between certified manufacturers and uncertified imports. Stakeholders must monitor evolving national implementation timelines for the EU's revised Machinery Regulation and China's updated GB standards to anticipate recertification costs and competitive displacement risks.
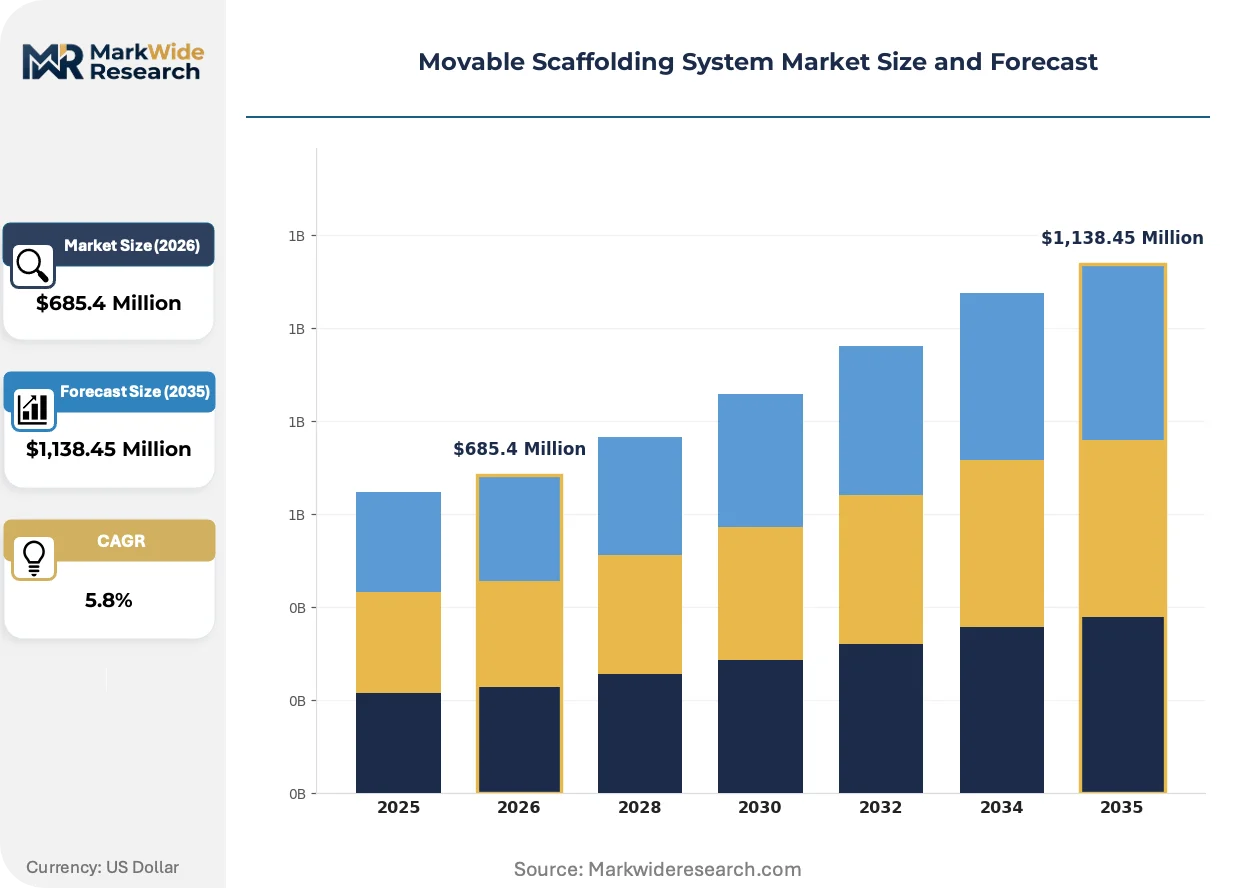
Market Dynamics
The movable scaffolding system market is being restructured by the divergence between aluminum modular systems favored for rapid assembly and steel cantilever configurations required for heavy industrial loads, with certification requirements under the EU Machinery Directive and China's GB 51210 code filtering supplier participation.
Growth Catalysts
- Bridge infrastructure renewal:Aging bridge stock across Germany and the United States is generating sustained demand for cantilever and underslung systems that enable soffit access without ground support structures.
- EU Machinery Directive enforcement:Mandatory CE marking and load testing protocols are displacing uncertified suppliers, consolidating procurement toward documented engineering-grade systems.
- Aluminum alloy 6061-T6 adoption:Corrosion resistance and manual handling advantages are expanding aluminum frame deployment in coastal and high-humidity construction zones.
Market Restraints
- Aluminum price volatility:Input cost swings for aluminum alloy 6061-T6 compress margin stability for frame fabricators and rental fleet operators.
- German engineering concentration:Premium system design and certification expertise clusters in German-speaking industrial regions, creating supply bottleneck risks for non-European projects.
- Steel substitution in heavy loads:Static load requirements exceeding 300 kg/m² in power plant and heavy industrial maintenance favor S355 structural steel alternatives.
Strategic Opportunities
- Yangtze River Delta corridor:China's high-speed rail and urban viaduct construction is creating concentrated demand for modular underslung systems with rapid repositioning capability.
- Integrated formwork-scaffolding bundles:Contractors are consolidating procurement toward single-source suppliers offering combined shoring, formwork, and access platforms.
- Rental fleet digitization:IoT-enabled asset tracking and predictive maintenance scheduling are opening service revenue streams beyond equipment supply.
Industry Challenges
- Certified welder scarcity:Aluminum TIG welding for structural repairs and modifications requires specialized labor pools that remain shallow outside major manufacturing clusters.
- Multi-jurisdiction documentation:Projects spanning Germany, France, and China must reconcile divergent load test documentation formats and inspector qualification requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Movable Scaffolding System Market |
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,138.45 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cantilever, Mobile Tower, Rolling Scaffold, Suspended Scaffold, System Scaffold Technology: Aluminum Frame, Steel Frame, Composite, Modular, Telescopic Application: Bridge Construction, Tunnel Renovation, Stadium Assembly, Shipbuilding, Power Plant Maintenance End User: General Contractors, Specialty Contractors, Industrial Fabricators, Infrastructure Developers, Maintenance Providers |
| Companies Covered | PERI Group, Layher Holding GmbH, BrandSafway, ULMA Construction, Altrad Group, ADTO Group, Waco Kwikform, MJ-Gerüst GmbH, Instant Upright, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Movable Scaffolding System Market Trends and Innovations
Digital engineering tools and connected equipment are compressing design-to-deployment cycles while regulatory documentation requirements harden. Three developments are restructuring competitive advantage.
Building information modeling is virtualizing scaffold configuration design before physical assembly. Bridge contractors in Germany and China are adopting BIM-integrated planning to pre-resolve interference conflicts and optimize material quantities. This virtualization is compressing on-site labor hours and reducing engineering change orders during complex geometry projects.
The EU's revised Machinery Regulation is tightening guardrail height specifications and emergency descent requirements for suspended platforms. Manufacturers serving European infrastructure projects must redesign mast climbing work platforms and underslung carriages to meet updated conformity assessment procedures. German notified bodies are experiencing certification backlog, delaying market entry for redesigned systems.
Equipment-as-a-service contracting is displacing capital purchase for large-scale infrastructure contractors. Rental providers in North America and Western Europe are unbundling maintenance, inspection, and operator training into recurring revenue streams. This shift is most visible among bridge construction consortia in the United States, where balance sheet constraints favor operational expenditure treatment.
Movable Scaffolding System Market Segmentation
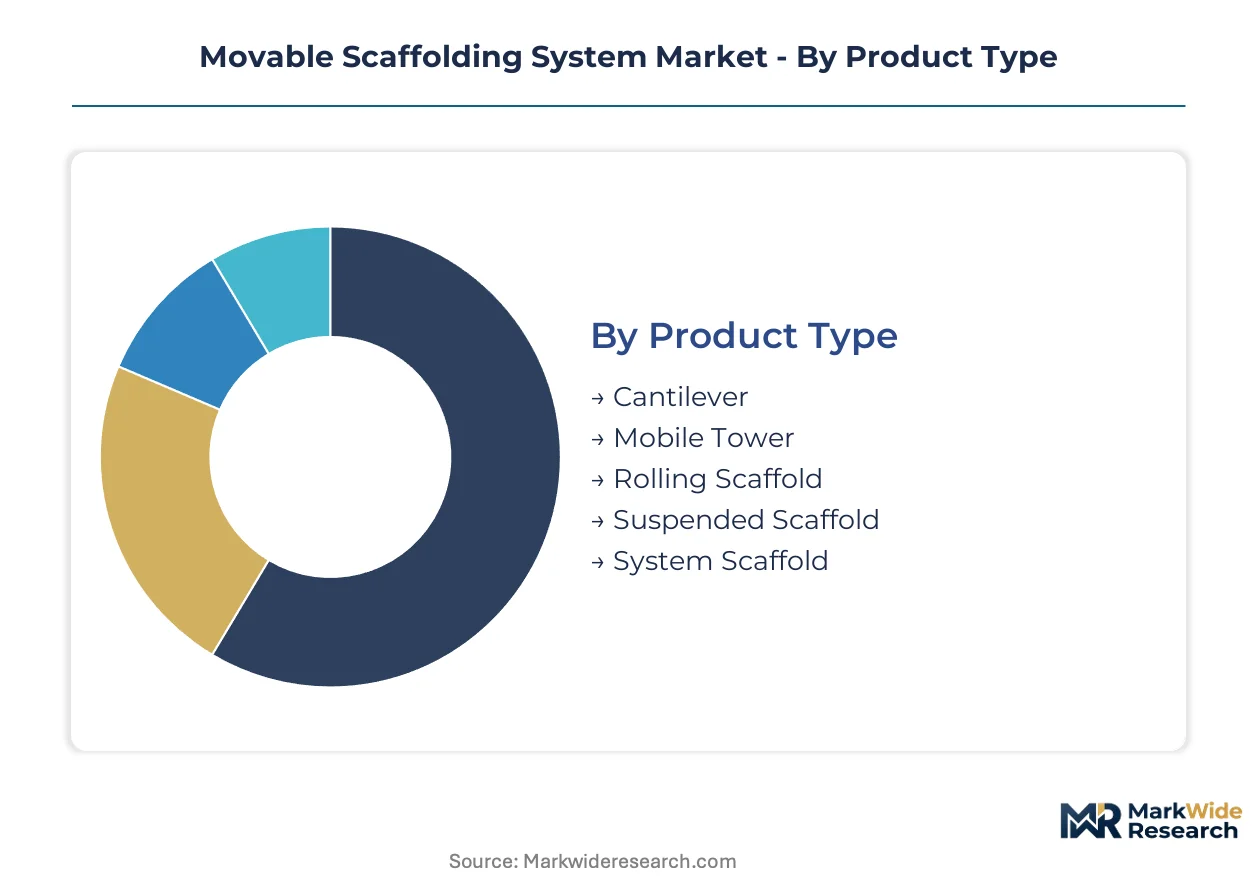
Segmentation in movable scaffolding systems tracks how asset utilization cycles vary dramatically across product configurations and end-use contexts. Contractors optimizing fleet turnover must match system selection to project duration and repositioning frequency.
Product Type:
Cantilever systems turn over slowest due to custom engineering requirements, while rolling scaffolds cycle fastest through standardized rental pools.
- System Scaffold:Modular aluminum or steel frames with standardized connection nodes enable rapid assembly and disassembly cycles. German bridge contractors and Yangtze River Delta infrastructure developers deploy these for viaduct construction where frequent repositioning demands standardized components.
- Cantilever:Underslung platforms extending from structural anchors without ground support, fabricated to project-specific geometries. Demand concentrates in German-speaking industrial clusters for aging bridge soffit access where ground support proves impractical and engineering documentation requirements under EU Machinery Directive extend procurement cycles.
- Mobile Tower:Self-contained vertical access units with integrated base frames and casters, suited for maintenance operations with moderate height requirements.
- Rolling Scaffold:Horizontal rail-mounted platforms for continuous facades, common in stadium assembly and tunnel lining operations.
- Suspended Scaffold:Wire rope-hung platforms for vertical faces, deployed in shipbuilding and high-rise renovation where ground-based systems cannot reach.
System scaffold anchors the volume base while cantilever gains share at the steepest rate as bridge renewal accelerates in Germany and China.
Technology:
Cost tiers separate premium aluminum systems from economy steel alternatives, with composite materials occupying a narrow mid-tier position.
- Aluminum Frame:Alloy 6061-T6 construction delivers corrosion resistance and manual handling advantages in coastal zones. China's GB 51210 certification requirements and EU Machinery Directive load testing protocols favor documented aluminum systems from certified fabricators.
- Modular:Standardized component systems with interchangeable braces and decks, enabling fleet flexibility across project types. Infrastructure developers in the Yangtze River Delta corridor specify modular configurations for high-speed rail viaducts where rapid assembly cycles compress labor costs.
- Steel Frame:S355 structural steel for static loads exceeding aluminum thresholds, dominant in power plant maintenance.
- Composite:Glass-reinforced polymer or hybrid materials for specialized corrosion environments.
- Telescopic:Height-adjustable masts for variable reach requirements in tunnel renovation.
Aluminum frame technology commands the revenue base while modular configurations climb the fastest as procurement consolidates toward single-source bundled suppliers.
Application:
Volume concentrates in horizontal infrastructure while vertical specialty applications sustain premium margins.
- Bridge Construction:Cantilever and underslung systems for soffit access during construction and renewal. German contractors face extended procurement cycles under EU Machinery Directive CE marking requirements, while Chinese developers in the Yangtze River Delta corridor prioritize rapid repositioning capability for urban viaduct programs.
- Power Plant Maintenance:Heavy-load steel configurations for turbine hall access and boiler maintenance. Static load requirements exceeding 300 kg/m² favor S355 structural steel over aluminum alternatives, with OSHA scaffold standards in the United States and China's GB 51210 code dictating guardrail and load test documentation.
- Tunnel Renovation:Telescopic and rolling systems for confined linear workspaces.
- Stadium Assembly:System scaffold for roof structures and rolling platforms for facade work.
- Shipbuilding:Suspended scaffolds for hull access in drydock environments.
Bridge construction anchors the volume base while power plant maintenance gains share at the steepest rate as industrial asset renewal accelerates.
End User:
Customer type determines procurement mode, with capital-constrained contractors favoring rental and integrated developers purchasing bundled systems.
- General Contractors:Diverse project portfolios requiring flexible fleet access across scaffold types. Equipment-as-a-service contracting is displacing capital purchase among bridge construction consortia in the United States where balance sheet constraints favor operational expenditure treatment.
- Infrastructure Developers:Long-horizon asset owners consolidating procurement toward integrated formwork-scaffolding-shoring bundles. Chinese state-owned developers in the Yangtze River Delta corridor specify single-source suppliers to compress coordination overhead on high-speed rail programs.
- Specialty Contractors:Niche providers focused on bridge access or industrial maintenance.
- Industrial Fabricators:In-house maintenance departments with captive scaffold fleets.
- Maintenance Providers:Service contractors with rental-dependent asset-light models.
General contractors anchor the volume base while infrastructure developers gain share at the steepest rate as bundled procurement consolidates supplier relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German engineering clusters export certified aluminum systems to bridge contractors across the Yangtze River Delta, while U.S. infrastructure consortia import modular configurations for aging viaduct renewal programs.
Germany
Bridge soffit access demand drives procurement of cantilever systems for autobahn renewal. The EU Machinery Directive enforces CE marking through notified bodies in Munich and Berlin. Bavarian engineering clusters around Munich supply documented systems to Austrian and Swiss cross-border projects.
China
High-speed rail viaduct construction in Jiangsu and Zhejiang provinces consumes modular underslung platforms. GB 51210 technical codes mandate load testing documentation for state-owned developer tenders. Shanghai-based fabricators serve the Yangtze River Delta infrastructure corridor with rapid-repositioning configurations.
United States
Aging interstate bridge stock generates demand for equipment-as-a-service contracting among capital-constrained consortia. OSHA scaffold standards dictate guardrail specifications and inspector qualification requirements. Gulf Coast contractors combine aluminum systems with corrosion-resistant coatings for humid coastal zones.
France
Nuclear power plant maintenance sustains heavy-load steel configuration demand beyond aluminum thresholds. ANSM and notified bodies enforce EU Machinery Directive conformity assessment procedures. Lyon industrial clusters supply S355 structural steel platforms to EDF maintenance schedules.
India
Metro rail viaduct expansion in Delhi-Mumbai corridors drives modular system adoption. BIS certification requirements and state-level contractor registration filter supplier participation. Gujarat fabrication hubs export standard frame components to Middle East infrastructure projects.
Movable Scaffolding System Market Competitive Landscape
On the supply side, the industry is consolidating around documented engineering-grade systems as certification requirements displace uncertified imports. Three strategic archetypes dominate: German-engineered premium system providers, North American rental fleet operators, and Chinese scale fabricators serving domestic infrastructure programs. Competitive moves center on integrated formwork-scaffolding bundling and IoT-enabled fleet digitization for recurring service revenue.
Within the premium engineering tier, PERI Group and Layher Holding GmbH exemplify German-origin system scaffold specialists whose documented configurations satisfy EU Machinery Directive CE marking requirements. BrandSafway anchors North American rental market positioning through extensive fleet coverage and equipment-as-a-service contracting models. These three companies represent distinct geographic and business model archetypes rather than direct product competitors.
| Leading Market Players |
|---|
| PERI Group |
| Layher Holding GmbH |
| BrandSafway |
| ULMA Construction |
| Altrad Group |
| ADTO Group |
| Waco Kwikform |
| MJ-Gerüst GmbH |
| Instant Upright |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Chinese aluminum extrusion capacity is compressing frame fabrication margins while concentrating procurement leverage with Yangtze River Delta infrastructure developers. This utilization imbalance feeds through to European system providers who must defend engineering premiums against commoditized modular imports.
Pricing Analysis
The pricing gap between legacy steel cantilever configurations and next-generation aluminum modular systems widened as alloy 6061-T6 processing costs diverged from S355 structural steel benchmarks. Three-tier pricing structure across premium, standard, and economy levels separates CE-certified German-engineered systems from documented Chinese fabricators and uncertified regional suppliers. Price differentiation hinges on certification grade under EU Machinery Directive and after-sales service bundling. Pricing pressure stems from aluminum price volatility eroding margin stability for frame fabricators. Rental fleet operators exhibit highest price sensitivity due to asset turnover velocity, while infrastructure developers prioritize documented engineering over unit cost.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk planning for aluminum frame fabricators serving North American bridge contractors. Manufacturing gravity centers on Germany, China, and India, with Bavarian engineering clusters supplying certified configurations to cross-border European projects. Raw material dependencies rest on aluminum alloy 6061-T6 billet, S355 structural steel plate, and precision-machined connection nodes. Single-source vulnerability concentrates in German TIG welding expertise for structural repairs. Distribution runs through rental fleet operators and direct procurement by infrastructure developers consolidating bundled formwork-scaffolding contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The shallow pool of certified aluminum TIG welders outside major manufacturing clusters is constraining fleet expansion velocity and inflating maintenance labor costs. This capability bottleneck favors incumbents with captive training pipelines and disadvantages asset-light entrants.
For Market Incumbents: Harden certification moats by accelerating CE marking investments under the EU's revised Machinery Regulation before notified body backlogs extend further. Deepen backward integration into aluminum alloy 6061-T6 processing to buffer margin compression from commodity volatility. Defend against Chinese scale fabricators by embedding IoT-enabled predictive maintenance into equipment-as-a-service contracts, locking in recurring revenue streams that commoditized imports cannot replicate. For New Entrants and Emerging Players: Pursue white-space opportunity in India's metro rail viaduct corridor where BIS certification requirements filter participation less stringently than EU or Chinese standards. Target equipment-as-a-service contracting among capital-constrained maintenance providers seeking asset-light fleet access. Lead with rental fleet digitization capabilities that incumbent fabricators have underinvested in, offering predictive maintenance scheduling as a differentiated service layer. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across IoT-enabled fleet operations as sensor hardware and connectivity infrastructure consume working capital. Long-term viability favors vertically integrated specialists with captive aluminum processing and documented welding labor pools. Monitor acquisition candidates with established notified body relationships and CE marking track records. The signal to watch is certification backlog duration at German notified bodies, which indicates pricing power inflection for pre-certified system providers.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Acceleration | Pre-emptive certification under EU Machinery Directive revisions locks in procurement eligibility before backlog delays competitor entry. |
| Backward Integration into Aluminum Processing | Captive alloy 6061-T6 extrusion capacity insulates margin stability from commodity price swings affecting frame fabricators. |
| IoT Fleet Digitization | Sensor-enabled asset tracking transforms rental operators into recurring revenue platforms with predictive maintenance services. |
| Integrated Formwork-Scaffolding Bundles | Single-source procurement consolidation by Yangtze River Delta infrastructure developers favors full-system suppliers over pure-play access providers. |
| Certified Welder Training Pipeline | Captive aluminum TIG welding labor pools overcome the structural scarcity constraining fleet expansion velocity outside German clusters. |
Research Methodology
Cross-validation between primary interviews with bridge construction procurement directors, rental fleet operations managers, and aluminum fabrication plant engineers anchors the qualitative findings. Secondary validation draws from EU Machinery Directive implementation notices, OSHA scaffold standard enforcement records, China GB 51210 technical code amendments, and customs trade data for aluminum alloy 6061-T6 billet movements. Bottom-up project pipeline assessments across German autobahn renewal programs and Yangtze River Delta high-speed rail corridors were triangulated against top-down infrastructure spending forecasts.
Calibration against historical repositioning frequency data and fleet utilization rates from rental operators informed the analytical framework across the projection horizon. Segmentation dimensions modeled include product configuration type, frame material technology, application context, and end-user procurement mode. CAGRs were derived from elasticity-adjusted demand curves incorporating aluminum price volatility scenarios and certification timeline assumptions. Industry-specific inputs encompass bridge soffit access cycle durations and power plant maintenance scheduling patterns.
Sensitivities concentrate around aluminum commodity price trajectories, notified body certification backlog durations, and contractor balance sheet constraints shifting capital purchase toward operational expenditure treatment. Forecasts reflect documented assumptions regarding regulatory implementation timelines and infrastructure program funding continuity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electro-Mech Systems
Tubular Motors Market
Electro-Mech Systems
HVAC Relay Market
Electro-Mech Systems
Wiring Duct Market
Electro-Mech Systems
Mechanical Auger Boring Machine Market
Electro-Mech Systems
Rodless Cylinders Market
Electro-Mech Systems
Agitator Drive Units Market
Electro-Mech Systems
Elevator Door-Motor Market
Electro-Mech Systems
Electric Winch Market
Electro-Mech Systems
Escalators and Moving Walkways Market
Electro-Mech Systems
Light Gauge Framing System Market
Electro-Mech Systems
Automatic Slack Adjusters Market
Electro-Mech Systems
Hydraulic Cab Tilt System Market
Electro-Mech Systems
Electric Overhead Travelling (EOT) Cranes Market
Electro-Mech Systems
Rigid Metal Electrical Conduit Market