
 Ultraviolet Light Stabilizer Market | 2026-2036
Ultraviolet Light Stabilizer Market Size, Share, and Industry Trends Forecast 2026-2036
Ultraviolet Light Stabilizer Market Insights
The split between premium and commodity ultraviolet light stabilizer tiers is repositioning around thermal stability thresholds and food-contact certification requirements. BASF SE leverages its integrated antioxidant portfolio to anchor high-margin automotive contracts. SONGWON Industrial Group sustains volume leadership through backward integration into key intermediates. Rianlon Corporation competes on cost-optimized benzotriazole grades for Asian packaging converters.
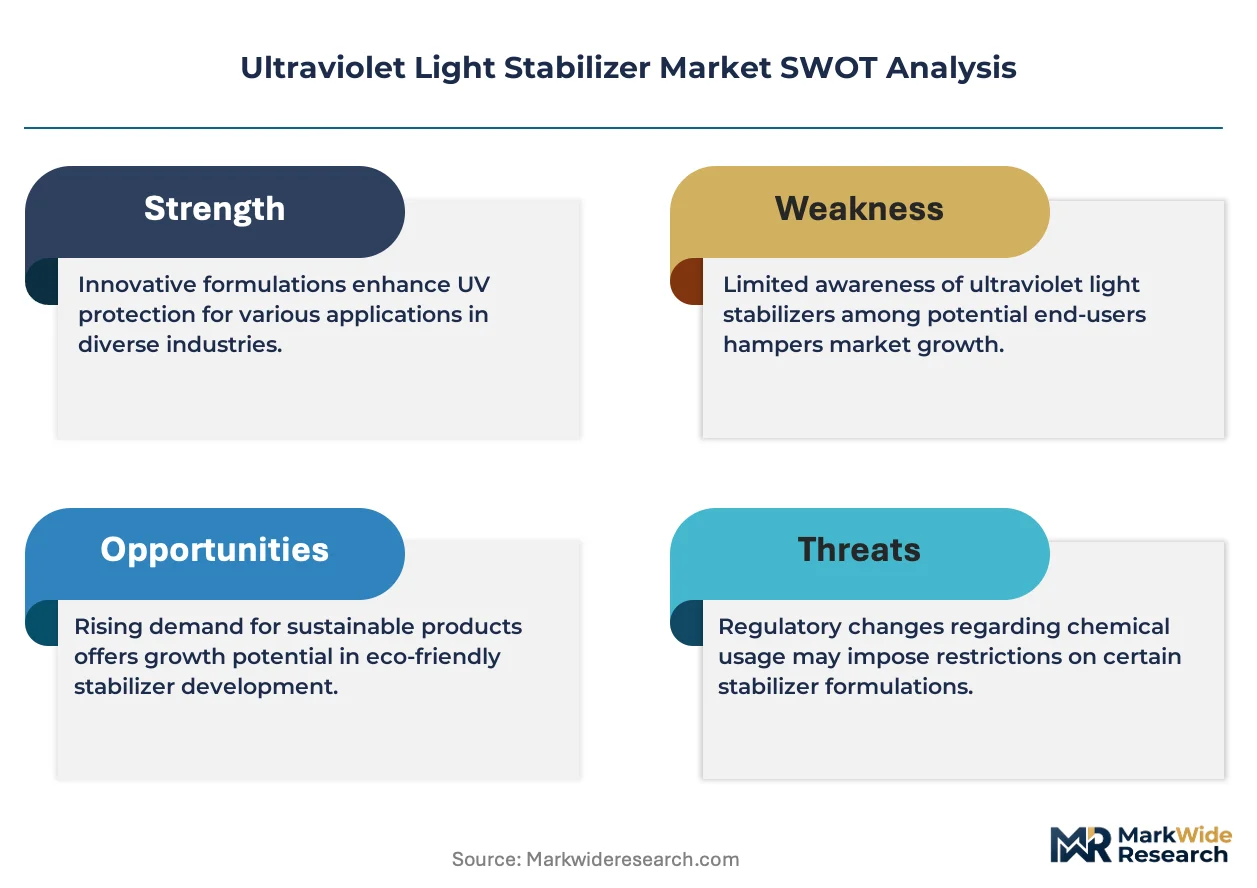
Ultraviolet light stabilizers comprise organic compounds—predominantly hindered amine light stabilizers, benzotriazoles, and hydroxybenzophenones—that interrupt photo-oxidation chains in polymer matrices by scavenging free radicals or absorbing UV-B and UV-C radiation below 400 nanometers. Their primary purpose is extending service life of plastics, coatings, and textiles exposed to solar irradiation. Hindered amine light stabilizers command the largest share due to regenerative radical-scavenging chemistry that outlasts sacrificial UV absorbers in agricultural films and automotive clearcoats. Benzotriazole stabilizers dominate electronics applications where transparency and minimal color shift are non-negotiable. The adhesives segment remains underpenetrated relative to plastics and coatings, presenting a latent margin pool for formulation specialists.
EPA regulates volatile organic compound emissions from coating systems containing UV stabilizers, while REACH restricts certain benzotriazole derivatives under authorization requirements. FDA food-contact notifications govern stabilizer migration limits in packaging films sold into the United States. Stakeholders must monitor regulatory divergence between jurisdictions to avoid reformulation costs and supply chain disqualification.
Market Dynamics
Automotive OEM warranty extensions beyond 7 years are forcing reformulation of exterior polymer specifications, creating tiered procurement demands that separate regenerative HALS chemistry from sacrificial UV absorbers in coating contracts.
Growth Catalysts
- REACH authorization tightening:European ECHA restrictions on legacy benzotriazole derivatives are redirecting formulation spend toward compliant hindered amine alternatives in agricultural film applications.
- Under-hood thermal requirements:Automotive manufacturers in Germany specify UV stabilization for engine-bay components exposed to combined heat and irradiation stress above 120°C.
- Photovoltaic encapsulant demand:Solar module producers require UV-stabilized ethylene-vinyl acetate to prevent encapsulant yellowing and power degradation in desert installations.
Market Restraints
- Intermediate supply concentration:Backward integration into 2,4-dihydroxybenzophenone precursors concentrates among Chinese specialty chemical producers, creating single-source vulnerability.
- REACH registration costs:Authorization dossier preparation for novel HALS structures exceeds €500,000 per substance, freezing SME innovation pipelines.
- Silica-based inorganic alternatives:Nano-structured UV-blocking ceramics in premium cosmetic packaging are capturing share from organic benzotriazoles in transparency-critical applications.
Strategic Opportunities
- Adhesives segment penetration:Structural bonding tapes for electric vehicle battery packs represent an untapped application requiring thermal-UV dual stabilization.
- US FDA food-contact expansion:Migration-tested HALS grades for polypropylene hot-fill containers open beverage packaging conversion opportunities.
- Reactive UV stabilizer grafting:Covalent attachment chemistry to polymer backbones is enabling permanent stabilization in recycling streams where extractable additives contaminate regrind.
Industry Challenges
- Formulation chemist scarcity:Expertise in photostabilizer-synergist pairing with hindered phenol antioxidants is retiring faster than training programs replace it.
- Multi-jurisdiction notification timelines:Parallel FDA, EFSA, and NMPA food-contact approvals for new HALS structures extend commercialization cycles beyond 4 years.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ultraviolet Light Stabilizer Market |
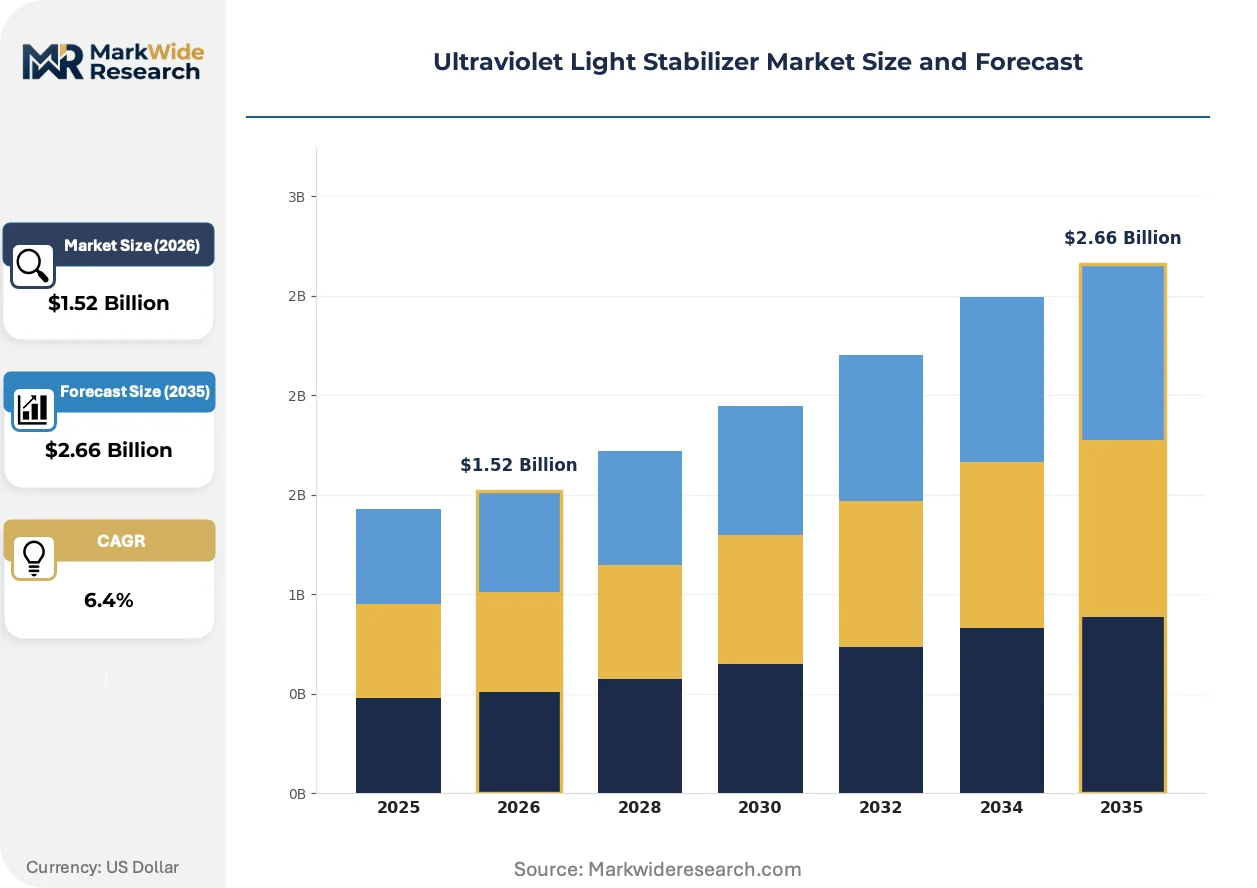
| Market Size in 2026 | $1.52 Billion |
| Market Size in 2035 | $2.66 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hindered Amine Light Stabilizers, Benzotriazole Stabilizers, UV Absorbers, Others End User: Plastics, Coatings, Textiles, Adhesives Application: Automotive, Construction, Packaging, Electronics Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesale |
| Companies Covered | Altana AG, SONGWON Industrial Group, BASF SE, Rianlon Corporation, Adeka Corporation, Clariant AG, Everlight Chemical Industrial Corporation, Valtris Specialty Chemicals, LANXESS AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ultraviolet Light Stabilizer Market Trends and Innovations
Reactive and polymeric UV stabilizer architectures are displacing monomeric additives in durability-critical applications, while regulatory pressure on extractables accelerates permanent-fixation chemistry development across packaging and automotive tiers.
Polymeric hindered amine light stabilizers with molecular weights exceeding 3,000 g/mol are overtaking conventional monomeric grades in automotive clearcoats. OEMs in Germany and Japan specify these non-fogging, non-migrating structures for interior trim applications where volatile loss causes windshield contamination. The shift is compressing demand for traditional low-MW HALS in premium coating contracts.
REACH authorization requirements for benzotriazole derivatives under sunset clause provisions are forcing reformulation of electronics-grade polycarbonate. ECHA's 2025 deadline for 2-(2H-benzotriazol-2-yl)-4,6-di-tert-pentylphenol is redirecting optical film producers toward hydroxyphenyl-triazine alternatives. Japanese display manufacturers are accelerating qualification timelines to secure supply continuity.
Specification-driven procurement consolidation is concentrating buying power among tier-1 automotive coaters. Direct contracting between BASF and Volkswagen, bypassing traditional distributor channels, is reshaping margin capture in European supply chains. This disintermediation is most visible in Germany, where OEMs now mandate stabilizer lot-traceability to resin compounders.
Ultraviolet Light Stabilizer Market Segmentation
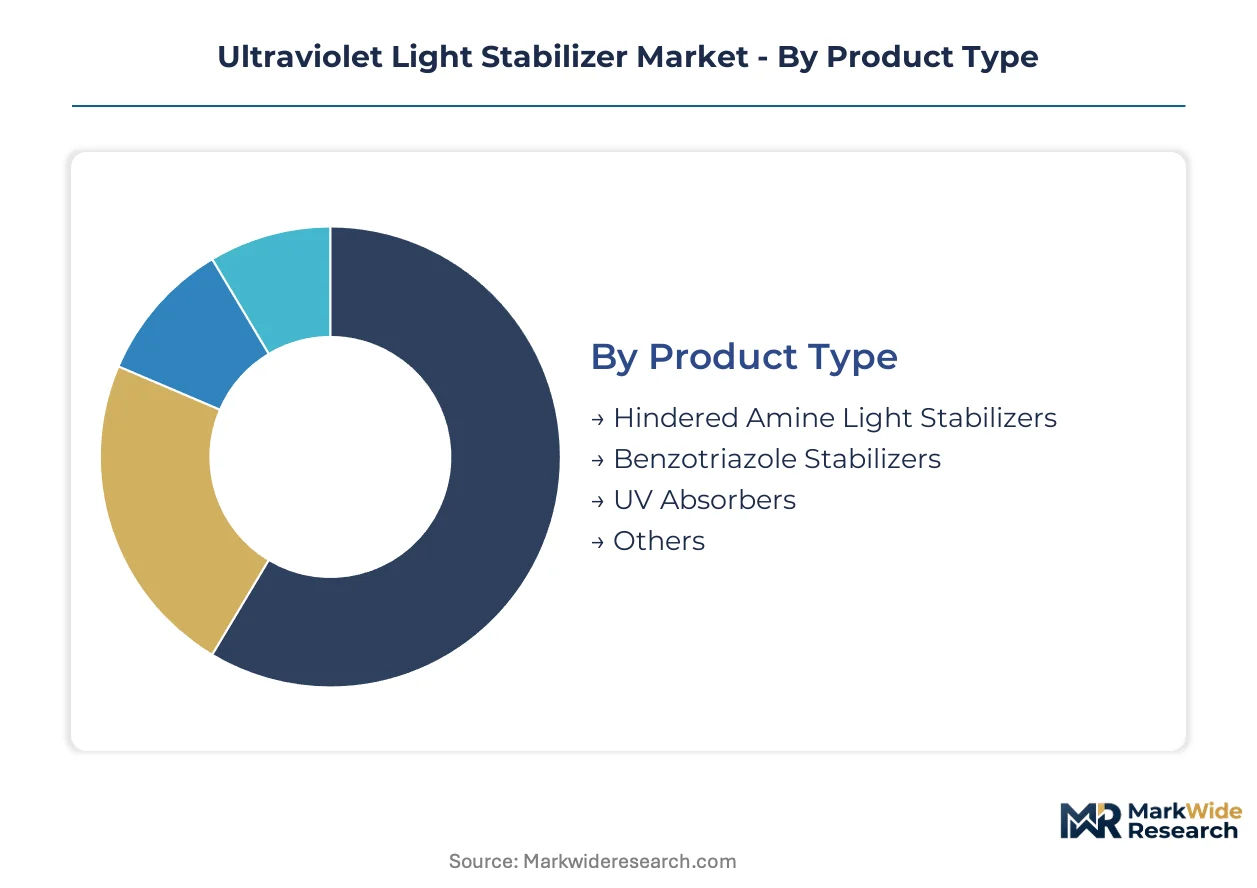
UV stabilizer procurement splits across certification requirements that separate food-contact grades from industrial specifications. Automotive OEMs now mandate lot-traceability that fragments supply chains by channel and geography.
Product Type:
FDA food-contact notifications and REACH authorization dossiers concentrate on benzotriazole and HALS chemistries differently, with migration-tested grades commanding premium positioning against industrial-only alternatives.
- Hindered Amine Light Stabilizers:Regenerative radical-scavenging chemistry enables extended service life in agricultural films and automotive clearcoats. German automotive OEMs specify HALS for under-hood components exposed to combined thermal-UV stress above 120°C, with procurement consolidating around backward-integrated suppliers.
- Benzotriazole Stabilizers:Sacrificial UV-B and UV-C absorption below 400 nanometers delivers transparency-critical performance in electronics-grade polycarbonate. Japanese display manufacturers are accelerating qualification timelines as ECHA sunset clauses approach for legacy derivatives.
- UV Absorbers:Hydroxybenzophenone chemistry serves cost-sensitive packaging converters in Asia-Pacific markets.
- Others:Hydroxyphenyl-triazine alternatives are gaining traction in optical film reformulations.
Leading the category by volume: Hindered Amine Light Stabilizers. Growing fastest: Hydroxyphenyl-triazine alternatives.
End User:
Margin structures diverge sharply between specification-driven automotive coatings and commodity packaging films, with adhesives representing an underpenetrated pool for thermal-UV dual stabilization formulations.
- Plastics:Polypropylene hot-fill containers and agricultural films drive food-contact HALS demand with FDA migration limits governing formulation selection.
- Coatings:Automotive clearcoat warranties beyond seven years force regenerative chemistry procurement from tier-1 German and Japanese OEMs.
- Textiles:Outdoor fabric applications in construction and recreational markets require wash-durable stabilization.
- Adhesives:Structural bonding tapes for electric vehicle battery packs remain nascent, lacking qualified thermal-UV dual stabilizer systems.
Highest margin capture: Coatings. Steepest expansion trajectory: Adhesives.
Application:
Regulatory pressure intensifies by end-use, with automotive and packaging facing divergent compliance burdens from EPA emissions rules versus FDA food-contact protocols.
- Automotive:Exterior trim and under-hood specifications in Germany and Japan concentrate demand for non-fogging polymeric HALS with molecular weights exceeding 3,000 g/mol.
- Construction:Roofing membranes and glazing profiles require weathering resistance in high-irradiation desert installations.
- Packaging:Beverage hot-fill containers in the United States demand migration-tested grades with full FDA notification pathways.
- Electronics:Display films and photovoltaic encapsulants prioritize minimal color shift and yellowing resistance.
Dominant application by procurement value: Automotive. Fastest qualification activity: Electronics.
Distribution Channel:
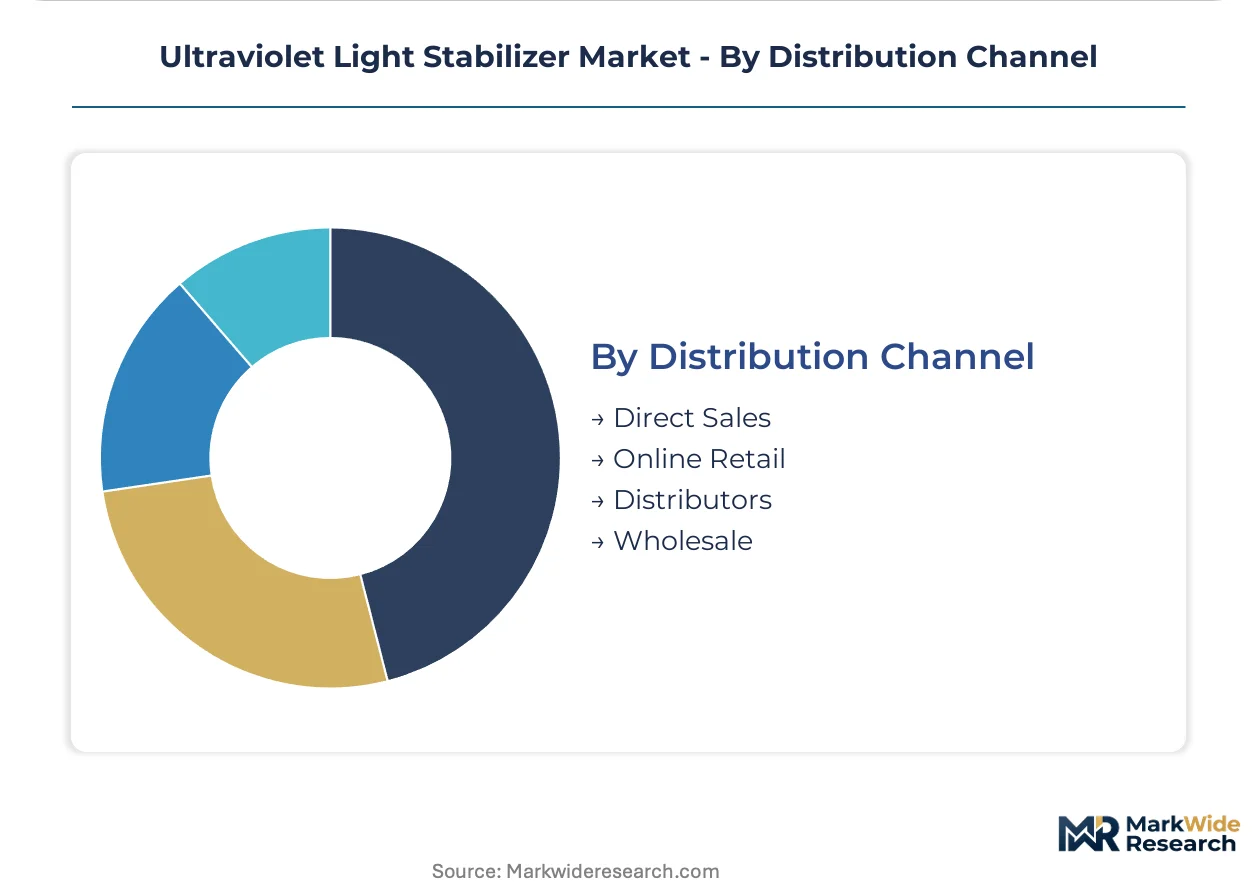
Direct contracting between BASF and Volkswagen in Germany is disintermediating traditional distributor channels, compressing margins for intermediaries while rewarding lot-traceability capabilities.
- Direct Sales:Automotive tier-1 coaters in Germany and Japan now mandate stabilizer lot-traceability to resin compounders, bypassing distributors entirely.
- Distributors:Regional chemical distributors serve mid-volume packaging converters lacking specification expertise.
- Online Retail:Small-batch procurement for R&D and specialty textile applications.
- Wholesale:Commodity benzotriazole grades for Asian packaging markets.
Channel concentration: Direct Sales. Emerging channel: Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ludwigshafen anchors European stabilizer formulation activity, where integrated chemical producers supply automotive OEMs with traceable HALS grades. Procurement consolidation around direct manufacturer relationships is reshaping regional distribution patterns.
Germany
Automotive OEMs in Stuttgart and Munich mandate UV stabilization for under-hood components exposed to thermal stress above 120°C. ECHA REACH authorization requirements for legacy benzotriazole derivatives are accelerating reformulation toward compliant hindered amine alternatives. The Rhine-Neckar chemical corridor concentrates backward-integrated production serving Volkswagen and BMW direct contracts.
United States
EPA volatile organic compound regulations govern coating systems containing UV stabilizers across automotive and construction applications. FDA food-contact notifications restrict stabilizer migration limits in polypropylene hot-fill containers for beverage packaging. The Gulf Coast petrochemical cluster supplies intermediates to domestic formulators serving Midwest automotive plants.
China
Packaging converters in Guangdong and Zhejiang procure cost-optimized benzotriazole grades for export-oriented film production. NMPA food-contact standards and GB technical regulations govern additive safety in domestic packaging applications. The Yangtze River Delta concentrates specialty chemical manufacturing with captive supply of 2,4-dihydroxybenzophenone precursors.
Japan
Display manufacturers in Osaka and Nagoya accelerate qualification timelines for hydroxyphenyl-triazine alternatives ahead of ECHA sunset deadlines. METI industrial standards guide stabilizer performance specifications in electronics-grade polycarbonate. The Chubu region hosts precision optical film producers transitioning from legacy benzotriazole chemistry.
South Korea
Photovoltaic module producers in Gyeonggi-do require UV-stabilized ethylene-vinyl acetate encapsulants for desert installation exports. MFDS food-contact regulations align with FDA migration limits for packaging applications. The Seoul Capital Area concentrates solar energy material supply chains integrating stabilizer procurement with module assembly.
Ultraviolet Light Stabilizer Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across differentiated stabilizer chemistries. The vendor base separates into integrated multinational chemical conglomerates, regional specialty additive houses, and focused Chinese intermediate suppliers. Three strategic archetypes dominate: backward-integrated producers controlling key raw material streams, formulation specialists bundling stabilizers with antioxidant synergists, and cost-optimized regional suppliers serving commodity packaging markets. Competitive dynamics center on direct OEM contracting disintermediating distributors, and regulatory-driven reformulation services capturing premium positioning.
Among European integrated chemical producers, BASF SE and LANXESS AG exemplify the backward-integrated archetype with captive supply of hindered amine intermediates. SONGWON Industrial Group occupies a position bridging Korean production scale with global automotive specification expertise. These three entities represent contrasting geographic anchors for procurement consolidation trends.
| Leading Market Players |
|---|
| Altana AG |
| SONGWON Industrial Group |
| BASF SE |
| Rianlon Corporation |
| Adeka Corporation |
| Clariant AG |
| Everlight Chemical Industrial Corporation |
| Valtris Specialty Chemicals |
| LANXESS AG |
| Others |
Pricing and Supply Chain Analysis
Backward-integrated chemical conglomerates with captive hindered amine intermediate production enforce pricing discipline through volume commitments to German automotive OEMs, while asset-light Chinese benzotriazole specialists compete on spot-market responsiveness for Asian packaging converters. This ownership split concentrates margin capture upstream with integrated producers and compresses distributor margins where specification expertise is absent.
Pricing Analysis
Warranty-linked performance guarantees anchor value-based pricing for automotive-grade HALS, with German OEMs paying premiums for lot-traceability and thermal stability above 120°C. Certification tiers separate FDA food-contact notifications from industrial-only grades, creating three-tier pricing structure across premium, standard, and economy levels. Cost compression in commodity benzotriazoles intensifies as Guangdong packaging converters consolidate procurement volumes. Mid-volume coating formulators show highest price sensitivity, while tier-1 automotive coaters prioritize specification compliance over unit cost.
Supply Chain Analysis
Container freight volatility from Shanghai to Hamburg disrupts just-in-time delivery of 2,4-dihydroxybenzophenone precursors, forcing European formulators to carry elevated safety stock. Manufacturing concentrates in China for benzotriazole intermediates, Germany for HALS formulation, and South Korea for photovoltaic-grade specialties. Raw material dependencies include hindered amine precursors, phenolic antioxidants, and ethylene-vinyl acetate base resins. Single-source vulnerability in Chinese specialty chemical producers creates supply chain risk. Distribution runs through direct manufacturer contracts for automotive tier-1s and regional distributors for packaging converters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Polymeric HALS architectures with molecular weights exceeding 3,000 g/mol are displacing monomeric grades in automotive clearcoats, creating a technology-transition phase where legacy benzotriazole suppliers face reformulation deadlines under ECHA sunset clauses.
For Market Incumbents: Anchor specification-driven procurement relationships by investing in reactive UV stabilizer grafting capabilities that enable permanent fixation for recycling streams. Deepen backward integration into hindered amine intermediates to defend against Chinese cost-optimized entrants. Prioritize certification investment for FDA food-contact HALS grades as beverage packaging converters seek migration-tested alternatives to benzotriazoles. For New Entrants and Emerging Players: Reactive covalent attachment chemistry offers a technology-first wedge into the adhesives segment for electric vehicle battery pack bonding tapes, where thermal-UV dual stabilization remains underqualified. Target structural adhesive formulators in South Korea and Germany with pre-validated stabilizer-synergist bundles. Pursue direct technical sales engagement bypassing distributor markups to capture margin in specification-naive mid-volume accounts. For Investors and Strategic Acquirers: Distressed-cycle entries favor regional specialty additive houses with existing ECHA authorization dossiers and automotive qualification pipelines in Germany. Long-term viability hinges on regulatory compliance moats rather than cost position alone. Watch for inflection signals in Japanese display manufacturer qualification timelines for hydroxyphenyl-triazine alternatives as benzotriazole sunset deadlines approach.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into HALS Intermediates | Captive supply of hindered amine precursors secures margin capture from German automotive OEM direct contracts. |
| Reactive UV Stabilizer Grafting Development | Permanent fixation chemistry addresses ECHA extractables restrictions in packaging recycling streams. |
| FDA Food-Contact Certification Investment | Migration-tested HALS grades unlock polypropylene hot-fill container conversions in US beverage packaging. |
| Direct OEM Contracting Bypass | Lot-traceability mandates from Volkswagen and BMW disintermediate distributor channels in European supply chains. |
| Adhesives Segment Technical Sales Buildout | Electric vehicle battery pack bonding tapes lack qualified thermal-UV dual stabilizer systems. |
Research Methodology
Multi-period observation of ECHA authorization timelines, automotive OEM warranty extensions, and photovoltaic encapsulant procurement patterns anchored the trend analysis, supplemented by interviews with plant managers at HALS production facilities, procurement leads at German tier-1 automotive coaters, distribution channel partners serving Asian packaging converters, and technical R&D directors at stabilizer formulators. Secondary validation drew from customs and trade data, Cefic chemical industry reports, SEC 10-K filings of listed additive producers, and FDA food-contact notification databases. Bottom-up volume modeling triangulated against top-down market sizing across product chemistry tiers.
Input-output matrices mapped hindered amine, benzotriazole, and hydroxyphenyl-triazine production volumes to end-use demand in plastics, coatings, adhesives, and textiles across the analysis window. Segmentation dimensions included certification grade, thermal stability threshold, end-use industry, and regional regulatory cluster. CAGRs derived from regression analysis of historical procurement volumes and forward-looking OEM specification timelines. Industry-specific forecast inputs incorporated REACH sunset clause implementation schedules and photovoltaic installation growth trajectories.
Several conditions sit outside the modeled scope, including unannounced regulatory amendments, abrupt raw material cost shocks, and technology substitutions beyond polymeric HALS architectures. Forecasts reflect documented assumptions about ECHA enforcement consistency and automotive warranty term stability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Plastics Modifiers Market
Additives
Zinc Dialkyldithiophosphates Additive Market
Additives
North America Fuel Additives Market
Additives
Global Feed Acidulants Market
Additives
India Feed Additives Market
Additives
Inorganic Filler Market
Additives
North America Pectin Market
Additives
Global Glass Additives Market
Additives
Octane Improver Fuel Additives Market
Additives
Automotive Additives Market
Additives
Ammonium Phosphatide Market
Additives
Sodium Stearyl Fumarate Market
Additives
Magnesium Stearate Market
Additives
Anti-Creasing Agent Market
Additives
Glycyrrhizic Acid Glycosides Market
Additives
Gluconic Acid and Derivatives Market