
 Performance Minerals Additives Market | 2026-2036
Performance Minerals Additives Market Size, Share, and Industry Trends Forecast 2026-2036
Performance Minerals Additives Market Intelligence
Pricing for specialty-grade performance minerals is decoupling from commodity mineral filler benchmarks as surface treatment complexity and particle size distribution tighten. Imerys S.A. leverages integrated quarry-to-delivery control across European calcium carbonate deposits. Minerals Technologies Inc. anchors its position through precipitated calcium carbonate technology leadership in paper and plastics substitution. Omya AG competes via global distribution density and on-site slurry production partnerships with coating manufacturers.
Performance minerals additives comprise inorganic solids—calcium carbonate, talc, barite, kaolin clay, and diatomaceous earth—processed to specific particle sizes between 0.5 and 50 microns, surface-treated with stearates or silanes to enhance dispersion, and engineered to modify rheology, reinforcement, or barrier properties in host matrices. The product type dimension shows calcium carbonate occupying the largest volume position across plastics and construction applications, while specialty-grade talc generates disproportionate margin contribution in automotive thermoplastics and food-contact packaging. Application segmentation reveals paints and coatings demanding ultrafine precipitated grades with controlled top-cut particle distribution, whereas rubber compounding absorbs coarser ground barite for density and stiffness modulation.
REACH registration requirements in Europe and EPA Toxic Substances Control Act thresholds in the United States are elevating trace metal testing burdens and documentation depth for industrial-grade mineral imports. China's GB standards for plastic additives and India's BIS certification for construction materials are creating parallel compliance tracklines that fragment supplier qualification protocols. Stakeholders must monitor how evolving food-contact regulations from EFSA and FDA reshape pharmaceutical and food-grade talc sourcing geography, as these grades command expanding premium positioning against industrial alternatives.
Market Dynamics
Automotive lightweighting mandates in Germany and Japan are compressing mineral filler specifications toward sub-micron particle distributions with enhanced polymer compatibility, forcing additive suppliers to recalibrate surface treatment chemistries and captive grinding investments.
Growth Catalysts
- REACH compliance thresholds:ECHA registration requirements for industrial mineral imports are elevating trace metal documentation burdens, advantaging European quarry operators with integrated testing laboratories over third-party traders.
- EV battery thermal management:Precipitated calcium carbonate with controlled top-cut distribution is absorbing demand from lithium-ion pack housings seeking flame-retardant mineral loadings without conductivity compromise.
- India construction acceleration:BIS certification requirements for polymer-modified cement are concentrating qualified talc and barite sourcing through domestic mineral processors with captive beneficiation assets.
Market Restraints
- High-purity barite concentration:API-grade drilling barite shortages are spilling into industrial filler markets, elevating input cost volatility for density-modified rubber compounds and sound-dampening automotive parts.
- Ultrafine grinding energy intensity:Sub-2 micron calcium carbonate production requires 40% higher specific energy consumption than standard grades, compressing margin structures for non-integrated processors without captive power or quarry positions.
- Food-grade talc substitution:EFSA and FDA scrutiny of asbestos trace contamination is accelerating precipitated silica and modified starch displacement in pharmaceutical tablet formulations and rice polishing applications.
Strategic Opportunities
- Brazil automotive polymer compounding:ANVISA alignment with USP standards for medical-grade mineral fillers is opening qualified supply positions for surface-treated calcium carbonate in surgical instrument housings and diagnostic device chassis.
- On-site slurry production partnerships:Co-located wet milling operations at coating manufacturer plants are eliminating dry powder handling costs and enabling just-in-time rheology modification for waterborne architectural paint lines.
- EU Green Deal carbon border adjustments:CBAM pilot phase inclusion of mineral products is creating first-mover advantage for quarry operators with renewable energy-powered classification and pneumatic conveying systems.
Industry Challenges
- Particle surface characterization expertise:Advanced silane coupling chemistry and zeta potential optimization require PhD-level materials scientists, creating recruitment competition with semiconductor and battery material sectors.
- Legacy ERP integration with batch tracking:REACH and FDA lot-level traceability mandates are forcing mineral processors to retrofit 1990s-era manufacturing execution systems with serialization modules, stretching IT implementation timelines.
- Multi-jurisdiction certification overlap:Simultaneous pursuit of USP, EP, and JP pharmacopeia approvals for pharmaceutical-grade talc creates redundant stability testing protocols and divergent impurity specification conflicts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Performance Minerals Additives Market |
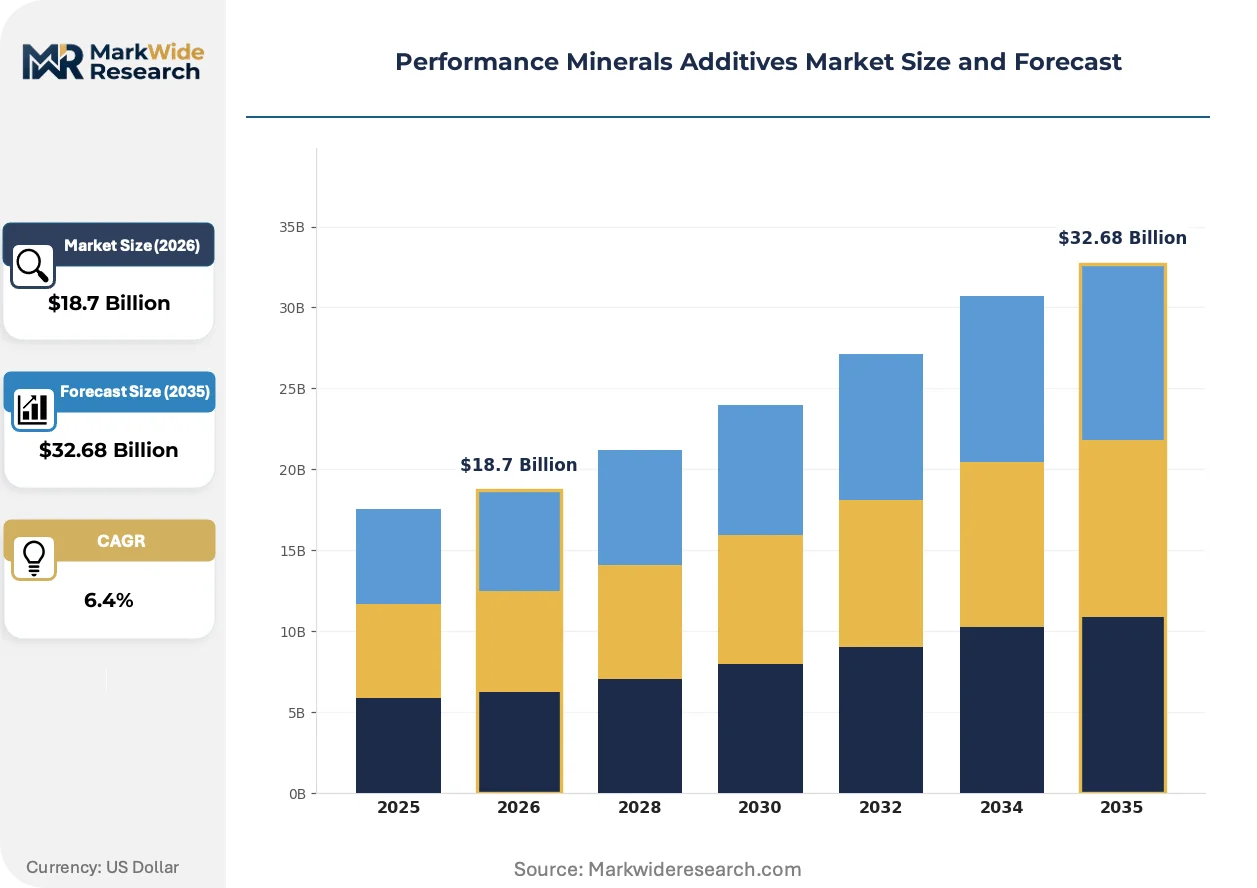
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Paints, Coatings, Plastics, Rubber Product Type: Calcium Carbonate, Talc, Barite, Clay End User: Construction, Automotive, Packaging, Consumer Goods Grade: Industrial, Food Grade, Pharmaceutical, Specialty |
| Companies Covered | Imerys S.A., Minerals Technologies Inc., Omya AG, BASF SE, LKAB Minerals, Sibelco Group, EP Minerals, The Chemours Company, Dicalite Management Group, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Performance Minerals Additives Market Strategic Shifts & Innovations
Surface functionalization chemistry and particle engineering are converging to displace commodity mineral fillers in performance-critical applications, while regulatory traceability requirements are digitizing supply chain documentation.
Surface-treated nano-calcium carbonate with stearate encapsulation is absorbing demand from automotive TPO bumper applications seeking scratch resistance without density penalties. Tier-1 compounders in Germany and Japan are qualifying these grades for 25% mineral loading targets in electric vehicle exterior panels. The technology is absorbing volume from conventional ground calcium carbonate in Class-A surface applications where gloss retention and paint adhesion determine specification approval.
EPA Toxic Substances Control Act Section 8(a) reporting expansions for industrial minerals are elevating pre-manufacture notification burdens for imported barite and kaolin. Mineral traders without US-based technical data generation capabilities are facing 180-day review windows that disrupt just-in-time supply contracts. The friction concentrates qualified supplier positions among North American quarry operators with in-house toxicology and environmental fate testing laboratories.
Coating manufacturers are consolidating mineral additive procurement through direct quarry partnerships that bypass regional distributor markups. Paints and coatings producers in Italy and Spain are negotiating toll-milling agreements with calcium carbonate processors for site-specific slurry formulations with locked rheology profiles. The pattern is most visible in Southern European architectural coatings where waterborne technology transitions have compressed formulation tolerance windows for viscosity and sag resistance.
Performance Minerals Additives Market Segmentation
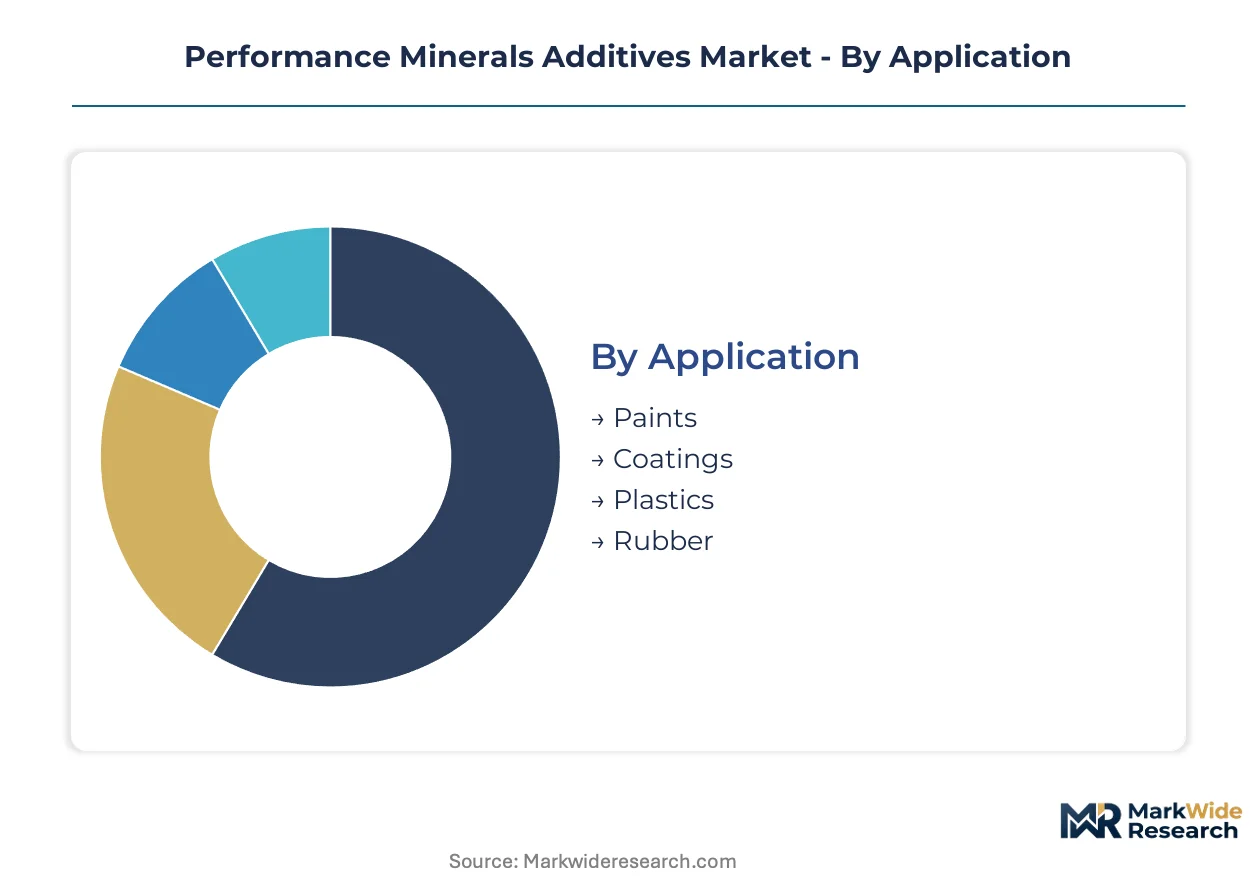
Performance minerals additives fragment across four intersecting dimensions that determine specification intensity, regulatory burden, and margin capture. Product chemistry and surface treatment protocols vary sharply between commodity industrial grades and certified pharmaceutical tiers, while application requirements in automotive lightweighting and food-contact packaging drive divergent particle engineering investments.
Application:
Upgrade cycles in coating formulation and polymer compounding are compressing specification windows and forcing mineral processors to recalibrate particle distribution curves.
- Paints:Ultrafine precipitated calcium carbonate with controlled top-cut distribution dominates waterborne architectural formulations. Italian and Spanish coating manufacturers are consolidating procurement through direct quarry partnerships for locked rheology profiles.
- Coatings:Surface-treated nano-calcium carbonate with stearate encapsulation absorbs demand from automotive TPO bumper applications seeking scratch resistance without density penalties. German Tier-1 compounders qualify these grades for 25% mineral loading targets in electric vehicle exterior panels.
- Plastics:Sub-micron talc and surface-modified calcium carbonate modify rheology and reinforcement in polypropylene compounds.
- Rubber:Coarser ground barite modulates density and stiffness in sound-dampening automotive parts and industrial belting.
Paints sits at the top of the volume ranking, with Coatings climbing the fastest.
Product Type:
Cost tier differentiation separates commodity ground minerals from precipitated and surface-engineered grades that command 3-4x unit economics.
- Calcium Carbonate:Ground limestone serves construction and commodity plastics, while precipitated grades with silane surface treatment penetrate automotive thermoplastics and food-contact packaging. Imerys S.A. leverages integrated quarry-to-delivery control across European deposits.
- Talc:Lamellar magnesium silicate concentrates margin contribution in automotive thermoplastics and pharmaceutical tablet formulations. EFSA and FDA scrutiny of asbestos trace contamination is accelerating displacement by precipitated silica in rice polishing applications.
- Barite:Barium sulfate density modifier faces input cost volatility as API-grade drilling barite shortages spill into industrial filler markets.
- Clay:Kaolin and bentonite grades serve paper coating and drilling fluid applications with regional sourcing concentration in Georgia and Brazil deposits.
Calcium Carbonate holds the broadest volume position, with Talc generating disproportionate margin expansion.
End User:
Customer type segmentation reveals divergent procurement patterns between specification-tolerant construction buyers and certification-intensive automotive and food-contact purchasers.
- Construction:Polymer-modified cement and concrete additives absorb coarse-ground calcium carbonate and talc. India's BIS certification requirements concentrate qualified sourcing through domestic mineral processors with captive beneficiation assets.
- Automotive:Lightweighting mandates in Germany and Japan compress mineral filler specifications toward sub-micron particle distributions with enhanced polymer compatibility.
- Packaging:Food-contact regulations from EFSA and FDA reshape pharmaceutical and food-grade talc sourcing geography, with these grades commanding expanding premium positioning.
- Consumer Goods:Personal care and household product formulations utilize ultrafine precipitated grades for opacity and texture modification.
Construction anchors absolute volume consumption, with Automotive expanding most quickly on specification intensity.
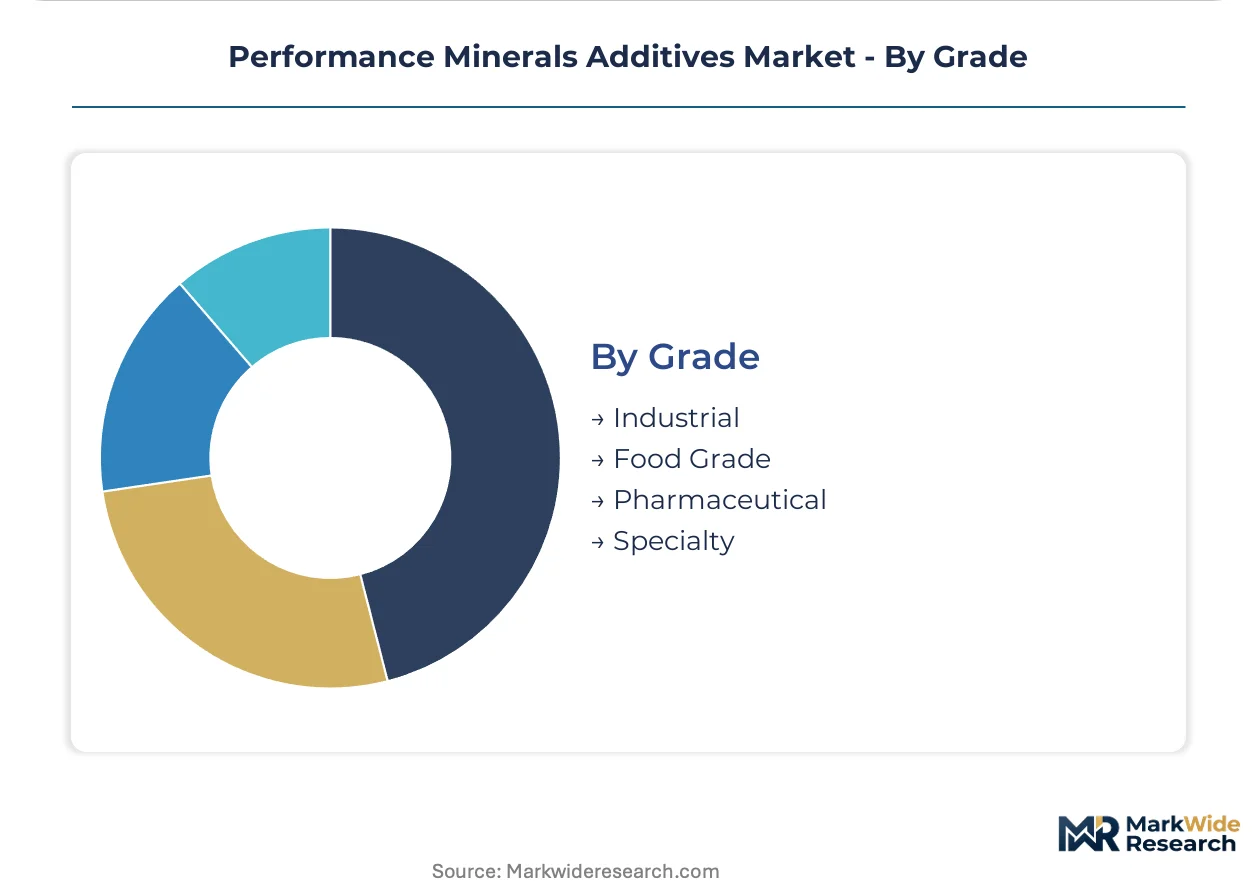
Grade:
Certification tier determines testing burden, documentation depth, and allowable impurity thresholds across regulatory jurisdictions.
- Industrial:Standard ground and precipitated grades serve non-contact applications with REACH registration and EPA Toxic Substances Control Act compliance requirements. Traders without US-based technical data generation capabilities face 180-day pre-manufacture notification review windows.
- Food Grade:Talc and calcium carbonate for direct food contact require EFSA and FDA clearance with lot-level traceability mandates forcing retrofit of legacy manufacturing execution systems.
- Pharmaceutical:USP, EP, and JP pharmacopeia approvals for tablet formulations and excipients create redundant stability testing protocols and divergent impurity specification conflicts.
- Specialty:Surface-functionalized nano-grades with silane coupling chemistry and zeta potential optimization require PhD-level materials scientists, creating recruitment competition with semiconductor and battery material sectors.
Industrial grade maintains volume dominance, with Specialty grades gaining share fastest on margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialist mineral processing engineers cluster in Germany's Ruhr industrial belt and Japan's Chubu region, anchoring the technical workforce that drives sub-micron particle engineering and surface treatment chemistry innovation.
United States
Automotive lightweighting programs in Michigan and Ohio absorb precipitated calcium carbonate for thermoplastic olefin compounds. EPA Toxic Substances Control Act Section 8(a) reporting expansions elevate pre-manufacture notification burdens for imported barite and kaolin. Georgia's sedimentary kaolin belt concentrates paper coating and drilling fluid grade production with integrated beneficiation infrastructure.
Germany
Tier-1 automotive compounders in Bavaria and Baden-Württemberg qualify surface-treated nano-calcium carbonate for electric vehicle exterior panels. REACH registration requirements through ECHA advantage domestic quarry operators with integrated testing laboratories over third-party traders. The Upper Palatinate region anchors integrated calcium carbonate processing from quarry to slurry delivery.
China
Specialty-grade barite and surface-treated calcium carbonate demand concentrates in Yangtze River Delta manufacturing clusters. GB standards for plastic additives create parallel compliance tracklines that fragment supplier qualification protocols. Shandong Province's mineral processing corridor scales precipitated calcium carbonate output for lithium-ion battery pack housings.
India
Polymer-modified cement applications in Maharashtra and Gujarat absorb coarse-ground talc and barite. BIS certification requirements concentrate qualified sourcing through domestic mineral processors with captive beneficiation assets. Rajasthan's marble belt supplies construction-grade calcium carbonate with regional grinding infrastructure.
Brazil
Automotive polymer compounding in São Paulo and Minas Gerais opens qualified supply positions for surface-treated calcium carbonate. ANVISA alignment with USP standards for medical-grade mineral fillers expands specification intensity for surgical instrument applications. Bahia's sedimentary deposits anchor regional barite sourcing for density-modified rubber compounds.
Performance Minerals Additives Market Key Industry Players
Capital-heavy quarry operators compete with asset-light toll-milling specialists across the value chain. The market structure concentrates among integrated European processors with captive mineral reserves and Asian precipitated carbonate specialists with chemical process expertise. Three archetypes dominate: vertically integrated quarry-to-delivery operators, precipitated mineral technology leaders, and regional toll-milling service providers. Capacity expansion in sub-micron grinding assets and strategic partnerships for on-site slurry production represent the dominant competitive moves reshaping procurement relationships.
Among integrated European operators, Imerys S.A. and Omya AG exemplify the quarry-to-delivery archetype with captive mineral reserve positions. Minerals Technologies Inc. occupies a position representing precipitated calcium carbonate technology leadership. These three anchors illustrate how geographic mineral access and surface treatment chemistry capability determine competitive positioning across specification-intensive applications.
| Leading Market Players |
|---|
| Imerys S.A. |
| Minerals Technologies Inc. |
| Omya AG |
| BASF SE |
| LKAB Minerals |
| Sibelco Group |
| EP Minerals |
| The Chemours Company |
| Dicalite Management Group, Inc. |
| Others |
Cost & Logistics Intelligence
Automotive Tier-1 compounders in Germany and Japan are consolidating procurement through direct quarry partnerships for locked rheology profiles, forcing mineral processors to absorb logistics costs and recalibrate margin structures around slurry delivery premiums.
Pricing Analysis
Bundled on-site slurry production contracts command 15-20% premiums over unbundled dry powder spot purchases. Three-tier pricing structure across specialty, industrial, and commodity grades reflects surface treatment complexity and certification burden. Cost compression in industrial-grade calcium carbonate is intensifying because API-grade drilling barite shortages spill into filler markets. Construction buyers in India and Brazil exhibit highest price sensitivity, while pharmaceutical formulators accept steep premiums for USP-certified talc.
Supply Chain Analysis
India's BIS certification requirements and China's GB standards for plastic additives are reshaping sourcing toward domestic mineral processors with captive beneficiation assets. Raw material flows draw from Shandong Province's precipitated carbonate corridor, Rajasthan's marble belt, and Bahia's sedimentary barite deposits. Single-source vulnerability concentrates around Yangtze River Delta grinding capacity for sub-micron grades. Distribution runs through toll-milling partnerships at coating manufacturer plants and regional distributor networks for commodity construction grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EU Green Deal carbon border adjustments disadvantage Chinese exporters against European quarry operators with renewable-powered classification infrastructure.
For Market Incumbents: Cement quarry-to-delivery control through captive slurry production partnerships with German and Italian coating manufacturers. Surface treatment chemistry expertise in silane coupling and zeta potential optimization creates defensive moats against commodity traders facing REACH documentation burdens. Backward integration into renewable-powered grinding assets captures CBAM first-mover positioning. For New Entrants and Emerging Players: Capture Brazil's ANVISA-aligned medical-grade mineral filler qualification gap for surgical instrument housings and diagnostic device chassis. Toll-milling service provision to mid-size coating manufacturers in Southern Europe offers lowest competitive intensity. Partner with automotive compounders for EV battery thermal management grade development. For Investors and Strategic Acquirers: Asymmetric upside sits with precipitated calcium carbonate specialists with chemical process expertise and pharmaceutical-grade certification infrastructure. Long-term viability hinges on surface functionalization chemistry capabilities that displace commodity fillers in automotive lightweighting. Watch for EPA TSCA Section 8(a) enforcement intensity as inflection signal for import-dependent trader distress.| Strategic Initiative | Industry Significance |
|---|---|
| On-site Slurry Production Partnerships | Eliminates dry powder handling costs for Italian and Spanish coating manufacturers. |
| Sub-micron Grinding Capacity Expansion | Captures automotive TPO bumper specifications from German Tier-1 compounders. |
| Pharmaceutical-Grade Certification Investment | Opens USP, EP, and JP pharmacopeia approval positions for tablet excipients. |
| Renewable Energy-Powered Classification | Secures EU Green Deal CBAM compliance advantage for European quarry operators. |
| Direct Quarry-to-Coating Manufacturer Contracts | Bypasses regional distributor markups in waterborne architectural paint procurement. |
Research Approach
Direct dialogue with mineral processing plant managers, procurement leads at automotive Tier-1 compounders, coating manufacturer technical directors, and distribution channel partners anchored qualitative findings. Secondary validation drew from ECHA REACH registration databases, US EPA TSCA filings, Indian BIS certification records, Chinese customs trade data, and Cefic industrial mineral reports. Bottom-up volume modeling triangulated against top-down value estimates across product chemistry, application, end-use, and grade segmentation.
Cross-segment CAGRs emerged from regression analysis against automotive production forecasts, construction spending indices, and coating formulation technology transitions. The analytical framework incorporated particle size distribution intensity, surface treatment protocol complexity, and regional regulatory burden differentials across the projection horizon. Battery thermal management grade absorption rates and food-contact certification timelines served as industry-specific demand drivers.
REACH threshold revisions, EPA enforcement intensity shifts, and API-grade barite supply disruptions are the dominant revision risks to volume and value assumptions. Forecasts reflect documented assumptions regarding automotive lightweighting program adoption curves and pharmaceutical-grade talc substitution rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Microcrystalline Cellulose (MCC) Market
Additives
Asia-Pacific Fuel Additives Market
Additives
Global Propyl Acetate Market
Additives
Global Dicalcium Phosphate (Feed Grade) Market
Additives
Global Scale Inhibitors Market
Additives
Calcium Stearate Market
Additives
Global Inorganic Corrosion Inhibitors Market
Additives
Ruminant Feed Additive Market
Additives
Sodium Diacetate Market
Additives
Silicone Additives Market
Additives
Tartaric Acid Market
Additives
Dishwashing Additives Market
Additives
Refinery Process Additives Market
Additives
Polyethylene Terephthalate Additives Market
Additives
Global Performance Additives Market
Additives
Sodium Potassium Tartrate Market