
 Biofuel Additives Market | 2026-2036
Biofuel Additives Market Size, Share, and Industry Trends Forecast 2026-2036
Biofuel Additives Market Intelligence
Specialty chemical distribution networks are reshaping how biofuel additives reach blenders and terminal operators across major fuel corridors. BASF SE leverages its global manufacturing footprint to supply corrosion inhibitors and cetane improvers to European biodiesel producers. Innospec Inc. anchors its position through specialized detergent and combustion-improver portfolios tailored for ethanol-gasoline blends. Evonik Industries AG competes on antioxidant technology leadership, sustaining R&D intensity for stabilizer formulations that extend fuel shelf life in tropical climates.
Biofuel additives comprise functional chemical compounds blended into ethanol, biodiesel, biobutanol, and bio-DME to enhance combustion efficiency, oxidative stability, and engine compatibility, with typical treat rates ranging from 50 to 2,000 parts per million depending on base fuel quality and storage conditions. These additives prevent phase separation in ethanol-gasoline blends, inhibit microbial growth in biodiesel, and protect fuel system components from acidic corrosion during extended operation. Cetane improvers and stabilizers command disproportionate margin pools due to their critical role in meeting ASTM D6751 and EN 14214 specifications, while antioxidant demand accelerates fastest as biodiesel producers extend supply chains into warmer, higher-humidity regions. The transportation application dominates volume consumption, though agricultural end users represent an emerging segment as farm equipment operators transition to higher biodiesel blends.
The U.S. EPA Renewable Fuel Standard mandates annual renewable volume obligations that directly determine additive procurement levels by domestic fuel suppliers, while the EU F-Gas Regulation and REACH framework constrain certain traditional additive chemistries and accelerate bio-based formulation development. India's BIS standards for ethanol blending and the country's PLI scheme for biofuel infrastructure create parallel compliance-driven demand channels for additive manufacturers. Stakeholders must monitor how evolving carbon intensity scoring in California's Low Carbon Fuel Standard and prospective EU renewable energy directive revisions redefine the performance thresholds that additives must satisfy to maintain blend certification.
Market Dynamics
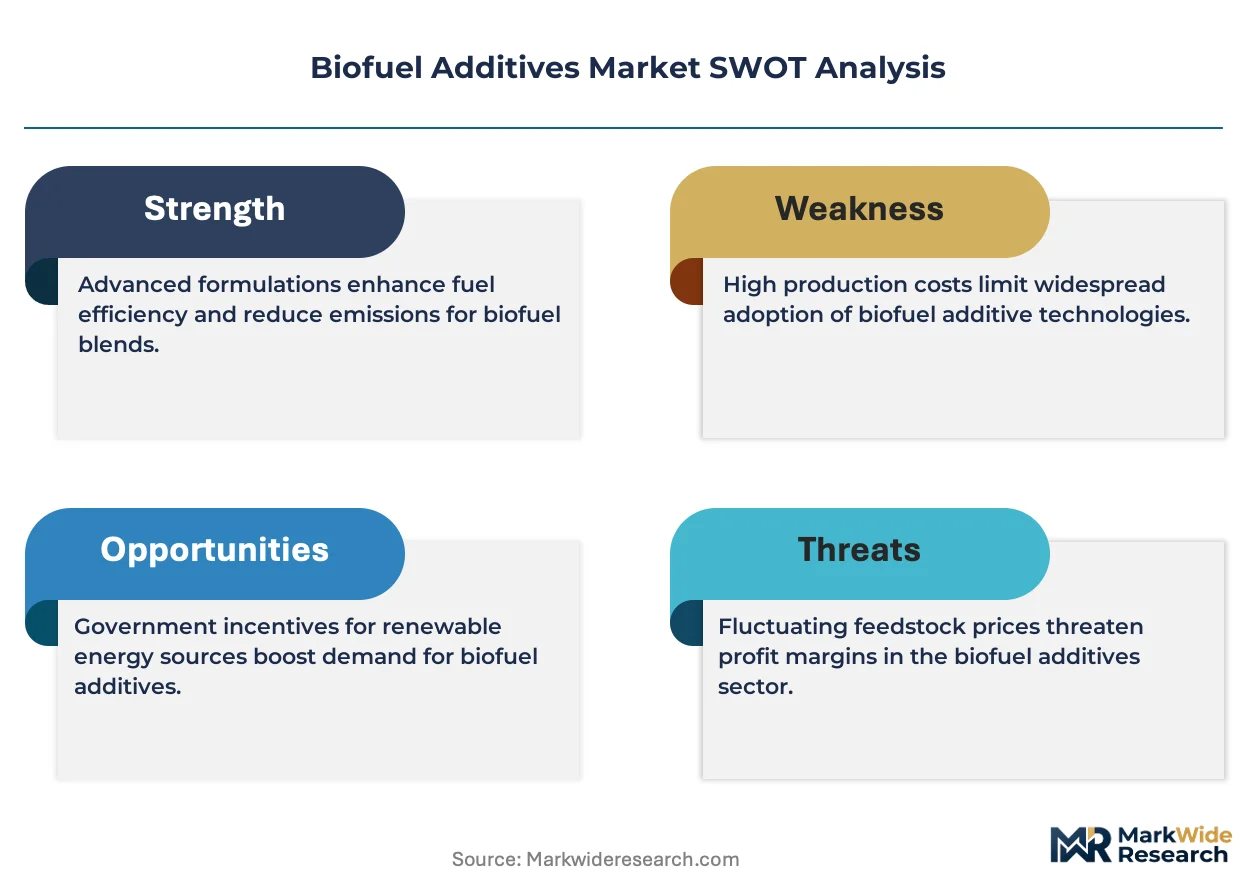
Renewable fuel mandates in the United States and European Union are compressing blend timelines and forcing additive suppliers to accelerate reformulation cycles for higher ethanol and biodiesel concentrations.
Growth Catalysts
- EPA Renewable Fuel Standard:Annual volume obligations mandate escalating ethanol and biodiesel blends, forcing U.S. fuel suppliers to expand additive procurement for phase separation prevention and cetane enhancement.
- Biodiesel oxidation stability gaps:Extended supply chains into tropical and humid climates accelerate demand for antioxidant packages that protect fuel integrity during ocean transit and storage.
- EU Green Deal targets:The European Commission's renewable energy directive revisions tighten carbon intensity thresholds, compelling blenders to invest in reformulation additives that reduce lifecycle emissions.
Market Restraints
- Palm oil feedstock volatility:Biodiesel producers face margin compression when vegetable oil prices spike, constraining discretionary spending on premium stabilizer and detergent packages.
- REACH framework constraints:The European Chemicals Agency's authorization requirements restrict traditional corrosion inhibitor chemistries, forcing costly re-registration and substitution programs.
- Technical limitation in cold flow:Biodiesel's poor low-temperature operability below cloud point thresholds limits year-round deployment in Nordic climates without expensive pour point depressant overdosing.
Strategic Opportunities
- India's ethanol blending roadmap:The country's 20% ethanol blending target by 2025 and PLI scheme for biofuel infrastructure create first-mover positioning for additive suppliers establishing local formulation partnerships.
- Marine biofuel applications:International Maritime Organization decarbonization timelines are opening vessel engine compatibility testing for bio-DME and biodiesel additives that address marine fuel stability challenges.
- Digital blending optimization:Terminal operators are deploying real-time dosing analytics that enable precision additive injection, reducing waste and enabling outcome-based supply contracts with chemical distributors.
Industry Challenges
- ASTM D6751 and EN 14214 synchronization:Additive formulators must maintain dual certification pathways as specification timelines diverge between U.S. and European test protocols for biodiesel quality.
- Specialized chemist scarcity:The intersection of fuel chemistry, regulatory compliance, and engine engineering requires talent pools that traditional petrochemical training programs do not produce at sufficient scale.
- Microbial contamination protocols:Biodiesel's water affinity creates persistent biocide efficacy testing burdens that extend product validation cycles and delay market entry for novel formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biofuel Additives Market |
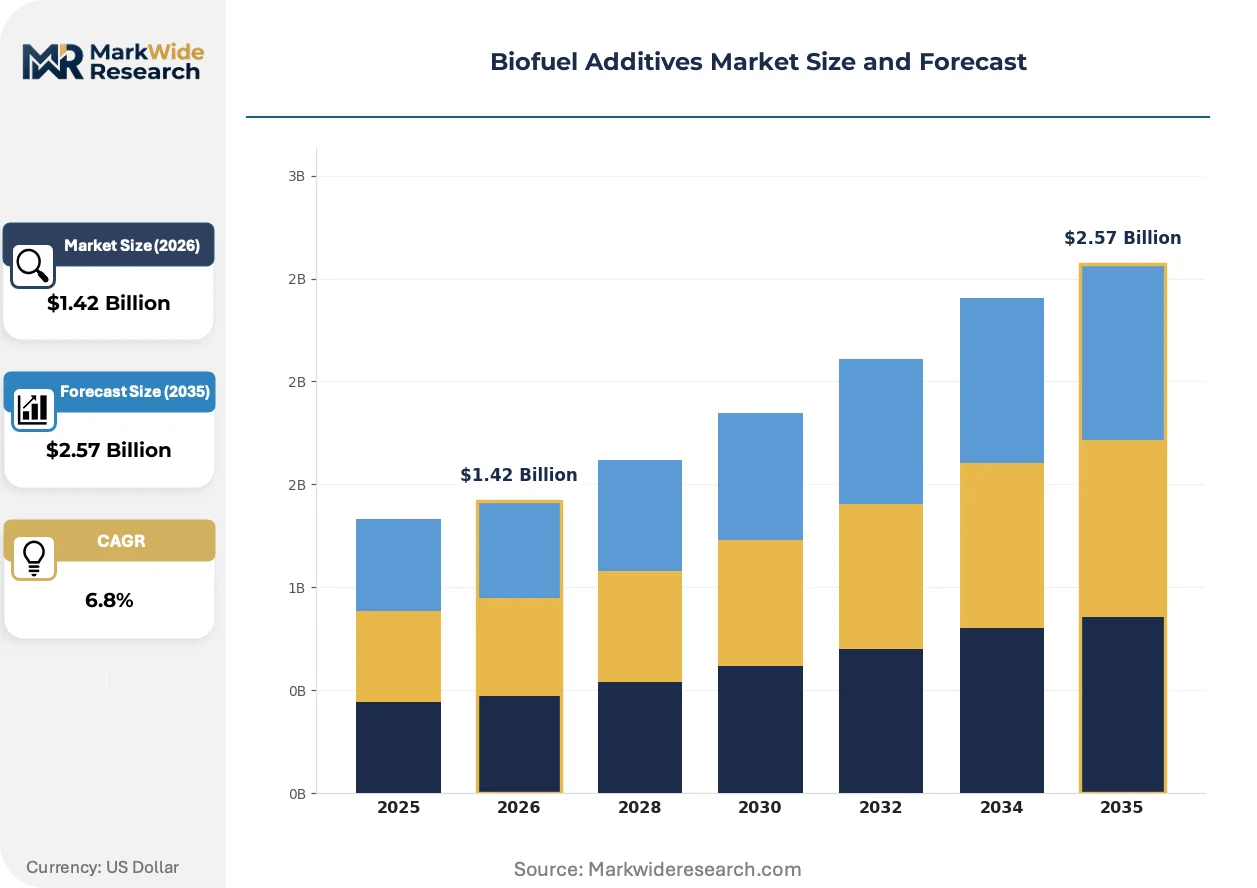
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ethanol, Biodiesel, Biobutanol, Bio-DME Application: Transportation, Industrial, Residential, Agricultural Additive Type: Stabilizers, Cetane Improvers, Antioxidants, Corrosion Inhibitors End User: Fuel Suppliers, Oil Companies, Automotive OEMs, Logistics Providers |
| Companies Covered | Infineum International Limited, Innospec Inc., BASF SE, Clariant, Croda International Plc, Lubrizol Corporation, Evonik Industries AG, Dow Chemical Company, Afton Chemical Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biofuel Additives Market Strategic Shifts & Innovations
Formulation science is converging with digital supply chain tools to enable just-in-time additive blending at fuel terminals, compressing inventory cycles and reducing working capital intensity for distributors.
Bio-based antioxidant technology is hybridizing synthetic phenolic stabilizers with natural tocopherol derivatives to meet REACH authorization constraints while maintaining oxidative stability performance in palm and soy methyl ester fuels. European biodiesel producers are adopting these hybrid packages fastest, driven by ECHA compliance deadlines. The structural consequence is a bifurcation between premium bio-based formulations and legacy chemistries facing phase-out timelines.
California's Low Carbon Fuel Standard is recalibrating carbon intensity scoring methodologies to reward biofuel pathways with lower upstream agricultural emissions, directly altering which feedstock-additive combinations qualify for maximum credit generation. Fuel suppliers are reformulating to capture these credit premiums. Biodiesel distributors in the Western United States are restructuring procurement specifications around CI scores rather than traditional ASTM metrics alone.
Terminal operators are consolidating additive purchasing through integrated supply agreements that bundle corrosion inhibitors, cetane improvers, and cold flow modifiers under single-source contracts with volume-tier pricing. This behavior concentrates bargaining power with large chemical distributors and marginalizes smaller regional blenders. The pattern is most pronounced along the U.S. Gulf Coast refining corridor where pipeline terminal consolidation has accelerated.
Biofuel Additives Market Segmentation
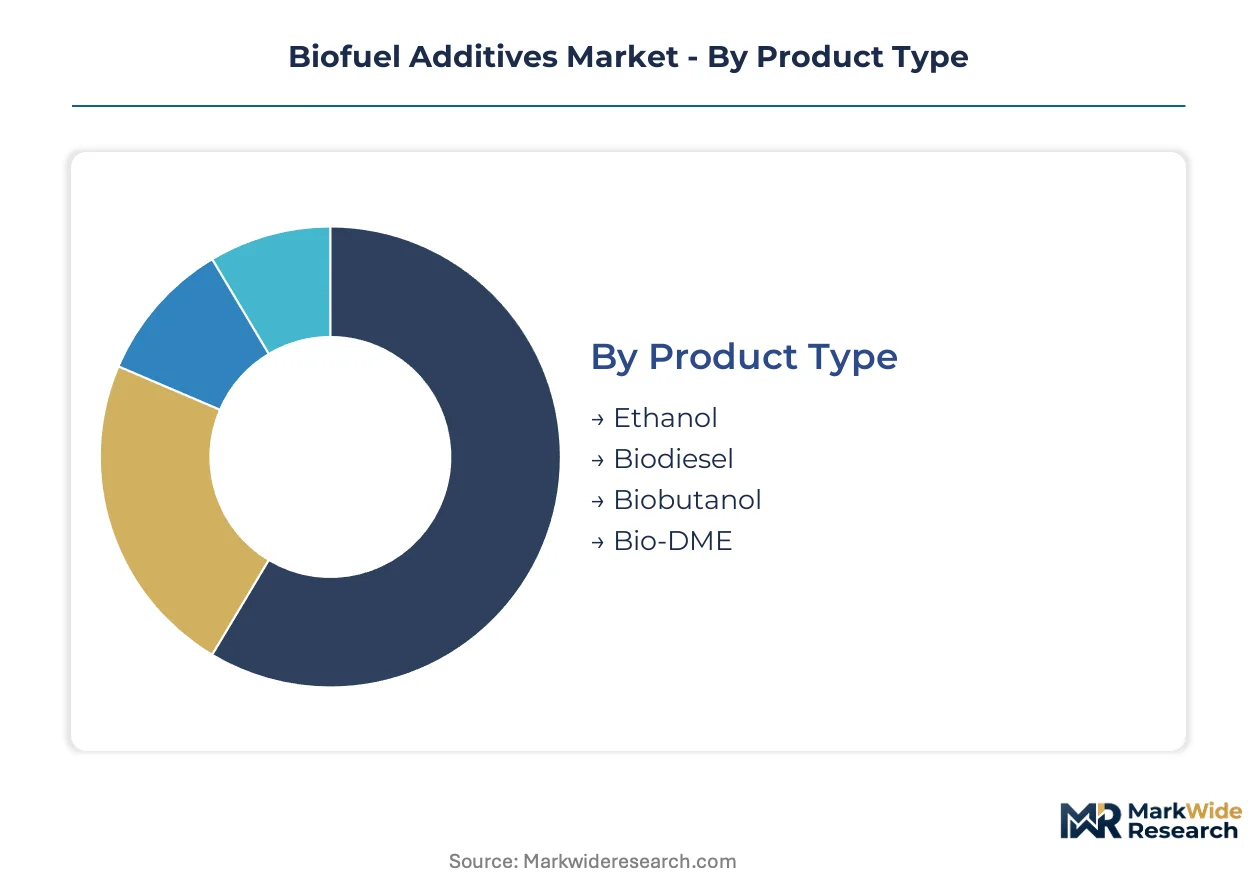
Segmentation in biofuel additives reveals how formulation requirements diverge across fuel chemistries and end-use environments. Procurement patterns vary sharply between ethanol-gasoline blenders facing phase separation risks and biodiesel operators managing oxidation stability in extended supply chains.
Product Type:
Each base fuel chemistry imposes distinct additive specifications driven by combustion characteristics and infrastructure compatibility requirements.
- Ethanol:Phase separation inhibitors and corrosion protectants dominate formulation spend for ethanol-gasoline blends. U.S. fuel suppliers along the Midwest corn-ethanol corridor purchase these additives in the highest volumes to meet EPA Renewable Fuel Standard blending mandates.
- Biodiesel:Antioxidant packages and cold flow improvers command premium positioning due to biodiesel's inherent oxidation susceptibility and poor low-temperature operability. European producers under EU Green Deal targets are accelerating procurement of stabilizer formulations that extend fuel integrity during ocean transit to tropical markets.
- Biobutanol:Compatibility additives address elastomer swelling and material degradation in legacy fuel system components. Niche demand concentrates among automotive OEMs testing higher biobutanol concentrations in flex-fuel vehicle programs.
- Bio-DME:Lubricity enhancers and injection system protectants serve compressed ignition engines adapted for dimethyl ether combustion. Marine fuel trials under International Maritime Organization decarbonization timelines are opening initial specification development for this segment.
Established volume favors ethanol; emerging adoption favors biodiesel as supply chains extend into higher-humidity climates.
Application:
End-use environments determine treat rate intensity and performance certification requirements across additive procurement.
- Transportation:Fleet operators and fuel retailers purchase multi-functional additive packages to prevent filter plugging, injector deposits, and fuel system corrosion in high-duty cycles. The segment absorbs the majority of cetane improver and detergent volumes as road transport electrification timelines create interim diesel demand concentration.
- Industrial:Power generation and heating oil applications require simplified additive formulations with lower treat rates. Boiler operators in Northern Europe favor biodiesel blends with basic antioxidant protection over comprehensive multi-additive packages.
- Residential:Home heating and small-scale generator applications drive seasonal procurement patterns with minimal technical specification complexity. Distributors serve this segment through pre-blended heating fuels requiring no terminal additive injection.
- Agricultural:Farm equipment operators transitioning to higher biodiesel blends create emerging demand for cold flow modifiers and water dispersants. Equipment manufacturers in Brazil and the United States are field-testing additive requirements for harvest-season operational reliability.
Transportation commands current procurement scale; agricultural equipment represents the steepest expansion trajectory as mechanization intensifies in biodiesel-producing regions.
Additive Type:
Functional chemistry categories align with specific fuel degradation mechanisms and regulatory compliance thresholds.
- Stabilizers:Metal deactivators and dispersant polymers prevent gum formation and particulate precipitation in stored biofuels. Refiners in the U.S. Gulf Coast corridor specify these additives for ethanol pipeline batches subject to extended terminal residence times.
- Cetane Improvers:Alkyl nitrates and peroxide-based ignition enhancers raise combustion quality in biodiesel and bio-DME to meet ASTM D6751 and EN 14214 minimums. The category captures disproportionate margin pools due to its direct link to blend certification.
- Antioxidants:Phenolic and aminic radical scavengers interrupt oxidative chain reactions in unsaturated fatty acid methyl esters. REACH authorization constraints in Europe are accelerating formulation shifts toward bio-based tocopherol hybrids.
- Corrosion Inhibitors:Film-forming amines and carboxylic acid derivatives protect fuel system metals from acidic byproducts of biofuel degradation. ECHA registration requirements are forcing costly re-registration programs for legacy chemistries.
Cetane improvers anchor premium pricing; antioxidants are climbing the fastest as tropical biodiesel deployment accelerates.
End User:
Procurement sophistication and volume concentration vary sharply across customer categories with differing technical capabilities.
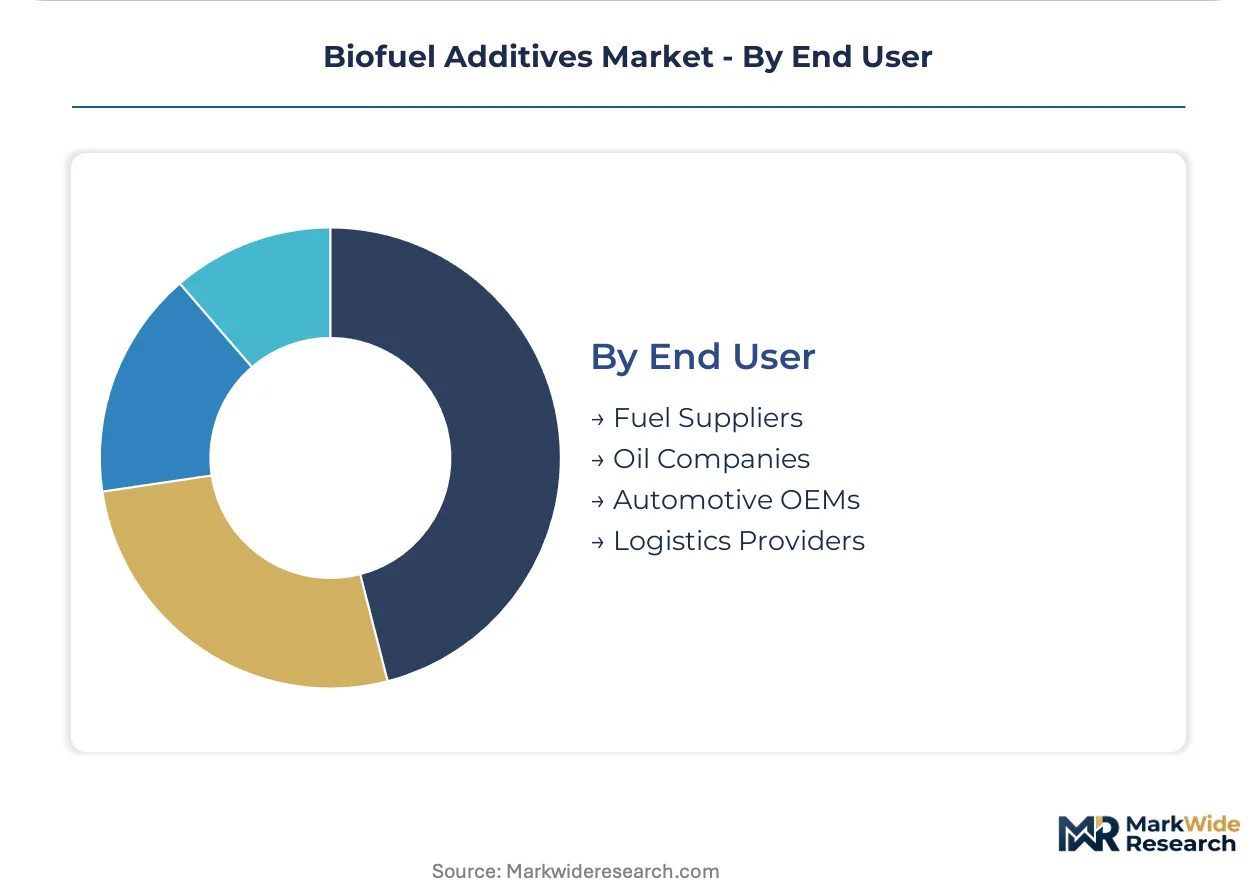
- Fuel Suppliers:Terminal operators and blenders purchase integrated additive packages under volume-tier contracts with integrated distributors. The category consolidates bargaining power through pipeline terminal networks along major U.S. and European fuel corridors.
- Oil Companies:Integrated refiners maintain captive additive formulation capabilities and direct manufacturing relationships with specialty chemical producers. Their procurement emphasizes supply security and specification customization over cost minimization.
- Automotive OEMs:Vehicle manufacturers specify additive requirements for warranty-compliant fuels and conduct compatibility testing for next-generation biofuel concentrations. Their influence on additive standards is expanding as engine calibration grows more sensitive to fuel quality variation.
- Logistics Providers:Fleet operators and marine fuel purchasers are emerging as direct additive buyers as outcome-based fuel supply contracts gain traction. Digital blending analytics enable these users to optimize dosing precision and reduce waste.
Fuel suppliers dominate current procurement volume; logistics providers are gaining share fastest as direct purchasing bypasses traditional distributor channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Colonial Pipeline network and Gulf Coast terminal infrastructure anchor United States additive procurement volumes, while Rotterdam's ARA hub and pipeline corridors sustain European distribution density.
United States
Midwest corn-ethanol production clusters and Gulf Coast biodiesel import terminals drive concentrated additive demand. The EPA Renewable Fuel Standard mandates annual renewable volume obligations that directly determine procurement levels by domestic fuel suppliers. Chicago-area blenders and Houston-Galveston terminal operators purchase phase separation inhibitors and cetane improvers in the highest volumes.
Germany
Rapeseed methyl ester production in Lower Saxony and biodiesel refining along the Rhine corridor create sustained stabilizer demand. The ECHA REACH framework restricts traditional corrosion inhibitor chemistries, forcing costly re-registration programs. Hamburg and Rotterdam-connected terminals are accelerating adoption of bio-based antioxidant hybrids to meet compliance deadlines.
India
Sugar-ethanol distilleries in Maharashtra and Uttar Pradesh are expanding capacity to meet 20% ethanol blending targets by 2025. The BIS standards for ethanol blending and the PLI scheme for biofuel infrastructure create compliance-driven procurement channels. Pune-based formulators are establishing local partnerships with global additive suppliers to capture first-mover positioning.
Brazil
Sugarcane-ethanol infrastructure in São Paulo state and expanding biodiesel production in Mato Grosso sustain South American demand concentration. ANVISA and national biofuel agency regulations govern blend specifications and additive certification requirements. Santos port terminal operators are investing in corrosion protection systems for ethanol export shipments.
Netherlands
The ARA refining hub and extensive inland waterway distribution networks position the country as Europe's additive formulation and re-export center. EU Green Deal targets and F-Gas Regulation constraints accelerate bio-based formulation development. Rotterdam terminal operators are deploying integrated supply agreements that bundle multi-additive packages under volume-tier contracts.
Biofuel Additives Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream with narrower functional portfolios. The vendor base stratifies between integrated chemical conglomerates with captive manufacturing and specialized distributors serving regional terminal networks. Three archetypes dominate: global formulators with full additive portfolios, regional blenders with formulation customization capabilities, and technology licensors with proprietary stabilizer chemistries. Consolidation concentrates bargaining power through pipeline terminal networks, while partnerships between distributors and terminal operators enable outcome-based supply contracts.
Within the integrated chemical conglomerate tier, BASF SE and Evonik Industries AG exemplify platform-scale positioning with global manufacturing footprints and diversified specialty chemical portfolios. Innospec Inc. occupies a distinct position as a focused additive specialist with concentrated expertise in detergent and combustion-improver formulations. These three entities represent the structural spectrum from broad chemical platforms to narrowly focused fuel additive specialists, with each archetype commanding different margin pools and customer relationship intensities.
| Leading Market Players |
|---|
| Infineum International Limited |
| Innospec Inc. |
| BASF SE |
| Clariant |
| Croda International Plc |
| Lubrizol Corporation |
| Evonik Industries AG |
| Dow Chemical Company |
| Afton Chemical Corporation |
| Others |
Cost & Logistics Intelligence
Rotterdam's ARA hub capacity expansion and terminal consolidation dynamics concentrate bargaining power among integrated chemical distributors serving European biodiesel blenders. Gulf Coast pipeline terminal operators in the United States similarly compress procurement cycles through volume-tier contracts that bundle corrosion inhibitors, cetane improvers, and cold flow modifiers under single-source agreements.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates REACH-compliant bio-based antioxidant formulations from legacy synthetic chemistries facing phase-out timelines. Price differentiation hinges on certification grade for ECHA registration compliance and volume scale for terminal network access. Cost compression in standard-tier legacy formulations is intensifying because palm oil feedstock volatility constrains biodiesel producer discretionary spending. Agricultural equipment operators demonstrate highest price sensitivity due to seasonal procurement patterns, while integrated oil companies prioritize supply security over cost minimization.
Supply Chain Analysis
Upstream vegetable oil feedstock availability in Indonesia, Malaysia, and Brazil anchors biodiesel additive demand volatility through price transmission effects. Specialty chemical manufacturing draws from phenolic antioxidant precursors, alkyl nitrate cetane improver intermediates, and film-forming amine corrosion inhibitor bases. Single-source vulnerability concentrates in European antioxidant production where ECHA authorization timelines constrain formulation alternatives. Distribution runs through integrated chemical conglomerates with captive terminal injection capabilities and specialized regional blenders serving isolated fuel corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The biofuel additives market exhibits cyclical recovery characteristics tied to renewable fuel mandate acceleration in the United States and European Union, with procurement pull intensifying as blend timelines compress toward 2030 targets.
For Market Incumbents: Pre-empt margin erosion in legacy corrosion inhibitor chemistries by accelerating bio-based formulation R&D ahead of REACH authorization deadlines. BASF SE and Evonik Industries AG should deepen backward integration into tocopherol derivative supply chains to secure feedstock for hybrid antioxidant production, defending against specialty chemical distributors consolidating terminal network access through integrated supply agreements. For New Entrants and Emerging Players: Build out local formulation partnerships in Maharashtra and Uttar Pradesh to capture India's ethanol blending infrastructure expansion under BIS standards and the PLI scheme. The agricultural equipment segment offers the most penetrable white space as Brazilian and American farm operators field-test cold flow modifier requirements for harvest-season biodiesel reliability, with go-to-market traction achievable through equipment manufacturer co-development programs. For Investors and Strategic Acquirers: Carve-out targets emerge from integrated oil companies spinning non-core additive formulation capabilities as they prioritize downstream retail and renewable fuel production investments. Long-term viability centers on suppliers with demonstrated REACH compliance pathways and established terminal injection infrastructure. Watch for inflection signals in California LCFS carbon intensity scoring methodology revisions that would requalify feedstock-additive combinations for maximum credit generation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Based Feedstocks | Secures tocopherol supply chains for REACH-compliant antioxidant hybrids ahead of ECHA deadlines. |
| Terminal Network Consolidation | Concentrates bargaining power with Rotterdam and Gulf Coast pipeline operators through volume-tier contracts. |
| Local Formulation Partnerships | Captures first-mover positioning in India's sugar-ethanol corridor under BIS blending mandates. |
| Digital Blending Analytics Deployment | Enables precision additive injection for logistics providers adopting outcome-based fuel supply contracts. |
| Marine Biofuel Compatibility Testing | Addresses International Maritime Organization decarbonization timelines for bio-DME lubricity enhancers. |
Research Approach
The analysis maps ethanol-gasoline phase separation inhibitors, biodiesel antioxidant packages, biobutanol compatibility additives, and bio-DME lubricity enhancers, each validated through terminal operators, biodiesel plant managers, fuel procurement leads at integrated oil companies, and specialty chemical distribution channel partners. Primary interview intelligence triangulates against customs and trade data for vegetable oil methyl ester flows, American Chemistry Council and Cefic specialty chemical reports, EPA Renewable Fuel Standard compliance filings, and SEC 10-K disclosures from listed additive manufacturers. Bottom-up volume builds from terminal procurement patterns reconcile with top-down market sizing across fuel chemistry and application segments.
Assumptions hold renewable fuel mandate trajectories in the United States and European Union at announced policy levels, with sensitivity testing for accelerated LCFS carbon intensity thresholds and delayed EU Green Deal implementation. Segmentation modeling spans base fuel chemistry, end-use application, functional additive type, and procurement sophistication across fuel suppliers, oil companies, automotive OEMs, and emerging logistics provider buyers. CAGRs derive from additive treat rate intensity projections tied to blend concentration increases and supply chain extension into tropical climates, with biodiesel oxidation stability requirements and ethanol phase separation risk serving as primary demand drivers.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese specialty chemical producers or sudden REACH authorization withdrawals would shift outcomes materially. Cross-checking against EPA renewable volume obligation compliance data and EU biodiesel import statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Biosaccharide Gum Market
Additives
Global Propyl Acetate Market
Additives
Sodium Potassium Tartrate Market
Additives
Material Shrinkage-reducing Agents Market
Additives
Global Pour Point Depressant Market
Additives
Germany Sodium Reduction Ingredient Market
Additives
Cement Grinding Aid and Performance Enhancers Market
Additives
Shortstop Inhibitor Market
Additives
Hydroxyethyl Cellulose Market
Additives
Tocopheryl Acetate Market
Additives
Gasoline Additives Market
Additives
Chemical Silage Additives Market
Additives
Oilfield Drilling Fluid Additive Market
Additives
Global Sizing Agents Market
Additives
Nucleotide Premix Market
Additives
Tris Nonylphenyl Phosphite Market