
 Antiknock Agents Market | 2026-2036
Antiknock Agents Market Size, Share, and Industry Trends Forecast 2026-2036
Antiknock Agents Market Outlook
Aviation fuel blending is restructuring demand profiles across the antiknock value chain. Afton Chemical leverages its additive technology portfolio to serve high-octane aviation gasoline requirements. Innospec anchors manganese tricarbonyl supply for markets transitioning away from tetraethyl lead. Chevron Oronite Company competes through integrated refinery relationships that sustain volume commitments.
Antiknock agents are fuel additives that raise gasoline octane ratings by modifying combustion kinetics, typically containing organometallic compounds or oxygenates dosed at parts-per-thousand levels to prevent engine knock and pre-ignition damage. Methylcyclopentadienyl manganese tricarbonyl dominates premium formulations where high-octane delivery per unit volume outweighs cost, while ethanol blends occupy oxygenate mandates in renewable fuel regulations. Liquid concentrates capture the majority of volume due to ease of inline blending at terminal and refinery injection points.
EPA fuel additive registration requirements under the Clean Air Act constrain product entry timelines and testing burdens for new chemistries. REACH authorization processes in Europe impose substitution obligations that favor manganese-based agents over legacy lead formulations. India's BIS fuel quality standards and automotive emission norms under the Central Pollution Control Board shape import and local formulation strategies. Stakeholders must monitor regulatory divergence between lead-phase-out deadlines and octane maintenance requirements to align R&D portfolios with enforceable compliance calendars.
Market Dynamics
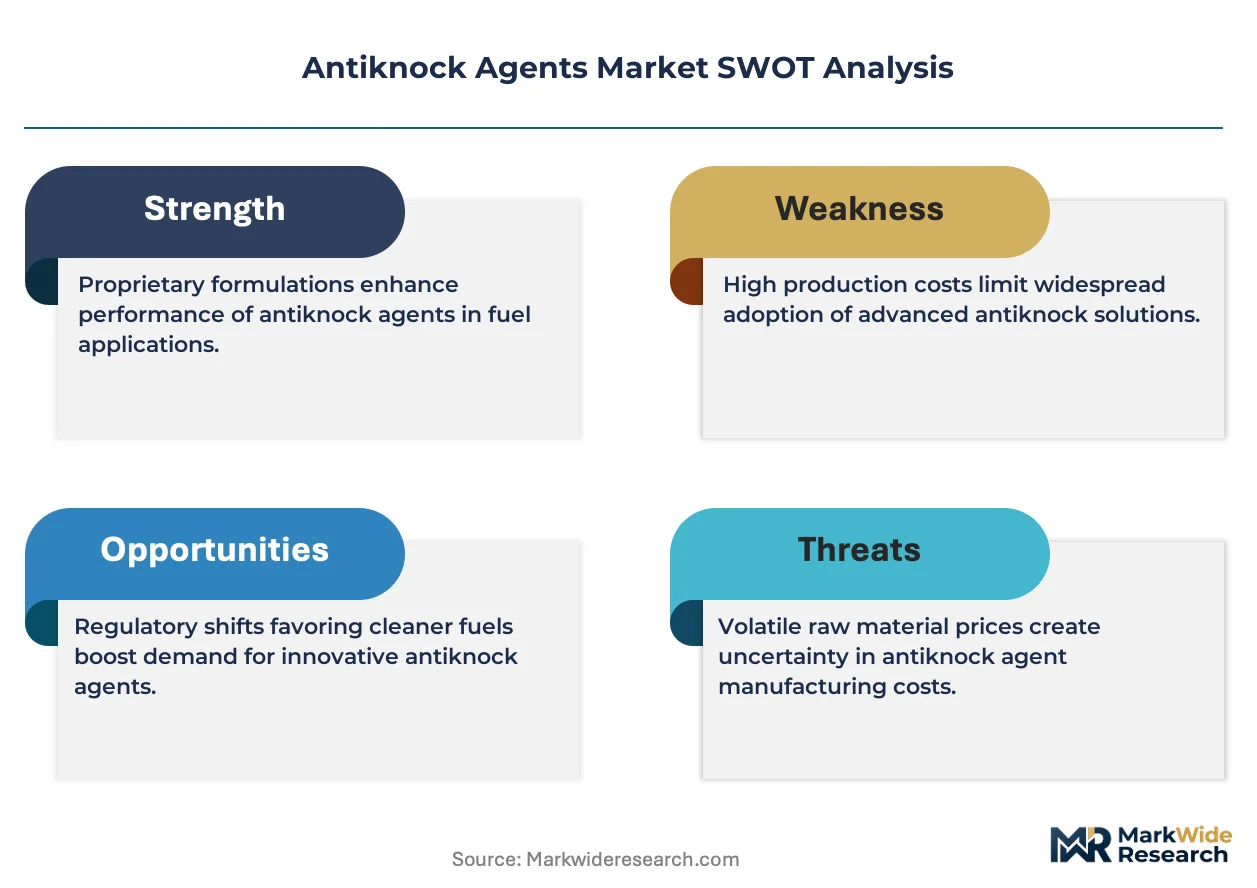
Refinery-grade manganese tricarbonyl supply is consolidating around three integrated producers, compressing formulation margins for independent blenders and forcing terminal operators into long-term offtake commitments.
Growth Catalysts
- India's BIS fuel quality standards:Bharat Stage VI emission norms mandate 91+ octane gasoline nationwide, pulling manganese-based additive volumes into refinery upgrade cycles.
- Aviation gasoline reformulation:Piston-engine aircraft operators are switching from leaded avgas to high-octane unleaded alternatives, opening a dedicated antiknock demand channel.
- Oxygenate blending mandates:Ethanol integration requirements under renewable fuel regulations in Brazil and the United States are expanding the addressable additive market for octane boosters.
Market Restraints
- Manganese feedstock concentration:Electrolytic manganese metal supply clusters in South Africa and Gabon, exposing additive producers to export duty volatility and logistics bottlenecks.
- REACH authorization timelines:ECHA's substance evaluation protocols for organometallic fuel additives extend commercialization cycles by 18-24 months beyond historical baselines.
- Battery-electric vehicle displacement:Passenger EV fleet penetration in China and Norway is structurally compressing gasoline demand in premium octane segments.
Strategic Opportunities
- Southeast Asia refinery greenfield builds:Vietnam's Nghi Son and Indonesia's Tuban complexes lack legacy additive infrastructure, creating first-mover positioning for manganese tricarbonyl suppliers.
- Marine gasoline outboard engines:Recreational boating regulations in the European Union are phasing out leaded two-stroke fuels, opening a specialized high-octane niche.
- Carbon border adjustment mechanisms:The EU's CBAM framework incentivizes low-carbon additive production pathways, rewarding producers with integrated renewable energy supply.
Industry Challenges
- Organometallic chemist talent scarcity:Formulation laboratories face recruitment gaps in transition-metal catalysis expertise as academic programs pivot to battery materials.
- Inline blending system retrofit costs:Terminal operators must deploy corrosion-resistant injection skids and real-time octane analyzers to handle manganese-based concentrates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Antiknock Agents Market |
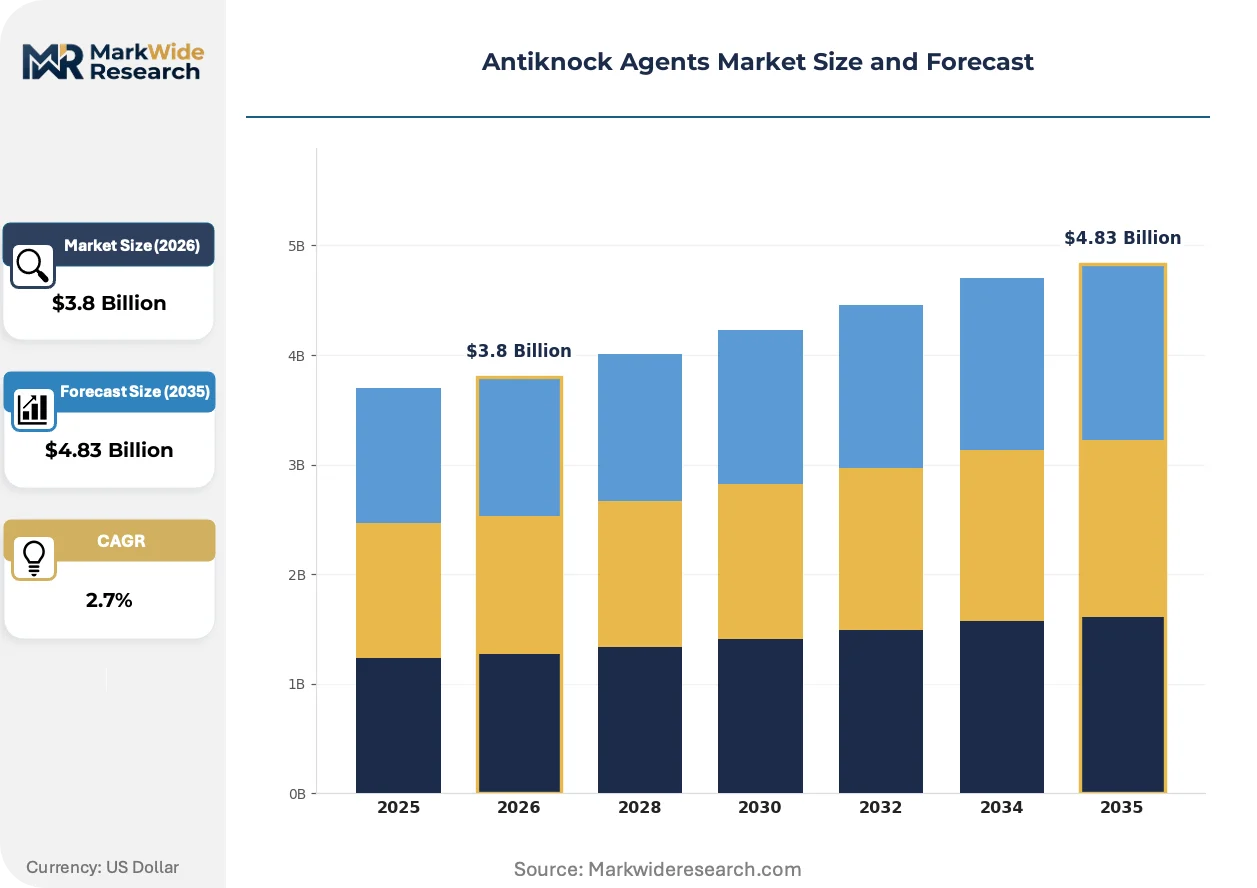
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $4.83 Billion |
| CAGR (2026 – 2036) | 2.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Additive Type: Tetraethyl Lead, Methylcyclopentadienyl Manganese Tricarbonyl, Ethanol, Others End Use Industry: Aerospace, Automotive, Marine, Power Generation Form: Liquid, Powder, Concentrate, Emulsion Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | Afton Chemical, Dorf Ketal Chemicals, Innospec, Infineum International, The Lubrizol Corporation, Chevron Oronite Company, Evonik Industries, TotalEnergies, BASF, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Antiknock Agents Market Strategic Shifts
Continuous inline blending instrumentation is compressing quality assurance cycles and enabling just-in-time additive dosing at fuel terminals rather than centralized refinery batch processing.
Micro-dosing pump technologies are decentralizing antiknock agent deployment from large-scale refinery units to distributed terminal infrastructure. Independent fuel marketers in India and Mexico are adopting skid-mounted injection systems that bypass traditional bulk additive contracts. This hardware shift is fragmenting procurement patterns and eroding volume commitments that historically anchored supplier relationships.
REACH authorization processes are tightening substitution obligations for organometallic fuel additives across the European Union. ECHA's 2024-2026 rolling action plan prioritizes manganese compound assessments, forcing reformulators to accelerate alternative chemistry documentation. German and Dutch refiners are pre-registering iron-based antiknock candidates to secure regulatory runway before authorization deadlines.
Aftermarket fuel additive channels are capturing share from refinery-direct supply as ride-hailing fleet operators seek octane insurance for high-compression engine platforms. Independent service stations in São Paulo and Jakarta now stock branded concentrate bottles for driver self-dosing. This behavior shift is creating parallel demand outside regulated refinery blending mandates.
Antiknock Agents Market Segmentation
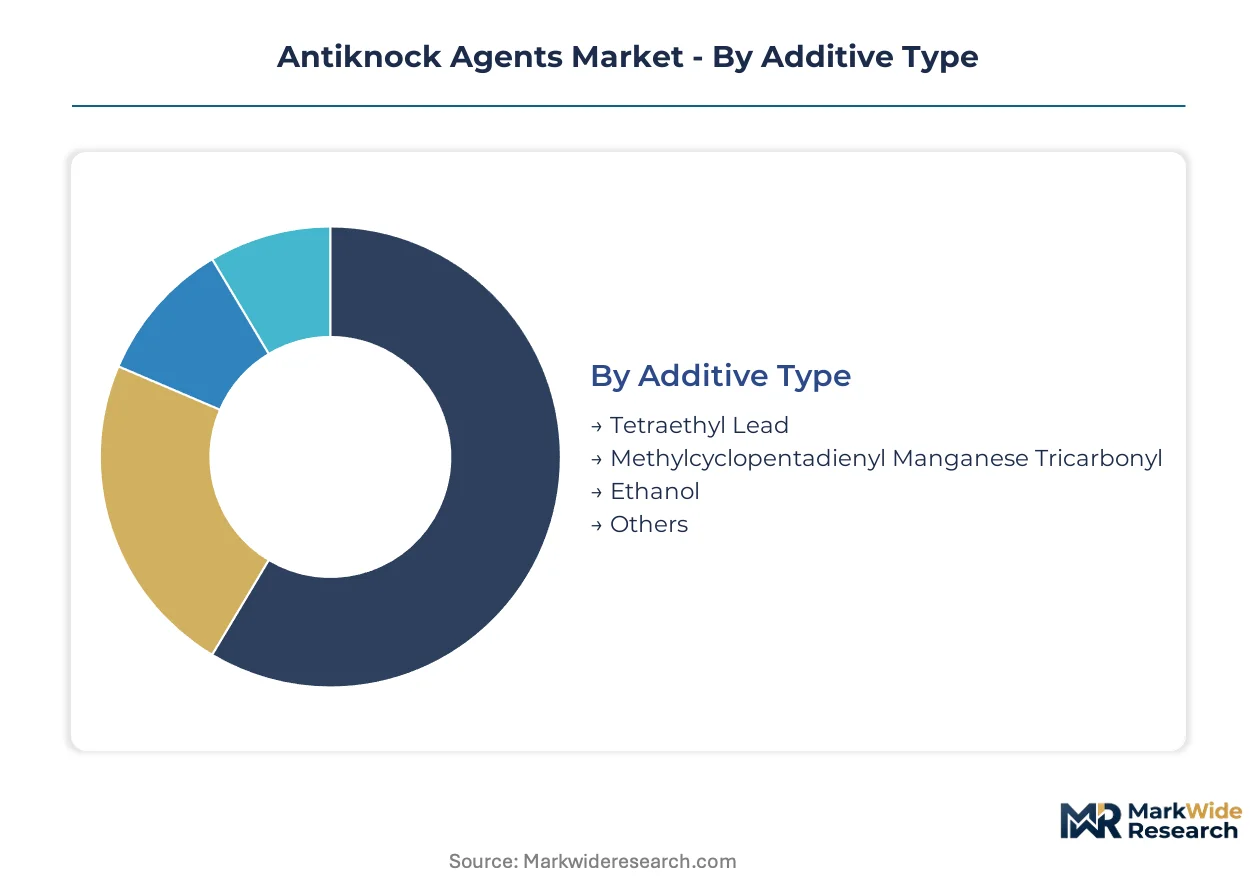
Antiknock agent procurement patterns diverge sharply between refinery-direct bulk contracts and distributed terminal sales. Formulation chemistry and physical state determine blending infrastructure requirements, while end-use specifications dictate octane delivery thresholds.
Additive Type:
Volume applications favor cost-efficient oxygenates, while premium formulations command manganese-based price premiums for high-octane density.
- Methylcyclopentadienyl Manganese Tricarbonyl:Organometallic compound delivering 103+ octane boost per unit volume. Indian refiners at Paradip and Jamnagar anchor demand as Bharat Stage VI mandates compress formulation windows. REACH substitution protocols in Europe accelerate manganese adoption where lead phase-out deadlines precede infrastructure replacement cycles.
- Ethanol:Oxygenate additive blended at 10-85% concentrations depending on renewable fuel mandates. Brazilian ANP regulations and U.S. EPA renewable volume obligations sustain bulk procurement through integrated sugarcane and corn ethanol supply chains. Terminal operators in São Paulo and Iowa prioritize hydrous ethanol for cost-competitive octane enhancement.
- Tetraethyl Lead:Legacy organolead compound restricted to aviation gasoline and specialized industrial applications under EPA and ECHA exemptions. Piston-engine aircraft operators in Alaska and remote Australian outposts maintain residual demand.
- Others:Iron-based experimental formulations and proprietary amine blends under pre-registration for REACH authorization.
Today's leader: Methylcyclopentadienyl Manganese Tricarbonyl. Tomorrow's challenger: Ethanol.
End Use Industry:
Automotive applications dominate tonnage, while aerospace specifications command the steepest price premiums per treated liter.
- Automotive:Passenger vehicle and commercial fleet gasoline blending at 91-98 octane ratings. Indian and Indonesian refinery upgrades pull manganese tricarbonyl volumes into new hydrocracker units. China's MIIT fuel quality standards enforce 92+ octane nationwide, compressing additive selection windows.
- Aerospace:Piston-engine aviation gasoline requiring 100+ octane without tetraethyl lead. FAA certification pathways for unleaded avgas alternatives concentrate demand around Afton Chemical and Innospec formulations. Alaska and Australian general aviation clusters drive pilot program adoption.
- Marine:Outboard two-stroke engines facing EU recreational boating lead bans. German and Dutch inland waterway operators pre-position manganese-based stocks for regulatory transition.
- Power Generation:Stationary gasoline engines for backup and remote power. Nigerian and Bangladeshi telecom tower operators procure high-octane fuel for generator reliability in grid-unreliable zones.
Automotive absorbs volume scale. Aerospace captures margin concentration.
Form:
Liquid concentrates align with existing terminal infrastructure, while emulsion formats target corrosion-sensitive marine applications.
- Liquid:Inline-blendable concentrates dosed at 500-2000 ppm through corrosion-resistant injection skids. Indian Oil Corporation and Reliance Industries deploy liquid manganese tricarbonyl at Jamnagar and Paradip terminals.
- Concentrate:High-potency formulations requiring dilution before terminal injection. Mexican independent fuel marketers adopt skid-mounted systems for self-blending at Guadalajara and Monterrey distribution points.
- Powder:Solid-state manganese compounds for remote logistics where liquid transport proves uneconomical. Mongolian mining operations utilize powder formats for on-site gasoline conditioning.
- Emulsion:Water-based dispersions reducing metallic corrosion in marine engine fuel systems. Baltic Sea ferry operators trial emulsion antiknocks under Finnish environmental port regulations.
Liquid maintains infrastructure lock-in. Emulsion gains regulatory tailwinds.
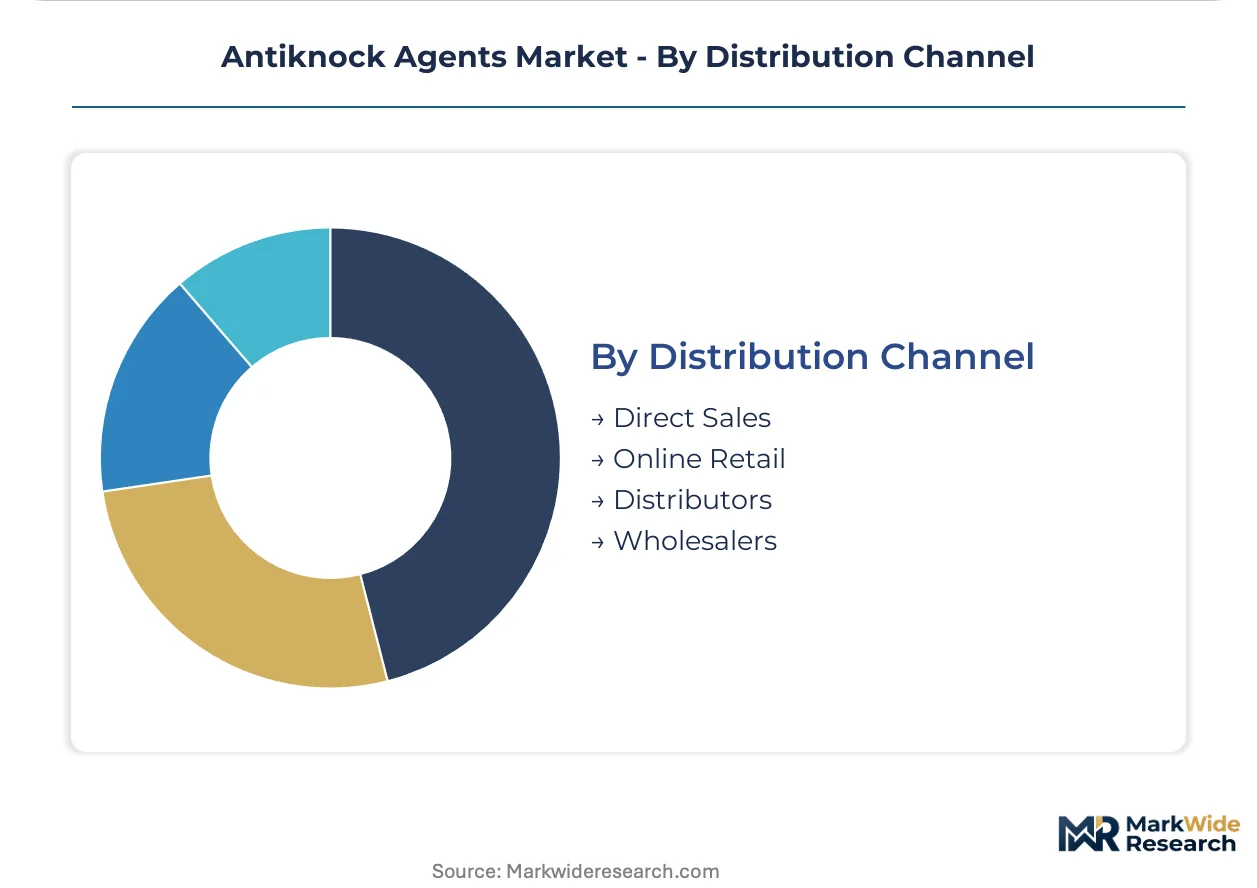
Distribution Channel:
Direct refinery relationships anchor volume commitments, while distributor networks fragment procurement toward smaller blenders.
- Direct Sales:Long-term offtake contracts between integrated additive producers and national oil companies. Saudi Aramco and Indian Oil Corporation lock in manganese tricarbonyl supply through 3-5 year framework agreements.
- Distributors:Regional chemical handlers stocking antiknock concentrates for independent terminal operators. Indonesian PT Pertamina distributors serve Nghi Son refinery customers in Java and Sumatra.
- Wholesalers:Bulk fuel marketers blending antiknocks at secondary terminals. Brazilian distributors in São Paulo state aggregate ethanol and manganese additive purchases for independent postos.
- Online Retail:Branded concentrate bottles for ride-hailing driver self-dosing. Grab and Gojek fleet operators in Jakarta procure aftermarket octane boosters through e-commerce platforms.
Direct sales defend volume share. Online retail fragments price discipline.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting antiknock agent production toward jurisdictions with streamlined fuel additive registration pathways. Cost-of-compliance gaps between REACH-authorized European markets and emerging Asian economies are accelerating capacity relocation to refinery clusters with faster approval timelines.
United States
Aviation gasoline reformulation and renewable fuel mandates drive additive procurement at 100LL avgas replacement facilities. EPA Clean Air Act registration requirements constrain new chemistry entry but sustain incumbent manganese tricarbonyl suppliers. Houston-Gulf Coast refiners anchor domestic blending capacity for high-octane automotive and aerospace specifications.
India
Bharat Stage VI emission norms mandate 91+ octane gasoline across all states, compressing refinery upgrade schedules at Paradip and Jamnagar. BIS fuel quality standards and Central Pollution Control Board enforcement shape import and local formulation strategies. Reliance Industries and Indian Oil Corporation terminal operators deploy liquid manganese concentrates for inline blending infrastructure.
Germany
ECHA REACH authorization timelines for organometallic additives extend commercialization cycles, forcing pre-registration of iron-based alternatives. German refiners in the Rhine-Ruhr industrial corridor navigate substitution obligations while maintaining octane delivery for high-compression engine platforms. Bavarian chemical handlers stock transitional manganese inventories ahead of 2024-2026 substance evaluation deadlines.
Brazil
ANP renewable fuel regulations sustain hydrous ethanol blending at 27% gasoline concentrations, expanding oxygenate-mandate addressable markets. Independent postos in São Paulo state aggregate ethanol and manganese additive purchases through distributor networks. Petrobras refinery upgrades in the Southeast region integrate antiknock dosing systems for flex-fuel vehicle fleet requirements.
China
MIIT fuel quality standards enforce 92+ octane nationwide, eliminating lower-grade gasoline distribution from coastal refinery clusters. Ningbo-Zhoushan and Dalian terminal operators retrofit corrosion-resistant injection skids for manganese-based concentrate handling. Provincial environmental regulators accelerate lead-phase-out enforcement in Yangtze River Delta manufacturing corridors.
Antiknock Agents Market Competitive Environment
Long-term offtake contracting dominates the current landscape as integrated producers compress formulation margins for independent blenders. Three integrated manganese tricarbonyl suppliers anchor supply-side concentration, forcing terminal operators into volume-commitment structures. Strategic archetypes divide between petrochemical-integrated majors, specialized fuel additive houses, and regional chemical distributors. Competitive moves center on backward integration into electrolytic manganese metal supply and technology licensing partnerships for REACH-compliant alternative chemistries.
Among petrochemical-integrated majors, Chevron Oronite Company and TotalEnergies occupy positions sustained by captive refinery relationships and captive supply of feedstock streams. Specialized additive houses exemplified by Afton Chemical and Innospec represent formulation expertise archetypes, anchoring high-octane aviation and automotive specification development. Regional chemical distributors including Dorf Ketal Chemicals sit within procurement-fragmentation vectors, serving independent terminal operators bypassing traditional bulk contracts through skid-mounted injection systems.
| Leading Market Players |
|---|
| Afton Chemical |
| Dorf Ketal Chemicals |
| Innospec |
| Infineum International |
| The Lubrizol Corporation |
| Chevron Oronite Company |
| Evonik Industries |
| TotalEnergies |
| BASF |
| Others |
Value Chain & Pricing Dynamics
National oil companies in India and Indonesia anchor procurement volume, locking contract-based long-term offtake structures that compress spot-market liquidity and tether pricing to refinery upgrade cycles rather than commodity spot indices. This buyer concentration forces additive producers into framework agreements with volume-commitment floors, while independent terminal operators face margin erosion from skid-mounted injection system retrofits.
Pricing Analysis
Distributor margins for manganese tricarbonyl concentrates typically run 12-18% above refinery-direct contract rates, with terminal operators in Southeast Asia capturing additional markup for corrosion-resistant injection skid deployment. Price differentiation rests on REACH authorization status and BIS certification tier, with German and Indian refiners paying premiums for pre-registered formulations. Cost compression in the independent blender tier is intensifying because three integrated producers control electrolytic manganese metal feedstock. Ride-hailing fleet operators in São Paulo and Jakarta show highest price sensitivity through aftermarket self-dosing channels, while aviation gasoline blenders in Alaska and Australia absorb steep premiums for unleaded high-octane specifications.
Supply Chain Analysis
India's PLI scheme for specialty chemicals and Indonesia's domestic content rules for refinery infrastructure are reshaping sourcing patterns, pulling formulation capacity toward Nghi Son and Jamnagar clusters. Electrolytic manganese metal supply draws from South Africa, Gabon, and China, with organometallic synthesis concentrated in the US Gulf Coast and Rhine-Ruhr industrial corridor. Raw material dependencies rest on manganese ore grade, carbon monoxide feedstock purity, and methylcyclopentadiene dimer availability. Single-source vulnerability runs through South African export duty volatility. Distribution feeds from integrated producer tank farms to national oil company terminals, with independent distributors in Brazil and Mexico fragmenting last-mile procurement through skid-mounted systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The antiknock agents market represents a late-cycle quality story as Bharat Stage VI and MIIT fuel standards compress formulation windows toward premium manganese-based specifications that command sustained price premiums over oxygenate alternatives.
For Market Incumbents: Cement backward integration into electrolytic manganese metal supply to defend against South African export duty volatility and Gabon logistics bottlenecks. Lock 5-7 year framework agreements with Indian Oil Corporation and Pertamina before Nghi Son and Tuban refinery greenfield builds reach commissioning. Prioritize REACH pre-registration for iron-based alternative chemistries to secure regulatory runway ahead of ECHA's 2024-2026 substance evaluation deadlines.
For New Entrants and Emerging Players: E-commerce platforms for ride-hailing fleet self-dosing offer the most penetrable route into fragmented aftermarket demand in Jakarta, São Paulo, and Mexico City. Target marine gasoline outboard applications under EU recreational boating lead bans, where emulsion formulation expertise creates defensible positioning. Pursue technology licensing partnerships with German refiners pre-registering iron-based candidates to bypass 18-24 month ECHA authorization timelines.
For Investors and Strategic Acquirers: Petrochemical-integrated majors with captive refinery relationships are the most active acquirer in this space, seeking formulation expertise to complement feedstock positions. Mid-cap additive houses with REACH-authorized manganese portfolios and aviation gasoline certification pathways represent prime acquisition targets over a 5-10 year horizon. Monitor FAA certification progress for unleaded avgas alternatives as the critical inflection signal for aerospace demand reallocation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Manganese Feedstock | Captive supply of electrolytic manganese metal from South African or Gabonese sources insulates margin from export duty volatility. |
| REACH Pre-Registration for Alternative Chemistries | Iron-based antiknock candidates secure regulatory runway before ECHA's 2024-2026 substance evaluation deadlines. |
| Skid-Mounted Injection System Deployment | Terminal operators in India and Mexico bypass traditional bulk additive contracts through distributed micro-dosing infrastructure. |
| Aviation Gasoline Certification Pathway | FAA approval for unleaded high-octane formulations opens dedicated demand channel in Alaska and Australian general aviation clusters. |
| Long-Term Refinery Framework Agreement | Indian Oil Corporation and Reliance Industries lock in volume commitments through Bharat Stage VI upgrade cycles at Paradip and Jamnagar. |
Study Parameters
Direct dialogue with refinery operations managers, fuel terminal procurement leads, additive formulation chemists, and aviation gasoline blenders grounded qualitative assessment in operational reality across the value chain. Secondary validation drew from EPA fuel additive registration databases, ECHA REACH authorization filings, BIS fuel quality standards documentation, and customs trade data for manganese compound imports. Bottom-up terminal-level demand estimates triangulated against top-down refinery capacity expansion projections.
Segment-level value outputs reflect a structured analytical approach across the projection horizon, modeling additive type, end-use industry, physical form, and distribution channel dimensions. CAGRs derived from refinery upgrade cycle timing, regulatory compliance deadline clustering, and aviation gasoline reformulation adoption curves. Forecast inputs incorporated Bharat Stage VI implementation pace, ECHA rolling action plan prioritization, and FAA certification pathway milestones for unleaded avgas alternatives.
The model assumes a particular technology adoption path; alternative pathways for iron-based organometallic antiknock agents or advanced bio-oxygenate blends would alter the outlook through substitution dynamics and REACH authorization timeline compression. Forecasts reflect assumptions around manganese feedstock supply continuity, refinery greenfield build schedules, and piston-engine aircraft fleet persistence. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Tricalcium Citrate Market
Additives
Weighing Agents Market
Additives
Crack-Bridging Flexible Polymer Additives for Repair Mortars Market
Additives
Global Flame Retardant Masterbatches Market
Additives
Feedstuff Additives Market
Additives
Organic Dispersants Market
Additives
Alkyl Ketene Dimers (AKD) Wax Market
Additives
High Performing Matting Agents Market
Additives
Electrolyte Additives for Lithium Ion Battery Market
Additives
United Kingdom Feed Additives Market
Additives
China Sodium Reduction Ingredient Market
Additives
Global Hindered Amine Light Stabilizers Market
Additives
Metallic Stearate Market
Additives
Refining Additives Market
Additives
Global Performance Additives Market
Additives
Biofuel Additives Market