
 Volatile Corrosion Inhibitors Market | 2026-2036
Volatile Corrosion Inhibitors Market Size, Share, and Industry Trends Forecast 2026-2036
Volatile Corrosion Inhibitors Market Analytics
Asset-light leasing models for vapor-phase corrosion protection systems are reshaping competitive dynamics in this sector. Cortec Corporation leverages its specialized manufacturing scale to dominate North American supply channels. BASF SE anchors European demand through backward integration into amine-based precursor chemistry. Nouryon competes via proprietary solvent-delivery platforms that extend service intervals for marine applications.
Volatile corrosion inhibitors are organic compounds that volatilize from a carrier material and condense on metal surfaces to form a molecular barrier against oxidation, typically functioning within vapor pressures of 10⁻⁴ to 10⁻¹ mmHg at ambient temperatures. These formulations protect ferrous and non-ferrous metals during storage, transit, and operational standby across precision manufacturing and heavy industrial contexts. Nitrogen-based formulations lead product type revenue due to established performance in closed-loop aerospace systems, while biobased alternatives represent the fastest-expanding category as REACH restrictions tighten solvent-phase allowances. Metal protection applications command the deepest margin pools owing to specification-intensive defense and aviation contracts, though packaging applications show broadest volume traction across automotive tier-one suppliers.
EPA regulations under the Clean Air Act limit volatile organic compound emissions from industrial coatings and packaging films, directly constraining solvent-based formulation growth in US manufacturing corridors. ECHA's REACH framework and RoHS directives in Europe mandate disclosure of chlorinated compound content, accelerating substitution toward nitrogen and biobased chemistries among exporters serving EU markets. Stakeholders must monitor evolving MEE enforcement in China and SAMR standard updates that will determine market access terms for foreign corrosion inhibitor suppliers targeting domestic precision electronics manufacturing.
Market Dynamics
REACH and RoHS frameworks in Europe are compressing solvent-phase formulation margins while accelerating nitrogen-based and biobased chemistry substitution across precision metalworking and aerospace supply chains.
Growth Catalysts
- Aerospace Maintenance Expansion:Vapor-phase protection systems are penetrating deeper into aircraft storage and MRO operations as carriers extend fleet standby periods.
- REACH Solvent Restrictions:ECHA's tightening volatile organic compound thresholds are pulling demand toward compliant nitrogen-based inhibitor formulations.
- Germany's Industrial Corridor:Precision metalworking clusters in Baden-Württemberg and Bavaria are specifying advanced corrosion management for high-value component inventory.
Market Restraints
- Amine Precursor Cost Volatility:Backward integration into specialty amine chemistry requires capital commitments that mid-scale formulators cannot absorb.
- Chlorinated Compound Disclosure:RoHS mandates create compliance friction for legacy formulations containing undisclosed halogenated content.
- Biobased Performance Gap:Plant-derived alternatives still exhibit shorter service intervals in marine humidity conditions versus synthetic baselines.
Strategic Opportunities
- China Precision Electronics:SAMR standard updates and MEE enforcement patterns will determine access terms for foreign suppliers targeting domestic semiconductor packaging.
- Asset-Light Leasing Models:Vapor-phase system rental programs reduce customer capex barriers while locking in recurring consumable revenue.
- Marine Application Extension:Proprietary solvent-delivery platforms that lengthen protection intervals address vessel lay-up and offshore equipment storage.
Industry Challenges
- Formulation Chemist Scarcity:Expertise in vapor-pressure engineering and metal-specific adsorption kinetics concentrates among retiring specialists.
- Multi-Jurisdiction Registration:Separate dossier requirements for EPA, ECHA, and China's MEE extend product launch timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Volatile Corrosion Inhibitors Market |
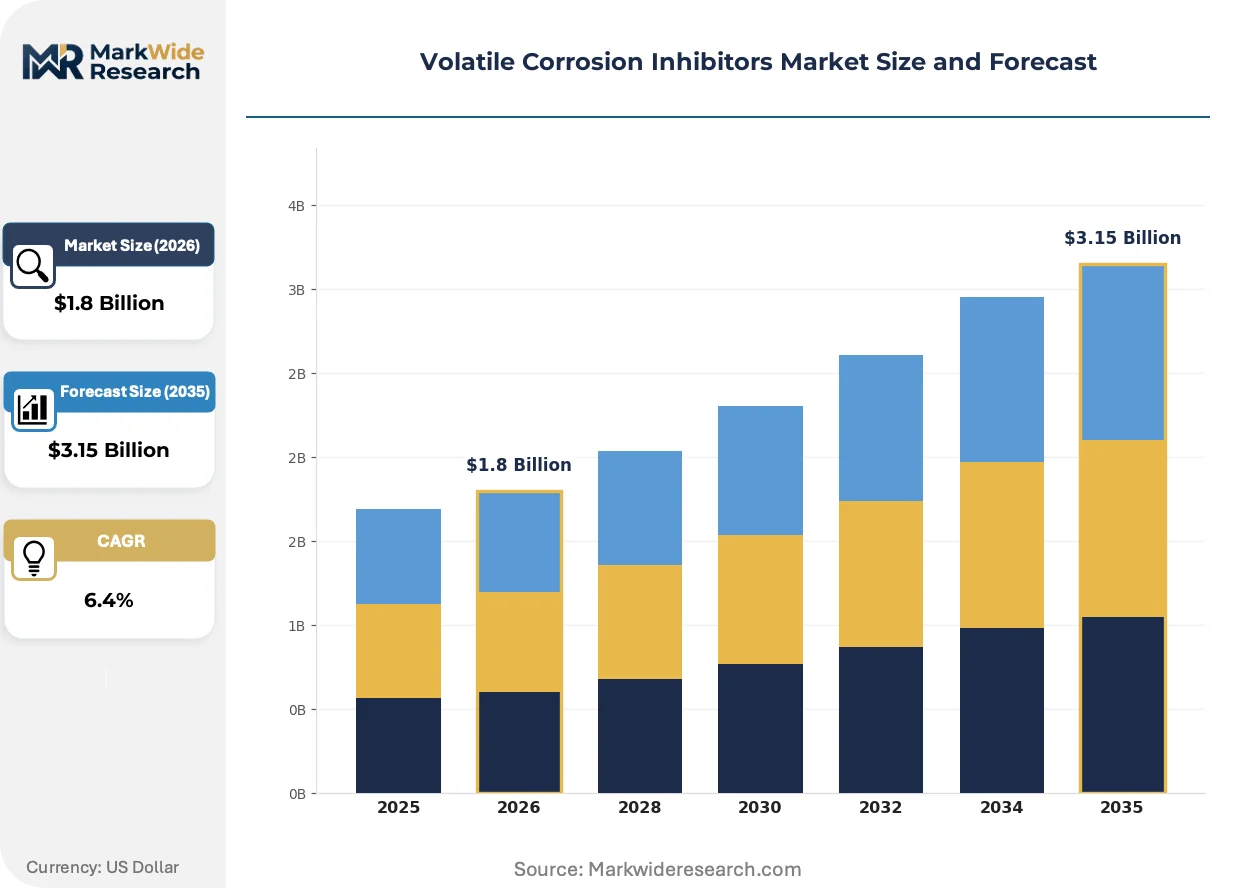
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nitrogen-based, Chlorinated, Biobased, Solvent-based End Use: Aerospace, Marine, Automotive, Electronics Application: Metal Protection, Packaging, Coatings, Cleaning Distribution Channel: Direct Sales, Retail, Online, Distributors |
| Companies Covered | Cortec Corporation, BASF SE, The Dow Chemical Company, Henkel AG & Co. KGaA, Akzo Nobel NV, Ecolab, Nouryon, LANXESS AG, Protective Packaging Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Volatile Corrosion Inhibitors Market Evolving Landscape
Formulation chemistry is pivoting toward biobased feedstocks while delivery mechanisms and procurement structures undergo parallel transformation across defense, aviation, and automotive supply chains.
Biobased volatile corrosion inhibitors derived from agricultural waste streams are migrating from niche packaging applications toward specification-intensive aerospace contracts. Tier-one suppliers in Germany and France are piloting these formulations for engine component storage. This chemistry shift is compressing the premium commanded by petroleum-derived nitrogen bases in closed-loop systems.
EPA enforcement under the Clean Air Act is tightening volatile organic compound emission limits for industrial coatings and packaging films. US manufacturing corridors face reformulation costs or capacity constraints. Metal protection applications serving defense contracts are absorbing compliance premiums while packaging segments explore waterborne carrier alternatives.
Leasing arrangements for vapor-phase protection hardware are displacing outright equipment purchases among automotive tier-one suppliers. Fixed monthly fees cover system installation, inhibitor replenishment, and performance monitoring. This model concentrates in Germany's supplier parks where inventory turnover cycles align with contract durations.
Volatile Corrosion Inhibitors Market Segmentation
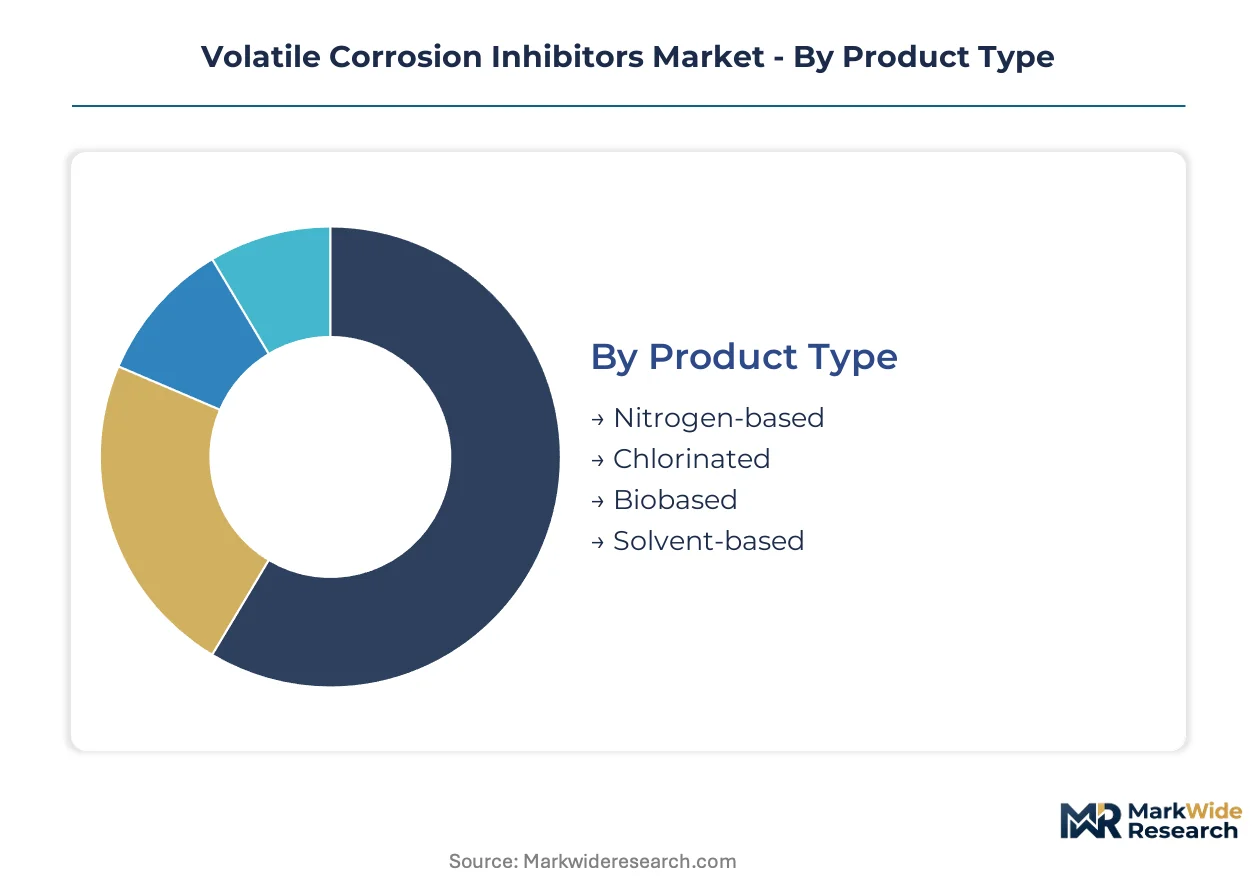
Segmentation in volatile corrosion inhibitors determines formulation chemistry, service intensity, and margin architecture. Product type dictates regulatory compliance pathways while end-use segments command vastly different specification thresholds and contract structures.
Product Type:
After-sales-service intensity varies sharply across chemistry platforms, with nitrogen-based systems requiring continuous vapor-pressure monitoring and biobased alternatives demanding more frequent reapplication protocols.
- Nitrogen-based:Amine and amine-salt formulations dominate closed-loop aerospace systems with vapor pressures engineered between 10⁻⁴ and 10⁻¹ mmHg. German precision metalworking clusters in Baden-Württemberg specify these chemistries for high-value component inventory under REACH solvent restrictions.
- Biobased:Agricultural waste-derived compounds from corn stover and lignin fractions are penetrating aerospace contracts previously reserved for synthetic bases. France's engine component storage pilots are compressing the premium commanded by petroleum-derived alternatives.
- Chlorinated:Legacy halogenated formulations face RoHS disclosure friction and substitution pressure across EU export markets.
- Solvent-based:Carrier-phase systems confront EPA Clean Air Act emission limits and reformulation costs in US manufacturing corridors.
By volume, nitrogen-based formulations lead. By growth pace, biobased alternatives are climbing the fastest.
End Use:
Application-specific performance requirements stratify pricing tiers, with aerospace and marine contracts absorbing specification premiums while automotive procurement shifts toward leased vapor-phase systems.
- Aerospace:Aircraft storage and MRO operations specify vapor-phase protection for extended fleet standby periods. Defense contracts absorb compliance premiums for EPA-regulated formulations.
- Marine:Vessel lay-up and offshore equipment storage drive demand for proprietary solvent-delivery platforms that lengthen protection intervals in humidity-intensive conditions.
- Automotive:Tier-one suppliers in Germany's supplier parks are adopting fixed-fee leasing arrangements covering installation, replenishment, and monitoring.
- Electronics:Semiconductor packaging applications in China face access terms determined by SAMR standard updates and MEE enforcement patterns.
Aerospace commands the deepest margin pools. Electronics shows the steepest expansion trajectory as precision manufacturing localizes in Asia-Pacific.
Application:
Functional deployment determines carrier material selection and reapplication frequency, with metal protection requiring direct surface adsorption engineering and packaging favoring diffuse vapor distribution.
- Metal Protection:Direct molecular barrier formation on ferrous and non-ferrous surfaces serves specification-intensive defense and aviation contracts with the highest margin capture.
- Packaging:Diffuse vapor-phase distribution across enclosed volumes shows broadest volume traction among automotive tier-one suppliers exploring waterborne carrier alternatives.
- Coatings:Integrated corrosion management within industrial coating systems faces volatile organic compound thresholds under EPA and ECHA frameworks.
- Cleaning:Degreasing and surface preparation applications incorporate inhibitor residues for interim protection during manufacturing workflows.
Metal protection leads by revenue concentration. Packaging dominates by unit volume across supplier networks.
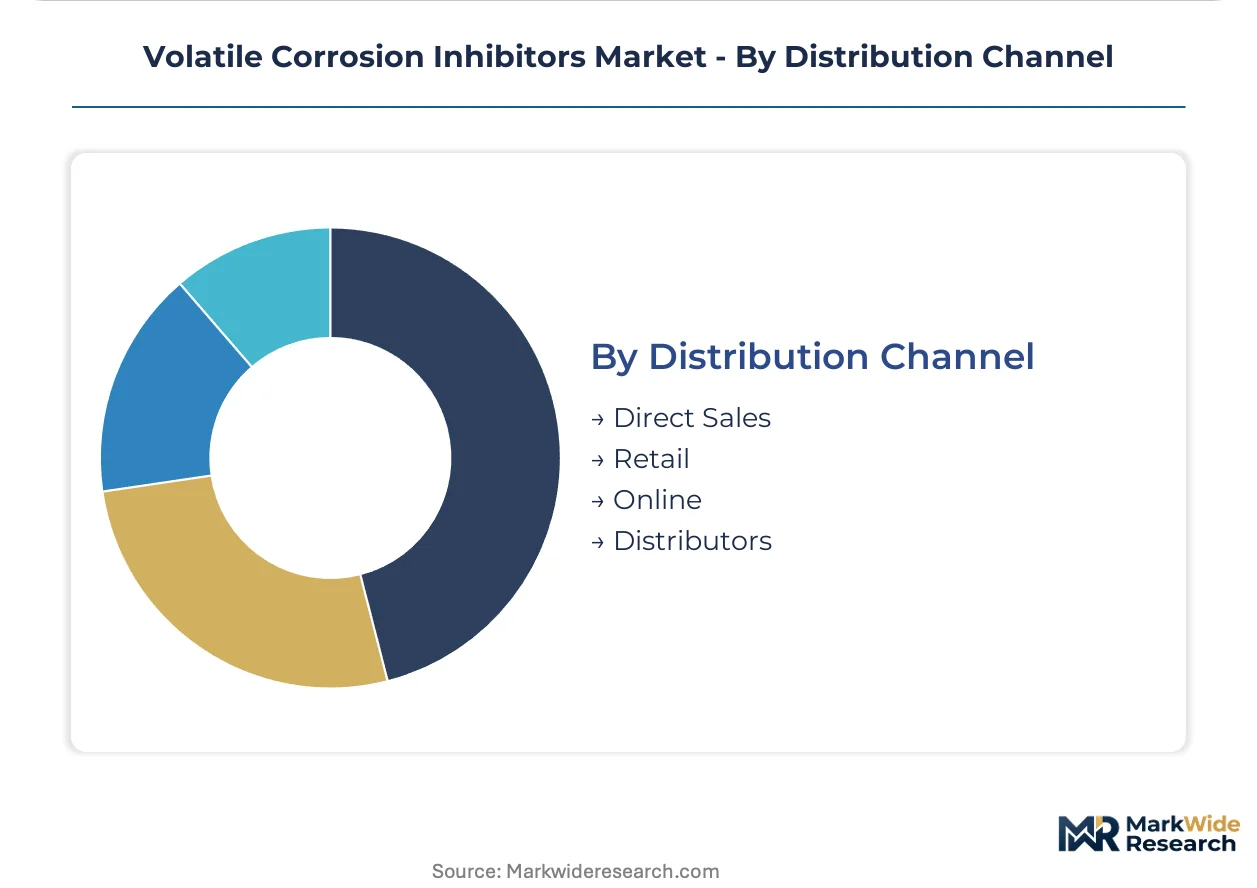
Distribution Channel:
Channel selection reflects customer scale and technical support requirements, with direct sales locking in long-term consumable commitments and distributor networks extending geographic reach.
- Direct Sales:Long-term supply agreements with aerospace OEMs and defense contractors include embedded technical service and vapor-pressure monitoring protocols.
- Distributors:Regional chemical distributors extend formulation access to mid-scale metalworking operations lacking in-house corrosion engineering expertise.
- Retail:Small-volume packaging for maintenance shops and independent repair operations carries higher per-unit margins with minimal service attachment.
- Online:Digital procurement platforms are emerging for standardized inhibitor formulations with established technical specifications and reduced consultation requirements.
Direct sales capture the highest contract values. Distributor channels are gaining share fastest among precision metalworking clusters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense contractors and automotive tier-one suppliers concentrate procurement in manufacturing corridors where REACH compliance costs and precision metalworking density overlap. Aerospace MRO operators drive specification intensity in regions with extended fleet standby protocols.
United States
EPA enforcement under the Clean Air Act tightens volatile organic compound emission limits for industrial coatings and packaging films. Defense contracts absorb compliance premiums for metal protection formulations serving aviation and naval applications. Manufacturing corridors in Michigan and Ohio face reformulation costs as solvent-based systems confront capacity constraints.
Germany
Precision metalworking clusters in Baden-Württemberg and Bavaria specify advanced corrosion management for high-value component inventory. ECHA's REACH framework mandates disclosure of chlorinated compound content, accelerating nitrogen-based chemistry substitution. Stuttgart's supplier parks pilot fixed-fee leasing arrangements covering vapor-phase system installation and inhibitor replenishment.
China
SAMR standard updates and MEE enforcement patterns determine market access terms for foreign suppliers targeting domestic semiconductor packaging. Precision electronics manufacturing localizes in the Yangtze River Delta and Pearl River Delta regions. Domestic formulators compete on cost while foreign players navigate dual carbon goal alignment.
France
Engine component storage pilots in Toulouse and Paris-Saclay aerospace clusters compress premiums commanded by petroleum-derived nitrogen bases. RoHS directives create compliance friction for legacy halogenated formulations in EU export markets. Biobased alternatives derived from agricultural waste streams penetrate specification-intensive contracts previously reserved for synthetic chemistries.
Japan
METI industrial standards shape formulation requirements for precision electronics and automotive component protection. Kanto and Kansai manufacturing belts specify vapor-phase systems for extended inventory standby periods. Domestic chemical conglomerates leverage backward integration into amine precursor chemistry to serve regional aerospace supply chains.
Volatile Corrosion Inhibitors Market Competitive Landscape
Channel-controlling players compete with product-specialist players across formulation chemistry and delivery platform segments. The vendor base stratifies between integrated chemical conglomerates with captive raw material positions and focused corrosion protection specialists. Three archetypes dominate: backward-integrated precursor producers, proprietary solvent-delivery platform developers, and asset-light system leasing operators. Competitive moves concentrate on geographic expansion through distributor partnerships and portfolio diversification into biobased chemistries.
Among integrated chemical conglomerates, BASF SE anchors European demand through captive amine-based precursor production. Nouryon occupies a position within proprietary solvent-delivery platform development for marine humidity applications. Cortec Corporation exemplifies the North American specialist model with concentrated manufacturing scale serving regional supply channels.
| Leading Market Players |
|---|
| Cortec Corporation |
| BASF SE |
| The Dow Chemical Company |
| Henkel AG & Co. KGaA |
| Akzo Nobel NV |
| Ecolab |
| Nouryon |
| LANXESS AG |
| Protective Packaging Corporation |
| Others |
Value Network & Pricing Analysis
The Rotterdam-Antwerp chemical corridor's freight cost dynamics concentrate supply power among backward-integrated amine producers while forcing three-tier price differentiation across aerospace, automotive, and packaging buyer segments.
Pricing Analysis
Cost-plus contracts indexed to ethylene oxide and specialty amine benchmarks dominate long-term aerospace supply agreements. Three-tier pricing structure across premium, standard, and economy levels separates defense-specification nitrogen-based formulations from REACH-compliant biobased alternatives and commodity solvent-based systems. Pricing pressure stems from EPA Clean Air Act compliance costs compressing margins on legacy chlorinated formulations. Automotive tier-one suppliers exhibit highest price sensitivity through fixed-fee leasing negotiations, while defense contractors absorb specification premiums with minimal elasticity.
Supply Chain Analysis
Upstream feedstock concentration in Germany, the Netherlands, and Belgium anchors European nitrogen-based inhibitor production through captive amine precursor facilities. Specialty amine chemistry, agricultural waste lignin fractions, and halogenated compound precursors constitute critical input dependencies. Single-source vulnerability concentrates around cyclohexylamine and dicyclohexylamine suppliers serving aerospace formulators. Distribution runs through direct sales channels for defense and aviation contracts, with regional chemical distributors extending access to mid-scale metalworking operations lacking corrosion engineering expertise.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Formulation expertise in vapor-pressure engineering and metal-specific adsorption kinetics concentrates among a shrinking cohort of specialists, creating durable capability moats for firms that secure this talent.
For Market Incumbents: Harden supply security through backward integration into specialty amine precursor chemistry or long-term offtake agreements with European petrochemical hubs. BASF SE's captive production model demonstrates how upstream control neutralizes raw material volatility threatening mid-scale competitors. Prioritize biobased R&D investment to preempt REACH solvent-phase restrictions that will disqualify legacy formulations from EU export markets. For New Entrants and Emerging Players: China's precision electronics packaging sector, where SAMR standard updates create temporary access windows for compliant foreign suppliers, represents the most penetrable entry point before domestic formulators achieve technical parity. Marine humidity applications with proprietary solvent-delivery platforms offer second white-space opportunity given Nouryon's limited geographic coverage. Partner with regional chemical distributors in Germany's supplier parks to bypass direct sales capability gaps. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors asset-light system leasing operators with recurring consumable revenue over capital-intensive manufacturing scale players. Long-term viability hinges on biobased chemistry transition completion and REACH compliance certification depth. Monitor ECHA substance of very high concern candidate list updates as inflection signal for accelerated chlorinated formulation substitution.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Amine Precursors | Captive supply of cyclohexylamine derivatives neutralizes cost volatility threatening German formulators. |
| Biobased Formulation Certification | REACH-compliant agricultural waste-derived chemistry unlocks aerospace contracts previously reserved for petroleum bases. |
| Asset-Light Leasing Model Expansion | Fixed-fee vapor-phase system rentals reduce customer capex barriers while locking in recurring inhibitor revenue. |
| Marine Application Platform Extension | Proprietary solvent-delivery systems addressing vessel lay-up conditions extend protection intervals beyond synthetic baselines. |
| China Market Access Preparation | SAMR standard alignment and MEE enforcement pattern monitoring determine semiconductor packaging entry timing. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with formulation chemists, aerospace procurement directors, marine fleet maintenance officers, and automotive tier-one supply chain managers; and secondary validation through ECHA REACH registration dossiers, EPA Clean Air Act enforcement records, SAMR standard update bulletins, and customs trade flow data for amine-based corrosion inhibitor precursors. Bottom-up triangulation across product type, end-use application, and regional demand clusters anchored volume estimates, while top-down cross-checks against chemical industry association reports ensured consistency.
Forecast inputs considered nitrogen-based versus biobased chemistry substitution rates, REACH solvent restriction phase-in timelines, aerospace fleet storage duration extensions, and automotive leasing model adoption curves across the analysis window. Segmentation modeling spanned product chemistry platforms, end-use industries, application methods, and distribution channel structures. CAGRs derived from regression analysis of historical demand patterns adjusted for regulatory inflection points and technology substitution elasticities.
Practitioners should monitor ECHA SVHC candidate list expansions, EPA VOC emission threshold revisions, and MEE enforcement intensity patterns for early signals requiring forecast reassessment. Cross-checking against Cefic chemical production statistics and ACC end-use demand surveys is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Oilfield Drilling Fluid Additive Market
Additives
Additives for Floor Coatings Market
Additives
Surface Modifiers Market
Additives
Phthalate Plasticizer Market
Additives
Stabilizers Market
Additives
Sodium Potassium Tartrate Market
Additives
Antiscalants/Scale Inhibitors Market
Additives
Asia-Pacific Water Enhancer Market
Additives
Flux Injection System Market
Additives
Isobutyl Acetate Market
Additives
Hydrogen Peroxide Chemical Indicator Market
Additives
Global Sodium Acetate Market
Additives
Global Propyl Acetate Market
Additives
Anti-Creasing Agent Market
Additives
Anti Crystallizing Agents Market
Additives
Asia-Pacific Concrete Admixtures Market