
 Sodium Metabisulfite Market | 2026-2036
Sodium Metabisulfite Market Size, Share, and Industry Trends Forecast 2026-2036
Sodium Metabisulfite Market Analysis
ISO 22000 food safety management certification is bifurcating the competitive landscape into qualified and non-qualified suppliers. BASF SE leverages its integrated sulfur chemistry platform to sustain cost advantages across European and Asian markets. Aditya Birla Chemicals anchors significant production capacity in India, competing on proximity to South Asian food processing demand. FMC Corporation differentiates through pharmaceutical-grade specialization, navigating stringent purity requirements in regulated end uses.
Sodium metabisulfite (Na₂S₂O₅) is an inorganic compound produced via the crystallization of sodium bisulfite solutions, typically containing 65-67% sulfur dioxide equivalent by weight. The compound functions primarily as an oxygen scavenger, antimicrobial agent, and reducing agent across food preservation, water dechlorination, and chemical synthesis applications. Food Grade product type dominates value capture due to stringent certification overhead and recurring batch testing requirements, while Industrial Grade segments compete on volume throughput with thinner margin structures. Water Treatment application is expanding fastest as municipal utilities confront stricter discharge limits, though Food Preservation retains the largest absolute revenue pool tied to wine, fruit, and seafood processing demand.
FDA food additive regulations under 21 CFR 182.3766 govern permissible sulfur dioxide residual limits in processed foods, directly constraining formulation practices and supplier documentation burdens. EPA effluent guidelines for textile and chemical processing plants mandate sodium metabisulfite deployment in wastewater dechlorination, creating compliance-driven demand independent of industrial production cycles. EFSA and REACH frameworks in Europe impose additional purity and traceability requirements that filter market access for non-certified producers. Stakeholders must monitor evolving sulfur dioxide labeling thresholds and dual-use chemical security protocols that could redirect procurement toward qualified regional suppliers.
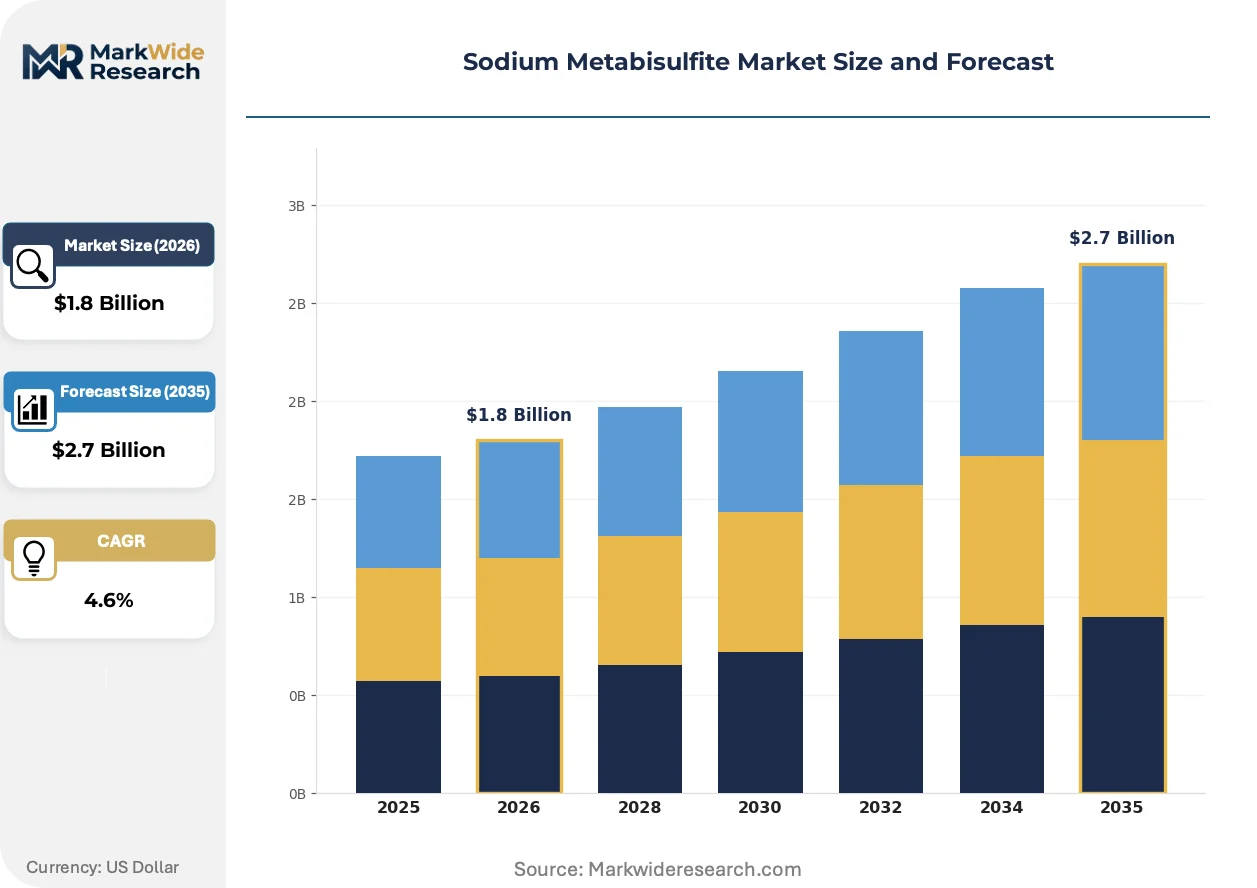
Market Dynamics
ISO 22000 certification requirements are concentrating buyer procurement toward qualified suppliers while sulfur dioxide residual limits under FDA 21 CFR 182.3766 tighten formulation tolerances across food preservation applications.
Growth Catalysts
- EPA effluent guidelines:Textile and chemical processing plants deploy sodium metabisulfite for wastewater dechlorination, creating compliance-driven demand independent of industrial production cycles.
- China's chemical clusters:Shandong and Jiangsu province production hubs supply domestic food processors and export markets, anchoring regional supply security.
- Water treatment utilities:Municipal operators confront stricter discharge limits, accelerating oxygen scavenger adoption in dechlorination infrastructure.
Market Restraints
- Sulfur input volatility:Feedstock sulfur price swings compress margin structures for crystallization-dependent producers without integrated sulfur chemistry platforms.
- REACH purity mandates:ECHA traceability requirements filter market access for non-certified producers, elevating documentation burdens.
- Potassium sorbate substitution:Alternative preservatives displace sodium metabisulfite in certain fruit processing applications where sulfur dioxide labeling thresholds tighten.
Strategic Opportunities
- Pharmaceutical-grade specialization:Stringent purity requirements in regulated end uses create premium positioning for batch-certified production.
- EU Green Deal alignment:Circular chemistry incentives favor sulfur recovery processes and closed-loop manufacturing investments.
- Direct-to-processor digital channels:Food and beverage manufacturers bypass traditional distributors for certified bulk procurement, reducing qualification friction.
Industry Challenges
- ISO 22000 audit timelines:Certification backlog delays supplier qualification, constraining revenue recognition for expanding producers.
- Legacy water treatment infrastructure:Municipal utility capital constraints slow dechlorination system retrofits, extending sales cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sodium Metabisulfite Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food Grade, Industrial Grade, Pharmaceutical Grade, Technical Grade Application: Food Preservation, Water Treatment, Textile Industry, Photography End User: Food & Beverage, Chemicals, Pharmaceuticals, Agriculture Packaging Type: Bags, Drums, Totes, Bulk Containers |
| Companies Covered | BASF SE, Aditya Birla Chemicals, FMC Corporation, Esseco USA, Solvay, INEOS Calabrian, Grillo-Werke, Shandong Kailong Chemical Technology, Hawkins, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sodium Metabisulfite Market Emerging Trajectories
Process intensification in crystallization technology and tightening sulfur dioxide labeling thresholds are reshaping competitive differentiation between food-grade and industrial-grade supply tiers.
Continuous crystallization systems with inline purity monitoring are bifurcating the supplier base. Large-scale food processors adopt automated batch certification to reduce testing overhead. This technology is bifurcating margin capture between integrated sulfur chemistry platforms and commodity crystallization operators.
REACH authorization requirements for sulfur dioxide derivatives tighten substance volume tracking across European supply chains. Chemical processors face expanded safety data sheet obligations and downstream user communication mandates. Food-grade exporters to Europe invest in dedicated REACH-compliant production lines to maintain market access.
Buyer consolidation among wine and dried fruit processors concentrates procurement leverage toward qualified suppliers with multi-site certification. Long-term supply agreements replace spot purchasing, locking in volume commitments. This pattern is most visible across California's Central Valley and France's Languedoc-Roussillon wine regions.
Sodium Metabisulfite Market Segmentation
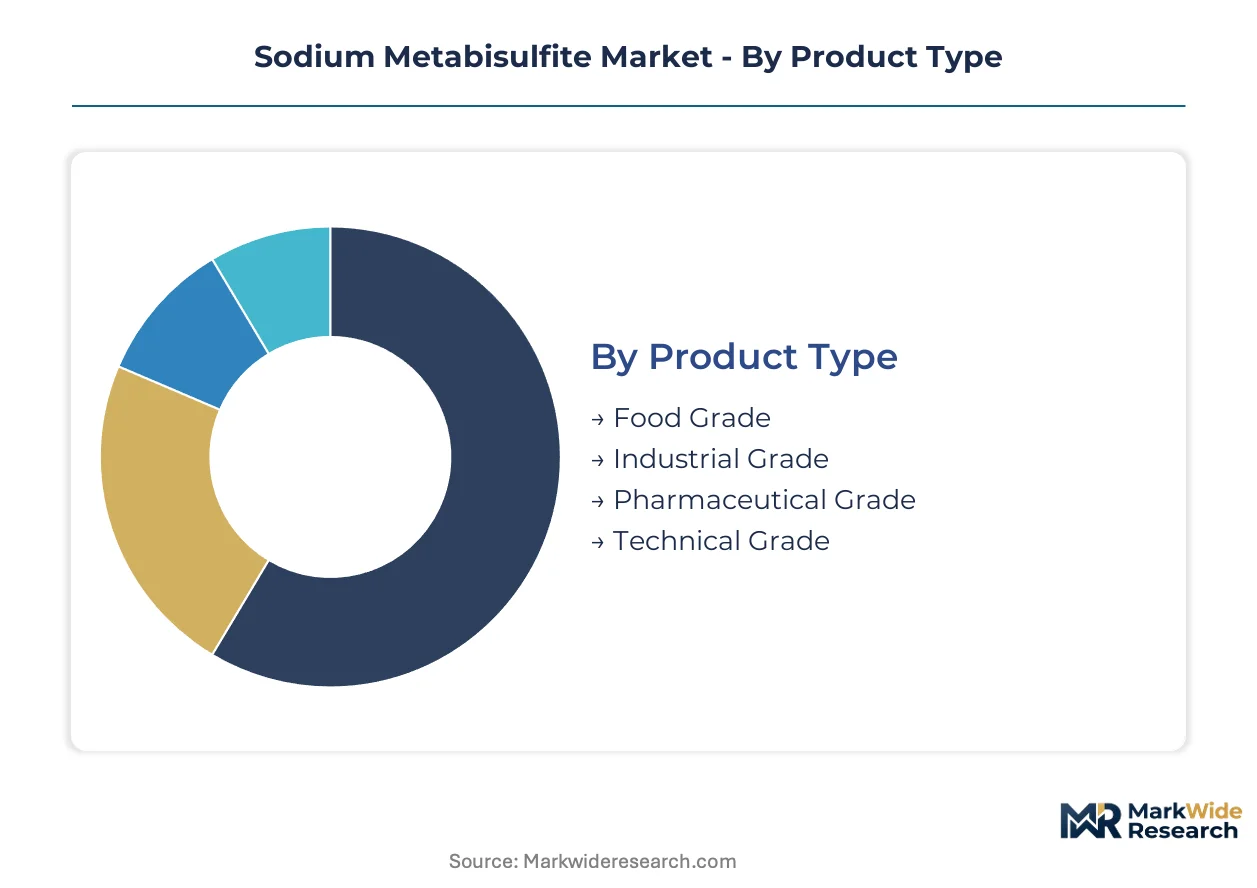
Sodium metabisulfite procurement patterns diverge sharply across grade purity, with certification overhead creating distinct pricing tiers that reshape supplier selection. Food-grade specifications command premium positioning due to batch testing burdens, while industrial applications compete on volume throughput with thinner margins.
Product Type:
Potassium sorbate substitution pressure falls heaviest on technical and industrial grades, where labeling flexibility allows preservative switching; food and pharmaceutical grades resist displacement due to regulatory lock-in.
- Food Grade:Specifications require 65-67% sulfur dioxide equivalent with ISO 22000 batch certification. Wine processors in France's Languedoc-Roussillon and dried fruit packers in California's Central Valley concentrate procurement toward multi-site certified suppliers, locking in long-term supply agreements that displace spot purchasing.
- Industrial Grade:Crystallization-dependent production with thinner margin structures competes on volume throughput. Textile wastewater dechlorination plants under EPA effluent guidelines anchor demand, though sulfur input volatility compresses margins for non-integrated producers.
- Pharmaceutical Grade:Stringent purity requirements with batch-certified documentation for regulated end uses.
- Technical Grade:Standard crystallization output serving chemical synthesis and non-food applications with minimal certification overhead.
Food Grade retains volume leadership; Pharmaceutical Grade holds the steepest expansion curve.
Application:
Cost tier stratification separates compliance-driven municipal procurement from discretionary industrial purchasing, with water treatment utilities bearing mandated upgrade cycles.
- Food Preservation:FDA 21 CFR 182.3766 sulfur dioxide residual limits constrain formulation practices. Wine, dried fruit, and seafood processors generate recurring demand tied to harvest cycles and seasonal processing windows.
- Water Treatment:Municipal utilities confront stricter discharge limits under EPA effluent guidelines, accelerating oxygen scavenger adoption in dechlorination infrastructure retrofits.
- Textile Industry:Wastewater dechlorination mandates create compliance-driven demand independent of textile production cycles.
- Photography:Declining analog imaging demand constrains volume, though specialized archival applications sustain niche procurement.
Food Preservation dominates absolute revenue; Water Treatment is climbing the fastest.
End User:
Customer type concentration reflects divergent qualification friction, with food and pharmaceutical buyers imposing multi-audit supplier screening that excludes commodity producers.
- Food & Beverage:ISO 22000 certification backlog delays supplier qualification, constraining revenue recognition for expanding producers. Direct-to-processor digital channels bypass traditional distributors.
- Pharmaceuticals:REACH authorization requirements and EFSA purity mandates filter market access, elevating documentation burdens for non-certified producers.
- Chemicals:Industrial synthesis applications with price-sensitive procurement and thinner margin tolerance.
- Agriculture:Post-harvest treatment and soil amendment applications with seasonal demand concentration.
Food & Beverage captures the largest procurement pool; Pharmaceuticals shows the sharpest margin premium.
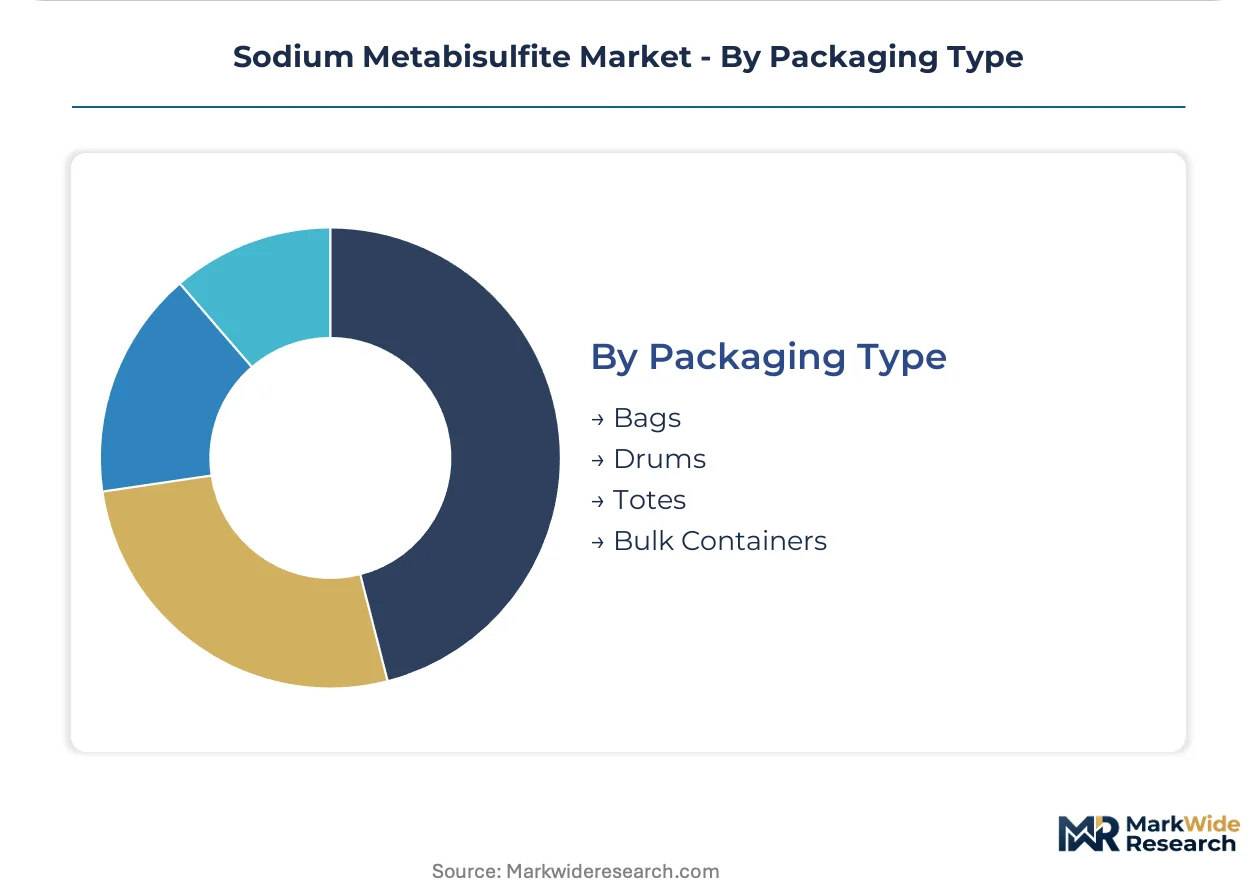
Packaging Type:
Supply chain configuration varies by delivery scale, with bulk infrastructure investments separating integrated chemical platforms from repackaging intermediaries.
- Bags:25-50kg woven polypropylene units for mid-scale food processors and agricultural distributors.
- Drums:Standard 200-250kg steel or fiber containers for chemical synthesis and textile processing plants.
- Totes:Intermediate bulk containers enabling automated handling at municipal water treatment facilities.
- Bulk Containers:Tanker and silo delivery for integrated sulfur chemistry platforms serving high-volume industrial offtake.
Bulk Containers anchor industrial volume; Totes are gaining share fastest in utility retrofit programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA effluent guidelines and REACH authorization protocols are concentrating sodium metabisulfite procurement toward certified suppliers in major processing economies. Food safety mandates and water treatment compliance drive divergent qualification requirements across national markets.
United States
California's Central Valley dried fruit processors and wine regions anchor food-grade demand under FDA 21 CFR 182.3766 sulfur dioxide limits. EPA effluent guidelines for textile plants mandate wastewater dechlorination deployment. Texas and Louisiana chemical corridors supply industrial-grade volume to Gulf Coast refineries and municipal utilities.
China
Shandong and Jiangsu province chemical clusters dominate crystallization capacity serving domestic food processors and export markets. The country's dual carbon goals tighten emissions standards for sulfur-based chemical production. Qingdao and Nanjing port infrastructure enables bulk container shipment to Southeast Asian food manufacturers.
Germany
BASF SE's integrated sulfur chemistry platform in Ludwigshafen sustains cost advantages across European distribution. ECHA REACH traceability requirements filter market access for non-certified producers. The country's pharmaceutical-grade specialization aligns with EFSA purity mandates for regulated end uses.
India
Aditya Birla Chemicals anchors production capacity in Gujarat competing on proximity to South Asian food processing demand. FSSAI food additive standards tighten documentation burdens for imported sulfur dioxide derivatives. Maharashtra and Karnataka states concentrate procurement from qualified suppliers with multi-site ISO 22000 certification.
France
Languedoc-Roussillon wine processors concentrate procurement leverage toward long-term supply agreements with certified suppliers. EU Green Deal circular chemistry incentives favor sulfur recovery investments. ANSM pharmaceutical regulations impose batch-certified documentation requirements for medical-grade applications.
Sodium Metabisulfite Market Vendor Landscape
Listed leaders compete with private specialists across certification tiers and geographic coverage. The supplier base concentrates around integrated sulfur chemistry platforms and regional crystallization operators. Three archetypes dominate: diversified chemical conglomerates with captive sulfur supply, mid-scale regional producers competing on proximity, and pharmaceutical-grade specialists capturing premium positioning. Competitive moves center on backward integration into sulfur sourcing and multi-site ISO 22000 certification expansion.
Among diversified chemical conglomerates, BASF SE and Solvay exemplify integrated platform strategies spanning food-grade and industrial applications. Aditya Birla Chemicals occupies a position within the regional proximity tier, anchoring supply security for South Asian processors. FMC Corporation represents the pharmaceutical-grade specialization vector, navigating stringent purity requirements through batch-certified production protocols.
| Leading Market Players |
|---|
| BASF SE |
| Aditya Birla Chemicals |
| FMC Corporation |
| Esseco USA |
| Solvay |
| INEOS Calabrian |
| Grillo-Werke |
| Shandong Kailong Chemical Technology |
| Hawkins, Inc. |
| Others |
Supply Flow & Price Mechanics
ISO 22000 certification gates simultaneously constrain supplier qualification and amplify price differentiation between food-grade and industrial-grade tiers. This dual-gating mechanism concentrates procurement leverage among multi-site certified producers while compressing margins for commodity crystallization operators lacking integrated sulfur chemistry platforms.
Pricing Analysis
Certification level creates the primary spread between pharmaceutical-grade premiums and industrial-grade commodity pricing. Three-tier pricing structure across food-grade, industrial-grade, and technical-grade levels reflects batch testing burdens and documentation overhead. Cost compression in industrial grades is intensifying because sulfur input volatility squeezes crystallization-dependent producers without captive supply. Chemical synthesis buyers exhibit highest price sensitivity, while pharmaceutical formulators accept steep premiums for batch-certified documentation.
Supply Chain Analysis
Strategic stockpiling dominates food-grade procurement to secure harvest-season supply continuity, while industrial buyers favor just-in-time contracts indexed to sulfur feedstock movements. Manufacturing concentrates in China, Germany, and India, with Shandong province crystallization hubs feeding Asian food processors and BASF's Ludwigshafen platform anchoring European distribution. Production draws from elemental sulfur, caustic soda, and energy inputs, with single-source vulnerability concentrated in sulfur mining geographies. Distribution runs through integrated chemical platforms for bulk industrial offtake and regional distributors for bagged food-grade shipments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EPA effluent guideline expansion and REACH authorization tightening signal early-cycle adoption acceleration in compliance-driven water treatment and pharmaceutical-grade segments. Penetration tailwinds favor suppliers with pre-positioned certification infrastructure.
For Market Incumbents: Consolidate multi-site ISO 22000 certification coverage to defend against potassium sorbate substitution in fruit processing applications. BASF SE's integrated sulfur chemistry platform exemplifies backward integration into captive feedstock supply that locks in cost advantages against commodity crystallization competitors. For New Entrants and Emerging Players: Differentiate on pharmaceutical-grade batch certification to capture premium positioning in EFSA-regulated European markets. Municipal water treatment utilities in North America represent the most penetrable white-space segment, with direct-to-processor digital channels reducing traditional distributor qualification friction. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates seeking to divest non-core sulfur derivative operations. Long-term viability hinges on sulfur recovery process investments aligned with EU Green Deal circular chemistry incentives. Revision becomes warranted when sulfur dioxide labeling threshold tightening accelerates preservative substitution beyond modeled rates.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sulfur Sourcing | BASF SE's captive sulfur supply locks in margin protection against feedstock volatility. |
| Multi-Site ISO 22000 Certification Expansion | Aditya Birla Chemicals leverages Gujarat production proximity to South Asian food processors. |
| Pharmaceutical-Grade Specialization | FMC Corporation navigates ANSM batch documentation requirements for medical-grade applications. |
| Long-Term Supply Agreement Lock-In | Languedoc-Roussillon wine processors displace spot purchasing with qualified supplier commitments. |
| REACH-Compliant Production Line Investment | Food-grade exporters to Europe maintain market access under ECHA traceability mandates. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of customs trade data, chemical industry association reports, and regulatory filings from FDA, ECHA, and FSSAI. Plant managers at crystallization facilities, procurement leads at wine and dried fruit processors, distribution channel partners, and technical R&D directors contributed operational perspective. Bottom-up volume modeling triangulates against top-down value estimates derived from trade flow analysis and capacity announcements.
Segmentation dimensions modeled include grade purity tier, end-use application, packaging format, and regional production hub across the projection horizon. CAGRs derive from regression analysis of historical price-volume relationships and forward assessment of regulatory compliance cost trajectories. Forecast inputs incorporate sulfur feedstock price elasticity and municipal utility capital expenditure cycles for dechlorination infrastructure.
Material uncertainties — sulfur dioxide labeling threshold revisions, potassium sorbate substitution acceleration, and REACH authorization timeline shifts — sit outside the modeled envelope. Forecasts reflect assumptions about certification backlog resolution and utility capital constraint persistence. Revision becomes warranted when EPA effluent guideline enforcement intensity crosses thresholds that alter municipal procurement urgency.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
China Feed Additives Market
Additives
Triazine UV Absorber Market
Additives
Germany Sodium Reduction Ingredient Market
Additives
United Kingdom Feed Additives Market
Additives
Pectin Market
Additives
Cassia Gum Market
Additives
Battery Additives Market
Additives
Global Sodium Acetate Market
Additives
Global UV Stabilizers Market
Additives
Calcium Diglutamate Market
Additives
Flux Injection System Market
Additives
Carboxymethyl Cellulose Market
Additives
Wax Additives Market
Additives
Humectants Market
Additives
Antiblock Agents Market
Additives
Crosslinking Agents Market