
 Tire Additives Market | 2026-2036
Tire Additives Market Size, Share, and Industry Trends Forecast 2026-2036
Tire Additives Market Analytics
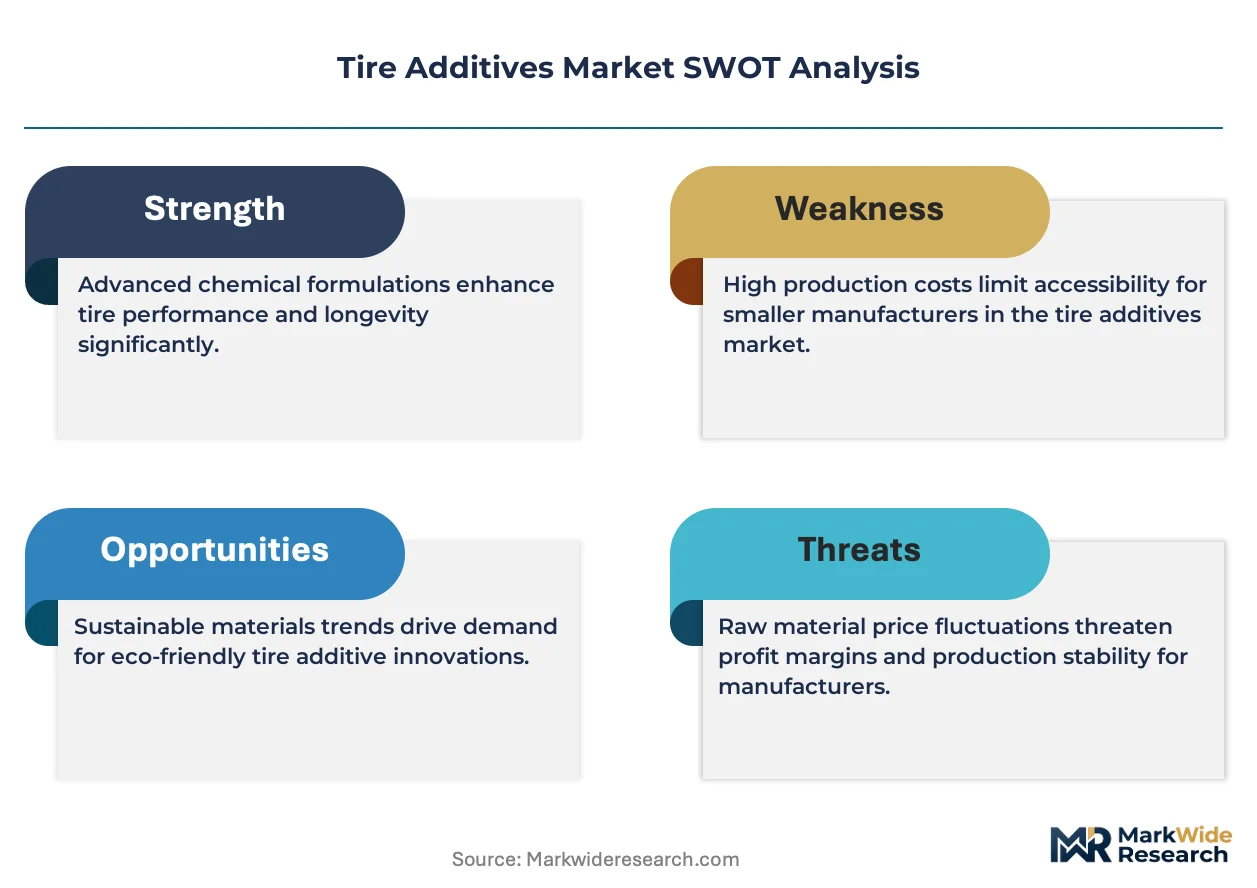
High-performance silica-grade specifications is bifurcating the competitive landscape between commodity suppliers and technical compound specialists. BASF SE leverages its integrated polymer research network to develop advanced coupling agent systems for green tire formulations. Lanxess anchors its position through backward integration into rubber chemical precursors, securing feedstock reliability across European and Asian manufacturing sites. Eastman Chemical Company differentiates via proprietary resin technologies that enhance tire durability without sacrificing rolling resistance targets.
Tire additives comprise specialized chemical compounds and reinforcing materials blended into rubber formulations during compounding to modify physical properties such as tensile strength, abrasion resistance, thermal stability, and wet traction coefficients. These substances function through mechanisms including free-radical scavenging, filler dispersion improvement, and polymer crosslink density modification to meet original equipment and replacement tire specifications. Among product type segments, fillers commands the dominant value share due to carbon black and precipitated silica volumes required per tire unit, while coupling agents represents the fastest-expanding category as silica-reinforced green tire architectures proliferate. Within end use industry segmentation, automotive absorbs the majority of additive volumes, though aerospace applications command premium pricing tiers given certification requirements for landing gear and high-speed tire assemblies.
The EPA oversees volatile organic compound emissions from tire manufacturing facilities under Clean Air Act provisions, directly influencing solvent-based processing aid formulations and driving waterborne system substitution. REACH registration requirements administered by ECHA mandate full toxicity dossiers for antioxidant and accelerator substances imported into European Union member states, elevating compliance costs for non-European suppliers. China's MEE implements increasingly stringent emission standards for carbon black production facilities, reshaping regional supply availability for reinforcing fillers. Stakeholders must monitor evolving chemical substance restriction lists across multiple jurisdictions while evaluating bio-based feedstock pathways that satisfy both performance benchmarks and emerging sustainability procurement criteria from vehicle manufacturers.
Market Dynamics
Silica-reinforced green tire architectures are forcing a wholesale reformulation of additive portfolios, as rolling resistance regulations tighten and electric vehicle torque profiles demand new rubber compound performance envelopes.
Growth Catalysts
- EU REACH registration mandates:Full toxicity dossiers for antioxidant substances elevate compliance barriers that favor established technical compound specialists with regulatory infrastructure.
- China domestic tire production expansion:Passenger and commercial vehicle segments concentrate additive demand in manufacturing clusters serving both domestic consumption and export markets.
- Silica coupling agent chemistry:Advanced organosilane systems enable filler dispersion at lower loadings while maintaining wet traction coefficients for original equipment specifications.
Market Restraints
- Carbon black feedstock volatility:Crude oil and natural gas price swings transmit directly into reinforcing filler cost structures, compressing compounder margins during upstream spikes.
- MEA emission standards:China's Ministry of Ecology and Environment enforcement is shuttering marginal carbon black production capacity, constraining regional supply availability for tire manufacturers.
- Accelerator substitution limitations:Thiazole and sulfenamide chemistries retain performance advantages that bio-based alternatives have not yet replicated at commercial scale.
Strategic Opportunities
- India tire manufacturing corridors:Tamil Nadu and Gujarat states attract greenfield tire plants serving domestic automotive growth and Middle East export markets with localized additive supply.
- EU Green Deal procurement criteria:Vehicle manufacturer sustainability scorecards create preferential purchasing pathways for bio-based processing aids and recycled carbon black formulations.
- Digital compounding platforms:AI-driven formulation optimization converges with laboratory automation to compress development cycles for custom tire specifications.
Industry Challenges
- Rubber chemist talent scarcity:Formulation expertise in precipitated silica dispersion and coupling agent kinetics concentrates among retiring specialists with limited knowledge transfer infrastructure.
- Multi-jurisdiction substance restriction tracking:ECHA SVHC candidate list evolution, EPA TSCA Section 6 activity, and state-level chemical disclosure requirements demand dedicated regulatory intelligence functions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tire Additives Market |
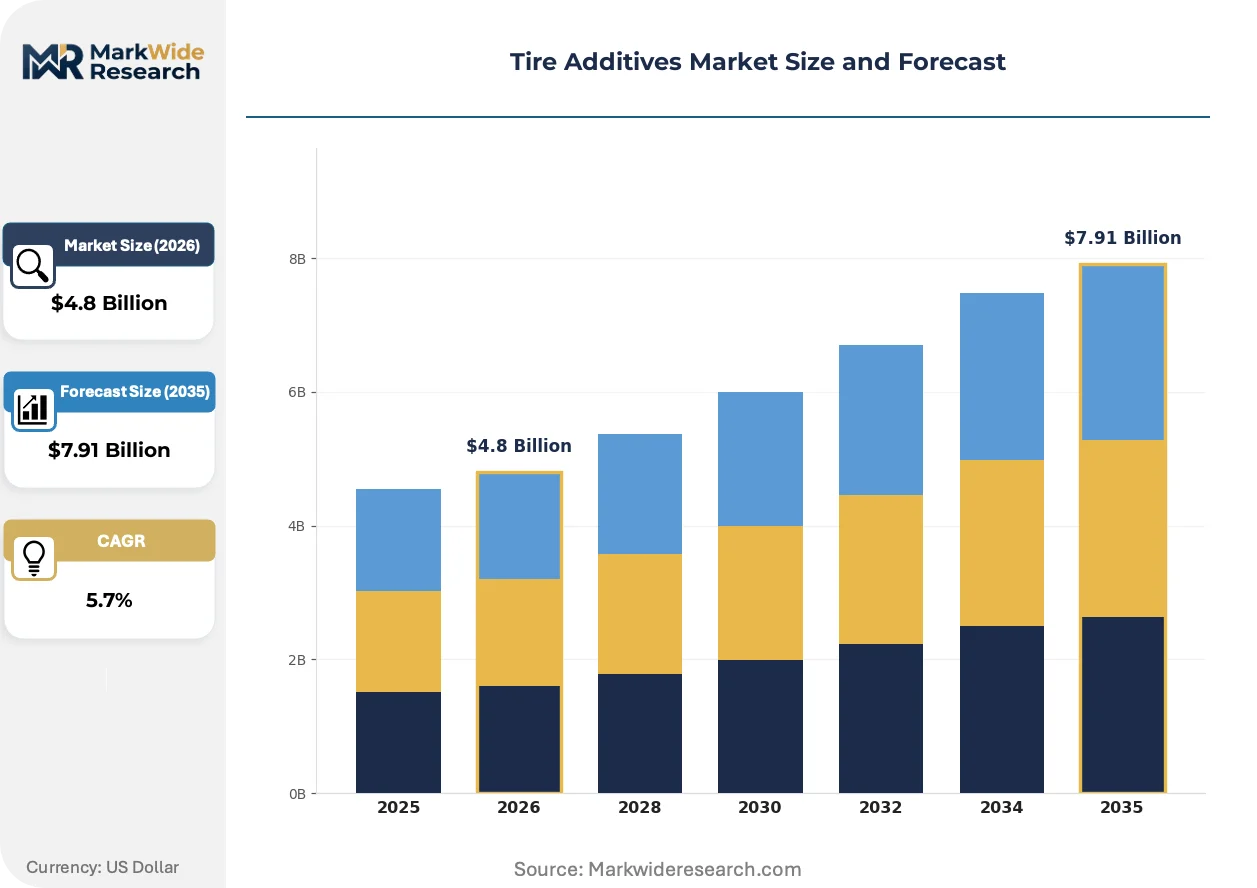
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antioxidants, Fillers, Processing Aids, Coupling Agents End Use Industry: Automotive, Aerospace, Construction, Agriculture Material Type: Natural Rubber, Synthetic Rubber, Carbon Black, Chemicals Functionality: Durability Enhancer, Heat Resistance, Grip Improvement, Performance Booster |
| Companies Covered | BASF SE, Lanxess, Eastman Chemical Company, Evonik Industries AG, Solvay S.A., Sinopec Corporation, Akzo Nobel N.V., Cabot Corporation, Phillips Carbon Black Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tire Additives Market Evolving Landscape
Active materials and process chemistry are converging to redefine performance benchmarks, with sustainability imperatives now embedded in specification development rather than treated as aftermarket positioning.
Functionalized silica surface treatments are miniaturizing particle agglomerate structures to enhance polymer-filler interaction at reduced loadings. Tier-one tire manufacturers specify these grades for electric vehicle platforms where reduced rolling resistance must coexist with high-torque durability requirements. The technology is miniaturizing the trade-off space between fuel efficiency and treadwear performance that previously constrained compound design.
EPA Clean Air Act enforcement on volatile organic compound emissions from tire manufacturing is eliminating solvent-based processing aids from domestic formulations. Waterborne system substitution requires reformulation of antiozonant and plasticizer packages to maintain scorch safety and extrusion throughput. Original equipment suppliers in the US market are qualifying these converted additive packages ahead of replacement tire channel adoption.
Fleet procurement departments now specify total cost of ownership metrics that incorporate tire life, fuel consumption, and retreadability into additive selection criteria. This displaces spot purchasing of commodity compounds in favor of multi-year supply agreements with technical service support. The shift concentrates additive volumes among compounders capable of predictive wear modeling and field performance validation.
Tire Additives Market Segmentation
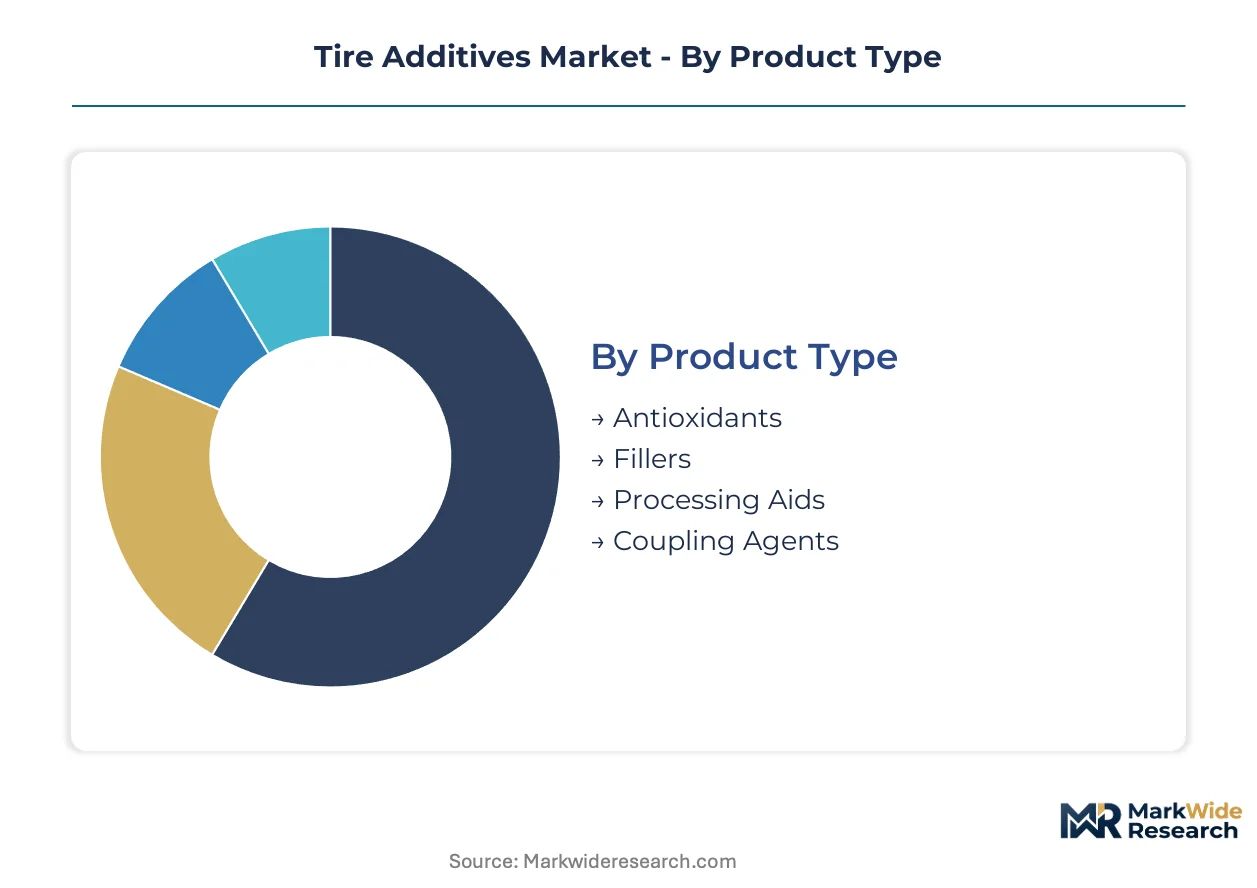
Tire additive formulations flow through distinct commercial channels based on specification complexity and end-use certification requirements. Segment boundaries increasingly blur as electric vehicle platforms demand multi-functional compounds that simultaneously address rolling resistance, durability, and wet traction.
Product Type:
Original equipment manufacturers route high-specification additives through qualified supplier programs with embedded technical service, while replacement tire compounders purchase commodity grades via distributor networks.
- Fillers:Carbon black and precipitated silica constitute the bulk volume in every tire formulation, with silica grades experiencing specification bifurcation between commodity precipitated variants and surface-functionalized grades for green tire architectures. Passenger vehicle OEMs in China are scaling purchases of high-dispersion silica grades that enable reduced rolling resistance without sacrificing treadwear performance.
- Coupling Agents:Organosilane chemistry creates covalent bonds between hydrophilic silica surfaces and hydrophobic rubber matrices, enabling lower filler loadings while maintaining mechanical properties. Electric vehicle torque profiles are accelerating adoption of advanced bifunctional silanes that address heat buildup in high-load applications.
- Antioxidants:Amine and phenolic stabilizers scavenge free radicals generated during thermal-oxidative aging, with para-phenylenediamine derivatives dominating heavy-duty tire specifications.
- Processing Aids:Peptizers, plasticizers, and homogenizing agents control viscosity and dispersion during mixing and extrusion operations.
By volume, Fillers leads. By growth pace, Coupling Agents is climbing the fastest.
End Use Industry:
Application-specific certification tiers create pricing stratification that separates aerospace and automotive qualification pathways from construction and agriculture commercial standards.
- Automotive:Passenger and commercial vehicle tires absorb the majority of additive volumes, with OEM specifications tightening around rolling resistance coefficients under EPA fuel economy regulations and EU CO2 emission standards. Chinese domestic tire production expansion is concentrating demand for silica-reinforced compounds serving both local vehicle assembly and export markets.
- Aerospace:Landing gear and high-speed tire assemblies command premium pricing tiers due to FAA and EASA certification requirements, with additive specifications traceable to individual polymer batches. The segment demands specialized heat-resistant formulations that maintain structural integrity through repeated thermal cycling during takeoff and landing sequences.
- Construction:Off-the-road tires for earthmoving equipment prioritize cut resistance and bead durability over rolling efficiency.
- Agriculture:Tractor and implement tires emphasize soil compaction reduction and flotation characteristics through specialized tread compound formulations.
Automotive generates the highest absolute consumption. Aerospace delivers the steepest margin expansion.
Material Type:
Feedstock origin determines regulatory compliance pathways, with bio-based alternatives gaining procurement preference under EU Green Deal sustainability scorecards.
- Synthetic Rubber:Solution-polymerized styrene-butadiene and butadiene rubber grades provide consistent molecular weight distribution for high-performance tire constructions. Styrene-butadiene copolymers dominate passenger tire tread formulations where glass transition temperature tuning enables wet grip optimization.
- Carbon Black:Furnace black grades from N100 through N700 series provide reinforcing properties scaled to tread, carcass, and sidewall applications. China's MEE emission enforcement is shuttering marginal production capacity and reshaping regional supply availability for tire manufacturers.
- Natural Rubber:Hevea brasiliensis latex and ribbed smoked sheet grades supply strain-crystallization properties essential for heavy-load tire components.
- Chemicals:Accelerator, antioxidant, and antiozonant substances complete the compounding matrix with specialized functional chemistries.
Synthetic Rubber anchors volume consumption. Carbon Black faces the most acute supply restructuring.
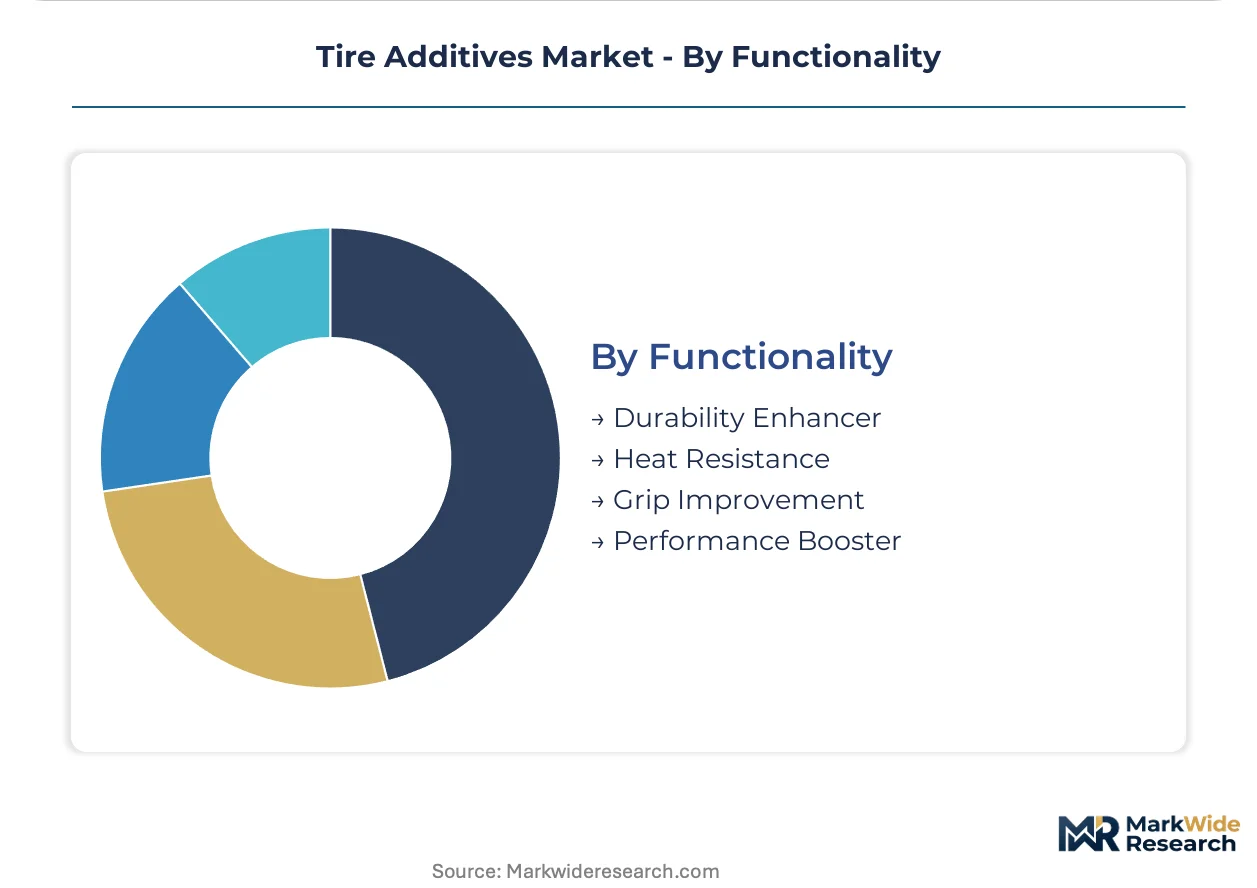
Functionality:
Performance targets now bundle multiple functional attributes into single additive packages rather than discrete component additions.
- Durability Enhancer:Antioxidant and antiozonant systems extend service life through free-radical scavenging and ozone attack mitigation, with paraphenylenediamine derivatives forming protective surface films on tire exteriors. Fleet procurement departments specify total cost of ownership metrics that incorporate predicted tire life and retreadability into additive selection criteria.
- Grip Improvement:Resin tackifiers and silica dispersion technologies enhance wet and dry traction coefficients through modified viscoelastic response in the tread contact patch. Electric vehicle regenerative braking systems place new demands on low-temperature grip retention that conventional compound architectures struggle to satisfy.
- Heat Resistance:Thermal stabilizers and specialized curing systems maintain mechanical properties under sustained high-temperature operation.
- Performance Booster:Multi-functional additive packages combine rolling resistance reduction, wear resistance, and handling response in integrated formulations.
Durability Enhancer captures the largest installed base. Grip Improvement is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China exports finished tires while importing specialized additive chemistries, creating asymmetric trade flows that reshape regional supply chains. Germany and the United States balance domestic compounding capacity with selective imports of high-performance silica grades. India's additive demand is accelerating faster than local production capacity, drawing cross-border investment into manufacturing corridors.
China
Domestic tire production expansion for electric vehicles and commercial fleets is concentrating additive demand in Shandong and Jiangsu manufacturing clusters. MEE emission enforcement is shuttering marginal carbon black capacity, tightening supply availability for reinforcing fillers. Qingdao and Yangzhou chemical parks are attracting greenfield organosilane plants to serve silica-reinforced green tire architectures.
Germany
Automotive OEM specifications for rolling resistance and wet traction are driving specialized coupling agent demand from Continental and Michelin supply chains. ECHA REACH registration mandates elevate compliance barriers for antioxidant and accelerator substances imported from non-European suppliers. The Cologne-Leverkusen chemical corridor anchors backward integration into rubber chemical precursors.
United States
EPA Clean Air Act enforcement on volatile organic compound emissions is eliminating solvent-based processing aids from domestic tire formulations. Fleet procurement departments specify total cost of ownership metrics that incorporate tire life and retreadability into additive selection criteria. Gulf Coast petrochemical complexes supply synthetic rubber feedstocks to Southeast tire manufacturing plants.
India
Tamil Nadu and Gujarat states attract greenfield tire plants serving domestic automotive growth and Middle East export markets with localized additive supply. BIS certification requirements for tire safety standards are tightening formulation documentation for imported chemical substances. Chennai and Ahmedabad industrial corridors concentrate demand for precipitated silica and carbon black reinforcing fillers.
Japan
Premium tire exports to Southeast Asian and North American markets sustain demand for high-dispersion silica and advanced coupling agent systems. METI energy efficiency regulations for vehicle tires are accelerating adoption of low-rolling-resistance compound architectures. Osaka-Kobe chemical manufacturing zones maintain specialized production of functionalized rubber additives.
Tire Additives Market Competitive Landscape
Concentration sits with integrated chemical conglomerates that control precursor supply chains and maintain regulatory compliance infrastructure across multiple jurisdictions. The market structure tiers between commodity carbon black suppliers and technical compound specialists serving OEM qualification programs. Three archetypes dominate: backward-integrated polymer researchers, specialized rubber chemical manufacturers, and diversified materials conglomerates. Capacity expansion in Asian manufacturing corridors and strategic partnerships for bio-based feedstock development represent the dominant competitive moves.
Among European-based chemical specialists, BASF SE and Lanxess occupy positions within the integrated research tier, exemplifying archetypes that combine polymer science capabilities with regulatory dossier management. Eastman Chemical Company represents the specialized resin technology vector, anchoring a position in durability-enhancing additive formulations. These three entities illustrate how geographic origin and corporate structure correlate with strategic positioning in coupling agent and processing aid segments.
| Leading Market Players |
|---|
| BASF SE |
| Lanxess |
| Eastman Chemical Company |
| Evonik Industries AG |
| Solvay S.A. |
| Sinopec Corporation |
| Akzo Nobel N.V. |
| Cabot Corporation |
| Phillips Carbon Black Limited |
| Others |
Value Network & Pricing Analysis
Carbon black furnace capacity utilization above 85 percent in Shandong and Jiangsu provinces creates asymmetric pricing power for reinforcing filler suppliers serving domestic tire manufacturers. Scale concentration among state-owned petrochemical complexes establishes price floors that commodity compounders cannot undercut without sacrificing quality consistency under China's MEE emission enforcement.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that lock in silica and coupling agent volumes across multi-year frameworks. Pricing stratifies across premium, standard, and economy tiers based on certification grade and volume scale, with aerospace-qualified additives commanding substantial premiums over replacement tire commodity grades. Cost compression in carbon black feedstocks is intensifying because crude oil volatility transmits directly into reinforcing filler cost structures. Replacement tire compounders exhibit the highest price sensitivity, while electric vehicle OEMs prioritize performance specifications over unit cost.
Supply Chain Analysis
Port congestion on Shanghai-Ningbo trade lanes elevates inbound logistics costs for European and North American chemical suppliers serving Chinese tire manufacturing clusters. Raw material sourcing draws from China, Germany, and the United States for specialized organosilane coupling agents, carbon black feedstocks, and synthetic rubber precursors. Single-source vulnerability concentrates in high-dispersion silica grades where functionalized surface treatment technology remains tethered to select chemical parks. Distribution runs through qualified supplier programs with embedded technical service for OEM channels, while commodity grades flow via distributor networks to replacement tire compounders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as electric vehicle production scales drive specialized silica-reinforced compound adoption beyond historical penetration rates in internal combustion platforms.
For Market Incumbents: Fortify backward integration into rubber chemical precursors to secure feedstock reliability against carbon black supply restructuring under MEE enforcement. Deepen technical service capabilities in silica dispersion optimization to defend against emerging specialty chemical entrants targeting green tire architectures. Prioritize regulatory dossier infrastructure investment to maintain REACH compliance advantages over non-European suppliers. For New Entrants and Emerging Players: Anchor in India's Tamil Nadu and Gujarat tire manufacturing corridors where localized additive supply lags behind greenfield plant commissioning. Target bio-based processing aid development as the most penetrable segment under EU Green Deal procurement criteria. Pursue joint formulation qualification programs with mid-size tire manufacturers seeking alternatives to incumbent supplier concentration. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors compound specialists with captive coupling agent chemistry and established OEM qualification pathways. Long-term viability hinges on regulatory compliance infrastructure that sustains market access across REACH, EPA, and evolving chemical substance restriction lists. Watch silica coupling agent patent expiration schedules as inflection indicators for generic competition entry.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rubber Chemical Precursors | Lanxess secures feedstock reliability across European and Asian manufacturing sites against supply volatility. |
| Green Manufacturing Transition | Bio-based processing aids satisfy EU Green Deal sustainability scorecards from vehicle manufacturers. |
| Long-term Supply Agreement | Fleet procurement departments lock in multi-year additive volumes with predictive wear modeling support. |
| Joint Venture | Qingdao and Yangzhou chemical parks attract greenfield organosilane plants for silica-reinforced architectures. |
| Capacity Expansion | Shandong manufacturing clusters scale precipitated silica output for domestic electric vehicle tire production. |
Research Methodology
The analysis maps filler grades, coupling agent chemistries, antioxidant systems, and processing aid formulations, each validated through procurement directors at tire manufacturers, technical R&D leads at chemical suppliers, and regulatory affairs specialists. Primary interviews with plant managers at carbon black facilities, distribution channel partners, and OEM platform engineers combined with secondary validation from customs/trade data, ACC/Cefic industry reports, SEC 10-K filings, and EPA enforcement records. Bottom-up volume modeling and top-down value reconciliation triangulate across these sources.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include product type tier, end-use industry certification level, material feedstock origin, and regional production hub. CAGRs were derived from fitted growth curves applied to base-year estimates, incorporating electric vehicle penetration trajectories, rolling resistance regulation tightening schedules, and carbon black capacity closure announcements as industry-specific forecast inputs.
Material uncertainties — feedstock price spikes, unscheduled regulatory substance restrictions, and accelerated bio-based substitute commercialization — sit outside the modeled envelope. Forecasts reflect assumptions about continued OEM qualification pathway stability and emission enforcement continuity. Recalibration cycles align with material shifts in electric vehicle adoption rates and chemical substance restriction list updates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Paint Additives Market
Additives
Anti-Settling Agents Market
Additives
Asia Pacific Silage Additives Market
Additives
Global Chelated Trace Minerals Market
Additives
Potassium Nitrate Market
Additives
Global PVC Stabilizer Market
Additives
Global Rheology Modification Coating Additives Market
Additives
Antiblock Agents Market
Additives
North America Citric Acid Market
Additives
Electrolyte Additives for Lithium Ion Battery Market
Additives
Global Rheology Modifiers Market
Additives
Grease Additives Market
Additives
Fuel Additives Market
Additives
Citric Acid Anhydrous Market
Additives
Refining Additives Market
Additives
Supplemental Coolant Additives Market