
 Amino Acids Premixes Market | 2026-2036
Amino Acids Premixes Market Size, Share, and Industry Trends Forecast 2026-2036
Amino Acids Premixes Market Outlook
Pharmaceutical-grade purity specifications is reorganizing competitive dynamics across the amino acids premixes value chain. DSM-Firmenich leverages its integrated biotechnology platforms to sustain leadership in fermentation-derived essential amino acids. Evonik Industries AG anchors its position through captive production of MetAMINO methionine with backward integration into petrochemical precursors. Cargill Incorporated competes via its global grain origination network, which secures carbohydrate feedstock cost advantages for microbial fermentation.
Amino acids premixes constitute homogeneous blends of crystalline or spray-dried essential and non-essential amino acids, typically standardized to 98.5% minimum assay purity with defined particle size distribution for uniform dispersion in complete feeds or pharmaceutical excipients. Lysine and methionine dominate volume flows in animal feed applications, where structural oversupply in Chinese lysine capacity has compressed spot margins while contract volumes sustain integrated producers. Nutraceutical and pharmaceutical applications command premium pricing due to USP-grade certification requirements and batch-level traceability mandates that smaller compounders cannot satisfy.
The FDA's Center for Veterinary Medicine enforces medicated feed mill licensing that elevates compliance barriers for premix suppliers serving US livestock operations, while the EU Green Deal's Farm to Fork strategy mandates measurable livestock emission reductions that amino acid balancing directly addresses. China's Ministry of Agriculture and Rural Affairs maintains its feed additive import registration system, creating asymmetric market access that favors domestic champions with established regulatory dossiers. Stakeholders must monitor how carbon border adjustment mechanisms reshape the cost calculus of imported versus regionally manufactured premixes.
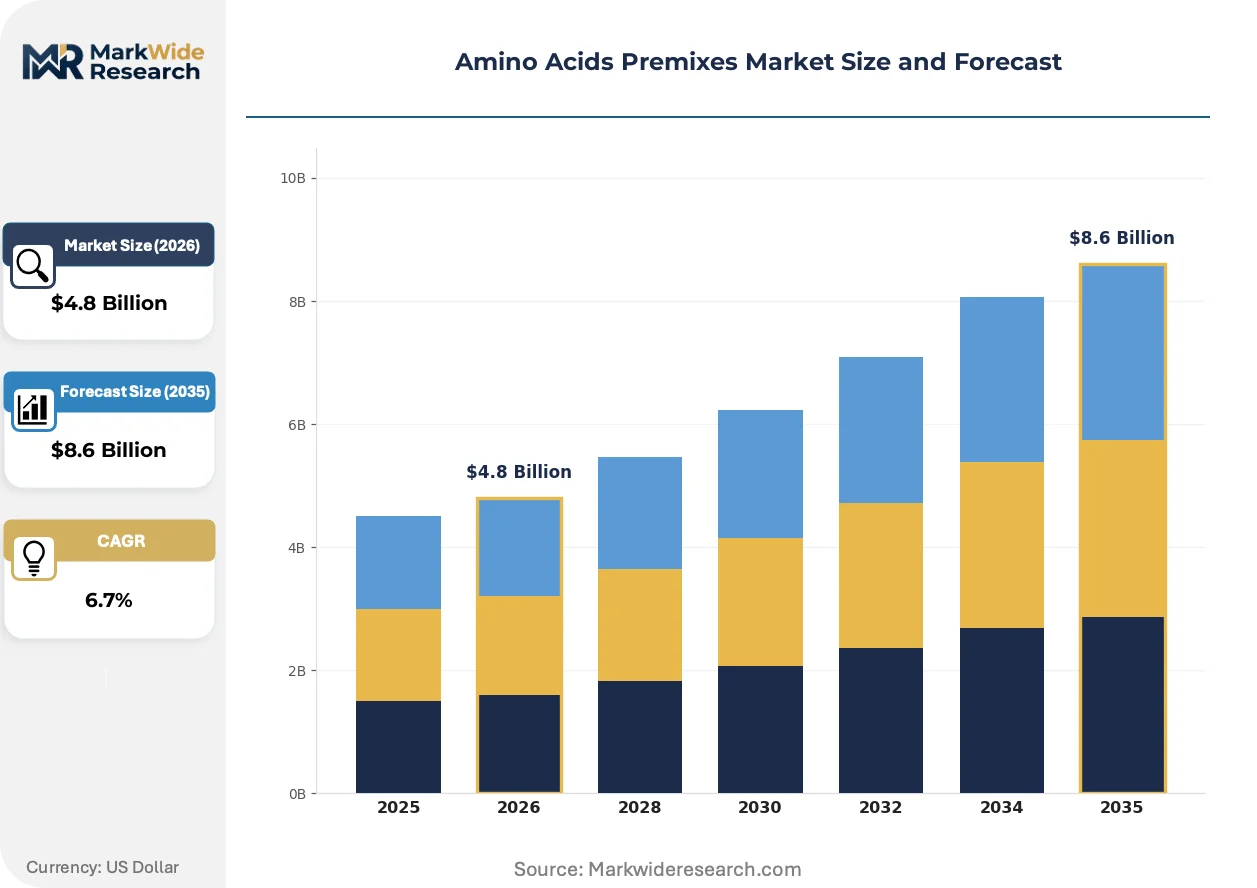
Market Dynamics
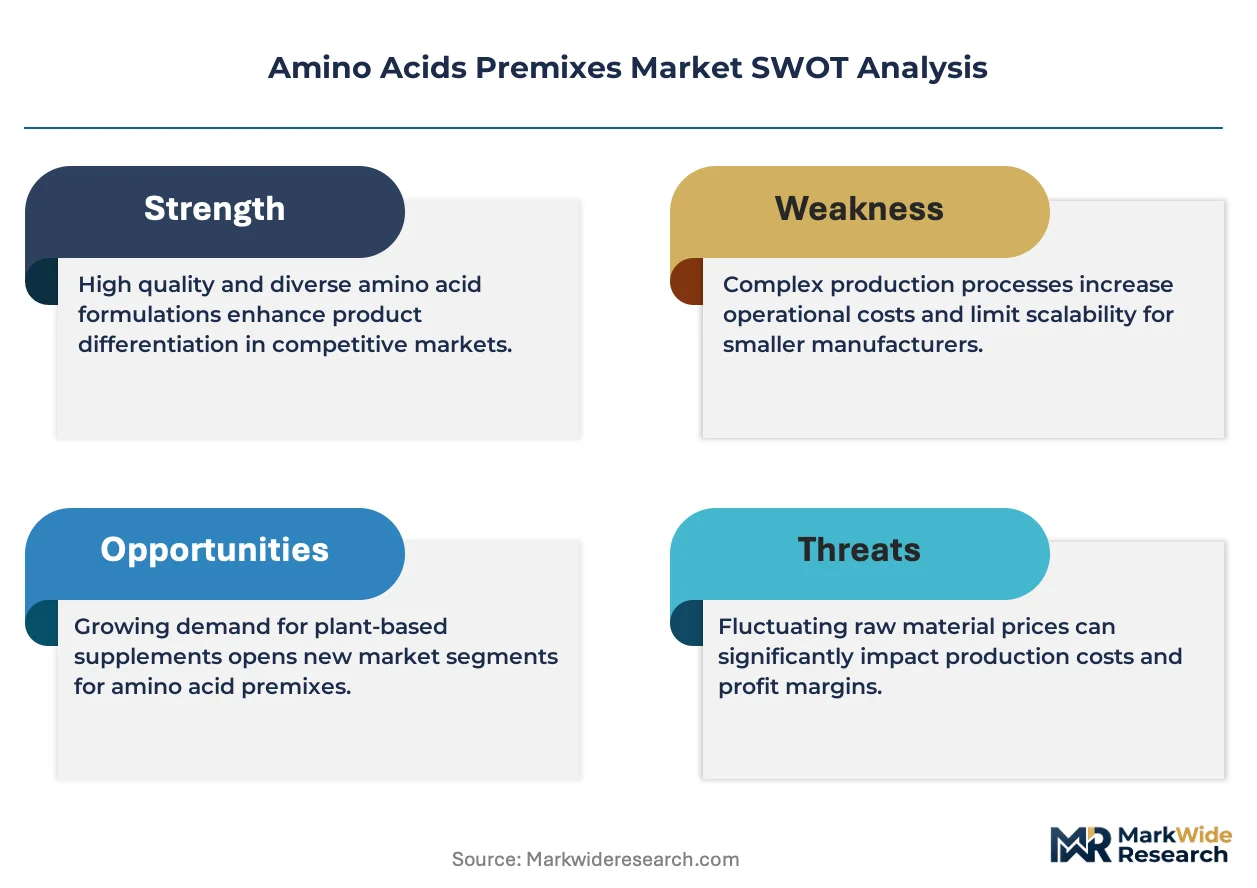
Structural oversupply in Chinese lysine capacity is compressing spot margins while contract volumes sustain integrated producers with captive fermentation infrastructure, forcing non-integrated compounders toward pharmaceutical-grade certifications to escape commodity pricing traps.
Growth Catalysts
- EU Green Deal Farm to Fork strategy:Mandatory livestock emission reductions are accelerating amino acid balancing adoption as a measurable compliance pathway for industrial pork and poultry operations.
- Precision livestock farming:Sensor-integrated feed systems are pulling customized premix formulations into large-scale operations to optimize feed conversion ratios and nitrogen excretion metrics.
- FDA Center for Veterinary Medicine medicated feed mill licensing:Elevated compliance barriers are filtering smaller suppliers and concentrating procurement among certified premix providers serving US livestock operations.
Market Restraints
- Feedstock cost volatility:Carbohydrate feedstock prices tied to grain origination networks create margin instability for microbial fermentation-dependent producers.
- Chinese lysine capacity concentration:Structural oversupply in domestic fermentation capacity limits pricing power for non-integrated premix compounders sourcing spot volumes.
- Antibiotic growth promoter substitution ceiling:Residual veterinary drug residue regulations have already captured low-hanging conversion demand, narrowing the remaining addressable base for amino acid displacement.
Strategic Opportunities
- Pharmaceutical excipient certification:USP-grade batch-level traceability mandates create premium pricing tiers that smaller compounders cannot satisfy, opening margin expansion for qualified suppliers.
- Carbon border adjustment mechanism positioning:EU carbon border adjustments are reshaping cost calculus between imported and regionally manufactured premixes, favoring European production investments.
- Nutraceutical application expansion:Human dietary supplement formulations are absorbing pharmaceutical-grade lysine and methionine volumes at price multiples exceeding feed applications.
Industry Challenges
- Fermentation process engineering talent scarcity:Specialized bioprocess optimization expertise for 98.5% purity crystalline production concentrates among legacy biotechnology platforms.
- Dual registration burden:China's Ministry of Agriculture and Rural Affairs feed additive import registration system requires parallel dossier maintenance for domestic and export market access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Amino Acids Premixes Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lysine, Methionine, Threonine, Tryptophan Application: Animal Feed, Nutraceuticals, Pharmaceuticals, Food & Beverage End User: Agriculture, Healthcare, Food Industry, Dietary Supplements Packaging Type: Bags, Drums, Sachets, Bulk |
| Companies Covered | Cargill Incorporated, Archer Daniels Midland Company, DSM-Firmenich, Evonik Industries AG, BASF SE, Nutreco N.V., Ajinomoto Co., Inc., Alltech Inc., Kemin Industries Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Amino Acids Premixes Market Strategic Shifts
Biotechnology platforms are actively reorganizing competitive dynamics across the amino acids premixes value chain, with fermentation-derived production methods, regulatory compliance automation, and precision nutrition integration emerging as the dominant vectors of change.
Spray-dried crystalline amino acid formulations are decomposing the traditional distinction between feed-grade and pharmaceutical-grade supply chains. Large-scale pork operations in Denmark and the Netherlands are adopting these unified-format premixes at accelerating rates. This convergence is decomposing the historical pricing premiums that separated commodity lysine from excipient-grade material.
REACH registration requirements for fermentation-derived amino acid intermediates are tightening substance data documentation obligations for EU market access. Industrial compounders must now maintain extended safety dossiers covering petrochemical precursor chains. German and Dutch premix manufacturers are responding by consolidating backward integration into captive precursor production to control registration continuity.
Buyer concentration among industrialized livestock operations is compressing procurement cycles and unbundling technical advisory services from premix supply contracts. Large integrators in China's Shandong and Henan provinces are negotiating direct fermentation supply agreements that displace traditional distribution intermediaries. This disintermediation is most visible in contract methionine volumes where captive supply agreements now exceed spot market participation.
Amino Acids Premixes Market Segmentation
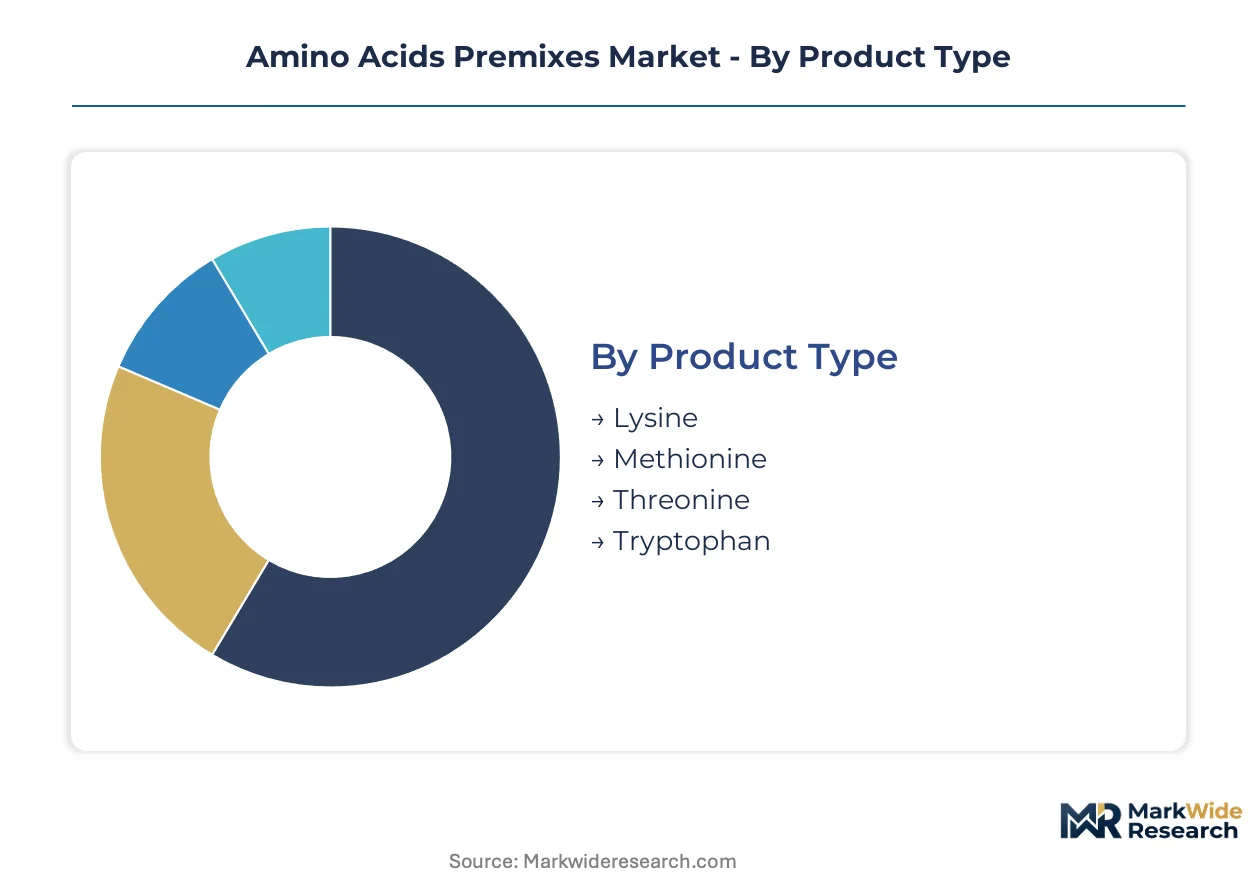
Premix segmentation determines procurement economics and margin architecture across the value chain. Product purity grades and application-specific certifications create divergent pricing tiers that reshape supplier positioning.
Product Type:
Substitution pressure from alternative protein sources and synthetic biology routes varies sharply across amino acid categories, with fermentation-derived lysine facing the most acute oversupply displacement.
- Lysine:Crystalline L-lysine monohydrochloride standardized to 98.5% assay purity dominates volume flows in swine and poultry formulations. Chinese fermentation capacity concentration has collapsed spot margins, forcing integrated producers toward long-term contract structures with Shandong and Henan integrators.
- Methionine:DL-methionine and hydroxy analog formulations anchor poultry feed conversion optimization, with petrochemical precursor integration determining cost competitiveness. Evonik's captive acrolein supply secures margin stability against volatile propylene feedstock swings.
- Threonine:Essential for intestinal mucin synthesis in young livestock, threonine premixes command modest premiums over lysine in starter diet formulations.
- Tryptophan:Limited fermentation capacity and complex indole precursor chemistry sustain higher pricing tiers for this serotonin pathway precursor in swine stress reduction applications.
Lysine retains volume leadership; methionine holds the steepest expansion curve.
Application:
Cost tier stratification separates commodity feed-grade volumes from pharmaceutical-certified premiums, with certification burden determining accessible market tiers.
- Animal Feed:Standardized crystalline blends for swine, poultry, and aquaculture operations constitute the dominant volume channel. EU Green Deal emission mandates are accelerating precision amino acid balancing in Danish and Dutch industrial pork operations.
- Nutraceuticals:USP-grade lysine and methionine for human dietary supplements absorb production volumes at substantial price multiples over feed applications, with batch-level traceability dossiers filtering smaller compounders.
- Pharmaceuticals:Excipient-grade specifications for parenteral nutrition and infusion therapies demand endotoxin-controlled manufacturing environments that only integrated biotechnology platforms sustain.
- Food & Beverage:Fortification applications in processed foods and sports nutrition products require FSSAI, FDA, or EFSA food additive approvals with parallel safety documentation.
Animal Feed retains volume leadership; Pharmaceuticals holds the steepest expansion curve.
End User:
Customer type concentration is reshaping distribution economics, with large integrators disintermediating traditional compounders through direct fermentation supply agreements.
- Agriculture:Industrialized livestock operations in China, Brazil, and the United States negotiate direct premix procurement with volume-tiered pricing. Precision farming sensor integration is pulling customized formulation services into core supply contracts.
- Healthcare:Hospital nutrition services and clinical dietetics drive pharmaceutical-grade lysine demand for metabolic disorder management and post-surgical recovery protocols.
- Food Industry:Processed meat and plant-based protein manufacturers utilize amino acid premixes for flavor modulation and nutritional fortification compliance.
- Dietary Supplements:Sports nutrition and wellness brands source pharmaceutical-grade methionine and tryptophan for capsule and powder formulations targeting sleep and recovery positioning.
Agriculture retains volume leadership; Dietary Supplements holds the steepest expansion curve.
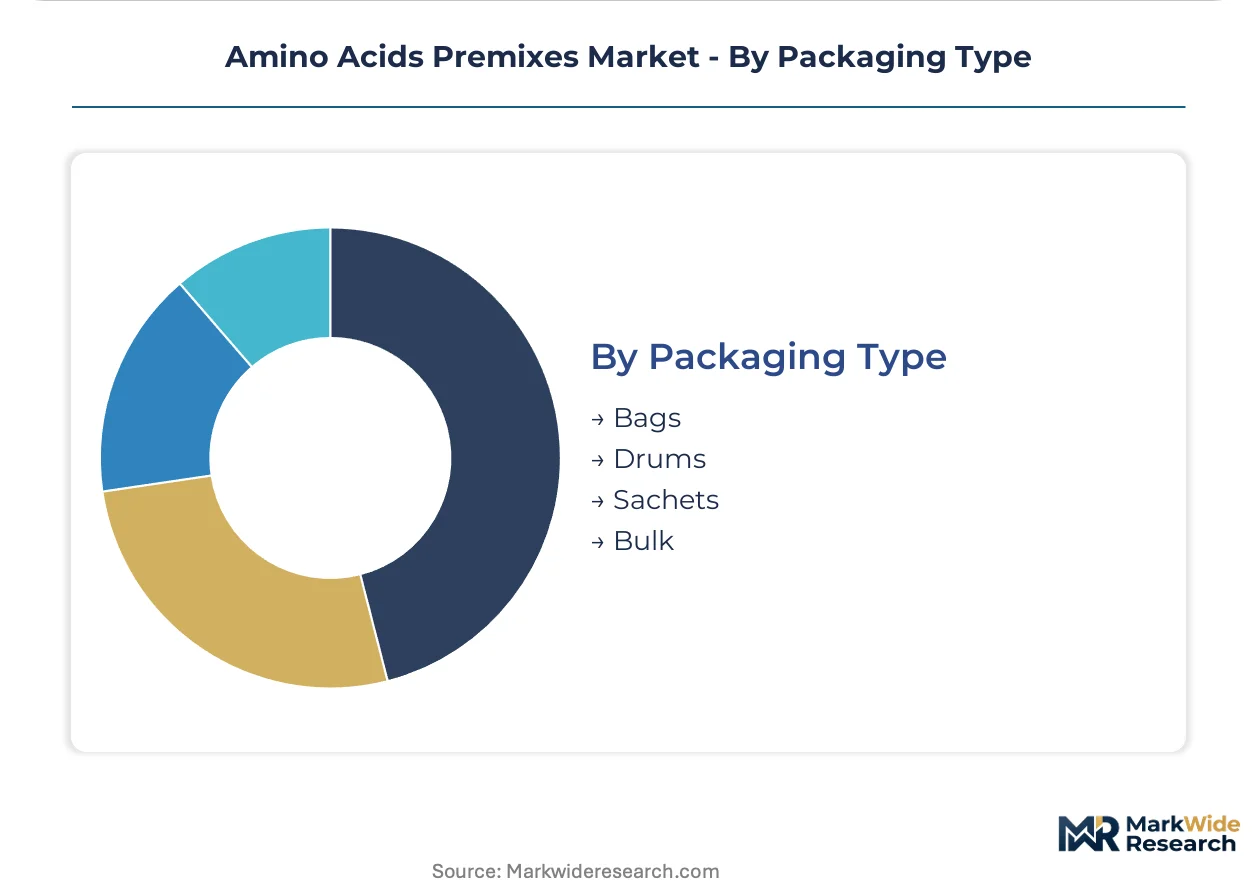
Packaging Type:
Supply chain configuration directly determines packaging economics, with bulk formats dominating integrated operations and unit-dose formats serving fragmented downstream channels.
- Bags:Multi-layer laminated 25kg sacks with moisture barriers constitute the standard for regional distribution to mid-scale compounders and feed mills.
- Drums:Fiber or steel drums with nitrogen flushing protect hygroscopic crystalline amino acids during ocean freight and extended storage.
- Sachets:Unit-dose foil pouches serve pharmaceutical and nutraceutical repackaging operations requiring precise aliquot dispensing.
- Bulk:Pneumatic discharge tanker and flexible intermediate bulk container formats minimize handling costs for large integrators with captive blending capacity.
Bulk retains volume leadership; Sachets holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in amino acids premixes reveal stark regional asymmetries. China maintains net-export dominance in fermentation-derived lysine, while the United States and Germany absorb premium volumes for pharmaceutical-grade applications. Trade friction around carbon border adjustments is redirecting regional sourcing strategies.
China
Industrialized pork operations in Shandong and Henan provinces drive domestic lysine consumption at unprecedented scale. The Ministry of Agriculture and Rural Affairs enforces feed additive import registrations that shield domestic champions from foreign competition. Fermentation capacity concentration in Jilin and Heilongjiang provinces has collapsed spot pricing, forcing producers toward long-term contract structures with provincial integrators.
United States
Precision livestock farming adoption across Iowa and North Carolina operations pulls customized premix formulations into core procurement contracts. FDA Center for Veterinary Medicine medicated feed mill licensing elevates compliance barriers, filtering smaller suppliers from the certified vendor pool. The Corn Belt's grain origination network secures carbohydrate feedstock cost advantages for domestic microbial fermentation.
Germany
EU Green Deal Farm to Fork emission mandates accelerate amino acid balancing in Lower Saxony and North Rhine-Westphalia pork operations. REACH registration requirements for fermentation-derived intermediates tighten substance data documentation obligations. Bavarian premix manufacturers consolidate backward integration into captive precursor production to control registration continuity.
Brazil
Soybean-fed poultry integrators in São Paulo and Paraná states negotiate direct premix procurement with volume-tiered pricing structures. ANVISA veterinary drug residue regulations push feed producers toward amino acid-based nutritional solutions over antibiotic growth promoters. The Central-West agricultural frontier absorbs expanding premix volumes as industrialized operations displace traditional farming.
India
Dairy and poultry cooperatives in Maharashtra and Gujarat states scale premix adoption to meet domestic protein targets. FSSAI food additive approvals with parallel safety documentation requirements filter smaller compounders from pharmaceutical-grade supply chains. The Punjab-Haryana dairy belt concentrates demand for rumen-protected amino acid formulations in high-yield cattle operations.
Amino Acids Premixes Market Competitive Environment
Listed leaders compete with private specialists across fermentation capacity and regulatory certification dimensions. The vendor base organizes around three tiers: integrated biotechnology platforms with captive petrochemical precursor supply, global grain traders leveraging origination networks for feedstock cost control, and regional compounders surviving on pharmaceutical-grade niche certifications. Strategic moves concentrate on M&A for regulatory dossier accumulation and capacity expansion in carbon-adjusted trade zones.
Within the integrated biotechnology tier, DSM-Firmenich and Evonik Industries AG exemplify archetypes combining fermentation expertise with backward integration into precursor chemistry. Cargill Incorporated anchors the agricultural-commodity vector, leveraging global grain origination networks that secure carbohydrate feedstock cost advantages. These three entities represent distinct competitive positions: biotechnology-led purity control, petrochemical-captive supply security, and agricultural-feedstock scale economics.
| Leading Market Players |
|---|
| Cargill Incorporated |
| Archer Daniels Midland Company |
| DSM-Firmenich |
| Evonik Industries AG |
| BASF SE |
| Nutreco N.V. |
| Ajinomoto Co., Inc. |
| Alltech Inc. |
| Kemin Industries Inc. |
| Others |
Value Chain & Pricing Dynamics
Fermentation capacity utilization rates above 85% in Jilin and Heilongjiang provinces have compressed spot margins for Chinese lysine producers while sustaining contract premiums for integrated operations with captive carbohydrate feedstock supply. This scale asymmetry creates divergent price floors: non-integrated compounders face commodity pricing traps, while backward-integrated platforms preserve margin architecture through long-term offtake structures with Shandong and Henan integrators.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake pricing across the amino acids premixes value chain. Three-tier pricing structure across pharmaceutical-grade, feed-grade, and excipient-grade certifications separates premium USP-grade batches from standard crystalline formulations. Cost compression in feed-grade lysine is intensifying because Chinese fermentation capacity concentration has eliminated spot market pricing power. Small regional compounders exhibit highest price sensitivity, while pharmaceutical-certified suppliers serving parenteral nutrition applications maintain lowest sensitivity due to irreplaceable endotoxin-controlled manufacturing requirements.
Supply Chain Analysis
Strategic stockpile preferences dominate inventory strategy among European pharmaceutical premix buyers confronting REACH registration continuity risks, while North American feed operations favor just-in-time delivery synchronized with corn harvest cycles. Supply concentrates in China, Germany, and the United States for fermentation-derived crystalline production. Raw material dependencies center on carbohydrate feedstocks from grain origination networks, petrochemical precursors for methionine synthesis, and indole chemistry for tryptophan fermentation. Single-source vulnerability in Chinese lysine capacity creates structural exposure to export license disruptions. Distribution runs through direct fermentation supply agreements that displace traditional distribution intermediaries for large integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Formulation advisory services and batch-level traceability documentation represent expanding recurring-revenue layers that compound faster than commodity premix volumes, creating service-attach economics for qualified suppliers.
For Market Incumbents: Consolidate regulatory dossier portfolios through targeted acquisition of regional compounders holding pharmaceutical-grade certifications in carbon-adjusted trade zones. Captive precursor production investments in Bavaria and Lower Saxony defend margin position against REACH registration disruption risks from petrochemical supply chain volatility. Backward integration into carbohydrate feedstock origination secures cost stability against grain price swings. For New Entrants and Emerging Players: Customized precision nutrition formulation services for sensor-integrated livestock operations in Iowa and North Carolina represent the most penetrable white-space target, as incumbent biotechnology platforms under-serve technical advisory integration. Nutraceutical-grade methionine for human dietary supplements offers secondary entry path at price multiples exceeding feed applications. Go-to-market execution should emphasize direct technical partnership models with large integrators rather than distribution channel penetration. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated biotechnology platforms with captive fermentation infrastructure and established pharmaceutical excipient certifications, positioning these archetypes for superior cash flow quality across the analysis window. Acquisition targets should prioritize mid-scale compounders holding parallel FDA Center for Veterinary Medicine and EU regulatory dossiers. Monitor carbon border adjustment mechanism implementation timelines as inflection indicator for regional production investment viability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Petrochemical Precursors | Evonik's captive acrolein supply secures margin stability against propylene volatility. |
| Pharmaceutical Excipient Certification Investment | USP-grade batch traceability creates premium pricing tiers inaccessible to commodity compounders. |
| Precision Livestock Farming Partnership | Sensor-integrated feed systems pull customized formulations into core procurement contracts. |
| Carbon-Adjusted Regional Capacity Expansion | EU carbon border adjustments favor European production investments over imported volumes. |
| Long-term Contract Structuring with Provincial Integrators | Shandong and Henan direct supply agreements displace spot market participation. |
Study Parameters
Initial hypotheses were tested against primary input from fermentation plant managers, feed mill procurement leads, regulatory affairs directors at premix manufacturers, and veterinary nutrition specialists at large livestock integrators and refined through secondary validation against customs trade data, SEC 10-K filings, ECHA REACH registration databases, and Ministry of Agriculture feed additive import records. Bottom-up volume triangulation across product-grade segments was cross-checked against top-down value estimates derived from regional production capacity assessments.
Variance decomposition across the projection horizon isolates volume drivers from price-mix effects within each segmentation dimension: amino acid type, application certification tier, end-user concentration level, and regional regulatory cluster. CAGRs were derived from modeled segment trajectories incorporating capacity utilization rates, contract renewal patterns, and substitution elasticity estimates for antibiotic growth promoter displacement. Fermentation yield improvements and carbon border adjustment cost pass-through assumptions inform margin evolution projections.
Forecasts assume regulatory continuity in FDA Center for Veterinary Medicine licensing, EU Green Deal Farm to Fork emission mandates, and China's Ministry of Agriculture feed additive registration system; material policy shifts in veterinary drug residue thresholds or carbon border adjustment scope would require re-modeling. Practitioners should keep alternative scenarios live as REACH registration documentation obligations and precision livestock technology adoption curves evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Alginic Acid Market
Additives
Epoxy Type Stabilizers Market
Additives
United Kingdom Feed Additives Market
Additives
Butyrate Additives Market
Additives
Ballast Tank Corrosion Inhibitors Market
Additives
South Africa Acidulants Market
Additives
Glacial Acetic Acid Market
Additives
Plastic Fillers Market
Additives
Sodium Diacetate Market
Additives
Pearlizers Market
Additives
Disodium Inosinate Market
Additives
Asia-Pacific Fuel Additives Market
Additives
Crystal Growth Modifier Market
Additives
North America Paints and Coatings Additives Market
Additives
Inorganic Rheology Modifiers Market
Additives
Organic Friction Modifier Additives Market