
 Foundry Additives Market | 2026-2036
Foundry Additives Market Size, Share, and Industry Trends Forecast 2026-2036
Foundry Additives Market Foresight
The price-performance gap between premium synthetic binders and commodity-grade bentonite is hardening as automotive foundries enforce stricter surface-finish specifications. ASK Chemicals leverages its phenolic resin expertise to dominate high-pressure molding lines for engine block production. Elkem ASA anchors silicon-based deoxidizer supply to European steel foundries through captive ferroalloy sourcing. Ferroglobe competes on scale in metallurgical-grade silicon for gray iron applications across Mediterranean markets.
Foundry additives are chemical or mineral formulations—typically comprising organic binders (furan, phenolic, or urethane resins at 1.5–3.0% by weight), inorganic refractory coatings (zircon- or alumina-based slurries with 60–75% solids content), and deoxidizing agents (aluminum, silicon, or calcium ferroalloys)—engineered to modify mold integrity, metal fluidity, and final casting surface quality in ferrous and non-ferrous foundry processes. Binder systems command the deepest margin pools where proprietary low-emission formulations differentiate suppliers, while refractory coatings face volume pressure from ceramic shell investment casting growth in aerospace turbine blade production. Anti-foaming agents remain a mature, price-tight category with limited innovation headroom.
EPA air toxics standards for metal casting MACT compliance and REACH restrictions on formaldehyde-based resin precursors are elevating demand for water-glass and alkali-activated inorganic binder alternatives. China's MEE enforcement of foundry sector emission limits is accelerating regional supplier consolidation around cleaner synthesis routes. Stakeholders must monitor binder technology substitution curves and regulatory phase-in timelines to calibrate R&D allocation between organic and inorganic platform investments.
Market Dynamics
Automotive OEMs enforcing tighter dimensional tolerances on engine block castings are compressing the acceptable performance gap between premium synthetic binders and commodity bentonite, forcing foundries to upgrade additive specifications across high-pressure molding lines.
Growth Catalysts
- REACH Phase-Out of Formaldehyde-Based Resins:European ECHA restrictions on phenolic resin precursors are accelerating foundry migration to water-glass and alkali-activated inorganic binders, creating replacement demand across German and Italian automotive casting clusters.
- China's Dual Carbon Goals:MEE enforcement of foundry sector emission limits is consolidating consumption around cleaner synthesis routes in Hebei and Shandong province steel-casting complexes.
- Aerospace Investment Casting Expansion:Ceramic shell turbine blade production is driving volume demand for zircon-based refractory coatings with elevated solids content specifications.
Market Restraints
- Ferroalloy Price Volatility:Silicon and aluminum deoxidizer input costs fluctuate with ferroalloy smelter energy tariffs, compressing margin pools for gray iron foundries in Mediterranean markets.
- Binder Chemistry Lock-In:Existing furan and phenolic resin production infrastructure represents sunk capital that retards adoption of inorganic alternatives despite regulatory pressure.
- Refractory Coating Substitution:Ceramic shell investment casting growth in aerospace applications is displacing traditional zircon slurry volumes in select high-value segments.
Strategic Opportunities
- India's PLI-Linked Foundry Modernization:Production-linked incentive schemes for automotive component manufacturing are creating additive upgrade cycles in Tamil Nadu and Gujarat casting clusters.
- Water-Glass Binder Formulation Gaps:Proprietary low-emission inorganic binder platforms remain underdeveloped relative to organic resin performance benchmarks, opening white space for R&D investment.
- Digital Mold Monitoring Integration:Convergence of additive dosing systems with real-time thermal sensors enables predictive binder consumption optimization in automated high-pressure molding lines.
Industry Challenges
- Formulation Chemist Scarcity:Expertise in alkali-activated binder synthesis and low-emission resin modification remains concentrated among senior technical staff approaching retirement in European supplier labs.
- MACT Compliance Timelines:US EPA metal casting air toxics standards require emission control retrofits that compress capital allocation windows for additive system upgrades.
- Multi-Specification Inventory Complexity:Foundries serving both automotive and aerospace verticals must maintain parallel binder inventories with incompatible certification requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Foundry Additives Market |
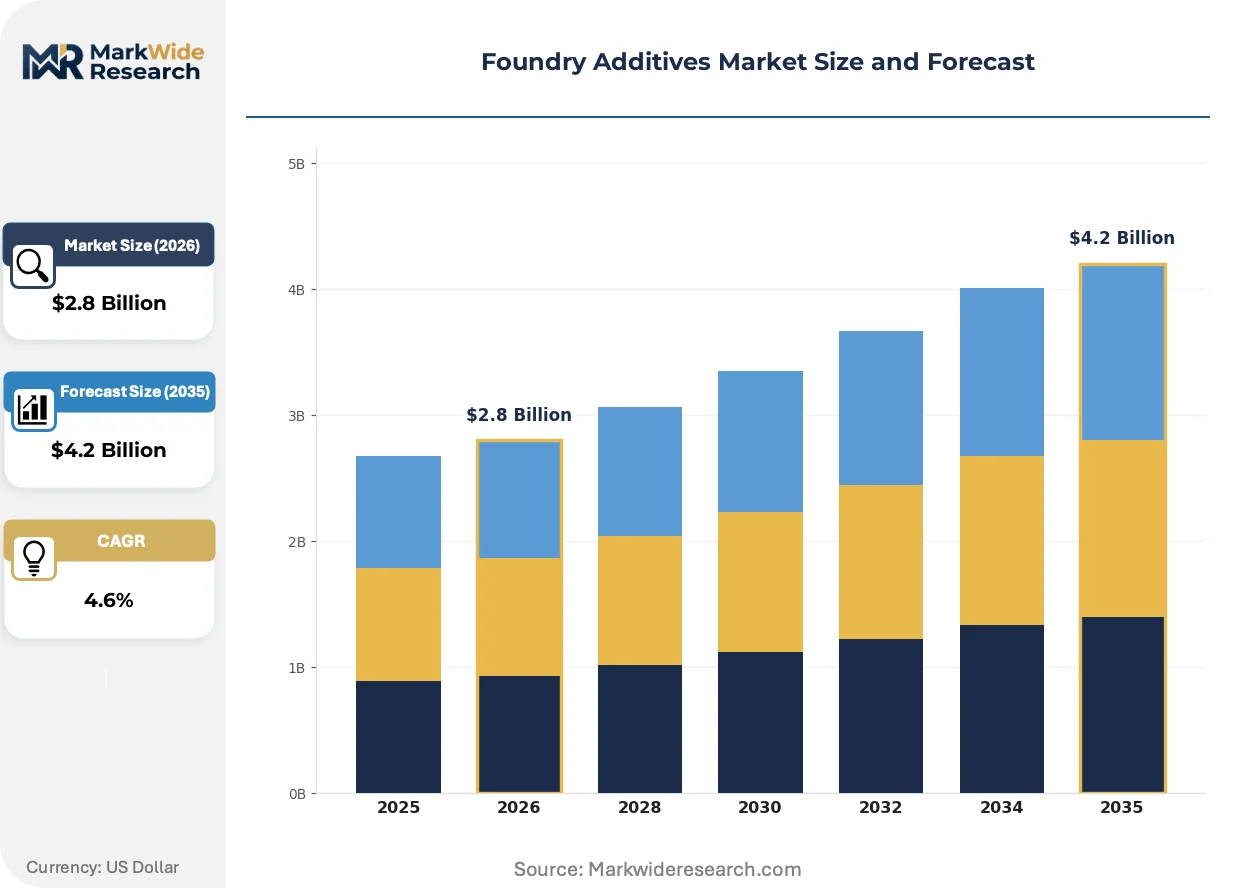
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.2 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Binder, Anti-Foaming Agent, Refractories, Coatings, Deoxidizers, Others Application: Metal Casting, Sand Molding, Investment Casting, Die Casting, Shell Molding, Centrifugal Casting End User: Foundry Shops, Metal Fabricators, Casting Manufacturers, Pattern Makers Distribution Channel: Direct Sales, Distributors, Online Retailers, Industrial Suppliers, Wholesale Dealers |
| Companies Covered | ASK Chemicals, Imerys, Vesuvius, HA International, Hüttenes-Albertus Chemische Werke, Elkem ASA, Ferroglobe, Sibelco, BASF, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Foundry Additives Market Shifts & Advancements
Active reshaping in this market centers on chemistry platform substitution driven by regulatory emission limits, digital integration of additive dosing with process control systems, and procurement consolidation among tier-one automotive suppliers.
Alkali-activated inorganic binder technology is consolidating its position as the primary alternative to formaldehyde-based phenolic resins in European automotive foundries. German and Italian engine block producers are adopting water-glass formulations at accelerated rates to preempt REACH compliance deadlines. This chemistry transition is consolidating supplier market share around firms with captive silicate processing capabilities while marginalizing regional resin blenders lacking inorganic synthesis expertise.
EPA metal casting MACT standards for hazardous air pollutant control are mandating emission capture retrofits across US ferrous foundries. The regulatory burden falls most heavily on small and mid-tier gray iron operations in the Midwest that lack capital reserves for scrubber installation. These foundries are responding by consolidating purchasing volumes through cooperative procurement networks to secure volume-tier pricing on low-emission binder alternatives.
Automotive tier-one suppliers are compressing their approved vendor lists for critical casting additives to reduce qualification overhead. This buyer concentration is displacing fragmented regional distributors with direct supply agreements to multinational additive formulators. The shift is most visible in China's Yangtze River Delta automotive cluster, where BYD and Geely casting divisions have reduced their active binder suppliers from twelve to four qualified sources since 2022.
Foundry Additives Market Segmentation
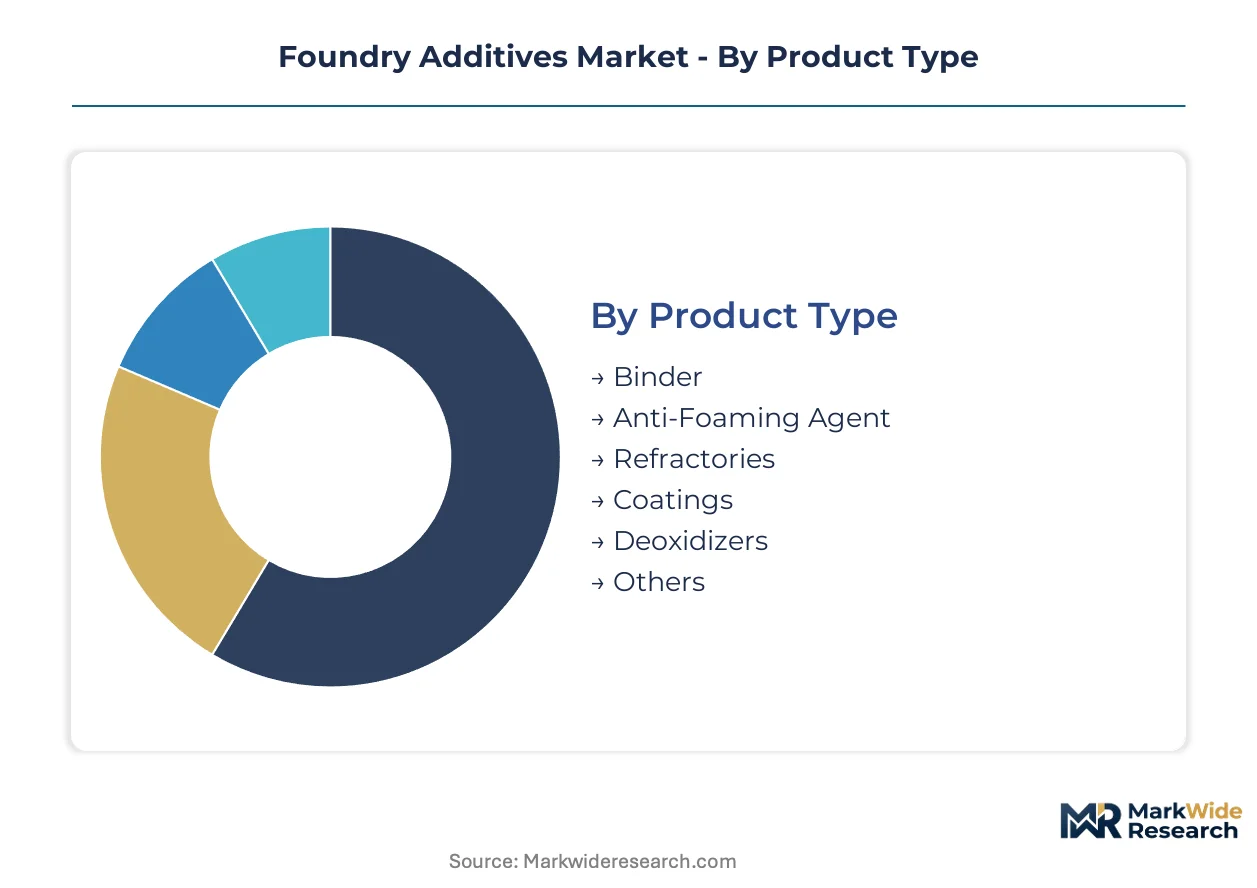
Segmentation in foundry additives reveals divergent margin structures across chemistry platforms and casting processes. Binder systems command premium pricing through proprietary formulations, while refractory coatings compete on volume throughput in automated shell production.
Product Type:
Volume concentrates in commodity mineral additives, while synthetic resin binders capture disproportionate margin pools through emission-compliant chemistry.
- Binder:Organic furan and phenolic resins (1.5–3.0% by weight) provide mold integrity in high-pressure automotive lines. Demand clusters in German and Italian engine block foundries confronting REACH formaldehyde restrictions. Water-glass alternatives are gaining share fastest as MEE enforcement tightens in Hebei province.
- Refractories:Zircon- and alumina-based slurries with 60–75% solids content protect mold surfaces from molten metal erosion. Aerospace turbine blade producers in France and the UK specify elevated purity grades, compressing acceptable supplier lists to three qualified sources.
- Anti-Foaming Agent:Silicone and mineral oil formulations prevent gas porosity in gray iron pours. Mediterranean foundries source through cooperative procurement networks to offset ferroalloy price swings.
- Coatings:Graphite- and alcohol-based dressings improve casting surface finish in sand molds. Indian Tamil Nadu cluster adoption is accelerating under PLI-linked modernization schemes.
- Deoxidizers:Aluminum, silicon, and calcium ferroalloys scavenge dissolved oxygen from molten steel. Elkem ASA's captive ferroalloy sourcing anchors European supply security.
- Others:Specialty inoculants and nodularizers modify graphite morphology in ductile iron. Chinese Shandong province integrated steel-casting complexes consume bulk volumes.
Today's leader: Binder systems. Tomorrow's challenger: Alkali-activated inorganic alternatives.
Application:
Process selection determines additive specification intensity, with investment casting demanding the most stringent refractory purity while sand molding maximizes throughput volume.
- Metal Casting:Ferrous and non-ferrous pouring operations across gray iron, steel, and aluminum alloys. US Midwest foundries face EPA MACT retrofit burdens that compress capital for additive upgrades.
- Investment Casting:Ceramic shell production for aerospace turbine blades requires zircon slurry with tight particle size distribution. French ANSM certification requirements limit active suppliers.
- Sand Molding:Green sand and chemically bonded systems dominate automotive component production. China's BYD and Geely casting divisions have consolidated from twelve to four qualified binder sources.
- Die Casting:High-pressure aluminum injection for transmission housings and structural components. Lubricant and release agent formulations differ fundamentally from sand mold chemistry.
- Shell Molding:Resin-coated sand processes for precision steel castings. German KBA automotive certification drives specification tightening.
- Centrifugal Casting:Rotational metal distribution for pipe and cylinder liners. Refractory coating requirements are minimal compared to static mold processes.
Shell molding holds the steepest expansion trajectory in automotive lightweighting. Sand molding retains absolute volume dominance.
End User:
Customer scale dictates procurement leverage, with tier-one automotive suppliers extracting volume-tier pricing while job shops absorb distributor markups.
- Foundry Shops:Independent operations serving diversified industrial casting demand. US small and mid-tier gray iron foundries lack scrubber capital, forcing cooperative purchasing networks.
- Casting Manufacturers:Integrated producers with captive mold-making capability. China's Yangtze River Delta automotive cluster exhibits the most aggressive supplier consolidation.
- Metal Fabricators:Secondary processors adding cast components to welded assemblies. Specification authority rests with downstream OEMs, not fabricators themselves.
- Pattern Makers:Tooling specialists requiring release agents and surface treatments for master pattern production. Niche volume with high technical service demands.
Procurement power concentrates with casting manufacturers. Foundry shops face margin compression from both input costs and customer consolidation.
Distribution Channel:
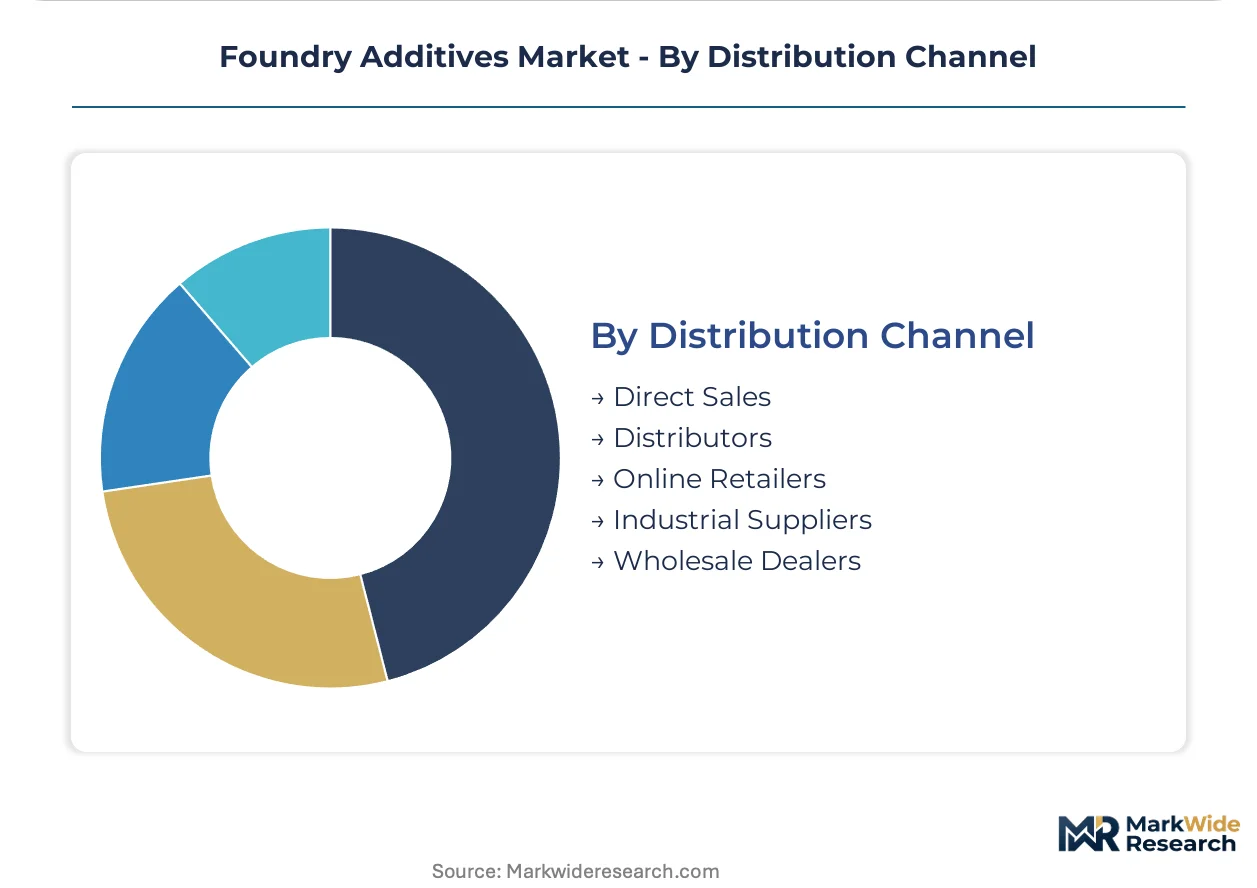
Channel selection reflects order scale and technical service requirements, with direct supply agreements displacing fragmented regional distribution.
- Direct Sales:Multinational formulators contract directly with tier-one automotive casting divisions. ASK Chemicals dominates European high-pressure molding lines through this channel.
- Distributors:Regional stockists serve job shops with fragmented demand and urgent replenishment needs. Margin pools erode as supplier lists compress.
- Industrial Suppliers:Broad-line distributors bundling foundry supplies with cutting tools and abrasives. Value-add concentrates in logistics integration, not technical formulation support.
- Wholesale Dealers:Bulk mineral additive traders serving commodity bentonite and silica sand demand. Price transparency limits differentiation.
- Online Retailers:Emerging channel for standardized consumables and technical documentation. Limited penetration in specification-critical binder systems.
Direct sales commands specification authority. Distributors retain relevance only where technical service requirements are minimal.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled formulation chemists in Germany's Rhineland and process engineers in China's Hebei province anchor regional competitive positioning. Technical expertise concentration determines where next-generation binder platforms achieve commercial scale first.
China
Hebei and Shandong province integrated steel-casting complexes consume bulk volumes of metallurgical-grade additives. MEE enforcement of foundry sector emission limits is consolidating consumption around cleaner synthesis routes. Yangtze River Delta automotive clusters have reduced active binder suppliers from twelve to four qualified sources since 2022.
Germany
Engine block foundries in Baden-Württemberg and North Rhine-Westphalia confront REACH formaldehyde restrictions on phenolic resin precursors. KBA automotive certification drives specification tightening for shell molding applications. German suppliers with captive silicate processing capabilities are capturing share from regional resin blenders lacking inorganic synthesis expertise.
United States
Midwest gray iron foundries face EPA metal casting MACT standards for hazardous air pollutant control. Small and mid-tier operations lack capital reserves for scrubber installation, forcing cooperative procurement networks for low-emission binder alternatives. Tier-one automotive suppliers are compressing approved vendor lists to reduce qualification overhead.
India
Tamil Nadu and Gujarat casting clusters are accelerating additive upgrade cycles under PLI-linked foundry modernization schemes. CDSCO-aligned technical documentation requirements are elevating entry barriers for unqualified distributors. Indian automotive component manufacturers are migrating from commodity bentonite to synthetic binder systems for tighter dimensional tolerances.
Italy
Automotive casting clusters in Emilia-Romagna and Lombardy are adopting water-glass formulations at accelerated rates to preempt REACH compliance deadlines. Italian engine block producers specify elevated purity grades that compress acceptable supplier lists. Regional foundries maintain parallel binder inventories with incompatible certification requirements for automotive and aerospace verticals.
Foundry Additives Market Competitive Landscape
Capital-heavy producers with captive ferroalloy smelters and resin synthesis plants compete with asset-light distributors bundling logistics and technical service. The market structure consolidates around multinational formulators with direct automotive supply agreements, while regional blenders face margin compression from buyer concentration. Three archetypes dominate: integrated chemistry platforms with backward mineral control, specialized resin formulators with proprietary low-emission formulations, and broad-line distributors serving fragmented job-shop demand. Competitive moves center on M&A to secure silicate processing capabilities and strategic partnerships for digital mold monitoring integration.
Within the integrated chemistry tier, Elkem ASA and Ferroglobe exemplify players with upstream ferroalloy anchoring. Among specialized resin formulators, ASK Chemicals occupies a position representing phenolic resin expertise for high-pressure molding lines. BASF sits within the diversified multinational archetype, leveraging scale across multiple industrial chemistry verticals. These three company types illustrate how competitive positioning stratifies between mineral-backed supply security and formulation-driven specification authority.
| Leading Market Players |
|---|
| ASK Chemicals |
| Imerys |
| Vesuvius |
| HA International |
| Hüttenes-Albertus Chemische Werke |
| Elkem ASA |
| Ferroglobe |
| Sibelco |
| BASF |
| Others |
Supply & Pricing Matrix
Family-owned mid-cap resin blenders across Italy's Emilia-Romagna cluster anchor supply-side discipline through generational capital patience, insulating pricing from quarterly earnings pressure while compressing distributor margins through cooperative foundry purchasing networks. This ownership pattern concentrates pricing power with captive silicate processors in Germany and China, who extract volume-tier premiums from automotive casting divisions consolidating approved vendor lists.
Pricing Analysis
Bundled technical service contracts dominate premium synthetic binder sales, while unbundled commodity bentonite moves through spot-market mineral traders. Three-tier pricing structure across emission-compliant, standard-grade, and economy mineral tiers separates REACH-certified water-glass formulations from formaldehyde-based phenolic resins. Pricing pressure stems from ferroalloy smelter energy tariff volatility compressing deoxidizer margins. Tier-one automotive suppliers exhibit lowest price sensitivity, while Midwest gray iron job shops absorb full distributor markups.
Supply Chain Analysis
China's domestic-content mandates for foundry sector emission compliance are reshaping sourcing patterns, forcing multinational formulators to localize silicate processing within Hebei province boundaries. Supply concentrates in China, Germany, and India for metallurgical-grade silicon, phenolic resin precursors, and zircon refractory feedstocks respectively. The chain rests on captive ferroalloy smelting, alkali-activated binder synthesis, and ceramic shell slurry formulation. Single-source vulnerability concentrates in European phenolic resin precursor supply. Distribution runs through direct sales agreements with tier-one automotive casting divisions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder where REACH formaldehyde restrictions and China's MEE enforcement create replacement demand cycles that outpace organic volume growth.
For Market Incumbents: Deepen backward integration into silicate mining and alkali-activated synthesis to preempt water-glass formulation gaps. Secure KBA automotive certification for shell molding lines before Italian competitors consolidate German engine block share. Add captive ferroalloy smelting capacity in Norway to offset Mediterranean energy tariff exposure. For New Entrants and Emerging Players: Small and mid-tier US gray iron foundries lacking scrubber capital represent the most penetrable buyer archetype for cooperative procurement network participation. Target India's Tamil Nadu PLI-linked modernization clusters for synthetic binder upgrade cycles. Enter through technical service partnerships with local distributors holding CDSCO-aligned documentation capabilities. For Investors and Strategic Acquirers: Valuations sit cheapest among asset-light regional resin blenders lacking inorganic synthesis expertise but holding automotive qualification relationships. Five-to-ten year viability hinges on chemistry platform substitution curves favoring alkali-activated alternatives. Watch ECHA regulatory phase-in timelines as inflection indicators for water-glass adoption acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silicate Mining | Captive mineral supply secures water-glass formulation margins against commodity zircon price swings. |
| Long-term Supply Agreement with Automotive OEMs | Direct contracts with BYD and Geely casting divisions lock in volume-tier pricing. |
| Green Manufacturing Transition | Low-emission binder platforms preempt REACH compliance deadlines in German engine block foundries. |
| Joint Venture for Regional Production | Localized Hebei province synthesis meets China's MEE domestic-content mandates. |
| Acquisition of Specialist Inorganic Formulator | Silicate processing expertise displaces phenolic resin blenders in European automotive clusters. |
Research Methodology
Multiple input streams — technical formulation interviews, procurement pattern analysis, and regulatory filing review — were reconciled to construct demand estimates. Primary discussions engaged foundry plant managers, automotive Tier 1 procurement leads, resin R&D directors, and cooperative purchasing network coordinators. Secondary validation drew from ECHA restriction dossiers, MEE emission enforcement circulars, SEC 10-K chemical segment disclosures, and German KBA certification registries. Bottom-up additive consumption modeling and top-down casting output triangulation converged on segment-level projections.
Data-stream reconciliation across chemistry platform substitution curves, automotive production forecasts, and regulatory phase-in timelines anchored the analytical framework. Segmentation dimensions included binder chemistry type, casting process intensity, end-use certification tier, and regional regulatory cluster. CAGRs were derived from slope analysis of technology adoption curves and enforcement-driven replacement cycles. Ferroalloy price volatility indices and scrubber retrofit capital constraints informed scenario boundaries.
Underlying measurement precision varies by segment; REACH-compliant water-glass volumes carry tighter precision than informal economy bentonite trade. Forecasts embed assumptions regarding ECHA restriction enforcement timelines and MEE inspection intensity. Commodity mineral price swings, automotive platform electrification, and aerospace casting demand shifts could revise trajectory. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Citrate Ester Market
Additives
China Feed Additives Market
Additives
Global Feed Acidifiers Market
Additives
Liquid Silage Additive Market
Additives
Global Ester Gum Market
Additives
Global Calcium Formate Market
Additives
Global Propyl Acetate Market
Additives
Sodium Benzoate Market
Additives
Global UV Stabilizers Market
Additives
Emulsifiers In Personal Care Market
Additives
Spain Anti Caking Market
Additives
Europe Choline Chloride Market
Additives
Global Slip Additives Market
Additives
Global Chelated Trace Minerals Market
Additives
United States Citric Acid Market
Additives
Germany Sodium Reduction Ingredient Market