
 Dental Putty Market | 2026-2036
Dental Putty Market Size, Share, and Industry Trends Forecast 2026-2036
Dental Putty Market Analysis
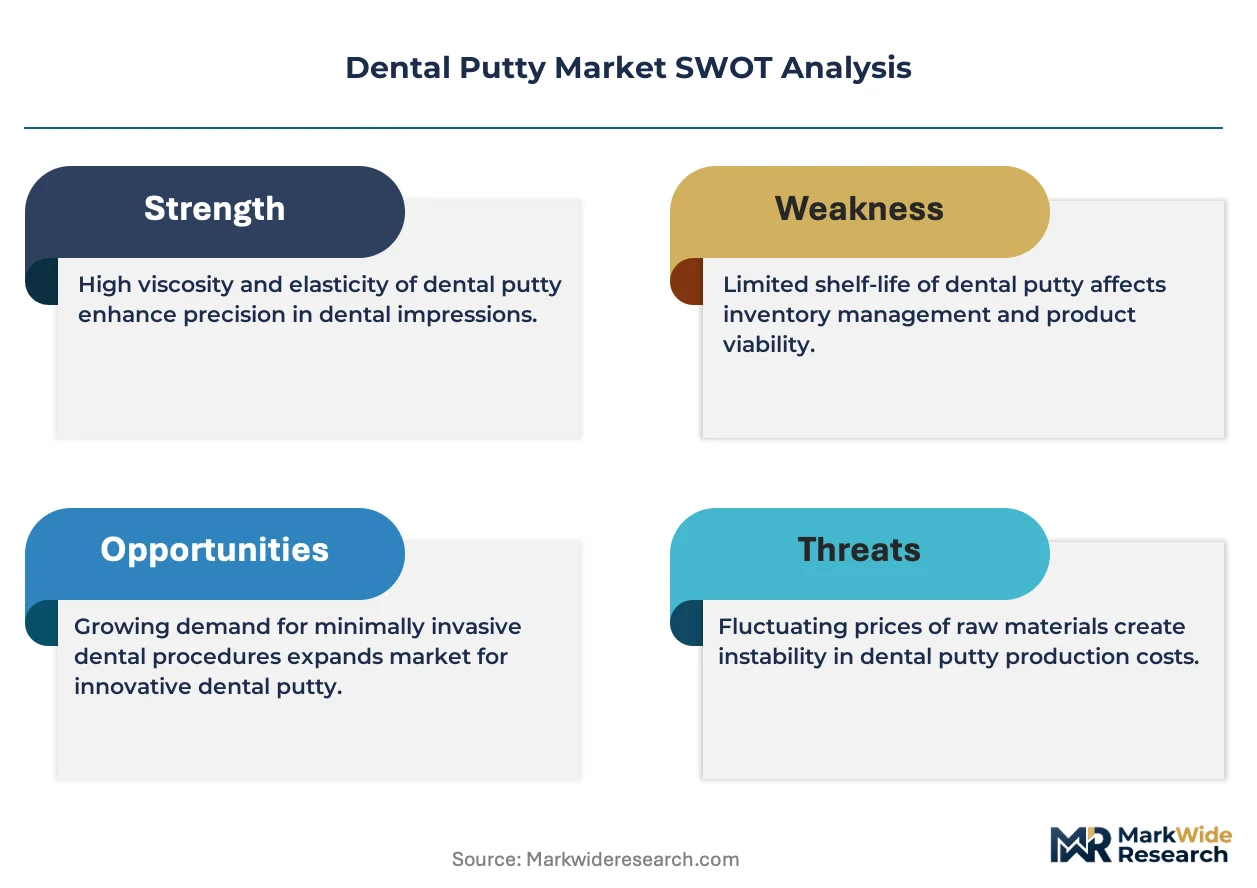
The EU Medical Device Regulation is recalibrating the cost-of-entry calculus for dental putty manufacturers seeking European market access. Dentsply Sirona leverages its vertically integrated supply chain to absorb compliance costs more efficiently than smaller rivals. Ivoclar Vivadent anchors its competitive position through specialized R&D in high-precision impression materials. Kerr Corporation differentiates via channel control across North American dental distributors.
Dental putty denotes a pliable, elastomeric compound formulated from addition silicone, polyether, or alginate bases that sets via chemical crosslinking to capture negative replicas of oral anatomy with micron-level accuracy. Manufacturers typically meter base and catalyst pastes through automated mixing systems to achieve homogeneous consistency and controlled working times between 90 and 180 seconds. Addition silicone dominates product type revenue due to its dimensional stability and tear strength, while polyether captures premium margin pools where subgingival detail reproduction matters most. Dental clinics represent the largest end user channel by volume, though dental laboratories generate higher per-unit value through specialized cast work.
FDA 510(k) clearance pathways and ISO 4823 standards govern material classification and performance testing in the United States, while the EU MDR and REACH chemical safety frameworks shape formulation constraints across European markets. Japan's PMDA and METI coordinate domestic approval timelines that frequently lag Western certification by 12-18 months, creating asynchronous launch windows. Stakeholders must monitor evolving biocompatibility testing protocols and raw material substitution pressures as regulatory stringency tightens without explicit phase-in deadlines.
Market Dynamics
The EU Medical Device Regulation is compressing formulation flexibility while elevating biocompatibility testing burdens, forcing manufacturers to reengineer supply chains around certified raw material streams and captive analytical capabilities.
Growth Catalysts
- Cosmetic dentistry volume:Elective veneer and implant procedures in private clinics drive recurring impression material consumption at premium price points.
- ISO 4823 harmonization:Standardized dimensional stability testing reduces cross-border certification friction for addition silicone formulations.
- Germany's manufacturing corridor:Concentrated dental equipment production around Biberach and Hanau creates localized demand pull for compatible putty systems.
Market Restraints
- Platinum catalyst volatility:Addition silicone crosslinking depends on platinum group metals exposed to mining supply concentration in South Africa and Russia.
- EU MDR transition costs:Clinical evidence requirements for Class IIa devices impose documentation burdens that favor incumbent balance sheets over entrants.
- Intraoral scanning substitution:Chairside digital impression systems capture anterior cases that previously required conventional putty workflows.
Strategic Opportunities
- Japan's asynchronous approval window:PMDA certification timelines lag Western markets by 12-18 months, creating first-mover advantages for prepared entrants.
- 3D-printed model integration:Hybrid workflows combining conventional impressions with digital model production open laboratory service expansion.
- REACH substitution mandates:Phthalate and tin catalyst restrictions accelerate demand for platinum-catalyzed and polyether alternatives with cleaner toxicological profiles.
Industry Challenges
- Mixing system calibration:Automated dispensing equipment requires field service networks that strain mid-tier manufacturer operating models.
- Biocompatibility test backlog:ISO 10993 cytotoxicity and sensitization studies face laboratory capacity constraints that extend product launch timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dental Putty Market |
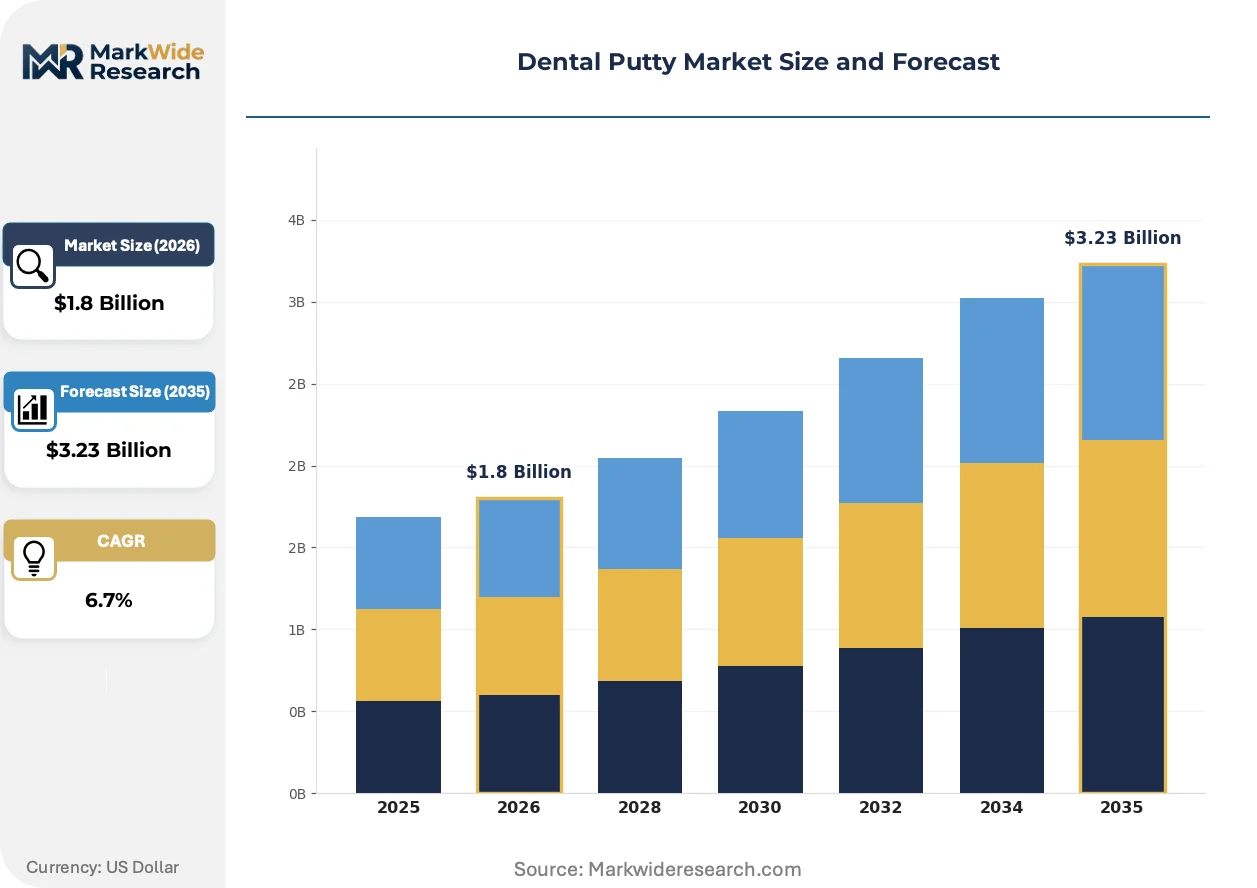
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Addition Silicone, Polyether, Alginate, Other Types Application: Impressions, Restorations, Casts, Other Applications End User: Dental Clinics, Hospitals, Dental Laboratories, Other Users Packaging Type: Tubes, Jars, Pouches, Other Packaging |
| Companies Covered | 3M, Dentsply Sirona, Ivoclar Vivadent, Heraeus Kulzer, GC Corporation, Kerr Corporation, Coltene Holding AG, Zhermack, Septodont, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dental Putty Market Emerging Trajectories
Digital dentistry workflows are fragmenting impression capture between chairside scanning and conventional elastomeric methods, forcing putty manufacturers to defend material relevance through precision specialization and hybrid system compatibility.
Fast-setting addition silicone variants with sub-120-second working times are absorbing chairside efficiency demands from high-volume cosmetic practices. These formulations sacrifice some working latitude for clinical throughput gains. The compression is absorbing margin from conventional 180-second products in time-sensitive applications.
REACH Annex XVII restrictions on organotin catalysts are forcing polyether and condensation silicone reformulations across European supply chains. Manufacturers with pre-validated platinum-catalyzed alternatives capture shelf space as competitors face substance sunset deadlines. German dental distributors report accelerated SKU transitions in Q3 procurement cycles.
Consolidated procurement by dental service organizations is unbundling traditional distributor relationships in North American metropolitan markets. Group purchasing contracts favor suppliers with direct logistics infrastructure over regional distributor networks. Texas and Florida multi-site operators lead this behavioral shift through centralized material standardization mandates.
Dental Putty Market Segmentation
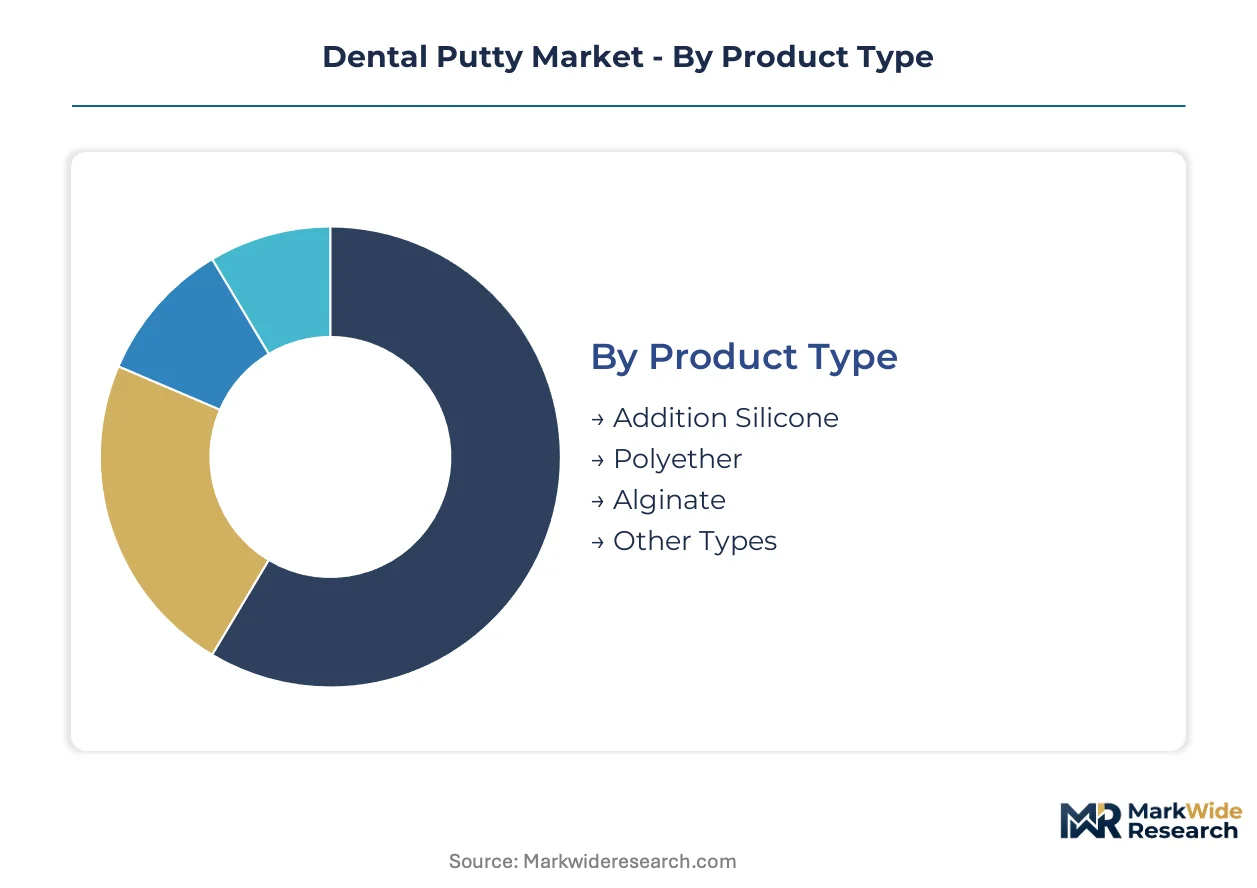
Dental putty segmentation reveals how material chemistry, clinical workflow, and procurement economics intersect. Manufacturers align formulation portfolios against specific impression precision requirements and end-user infrastructure capabilities.
Product Type:
Material chemistry determines dimensional stability, tear strength, and setting kinetics across impression workflows.
- Addition Silicone:Hydrogen-functional polysiloxane bases crosslink via platinum-catalyzed hydrosilylation, delivering superior elastic recovery and minimal shrinkage. Demand concentrates in Germany's Biberach-Hanau manufacturing corridor where precision casting for implant prosthetics drives specification. ISO 4823 Type 3 classification governs clinical acceptance thresholds.
- Polyether:Aziridine-terminated prepolymers polymerize through cationic ring-opening, producing hydrophilic surfaces that capture subgingival detail in moist environments. Swiss and Austrian private clinics specify polyether for crown-and-bridge impressions where margin definition determines restoration fit. REACH Annex XVII organotin restrictions are accelerating platinum-catalyzed formulation transitions.
- Alginate:Irreversible hydrocolloid derived from brown seaweed alginate salts, suitable for preliminary study models and orthodontic appliances. Cost-sensitive volume applications in school-based screening programs.
- Other Types:Condensation silicone and zinc oxide-eugenol variants serving niche remount and border-molding functions in complete denture fabrication.
Mature deployment sits with addition silicone. Newer deployment is concentrated in polyether as biocompatibility standards tighten.
Application:
Clinical use case dictates working time, viscosity grade, and delivery system requirements.
- Impressions:Negative replica capture for fixed and removable prosthodontics, requiring tray adhesives and border seal techniques. German dental laboratories generate premium per-unit value through specialized cast work.
- Restorations:Direct chairside applications including temporary crown matrices and occlusal registration. Fast-setting variants with sub-120-second working times absorb cosmetic dentistry throughput demands in high-volume Florida and Texas practices.
- Casts:Positive model production for appliance fabrication and diagnostic mounting. Dental service organization procurement consolidation favors suppliers with direct logistics infrastructure over regional distributors.
- Other Applications:Bite registration, custom tray fabrication, and implant surgical guide modeling.
Volume concentration rests with impressions. Margin expansion is concentrated in restorations as chairside efficiency pressures intensify.
End User:
Procurement scale and technical sophistication create distinct service requirements.
- Dental Clinics:Private practice settings performing direct patient care, representing the largest channel by material volume. Automated mixing system compatibility influences brand loyalty and reorder patterns.
- Hospitals:Academic medical centers and oral surgery units managing complex trauma and oncology cases. Bulk purchasing agreements and infection control protocols shape supplier selection.
- Dental Laboratories:Independent and commercial prosthetic fabrication facilities generating higher per-unit material value through specialized cast work and model production.
- Other Users:Dental schools, research institutions, and military dental services with training and non-clinical applications.
Established procurement sits with dental clinics. Accelerating investment is concentrated in dental laboratories integrating 3D-printed model workflows.
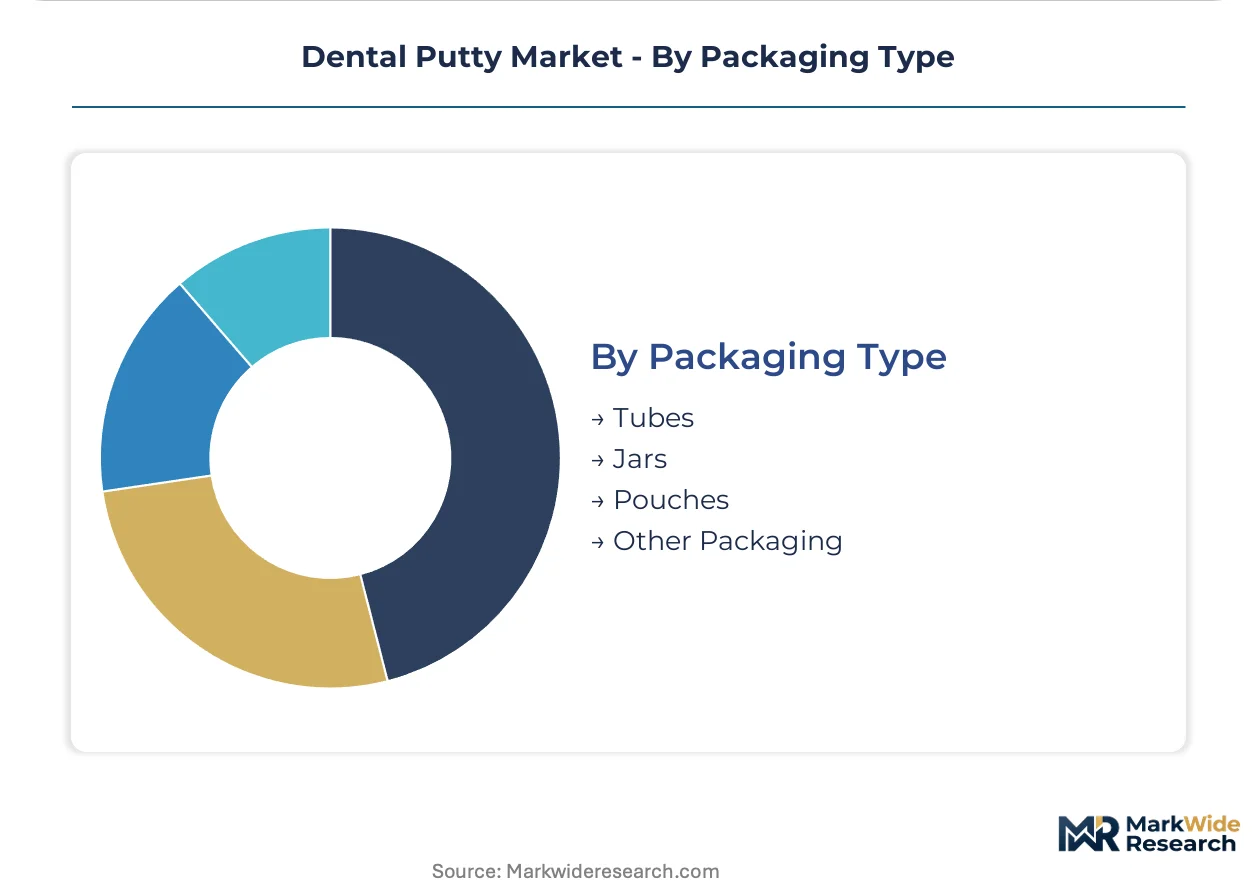
Packaging Type:
Delivery format determines shelf stability, dosing accuracy, and cross-contamination risk.
- Tubes:Collapsible aluminum or laminate tubes for manual mixing applications, prevalent in cost-conscious markets and field dental units.
- Jars:Wide-mouth containers for spatula-mixing techniques in laboratory settings where bulk dispensing reduces unit costs.
- Pouches:Pre-dosed single-use sachets eliminating measurement error and reducing waste in infection-control-sensitive environments.
- Other Packaging:Cartridge systems for automated mixing devices and unit-dose capsules for specific impression material lines.
Standard deployment sits with tubes. Premium migration is concentrated in pouches as chairside efficiency and infection control priorities advance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany absorbs the highest per-capita dental putty consumption in Europe, driven by its dense concentration of precision dental manufacturing and private cosmetic dentistry clinics. The United States and Japan follow as distinct demand poles, each shaped by divergent regulatory timelines and clinical workflow preferences.
Germany
Private cosmetic dentistry clinics in Munich and Hamburg drive recurring consumption of fast-setting addition silicone formulations. The EU MDR tightens biocompatibility documentation requirements for Class IIa devices, extending certification timelines for new product launches. The Biberach-Hanau manufacturing corridor anchors European supply, with local laboratories generating premium per-unit value through specialized implant prosthetic casting.
United States
Florida and Texas multi-site dental service organizations consolidate procurement through centralized material standardization mandates. FDA 510(k) clearance pathways govern material classification, though ISO 4823 harmonization reduces cross-border friction for addition silicone imports. The Greater Boston research corridor hosts specialized biocompatibility testing laboratories facing capacity constraints that extend product launch timelines.
Japan
High-volume cosmetic practices in Tokyo and Osaka absorb chairside efficiency demands through sub-120-second working time formulations. METI and PMDA coordinate domestic approval timelines that lag Western certification by 12-18 months, creating asynchronous launch windows for prepared entrants. The Nagoya industrial zone concentrates dental equipment production, generating localized demand pull for compatible putty systems.
Switzerland
Swiss private clinics specify polyether formulations for crown-and-bridge impressions where subgingival margin definition determines restoration fit. Swissmedic maintains alignment with EU MDR standards while preserving independent approval pathways for novel material chemistries. The Basel-Zurich corridor hosts precision chemical manufacturing facilities supplying platinum catalyst streams to regional formulators.
China
Expanding private dental clinic chains in Shanghai and Beijing drive volume demand for cost-optimized alginate and addition silicone products. NMPA medical device registration requirements are converging toward ISO standards, though GB testing protocols retain distinct documentation burdens. The Yangtze River Delta concentrates dental consumables distribution infrastructure serving domestic and export markets.
Dental Putty Market Vendor Landscape
German and Swiss producers anchor the premium formulation tier; American and Japanese specialists hold positions in high-throughput clinical workflows and precision casting applications. The vendor base concentrates around three strategic archetypes: vertically integrated dental conglomerates with captive raw material supply, mid-tier regional formulators serving distributor networks, and niche specialists in polyether and fast-setting chemistries. Competitive moves center on backward integration into platinum catalyst supply chains and direct logistics infrastructure bypassing traditional distribution.
Among diversified dental conglomerates, Dentsply Sirona and Ivoclar Vivadent occupy positions representing distinct strategic emphases—upstream supply chain control versus specialized R&D in high-precision impression materials. Kerr Corporation exemplifies the North American channel-control archetype, with its position reflecting distributor relationship depth across metropolitan dental service organizations. These three entities collectively illustrate how scale, specialization, and geographic focus segment competitive positioning in elastomeric impression materials.
| Leading Market Players |
|---|
| 3M |
| Dentsply Sirona |
| Ivoclar Vivadent |
| Heraeus Kulzer |
| GC Corporation |
| Kerr Corporation |
| Coltene Holding AG |
| Zhermack |
| Septodont |
| Others |
Supply Flow & Price Mechanics
Backward integration into platinum catalyst supply chains anchors both cost predictability and premium-tier pricing power for addition silicone formulators navigating REACH substitution mandates. German manufacturers with captive analytical capabilities absorb EU MDR compliance burdens more efficiently than distributor-dependent rivals, compressing mid-tier margin structures.
Pricing Analysis
Volume concentrates in standard-grade addition silicone tubes sold through dental distributors, while margin pools accrue to polyether pouches and fast-setting variants specified by cosmetic dentistry clinics. Price differentiation hinges on ISO 4823 Type 3 certification tier and automated mixing system compatibility. Pricing pressure stems from dental service organization procurement consolidation favoring direct logistics infrastructure. Cost-sensitive volume buyers in school-based screening programs exhibit highest price elasticity, whereas Swiss private clinics demonstrate lowest sensitivity for subgingival detail reproduction.
Supply Chain Analysis
Freight cost volatility from South African and Russian platinum group metal shipments feeds into addition silicone formulation economics, compressing landed cost advantages for European manufacturers. Raw material sourcing draws from German chemical corridors, Japanese silicone precursors, and South African platinum catalyst streams. Single-source vulnerability concentrates in platinum mining supply exposed to geopolitical disruption. Distribution runs through dental distributor networks in North America, direct manufacturer relationships in Germany, and consolidated procurement platforms in Texas and Florida multi-site operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU MDR transition is forcing weaker formulators without captive testing infrastructure toward exit or acquisition, consolidating viable supply around balance-sheet-resilient incumbents.
For Market Incumbents: Anticipate intraoral scanning substitution by defending material relevance through hybrid workflow compatibility and sub-120-second fast-setting specialization. Prioritize backward integration into platinum catalyst supply chains to insulate margin from REACH-driven organotin restrictions. Channel control investments across dental service organization procurement platforms offset distributor relationship erosion in metropolitan markets. For New Entrants and Emerging Players: Japan's asynchronous approval window offers first-mover positioning for prepared entrants with pre-validated ISO 4823 Type 3 documentation and METI-aligned toxicological profiles. Target laboratory service expansion in 3D-printed model integration workflows where hybrid conventional-digital demand outpaces incumbent coverage. Pursue direct logistics infrastructure bypassing regional distributor networks to capture dental service organization procurement consolidation. For Investors and Strategic Acquirers: Exit pathways concentrate in mid-tier regional formulators facing EU MDR documentation burdens without captive analytical capabilities. Long-term viability favors specialists with pre-validated platinum-catalyzed alternatives and direct channel relationships. Watch PMDA certification timeline compression as inflection indicator for Japanese market entry feasibility.| Strategic Initiative | Industry Significance |
|---|---|
| Platinum Catalyst Backward Integration | Insulates margin from South African supply concentration and REACH substitution mandates. |
| Fast-Setting Formulation R&D | Captures chairside efficiency demands from Florida and Texas cosmetic dentistry volumes. |
| EU MDR Certification Investment | Creates regulatory moat against mid-tier formulators lacking ISO 10993 testing capacity. |
| Dental Service Organization Direct Logistics | Bypasses distributor networks consolidating procurement in North American metropolitan markets. |
| Hybrid Workflow Compatibility Development | Defends material relevance against intraoral scanning substitution in anterior impression capture. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across dental materials procurement managers, laboratory technical directors, GPO contracts specialists, and regulatory affairs leads at formulators. FDA 510(k) databases, EU MDR notified body documentation, PMDA approval registries, and ISO 4823 certification records provided secondary validation. Bottom-up volume estimates from end-user channel segmentation triangulated against top-down manufacturer capacity assessments.
Granularity extended to material chemistry tier, clinical workflow application, packaging format, and end-user procurement scale across the projection horizon. Addition silicone, polyether, and alginate segments were modeled separately with distinct elasticity assumptions. CAGRs derived from regression against cosmetic dentistry procedure volumes, regulatory transition timelines, and digital dentistry adoption curves. Platinum group metal price volatility and biocompatibility testing laboratory capacity constraints informed scenario-weighted outputs.
Revisions become necessary when EU MDR implementation deadlines accelerate, platinum supply disruptions materialize, or intraoral scanning penetration exceeds base-case assumptions. Forecasts reflect documented assumptions about regulatory timeline stability and raw material substitution feasibility. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Materials
Global Dental Cements Market
Dental Materials
Toothpaste Market
Dental Materials
Dental Polymerization Lamps Market
Dental Materials
Fluoride Materials Market
Dental Materials
Dental Amalgam Market
Dental Materials
Global Endodontic Consumables Market
Dental Materials
Teeth Whitening Market
Dental Materials
Dental Plaster Market
Dental Materials
Oral Bone Implant Material Market
Dental Materials
Tooth Filling Materials Market
Dental Materials
Global Teeth Whitening Product Market
Dental Materials
Dental Fiber Posts Market
Dental Materials
Remineralizing Gum Market
Dental Materials
Dental Matrix Systems Market
Dental Materials
Dental Bonding Agent Market
Dental Materials
Dental Gypsum Market