
 Military Propellants Market | 2026-2036
Military Propellants Market Size, Share, and Industry Trends Forecast 2026-2036
Military Propellants Market Insights
Missile manufacturers are rotating procurement toward solid composite propellants as armed forces prioritize extended-range precision strike systems. BAE Systems leverages in-house nitrocellulose synthesis to secure raw material continuity across European supply chains. Rheinmetall AG anchors artillery propellant output through scaled nitramine production in Germany. Nammo AS specializes in minimum-signature propellants for guided munitions, competing on thermal signature reduction.
Military propellants are energetic materials formulated from nitrocellulose, nitroglycerin, or ammonium perchlorate composite blends that undergo controlled exothermic decomposition to generate thrust without external oxygen. Solid propellants dominate volume due to storability and mechanical simplicity in artillery and rocket motor applications, while liquid systems retain niche status in throttleable missile platforms. Hybrid propellants represent the fastest-growing technology segment as defense contractors seek safety advantages over liquids with performance approaching solids. Chemical technology leads absolute value generation across missile and artillery applications where electromechanical alternatives remain developmental.
The U.S. Department of Defense, NATO Standardization Office, and EU REACH framework collectively govern propellant composition, environmental discharge, and cross-border transfer protocols. REACH restrictions on nitrosamine precursors force reformulation investments, while DoD performance specifications mandate insensitive munitions compliance for new procurements. Stakeholders must monitor evolving energetic material classification under dual-use export controls and assess reformulation costs against qualification timelines for next-generation propellant families.
Market Dynamics
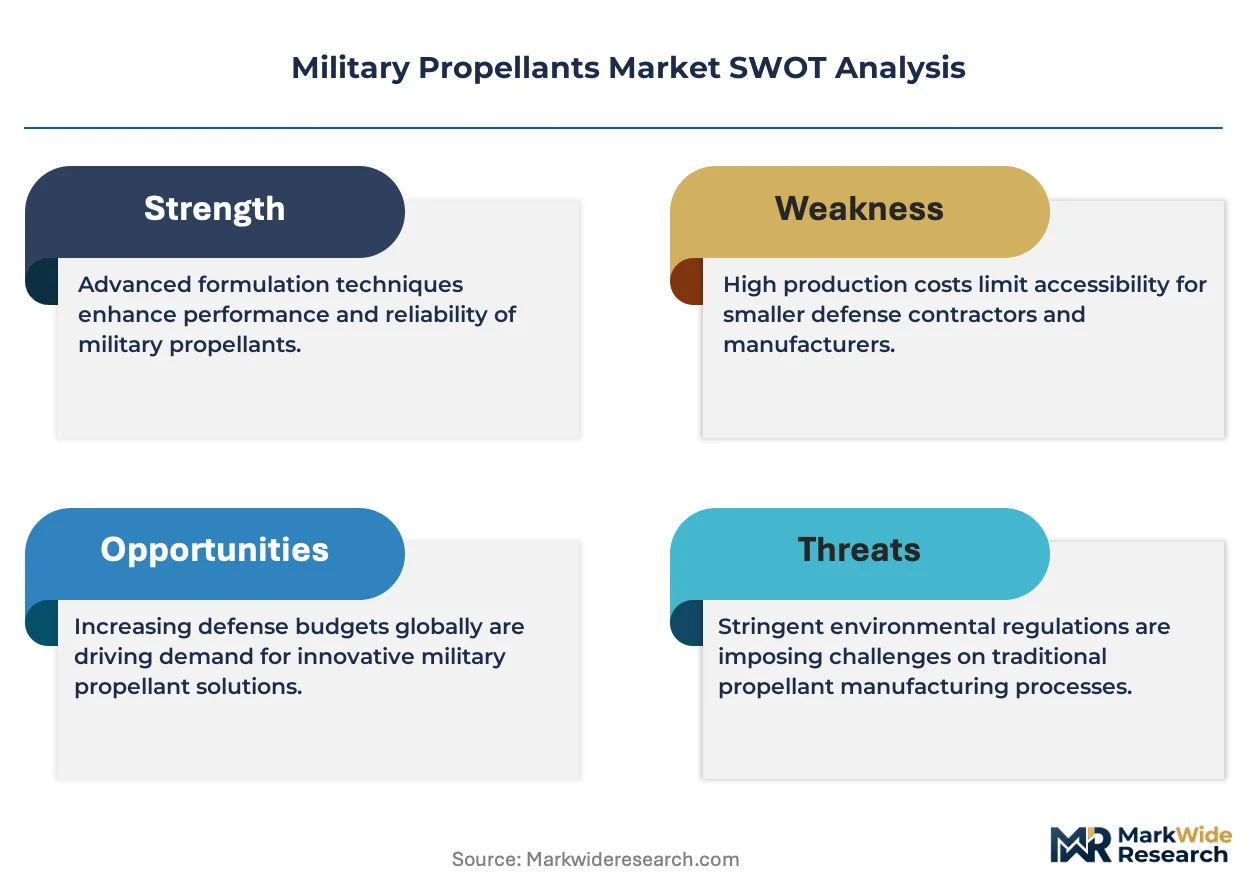
Hypersonic weapons programs are compressing qualification timelines for next-generation propellant families, forcing defense contractors to accelerate insensitive munitions certification while maintaining ballistic performance thresholds. This structural pressure cascades through nitramine supply chains and reformulation R&D budgets.
Growth Catalysts
- Artillery Replenishment Cycles:Sustained NATO stockpile rebuilding is pulling composite solid propellants through multi-year procurement frameworks. The U.S. Department of Defense's next-generation munitions specifications are mandating extended-range precision requirements that favor advanced nitramine formulations.
- REACH Reformulation Mandates:EU restrictions on nitrosamine precursors are accelerating investment in cleaner synthesis pathways. European defense contractors are qualifying alternative binders ahead of compliance deadlines to maintain cross-border transfer eligibility.
- Minimum-Signature Demand:Guided munitions programs are specifying reduced thermal and radar signatures for survivability against counter-battery systems. This technical requirement is expanding addressable volume for low-smoke composite propellants in tactical missile applications.
Market Restraints
- Nitrocellulose Supply Concentration:European nitrocellulose synthesis capacity clusters in Germany and France, creating single-point vulnerability for artillery propellant output. Any disruption to these facilities propagates through NATO ammunition supply chains.
- Ammonium Perchlorate Cost Volatility:Solid rocket motor propellants depend on this oxidizer, whose price swings with chlor-alkali industry cycles and environmental discharge permitting. Defense contractors face margin compression when input costs spike between contract awards.
- Insensitive Munitions Compliance Friction:DoD specifications for reduced accidental detonation risk impose qualification timelines that extend 18-24 months beyond traditional propellant certification. This technical barrier delays revenue recognition for new product families.
Strategic Opportunities
- Hybrid Propellant White Space:Safety advantages over liquid systems combined with performance approaching solids are opening missile platform opportunities. Defense contractors with hybrid motor test infrastructure can capture development contracts ahead of solid-propellant incumbents.
- Hypersonic Glide Vehicle Integration:Boost-glide architectures require propellants with extreme temperature tolerance and rapid ignition reliability. This emerging application rewards materials science capabilities that exceed legacy tactical missile requirements.
- Domestic Synthesis Incentives:U.S. Department of Defense industrial base policies are channeling capital toward onshore nitrocellulose and nitramine production. Contractors establishing captive raw material supply secure preferential qualification status for strategic programs.
Industry Challenges
- Energetic Materials Talent Scarcity:Specialized chemists and process safety engineers with propellant formulation expertise are retiring faster than university programs replenish the pipeline. Defense contractors compete for limited personnel against commercial explosives and pharmaceutical sectors.
- Legacy Facility Modernization Burden:Cold War-era propellant manufacturing plants require hazardous materials remediation and automated process controls to meet current OSHA and EPA standards. Capital allocation to environmental compliance diverts resources from next-generation R&D.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Military Propellants Market |
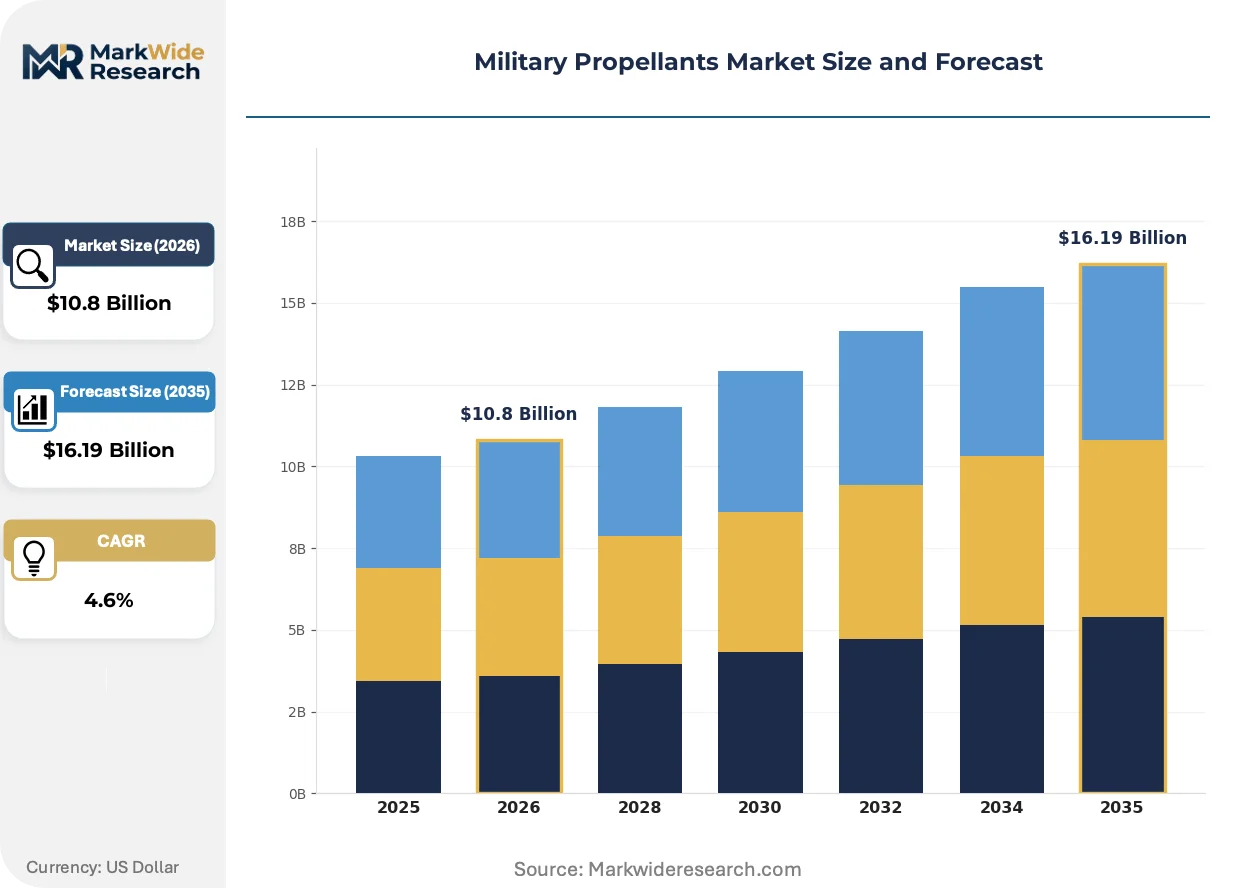
| Market Size in 2026 | $10.8 Billion |
| Market Size in 2035 | $16.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Propellant Type: Solid, Liquid, Hybrid, Composite, Gelled Technology: Chemical, Electromechanical, Electromagnetic, Cryogenic, Thermal Application: Missiles, Artillery, Rocket Launchers, Torpedoes, Guided Munitions End User: Defense Contractors, Armed Forces, Missile Manufacturers, Ordnance Suppliers |
| Companies Covered | Northrop Grumman Corporation, General Dynamics Corporation, BAE Systems, Raytheon Technologies Corporation, Rheinmetall AG, Lockheed Martin Corporation, Nammo AS, Eurenco, MAXAM Corp, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Military Propellants Market Trends and Innovations
Solid propellant chemistry is undergoing generational transition as defense agencies prioritize insensitive munitions compliance without sacrificing specific impulse. This technical evolution is reshaping competitive positioning around materials science capabilities rather than scale economics alone.
Hybrid propellant systems combining liquid oxidizer injection with solid fuel grains is bifurcating the tactical missile segment. Throttleable thrust profiles enable precision terminal maneuvering that solid motors cannot achieve. Defense contractors with hybrid test infrastructure are capturing development contracts for loitering munitions and reusable target systems, compressing incumbent solid-motor suppliers into artillery and strategic rocket niches.
EU REACH restrictions on nitrosamine precursors are forcing reformulation of nitrocellulose-based propellants across European defense supply chains. ECHA classification updates are triggering mandatory safety data sheet revisions and downstream user notifications. German and French contractors are accelerating alternative binder qualification to maintain cross-border transfer eligibility under dual-use export controls.
Defense procurement offices are consolidating supplier bases through multi-year strategic sourcing agreements that bundle propellant supply with integrated missile system contracts. This buyer concentration is displacing spot-market transactions and fragmenting Tier-2 chemical suppliers. The shift is most visible in U.S. Army artillery modernization programs, where prime contractors now assume formulation risk rather than delegating to independent propellant houses.
Military Propellants Market Segmentation
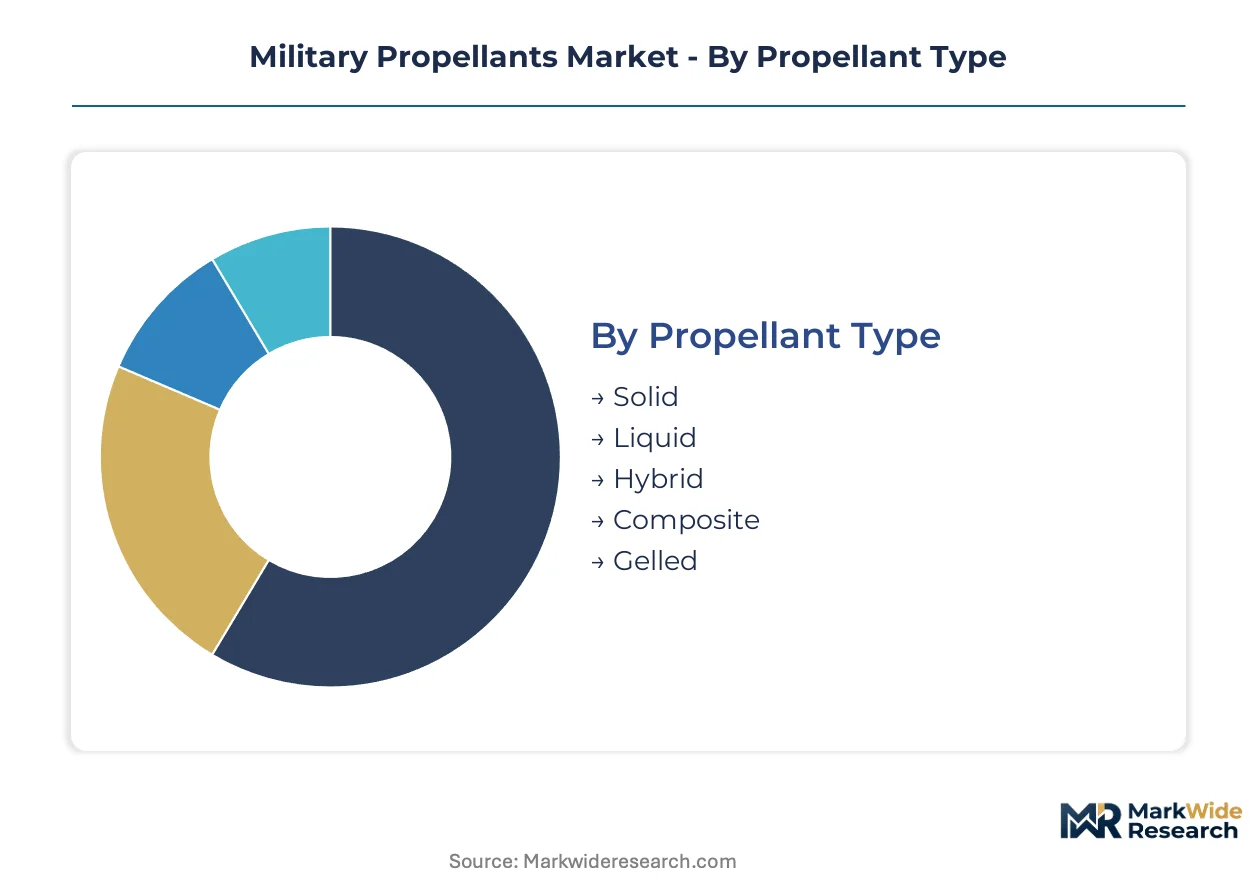
Military propellant procurement flows through distinct technical and commercial channels, with each segment commanding specialized qualification protocols and supply chain configurations. Understanding these pathways reveals where formulation risk concentrates and where contractor margins diverge.
Propellant Type:
Channel mix varies sharply by physical state—solid formulations move through integrated prime contractor agreements, while liquid and hybrid systems retain spot-market flexibility for development programs.
- Solid:Nitrocellulose and composite grain formulations dominate artillery and strategic rocket motor production. Demand concentrates in U.S. Army replenishment programs and NATO stockpile rebuilding, where storability and mechanical simplicity override throttleability requirements. REACH-driven reformulation of European nitrocellulose supply chains is compressing contractor margins.
- Liquid:Bi-propellant systems combining hydrazine derivatives with nitrogen tetroxide retain niche status in throttleable tactical missiles and satellite maneuvering thrusters. Missile manufacturers in the United States specify these for precision terminal engagement profiles where solid motors cannot achieve required divert capability.
- Hybrid:Solid fuel grains with liquid oxidizer injection are climbing the fastest as defense contractors seek safety advantages over liquids with performance approaching solids. Loitering munitions and reusable target systems are pulling volume through hybrid motor test infrastructure investments.
- Composite:Ammonium perchlorate-based formulations with elastomeric binders serve high-performance strategic applications. Cost volatility in chlor-alkali-derived oxidizer supply constrains procurement planning.
- Gelled:Thixotropic propellants combining liquid oxidizers with gelling agents offer reduced spill hazard for naval applications. Limited production scale restricts qualification to specialized torpedo programs.
Solid propellants dominate installed base across artillery and strategic rocket inventories. Hybrid systems are where expansion concentrates as development contracts shift toward throttleable architectures.
Technology:
Cost tier separation is pronounced—chemical propulsion commands mature qualification pathways while electromechanical alternatives absorb disproportionate R&D allocation without production scale.
- Chemical:Exothermic decomposition of energetic materials generates thrust through controlled oxidation reactions. This tier captures absolute value generation across missile and artillery applications where electrochemical alternatives remain developmental.
- Electromechanical:Electric motor-driven turbopumps and valve systems enable precision propellant metering for responsive thrust modulation. Armed forces in the United States are funding demonstration programs for responsive space launch, though operational deployment remains years from qualification.
- Electromagnetic:Railgun and coilgun acceleration of inert projectiles eliminates chemical storage hazards. Naval Surface Warfare Center testing programs are evaluating electromagnetic launch for naval gunfire support, with energy storage density representing the binding constraint.
- Cryogenic:Liquid hydrogen and liquid oxygen systems achieve highest specific impulse for heavy-lift launch vehicles. NASA and Space Force procurement for strategic launch maintains residual demand despite operational complexity penalties.
- Thermal:Solar-thermal and nuclear-thermal concepts leverage external heat sources for propellant expansion. Research funding concentrates in Defense Advanced Research Projects Agency programs without near-term production pathways.
Chemical technology anchors current procurement volume. Electromechanical systems absorb disproportionate development investment without corresponding revenue recognition.
Application:
Volume distribution tracks platform modernization cycles, with artillery and missile programs commanding multi-year procurement frameworks while torpedo and guided munitions orders fragment across shorter development timelines.
- Missiles:Tactical and strategic rocket motors require propellants balancing specific impulse with insensitive munitions compliance. Hypersonic boost-glide programs in the United States are compressing qualification timelines for extreme-temperature-tolerant formulations.
- Artillery:Nitrocellulose-based propellants for gun-launched projectiles follow NATO standardization protocols. German and French synthesis capacity clusters create single-point vulnerability for European supply security.
- Rocket Launchers:Man-portable and vehicle-mounted systems demand minimum-signature propellants for crew survivability. Nammo AS specialization in thermal signature reduction competes for guided munitions contracts.
- Torpedoes:Otto Fuel II and hydroxylammonium perchlorate formulations serve underwater propulsion with seawater-compatible exhaust chemistry. Limited production runs sustain specialized ordnance suppliers.
- Guided Munitions:Precision artillery projectiles and glide weapons require propellants compatible with onboard electronics and seeker systems. Extended-range specifications favor advanced nitramine formulations with reduced residue.
Missile applications concentrate development investment. Artillery volume dominates steady-state procurement through replenishment cycles.
End User:
Customer type determines contract structure—prime contractors assume formulation risk in integrated system awards while independent ordnance suppliers retain spot-market flexibility for legacy platform sustainment.
- Defense Contractors:Lockheed Martin, Raytheon, and Northrop Grumman bundle propellant supply with missile system contracts under multi-year strategic sourcing agreements. This buyer concentration displaces independent propellant houses from tactical missile procurement.
- Armed Forces:Direct procurement of artillery propellants follows NATO standardization office specifications for interoperability. U.S. Army ammunition plants maintain government-owned, contractor-operated production for strategic reserve.
- Missile Manufacturers:Specialized producers of tactical rockets and loitering munitions source propellants through developmental contracts with qualification milestones. Hybrid motor infrastructure investments differentiate suppliers in this segment.
- Ordnance Suppliers:Legacy ammunition contractors sustain artillery propellant output for allied military sales and reserve stockpile rotation. REACH compliance deadlines force reformulation investments to maintain cross-border transfer eligibility.
Defense contractors dominate forward procurement through integrated system awards. Ordnance suppliers retain residual volume in legacy platform sustainment and allied military sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European nitrocellulose synthesis capacity clusters in Germany and France, creating single-point vulnerability for NATO artillery propellant supply chains. This geographic concentration forces defense planners to prioritize supply security alongside performance specifications.
United States
Hypersonic weapons programs and artillery replenishment cycles drive procurement of advanced nitramine formulations. The Department of Defense's insensitive munitions specifications mandate extended-range precision requirements. Utah and Tennessee host government-owned, contractor-operated production facilities for strategic reserve propellants.
Germany
Rheinmetall AG anchors European artillery propellant output through scaled nitramine production. ECHA REACH restrictions on nitrosamine precursors force reformulation investments ahead of compliance deadlines. The Lower Saxony chemical corridor concentrates nitrocellulose synthesis capacity serving NATO standardization protocols.
France
Eurenco maintains integrated energetic materials production for guided munitions and rocket motor applications. ANSM and ECHA jointly govern environmental discharge and cross-border transfer protocols. The Saint-Etienne ordnance cluster specializes in minimum-signature propellants for tactical missile systems.
United Kingdom
BAE Systems leverages in-house nitrocellulose synthesis to secure raw material continuity across European supply chains. UK REACH alignment with EU restrictions drives alternative binder qualification programs. The Glascoed Royal Ordnance facility sustains government-owned production for allied military sales.
Norway
Nammo AS specializes in minimum-signature propellants competing on thermal signature reduction for guided munitions. Norwegian defense procurement prioritizes low-smoke formulations for crew survivability in rocket launcher applications. The Raufoss industrial park concentrates energetic materials research and production.
Military Propellants Market Competitive Landscape
Concentration sits with integrated defense contractors bundling propellant supply with missile system contracts under multi-year strategic sourcing agreements. This buyer consolidation displaces independent propellant houses from tactical missile procurement. Three archetypes dominate: prime contractors assuming formulation risk, government-owned facilities sustaining strategic reserve production, and specialized ordnance suppliers serving legacy platform sustainment. Competitive dynamics center on backward integration into raw material synthesis and qualification timeline acceleration for insensitive munitions certification.
Among North American prime contractors, Northrop Grumman Corporation and Raytheon Technologies Corporation exemplify the integrated system award archetype. European specialists occupy differentiated positions, with Rheinmetall AG representing scaled nitramine production capabilities and Nammo AS exemplifying minimum-signature formulation expertise. These companies anchor competitive positioning around materials science capabilities rather than scale economics alone.
| Leading Market Players |
|---|
| Northrop Grumman Corporation |
| General Dynamics Corporation |
| BAE Systems |
| Raytheon Technologies Corporation |
| Rheinmetall AG |
| Lockheed Martin Corporation |
| Nammo AS |
| Eurenco |
| MAXAM Corp |
| Others |
Pricing and Supply Chain Analysis
Nitramine substitution for legacy nitrocellulose formulations in NATO artillery propellants simultaneously redraws European supply geography and compresses pricing economics across contractor tiers. REACH-mandated reformulation investments cascade through German and French synthesis clusters, forcing price realignment between incumbent nitrocellulose suppliers and emerging nitramine-qualified competitors bidding for U.S. Army replenishment contracts.
Pricing Analysis
Three-tier pricing structure across insensitive munitions-certified, standard military-grade, and developmental propellant levels governs contractor procurement. Price differentiation hinges on IM compliance certification tier and backward integration into nitrocellulose or nitramine synthesis. Pricing pressure stems from ammonium perchlorate cost volatility in chlor-alkali cycles. Defense contractors with captive raw material supply exhibit lowest price sensitivity; independent ordnance suppliers face acute margin compression during oxidizer price spikes.
Supply Chain Analysis
Inbound logistics costs for nitrocellulose feedstock spike when Rhine waterway congestion delays barge delivery to German Lower Saxny chemical corridor plants. Supply concentrates in Germany, France, and the United States for NATO-standard propellants. Raw material dependencies rest on cotton linters for nitrocellulose, chlor-alkali-derived ammonium perchlorate, and specialized nitramine precursors. Single-source vulnerability pervades European nitrocellulose synthesis. Distribution runs through prime contractor integrated agreements displacing spot-market transactions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Military propellants trace a cyclical recovery arc driven by NATO artillery replenishment cycles following sustained drawdowns. Procurement velocity accelerates as defense agencies prioritize insensitive munitions modernization alongside hypersonic weapons qualification timelines.
For Market Incumbents: Shield formulation expertise through accelerated IM certification pipelines that compress 18-24 month qualification windows. Lock in multi-year strategic sourcing agreements with U.S. Department of Defense prime contractors to preempt hybrid propellant entrants from capturing loitering munitions development contracts. Prioritize backward integration into domestic nitramine synthesis under DoD industrial base incentives. For New Entrants and Emerging Players: Hybrid motor test infrastructure gaps in incumbent solid-propellant suppliers open white-space in throttleable tactical missile development. Target U.S. loitering munitions and reusable target system programs where solid-motor incumbents lack responsive thrust modulation capabilities. Enter through qualification partnerships with missile manufacturers seeking alternatives to bundled prime contractor propellant supply. For Investors and Strategic Acquirers: The market sits at an early-cycle expansion phase that favors materials science specialists with IM certification infrastructure over scale-commoditized incumbents. Five-to-ten year viability hinges on qualification timeline acceleration capabilities. Acquisition targets should demonstrate captive nitramine or nitrocellulose synthesis and active hypersonic propellant R&D pipelines. Watch for ECHA REACH enforcement actions against non-compliant European suppliers as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nitramine Synthesis | Captive supply secures DoD preferential qualification status for strategic hypersonic programs. |
| Insensitive Munitions Certification Acceleration | Compressed 18-24 month timelines differentiate contractors in next-generation artillery procurement. |
| Hybrid Motor Test Infrastructure Investment | Development contracts for loitering munitions shift volume from solid-propellant incumbents. |
| REACH-Compliant Binder Qualification | Alternative formulations maintain EU cross-border transfer eligibility under ECHA restrictions. |
| Multi-Year Strategic Sourcing Agreements | Prime contractor bundling displaces independent propellant houses from tactical missile revenue. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of U.S. Department of Defense contract announcements, ECHA regulatory filings, and NATO standardization office specifications. Interviews with propellant formulation chemists, missile system procurement officers, energetic materials plant managers, and defense contractor supply chain directors informed demand-side validation. Secondary sources include SEC 10-K disclosures from listed defense primes, customs trade data on nitrocellulose and nitramine shipments, and Army Ammunition Plant production reports. Bottom-up volume estimates triangulate against top-down military expenditure allocation models.
Segmentation dimensions modeled encompass propellant physical state, chemical technology tier, platform application, and end-user contract structure across the projection horizon. CAGRs derive from production capacity buildout schedules, qualification timeline distributions, and procurement award velocity analysis. Industry-specific forecast inputs incorporate DoD insensitive munitions specification adoption curves and ECHA REACH compliance deadline impacts on European supply capacity.
Underlying assumptions cover sustained NATO artillery replenishment funding, stable chlor-alkali industry ammonium perchlorate supply, and incremental IM specification adoption rates, with deviation risk concentrated in REACH enforcement stringency and hypersonic program funding volatility. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Petrochemicals
Oman Pyrolysis Gasoline Market
Petrochemicals
Propylene Market
Petrochemicals
Fossil Fuel-Based Plastics Market
Petrochemicals
Alkylate Market
Petrochemicals
Propane Market
Petrochemicals
Anthracene Oil Market
Petrochemicals
Pentaerythritol Market
Petrochemicals
Olefin Derivatives Market
Petrochemicals
Synthetic and Biobased Butadiene Market
Petrochemicals
Aliphatic Hydrocarbon Market
Petrochemicals
Global Butadiene Market
Petrochemicals
Pentane Market
Petrochemicals
Flame-Retardant Polypropylene (PP) Market
Petrochemicals
Malaysia Chemical and Petrochemical Market
Petrochemicals
Global Polypropylene Market
Petrochemicals
Tert Butyl Hydroperoxide Market