
 Sodium Potassium Tartrate Market | 2026-2036
Sodium Potassium Tartrate Market Size, Share, and Industry Trends Forecast 2026-2036
Sodium Potassium Tartrate Market Analytics
Biocatalytic processing is tilting production economics toward enzymatic synthesis routes that reduce thermal energy inputs and improve optical purity yields. Merck sustains R&D intensity in high-purity crystallization protocols for laboratory-grade supply. Tártaros Gonzalo Castelló anchors Spanish wine-lees sourcing networks that dominate European raw material flows. Anhui Aibo leverages integrated tartaric acid refining capacity to control cost positions across powder and crystalline forms.
Sodium potassium tartrate, also known as Rochelle salt, is a double salt of tartaric acid with the formula KNaC₄H₄O₆·4H₂O, typically manufactured through neutralization of tartaric acid with sodium and potassium carbonates followed by controlled crystallization. It functions primarily as a sequestrant, pH buffer, and chiral reagent across food preservation, pharmaceutical formulation, and analytical chemistry applications. Food Grade supply dominates volume flows as tartar control applications in baking and wine stabilization absorb consistent procurement, while Pharmaceutical Grade commands margin concentration due to USP and EP compliance burdens on injectable and oral dosage formulations. Powder form leads industrial logistics for bulk chemical distribution, though crystalline variants capture premium positioning in laboratory and diagnostic reagent channels where particle uniformity affects dissolution kinetics.
REACH registration requirements in Europe and FDA food additive regulations in the United States constrain market access for non-compliant producers, elevating testing and documentation costs that filter through to end-user pricing. China's SAMR and NMPA alignment with ICH Q3D elemental impurity guidelines is reshaping pharmaceutical-grade specifications for Asian supply. Stakeholders must monitor regulatory divergence between pharmacopeial standards and food-grade additive codes as dual-use classification risks intensify compliance complexity for cross-border shipments.
Market Dynamics
Biocatalytic processing is restructuring sodium potassium tartrate production economics by displacing thermal crystallization with enzymatic synthesis routes that cut energy inputs and boost optical purity yields.
Growth Catalysts
- Clean-label preservation mandate:Food manufacturers across the European Union are reformulating with natural sequestrants as EFSA scrutiny intensifies on synthetic additive portfolios.
- Pharmaceutical-grade specification convergence:China's NMPA alignment with ICH Q3D elemental impurity guidelines is expanding compliant supply capacity for injectable formulations.
- Wine-lees valorization infrastructure:Spanish and Italian tartaric acid recovery networks are securing raw material flows for double-salt crystallization at scale.
Market Restraints
- Input cost volatility:Tartaric acid spot prices fluctuate with grape harvest yields and wine industry cyclicality, compressing margin predictability for crystalline grade producers.
- Supply concentration risk:European wine-lees sourcing dominates raw material flows, creating geographic single-point vulnerability for non-integrated manufacturers.
- Regulatory friction:REACH registration requirements in Europe elevate testing and documentation burdens that filter through to end-user pricing for laboratory-grade supply.
Strategic Opportunities
- Underpenetrated diagnostic reagent channels:Clinical chemistry laboratories in India and Southeast Asia are expanding chiral reagent procurement as domestic pharmaceutical analysis capacity scales.
- Regulatory tailwind:The EU Green Deal is accelerating funding for bio-based chemical processes that reduce thermal energy intensity in tartaric acid derivative production.
- Technology convergence:Continuous crystallization systems combined with inline optical purity monitoring are enabling real-time process control for pharmaceutical-grade specifications.
Industry Challenges
- Specialized talent scarcity:Chiral chemistry expertise and biocatalytic process engineering skills are concentrated among legacy tartaric acid specialists, constraining workforce expansion for new market entrants.
- Dual-use classification complexity:Cross-border shipments face heightened customs scrutiny when product codes span food additive and pharmaceutical reagent classifications, extending clearance timelines.
- Capex intensity for compliance:USP and EP certification requires dedicated cleanroom crystallization suites and validated analytical infrastructure that locks up capital for smaller producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sodium Potassium Tartrate Market |
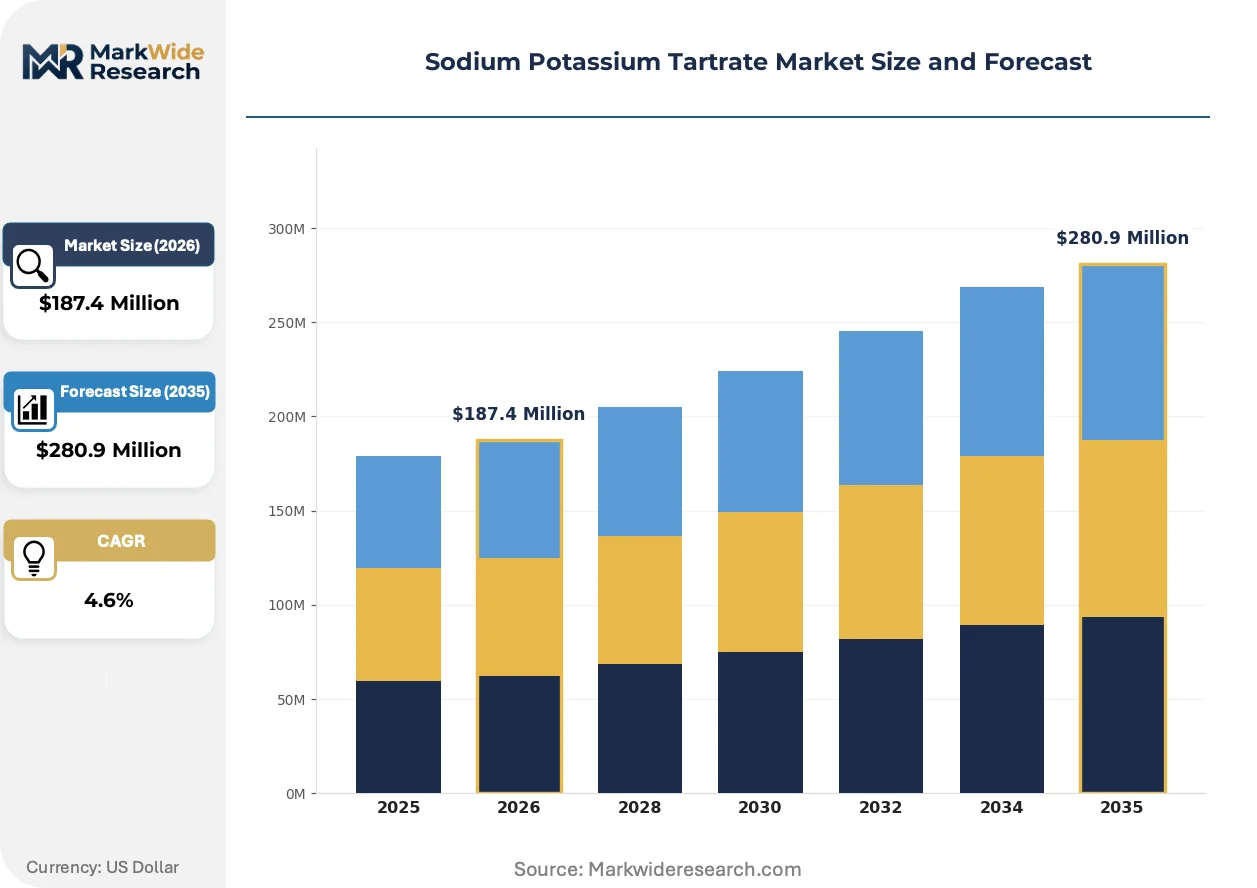
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $280.9 Million |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food Grade, Pharmaceutical Grade, Industrial Grade, Laboratory Grade Application: Food Preservative, Tartar Control, Electrolyte Management, Pharmaceutical Formulation End User: Food Industry, Healthcare Providers, Research Institutions, Chemical Manufacturers Form: Powder, Crystalline, Granular, Liquid |
| Companies Covered | Tártaros Gonzalo Castelló, Pahí, Merck, BEANTOWN CHEMICAL, Hach, Novarina, Randi Group, Anhui Aibo, ATPGroup, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sodium Potassium Tartrate Market Evolving Landscape
Enzymatic synthesis routes and continuous processing architectures are displacing batch thermal crystallization as the dominant production paradigm, reshaping capital deployment and competitive positioning across grade tiers.
Membrane-assisted crystallization is virtualizing traditional evaporative concentration steps by replacing thermal energy inputs with selective permeation separation. Pharmaceutical manufacturers in Germany and Switzerland are piloting these systems for high-purity Rochelle salt production. This technology is virtualizing the energy cost structure that previously favored large-scale integrated producers.
REACH authorization timelines are tightening for tartaric acid derivatives used in food contact applications, forcing reformulation documentation and extended safety dossier preparation. The European Chemicals Agency's evolving substance evaluation criteria are elevating purity thresholds for sequestrant-grade supply. Food additive distributors are consolidating supplier bases to reduce compliance audit burden.
Diagnostic laboratories are unbundling reagent procurement from instrument service contracts, creating direct purchasing relationships with specialty chemical distributors. This pattern is compressing traditional channel margins for bundled supply arrangements. The shift is most visible in North American and Western European clinical chemistry markets where laboratory consolidation has concentrated buying power.
Sodium Potassium Tartrate Market Segmentation
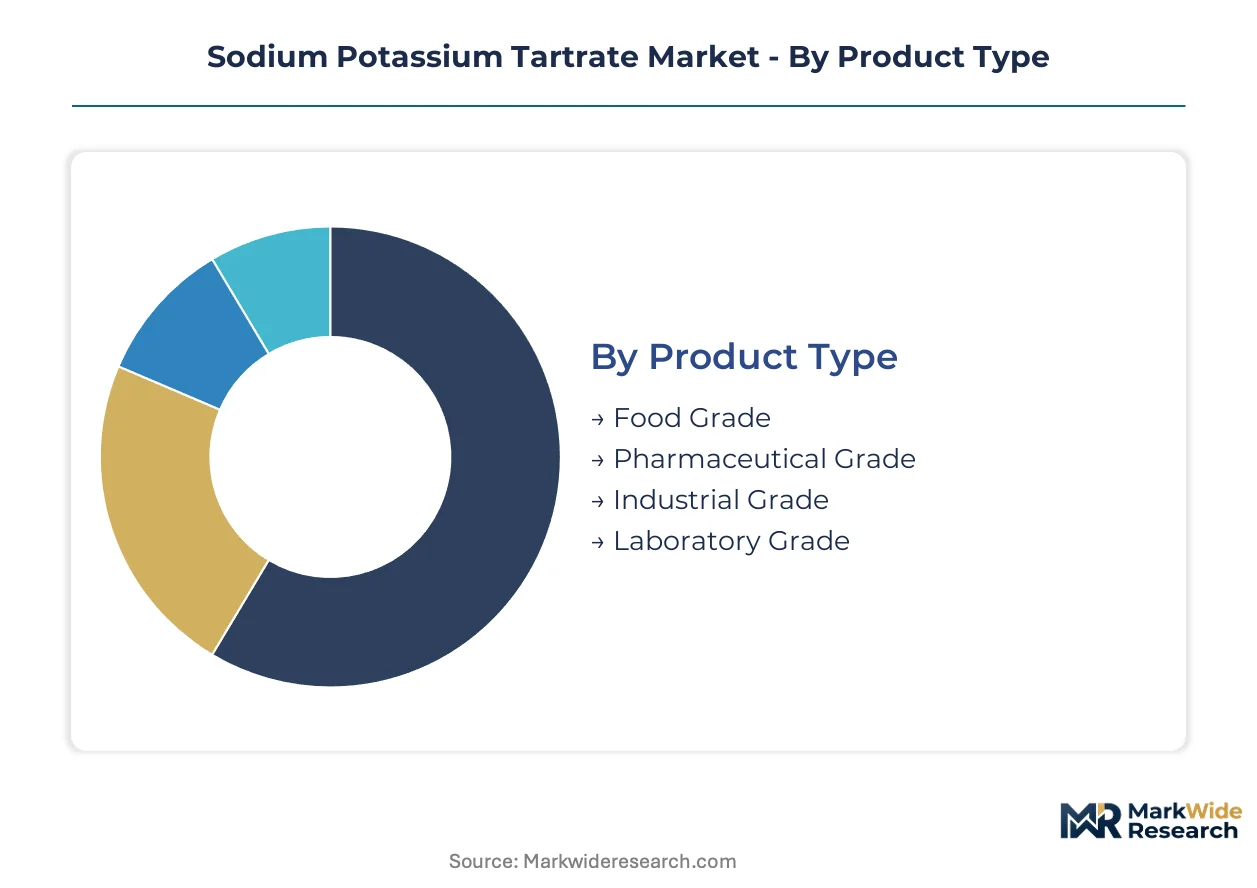
Sodium potassium tartrate supply stratifies sharply across purity tiers, with regulatory classification determining accessible end-use markets and margin structures. Grade-specific certification requirements create hard boundaries between food additive, pharmaceutical, and laboratory channels that reshape competitive positioning.
Product Type:
The maturity spectrum runs from established food-grade commoditization to emerging laboratory-grade precision manufacturing.
- Food Grade:Standardized sequestrant purity for baking powder and wine stabilization applications. Food manufacturers in Italy and France absorb consistent procurement volumes as clean-label reformulation accelerates under EFSA additive scrutiny.
- Pharmaceutical Grade:USP and EP-compliant specifications for injectable and oral dosage formulations. China's NMPA alignment with ICH Q3D guidelines is expanding compliant capacity for domestic pharmaceutical formulation scaling.
- Industrial Grade:Lower-purity material for electroplating and metal finishing operations.
- Laboratory Grade:Ultra-high purity for analytical chemistry and chiral synthesis reagents.
Food Grade handles the majority of throughput; Laboratory Grade is climbing the fastest on share.
Application:
Cost tier differentiation separates commodity food preservation from premium pharmaceutical channels.
- Food Preservative:Sequestrant function in processed foods and beverages requiring pH stabilization. European Union manufacturers are expanding procurement as synthetic additive replacement mandates intensify under EFSA evaluations.
- Tartar Control:Baking powder acidulant and wine stabilization agent. Spanish and Italian wine-lees recovery networks secure raw material flows for this mature application segment.
- Electrolyte Management:Specialized buffering in industrial processes and laboratory settings.
- Pharmaceutical Formulation:Excipient and active ingredient in oral and parenteral dosage forms.
Tartar Control anchors volume flows; Pharmaceutical Formulation shows the steepest expansion trajectory.
End User:
Customer type determines procurement pattern complexity from bulk chemical distribution to validated supply agreements.
- Food Industry:Large-scale manufacturers of baking ingredients and processed foods. Clean-label preservation mandates across Germany and the Netherlands are reshaping supplier qualification requirements.
- Healthcare Providers:Hospital systems and compounding pharmacies requiring pharmaceutical-grade supply. India's CDSCO is tightening documentation standards for imported excipient materials.
- Research Institutions:Universities and analytical laboratories with precise specification demands.
- Chemical Manufacturers:Downstream processors integrating Rochelle salt into specialty chemical production.
Food Industry commands the largest procurement base; Research Institutions are gaining share fastest.
Form:
Supply concentration in powder production contrasts with crystalline premium positioning.
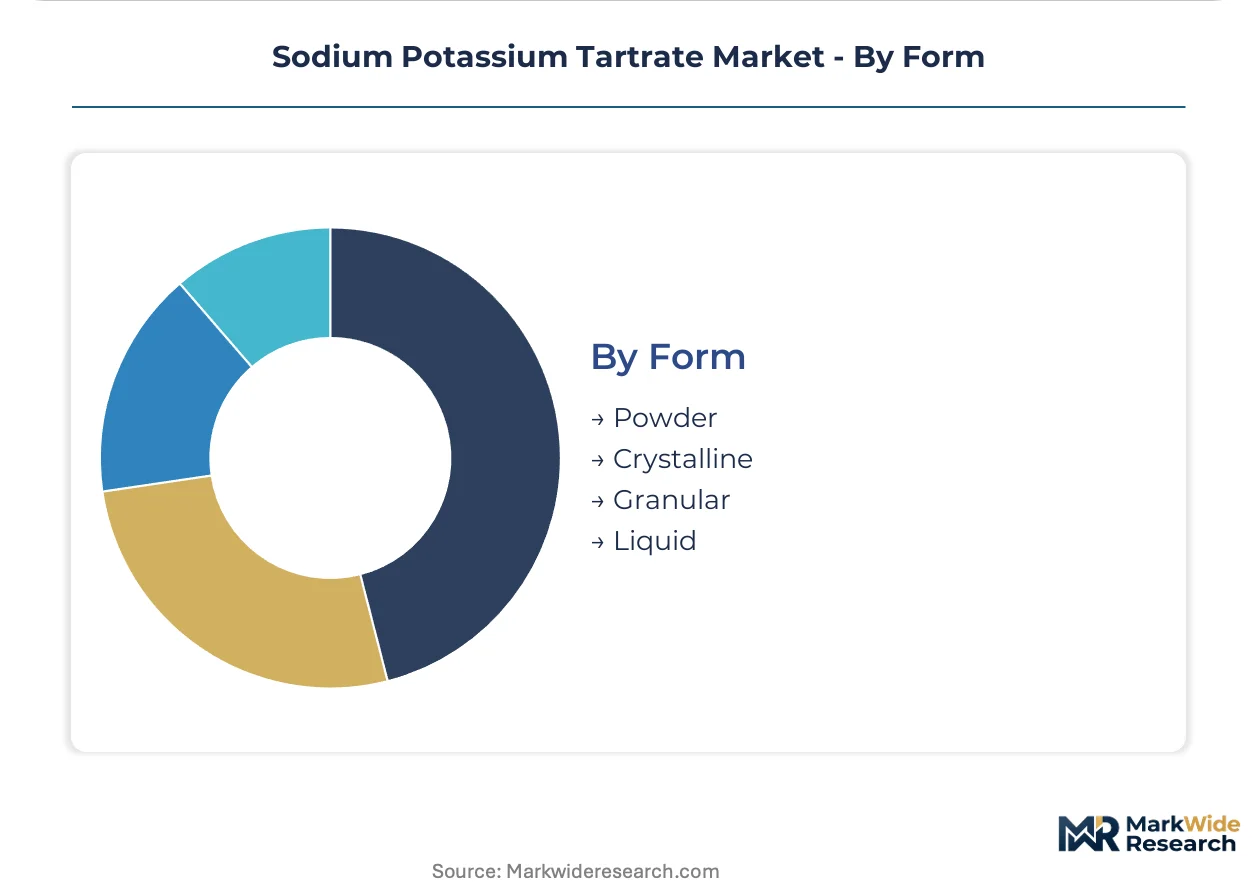
- Powder:Milled material optimized for bulk handling and rapid dissolution in food processing. Industrial logistics networks across China and India prioritize powder form for cost-efficient distribution.
- Crystalline:Controlled particle size for laboratory reagent and pharmaceutical excipient applications. German and Swiss pharmaceutical manufacturers specify crystalline grades for dissolution kinetics consistency.
- Granular:Intermediate particle size for reduced dusting in industrial handling.
- Liquid:Pre-dissolved solutions for automated dosing systems in beverage manufacturing.
Powder handles the majority of throughput; Crystalline is expanding most quickly on share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Spanish wine-lees recovery networks supply tartaric acid feedstock to pharmaceutical formulators in Germany and Switzerland, while Chinese integrated producers scale crystalline-grade output for domestic excipient demand.
Spain
Wineries in La Rioja and Catalonia operate tartaric acid recovery infrastructure that dominates European raw material flows for double-salt crystallization. EFSA additive scrutiny under the EU Green Deal is accelerating clean-label reformulation mandates for sequestrant-grade supply. Tarragona chemical processors concentrate crystallization capacity for food-grade export to France and Italy.
China
Domestic pharmaceutical formulation activity in Jiangsu and Zhejiang provinces is scaling procurement of USP-compliant crystalline grades for injectable dosage production. NMPA alignment with ICH Q3D elemental impurity guidelines is tightening purity thresholds for excipient-grade supply. Anhui province hosts integrated tartaric acid refining clusters that control cost positions across powder and crystalline forms.
Germany
Specialty chemical distributors in Baden-Württemberg and North Rhine-Westphalia are consolidating laboratory-grade procurement channels for diagnostic reagent manufacturers. REACH registration requirements and ECHA substance evaluation timelines are elevating documentation burdens for imported tartaric acid derivatives. Ludwigshafen chemical parks pilot membrane-assisted crystallization systems for pharmaceutical-grade Rochelle salt production.
India
CDSCO documentation standards for imported excipient materials are tightening qualification requirements for pharmaceutical-grade supply to Maharashtra and Gujarat formulation clusters. Domestic baking powder manufacturers in Tamil Nadu absorb consistent food-grade procurement volumes. Hyderabad analytical chemistry laboratories are expanding chiral reagent procurement as domestic pharmaceutical analysis capacity scales.
United States
FDA food additive regulations constrain market access for non-compliant tartaric acid derivative producers, elevating testing costs that filter through to end-user pricing. Diagnostic laboratories in Massachusetts and North Carolina are unbundling reagent procurement from instrument service contracts. New Jersey chemical distributors manage validated supply agreements for pharmaceutical-grade crystalline forms.
Sodium Potassium Tartrate Market Competitive Landscape
On the supply side, the industry is bifurcated between integrated wine-lees processors and specialty chemical distributors, with concentration in European raw material sourcing creating tiered access to crystalline-grade capacity. Strategic archetypes span backward-integrated tartaric acid refiners, laboratory-grade precision manufacturers, and regional food-additive distributors. Competitive moves center on wine-lees sourcing network consolidation and continuous crystallization technology licensing.
Among Spanish wine-lees processors, Tártaros Gonzalo Castelló exemplifies the backward-integrated archetype, while Merck occupies a position in the laboratory-grade precision tier. Anhui Aibo represents the Asian integrated refining model. These three anchors illustrate how geographic concentration in raw material sourcing and certification-grade manufacturing creates distinct competitive positions across the value chain.
| Leading Market Players |
|---|
| Tártaros Gonzalo Castelló |
| Pahí |
| Merck |
| BEANTOWN CHEMICAL |
| Hach |
| Novarina |
| Randi Group |
| Anhui Aibo |
| ATPGroup |
| Others |
Value Network & Pricing Analysis
Undercapacity in European wine-lees processing is elevating tartaric acid spot volatility and forcing crystalline-grade producers toward long-term offtake contracts with Spanish refiners. This utilization squeeze transmits directly into margin compression for non-integrated manufacturers while rewarding backward-integrated players with captive raw material access.
Pricing Analysis
The thermal-crystallization versus enzymatic-synthesis pricing gap separates legacy batch producers from biocatalytic entrants, with pharmaceutical-grade crystalline forms commanding three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on USP/EP certification status and optical purity yields, with REACH-registered European supply capturing brand premiums over unregistered Asian imports. Cost compression in food-grade powder is intensifying because grape harvest cyclicality feeds tartaric acid spot volatility. Contract manufacturers in baking and wine stabilization exhibit highest price sensitivity, while diagnostic laboratories purchasing laboratory-grade crystalline forms demonstrate lowest sensitivity due to dissolution-kinetics specifications.
Supply Chain Analysis
Contract-manufacturing concentration among Spanish wine-lees processors Tártaros Gonzalo Castelló and Italian tartaric acid refiners holds crystalline-grade capacity for European pharmaceutical formulators. Geographic supply concentrates in Spain, China, and India, with Spanish lees-recovery networks feeding German and Swiss pharmaceutical clusters while Anhui province hosts integrated refining for Asian excipient demand. Raw material dependencies center on grape-derived tartaric acid, sodium and potassium carbonate feedstocks, and enzymatic biocatalysts for optical purity enhancement. Single-source vulnerability runs through European wine-lees concentration, where climate-driven harvest failures cascade through double-salt crystallization economics. Distribution runs through specialty chemical distributors managing validated supply agreements for pharmaceutical-grade tiers and bulk commodity channels for food-grade powder.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Laboratory consolidation across North American and Western European clinical chemistry markets is shifting procurement power toward consolidated buyers unbundling reagent procurement from instrument service contracts.
For Market Incumbents: Pre-empt biocatalytic displacement by licensing continuous crystallization systems with inline optical purity monitoring before enzymatic synthesis routes achieve cost parity. Secure wine-lees sourcing networks through long-term offtake agreements with La Rioja and Catalonia refiners to defend against tartaric acid spot volatility. Certification investment in NMPA-aligned ICH Q3D compliance for Chinese pharmaceutical-grade supply represents the critical defensive lever against domestic integrated producers. For New Entrants and Emerging Players: Pursue underpenetrated diagnostic reagent channels in Indian and Southeast Asian clinical chemistry laboratories where chiral reagent procurement is expanding with domestic pharmaceutical analysis capacity. Target pharmaceutical-grade crystalline supply to Hyderabad analytical clusters and Maharashtra formulation hubs as the most penetrable geography. Establish direct purchasing relationships with unbundled laboratories rather than competing through bundled instrument service contracts. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among laboratory-grade precision manufacturers serving diagnostic reagent channels with dissolution-kinetics specifications. Long-term viability over the five-to-ten year window favors integrated tartaric acid refiners with captive wine-lees access and enzymatic synthesis capabilities. Acquisition targets should center on Spanish wine-lees processors with uncontracted crystalline-grade capacity. The signal to watch is NMPA enforcement timelines for ICH Q3D elemental impurity compliance, which will determine which Asian excipient suppliers retain pharmaceutical-grade market access.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Wine-Lees Recovery | Captive tartaric acid supply from La Rioja wineries insulates margin from harvest cyclicality. |
| Continuous Crystallization Technology Licensing | German pharmaceutical manufacturers pilot membrane-assisted systems for real-time USP-grade process control. |
| NMPA ICH Q3D Compliance Certification | Elemental impurity guideline alignment unlocks injectable excipient supply to Jiangsu formulation clusters. |
| Diagnostic Reagent Channel Direct Access | Unbundled procurement from Massachusetts laboratories compresses traditional distributor margins. |
| Biocatalytic Synthesis Route Scale-Up | Enzymatic displacement of thermal crystallization cuts energy intensity for EU Green Deal funding eligibility. |
Research Methodology
Desk research of customs and trade databases, SEC and ECHA regulatory filings, and pharmaceutical excipient pharmacopeia preceded structured interviews with tartaric acid plant managers, pharmaceutical procurement leads at German and Swiss formulators, specialty chemical distribution channel partners, and CDSCO regulatory affairs directors. Primary fieldwork combined with secondary validation from FDA food additive regulations, REACH registration databases, and NMPA ICH Q3D guidance documents. Bottom-up volume modeling across grade tiers and top-down value reconciliation anchored forecast triangulation.
Forecast assumptions held fixed the current regulatory divergence between USP/EP pharmacopeial standards and food-grade additive codes, while varying enzymatic synthesis adoption rates and wine-lees recovery capacity utilization across the projection horizon. Segmentation dimensions modeled include grade tier certification, end-use application, crystalline versus powder form, and regional production hub clustering. CAGRs derived from regression against pharmaceutical formulation scaling and clean-label food preservation procurement trends, with tartaric acid spot price volatility and REACH authorization timelines as industry-specific forecast inputs.
Sensitivities concentrate around grape harvest yields, NMPA enforcement intensity for elemental impurity compliance, and biocatalytic process economics achieving cost parity with thermal crystallization. Quarterly review of tartaric acid spot pricing, ECHA substance evaluation timelines, and diagnostic laboratory procurement unbundling indicators is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Octane Improver Fuel Additives Market
Additives
Citric Acid Market
Additives
Europe Anti-Caking Market
Additives
PVC Plasticizers and Stabilizers Market
Additives
Extrusion Aids Market
Additives
Low-Carbon Concrete Shrinkage-Reduction Additives Market
Additives
Agrochemicals Additives Market
Additives
Global UV Absorbers Market
Additives
Wax Additives Market
Additives
Phthalate and Non-Phthalate Plasticizers Market
Additives
Iso-Butyric Acid Market
Additives
Global Propyl Acetate Market
Additives
Crystal Growth Modifier Market
Additives
Global Pour Point Depressant Market
Additives
Organic Friction Modifier Additives Market
Additives
Indonesia Feed Additives Market