
 Wax Additives Market | 2026-2036
Wax Additives Market Size, Share, and Industry Trends Forecast 2026-2036
Wax Additives Market Outlook
Specialty chemical distribution networks serving coatings formulators is reshaping how wax additives reach end-users in fragmented regional markets. BASF SE leverages its integrated polymer-wax portfolio to control specification-setting relationships with large coatings producers. Honeywell International Inc. competes through synthetic wax technology leadership in high-performance polyethylene grades. Clariant anchors Southern European supply through specialized micronized wax production.
Wax additives comprise refined hydrocarbon or natural ester-based materials blended at 0.5-10% loading to modify surface properties, rheology, and abrasion resistance in industrial formulations. Synthetic wax, particularly oxidized polyethylene types, commands premium positioning due to controlled molecular weight distribution and thermal stability. Natural wax segments face margin compression from supply variability, while powder and granule forms dominate coatings and plastics processing where dust control and metering precision matter. Liquid wax emulsions represent the fastest-growing form segment in water-based ink and adhesive systems.
EPA VOC regulations and REACH substance restrictions are tightening permissible solvent content in coatings and inks, directly accelerating water-borne wax emulsion demand. China's MEE enforcement of GB standards on industrial emissions and India's BIS certification requirements for construction chemicals are reshaping product qualification pathways. Stakeholders must monitor regulatory divergence between jurisdictions to avoid reformulation costs and secure multi-region market access.
Market Dynamics
Water-borne coating formulation mandates across industrial manufacturing are compressing solvent-borne wax additive demand while expanding emulsion-grade procurement. EPA VOC rules and China's GB standards are forcing simultaneous reformulation across multiple continents.
Growth Catalysts
- GB Standard Enforcement:China's MEE is accelerating industrial coating reformulation toward water-borne systems, expanding oxidized polyethylene wax emulsion procurement from domestic and imported suppliers.
- Construction Chemical Certification:India's BIS requirements for infrastructure-grade coatings are redirecting formulator procurement toward certified natural-synthetic wax blends with documented thermal stability.
- Polyethylene Wax Technology:Controlled molecular weight distribution in synthetic grades is enabling thinner film builds with equivalent abrasion resistance, penetrating automotive OEM clearcoat specifications.
Market Restraints
- Petrochemical Feedstock Volatility:Ethylene and Fischer-Tropsch feedstock costs for synthetic wax production fluctuate with crude oil benchmarks, compressing margin predictability for oxidized polyethylene grades.
- Natural Wax Supply Concentration:Carnauba wax availability depends on Brazilian harvest cycles and climate patterns, creating formulation continuity risks for coatings producers requiring consistent ester profiles.
- REACH Registration Burden:ECHA substance registration costs and data requirements for novel wax chemistries are extending commercialization timelines for European specialty additive launches.
Strategic Opportunities
- India Industrial Corridor Expansion:Dedicated freight corridors and smart city infrastructure are generating concentrated demand for durable road-marking and protective coatings requiring high-performance wax modifiers.
- Bio-Based Emulsion Convergence:Fermentation-derived wax precursors combined with water-borne dispersion technology are opening premium positioning for carbon-accounted coating formulations.
- PLI Scheme Alignment:India's production-linked incentive framework for specialty chemicals is attracting greenfield wax additive manufacturing investment serving domestic coatings formulators.
Industry Challenges
- Formulation Compatibility Expertise:Water-borne wax emulsion integration with existing resin systems requires rheology specialists scarce in regional coatings laboratories outside major manufacturing clusters.
- Multi-Jurisdiction Certification Timelines:Parallel EPA, REACH, and BIS approval processes for new wax chemistries extend commercial launch windows by 18-36 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wax Additives Market |
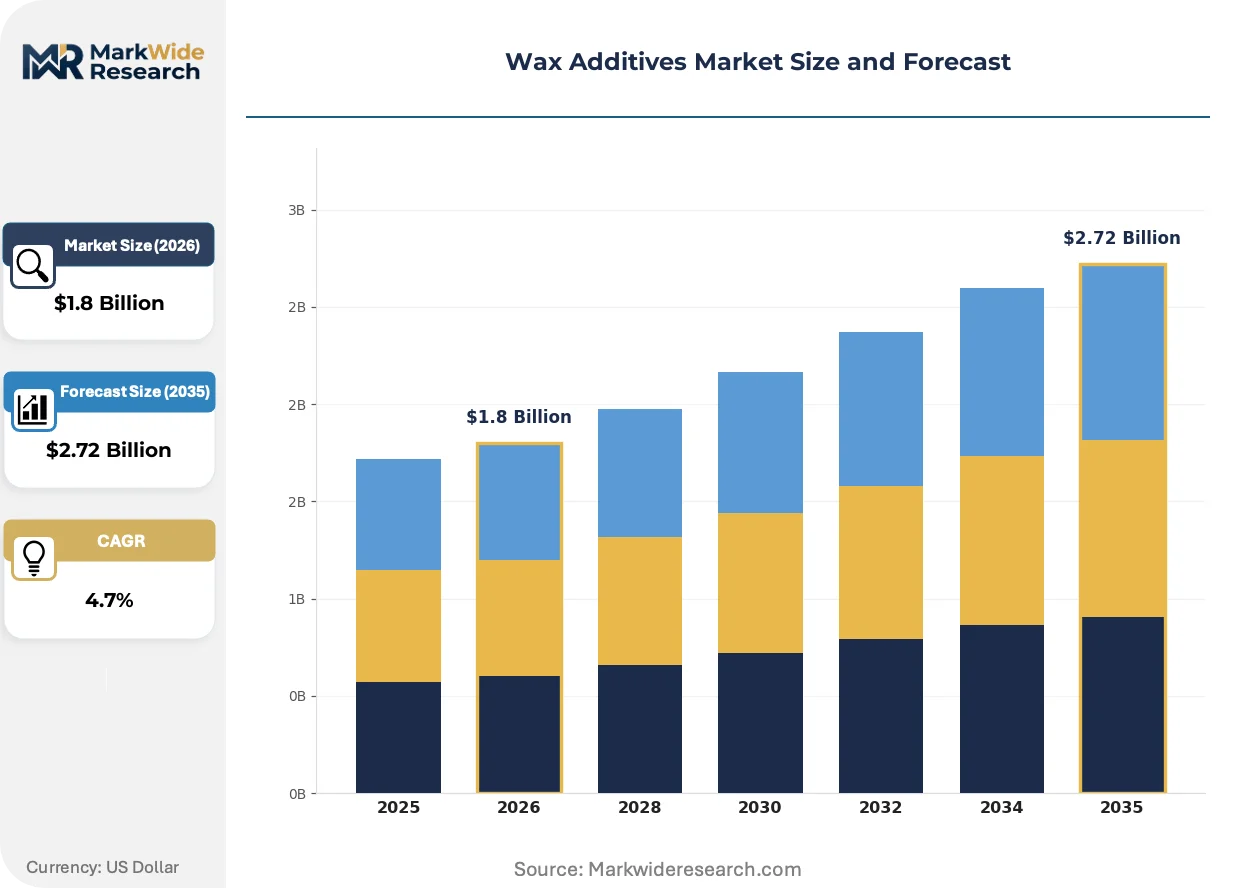
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Paraffin Wax, Microcrystalline Wax, Natural Wax, Synthetic Wax Application: Coatings, Adhesives, Plastics, Inks End Use Industry: Packaging, Automotive, Construction, Consumer Goods Form: Powder, Granule, Pellet, Liquid |
| Companies Covered | BASF SE, The Lubrizol Corporation, Arkema, Clariant, Honeywell International Inc., Sasol Limited, ExxonMobil Chemical Company, Eastman Chemical Company, Dow Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wax Additives Market Strategic Shifts
Active reformulation across coatings, inks, and adhesives is compressing legacy solvent-borne wax additive positions while elevating water-borne and bio-based alternatives. Technology suppliers are racing to match performance parity at equivalent cost structures.
Micronized synthetic wax production is collapsing traditional particle size limitations that previously separated premium coatings from commodity applications. Automotive OEM clearcoat formulators in Germany and Japan are adopting sub-10-micron polyethylene grades for scratch resistance without optical haze. This particle engineering advance is collapsing the price-performance gap between standard and specialty wax tiers.
EPA VOC regulations and REACH substance restrictions are tightening permissible solvent content thresholds in architectural and industrial coatings. Formulators must replace solvent-borne wax dispersions with water-borne emulsions or risk product disqualification from government and commercial procurement. North American and European coatings producers are accelerating emulsion qualification programs to maintain specification compliance.
Specialty chemical distributors are consolidating wax additive procurement for mid-size coatings formulators, displacing direct manufacturer relationships. Regional distributors in Asia-Pacific are building technical service capabilities to support water-borne emulsion selection and formulation troubleshooting. This channel evolution is most visible in China and India where fragmented coatings producer bases lack in-house rheology expertise.
Wax Additives Market Segmentation
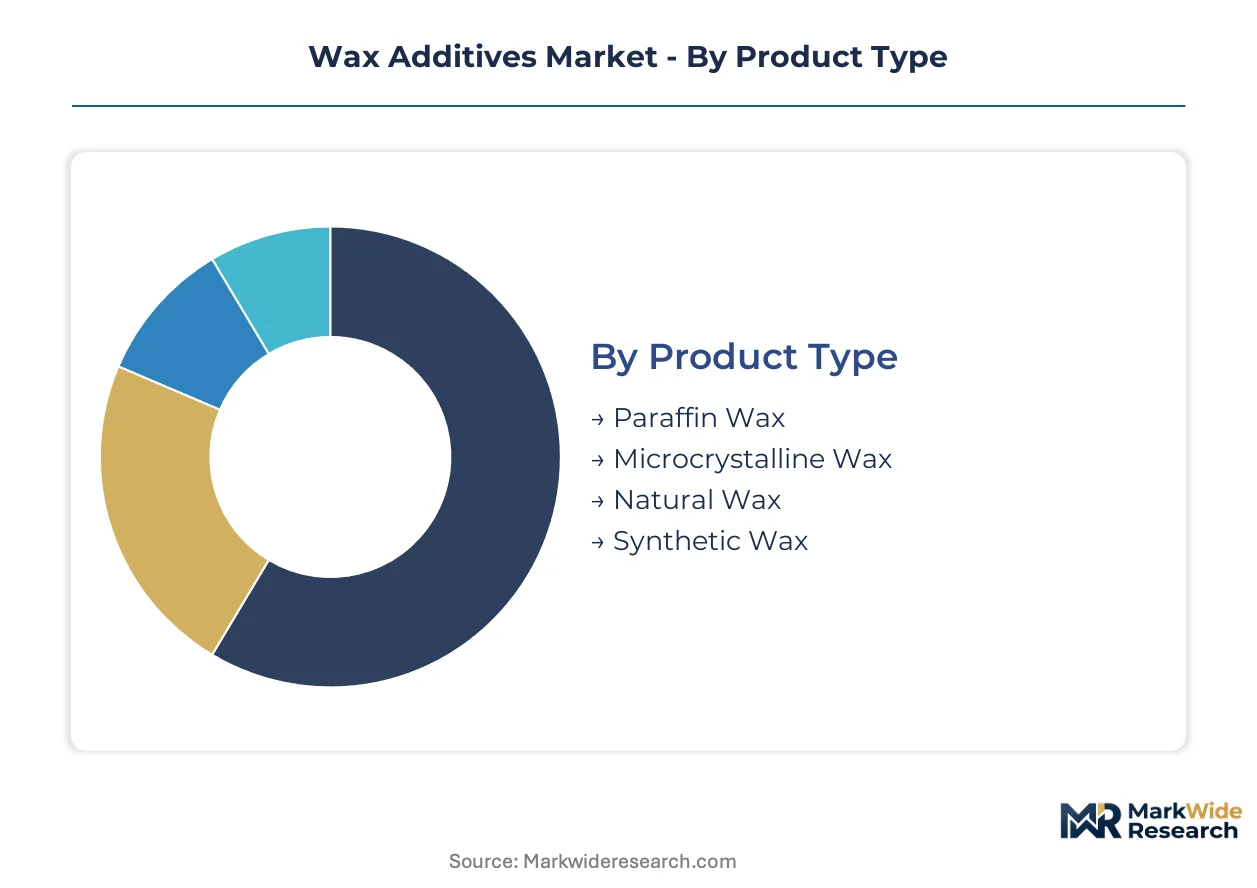
Wax additive specifications diverge sharply across end-use requirements, with thermal stability thresholds and surface modification needs dictating product selection. Formulators balance cost position against performance certification tiers when mapping procurement strategies across these segment boundaries.
Product Type:
Cost tier positioning separates commodity hydrocarbon grades from premium synthetic and natural ester alternatives, with feedstock volatility driving margin structure differentiation.
- Paraffin Wax:Refined petroleum distillate with crystalline structure and melting points between 46-68°C. Packaging coatings in India and China absorb volume through BIS-certified food-contact applications where low cost meets regulatory compliance.
- Synthetic Wax:Fischer-Tropsch and polyethylene-derived materials with controlled molecular weight distribution and superior thermal stability. Automotive OEM clearcoats in Germany and Japan specify oxidized polyethylene grades for scratch resistance without optical degradation.
- Microcrystalline Wax:Amorphous petroleum derivative with higher molecular weight and adhesive compatibility. Adhesive formulators value its tack retention and flexibility.
- Natural Wax:Carnauba, beeswax, and plant ester materials with renewable positioning. Supply concentration in Brazilian harvest regions constrains formulation continuity.
Paraffin wax holds installed capacity. Synthetic wax is rotating up the share rankings.
Application:
Application focus determines rheology modification intensity, with surface protection demands varying from decorative coatings to structural adhesives.
- Coatings:Architectural and industrial formulations requiring abrasion resistance, matting, and slip control. Water-borne architectural coatings in China face MEE-enforced GB standard reformulation, expanding oxidized polyethylene emulsion procurement.
- Plastics:Processing aids and surface modifiers for extrusion and injection molding. Polyethylene wax functions as internal and external lubricant in PVC and polyolefin compounding.
- Adhesives:Hot-melt and pressure-sensitive systems where wax controls open time and bond strength. Packaging adhesive formulators balance cost against thermal stability.
- Inks:Offset, gravure, and flexographic systems requiring rub resistance and gloss control. Liquid emulsion grades are climbing fastest in water-borne ink conversions.
Coatings maintains volume leadership. Inks is expanding most quickly through regulatory-driven emulsion adoption.
End Use Industry:
Customer type segmentation reveals divergent certification requirements, with automotive and construction formulators demanding documented thermal stability and multi-jurisdiction compliance.
- Packaging:Food-contact and corrugated board applications requiring FDA and BIS migration compliance. Paraffin and microcrystalline grades dominate cost-sensitive flexible packaging.
- Automotive:OEM clearcoats and underbody coatings with scratch resistance and weathering specifications. German and Japanese manufacturers specify sub-10-micron synthetic grades.
- Construction:Protective coatings and road-marking systems requiring durability certification. India's PLI scheme for specialty chemicals is attracting domestic wax additive manufacturing.
- Consumer Goods:Cosmetics, polishes, and candles where natural wax positioning commands premium. Carnauba supply variability constrains consistent formulation.
Packaging holds installed capacity. Construction is rotating up the share rankings through infrastructure corridor expansion.
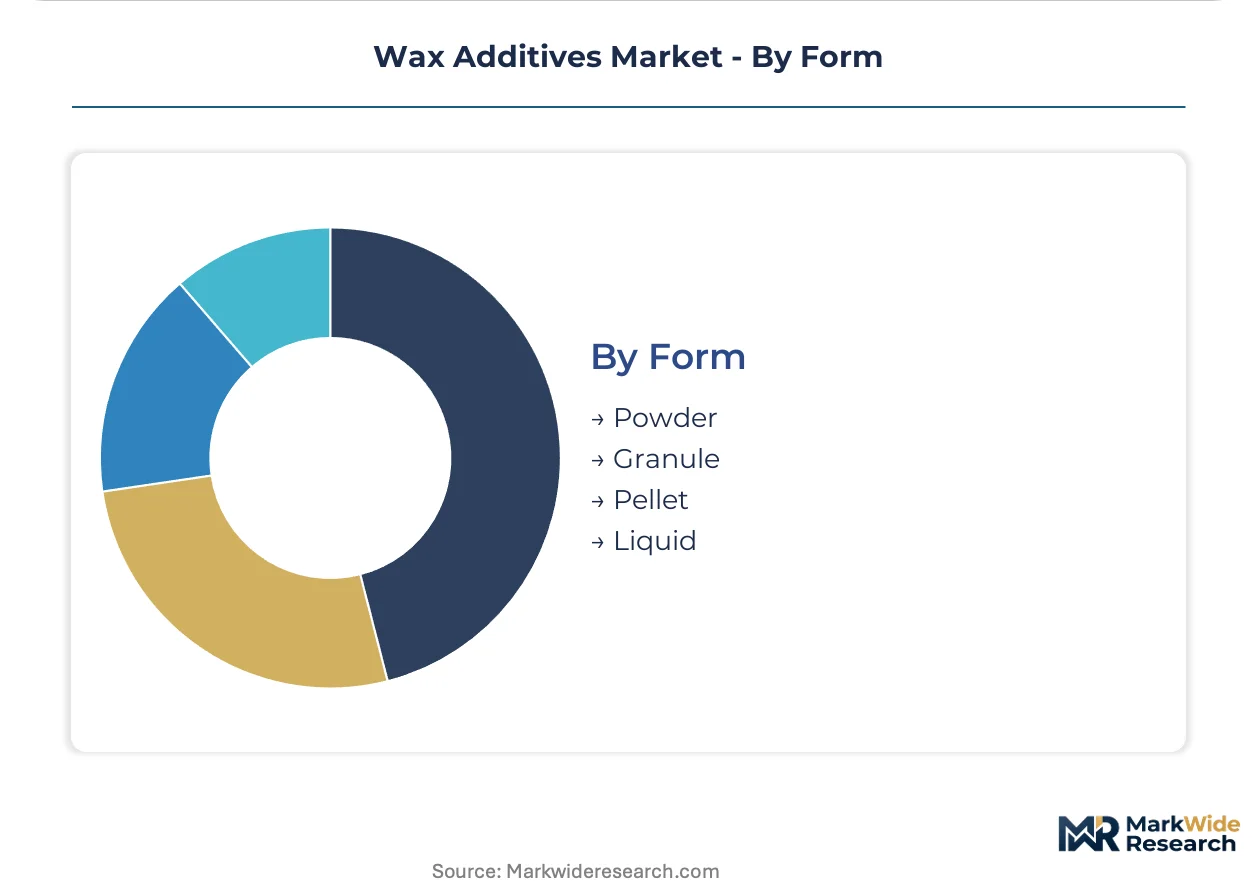
Form:
Physical form dictates processing integration method, with dust control and metering precision requirements shaping manufacturing equipment selection.
- Powder:Micronized particles below 50 microns for coatings and plastics compounding. Dust generation necessitates containment systems in high-volume processing.
- Liquid:Water-borne emulsions and solvent dispersions for ink and adhesive integration. EPA VOC regulations and REACH restrictions are accelerating displacement of solvent-borne alternatives.
- Granule:Intermediate particle size for controlled dissolution in hot-melt adhesive systems. Bulk handling efficiency favors automated dosing equipment.
- Pellet:Extruded forms for plastics compounding direct feed. Low dust generation supports continuous extrusion operations.
Powder holds installed capacity. Liquid is climbing the fastest through water-borne formulation mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates with German and Japanese formulators specifying sub-10-micron synthetic grades, while Indian and Chinese producers compete on certified natural-synthetic blend volumes. This asymmetry shapes procurement patterns across automotive OEM and infrastructure coating segments.
United States
Architectural coatings manufacturers face EPA VOC rule enforcement accelerating water-borne emulsion adoption. The agency's tightening permissible solvent content thresholds disqualify legacy solvent-borne wax dispersions from government procurement. Houston-Gulf Coast petrochemical corridors supply Fischer-Tropsch feedstock for domestic synthetic wax production serving regional formulators.
Germany
Automotive OEM clearcoat specifications drive premium oxidized polyethylene procurement from domestic and Dutch suppliers. ECHA REACH substance registration requirements extend commercialization timelines for novel wax chemistries entering European markets. The Ruhr industrial cluster hosts specialized micronized wax production facilities serving coatings formulators across Western Europe.
China
Industrial coating producers accelerate reformulation toward water-borne systems under MEE-enforced GB standards. The country's dual carbon goals pressure manufacturers toward lower-emission formulation technologies. Yangtze River Delta coatings clusters expand procurement of domestic and imported oxidized polyethylene wax emulsions.
India
Infrastructure corridor expansion generates concentrated demand for durable road-marking and protective coatings requiring high-performance wax modifiers. BIS certification requirements for construction chemicals redirect formulator procurement toward documented thermal stability grades. Gujarat and Maharashtra industrial zones attract greenfield wax additive manufacturing under PLI scheme incentives.
Japan
Automotive OEM specifications for scratch-resistant clearcoats specify controlled molecular weight distribution synthetic waxes. METI industrial standards shape qualification pathways for coating additives entering domestic supply chains. Kansai-Osaka manufacturing clusters process sub-10-micron polyethylene grades for export-oriented automotive coatings.
Wax Additives Market Competitive Environment
Integrated petrochemical conglomerates and specialized additive manufacturers split the market between scale-driven feedstock security and formulation-specific technical service. The vendor base concentrates around three strategic archetypes: diversified chemical majors controlling polymer-wax portfolios, synthetic wax technology specialists commanding premium polyethylene grades, and regional micronized production specialists serving Southern European supply. Dominant competitive moves include backward integration into Fischer-Tropsch and ethylene feedstock streams, plus geographic expansion through technical service partnerships in fragmented Asia-Pacific markets.
Within the diversified chemical major tier, BASF SE anchors integrated polymer-wax portfolio positioning with specification-setting relationships across large coatings producers. Honeywell International Inc. occupies the synthetic wax technology specialist position, particularly visible in high-performance polyethylene grade development. Clariant exemplifies the regional micronized production archetype, anchoring Southern European supply through specialized manufacturing capabilities. These three entities collectively represent the competitive structure's dominant positioning vectors without exhausting the participant base.
| Leading Market Players |
|---|
| BASF SE |
| The Lubrizol Corporation |
| Arkema |
| Clariant |
| Honeywell International Inc. |
| Sasol Limited |
| ExxonMobil Chemical Company |
| Eastman Chemical Company |
| Dow Inc. |
| Others |
Value Chain & Pricing Dynamics
Petrochemical feedstock volatility tethered to crude oil benchmarks compresses margin predictability for oxidized polyethylene grades while simultaneously determining the geographic locus of synthetic wax production. This dual dependency shapes pricing tier spreads between Fischer-Tropsch-derived premium grades and paraffin commodity positions, and concentrates supply chain investment around ethylene corridor access in the US Gulf Coast, Northwestern Europe, and coastal China.
Pricing Analysis
Configured-to-order pricing for sub-10-micron oxidized polyethylene grades commands substantial premiums over standard particle size distributions in automotive OEM clearcoat specifications. Three-tier pricing structure across premium, standard, and economy levels separates German and Japanese formulator contracts from Indian infrastructure-grade procurement and Chinese domestic coating volumes. Cost compression in paraffin segments is intensifying because Brazilian carnauba harvest variability forces natural wax buyers toward synthetic substitution. Packaging formulators in India exhibit the highest price sensitivity due to BIS certification cost absorption, while German automotive OEMs demonstrate the lowest sensitivity given specification-locked supply agreements.
Supply Chain Analysis
Tariff exposure between US and Chinese petrochemical feedstock flows dominates supply chain risk calculus for oxidized polyethylene wax emulsion producers. Manufacturing gravity centers on Germany, China, and the United States, with Fischer-Tropsch synthesis and ethylene cracking capacity anchoring synthetic wax output. Raw material dependencies rest on ethylene monomer, Fischer-Tropsch wax feedstock, and Brazilian carnauba crude. Single-source vulnerability concentrates in South American natural wax harvesting regions. Distribution runs through specialty chemical distributors consolidating procurement for mid-size coatings formulators across fragmented Asia-Pacific markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Formulation compatibility expertise for water-borne wax emulsion integration represents the critical capability gap constraining regional coatings laboratory capacity outside major manufacturing clusters. This scarcity determines competitive positioning across the value chain.
For Market Incumbents: Harden specification-setting relationships with large coatings producers through integrated polymer-wax portfolio control and documented thermal stability certification. Deepen backward integration into Fischer-Tropsch feedstock streams to defend margin position against ethylene cost volatility. Prioritize technical service partnerships in India's PLI scheme zones to preempt emerging domestic manufacturing competition.
For New Entrants and Emerging Players: Mid-market water-borne architectural coatings in India's industrial corridor expansion represent the most penetrable entry point given BIS certification bottlenecks constraining incumbent response speed. Bio-based emulsion convergence targeting carbon-accounted formulation premiums offers differentiated positioning against petrochemical majors. Pursue distributor technical service partnerships rather than direct formulator relationships to bypass rheology expertise scarcity in regional laboratories.
For Investors and Strategic Acquirers: The market sits at a regulatory-acceleration phase that favors micronized production specialists with proven water-borne emulsion capabilities and multi-jurisdiction certification track records. Long-term viability hinges on positioning for sustained water-borne formulation mandates across EPA, REACH, and GB standard jurisdictions. Acquisition focus should target regional micronized wax producers with existing ECHA registration portfolios. Monitor MEE enforcement intensity in China's Yangtze River Delta as the inflection indicator for emulsion-grade demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fischer-Tropsch Feedstock | Captive ethylene supply secures margin stability against crude oil benchmark volatility for synthetic wax producers. |
| Greenfield Manufacturing under PLI Scheme | India's production-linked incentive framework attracts domestic wax additive capacity serving infrastructure coating demand. |
| Multi-Jurisdiction Certification Investment | Parallel EPA, REACH, and BIS approval capabilities compress commercial launch windows for novel wax chemistries. |
| Technical Service Partnership Expansion | Distributor-led rheology support addresses formulation compatibility expertise scarcity in regional coatings laboratories. |
| Bio-Based Emulsion Development | Fermentation-derived wax precursors combined with water-borne technology open premium carbon-accounted positioning. |
Study Parameters
A standing panel of coatings formulator procurement directors, specialty chemical distribution channel managers, plant operations leaders at synthetic wax production facilities, and regulatory affairs specialists provided ongoing calibration across the study period. Primary fieldwork combined structured interviews with these stakeholders and secondary validation against customs and trade data, ACC and Cefic industry reports, SEC 10-K filings from disclosed market participants, and MEE enforcement action records. Bottom-up demand modeling from end-use application volumes and top-down supply capacity assessments were triangulated to establish market size and trajectory.
Scenario-bracketing framed analytical outputs across the projection horizon, with segmentation dimensions spanning product type grade tiers, end-use industry application intensity, physical form processing requirements, and regional regulatory cluster alignment. CAGRs were derived from modeled volume and value trajectories incorporating ethylene feedstock cost sensitivity, water-borne formulation mandate penetration curves, and micronized particle size adoption rates in automotive OEM specifications.
Practitioners should monitor Brazilian carnauba harvest yields, MEE GB standard enforcement intensity, and ethylene cracking margin compression for early signals requiring forecast reassessment. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Caustic Sulphite Caramel Market
Additives
Global Dicalcium Phosphate (Feed Grade) Market
Additives
Refinery Process Additives Market
Additives
Europe Choline Chloride Market
Additives
FD and C Lakes Market
Additives
Mycotoxin Binders Market
Additives
Low VOC Coating Additives Market
Additives
Carboxymethylcellulose (CMC) Market
Additives
Biofuel Additives Market
Additives
Grease Additives Market
Additives
Microcrystalline Cellulose (MCC) Market
Additives
Plastic Fillers Market
Additives
Zinc Dialkyldithiophosphates Additive Market
Additives
Acrylamide Reducing Ingredients Market
Additives
Alkyl Ketene Dimers (AKD) Wax Market
Additives
Trioctyldodecyl Citrate Market