
 Thermal Conductive Additives Market | 2026-2036
Thermal Conductive Additives Market Size, Share, and Industry Trends Forecast 2026-2036
Thermal Conductive Additives Market Intelligence
Electric vehicle powertrain thermal management is expanding its share of additive consumption as automakers push battery energy densities past conventional cooling limits. Dow Inc. leverages its silicone elastomer backbone chemistry to anchor high-volume supply contracts with North American EV battery assemblers. Shin-Etsu Chemical Co., Ltd. dominates fused silica and specialized ceramic filler production for semiconductor encapsulation grades in East Asian foundry markets.
Thermal conductive additives are inorganic or carbonaceous particulates dispersed within polymer, metal, or ceramic matrices to enhance heat transfer coefficients, typically measured in watts per meter-kelvin (W/m·K), with boron nitride achieving up to 400 W/m·K in oriented configurations. Carbon-based additives occupy the fastest-expanding product tier as graphene and carbon nanotube dispersions penetrate 5G base station and data center thermal interface applications where anisotropic conductivity proves critical. Ceramic fillers sustain the largest volume position due to alumina and boron nitride cost-performance ratios in mature automotive under-the-hood segments.
EPA toxics release thresholds and EU REACH substance authorization protocols constrain heavy-metal filler formulations, redirecting formulation R&D toward boron nitride and aluminum nitride chemistries. FDA biocompatibility standards for wearable medical electronics additionally shape silicone-based thermal pad specifications in health-monitoring device supply chains. Stakeholders must track evolving flammability standards from UL and IEC as higher thermal conductivity additives increasingly couple with fire-retardant requirements in enclosed battery architectures.
Market Dynamics
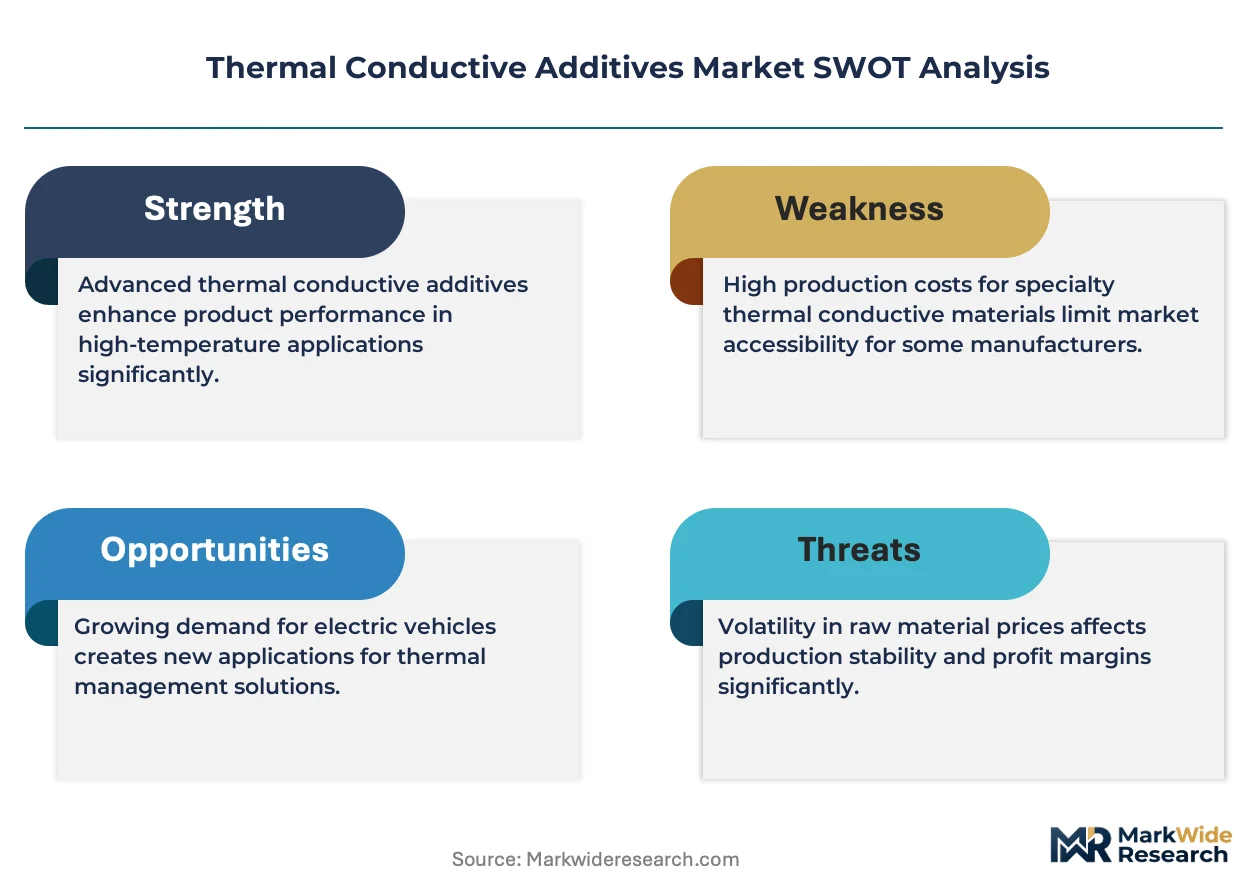
EU F-Gas Regulation phase-down schedules and REACH substance authorization protocols are compressing formulation choices for thermal interface material producers, forcing rapid chemistry pivots toward ceramic fillers with lower environmental persistence profiles.
Growth Catalysts
- Electric vehicle battery thermal management:Automakers are pushing lithium-ion energy densities beyond conventional liquid cooling limits, expanding boron nitride and alumina filler consumption in high-density pack architectures.
- REACH compliance acceleration:ECHA substance authorization timelines are redirecting R&D investment toward aluminum nitride and boron nitride chemistries that bypass heavy-metal restrictions.
- 5G infrastructure buildout:Base station OEMs in East Asian foundry markets are specifying anisotropic graphene and carbon nanotube dispersions for thermal interface pads managing millimeter-wave amplifier heat flux.
Market Restraints
- Boron nitride supply concentration:High-purity hexagonal boron nitride production clusters in limited East Asian and North American facilities, creating single-source vulnerability for premium thermal pad grades.
- Alumina price volatility:Smelter-grade alumina feedstock costs fluctuate with bauxite export restrictions and energy pricing, compressing margins for mid-tier filler compounders.
- Anisotropic conductivity manufacturing limits:Oriented boron nitride structures requiring 400 W/m·K through-plane performance demand specialized extrusion and calendaring equipment unavailable to smaller compounders.
Strategic Opportunities
- Wearable medical electronics:FDA biocompatibility standards for skin-contact thermal management are opening specification windows for platinum-cured silicone pads with specialized ceramic loading in health-monitoring device supply chains.
- Data center liquid cooling integration:Immersion cooling tank manufacturers are specifying thermally conductive encapsulants that bridge direct-to-chip and bath-cooled architectures, creating hybrid formulation demand.
- EU Green Deal industrial heat recovery:Waste heat capture systems in German and Dutch process industries are adopting high-temperature silicone thermal interface materials for heat exchanger optimization.
Industry Challenges
- Formulation-to-application engineering gap:Battery pack assemblers lack in-house rheology expertise to specify optimal filler loading and particle size distributions for automated dispensing lines.
- UL 94 V-0 and IEC 60695-11-10 certification timelines:Higher thermal conductivity formulations increasingly require coupled fire-retardant testing, extending qualification cycles by 8-14 months for enclosed battery architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thermal Conductive Additives Market |
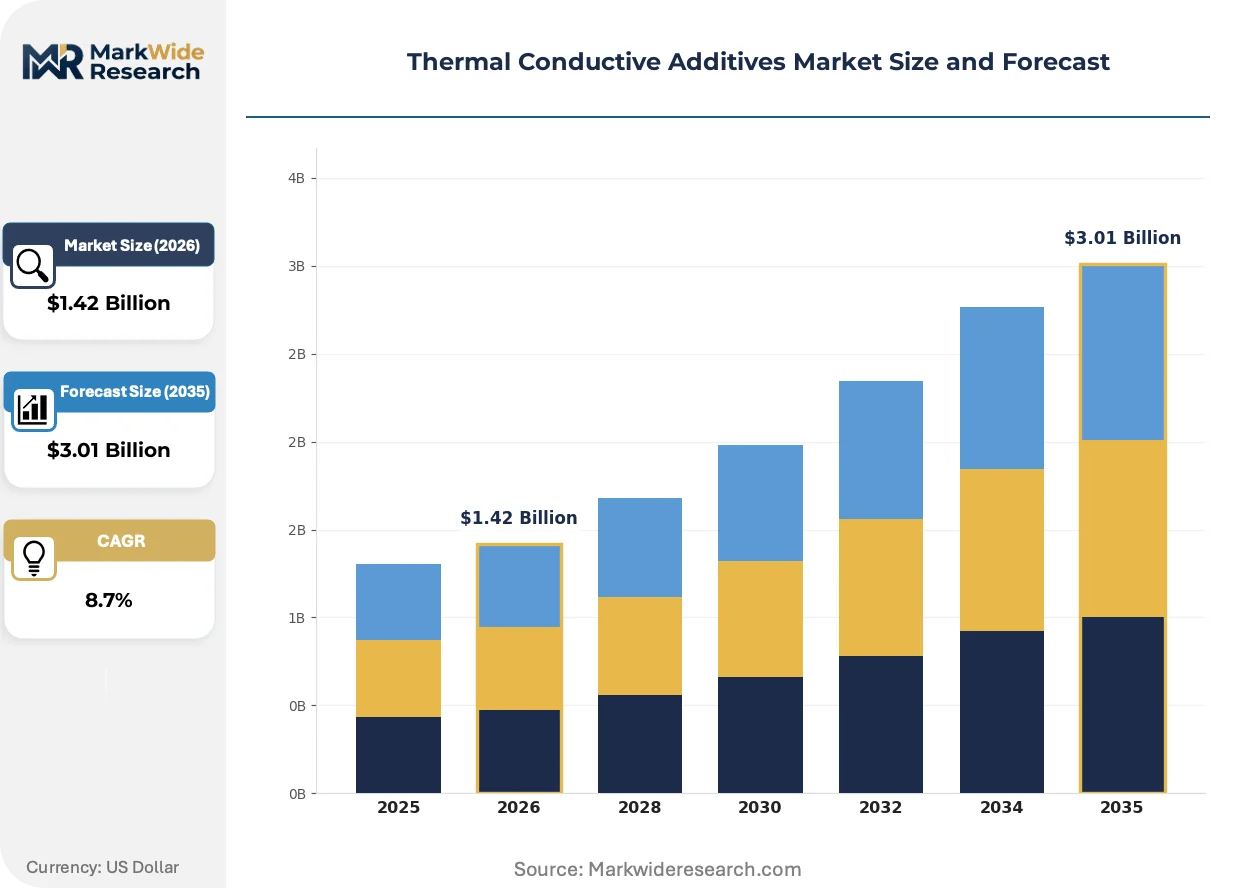
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $3.01 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Metallic Fillers, Carbon-Based Additives, Ceramic Fillers, Polymeric Composites Application: Electronics, Automotive, Aerospace, Industrial Equipment End User: Manufacturers, Research Institutions, Construction Firms, Consumer Electronics Form: Paste, Powder, Granulate, Liquid |
| Companies Covered | BASF SE, 3M Company, Henkel AG & Co. KGaA, Dow Inc., Momentive Performance Materials Inc., Saint-Gobain S.A., LG Chem Ltd., Shin-Etsu Chemical Co., Ltd., Morgan Advanced Materials, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thermal Conductive Additives Market Strategic Shifts & Innovations
Active chemistry convergence between thermal management and fire-safety specifications is compressing traditional formulation boundaries, with additive producers now engineering multi-functional particulate systems that satisfy both conductivity and flammancy requirements in single-pass compounding.
Graphene nanoplatelet dispersions are penetrating 5G base station and hyperscale data center thermal interface applications where anisotropic conductivity proves critical for managing non-uniform heat flux across processor dies. Telecom equipment OEMs are qualifying these carbon-based systems at accelerated 18-month cycles, displacing legacy metal-oxide greases in high-frequency amplifier modules. This material transition is converging with automated dispensing robotics, compressing assembly line changeover times and reducing thermal pad placement labor content.
EU F-Gas Regulation Annex III phase-down mandates are eliminating perfluorinated polymer options for high-temperature thermal interface applications, redirecting specification authority toward ceramic-filled silicone and hydrocarbon elastomer alternatives. Industrial equipment manufacturers in Germany's automotive supplier corridor are requalifying entire product lines to meet 2027 GWP thresholds. Semiconductor packaging houses in the Netherlands and France are accelerating aluminum nitride filler trials to preempt authorization bottlenecks under REACH candidate list protocols.
Direct material specification by EV battery pack assemblers is displacing traditional tier-two thermal pad distributor channels, with North American and European automakers building captive formulation laboratories. This channel compression concentrates volume with compounders capable of co-located technical service and just-in-time blending operations. Germany's Stuttgart-Munich corridor exemplifies this pattern, where tier-one electronics packaging firms now source boron nitride masterbatches through dedicated supply agreements rather than distributor inventories.
Thermal Conductive Additives Market Segmentation
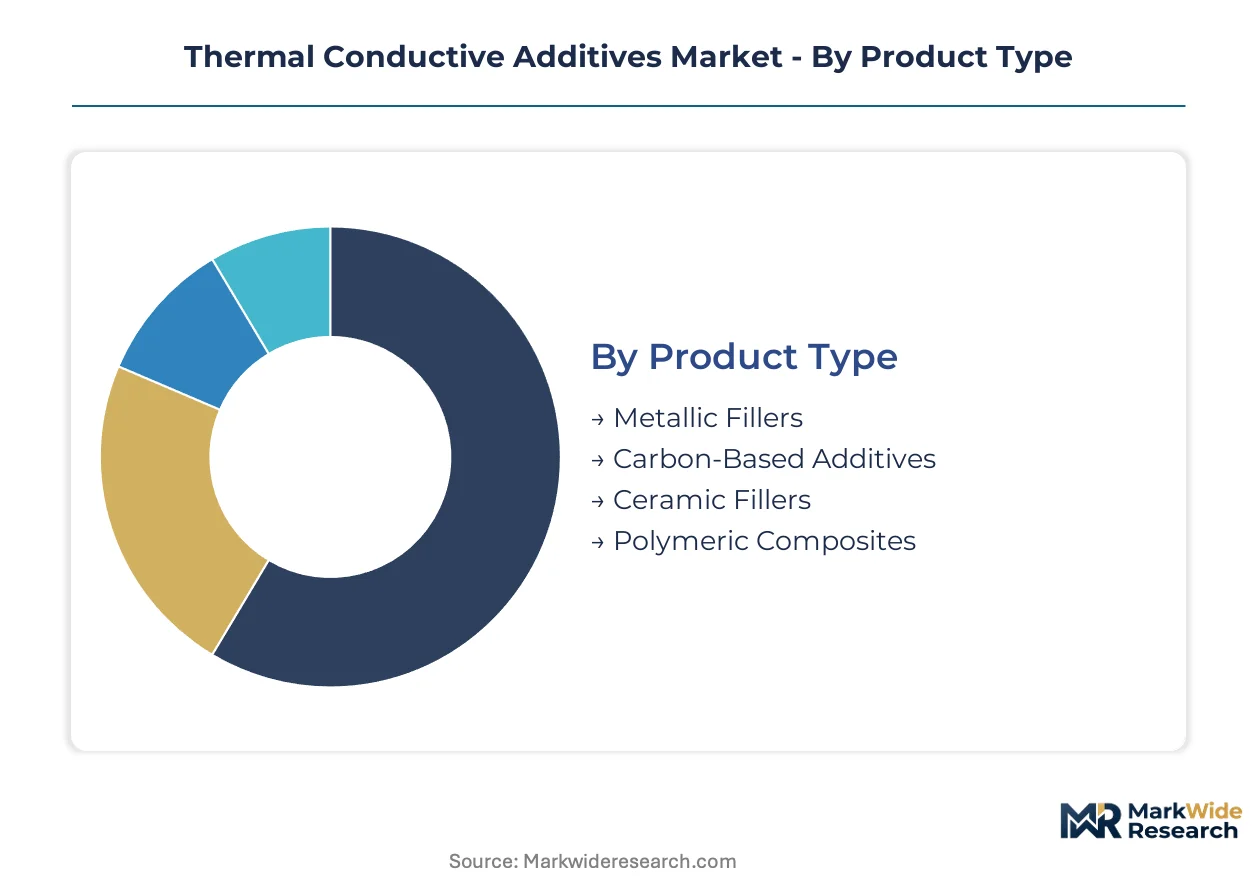
Thermal conductive additives fragment across material chemistries, application environments, and physical forms that dictate compounding economics. Each segmentation axis reveals distinct margin structures and qualification barriers that shape supplier positioning.
Product Type:
Ceramic fillers dominate volume consumption while carbon-based systems command premium pricing in high-performance niches.
- Ceramic Fillers:Alumina and boron nitride particulates dispersed in silicone or epoxy matrices deliver cost-effective conductivity from 1-10 W/m·K. EV battery pack manufacturers in Germany's Stuttgart corridor specify these formulations for module-level thermal interface pads where energy density requirements exceed liquid cooling capacity.
- Carbon-Based Additives:Graphene nanoplatelets and carbon nanotube dispersions achieve anisotropic conductivity exceeding 100 W/m·K in through-plane orientations. 5G base station OEMs in East Asian foundry markets qualify these materials for millimeter-wave amplifier thermal management where heat flux concentrates non-uniformly across processor dies.
- Metallic Fillers:Silver, copper, and aluminum flakes suspended in grease or gel carriers provide isotropic conductivity for legacy automotive under-the-hood applications.
- Polymeric Composites:Thermally conductive engineering plastics with integrated ceramic loading bridge structural and thermal functions in enclosure designs.
Today's leader: Ceramic Fillers. Tomorrow's challenger: Carbon-Based Additives.
Application:
Automotive electrification and data center densification are rewiring demand concentration across end-use verticals.
- Automotive:Battery thermal management systems consume boron nitride and alumina-filled interface materials as lithium-ion pack architectures push beyond conventional cooling limits. Tier-one suppliers co-located with German OEMs in Bavaria now specify masterbatch formulations directly rather than through distributor channels.
- Electronics:Semiconductor packaging houses in the Netherlands and France accelerate aluminum nitride trials to satisfy REACH authorization protocols while maintaining die-level thermal performance.
- Industrial Equipment:Heat exchanger optimization in German and Dutch process industries adopts high-temperature silicone thermal interfaces for waste heat recovery under EU Green Deal mandates.
- Aerospace:Saturation-resistant thermal gap fillers address avionics cooling in pressurized and unpressurized compartments.
Automotive commands current volume share; Electronics exhibits the steepest expansion trajectory as foundry node advancement intensifies thermal constraints.
End User:
Direct specification authority is migrating upstream from distributors to captive formulation laboratories at major manufacturers.
- Manufacturers:EV battery assemblers and electronics packaging firms now blend ceramic masterbatches in-house to control particle size distributions for automated dispensing lines. This backward integration compresses margins for independent compounders.
- Consumer Electronics:Wearable device OEMs specify platinum-cured silicone pads with specialized ceramic loading to satisfy FDA biocompatibility standards for skin-contact thermal management.
- Research Institutions:National laboratories and university centers trial next-generation anisotropic fillers for quantum computing and advanced packaging applications.
- Construction Firms:Building-integrated photovoltaic and LED lighting installers specify thermally conductive adhesives for junction box and heat sink attachment.
Manufacturers consolidate procurement power; Research Institutions seed technology transitions that reshape commercial specifications.
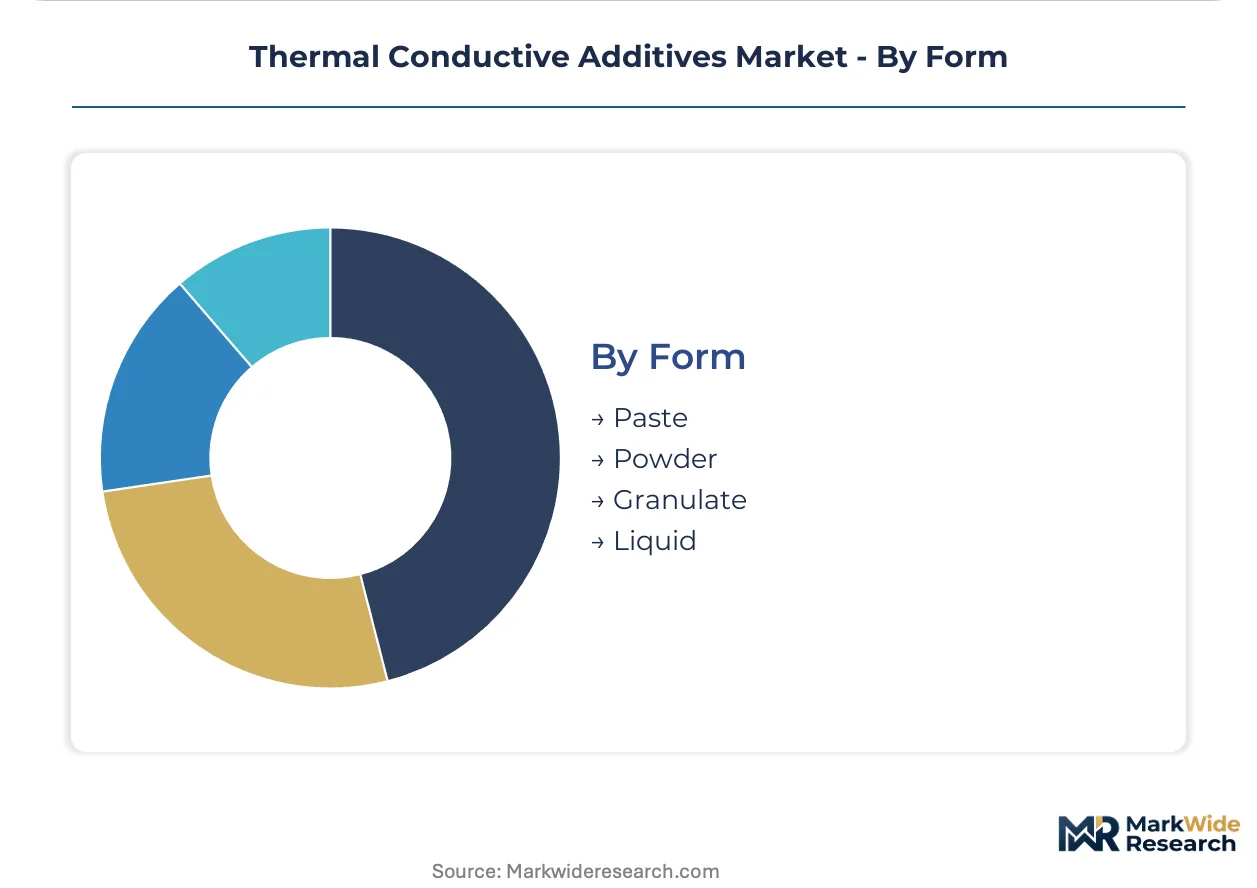
Form:
Physical state determines processing equipment requirements and logistics economics across the value chain.
- Paste:Screen-printable and dispensable thermal greases dominate high-volume electronics assembly. Automated robotic dispensing systems in telecom equipment manufacturing compress changeover times and reduce placement labor.
- Powder:Raw ceramic and carbon filler feedstocks ship to compounders for custom silicone or epoxy loading. Boron nitride powder supply concentrates in limited East Asian and North American facilities.
- Liquid:Two-part curable encapsulants bridge direct-to-chip and immersion cooling bath architectures in data center liquid cooling integration.
- Granulate:Pelletized masterbatches enable just-in-time blending operations for automotive suppliers requiring localized technical service.
Paste formats retain processing efficiency advantages; Liquid formulations gain share fastest as immersion cooling penetrates hyperscale facilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redrawing production maps as compounders relocate blending operations to jurisdictions with streamlined chemical authorization pathways. Cost-of-compliance gaps between REACH-regulated Europe and less restrictive Asian manufacturing zones are accelerating masterbatch facility investments in Southeast Asian industrial parks.
Germany
EV battery thermal management systems and semiconductor packaging drive boron nitride consumption in the Stuttgart-Munich automotive corridor. ECHA REACH substance authorization protocols redirect formulation R&D toward aluminum nitride and ceramic filler alternatives. Tier-one electronics firms in Bavaria now source thermal interface materials through direct supply agreements rather than distributor channels.
United States
North American EV battery assemblers specify silicone elastomer-based thermal pads for high-density lithium-ion configurations. EPA toxics release thresholds constrain heavy-metal filler formulations, pushing compounders toward boron nitride chemistries. Dow Inc. anchors high-volume supply contracts from Michigan and Texas production facilities serving automotive OEMs.
China
5G base station manufacturing and data center expansion propel graphene nanoplatelet demand in East Asian foundry markets. MIIT industrial standards and dual carbon goals shape domestic filler production quotas. Yangtze River Delta compounders specialize in carbon nanotube dispersions for millimeter-wave amplifier thermal management.
Japan
Semiconductor encapsulation grades and advanced packaging applications concentrate fused silica and specialized ceramic filler demand. METI technology roadmaps prioritize heat dissipation materials for next-generation computing architectures. Shin-Etsu Chemical Co., Ltd. dominates production from Nagoya-area facilities serving foundry customers across East Asia.
South Korea
Memory chip manufacturing and display panel production sustain alumina and boron nitride consumption for die-level thermal interfaces. MFDS and KATS standards govern chemical substance reporting for electronics-grade formulations. Seoul Capital Area compounders supply thermal greases to Samsung and SK Hynix packaging operations.
Thermal Conductive Additives Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with integrated chemical conglomerates commanding automotive volumes while regional compounders capture electronics niche specifications. The vendor base organizes around three archetypes: diversified materials giants with silicone backbone chemistry, ceramic filler specialists with boron nitride purification capabilities, and carbon additive innovators with graphene dispersion expertise. Strategic moves center on backward integration into high-purity hexagonal boron nitride production and co-location of technical service laboratories with EV battery assembly plants.
Among diversified chemical conglomerates, BASF SE and Dow Inc. exemplify the scale-driven archetype with polymer backbone integration spanning multiple thermal interface formats. Shin-Etsu Chemical Co., Ltd. occupies a distinctive position within the ceramic filler specialist tier, leveraging East Asian foundry market proximity for semiconductor-grade material qualification. These three anchors represent divergent competitive vectors: European REACH compliance leadership, North American EV supply chain embedding, and East Asian electronics packaging specialization.
| Leading Market Players |
|---|
| BASF SE |
| 3M Company |
| Henkel AG & Co. KGaA |
| Dow Inc. |
| Momentive Performance Materials Inc. |
| Saint-Gobain S.A. |
| LG Chem Ltd. |
| Shin-Etsu Chemical Co., Ltd. |
| Morgan Advanced Materials |
| Others |
Cost & Logistics Intelligence
Captive blending operations at EV battery assembly plants anchor supply positioning while compressing margins for independent compounders serving distributor channels. This integration pattern concentrates pricing power with manufacturers who control particle size distribution specifications for automated dispensing lines, leaving mid-tier compounders exposed to alumina feedstock volatility and REACH compliance cost escalation.
Pricing Analysis
Distributor margins in thermal interface materials have compressed from traditional 25-35% markups to 12-18% as direct supply agreements proliferate. Three-tier pricing structure across semiconductor-grade, automotive-grade, and industrial-grade specifications reflects certification burden differentials rather than raw material costs alone. Cost compression in mid-tier alumina formulations is intensifying because smelter-grade feedstock prices fluctuate with bauxite export restrictions. EV battery assemblers exhibit lowest price sensitivity due to thermal performance premiums, while construction segment buyers negotiate aggressively on volume contracts.
Supply Chain Analysis
REACH authorization timelines and UL 94 V-0 certification requirements gate supply chain participation, extending qualification cycles by 8-14 months for new entrants. High-purity hexagonal boron nitride production concentrates in Japan, the United States, and select Chinese facilities, creating single-source vulnerability for premium thermal pad grades. Formulation chemistry draws from alumina smelter output, silicone elastomer backbones, and specialized carbon nanotube dispersions. Tariff exposure on ceramic filler imports from East Asia is reshaping European compounder sourcing strategies. Distribution runs through direct supply agreements with tier-one automotive suppliers rather than traditional chemical distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between REACH-regulated Europe and Southeast Asian manufacturing zones offers margin expansion for compounders relocating masterbatch operations to jurisdictions with streamlined chemical authorization pathways. ECHA substance authorization costs in Germany run 40-60% above Malaysian industrial park equivalents.
For Market Incumbents: Deepen backward integration into high-purity boron nitride purification to offset single-source vulnerability in East Asian supply clusters. Add dedicated technical service laboratories in the Stuttgart-Munich corridor to defend against direct specification authority migrating to captive EV battery formulation labs. Prioritize aluminum nitride R&D investment ahead of REACH candidate list expansion for heavy-metal fillers. For New Entrants and Emerging Players: Specialty chemical distributors with existing silicone elastomer relationships offer the most accessible channel partnership for penetrating wearable medical electronics specifications. Target FDA biocompatibility-certified thermal pad supply to health-monitoring device OEMs in North American and European markets. Lead with platinum-cured silicone formulations that bypass incumbent ceramic filler supply concentration. For Investors and Strategic Acquirers: Roll-up economics work for regional compounders with localized technical service capabilities because EV battery assemblers demand just-in-time blending operations co-located with assembly plants. Five-to-ten year viability hinges on REACH compliance infrastructure and boron nitride supply security. Target mid-cap ceramic filler specialists with existing ECHA authorization dossiers. Monitor ECHA candidate list expansion for heavy-metal restrictions as the primary inflection signal for aluminum nitride demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Boron Nitride Purification | Shin-Etsu Chemical's Nagoya-area dominance demonstrates captive supply security for semiconductor-grade formulations. |
| Co-located Technical Service Laboratories | Dow Inc.'s Michigan and Texas facilities anchor high-volume automotive contracts through localized formulation support. |
| REACH Authorization Pre-Investment | Aluminum nitride trials in Dutch and French packaging houses preempt regulatory bottlenecks under ECHA protocols. |
| Direct Supply Agreement Migration | Bavarian tier-one electronics firms now source masterbatches through dedicated agreements rather than distributor inventories. |
| Graphene Dispersion Capability Buildout | Yangtze River Delta compounders capture 5G base station specifications with carbon nanotube expertise for millimeter-wave amplifiers. |
Research Approach
Direct dialogue with thermal materials R&D directors, EV battery pack procurement leads, semiconductor packaging engineers, and ECHA regulatory affairs specialists grounded qualitative findings in operational reality. Secondary validation drew from SEC 10-K filings of diversified chemical conglomerates, ECHA authorization dossiers, customs trade data for ceramic filler imports, and UL certification databases. Bottom-up volume estimates from individual compounder capacities triangulated against top-down demand projections from EV production and 5G infrastructure deployment schedules.
Bottom-up modeling of filler consumption by application—battery thermal management, semiconductor encapsulation, 5G base station assembly, and data center immersion cooling—anchored value projections across the analysis window. Segmentation dimensions included material chemistry (ceramic, carbon-based, metallic), physical form (paste, powder, liquid, granulate), and end-use vertical with regulatory cluster overlay. CAGRs derived from slope-logic trend fitting to historical capacity expansion announcements and OEM thermal management roadmaps. Boron nitride price elasticity and REACH authorization timeline uncertainty fed sensitivity bands around central projections.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ECHA substance authorization delays, alumina smelter capacity closures, and EV battery chemistry shifts toward solid-state architectures. Projections reflect assumptions about regulatory enforcement consistency and automotive platform thermal management specifications. A model refresh is warranted upon material change in EU F-Gas Regulation Annex III phase-down schedules or hexagonal boron nitride production capacity announcements in Southeast Asia.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Nucleotide Premix Market
Additives
Fuel Additives Market
Additives
Global Isononanoic Acid Market
Additives
Enzyme Stabilizer Market
Additives
Global Metal Scavenging Agents Market
Additives
Foundry Additives Market
Additives
Global Asphalt Additives Market
Additives
Europe Feed Additives Market
Additives
Tackifier Market
Additives
Gluconic Acid and Derivatives Market
Additives
Supplemental Coolant Additives Market
Additives
Green Chelates/Natural Chelating Agents Market
Additives
Combustion Clean-Up Additives for High-Mileage Fleets Market
Additives
Battery Additives Market
Additives
Cold Flow Improvers Market
Additives
Asia Pacific Silage Additives Market