
 North America Surfactants Market | 2026-2036
North America Surfactants Market Size, Share, and Industry Trends Forecast 2026-2036
North America Surfactants Market Outlook
The capital-intensity divergence between integrated petrochemical producers and specialty chemical houses is rotating competitive advantage toward those with captive ethylene oxide supply. Stepan Company leverages its US Gulf Coast manufacturing footprint to sustain cost-competitive anionic surfactant output for detergent majors. BASF SE anchors its North American position through backward integration into propylene oxide derivatives, while Evonik Industries AG differentiates via high-purity specialty surfactants for personal care applications.
Surfactants are amphiphilic compounds containing hydrophilic head groups and hydrophobic tail structures that reduce interfacial tension between immiscible phases, typically manufactured through sulfonation, ethoxylation, or amidation reactions depending on target ionic character. Their primary industrial purpose spans detergency, emulsification, wetting, and foaming across formulated consumer and industrial products. Nonionic surfactants dominate volume consumption in North America due to compatibility with concentrated liquid detergent formulations and cold-water washing trends. Cationic variants command premium positions in fabric softener and hair conditioning segments where substantivity to anionic substrates creates differentiated performance.
EPA oversight under the Toxic Substances Control Act and state-level frameworks including California's Safer Consumer Products regulations are elevating compliance costs for conventional petrochemical-derived surfactants while creating preference pathways for biodegradable alternatives. Health Canada and PMRA standards for antimicrobial cationic surfactants in sanitizing applications impose additional efficacy and environmental fate testing requirements. Stakeholders must monitor feedstock volatility in propylene and natural alcohol chains alongside evolving biobased certification standards to secure formulation partnerships with major household care brands.
Market Dynamics
EPA enforcement under the Toxic Substances Control Act and California's Safer Consumer Products regulations are forcing reformulation cycles across household care supply chains, compressing product development timelines while elevating compliance spend.
Growth Catalysts
- Cold-water washing adoption:Detergent formulators are accelerating nonionic surfactant incorporation to enable low-temperature cleaning performance, directly expanding volume demand from liquid laundry concentrate producers.
- California Safer Consumer Products:The state's regulatory framework creates preferential pathways for biodegradable surfactant alternatives, channeling R&D investment toward plant-derived feedstocks.
- US Gulf Coast feedstock concentration:Proximity to ethylene oxide and propylene oxide supply clusters reduces logistics costs for integrated producers serving North American detergent majors.
Market Restraints
- Natural alcohol feedstock volatility:Palm kernel and coconut oil price swings compress margin predictability for bio-based surfactant manufacturers dependent on agricultural supply chains.
- Propylene oxide supply concentration:Limited domestic propylene oxide producers create input bottlenecks for specialty nonionic surfactant houses without backward integration.
- Antimicrobial efficacy testing:Health Canada and PMRA requirements for cationic surfactant registration extend commercialization timelines by 18-24 months for sanitizing applications.
Strategic Opportunities
- Mexico manufacturing expansion:Underpenetrated surfactant production capacity in Mexican chemical corridors offers tariff-advantaged export positioning for US formulators.
- Personal care microbiome positioning:High-purity amphoteric surfactants for gentle cleansing applications command formulation partnerships with premium skincare brands.
- Biobased certification convergence:USDA BioPreferred and EPA Safer Choice label alignment creates dual-credential products qualifying for federal procurement preferences.
Industry Challenges
- Sulfonation process engineering talent:Specialized reactor operations expertise scarcity constrains capacity expansion at mid-scale anionic surfactant producers.
- Ethoxylation unit capex cycles:Multi-year investment horizons for ethylene oxide handling infrastructure delay market entry for specialty chemical entrants.
- Legacy formulation integration:Substituting petrochemical surfactants with bio-based alternatives requires extensive compatibility testing with existing brand owner product lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Surfactants Market |
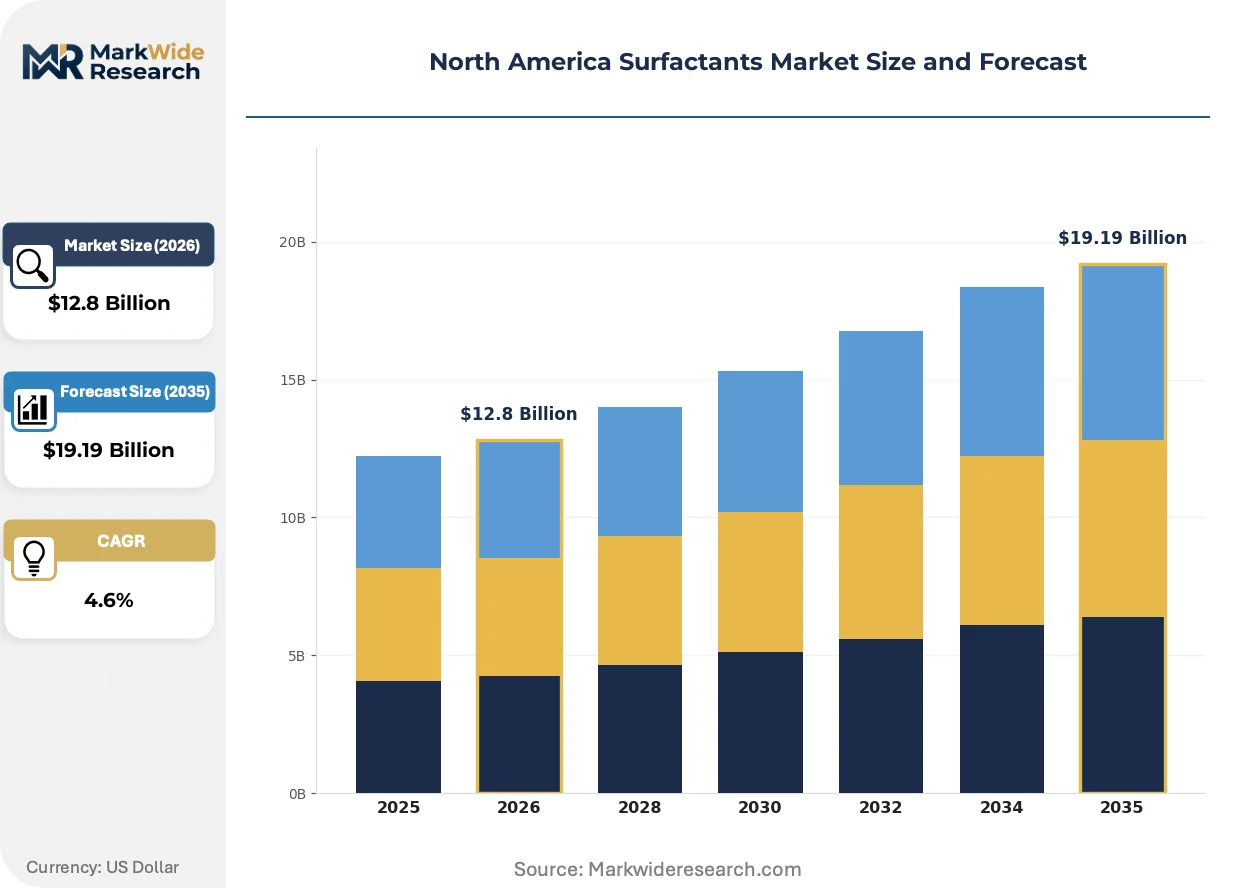
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $19.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Anionic, Cationic, Nonionic, Amphoteric End Use Industry: Household Care, Personal Care, Industrial, Oil & Gas Form: Liquid, Powder, Emulsion, Paste Distribution Channel: Online Retail, Supermarkets, Convenience Stores, Specialty Stores |
| Companies Covered | Stepan Company, Croda International Plc, BASF SE, Evonik Industries AG, Clariant AG, Dow Inc., Nouryon, AkzoNobel N.V., Huntsman International LLC, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Surfactants Market Strategic Shifts
Bio-based feedstock technologies are fragmenting competitive positioning between incumbent petrochemical routes and emerging fermentation-derived alternatives, with formulation partnerships becoming the primary battleground for supply security.
Alkyl polyglucoside synthesis from corn-derived glucose and fatty alcohols is bifurcating the mild surfactant segment. Personal care formulators at premium skincare houses are adopting APG systems at accelerated rates. This technology is compressing market share for traditional ethoxylated alcohols in baby shampoo and sensitive-skin applications.
EPA Safer Choice program expansion is tightening surfactant ingredient disclosure requirements across institutional cleaning contracts. Industrial consequence includes mandatory third-party verification for biodegradability and aquatic toxicity endpoints. Contract sanitation service providers in the US Northeast are reformulating floor-care concentrates to retain municipal procurement eligibility.
Direct formulation partnerships between surfactant producers and retail detergent brands are displacing traditional distribution intermediaries. Bulk supply agreements with volume commitments and co-development clauses are replacing spot purchasing through chemical distributors. This pattern is most visible in US mass-market laundry segments where Procter & Gamble and Church & Dwight concentrate procurement with preferred surfactant suppliers.
North America Surfactants Market Segmentation
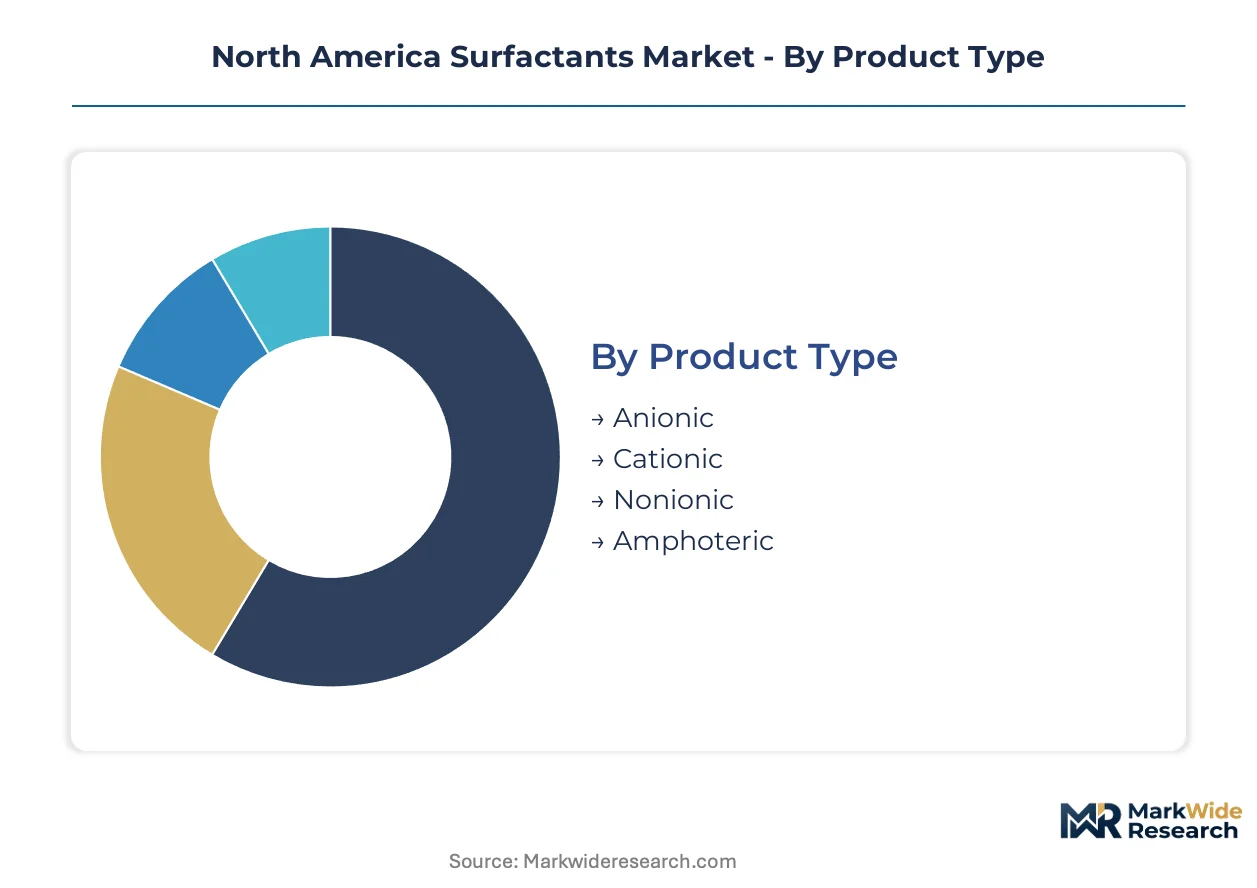
Surfactant segmentation in North America reflects divergent compliance pathways across EPA and state-level chemical disclosure frameworks. Product ionic character determines biodegradability testing burdens, while end-use industry dictates efficacy standards under Health Canada and PMRA antimicrobial registrations.
Product Type:
EPA Safer Choice and California's Safer Consumer Products regulations create tiered compliance costs across ionic categories, with biodegradable alternatives commanding formulation premiums.
- Anionic:Sulfate and sulfonate-based structures dominate detergent formulations for their foaming and emulsification performance. Demand concentrates in US Gulf Coast manufacturing corridors where Stepan Company and integrated petrochemical producers leverage captive ethylene oxide supply for cost-competitive linear alkylbenzene sulfonate output.
- Nonionic:Ethoxylated alcohols and alkylphenol derivatives enable cold-water washing compatibility in concentrated liquid detergents. EPA aquatic toxicity screening elevates compliance spend for ethoxylate manufacturers, channeling R&D toward narrow-range ethoxylation and plant-derived feedstock alternatives.
- Cationic:Quaternary ammonium compounds command fabric softener and hair conditioning segments through substantivity to anionic substrates.
- Amphoteric:Betaine and imidazoline derivatives serve mild cleansing applications in premium personal care formulations.
Established volume favors anionic surfactants; emerging adoption favors nonionic variants with biobased certification alignment.
End Use Industry:
Customer procurement patterns concentrate volume with detergent majors while fragmenting specialty demand across cosmetic and industrial formulators.
- Household Care:Laundry detergents, dishwashing liquids, and surface cleaners consume the majority of anionic and nonionic surfactant volume. Procter & Gamble and Church & Dwight procurement consolidation in the US Midwest and Northeast drives direct supply agreements with preferred surfactant manufacturers.
- Personal Care:Shampoos, body washes, and skincare formulations demand high-purity grades with microbiome-compatible mildness profiles. Premium skincare houses in California and New York metro areas are accelerating alkyl polyglucoside adoption for sensitive-skin positioning.
- Industrial:Metalworking fluids, agrochemical emulsions, and textile processing require performance-optimized surfactant packages.
- Oil & Gas:Enhanced oil recovery and drilling fluid applications consume specialized nonionic and amphoteric variants.
Procurement consolidation favors household care; formulation premiumization favors personal care.
Form:
Physical state selection hinges on downstream formulation compatibility and logistics economics across concentrated and dilute delivery systems.
- Liquid:Aqueous and solvent-based concentrates enable pumpable handling in automated detergent manufacturing. Cold-water washing trends in the US Northeast and Pacific Northwest accelerate liquid nonionic incorporation for low-temperature solubility.
- Powder:Spray-dried granules serve legacy detergent formulations and emerging markets with limited cold-chain logistics.
- Emulsion:Water-in-oil and oil-in-water dispersions address specialized industrial and personal care applications.
- Paste:High-active-content semisolids reduce shipping volumes for remote manufacturing locations.
Logistics efficiency favors liquid concentrates; shelf stability favors powder formats.
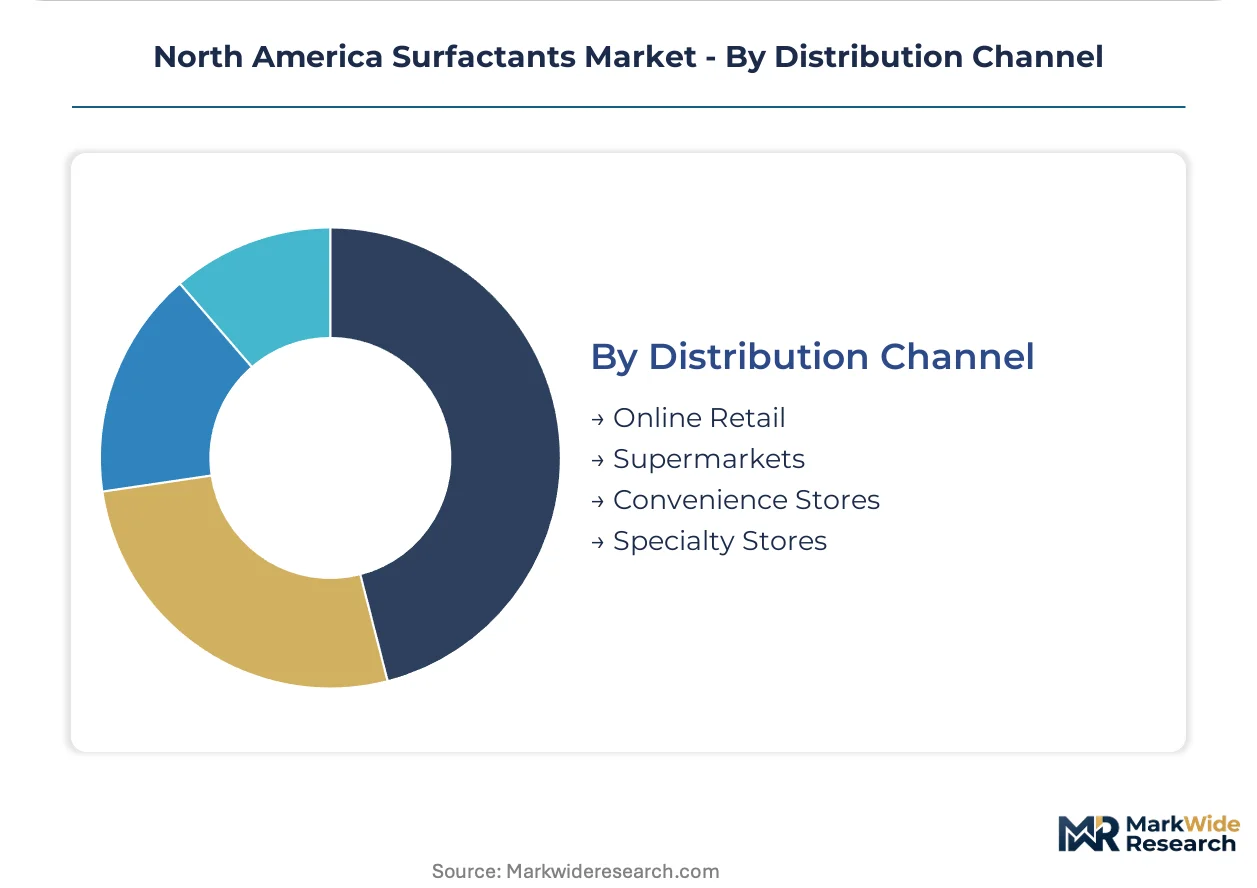
Distribution Channel:
Channel structure bifurcates between bulk industrial supply and packaged consumer retail, with institutional procurement creating a third pathway.
- Online Retail:E-commerce platforms serve small-scale formulators and research procurement with SKU breadth and technical documentation access. Amazon Business and specialty chemical marketplaces are capturing share from traditional distributor relationships for sub-tonnage orders.
- Supermarkets:Mass-market packaged surfactants for DIY and small commercial applications concentrate in Walmart, Kroger, and Target supply chains.
- Convenience Stores:Limited assortment of commodity surfactant products for emergency and travel-size demand.
- Specialty Stores:Professional beauty and janitorial supply outlets curate high-purity and application-specific surfactant grades.
Scale economies favor direct bulk supply; accessibility favors online retail expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows across North America favor US Gulf Coast producers with captive ethylene oxide supply, while Canadian and Mexican markets absorb specialty imports and intermediate chemicals. The region's surfactant demand concentrates in three national markets with divergent regulatory frameworks and industrial base characteristics.
United States
Household care formulators in the US Midwest and Northeast drive bulk surfactant consumption through direct procurement agreements with detergent majors. EPA enforcement under the Toxic Substances Control Act elevates compliance costs for conventional petrochemical-derived products. The US Gulf Coast petrochemical corridor anchors anionic surfactant manufacturing where integrated producers leverage feedstock access and downstream integration.
Canada
Antimicrobial cationic surfactant demand for sanitizing applications expands under Health Canada and PMRA efficacy testing requirements. The country's national chemical regulator imposes environmental fate testing that extends commercialization timelines for new product registrations. Ontario's manufacturing base concentrates personal care formulation activity around Toronto-Hamilton chemical processing clusters.
Mexico
Underpenetrated surfactant production capacity in Nuevo León and Jalisco chemical corridors offers tariff-advantaged export positioning for US formulators seeking cost arbitrage. The country's federal environmental regulator enforces biodegradability standards that align with California's Safer Consumer Products framework. Mexico City Metro anchors institutional cleaning demand where contract sanitation providers reformulate concentrates to retain procurement eligibility.
North America Surfactants Market Competitive Environment
Concentration sits with integrated petrochemical producers commanding captive ethylene oxide and propylene oxide supply chains. The vendor base stratifies across three tiers: multinational chemical conglomerates with backward integration, mid-scale specialty houses focusing on high-purity grades, and regional distributors serving fragmented small-formulator demand. Dominant competitive moves include direct formulation partnerships with retail detergent brands and capacity expansion along the US Gulf Coast.
Within the integrated producer tier, Stepan Company and BASF SE exemplify archetypes leveraging geographic positioning and feedstock control respectively. Specialty differentiation is occupied by Evonik Industries AG, which represents the high-purity surfactant segment serving personal care applications. These three entities anchor competitive positioning across the cost-performance spectrum without exclusive segment lock-in.
| Leading Market Players |
|---|
| Stepan Company |
| Croda International Plc |
| BASF SE |
| Evonik Industries AG |
| Clariant AG |
| Dow Inc. |
| Nouryon |
| AkzoNobel N.V. |
| Huntsman International LLC |
| Others |
Value Chain & Pricing Dynamics
Petrochemical-to-biobased feedstock substitution simultaneously redraws supply geography toward agricultural belts and compresses pricing power for ethylene oxide derivatives. Detergent majors in the US Midwest leverage this transition to renegotiate long-term supply agreements with dual-certified producers.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that stratify across USDA BioPreferred certification tiers, volume scale commitments, and captive ethylene oxide integration levels. Price differentiation hinges on biobased certification grade and geographic delivery cost from US Gulf Coast production clusters. Cost compression in standard-grade anionic surfactants is intensifying because of natural alcohol feedstock volatility. Commodity detergent manufacturers exhibit highest price sensitivity; premium personal care formulators show least.
Supply Chain Analysis
Strategic stockpiling of ethylene oxide and propylene oxide intermediates dominates inventory strategy among integrated producers hedging against feedstock volatility. Supply concentrates in the United States, Canada, and Mexico with the US Gulf Coast anchoring captive ethylene oxide production. The chain rests on ethylene oxide, propylene oxide, and natural fatty alcohol inputs. Single-source vulnerability in domestic propylene oxide producers creates structural risk. Distribution runs through direct bulk supply agreements with detergent majors and chemical distributor networks for fragmented formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biobased certification convergence under EPA Safer Choice and USDA BioPreferred programs creates a regulatory inflection that accelerates formulation partnership restructuring. This disruption favors producers with dual-credential capabilities and backward-integrated feedstock control.
For Market Incumbents: Secure captive ethylene oxide supply through capacity expansion along the US Gulf Coast petrochemical corridor. Deepen backward integration into natural alcohol feedstocks to mitigate agricultural price volatility threatening margin stability. Certification investment in dual-credential products creates defensive moats against emerging fermentation-derived surfactant technologies.
For New Entrants and Emerging Players: Differentiate on high-purity amphoteric surfactants for microbiome-compatible personal care applications where premium pricing tolerates smaller scale. Target underpenetrated Mexico manufacturing corridors for tariff-advantaged export positioning to US formulators. Pursue direct formulation partnerships with mid-tier household care brands bypassing traditional distributor intermediaries.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors specialty chemical houses with biobased certification pipelines and established brand owner relationships. Long-term viability centers on acquisition targets possessing EPA Safer Choice verification and USDA BioPreferred labeling infrastructure. Watch alkyl polyglucoside adoption rates in premium personal care segments as inflection indicator for fermentation-derived surfactant disruption timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Natural Feedstocks | Captive palm kernel and coconut oil supply secures margin predictability for biobased surfactant output. |
| Dual-Certification Investment | EPA Safer Choice and USDA BioPreferred alignment unlocks federal procurement preferences and premium pricing tiers. |
| Mexico Manufacturing Expansion | Nuevo León production corridors offer tariff advantages and proximity to US detergent major supply chains. |
| Direct Formulation Partnerships | Bulk supply agreements with Procter & Gamble and Church & Dwight displace distributor intermediaries in mass-market laundry. |
| High-Purity Amphoteric Capacity Addition | Specialized production for microbiome-compatible cleansing commands formulation partnerships with premium skincare houses. |
Study Parameters
Cross-validation between primary interviews with plant managers at integrated petrochemical producers and secondary validation through customs trade data, ACC industry reports, and SEC 10-K filings anchors the qualitative findings. Technical R&D directors at specialty surfactant houses, procurement leads at downstream detergent OEMs, and distribution channel partners provided operational perspective. Bottom-up capacity modeling triangulates against top-down demand aggregation across household care, personal care, and industrial end-use segments.
Sensitivity analysis frameworks stress-test volume and value outputs across ionic character categories, biobased certification tiers, and regional production hub configurations throughout the forecast period. CAGRs derive from segmented demand modeling incorporating cold-water washing adoption curves, EPA enforcement intensity trajectories, and feedstock price elasticity assumptions. Ethoxylation capacity expansion timelines and antimicrobial registration completion rates constitute industry-specific forecast inputs.
Forecasts assume regulatory continuity in EPA Safer Choice, California Safer Consumer Products, and Health Canada PMRA frameworks; material policy shifts would require re-modeling. Revision becomes warranted when natural alcohol feedstock volatility or biobased certification standard divergence crosses thresholds that alter formulation economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surfactants
Cetyl Chloride Market
Surfactants
Amino Acid Surfactants Market
Surfactants
Sugar-Based Surfactants Market
Surfactants
Zeolite for Detergents Market
Surfactants
Alkyl Polyglycoside (APG) Market
Surfactants
Non-Ionic Surfactants Market
Surfactants
Global Low Foam Surfactants Market
Surfactants
Wetting Agents Market
Surfactants
Global Hydrophobically Modified Alkali Swellable Emulsion (HASE) Market
Surfactants
Global Methyl Soyate Market
Surfactants
Anionic Surfactants Market
Surfactants
Wax Emulsion Market
Surfactants
Soap Salts Market
Surfactants
Specialty Surfactants Market
Surfactants
Alkyl Polyglucosides Market
Surfactants
MDEA Esterquats Market