
 Supplemental Coolant Additives Market | 2026-2036
Supplemental Coolant Additives Market Size, Share, and Industry Trends Forecast 2026-2036
Supplemental Coolant Additives Market Analytics
China is reconfiguring its position in the coolant additive supply base through new specialty chemical capacity in Jiangsu and Shandong provinces. BASF SE leverages its integrated glycol ether platform to sustain formulation leadership across automotive and industrial grades. Chevron Corporation anchors its position through captive distribution to fleet and power generation accounts. Penray differentiates via concentrated additive packages tailored to heavy-duty diesel service intervals.
Supplemental coolant additives comprise corrosion inhibitors, pH buffers, antifoam agents, and scale suppressants dosed into ethylene or propylene glycol base fluids to extend service life and protect aluminum, cast iron, and copper-nickel cooling system alloys. These additives function by forming passive oxide films on metal surfaces and maintaining alkaline reserve above pH 8.0 to neutralize acidic combustion byproducts. Organic Acid Technology formulations now lead product type segmentation due to extended drain intervals and compatibility with modern aluminum radiators, while pre-mixed formats in the form category are gaining fastest traction among do-it-yourself automotive consumers and small marine operators seeking dosing precision without field blending. Concentrate and gel forms retain stronger margins in industrial machinery and power generation channels where bulk procurement and automated dosing systems dominate.
The U.S. EPA regulates glycol discharge under Clean Water Act effluent guidelines, while OSHA sets exposure limits for triazole and nitrite-based inhibitor chemistries in manufacturing environments. REACH registrations in Europe constrain certain boron and amine-based formulations, redirecting R&D toward silicate-free and phosphate-free alternatives. Stakeholders must monitor regulatory divergence between EPA hazard communication standards and EU MDR-linked chemical restrictions to avoid formulation lock-in on non-exportable additive packages.
Market Dynamics
Organic Acid Technology formulations are compressing traditional additive replacement cycles while REACH and EPA discharge rules simultaneously constrain boron-based chemistries, forcing dual-track R&D investment across formulation portfolios.
Growth Catalysts
- Extended drain intervals:Heavy-duty fleet operators now demand 600,000-mile coolant service life, driving additive packages toward higher organic acid concentrations and premium pricing tiers.
- EPA effluent guidelines:Tighter Clean Water Act limits on glycol waste streams compel industrial coolant users to adopt closed-loop systems with supplemental additive monitoring.
- Aluminum radiator proliferation:Automotive thermal management designs now specify silicate-free inhibitors compatible with brazed aluminum heat exchangers, expanding addressable formulation volume.
Market Restraints
- Ethylene glycol feedstock volatility:Petrochemical input costs swing with crude oil indices, compressing additive blender margins during upstream price spikes.
- Triazole supply concentration:Benzotriazole and tolyltriazole corrosion inhibitors source predominantly from Chinese specialty chemical manufacturers, creating single-point vulnerability.
- REACH registration costs:European chemical compliance expenses for novel inhibitor molecules exceed €200,000 per substance, freezing SME formulation entry.
Strategic Opportunities
- Marine auxiliary power:Commercial vessel operators in the North Sea and Baltic trade zones seek pre-mixed coolant solutions for genset maintenance in port-constrained environments.
- Data center liquid cooling:Hyperscale compute facilities deploying direct-to-chip cooling loops require low-conductivity additive packages with biostatic properties.
- EU F-Gas Regulation alignment:Refrigeration-coupled cooling systems face phasedown timelines, creating retrofit demand for glycol-based thermal fluids with compatible supplemental chemistry.
Industry Challenges
- Formulation chemist scarcity:Experienced professionals capable of balancing nitrite-free corrosion protection with aluminum compatibility command premium compensation and limited mobility.
- Legacy fleet incompatibility:Mixed-metal cooling systems in pre-2010 commercial vehicles require transitional additive chemistries that straddle obsolete and modern specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Supplemental Coolant Additives Market |
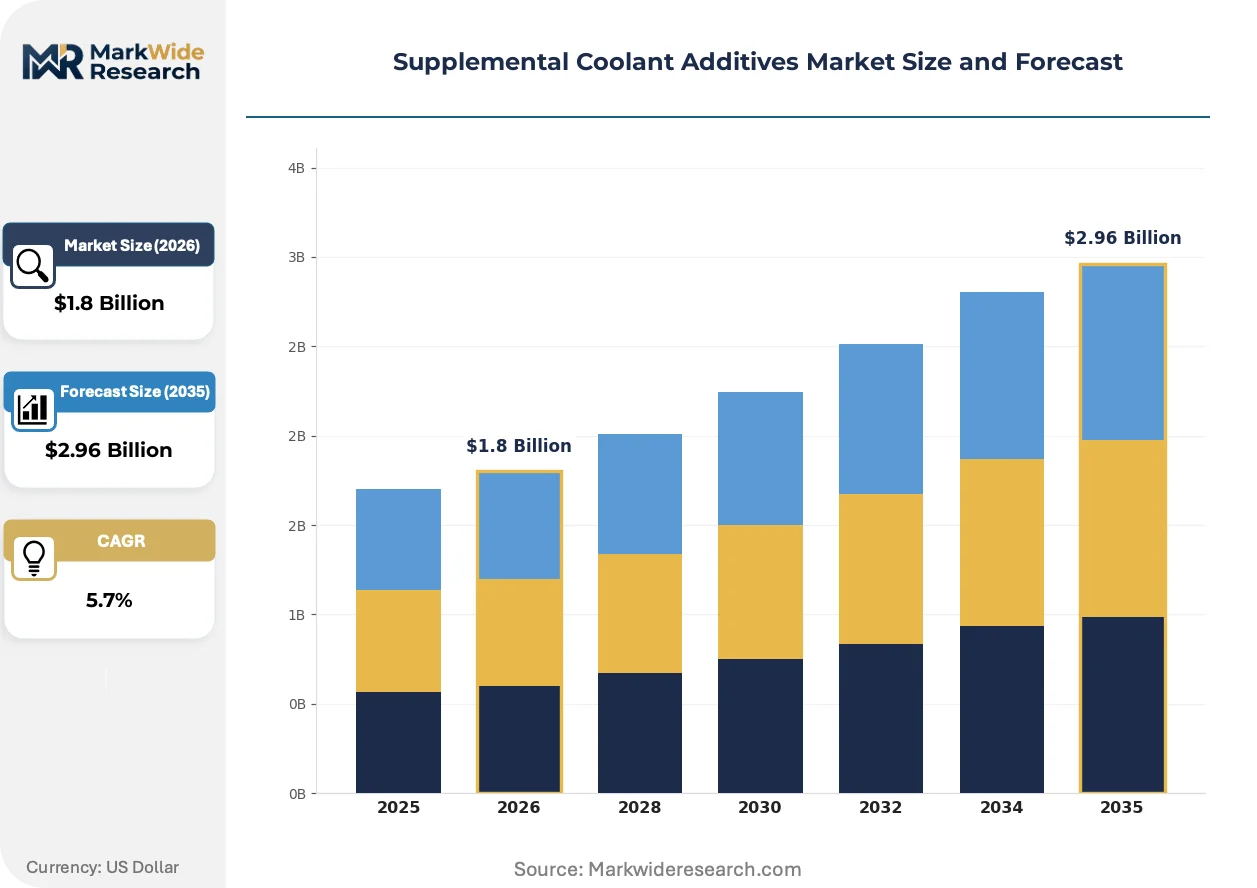
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Acid Technology, Traditional Inorganic, Hybrid, Pre-Mixed Application: Automotive, Industrial Machinery, Marine Engines, Power Generation Form: Liquid, Powder, Concentrate, Gel Packaging Type: Bottles, Drums, Bulk Containers, Sachets |
| Companies Covered | Cummins Filtration, Prestone Products Corporation, Penray, Dober, Chemtex Speciality Limited, Kellerstrass Oil, BASF SE, Chevron Corporation, Exxon Mobil Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Supplemental Coolant Additives Market Evolving Landscape
Silicate-free organic formulations are rewriting additive performance benchmarks while regulatory divergence between EPA hazard communication and EU MDR chemical restrictions fragments global product portfolios.
Hybrid organic acid-silicate (HOAT) chemistry is rendering obsolete conventional inorganic-heavy formulations in European passenger vehicle aftermarkets. German and French independent service chains now stock exclusively phosphate-free, amine-free concentrates. The technology is rendering obsolete legacy borate-nitrite packages that dominated 1990s coolant specifications.
REACH Annex XIV authorization requirements for boric acid derivatives are forcing additive blenders to reformulate heavy-duty diesel products before 2026 sunset dates. Industrial machinery OEMs in the Rhine-Ruhr manufacturing cluster now specify silicate-free factory fills to preempt regulatory non-compliance. The policy shift compresses product lifecycle planning horizons and accelerates R&D amortization schedules.
Fleet maintenance departments are consolidating coolant procurement under national distributor agreements with automated dosing system provisions. Independent jobbers in the U.S. Midwest automotive corridor lose share to integrated service contracts bundling fluid analysis, additive replenishment, and waste glycol recovery. The channel compression is most visible among Class 8 truck operators running dedicated routes between Detroit and Chicago manufacturing hubs.
Supplemental Coolant Additives Market Segmentation
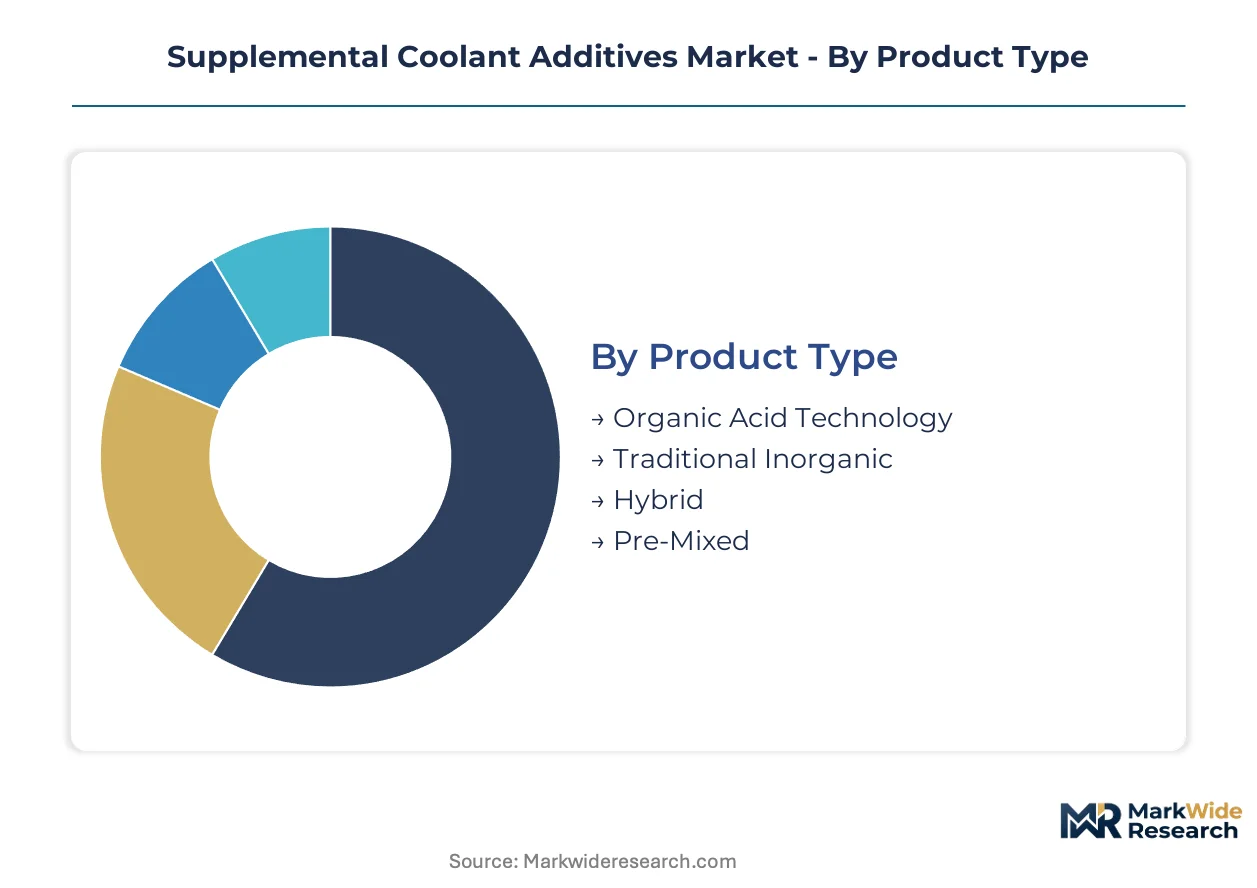
Coolant additive specifications diverge sharply across thermal management applications, with formulation chemistry and physical form determining compatibility with aluminum radiators, service interval targets, and automated dosing infrastructure. Procurement patterns in fleet maintenance and industrial machinery channels favor concentrated formats that reduce freight costs and inventory footprint.
Product Type:
Formulation chemistry spans a maturity spectrum from legacy inorganic packages to silicate-free organic systems engineered for extended drain intervals.
- Organic Acid Technology:Carboxylate-based inhibitors form durable passive films on aluminum and cast iron without silicate precipitation. Heavy-duty diesel fleets in the U.S. Midwest specify OAT formulations for 600,000-mile service life, compressing traditional replacement cycles.
- Traditional Inorganic:Borate-nitrite-silicate blends dominate legacy fleet maintenance where mixed-metal cooling systems predate aluminum radiator adoption. Demand concentrates in developing markets and pre-2010 commercial vehicle aftermarket channels facing cost constraints.
- Hybrid:HOAT chemistry combines organic acid longevity with supplemental silicate protection for transitional cooling system metallurgy.
- Pre-Mixed:Factory-blended solutions eliminate field dilution errors for marine operators and do-it-yourself automotive consumers.
The dominant share belongs to Organic Acid Technology, while Pre-Mixed formats are closing the gap fastest among small-fleet and recreational marine end-users.
Application:
End-use thermal loads and coolant loop architecture dictate inhibitor concentration, pH buffering capacity, and biostatic additive requirements.
- Automotive:Passenger vehicle OEMs specify silicate-free factory fills compatible with brazed aluminum heat exchangers. Light-duty and heavy-duty segments split procurement between pre-mixed retail channels and concentrated fleet contracts with automated monitoring.
- Industrial Machinery:Closed-loop cooling systems in metalworking and plastics processing demand scale suppressants and antifoam agents for high-pressure pump circuits. Rhine-Ruhr manufacturing clusters now mandate silicate-free formulations to preempt REACH compliance deadlines.
- Marine Engines:Commercial vessel auxiliary gensets in North Sea and Baltic trade zones require pre-mixed solutions for port-constrained maintenance windows.
- Power Generation:Combined-cycle gas turbine and reciprocating engine installations specify concentrated additive packages for bulk storage and automated dosing systems.
Automotive applications command the largest formulation volume, though Power Generation procurement exhibits the steepest expansion trajectory as distributed generation capacity adds thermal management infrastructure.
Form:
Physical state determines logistics economics, dosing precision, and compatibility with automated coolant management systems.
- Liquid:Ready-to-dose solutions dominate automotive aftermarket and small industrial accounts without blending equipment.
- Powder:Solid-phase additives reduce shipping weight for remote mining and construction machinery operations.
- Concentrate:High-strength formulations yield strongest margins in power generation and heavy industrial channels where bulk procurement and automated dosing systems justify capital investment in mixing infrastructure.
- Gel:Viscous suspensions enable precise metering in marine and stationary engine applications with limited agitation.
Concentrate formats retain premium positioning in industrial procurement, while Liquid forms expand most quickly through retail automotive channels.
Packaging Type:
Container specifications align with procurement scale, storage constraints, and waste glycol recovery integration.
- Bottles:Retail-format packaging serves do-it-yourself automotive consumers and small marine operators.
- Drums:Intermediate bulk containers balance handling convenience with unit economics for independent jobbers and regional distributors.
- Bulk Containers:Tote and tanker deliveries support national fleet contracts bundling fluid analysis, additive replenishment, and waste recovery.
- Sachets:Single-dose packets enable precise field dosing in remote machinery maintenance without measurement equipment.
Bulk Containers dominate fleet and industrial procurement by volume, while Sachet formats gain traction in mining and construction sectors with decentralized equipment footprints.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA discharge guidelines under the Clean Water Act anchor North American procurement patterns, while REACH chemical registrations in Europe and China's dual carbon targets reshape formulation standards across major manufacturing economies.
United States
Heavy-duty fleet operators in the Midwest manufacturing corridor now specify 600,000-mile coolant service intervals, compressing traditional additive replacement cycles. The EPA's tightened effluent limits on glycol waste streams compel industrial users toward closed-loop systems with supplemental additive monitoring. Detroit-to-Chicago logistics hubs concentrate demand among Class 8 truck operators running dedicated manufacturing supply routes.
Germany
Rhine-Ruhr industrial machinery OEMs now mandate silicate-free factory fills to preempt REACH Annex XIV authorization deadlines for boric acid derivatives. ECHA registration costs exceeding €200,000 per novel inhibitor molecule freeze SME formulation entry. Independent service chains in Stuttgart and Munich stock exclusively phosphate-free, amine-free concentrates for passenger vehicle aftermarkets.
China
Jiangsu and Shandong provinces are reconfiguring specialty chemical capacity to serve domestic coolant additive demand. The Ministry of Ecology and Environment enforces dual carbon goals that redirect R&D toward low-emission formulation processes. Yangtze River Delta automotive clusters specify organic acid technology compatible with brazed aluminum heat exchangers in new thermal management designs.
Japan
METI standards for industrial coolant recycling drive additive procurement toward extended-drain formulations in precision manufacturing. Osaka-based metalworking and plastics processing facilities demand scale suppressants for high-pressure pump circuits. Kansai region machinery OEMs specify concentrated additive packages to reduce freight costs and inventory footprint.
Supplemental Coolant Additives Market Competitive Landscape
Integrated petrochemical conglomerates and specialty chemical specialists split the market across formulation tiers. The structure concentrates around three strategic archetypes: captive glycol ether platforms sustaining vertical formulation control, concentrated additive packages targeting heavy-duty diesel service intervals, and automated dosing system bundlers capturing fleet maintenance contracts. Dominant competitive moves include backward integration into ethylene glycol feedstocks and strategic partnerships bundling fluid analysis with waste glycol recovery.
Within the integrated platform tier, BASF SE and Chevron Corporation exemplify archetypes leveraging captive chemical infrastructure and distribution networks respectively. Penray occupies a position among specialists engineering concentrated additive packages for extended service intervals. These three entities represent distinct competitive vectors: integrated petrochemical scale, downstream distribution anchoring, and formulation specialization.
| Leading Market Players |
|---|
| Cummins Filtration |
| Prestone Products Corporation |
| Penray |
| Dober |
| Chemtex Speciality Limited |
| Kellerstrass Oil |
| BASF SE |
| Chevron Corporation |
| Exxon Mobil Corporation |
| Others |
Value Network & Pricing Analysis
Chinese triazole manufacturers in Jiangsu and Shandong provinces anchor global corrosion inhibitor supply, concentrating margin capture upstream while downstream additive blenders face cost pass-through constraints. This upstream concentration forces procurement managers to balance long-term contract security against spot market exposure.
Pricing Analysis
North American additive packages trade at meaningful premiums to Asian-sourced equivalents, reflecting EPA compliance costs and freight differentials. Pricing stratifies across premium, standard, and economy tiers based on organic acid concentration and service interval certification. Cost compression in standard-tier concentrates is intensifying as ethylene glycol feedstock volatility feeds through formulation economics. Fleet operators running extended drain intervals exhibit lowest price sensitivity, while independent jobbers in retail automotive channels face acute margin pressure.
Supply Chain Analysis
Extended payment terms from Jiangsu specialty chemical suppliers now stretch to 90-120 days, straining working capital for mid-tier additive blenders without supply-chain finance facilities. Manufacturing concentration in China, Germany, and the United States shapes procurement geography, with benzotriazole corrosion inhibitors, ethylene glycol base stocks, and organic acid precursors forming critical input dependencies. Single-source vulnerability around Chinese triazole output represents the dominant structural risk. Distribution runs through national fleet service contracts bundling fluid analysis, additive replenishment, and waste glycol recovery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
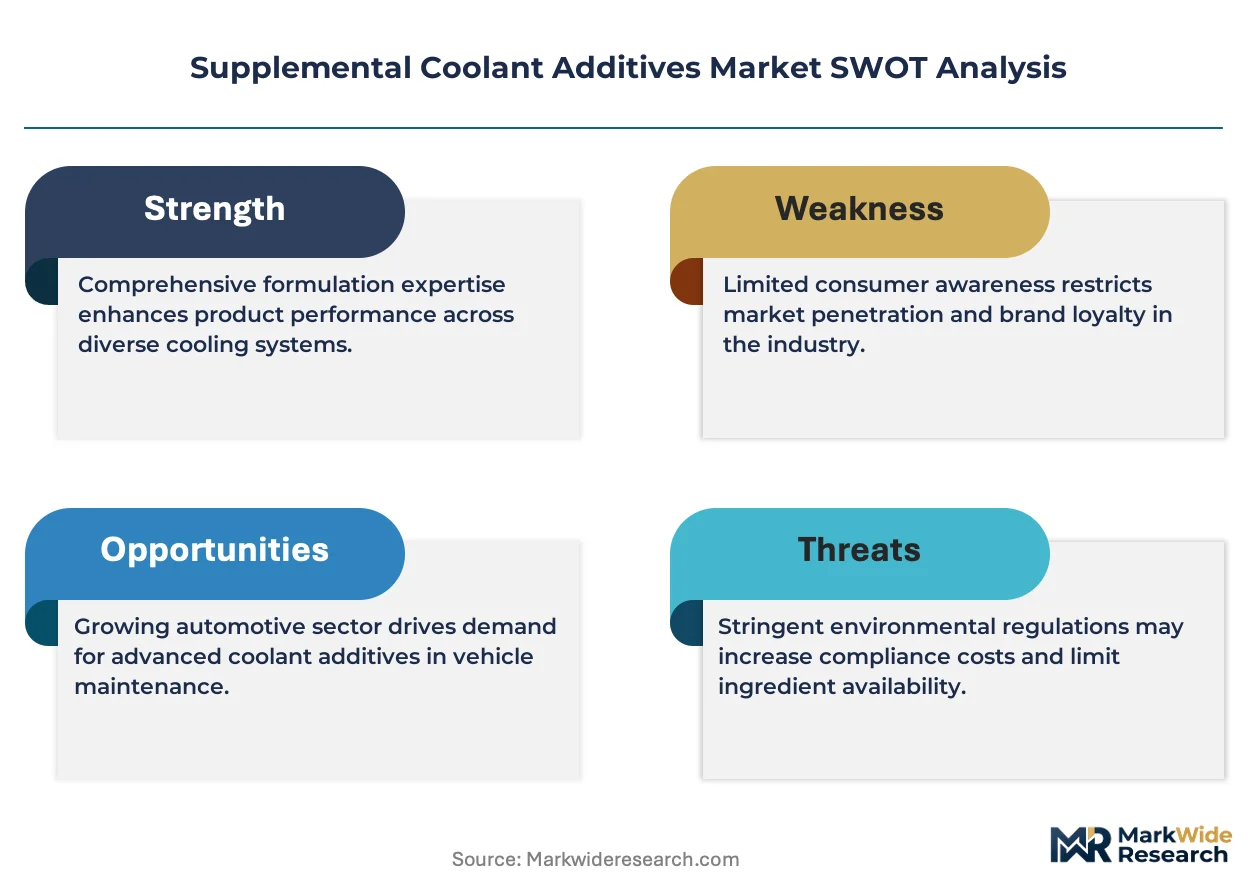
Formulation chemists capable of balancing nitrite-free corrosion protection with aluminum compatibility command premium compensation and limited mobility, constraining R&D velocity across the competitive landscape.
For Market Incumbents: Entrench position through captive ethylene glycol supply agreements and automated dosing system bundling with national fleet accounts. The emergence of silicate-free organic formulations threatens legacy borate-nitrite product lines. Backward integration into triazole precursor manufacturing in North America or Europe reduces single-source exposure to Chinese supply concentration. For New Entrants and Emerging Players: Marine auxiliary power gensets in North Sea and Baltic trade zones represent the most penetrable entry point, with port-constrained maintenance windows favoring pre-mixed solutions over field blending. Data center liquid cooling loops for hyperscale compute facilities offer second-mover advantage as low-conductivity additive specifications stabilize. A go-to-market angle bundling fluid analysis subscriptions with additive procurement accelerates customer acquisition. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed additive specialists holding concentrated heavy-duty diesel formulations and captive fleet distribution relationships. The five-to-ten year viability window favors platforms with REACH-compliant silicate-free portfolios and automated dosing system integration capabilities. The signal to watch is EPA enforcement intensity around Clean Water Act glycol discharge limits, which would accelerate closed-loop system adoption and concentrate procurement among integrated service providers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Triazole Manufacturing | Reduces single-source dependency on Jiangsu and Shandong suppliers amid geopolitical friction. |
| Silicate-Free Formulation Transition | Preempts REACH Annex XIV sunset dates for boric acid derivatives in European factory fills. |
| Automated Dosing System Deployment | Captures fleet maintenance contracts through integrated fluid analysis and waste recovery bundling. |
| Marine Pre-Mixed Product Line Launch | Addresses port-constrained maintenance windows in North Sea and Baltic commercial vessel operations. |
| Data Center Thermal Fluid Certification | Positions additive packages for hyperscale direct-to-chip cooling loop specifications. |
Research Methodology
Cross-validation between primary interviews with formulation chemists, fleet maintenance directors, and industrial procurement managers and secondary validation through EPA effluent guideline filings, ECHA REACH registration databases, and chemical trade flow data anchors the qualitative findings. Bottom-up demand modeling from end-use segments triangulates against top-down petrochemical capacity assessments.
Calibration against historical organic acid technology adoption curves and aluminum radiator penetration rates informs the projection framework across the analysis window. Segmentation dimensions include formulation chemistry tier, end-use thermal application, physical form factor, and regional regulatory cluster. CAGRs derive from elasticity-adjusted volume projections incorporating service interval extension trends and closed-loop system penetration.
Stress conditions across ethylene glycol price volatility, REACH authorization timeline acceleration, and Chinese triazole export restriction scenarios were modeled; outcomes outside those bands fall beyond the analytical envelope. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Extruded Inclusions Market
Additives
Global Scale Inhibitors Market
Additives
Diamino Stilbene Disulfonic Acid (DASDA) Market
Additives
Global Peptone Market
Additives
Printing Ink Additives Market
Additives
Global Anti-Fog Additives Market
Additives
Global Butyric Acid Derivatives Market
Additives
Material Shrinkage-reducing Agents Market
Additives
Global UV Stabilizers Market
Additives
Metal Modifiers Market
Additives
Citric Acid Anhydrous Market
Additives
Japan Sodium Reduction Ingredient Market
Additives
Polyethylene Terephthalate Additives Market
Additives
Grease Additives Market
Additives
Chelated Selenium Market
Additives
Gelatin Peptones Market