
 Anti-Slip Additives Market | 2026-2036
Anti-Slip Additives Market Size, Share, and Industry Trends Forecast 2026-2036
Anti-Slip Additives Market Analysis
Multi-source procurement of silica and polymer grit is hardening among European and North American coating formulators. Akzo Nobel BV leverages its integrated resin-additive portfolio to anchor specification-driven flooring projects across industrial facilities. PPG Industries competes through R&D intensity in liquid dispersible grades for automotive underbody coatings. Evonik Industries differentiates via surface-treated precipitated silicas that sustain premium positioning in marine and aerospace applications.
Anti-slip additives are surface-modifying agents—typically silica particles, aluminum oxide, or polymer beads ranging from 50 to 500 microns—that are dispersed into coatings, adhesives, or sealants to raise static and dynamic friction coefficients above regulatory thresholds. These additives are manufactured through precipitation, fumed silica processing, or controlled crushing and sizing of mineral aggregates, then surface-treated with silanes or waxes to optimize dispersion and binder compatibility. Coating additives dominate volume flows due to mature specification networks in industrial and marine protective coatings, while polymeric additives represent the fastest-expanding margin pool as automotive OEMs and consumer goods manufacturers seek lighter, non-abrasive alternatives that reduce substrate damage. Flooring applications within the construction end-user segment concentrate demand for granular and powder forms, where slip-resistance ratings under DIN 51130 and ASTM C1028 directly determine project approval.
REACH registration requirements through ECHA govern silica-based additive composition disclosure and hazard classification across Europe, while OSHA General Industry Standards 1910.22 in the United States mandate minimum slip-resistance thresholds for workplace walking surfaces. The EU Green Deal and associated CSRD reporting obligations are pushing construction and automotive buyers to document embedded carbon in additive supply chains, creating compliance-driven specification filters. Stakeholders must monitor divergence between regional test methodologies—pendulum versus ramp tests—as specification mismatches threaten cross-border product approvals and contract eligibility.
Market Dynamics
REACH and OSHA mandates are hardening slip-resistance thresholds, forcing coating formulators to requalify additive portfolios and pushing procurement toward specification-grade silica and polymer grit suppliers with verified compliance documentation.
Growth Catalysts
- REACH Registration Expansion:ECHA's tightened silica hazard classifications are disqualifying uncertified suppliers and concentrating demand among registered additive producers with full dossier transparency.
- Marine Coating Specification Networks:Shipbuilders in Germany, South Korea, and Norway are embedding high-friction surface treatments into newbuild contracts, creating pull-through for precipitated silica grades.
- Automotive Lightweighting Mandates:Polymeric bead additives are displacing mineral grit in underbody coatings as OEMs pursue mass reduction targets without sacrificing friction coefficients.
Market Restraints
- Quartz Feedstock Volatility:High-purity silica sand concentrates in limited mining districts, exposing additive producers to energy-linked processing cost swings.
- Surface Treatment Capacity Bottlenecks:Silane functionalization requires specialized reactor infrastructure; capacity is concentrated among German and Japanese chemical specialists.
- Cross-Border Test Methodology Divergence:Pendulum testers (UK/Germany) and ramp tests (France/Italy) produce non-convertible ratings, fragmenting product approval pathways.
Strategic Opportunities
- CSRD-Driven Supply Chain Documentation:EU construction and automotive buyers must now report embedded carbon in additive purchases, creating premium positioning for producers with lifecycle data.
- India Industrial Flooring Buildout:BIS adoption of EN 13893 slip-resistance standards is opening specification-grade markets in pharmaceutical and food processing facilities.
- Silica-Polymer Hybrid Formulations:Converging surface treatment chemistries enable single-additive solutions that bridge abrasive and non-abrasive performance tiers.
Industry Challenges
- Formulation Integration Complexity:Dispersing 50-500 micron particles without sag or settlement requires rheology expertise that coating labs report as scarce.
- Multi-Jurisdiction Certification Timelines:Securing DIN 51130, ASTM C1028, and EN 13893 approvals in parallel extends product launch cycles by 12-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anti-Slip Additives Market |
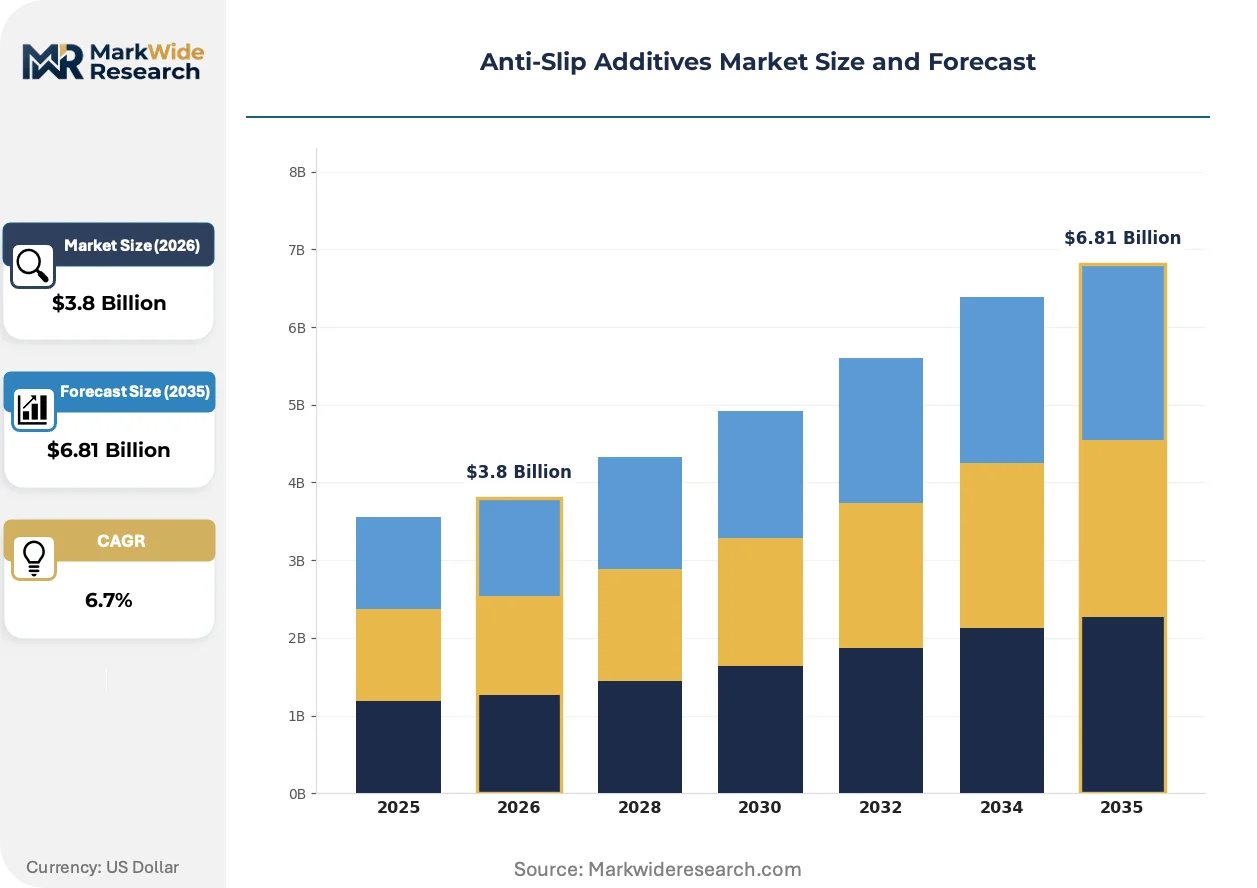
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polymeric Additives, Natural Additives, Coating Additives, Other Additives Application: Flooring, Coatings, Adhesives, Sealants End User: Construction, Automotive, Aerospace, Consumer Goods Form: Granular, Liquid, Powder, Paste |
| Companies Covered | Akzo Nobel BV, Axalta Coating Systems, PPG Industries Inc, Vexcon Chemicals, Rust-Oleum, Jotun, Hempel A/S, Evonik Industries, BYK (ALTANA), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anti-Slip Additives Market Emerging Trajectories
Surface treatment chemistry and dispersion technology are converging to enable single-additive platforms that span marine, automotive, and flooring specifications without reformulation.
Nano-structured precipitated silicas with tailored surface silanol densities are decentralizing the additive supply chain by allowing regional coating producers to match premium friction performance without importing specialized grades from German or Japanese suppliers. Mid-tier formulators in Poland, Mexico, and Vietnam are adopting these dispersible platforms to bypass legacy distributor networks. The technology is compressing the historical specification advantage held by integrated resin-additive majors.
OSHA's updated General Industry Standards 1910.22 are mandating documented slip-resistance testing for workplace walking surfaces in manufacturing facilities. Facility managers must now specify certified additives with traceable friction coefficient data. Industrial flooring contractors in Michigan, Texas, and Ohio are responding by pre-qualifying additive suppliers with third-party test reports, shifting procurement toward specification-grade producers.
Automotive OEMs are unbundling coating additive procurement from resin system contracts, creating direct purchasing relationships with silica and polymer grit specialists. Tier-1 suppliers in Stuttgart, Wolfsburg, and Detroit are establishing technical qualification programs that bypass traditional distributor markups. This channel disintermediation is most visible in underbody coating applications where friction and corrosion performance must be validated at the additive level.
Anti-Slip Additives Market Segmentation
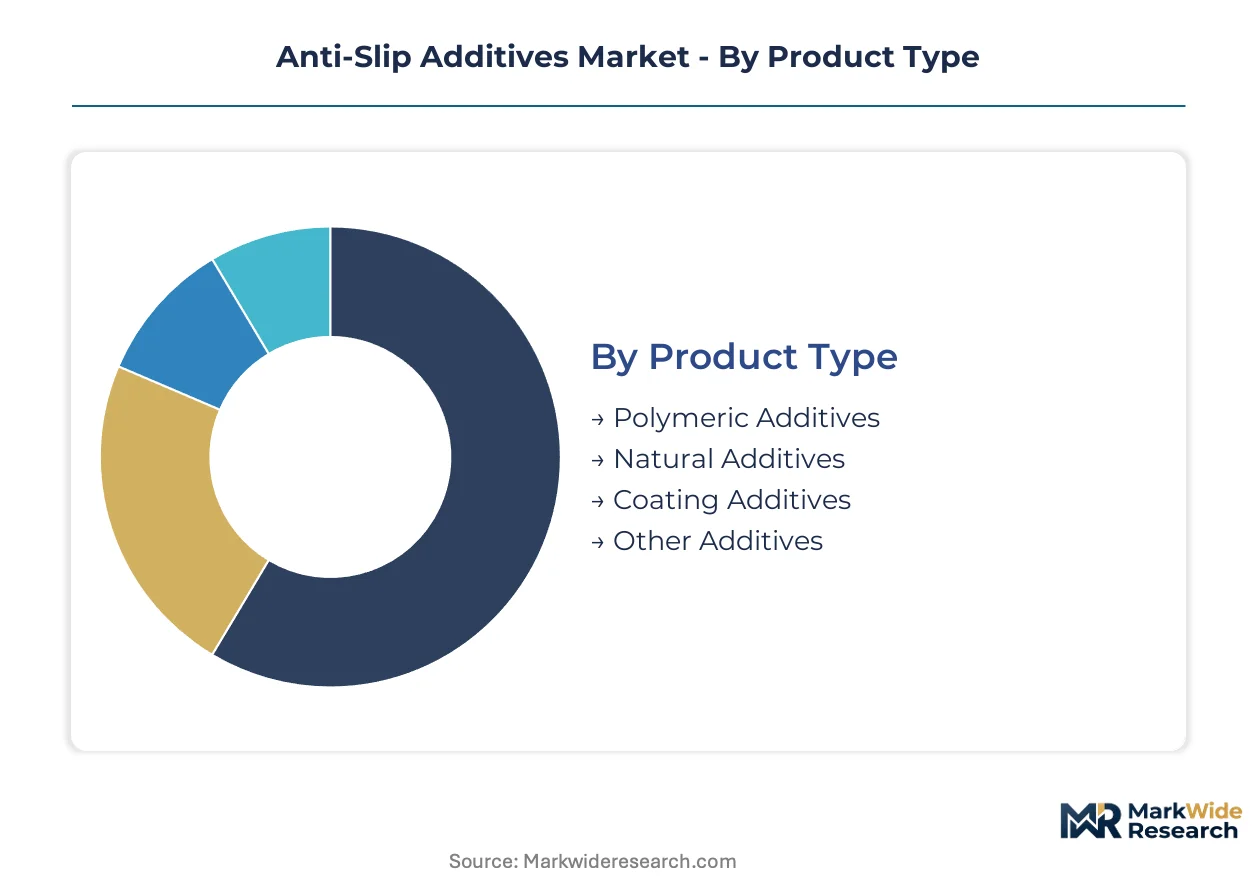
Anti-slip additive procurement diverges sharply across product categories, with certification requirements for marine coatings, automotive specifications, and flooring ratings creating distinct qualification barriers. Formulators must match additive selection to end-use test methodologies, as DIN 51130, ASTM C1028, and EN 13893 approvals rarely transfer across application boundaries.
Product Type:
REACH registration status and OSHA compliance documentation concentrate procurement power among certified producers, with ECHA dossier transparency becoming the primary filter for specification-grade supply relationships.
- Coating Additives:Precipitated silicas and fumed silica grades dominate marine protective coatings and industrial flooring systems. Shipbuilders in Germany, South Korea, and Norway embed these additives into newbuild contracts requiring documented friction coefficients. Specification networks in industrial facilities concentrate demand among registered producers with full ECHA dossiers.
- Polymeric Additives:Polymer beads ranging 50-300 microns displace mineral grit in automotive underbody coatings where mass reduction targets conflict with abrasion resistance. OEMs in Stuttgart and Detroit establish direct qualification programs that bypass traditional distributor channels. These additives sustain premium positioning through non-abrasive surface compatibility.
- Natural Additives:Crushed walnut shells and corncob grit serve specialty applications in consumer goods and food-contact flooring where synthetic material restrictions apply.
- Other Additives:Aluminum oxide and specialized mineral aggregates occupy niche positions in aerospace landing gear coatings and extreme-duty industrial surfaces.
Leading the category by volume: Coating Additives. Growing fastest: Polymeric Additives.
Application:
Cost stratification separates specification-grade systems from commodity formulations, with third-party testing expenses creating tiered entry barriers across flooring, marine, and automotive channels.
- Flooring:Granular and powder additives raise static friction coefficients above OSHA General Industry Standards 1910.22 thresholds in manufacturing facilities. Industrial contractors in Michigan, Texas, and Ohio pre-qualify suppliers with traceable pendulum or ramp test data. DIN 51130 and ASTM C1028 ratings directly determine project approval in commercial and industrial construction.
- Coatings:Marine protective coatings integrate high-friction surface treatments for offshore platform decking and shipboard walkways. Offshore operators in Norway demand additives with verified salt-spray corrosion compatibility alongside slip-resistance performance.
- Adhesives:Pressure-sensitive adhesive tapes for workplace safety marking incorporate micro-structured polymer grit to achieve EN 13893 compliance without surface damage.
- Sealants:Joint sealants in food processing and pharmaceutical facilities combine anti-slip performance with chemical resistance and cleanability certifications.
Dominating procurement spend: Flooring applications. Expanding most quickly: Coatings for marine and offshore specifications.
End User:
Customer sophistication varies dramatically, with automotive OEMs and aerospace primes demanding direct additive qualification while construction channels accept distributor-mediated supply.
- Construction:Commercial and industrial flooring contractors specify granular additives for warehouse, pharmaceutical, and food processing facilities. BIS adoption of EN 13893 standards in India is opening specification-grade procurement in emerging industrial clusters.
- Automotive:OEMs unbundle additive procurement from resin system contracts, creating direct relationships with silica and polymer grit specialists. Underbody coating applications require simultaneous validation of friction, corrosion, and chip-resistance performance.
- Aerospace:Landing gear coatings and maintenance platform surfaces demand additives with extreme temperature stability and jet fuel compatibility.
- Consumer Goods:Bath mats, footwear soles, and recreational equipment drive demand for soft-touch polymer beads that avoid skin abrasion.
Generating highest volume: Construction end users. Gaining share fastest: Automotive direct procurement programs.
Form:
Supply concentration in surface treatment capacity creates margin differentiation, with silane functionalization infrastructure limited to German and Japanese chemical specialists.
- Granular:Sized mineral and polymer particles 100-500 microns disperse into thick-film flooring and marine coatings. Bulk handling systems in industrial coating plants favor free-flowing granular forms for automated dosing.
- Powder:Fine precipitated silicas below 50 microns serve thin-film automotive and aerospace coatings where surface profile must be minimized. Powder forms dominate specification-grade procurement in DIN 51130-rated flooring systems.
- Liquid:Pre-dispersed additive concentrates eliminate dust handling and sag control challenges in high-build coating applications.
- Paste:High-solids dispersions target manual application in repair and maintenance scenarios where mixing equipment is unavailable.
Commanding greatest shipment volumes: Granular forms. Climbing the fastest: Liquid dispersible grades for automated coating lines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
High-purity silica sand deposits in Bavaria and Lower Saxony anchor German supply chains for precipitated silica manufacturing. Automotive OEM clusters in Stuttgart and Wolfsburg drive specification-grade additive procurement for underbody coatings. Marine coating demand concentrates in Hamburg and Bremen shipyards where offshore platform specifications mandate certified friction performance.
United States
OSHA General Industry Standards 1910.22 enforcement is tightening slip-resistance thresholds in Michigan, Texas, and Ohio manufacturing facilities. Industrial flooring contractors pre-qualify additive suppliers with third-party pendulum test reports. Detroit automotive OEMs establish direct qualification programs that bypass traditional distributor channels for polymer grit procurement.
Germany
REACH registration requirements through ECHA govern silica-based additive composition disclosure across industrial coatings. Automotive OEMs in Stuttgart and Wolfsburg embed friction coefficient specifications into underbody coating contracts. Hamburg and Bremen shipyards integrate high-friction surface treatments into newbuild offshore platform decking.
China
Marine coating production in Shanghai and Dalian is expanding specification-grade silica procurement for shipbuilding export contracts. The country's national chemical regulator maintains hazard classification protocols for industrial coating additives. Yangtze River Delta coating formulators are adopting nano-structured precipitated silicas to match premium friction performance.
South Korea
Shipbuilders in Ulsan and Geoje are embedding high-friction surface treatments into newbuild contracts requiring documented friction coefficients. The national standards body aligns marine coating specifications with international slip-resistance test methodologies. Busan-Ulsan industrial clusters concentrate demand for precipitated silica grades in offshore platform applications.
India
BIS adoption of EN 13893 slip-resistance standards is opening specification-grade markets in Maharashtra and Gujarat pharmaceutical facilities. Industrial flooring buildout in Telangana and Karnataka food processing plants requires certified granular additives. Mumbai and Ahmedabad construction markets are pre-qualifying suppliers with traceable DIN 51130 test data.
Anti-Slip Additives Market Vendor Landscape
Capacity expansion dominates the current landscape as additive producers scale surface treatment reactor infrastructure to meet REACH documentation requirements. The vendor base clusters around three strategic archetypes: integrated resin-additive majors with full ECHA dossiers, specialized silica producers with silane functionalization capabilities, and polymer grit specialists serving automotive direct procurement channels. M&A activity and geographic licensing agreements represent the primary competitive moves as firms secure regional test certification capabilities.
Among integrated coating specialists, Akzo Nobel BV and PPG Industries exemplify the specification-driven archetype through resin-additive portfolio integration. Evonik Industries occupies a position within the premium silica tier, representing German chemical specialists with precipitated silica surface treatment infrastructure. These three entities anchor the competitive structure by demonstrating how compliance documentation and technical qualification programs concentrate procurement relationships.
| Leading Market Players |
|---|
| Akzo Nobel BV |
| Axalta Coating Systems |
| PPG Industries Inc |
| Vexcon Chemicals |
| Rust-Oleum |
| Jotun |
| Hempel A/S |
| Evonik Industries |
| BYK (ALTANA) |
| Others |
Supply Flow & Price Mechanics
Certification-grade divergence between REACH-registered silica producers and uncertified commodity suppliers manifests in both pricing power and procurement channel structure. Buyers with DIN 51130 or ASTM C1028 project requirements pay premiums for documented friction coefficients while bypassing spot-market intermediaries entirely.
Pricing Analysis
Third-party test report bundling separates specification-grade suppliers from commodity sellers serving undifferentiated flooring projects. Three-tier pricing structure across premium, standard, and economy levels tracks ECHA dossier completeness and surface treatment chemistry sophistication. Cost compression in economy-grade mineral grit is intensifying because Chinese precipitated silica exports are capturing Asian marine coating demand. Industrial flooring contractors in Michigan and Texas show highest price sensitivity, while Stuttgart automotive OEMs prioritize friction performance over unit economics.
Supply Chain Analysis
REACH registration and OSHA compliance documentation gate access to specification-grade procurement channels in Germany, the United States, and South Korea. High-purity quartz feedstock draws from Bavarian mining districts and select Chinese deposits, while silane functionalization capacity rests on German and Japanese chemical specialists. Single-source vulnerability concentrates in surface treatment reactor infrastructure. Distribution runs through direct technical qualification programs at automotive OEMs and shipbuilder specification networks rather than traditional chemical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Silane functionalization reactor capacity constraints prop pricing premiums for REACH-registered producers, creating a supply-constrained market structure that favors incumbents with existing surface treatment infrastructure.
For Market Incumbents: Hedge quartz feedstock exposure through long-term offtake agreements with Bavarian and Lower Saxony mining operators. Expand silane functionalization capacity in Germany to capture specification-grade demand from Hamburg and Bremen shipbuilders before Japanese competitors replicate surface treatment chemistries for marine coating applications. For New Entrants and Emerging Players: BIS adoption of EN 13893 in India opens a window for specification-grade additive supply to Maharashtra pharmaceutical facilities and Telangana food processing plants. Target industrial flooring contractors in Ahmedabad and Mumbai with DIN 51130 test data packages. Build go-to-market through regional coating formulator partnerships rather than direct OEM qualification. For Investors and Strategic Acquirers: Re-rating potential sits with specialized silica producers possessing silane functionalization capabilities given CSRD-driven supply chain documentation requirements. The five-to-ten year viability window favors targets with embedded carbon lifecycle data and ECHA dossier transparency. Watch for India BIS enforcement acceleration as the inflection signal for emerging market specification-grade demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Quartz Feedstock | Captive supply of Bavarian high-purity silica sand reduces energy-linked processing cost volatility exposure. |
| Surface Treatment Reactor Capacity Expansion | Additional silane functionalization infrastructure in Germany locks in REACH-registered supply relationships with automotive OEMs. |
| CSRD-Compliant Lifecycle Data Development | Embedded carbon documentation opens premium positioning with EU construction and automotive buyers under Green Deal reporting. |
| India Market Technical Qualification | DIN 51130 and EN 13893 test certification in Mumbai and Ahmedabad enables specification-grade procurement in pharmaceutical flooring. |
| Silica-Polymer Hybrid Formulation Launch | Single-additive platforms spanning marine, automotive, and flooring specifications compress competitor reformulation cycles. |
Methodological Framework
Multi-period observation of REACH registration timelines, OSHA enforcement patterns, and marine coating specification adoption anchored the trend analysis, supplemented by interviews with coating formulator technical directors, industrial flooring contractor procurement leads, automotive OEM platform engineers, shipbuilder specification managers, and ECHA regulatory affairs specialists. Secondary validation drew from ECHA dossier databases, SEC 10-K filings of listed coating specialists, customs trade data for precipitated silica flows, and DIN/ASTM test methodology documentation. Bottom-up additive demand modeling triangulated against top-down construction and automotive production forecasts.
The input-output matrix framed volume and value projections across product type, application, end user, and form dimensions over the analysis window. CAGRs were derived from segment-level demand elasticity modeling against industrial construction spending and automotive lightweighting investment cycles. Forecast inputs included shipbuilding orderbook data from Hamburg and Ulsan, automotive underbody coating content per vehicle trajectories, and BIS standards adoption timelines in Indian industrial clusters.
The model assumes a particular technology adoption path for nano-structured precipitated silicas; alternative pathways for surface treatment chemistry decentralization would alter the outlook for German and Japanese supplier premium positioning. Forecasts reflect assumptions regarding REACH enforcement consistency and OSHA General Industry Standards 1910.22 inspection intensity. A model refresh is warranted upon material change in EU Green Deal CSRD reporting implementation or India BIS enforcement acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Global Cement and Concrete Additives Market
Additives
Oilfield Drilling Fluid Additive Market
Additives
Refinery Fuel Additives Market
Additives
Acrylamide Reducing Ingredients Market
Additives
Extruded Inclusions Market
Additives
Competitive Inhibitors Market
Additives
Butyrate Additives Market
Additives
Chelating Agents Market
Additives
Chitosan Powder Market
Additives
Driveline Additives Market
Additives
Engine Oil Additive Market
Additives
Iso-Butyric Acid Market
Additives
Global Carboxylic Acids Based Esters Market
Additives
Global Asphalt Additives Market
Additives
Piperonyl Butoxide (PBO) Market
Additives
Sodium Benzoate Market