
 Hydroxypropyl Distarch Phosphate Market | 2026-2036
Hydroxypropyl Distarch Phosphate Market Size, Share, and Industry Trends Forecast 2026-2036
Hydroxypropyl Distarch Phosphate Market Foresight
Specialized food chemist talent is reorganizing production capacity across modified starch suppliers. Tate & Lyle leverages its European ingredient science network to sustain technical service density for bakery clients. Ingredion Incorporated anchors North American supply through its corn wet milling infrastructure. Roquette Frères competes on pea-derived starch alternatives that differentiate its portfolio from conventional corn and potato sources.
Hydroxypropyl distarch phosphate is a cross-linked and etherified starch derivative produced by treating native starch with propylene oxide and phosphorylating agents, yielding resistance to acid, heat, and shear stress while maintaining viscosity stability. Food grade dominates volume as clean-label emulsifiers and thickeners replace synthetic additives in sauces and dressings. Powder form leads manufacturing economics due to lower transport costs and extended shelf stability, though liquid formulations are gaining traction in continuous-process dairy operations.
FDA food additive regulations and GRAS self-determination frameworks govern US market entry, while EFSA and REACH compliance shape European formulation standards and import documentation. China's NMPA and GB standards impose additional testing protocols for pharmaceutical grade material entering clinical nutrition supply chains. Stakeholders must monitor evolving dual carbon goals in China and the EU Green Deal's embodied carbon tracking requirements, as these will determine which production geographies retain cost-competitive access to regulated end markets.
Market Dynamics
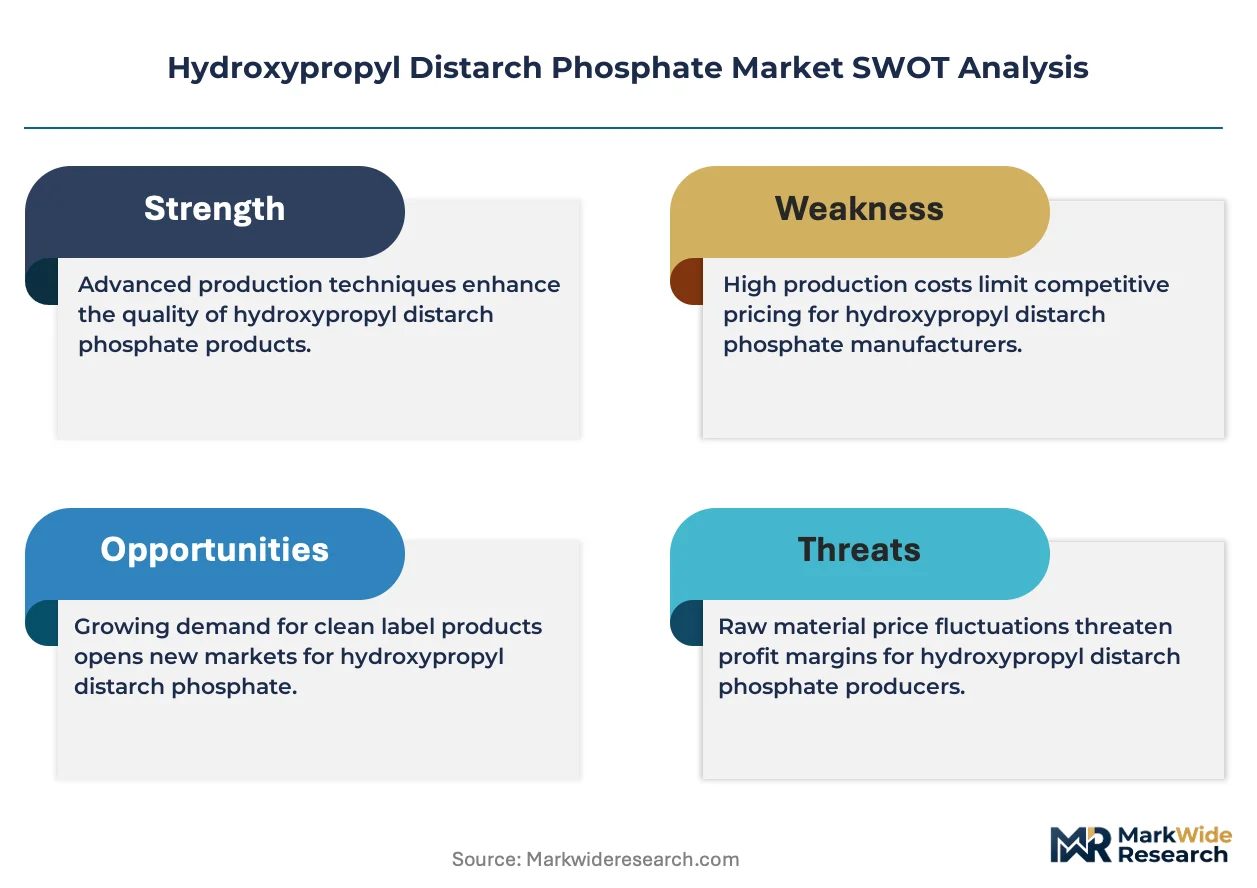
Clean-label reformulation mandates from EFSA and FDA are forcing starch suppliers to reengineer cross-linking chemistries while maintaining functional parity with synthetic alternatives.
Growth Catalysts
- REACH Phase-In Substances:ECHA's updated registration requirements for modified starches are accelerating compliance investments that favor established producers with dedicated regulatory affairs teams.
- Continuous-process dairy:Liquid HDP adoption in automated dairy lines is expanding as processors seek shear-stable thickeners for UHT and aseptic packaging operations.
- German bakery clusters:Concentrated demand from industrial bread and pastry manufacturers in Baden-Württemberg and Bavaria is anchoring regional capacity expansions.
Market Restraints
- Propylene oxide supply volatility:Petrochemical feedstock fluctuations and refinery maintenance cycles create input cost instability for etherification processes.
- Chinese corn wet milling dominance:Concentration of native starch supply in Shandong and Jilin provinces exposes downstream modifiers to single-geography disruption risk.
- Pea protein starch competition:Roquette's pea-derived alternatives are capturing clean-label share in premium sauce and dressing formulations.
Strategic Opportunities
- Clinical nutrition penetration:China's NMPA pharmaceutical-grade pathway for enteral feeding products offers regulated entry into high-margin medical applications.
- EU Green Deal embodied carbon tracking:Carbon footprint disclosure requirements will advantage European producers with renewable energy-integrated facilities.
- E-commerce ingredient platforms:Direct procurement channels serving mid-sized food manufacturers are compressing distributor margins and expanding addressable accounts.
Industry Challenges
- Cross-linked starch chemist scarcity:Specialized expertise in propylene oxide handling and phosphorylation kinetics is concentrated among retiring technical staff at legacy suppliers.
- Dual certification timelines:Simultaneous FDA GRAS self-determination and EFSA novel food assessments extend product launch cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydroxypropyl Distarch Phosphate Market |
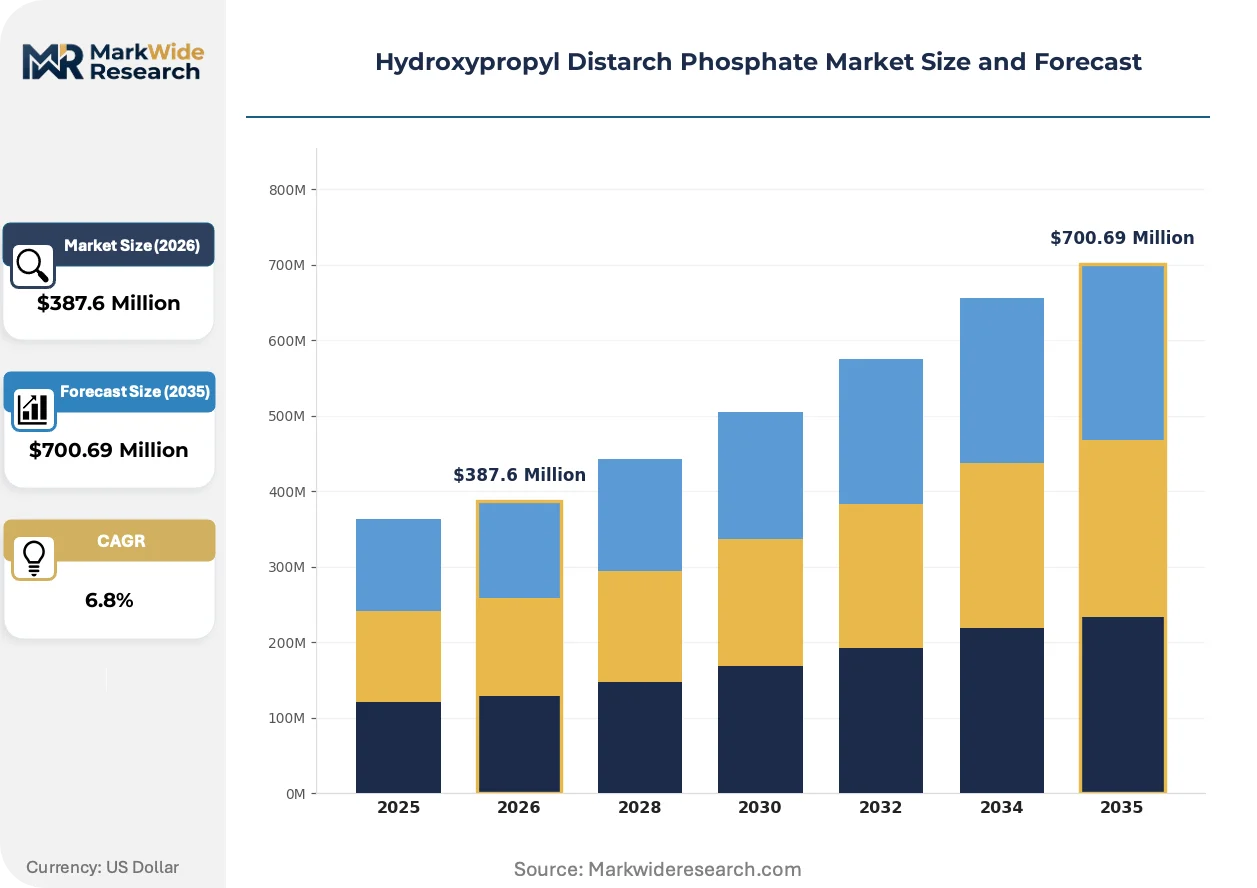
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food Grade, Industrial Grade, Pharmaceutical Grade, Cosmetic Grade Application: Baking, Sauces, Dressings, Dairy Products End User: Food Manufacturers, Pharmaceutical Companies, Cosmetic Manufacturers, Personal Care Brands Form: Powder, Granule, Liquid, Paste |
| Companies Covered | Tate & Lyle, Avebe, Ingredion Incorporated, Grain Processing Corporation, BENEO, Roquette Frères, AGRANA Beteiligungs AG, Nouryon, Cargill, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydroxypropyl Distarch Phosphate Market Shifts & Advancements
Reformulation pressures are converging with process intensification demands to reshape how modified starches are specified, supplied, and integrated into finished food systems.
Enzymatic phosphorylation is supplanting conventional chemical cross-linking in premium clean-label applications. Specialty sauce manufacturers in France and the Netherlands are piloting these processes to eliminate residual phosphate concerns. The technology is supplanting traditional HDP in organic-certified product lines where synthetic process aids face prohibition.
EU F-Gas Regulation restrictions on fluorinated greenhouse gases are indirectly tightening energy efficiency requirements for spray-drying operations used in powder HDP production. Manufacturers in Belgium and Italy are retrofitting drying towers with heat recovery systems to maintain cost parity. Food-grade powder operations face the steepest compliance cost escalation.
Buyer consolidation among multinational dairy processors is compressing supplier qualification cycles and demanding integrated technical service packages. Mid-sized starch suppliers are losing direct access to formulation decisions as procurement centralizes at headquarters level. Germany and Denmark exhibit the most pronounced buyer concentration effects.
Hydroxypropyl Distarch Phosphate Market Segmentation
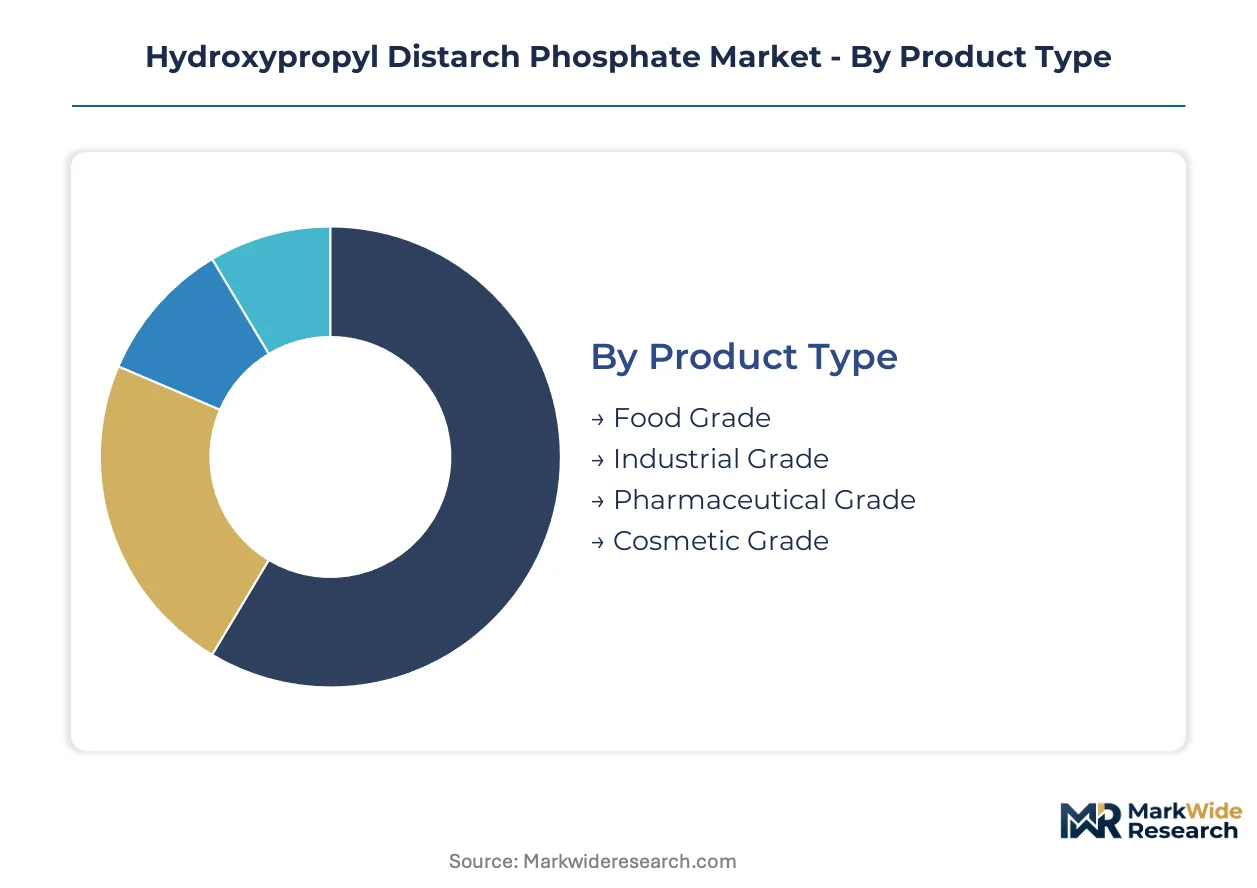
Segmentation in hydroxypropyl distarch phosphate markets reveals how functional requirements and regulatory pathways fragment demand across distinct procurement channels. Each category exposes different margin structures and qualification barriers that determine supplier access.
Product Type:
Food-grade material moves through bulk ingredient distributors serving industrial bakeries and sauce manufacturers, while pharmaceutical grades require direct contractual relationships with enteral nutrition formulators.
- Food Grade:Cross-linked and etherified starch meeting FDA GRAS and EFSA food additive standards, with viscosity stability under acid and heat stress. Demand concentrates in German industrial bread and pastry clusters where clean-label reformulation mandates from EFSA are displacing synthetic emulsifiers.
- Pharmaceutical Grade:Material produced under GMP conditions with NMPA or FDA drug master file documentation for clinical nutrition applications. China's enteral feeding supply chains are absorbing volumes as domestic hospital formulary expansion outpaces import capacity.
- Industrial Grade:Technical specifications for paper and textile sizing, sourced through chemical distributors rather than food ingredient channels.
- Cosmetic Grade:Refined for skincare emulsion stability, typically procured by personal care contract manufacturers in France and Italy.
By volume, Food Grade leads. By growth pace, Pharmaceutical Grade is climbing the fastest.
Application:
Cost tier separation distinguishes commodity sauce formulations from premium dairy applications requiring shear-stable viscosity under UHT processing.
- Baking:Industrial bread and pastry manufacturers in Baden-Württemberg and Bavaria specify HDP for dough conditioning and extended shelf life. German bakery clusters anchor regional consumption as centralized procurement at multinational headquarters compresses supplier lists.
- Dairy Products:UHT milk, yogurt, and aseptically packaged desserts demand liquid HDP formulations with shear resistance through homogenization. Continuous-process dairy lines in Denmark and Germany are expanding automated thickener dosing systems.
- Sauces:Pourable emulsions for foodservice and retail, where enzymatic phosphorylation alternatives are capturing organic-certified share.
- Dressings:Cold-process mayonnaise and vinaigrette applications, facing displacement from Roquette's pea-derived clean-label starches in premium segments.
By volume, Baking leads. By margin expansion, Dairy Products is gaining share fastest.
End User:
Customer type determines technical service intensity and regulatory documentation burden, with pharmaceutical and cosmetic buyers demanding integrated formulation support.
- Food Manufacturers:Multinational dairy and bakery processors with centralized procurement headquarters in Germany and Denmark. These buyers compress supplier qualification cycles and demand bundled technical service packages.
- Pharmaceutical Companies:Enteral nutrition and clinical feeding product formulators navigating China's NMPA pharmaceutical-grade pathway. Documentation requirements extend launch timelines but secure high-margin contracted supply.
- Cosmetic Manufacturers:Contract producers of skincare emulsions in France and Italy, procuring through specialized cosmetic ingredient distributors.
- Personal Care Brands:Direct-to-consumer beauty companies with sustainability disclosure requirements aligned to EU Green Deal embodied carbon tracking.
By volume, Food Manufacturers lead. By contract value concentration, Pharmaceutical Companies are expanding most quickly.
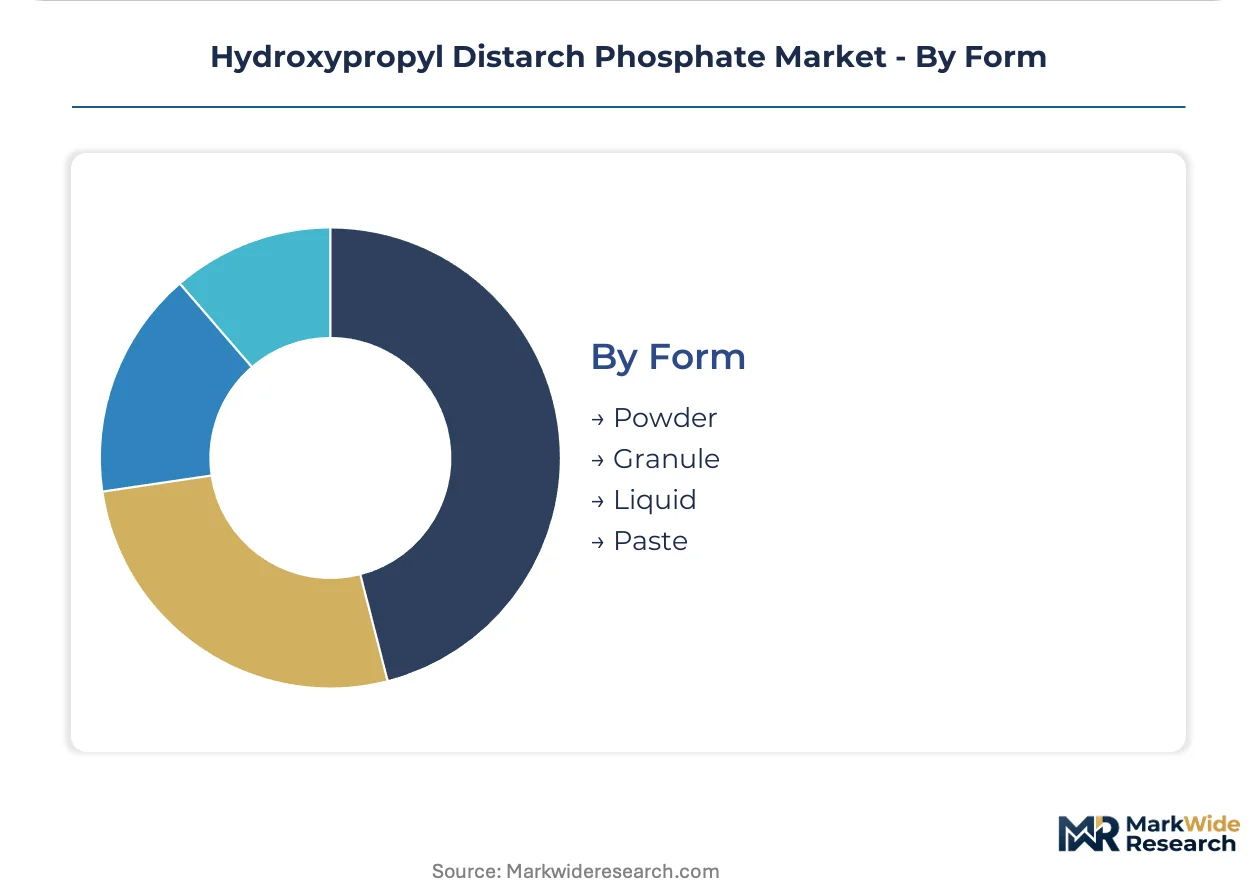
Form:
Supply concentration in powder production reflects manufacturing economics, while liquid form adoption tracks dairy processor automation investments.
- Powder:Spray-dried material with lower transport costs and extended shelf stability. EU F-Gas Regulation compliance costs for drying tower heat recovery are escalating production economics in Belgium and Italy.
- Liquid:Pre-hydrated suspensions for continuous-process dairy operations with automated dosing systems. UHT and aseptic packaging lines in Denmark and Germany are standardizing liquid HDP specifications.
- Granule:Intermediate flowability grade for dry-blend applications, typically specified by mid-sized sauce manufacturers.
- Paste:High-moisture concentrate for specialized bakery and confectionery applications with limited geographic penetration.
By volume, Powder leads. By adoption velocity, Liquid is ahead.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German bakery and dairy clusters while Chinese corn wet milling dominance suppresses input costs for Asia-Pacific modifiers. European producers absorb F-Gas Regulation compliance premiums that North American rivals avoid. Regional sourcing patterns fragment as carbon disclosure requirements reshape procurement geography.
United States
FDA GRAS self-determination frameworks govern clean-label reformulation by industrial sauce manufacturers. The EPA monitors propylene oxide handling standards at starch modification facilities. Midwest corn wet milling corridors in Iowa and Illinois supply native starch feedstock to downstream modifiers serving Cargill and Ingredion processing networks.
Germany
Baden-Württemberg and Bavaria bakery clusters anchor European HDP consumption for dough conditioning applications. EFSA clean-label mandates and REACH Phase-In Substances registration accelerate compliance investments by established producers. Dairy processors in Lower Saxony deploy automated liquid HDP dosing systems for UHT milk lines.
China
NMPA pharmaceutical-grade pathways attract enteral nutrition formulators seeking high-margin medical applications. Dual carbon goals and GB standards impose testing protocols on clinical nutrition supply chains. Shandong and Jilin corn wet milling concentration exposes downstream modifiers to single-geography disruption risk.
France
Specialty sauce manufacturers in Provence-Alpes-Côte d'Azur pilot enzymatic phosphorylation for organic-certified product lines. EU Green Deal embodied carbon tracking advantages producers with renewable energy-integrated facilities. Cosmetic contract manufacturers in Île-de-France procure refined grades for skincare emulsion stability.
Denmark
Multinational dairy processor headquarters compress supplier qualification cycles and demand bundled technical service packages. Continuous-process automation investments standardize liquid HDP specifications for aseptic packaging operations. Arla Foods procurement centralization exemplifies buyer concentration effects reshaping Nordic supply relationships.
Hydroxypropyl Distarch Phosphate Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with European specialists commanding premium positioning through regulatory compliance density while Asian corn-integrated processors dominate volume economics. The market structures around three tiers: multinational ingredient conglomerates with wet milling infrastructure, regional specialists in clean-label alternatives, and contract manufacturers serving pharmaceutical-grade niches. Dominant competitive moves include backward integration into native starch supply and geographic expansion through distributor acquisition.
Within the multinational conglomerate tier, Tate & Lyle and Ingredion Incorporated exemplify scale-driven positions anchored by North American and European ingredient science networks. Roquette Frères occupies a distinct specialization vector through pea-derived starch alternatives that differentiate its portfolio from conventional corn and potato sources. These three entities represent the primary competitive anchors reshaping procurement relationships with centralized dairy and bakery processors.
| Leading Market Players |
|---|
| Tate & Lyle |
| Avebe |
| Ingredion Incorporated |
| Grain Processing Corporation |
| BENEO |
| Roquette Frères |
| AGRANA Beteiligungs AG |
| Nouryon |
| Cargill |
| Others |
Supply & Pricing Matrix
Spray-drying capacity utilization in Belgium and Italy determines powder HDP price floors as EU F-Gas Regulation compliance costs concentrate among legacy producers. Scale advantages tether to heat recovery retrofits that smaller modifiers cannot absorb, compressing margin structures for non-integrated players while contract manufacturers capture premium spreads in pharmaceutical grades.
Pricing Analysis
Configured-to-order pharmaceutical-grade material commands substantial premiums over standard food-grade powder as NMPA documentation and GMP compliance layer qualification costs onto unit economics. Three-tier pricing structure across premium pharmaceutical, standard food-grade, and economy industrial grades separates buyers by certification burden and volume scale. Pricing pressure stems from enzymatic phosphorylation alternatives capturing organic-certified sauce formulations. Mid-sized sauce manufacturers exhibit highest price sensitivity, while enteral nutrition formulators prioritize supply security over unit cost.
Supply Chain Analysis
Inventory cycles for propylene oxide feedstock extend lead times through refinery maintenance windows, forcing modifiers to carry buffer stocks against etherification schedule disruptions. Native starch supply concentrates in Shandong and Jilin provinces of China, with Midwest corn wet milling corridors in Iowa and Illinois providing North American alternatives. Propylene oxide, phosphorylating agents, and native starch constitute the critical input trinity. Single-geography concentration in Chinese corn wet milling exposes downstream modifiers to disruption risk. Distribution runs through bulk ingredient distributors serving industrial bakeries and direct contractual channels for pharmaceutical buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Clean-label reformulation mandates from EFSA and FDA constitute a regulatory inflection accelerating enzymatic phosphorylation substitution, reshaping competitive viability for conventional HDP suppliers.
For Market Incumbents: Consolidate technical service density around German bakery and Danish dairy clusters where centralized procurement compresses supplier lists. Backward integration into native starch supply through captive corn wet milling or long-term offtake agreements with Shandong processors defends margin position against propylene oxide volatility. Prioritize REACH Phase-In Substances registration completion to exploit compliance investments that burden smaller competitors. For New Entrants and Emerging Players: Technical service gaps in mid-sized food manufacturer segments, where multinational incumbents cede direct access to distributor intermediaries, offer white-space entry points. China's NMPA pharmaceutical-grade pathway for enteral nutrition presents the most penetrable high-margin segment. Target e-commerce ingredient platforms serving regional sauce and dressing formulators with bundled formulation support as the primary go-to-market angle. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors regional specialists with enzymatic phosphorylation capabilities and renewable energy-integrated production facilities. Long-term viability across the projection horizon rests on carbon disclosure compliance density rather than scale alone. Acquisition target archetype: European modifiers with EU Green Deal-aligned heat recovery infrastructure and existing EFSA regulatory affairs teams. Watch enzymatic phosphorylation cost parity milestones as the critical inflection signal for conventional HDP demand erosion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Native Starch Supply | Captive corn wet milling in Iowa or Shandong insulates against feedstock disruption and input cost volatility. |
| Heat Recovery Retrofit for Spray-Drying Towers | EU F-Gas Regulation compliance in Belgium and Italy preserves cost parity against North American rivals. |
| NMPA Pharmaceutical-Grade Certification Investment | Documentation for China's enteral nutrition pathway secures high-margin contracted supply relationships. |
| Enzymatic Phosphorylation Pilot Scale-Up | Organic-certified production lines in France and Netherlands capture clean-label premium segments. |
| E-Commerce Ingredient Platform Partnership | Direct procurement channels compress distributor margins and expand addressable mid-sized manufacturer accounts. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with modified starch plant managers, procurement leads at German bakery and Danish dairy processors, distribution channel partners, and technical R&D directors; and secondary validation through EFSA additive registers, REACH Phase-In Substances filings, NMPA pharmaceutical-grade documentation databases, and customs trade records. Bottom-up volume modeling triangulated against top-down value estimates derived from corn wet milling capacity disclosures and propylene oxide consumption patterns.
Across the analysis window, forecasts segmented by grade tier, end-use application, form specification, and regional production hub generated volume and value trajectories. CAGRs emerged from fitted growth curves applied to historical consumption patterns and projected clean-label reformulation penetration rates. Key inputs included EFSA mandate implementation timelines, NMPA hospital formulary expansion rates, and EU Green Deal carbon disclosure phase-in schedules.
Underlying assumptions cover regulatory compliance continuity, propylene oxide supply stability, and enzymatic phosphorylation cost reduction curves, with deviation risk concentrated in Chinese corn wet milling disruption and accelerated organic certification adoption. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Dipotassium Guanylate Market
Additives
Dishwashing Additives Market
Additives
Plasticizers Market
Additives
Sorbitan Oleate Market
Additives
Biosaccharide Gum Market
Additives
Extruded Inclusions Market
Additives
Automotive Additives Market
Additives
Diamino Stilbene Disulfonic Acid (DASDA) Market
Additives
Enzyme Stabilizer Market
Additives
Global Pearlizing Agent Market
Additives
Polysaccharides and Oligosaccharides Market
Additives
Performance Minerals Additives Market
Additives
Global Matting Agents Market
Additives
Clouding Agents Market
Additives
Citrate Ester Market
Additives
Sorbitan Laurate Market