
 Phthalic Anhydride Derivatives Market | 2026-2036
Phthalic Anhydride Derivatives Market Size, Share, and Industry Trends Forecast 2026-2036
Phthalic Anhydride Derivatives Market Analytics
ISO 9001 certification cycles for petrochemical derivative suppliers is unwinding the competitive landscape, forcing smaller compounders to exit or consolidate. BASF SE leverages its integrated Verbund structure to control feedstock costs across plasticizer and resin chains. Polynt SpA specializes in unsaturated polyester resins, anchoring its position in European coatings demand. Thirumalai Chemicals Ltd dominates South Asian phthalic anhydride output, sustaining cost advantages through captive naphthalene oxidation.
Phthalic anhydride derivatives comprise esters, anhydrides, and substituted aromatics synthesized via catalytic oxidation of o-xylene or naphthalene, serving primarily as plasticizer precursors and alkyd resin building blocks. Plasticizers command the largest value pool due to PVC compounding scale, though non-phthalate alternatives are displacing legacy chemistries in consumer-facing applications. Resins for coatings and adhesives retain stable margins, while dyes and pigments face pricing pressure from Asian intermediates competition.
REACH registration requirements in Europe, EPA TSCA Section 5 premanufacture notices in the United States, and China's GB standards for plasticizer migration collectively determine market access and formulation viability. ECHA substance evaluation is forcing reformulation timelines, while China's MEE enforcement tightens emissions controls at oxidation plants. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory and compliance cost spikes.
Market Dynamics
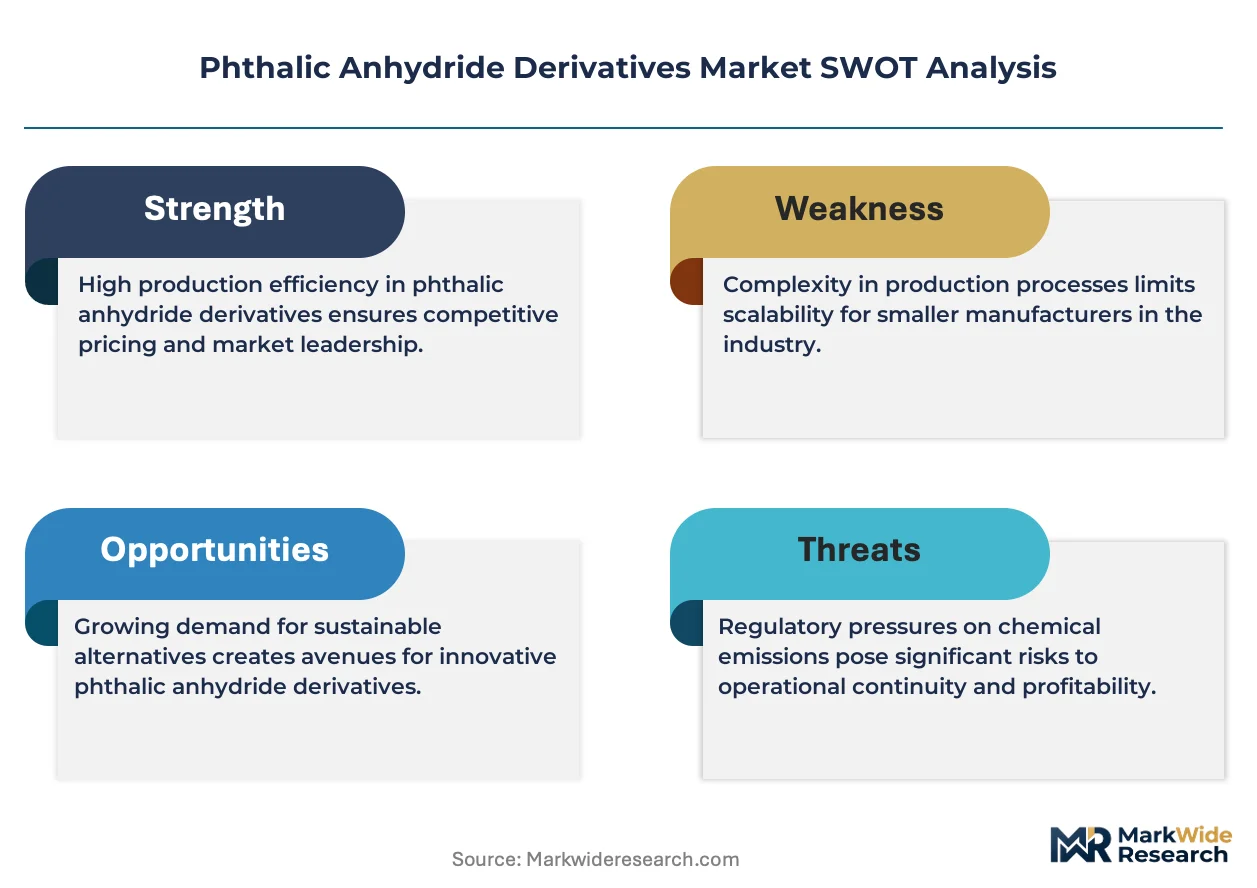
REACH substance evaluation timelines and EPA TSCA Section 5 premanufacture notice requirements are compressing reformulation cycles, forcing derivative manufacturers to accelerate non-phthalate plasticizer development or surrender consumer-facing PVC compound share.
Growth Catalysts
- Automotive lightweighting mandates:Flexible PVC interior applications in electric vehicles consume higher plasticizer loadings per vehicle as OEMs eliminate heavier thermoset alternatives.
- Construction-grade alkyd resins:India's infrastructure build-out and Southeast Asian urbanization sustain coating resin demand that anchors phthalic anhydride offtake.
- GB standards for plasticizer migration:China's tightening MEE enforcement on oxidation plant emissions is consolidating capacity toward integrated producers with scrubber investments.
Market Restraints
- Naphthalene feedstock volatility:Coal tar distillation economics swing with steel coke demand, pressuring margin stability for non-captive oxidation operators.
- Chinese production dominance:Concentration of oxidation capacity in Shandong and Jiangsu provinces creates geographic supply risk and price-setting power asymmetry.
- Non-phthalate substitution:Citrate esters and adipate alternatives are capturing medical device and food-contact PVC segments previously held by DEHP and DINP.
Strategic Opportunities
- India's specialty plasticizer deficit:Domestic formulation gaps in wire and cable sheathing invite backward integration by resin compounders with oxidation technology access.
- ISO 9001 certification arbitrage:Smaller European compounders exiting certification cycles create acquisition targets for quality-system-compliant mid-caps seeking REACH-registered substance portfolios.
- Bio-based o-xylene pathways:Catalytic biomass-to-aromatics pilot programs in Nordic clusters could decarbonize feedstock for premium resin grades.
Industry Challenges
- Cross-functional regulatory expertise:Simultaneous compliance with ECHA substance evaluation, EPA new chemical review, and GB migration limits demands toxicologists with multi-jurisdiction dossier experience that commands salary premiums.
- Catalytic oxidation reactor turnaround:Vanadium pentadium catalyst replacement cycles require 45-day shutdowns that strain working capital for single-train operators without product inventory buffers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Phthalic Anhydride Derivatives Market |
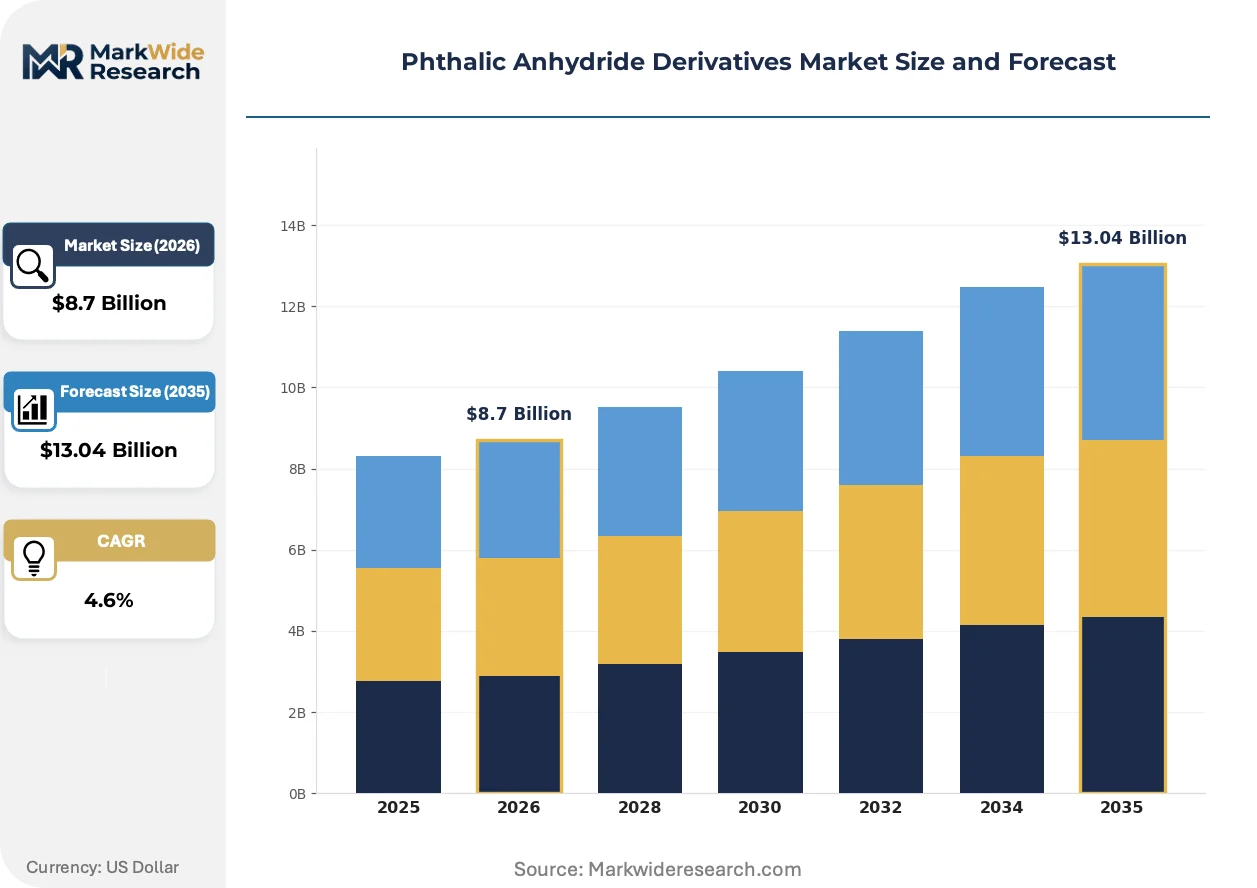
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plasticizers, Resins, Dyes, Pigments Application: Coatings, Adhesives, Sealants, Polymers End User: Construction, Automotive, Consumer Goods, Electronics Distribution Channel: Direct Sales, Online Retail, Distributors, Agents |
| Companies Covered | BASF SE, The Chemical Company, Koppers Inc., I G Petrochemicals Ltd, LANXESS, Polynt SpA, Thirumalai Chemicals Ltd, Stepan Company, JFE Chemical Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Phthalic Anhydride Derivatives Market Evolving Landscape
Formulation chemistry and regulatory enforcement are converging to accelerate non-phthalate plasticizer penetration while digital tools compress specification-to-supply timelines across derivative value chains.
Cyclohexane dicarboxylic acid esters (DINCH, DINP-alternatives) are supplanting traditional ortho-phthalates in European toy and medical device PVC compounds. Automotive interior suppliers in Germany and France have completed specification switches ahead of ECHA authorization list deadlines. The shift is compressing legacy plasticizer margins while rewarding early movers with dedicated hydrogenation capacity.
REACH registration dossier updates and ECHA substance evaluation are forcing 2025-2027 reformulation commitments for plasticizers above one tonne annual volume. Coating resin manufacturers face downstream notification obligations that extend compliance costs through alkyd supply chains. Western European formulators are consolidating supplier panels to reduce substance variety and simplify exposure scenario documentation.
Digital specification platforms are compressing buyer-supplier matching cycles from quarterly to monthly rhythms. PVC compounders in automotive supply chains now transmit real-time formulation requirements through vendor-managed inventory portals that bypass traditional distributor stocking. This channel shift is most advanced in German automotive tier-one supply bases where just-in-time delivery penalties enforce system adoption.
Phthalic Anhydride Derivatives Market Segmentation
Phthalic anhydride derivative specifications diverge sharply across end-use channels, with automotive and construction procurement teams demanding distinct certification bundles and volume profiles. Channel selection directly dictates margin capture, as direct sales to compounders bypass distributor markups while agent networks penetrate fragmented coating formulators.
Product Type:
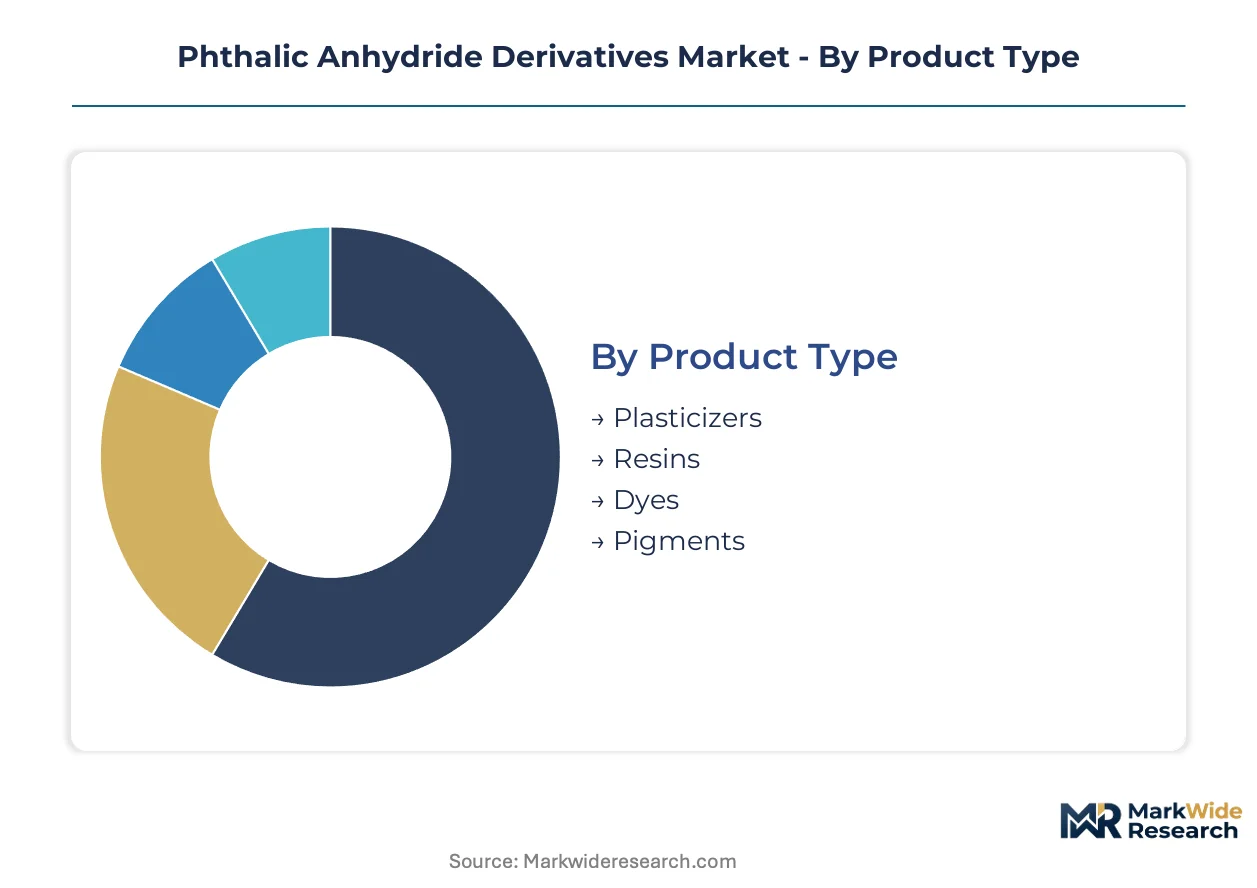
Plasticizers flow predominantly through direct sales channels to PVC compounders, while resins and pigments distribute via specialized chemical distributors with formulation technical service capabilities.
- Plasticizers:Ester compounds derived from phthalic anhydride and C8-C10 alcohols that impart flexibility to PVC matrices. Demand concentrates in automotive interior applications across Germany, France, and the United States as OEMs specify DINCH and other non-phthalate alternatives under tightening ECHA substance evaluation timelines.
- Resins:Alkyd and unsaturated polyester building blocks synthesized through polycondensation with polyols. Construction-grade alkyd consumption in India and Southeast Asia anchors volume, though coating formulators in Italy and Spain are consolidating supplier panels to simplify REACH exposure scenario documentation.
- Dyes:Anthraquinone and phthalein chromophores requiring precise sulfonation degrees for textile and printing applications.
- Pigments:Phthalocyanine blues and greens commanding premium pricing in automotive OEM coatings and electronics-grade inks.
Plasticizers dominate installed base. Resins are where expansion concentrates.
Application:
Cost tier stratification separates specification-grade coatings from commodity adhesives, with sealants occupying an intermediate position defined by weathering performance requirements.
- Coatings:Solvent-borne and water-reducible formulations incorporating alkyd resins for architectural and industrial protection. European decorative paint manufacturers in the Netherlands and Belgium are accelerating reformulation cycles ahead of ECHA authorization deadlines for legacy plasticizer coalescents.
- Adhesives:Hot-melt and solvent-based systems utilizing phthalate plasticizers for tack modulation. Electronics assembly operations in South Korea and Taiwan specify ultra-low volatility grades for precision component bonding.
- Sealants:Polyurethane and polysulfide formulations requiring plasticizer compatibility with curing catalysts.
- Polymers:PVC compounding and engineering resin modification representing the largest volume sink.
Coatings anchor value capture. Polymers are climbing the fastest.
End User:
Customer type determines procurement rhythm, with automotive and construction buyers operating on divergent specification and inventory cycles.
- Construction:Architectural coatings and sealant applications driving alkyd resin consumption. India's infrastructure build-out and Indonesian urbanization sustain phthalic anhydride offtake through local coating manufacturers.
- Automotive:Flexible PVC interior components and underbody coatings specifying migration-resistant plasticizers. German tier-one suppliers have completed DINCH switches ahead of ECHA deadlines, compressing legacy ortho-phthalate margins.
- Consumer Goods:Toy and food-contact applications facing the most stringent substitution pressure.
- Electronics:Wire and cable sheathing, plus component encapsulation, demanding thermal stability and low extractables.
Construction dominates installed base. Automotive is where specification premiums concentrate.
Distribution Channel:
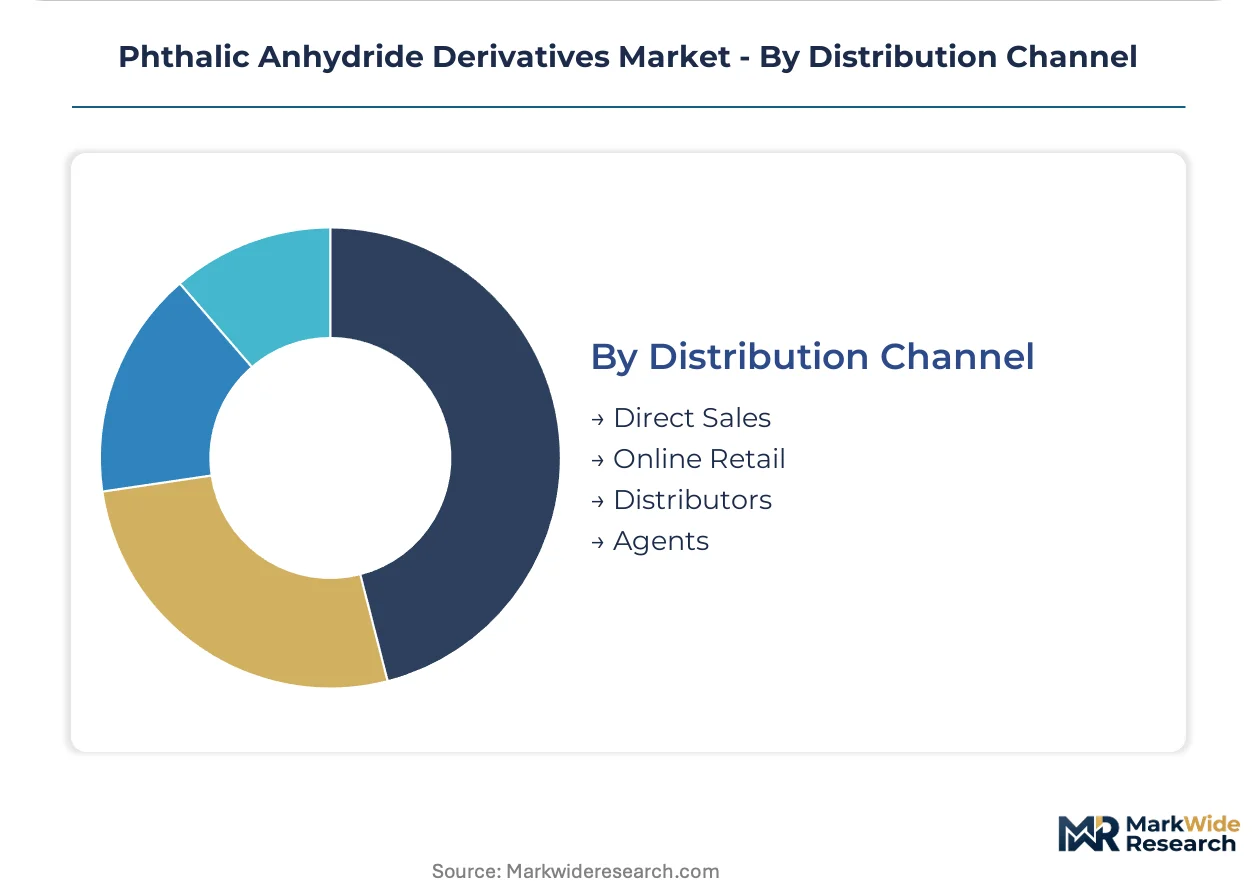
Supply concentration in Shandong and Jiangsu provinces shapes channel economics, with direct sales rewarding volume buyers and distributors capturing fragmented demand.
- Direct Sales:Bulk plasticizer and resin shipments to integrated PVC compounders and coating manufacturers. BASF SE and Polynt SpA leverage direct relationships with automotive tier-ones to enforce just-in-time delivery protocols.
- Distributors:Regional chemical distributors stocking multiple resin grades and pigment dispersions for small-to-mid coating formulators.
- Online Retail:Emerging channel for specialty pigment samples and technical documentation access.
- Agents:Commission-based representation penetrating fragmented construction chemical markets in secondary Indian and Southeast Asian cities.
Direct sales dominate volume. Distributors are where margin capture concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH substance evaluation timelines and EPA TSCA Section 5 premanufacture notice requirements are compressing reformulation cycles across major derivative-consuming economies. National regulators are accelerating non-phthalate transitions through divergent compliance instruments.
China
GB standards for plasticizer migration and MEE emissions enforcement are consolidating oxidation capacity toward integrated producers with scrubber investments. Shandong and Jiangsu provinces host the dominant production footprint. Qingdao-based compounders are expanding DINCH-equivalent hydrogenation capacity ahead of anticipated domestic authorization deadlines.
Germany
Automotive interior specifications for flexible PVC consume higher plasticizer loadings per electric vehicle as OEMs eliminate heavier thermoset alternatives. ECHA authorization list deadlines have compressed legacy ortho-phthalate margins. BASF SE's Ludwigshafen Verbund structure controls feedstock costs across plasticizer and resin chains.
United States
Construction-grade alkyd resin demand sustains coating applications despite pressure from water-borne alternatives. EPA TSCA Section 5 premanufacture notices govern new chemical introductions. Texas Gulf Coast petrochemical corridors leverage integrated naphtha crackers for captive phthalic anhydride feedstock.
India
Infrastructure build-out and urbanization sustain phthalic anhydride offtake through local coating manufacturers. BIS certification requirements for wire and cable shearding create formulation barriers for imported compounds. Thirumalai Chemicals Ltd dominates South Asian output through captive naphthalene oxidation at Tamil Nadu facilities.
Japan
Electronics assembly operations specify ultra-low volatility plasticizer grades for precision component bonding. METI chemical substance regulations align with REACH substance evaluation timelines. Chubu region resin compounders are consolidating supplier panels to simplify exposure scenario documentation.
Phthalic Anhydride Derivatives Market Competitive Landscape
Listed leaders compete with private specialists across integrated oxidation capacity and downstream formulation expertise. The vendor base stratifies between multinational chemical conglomerates with Verbund economics and regional compounders with captive feedstock positions. Three archetypes dominate: integrated petrochemical majors controlling naphtha-to-ester value chains, specialist resin manufacturers with alkyd and unsaturated polyester focus, and captive oxidation operators leveraging coal tar naphthalene economics. Competitive moves concentrate on backward integration into oxidation capacity and REACH-registered substance portfolio assembly through acquisition.
Within the integrated petrochemical tier, BASF SE exemplifies the Verbund-structured competitor controlling feedstock costs across multiple derivative chains. Among South Asian specialists, Thirumalai Chemicals Ltd occupies a position defined by captive naphthalene oxidation economics. European resin-focused players include Polynt SpA, which anchors its competitive stance in coating-grade alkyd and unsaturated polyester demand.
| Leading Market Players |
|---|
| BASF SE |
| The Chemical Company |
| Koppers Inc. |
| I G Petrochemicals Ltd |
| LANXESS |
| Polynt SpA |
| Thirumalai Chemicals Ltd |
| Stepan Company |
| JFE Chemical Corporation |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts between Shandong-based oxidation operators and European PVC compounders lock in feedstock access while capping price volatility exposure across the naphthalene-to-ester value chain. These arrangements concentrate margin protection with integrated producers possessing captive coal tar distillation capacity.
Pricing Analysis
Certification level creates the primary spread between REACH-registered substance grades and unregistered commodity esters. Contract-based long-term offtake dominates volume transactions, while spot purchases serve reformulation trial batches. Price differentiation hinges on ECHA dossier completeness and ISO 9001 quality system compliance. Cost compression in legacy ortho-phthalate tiers is intensifying because DINCH substitution has eroded specification premiums. Commodity adhesive compounders exhibit highest price sensitivity; automotive tier-ones prioritize migration compliance over unit cost.
Supply Chain Analysis
Strategic stockpile preferences dominate among European coating formulators hedging against Shandong supply interruptions, while German automotive suppliers run just-in-time vendor-managed inventory. Geographic supply concentrates in China, India, and Germany. Raw material flows draw from coal tar naphthalene, o-xylene from naphtha crackers, and C8-C10 alcohol feedstocks. Single-source vulnerability runs through Jiangsu oxidation capacity concentration. Distribution runs through direct bulk shipments to integrated compounders and specialized chemical distributors serving fragmented formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Non-phthalate plasticizer disruption is accelerating as ECHA authorization deadlines force specification switches across European automotive and medical device supply chains.
For Market Incumbents: Shield legacy margin pools by accelerating DINCH-equivalent hydrogenation capacity additions in China and India before domestic authorization deadlines replicate European substitution patterns. Prioritize REACH registration dossier updates for substances above one tonne annual volume to prevent downstream notification obligations from extending compliance costs through alkyd supply chains. For New Entrants and Emerging Players: Technical service gaps in Indian wire and cable shearding formulation invite backward integration by resin compounders with oxidation technology access. Target domestic specialty plasticizer deficit segments where BIS certification requirements create import barriers. Penetrate through toll-manufacturing partnerships with captive naphthalene oxidation operators in Tamil Nadu. For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap compounders with REACH-registered substance portfolios and ISO 9001 certification cycles that smaller European players are exiting. Long-term viability favors integrated oxidation-to-ester operators with scrubber investments consolidating Chinese capacity. Monitor ECHA substance evaluation timeline acceleration as inflection indicator for reformulation commitment windows.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Oxidation Capacity | Captive naphthalene oxidation at Thirumalai Chemicals locks in feedstock cost advantages against volatile coal tar economics. |
| REACH Registration Portfolio Assembly | Acquisition of quality-system-compliant mid-caps simplifies exposure scenario documentation for coating resin manufacturers. |
| DINCH-Equivalent Hydrogenation Scale-Up | Qingdao-based capacity expansion captures automotive interior specification switches ahead of anticipated Chinese authorization deadlines. |
| Vendor-Managed Inventory Portal Deployment | Real-time formulation transmission compresses buyer-supplier matching cycles from quarterly to monthly rhythms in German tier-one supply bases. |
| Joint Venture for Bio-Based O-Xylene Pathways | Nordic catalytic biomass-to-aromatics pilot programs could decarbonize feedstock for premium resin grades. |
Research Methodology
A standing panel of oxidation plant managers, PVC compounder procurement leads, coating formulator technical directors, and chemical distribution channel partners provided ongoing calibration across primary interview cycles. Secondary validation drew from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings, and ECHA substance evaluation dossiers. Bottom-up volume modeling across product grades and end-use applications triangulated against top-down petrochemical derivative demand estimates.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions including plasticizer grade tier, end-use industry cluster, and regional regulatory framework. CAGRs were derived from fitted growth curves applied to segment-level baseline estimates. Industry-specific forecast inputs incorporated automotive lightweighting content-per-vehicle trajectories and construction-grade alkyd resin demand from Indian infrastructure build-out data.
Underlying assumptions cover REACH enforcement continuity, naphthalene feedstock availability, and plasticizer migration standard stability, with deviation risk concentrated in regulatory timeline acceleration or coal tar distillation economics swings. Revision becomes warranted when ECHA authorization list expansion crosses thresholds that compress legacy reformulation windows below catalytic oxidation reactor turnaround cycles.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Biosaccharide Gum Market
Additives
Grinding Aids Market
Additives
Global Feed Acidifiers Market
Additives
Lubricant Additives Market
Additives
United States Citric Acid Market
Additives
Hydroxypropyl Distarch Phosphate Market
Additives
South America Concrete Admixtures Market
Additives
Anti-Pollution Ingredients Market
Additives
Cold Flow Improvers Market
Additives
Flux Injection System Market
Additives
Europe Choline Chloride Market
Additives
Potassium Nitrate Market
Additives
Global Caprylhydroxamic Acid Market
Additives
Plastic Fillers Market
Additives
Polysorbate-80 Market
Additives
Antioxidant and Stabilizer Agents Market