
 Polyols and Sorbitols Products Market | 2026-2036
Polyols and Sorbitols Products Market Size, Share, and Industry Trends Forecast 2026-2036
Polyols and Sorbitols Products Market Analytics
The EU Green Deal is consolidating demand for bio-based polyol production across European food and pharmaceutical supply chains. Roquette Frères leverages its starch-processing heritage to dominate crystalline sorbitol supply for oral care and confectionery applications. Cargill, Incorporated sustains broad geographic coverage through integrated corn wet-milling infrastructure that feeds both food-grade and industrial polyol lines. Südzucker AG anchors Central European supply with beet sugar-derived polyol specialization, competing against grain-based rivals on feedstock flexibility.
Polyols and sorbitols comprise hydrogenated carbohydrate derivatives with hydroxyl functionality typically ranging from four to six groups per molecule, manufactured through catalytic hydrogenation of reducing sugars under controlled temperature and pressure to yield sugar alcohols with reduced caloric content and modified hygroscopic properties. These compounds serve primarily as bulk sweeteners, humectants, stabilizers, and excipients across formulated consumer and industrial products. Sorbitol liquid formulations maintain the largest volume position due to established use in toothpaste and sugar-free confectionery, while erythritol crystalline grades are capturing the fastest growth trajectory driven by keto-label food manufacturer procurement and zero-glycemic-index positioning. Powder and granular mannitol commands premium margin pools within pharmaceutical applications where compressibility and compatibility with active pharmaceutical ingredients determine supplier selection.
The FDA maintains strict purity and labeling standards for polyol use in food and drug applications, while REACH registration requirements in Europe govern chemical safety documentation for industrial polyol volumes. China's NMPA enforces pharmaceutical excipient quality protocols that influence mannitol import specifications and domestic manufacturing upgrades. Stakeholders must monitor evolving sugar-reduction mandates from health regulators and corresponding reformulation requirements from packaged food manufacturers to align capacity investments with shifting end-user specifications.
Market Dynamics
Food and pharmaceutical manufacturers are reformulating product portfolios to satisfy tightening sugar-reduction mandates from health regulators across multiple jurisdictions, redirecting procurement toward hydrogenated carbohydrate sweeteners with validated glycemic profiles.
Growth Catalysts
- Sugar Reduction Mandates:The EU Green Deal's bioeconomy targets redirect European investment toward plant-derived polyol feedstocks for food and oral care applications.
- China:Domestic pharmaceutical firms expand mannitol capacity to serve excipient demand from NMPA-regulated drug manufacturers.
- Keto-Label Positioning:Erythritol crystalline grades capture formulation share from sugar alcohols with higher caloric density in North American functional food production.
Market Restraints
- Corn Price Volatility:Wet-milling feedstock costs fluctuate with grain commodity cycles, compressing margins for sorbitol producers dependent on corn-derived glucose.
- Supply Concentration:Crystalline sorbitol production clusters among European starch processors, creating single-source vulnerability for oral care compounders.
- Technical Limitation:Mannitol's low hygroscopicity restricts applications in moisture-sensitive confectionery where sorbitol dominates despite higher caloric content.
Strategic Opportunities
- Underpenetrated Geographies:Southeast Asian food manufacturers lack localized polyol blending capacity, creating import substitution openings for integrated producers.
- Regulatory Tailwind:India's FSSAI sugar-labeling rules accelerate reformulation demand from packaged food brands seeking clean-label positioning.
- Technology Convergence:Continuous hydrogenation reactor designs merge with membrane filtration to yield pharmaceutical-grade mannitol with reduced solvent residues.
Industry Challenges
- Capex Intensity:Pharmaceutical-grade crystallization trains require stainless steel infrastructure and cleanroom packaging lines that strain mid-tier producer balance sheets.
- Certification Timeline:REACH registration dossiers for novel polyol derivatives face 18-24 month ECHA review cycles that delay commercial launch.
- Integration Complexity:Legacy ERP systems at established food compounders resist real-time lot-tracking protocols demanded by pharmaceutical excipient buyers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyols and Sorbitols Products Market |
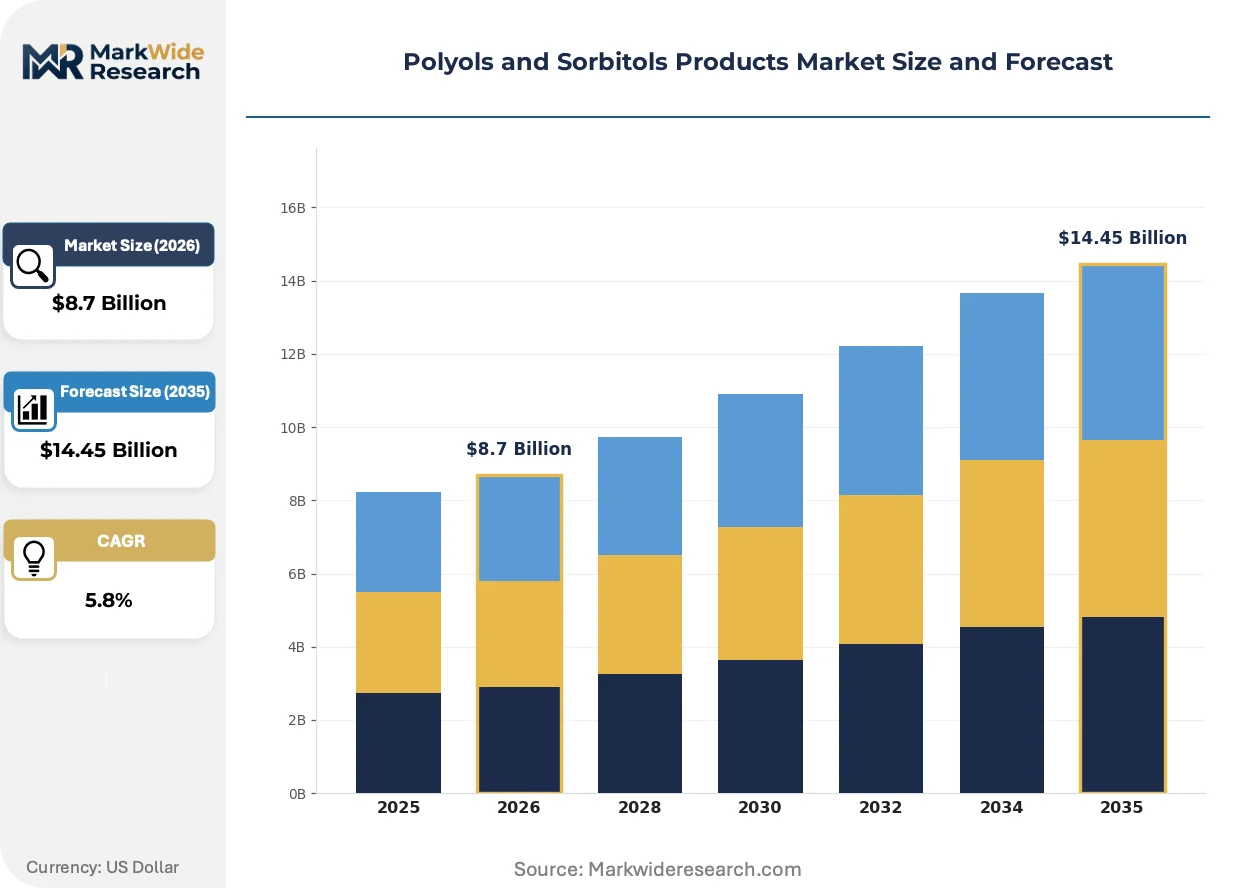
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
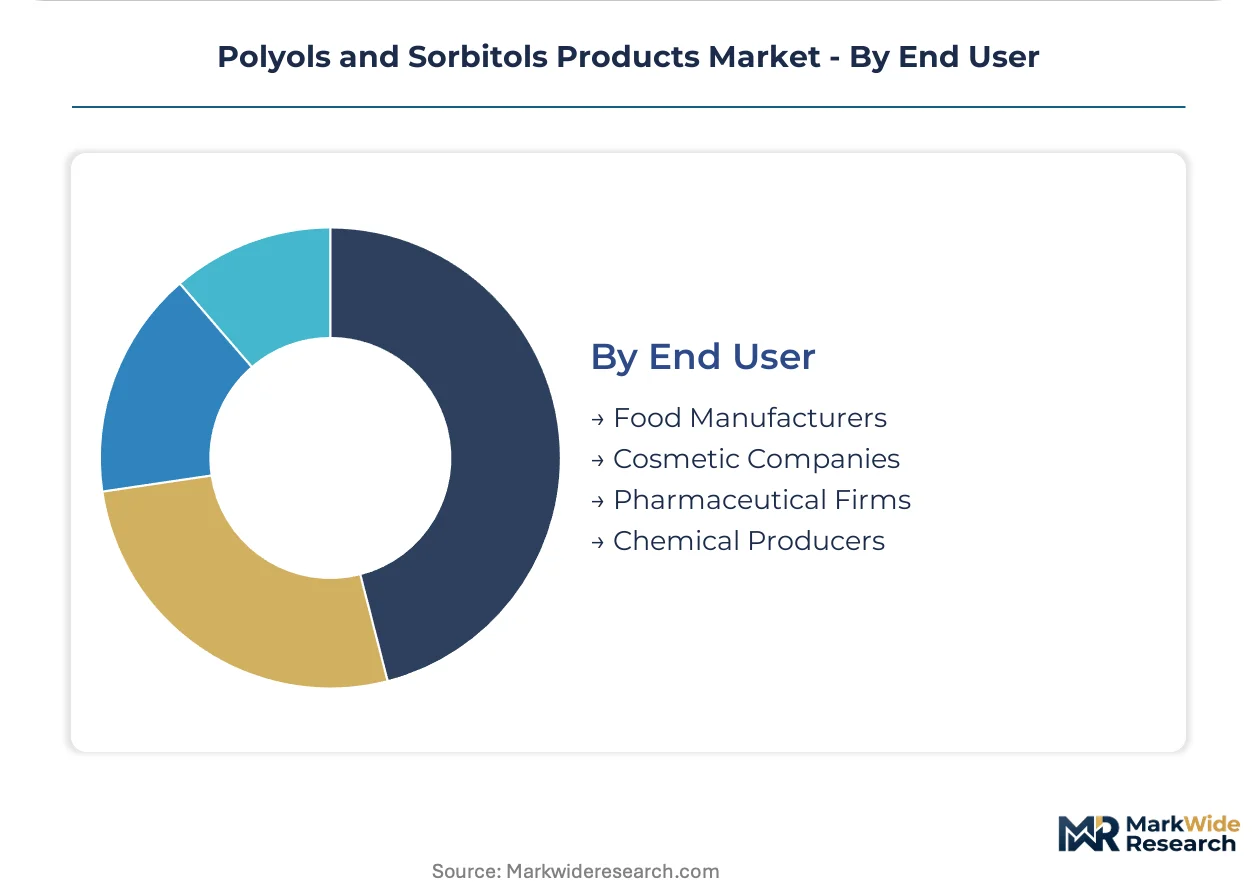
| Segmentation | Product Type: Sorbitol, Mannitol, Xylitol, Erythritol Application: Food and Beverages, Pharmaceuticals, Personal Care, Industrial Form: Liquid, Powder, Granular, Crystalline End User: Food Manufacturers, Cosmetic Companies, Pharmaceutical Firms, Chemical Producers |
| Companies Covered | Roquette Frères, Cargill, Incorporated, Archer Daniels Midland Company, Ingredion Incorporated, Tereos S.A., Gulshan Polyols Ltd., SPI Pharma, Inc., Südzucker AG, Merck KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyols and Sorbitols Products Market Evolving Landscape
Enzymatic conversion pathways and continuous processing architectures are displacing batch hydrogenation across polyol manufacturing, while regulatory pressure on sugar content accelerates end-use diversification beyond traditional confectionery and oral care segments.
Continuous catalytic hydrogenation technology is integrating into sorbitol production lines to replace batch reactor configurations. European and Asian starch processors adopt these systems to reduce energy intensity and improve yield consistency. The technology is integrating process control automation that compresses cycle times and narrows product specification bands for pharmaceutical customers.
REACH registration requirements govern chemical safety documentation for industrial polyol volumes entering European supply chains. ECHA's substance evaluation program forces manufacturers to upgrade toxicological data packages or face use restrictions. Industrial-grade sorbitol destined for polyurethane foam applications bears the heaviest compliance burden, driving some producers toward food-grade-only certification.
Direct procurement relationships between polyol producers and branded food manufacturers are displacing traditional distributor intermediaries in North America and Western Europe. Large confectionery and nutrition bar compounders negotiate volume commitments and co-development agreements for custom granulation specifications. This pattern concentrates most visibly in Germany and the Netherlands where private-label sugar-free product lines command substantial retail shelf space.
Polyols and Sorbitols Products Market Segmentation
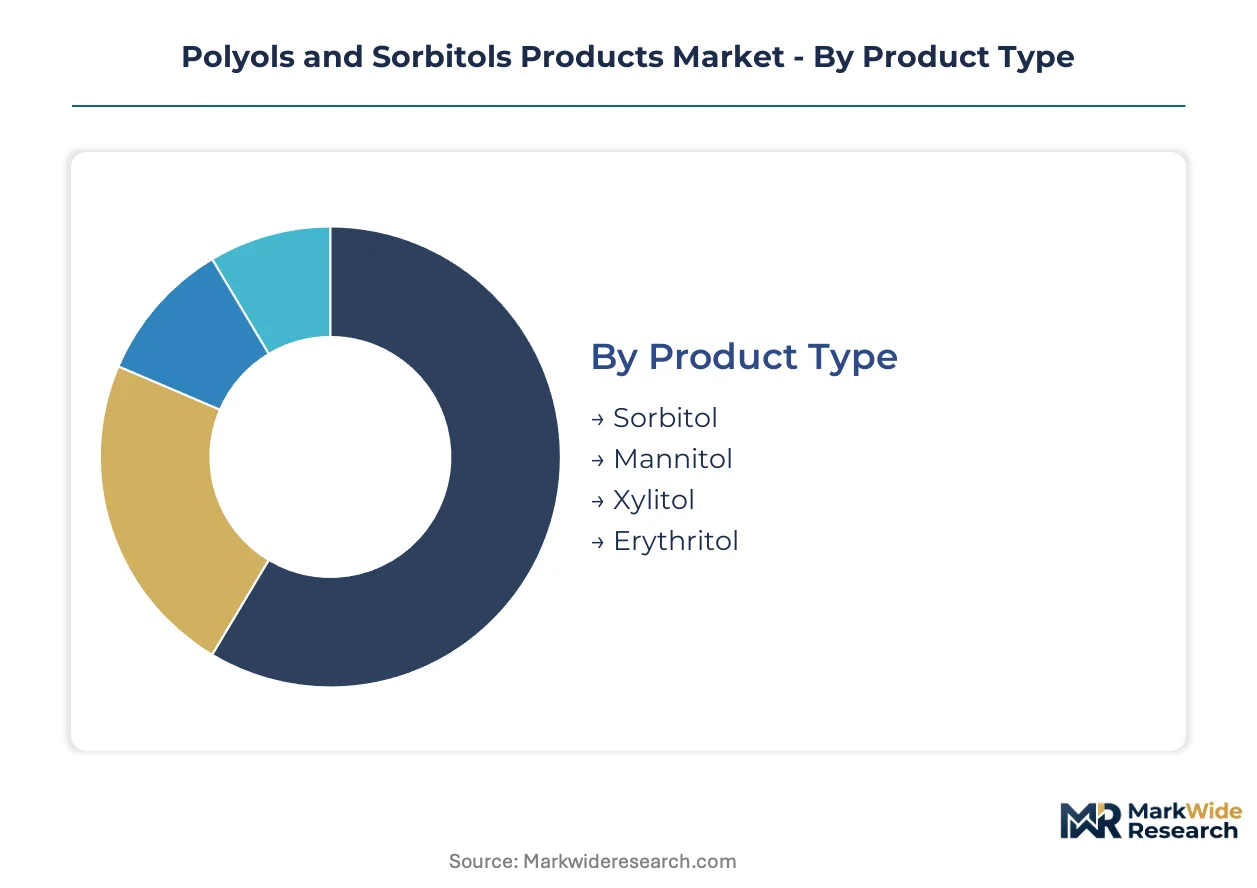
Polyol specifications diverge sharply across end-use requirements, with pharmaceutical compressibility standards, food-grade hygroscopicity thresholds, and industrial reactivity profiles creating incompatible supply tiers. Manufacturers configure hydrogenation and crystallization assets around these technical boundaries, fragmenting competitive positioning across specification bands.
Product Type:
Crystallization kinetics and hydroxyl group density separate commodity positioning from premium-grade capture in hydrogenated carbohydrate manufacturing.
- Sorbitol:Catalytic hydrogenation of glucose yields hexahydric alcohol with six hydroxyl groups and 2.6 kcal/g caloric density. Liquid sorbitol dominates toothpaste humectant procurement from Colgate-Palmolive and Unilever manufacturing sites in Mexico and Poland, while crystalline grades supply sugar-free gum base from Wrigley compounders in Tennessee and Georgia.
- Erythritol:Fermentative conversion of glucose by osmophilic yeast strains produces four-carbon sugar alcohol with near-zero glycemic index and 0.2 kcal/g caloric content. Keto-label positioning by Quest Nutrition and Perfect Keto in California and Colorado is compressing formulation share from higher-caloric polyols in protein bar and confectionery applications.
- Mannitol:Derived from fructose hydrogenation or seaweed extraction, this hexahydric alcohol exhibits low hygroscopicity and superior compressibility for tablet manufacturing.
- Xylitol:Birch wood hydrolysate or corn cob fermentation yields five-carbon pentitol with cooling effect and dental caries inhibition properties.
Sorbitol leads on scale; erythritol leads on momentum.
Application:
Regulatory validation requirements and formulation complexity create divergent margin structures across consumer and industrial demand pools.
- Food and Beverages:Sugar reduction mandates from FDA Nutrition Facts labeling rules and EU Green Deal bioeconomy targets are redirecting procurement toward hydrogenated sweeteners. Nestlé and PepsiCo reformulation teams in Switzerland and New York specify granular sorbitol for sugar-free chocolate and reduced-calorie beverage applications.
- Pharmaceuticals:NMPA excipient quality protocols and FDA IIG (Inactive Ingredient Guide) listings govern mannitol procurement for tablet diluents and lyophilization bulking agents. Pfizer and Roche manufacturing sites in Suzhou and Basel demand pharmaceutical-grade crystalline mannitol with validated particle size distribution and endotoxin documentation.
- Personal Care:Humectant and emollient functionality drives sorbitol liquid demand from L'Oréal and Estée Lauder formulation facilities in New Jersey and Île-de-France.
- Industrial:Polyurethane foam and alkyd resin applications consume technical-grade sorbitol for polyether polyol feedstock in BASF and Covestro production complexes.
Food and Beverages commands volume concentration; Pharmaceuticals captures premium expansion.
Form:
Physical state determines packaging infrastructure, shelf stability, and downstream handling economics across supply chain configurations.
- Liquid:Aqueous sorbitol solutions at 70% solids concentration serve toothpaste manufacturers and confectionery compounders requiring pumpable feedstock. Procter & Gamble oral care facilities in Iowa and Guangdong specify liquid delivery to eliminate powder handling and dust containment capital.
- Crystalline:Controlled cooling and seeding protocols yield high-purity sorbitol and mannitol crystals with defined morphology for pharmaceutical compressibility. Merck KGaA and Roquette Frères crystallization trains in Lestrem and Darmstadt supply excipient grades with batch-specific COA documentation.
- Powder:Spray-dried or milled grades provide rapid dissolution for instant beverage and nutritional powder applications.
- Granular:Intermediate particle size between powder and crystalline suits tableting operations requiring moderate flow properties.
Liquid leads on scale; crystalline leads on margin extraction.
End User:
Procurement sophistication and specification stringency stratify supplier relationships across customer categories.
- Food Manufacturers:Cargill and Ingredion direct sales teams negotiate annual volume contracts with Mondelez and Mars Wrigley procurement groups, specifying custom granulation and anti-caking additive packages for chocolate and gum applications.
- Pharmaceutical Firms:Audited supplier status, IPEC GMP certification, and drug master file availability dominate excipient selection criteria at Teva and Mylan generic manufacturing operations.
- Cosmetic Companies:Clean-label positioning and RSPO mass-balance certification influence humectant procurement from L'Oréal and Unilever personal care divisions.
- Chemical Producers:Technical-grade sorbitol for polyurethane polyol synthesis prioritizes price and supply security over certification documentation.
Food Manufacturers anchor volume commitment; Pharmaceutical Firms drive specification escalation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized chemical engineers and starch-processing technicians concentrate in European and Asian manufacturing clusters where hydrogenation expertise anchors polyol production capacity.
China
Domestic pharmaceutical manufacturers expand mannitol crystallization capacity to serve excipient demand from NMPA-regulated drug producers. The National Medical Products Administration enforces upgraded pharmaceutical excipient quality protocols that drive import substitution investments. Manufacturing activity clusters in Jiangsu and Zhejiang provinces where Teva and Roche contract manufacturers source pharmaceutical-grade mannitol.
Germany
Beet sugar processors and corn wet-millers compete for polyol feedstock supply to oral care and confectionery compounders. REACH registration requirements from ECHA govern chemical safety documentation for industrial sorbitol volumes entering polyurethane applications. The Lestrem industrial complex in northern France and Frankfurt-Rhine-Main corridor host crystalline sorbitol trains supplying Merck KGaA pharmaceutical operations.
United States
Keto-label food manufacturers in California and Colorado accelerate erythritol procurement for protein bar and functional confectionery formulations. FDA Nutrition Facts labeling rules mandate added sugar disclosure that redirects reformulation toward hydrogenated carbohydrate sweeteners. Corn Belt wet-milling infrastructure in Iowa and Illinois feeds integrated sorbitol production lines serving Procter & Gamble oral care facilities.
India
Packaged food brands accelerate sugar-reduced product development to satisfy FSSAI sugar-labeling regulations and clean-label positioning requirements. The Food Safety and Standards Authority of India mandates front-of-pack nutritional disclosure that compresses reformulation timelines. Gujarat and Maharashtra host emerging polyol blending operations supplying Mondelez and domestic chocolate manufacturers.
France
Starch-processing heritage anchors crystalline sorbitol supply for European oral care and sugar-free confectionery markets. The EU Green Deal's bioeconomy targets redirect investment toward plant-derived polyol feedstocks with verified sustainability credentials. Roquette Frères maintains production leadership from Lestrem facilities serving Unilever and Colgate-Palmolive manufacturing sites in Poland and Mexico.
Polyols and Sorbitols Products Market Competitive Landscape
Capital-heavy producers compete with asset-light formulation specialists across incompatible specification tiers. Crystallization train operators with integrated feedstock control dominate pharmaceutical-grade supply, while toll processors and regional compounders capture technical-grade volumes. The competitive structure stratifies into three archetypes: integrated starch processors with captive glucose supply, pharmaceutical excipient specialists with audited GMP infrastructure, and regional toll manufacturers serving industrial polyurethane applications. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with producers securing long-term supply agreements with branded food manufacturers to displace distributor intermediaries.
Among European integrated processors, Roquette Frères and Südzucker AG exemplify the starch-heritage archetype with beet sugar and grain-based feedstock flexibility. Cargill, Incorporated occupies a position representing North American corn wet-milling scale with geographic coverage spanning food-grade and industrial polyol lines. These three entities anchor competitive positioning across incompatible specification bands where pharmaceutical compressibility standards, food-grade hygroscopicity thresholds, and industrial reactivity profiles fragment supply relationships.
| Leading Market Players |
|---|
| Roquette Frères |
| Cargill, Incorporated |
| Archer Daniels Midland Company |
| Ingredion Incorporated |
| Tereos S.A. |
| Gulshan Polyols Ltd. |
| SPI Pharma, Inc. |
| Südzucker AG |
| Merck KGaA |
| Others |
Value Network & Pricing Analysis
Specialized starch-processing technicians and catalytic hydrogenation engineers concentrate in European and Chinese manufacturing clusters, with labor-cost differentials between Lestrem and Jiangsu province widening spreads between pharmaceutical-grade and technical-grade pricing tiers. Crystallization train operators command premium wage structures that feed into excipient-grade mannitol margins, while toll processors in lower-cost jurisdictions capture industrial sorbitol volumes on price.
Pricing Analysis
Three-tier pricing structure across pharmaceutical, food-grade, and industrial levels dominates polyol transactions, with FDA and NMPA certification tiers separating premium excipient grades from commodity sorbitol. Price differentiation rests on endotoxin documentation and validated particle size distribution for pharmaceutical buyers, while food manufacturers negotiate on granulation customization and volume scale. Cost compression in technical-grade sorbitol is intensifying because corn wet-millers face grain commodity cycle volatility. Chemical producers sourcing polyurethane feedstock exhibit highest price sensitivity; pharmaceutical tablet manufacturers show lowest sensitivity due to regulatory switching costs.
Supply Chain Analysis
Single-source vulnerability sits with crystalline sorbitol production clustering among European starch processors in France and Germany. Raw material flows draw from corn wet-milling in Iowa and Illinois, beet sugar processing in Central Europe, and seaweed-derived fructose streams for mannitol. Supply chain risk centers on REACH registration dossier delays at ECHA that restrict novel derivative commercialization. Distribution runs through direct procurement relationships displacing distributor intermediaries, with Roquette Frères and Cargill negotiating annual volume contracts with branded food manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EU Green Deal bioeconomy targets and FDA sugar-labeling mandates continuously redirect procurement toward plant-derived hydrogenated carbohydrate sweeteners.
For Market Incumbents: Anticipate enzymatic conversion technology displacing batch hydrogenation assets and eroding yield advantages at legacy crystallization trains. Defensive moves require backward integration into captive glucose supply through corn wet-milling infrastructure and investment in continuous reactor designs with membrane filtration for pharmaceutical-grade purity. REACH registration compliance at ECHA and NMPA excipient audits in China represent critical certification levers to maintain supplier status.
For New Entrants and Emerging Players: India's FSSAI sugar-labeling rules open a window for regional polyol blending capacity serving Mondelez and domestic chocolate manufacturers seeking clean-label positioning. White-space targets include Southeast Asian import substitution for localized polyol supply and keto-label erythritol formulation share in North American protein bar production. Go-to-market positioning should emphasize IPEC GMP certification for pharmaceutical excipient procurement at Teva and Mylan generic operations.
For Investors and Strategic Acquirers: Food-grade polyol specialists with audited GMP infrastructure are the most active acquirer in this space, consolidating toll processors to secure excipient-grade capacity. Long-term viability over a multi-year horizon favors integrated starch processors with captive feedstock and crystallization train assets. Watch for NMPA domestic manufacturing upgrade mandates in China as an inflection signal for import substitution investment flows.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Corn Wet-Milling | Cargill and Roquette Frères secure captive glucose feedstock against commodity price cycles. |
| Continuous Hydrogenation Technology Deployment | European starch processors reduce energy intensity and compress pharmaceutical-grade cycle times. |
| Pharmaceutical-Grade Crystallization Expansion | Merck KGaA and SPI Pharma capture premium margins from Pfizer and Roche excipient demand. |
| REACH Registration Dossier Investment | Industrial sorbitol producers at ECHA avoid use restrictions on polyurethane foam applications. |
| Direct Procurement Relationship Development | Large confectionery compounders in Germany and Netherlands displace distributor intermediaries. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with plant managers at starch processing facilities, procurement leads at oral care compounders, pharmaceutical excipient quality directors, and distribution channel partners with secondary validation. Secondary sources included customs and trade data, SEC 10-K filings from integrated processors, ECHA REACH registration databases, and NMPA pharmaceutical excipient quality protocols. Bottom-up capacity modeling and top-down demand triangulation anchored volume estimates.
Historical reference periods spanning installed hydrogenation capacity and crystallization train utilization established baseline trajectory parameters across the projection horizon. Segmentation dimensions modeled include product type crystallization kinetics, application-grade regulatory tier, physical form handling economics, and end-user procurement sophistication. CAGRs were derived from demand elasticity analysis against sugar-reduction mandate implementation timelines, with forecast inputs incorporating corn commodity cycle patterns and pharmaceutical excipient audit frequency trends.
Revisions become necessary when ECHA substance evaluation programs force toxicological data upgrades, NMPA domestic manufacturing mandates accelerate import substitution, or enzymatic conversion technologies achieve cost parity with catalytic hydrogenation. Forecasts reflect documented assumptions on regulatory enforcement intensity and feedstock cost trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Global Caprylhydroxamic Acid Market
Additives
Cement Grinding Aid and Performance Enhancers Market
Additives
Global Mold Release Agents Market
Additives
Antioxidant and Stabilizer Agents Market
Additives
Low VOC Coating Additives Market
Additives
Coating Additives Market
Additives
Metal Deactivators Market
Additives
Antiknock Agents Market
Additives
Sodium Caprylate Market
Additives
Pearlizers Market
Additives
Iso-Butyric Acid Market
Additives
Glycyrrhizic Acid Glycosides Market
Additives
Material Shrinkage-reducing Agents Market
Additives
Acrylamide Reducing Ingredients Market
Additives
Inorganic Rheology Modifiers Market
Additives
North America Citric Acid Market