
 Global Flame Retardant Masterbatches Market | 2026-2036
Global Flame Retardant Masterbatches Market Size, Share, and Industry Trends Forecast 2026-2036
Global Flame Retardant Masterbatches Market Foresight
Asset-light toll compounding and third-party manufacturing partnerships is rewriting competitive entry economics in flame retardant masterbatches. Albemarle Corporation leverages its bromine supply chain to sustain cost positions in halogenated grades. Clariant anchors its portfolio around phosphorus and nitrogen technologies that serve European electrical and electronics customers. Ampacet Corporation competes through specialized color and additive concentrates that integrate fire retardancy for wire and cable applications.
Flame retardant masterbatches are concentrated additive dispersions, typically containing 40-80% active fire suppressant loaded into polymer carrier resins such as polyethylene or polypropylene, designed to inhibit ignition and slow combustion in finished plastic articles. Brominated product types still occupy the largest share of current volume but face structural pressure from regulatory limits on halogenated substances. Phosphorus-based formulations represent the fastest-expanding segment as manufacturers reformulate to meet evolving fire safety and environmental standards. Intumescent grades command premium positioning in construction materials and transportation components where thick char formation provides critical passive protection.
REACH restrictions on persistent organic pollutants and RoHS substance limits enforced by ECHA are redirecting formulation investments toward halogen-free alternatives across European supply chains. The US EPA and FAA maintain stringent flammability protocols for aerospace and consumer appliance applications that elevate testing burdens for new entrants. China's GB standards and MIIT directives on electrical product safety are tightening parallel requirements in the world's largest manufacturing base. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded formulation investments and misaligned capacity.
Market Dynamics
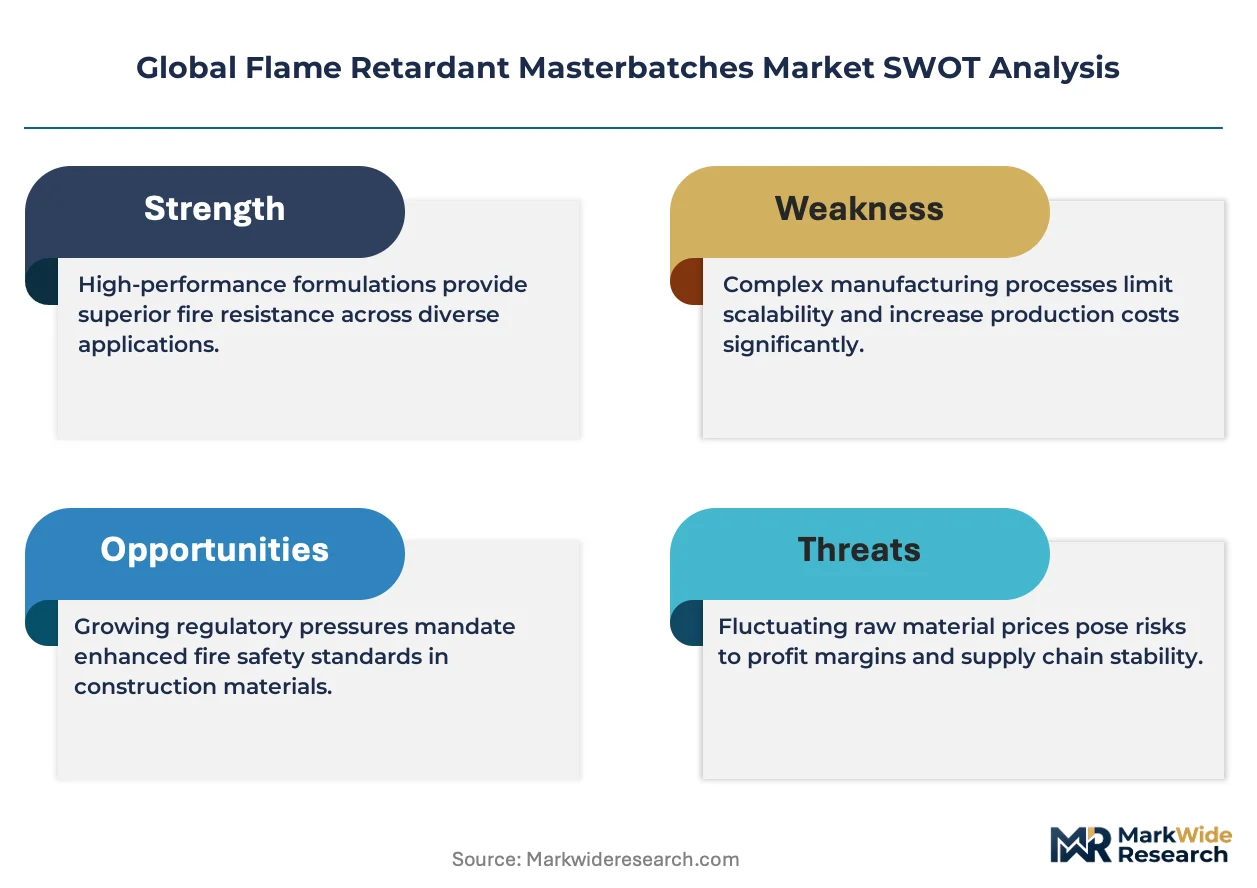
Phosphorus-based formulations are systematically displacing legacy halogenated chemistries as REACH substance restrictions and RoHS directives tighten across European supply chains, forcing reformulation investments that reshape competitive positioning and margin structures for compounders worldwide.
Growth Catalysts
- REACH substance restrictions:ECHA enforcement of persistent organic pollutant limits accelerates halogen-free transitions across German and French electrical manufacturing supply chains.
- China GB standard tightening:MIIT directives on appliance wiring safety mandate enhanced fire suppression in domestic appliance and automotive cable production.
- Intumescent technology maturation:Char-forming additive systems unlock premium positioning in transportation seating and construction panel applications where passive protection requirements dominate.
Market Restraints
- Phosphorus raw material concentration:Elemental phosphorus supply concentrates in Chinese and Moroccan mining operations, creating input cost volatility and security-of-supply exposure for Western compounders.
- Technical performance gaps:Halogen-free alternatives still exhibit inferior thermal stability in high-temperature polymer processing above 280°C, limiting adoption in engineering resin applications.
- Regulatory fragmentation:Divergent flammability testing protocols between FAA aerospace specifications and UL consumer appliance standards force redundant certification investments.
Strategic Opportunities
- India BIS standard adoption:Mandatory fire safety certification for electrical infrastructure creates first-mover advantage for halogen-free masterbatch suppliers establishing local compounding partnerships.
- Battery enclosure applications:Electric vehicle thermal runaway protection requirements open specialized formulation demand for ceramic-forming intumescent systems in lithium-ion pack housings.
- Recycling-compatible formulations:Phosphorus-nitrogen synergists that retain performance through multiple mechanical recycling cycles address circular economy mandates in EU packaging directives.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in phosphorus-nitrogen synergism and polymer compatibility testing commands premium compensation and constrains R&D throughput at mid-scale compounders.
- Multi-jurisdiction certification timelines:Parallel UL, VDE, and CCC approval processes extend product launch cycles to 18-24 months, compressing returns on reformulation investments.
- Legacy equipment retrofit costs:Halogenated compound production lines require dedicated cleaning and ventilation upgrades to prevent cross-contamination with halogen-free product streams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Flame Retardant Masterbatches Market |
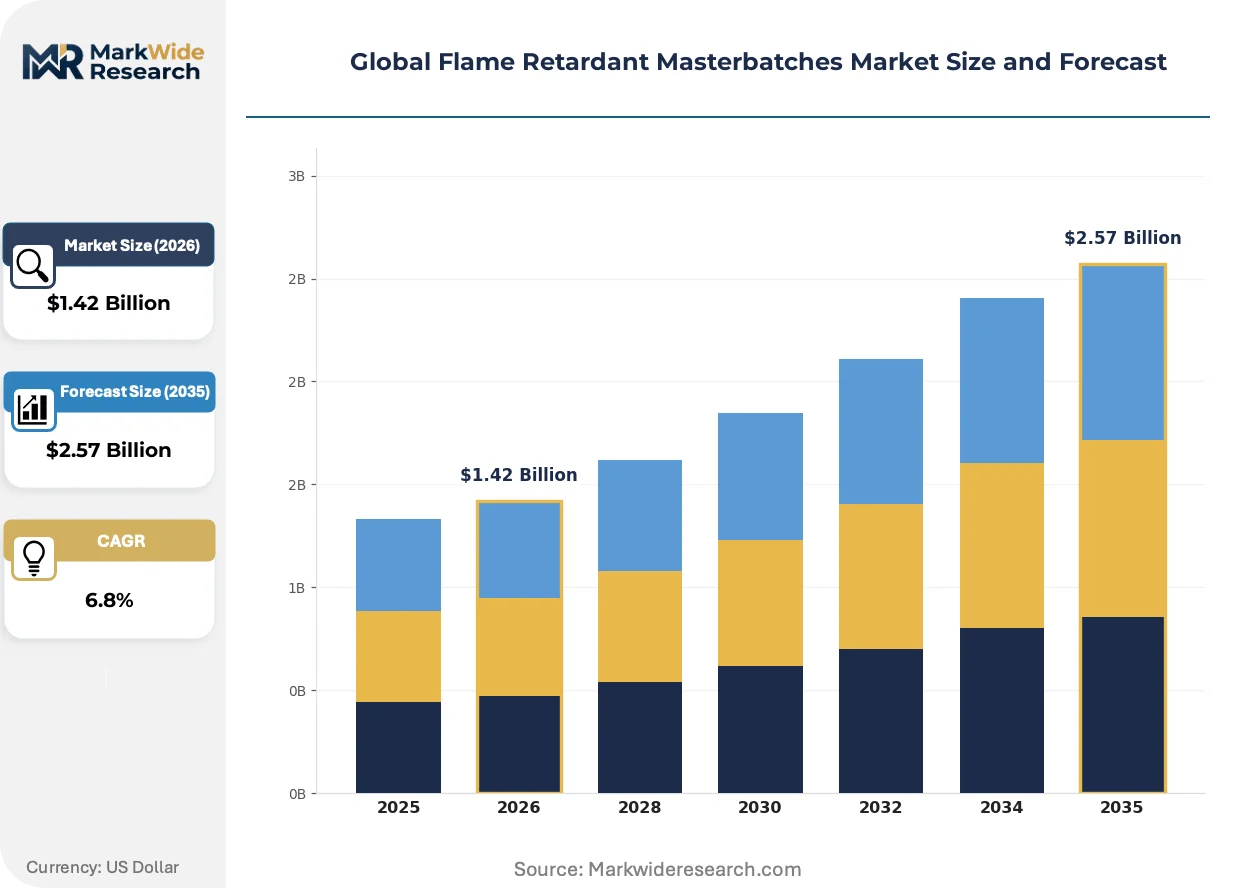
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Brominated, Phosphorus-Based, Nitrogen-Based, Inorganic, Intumescent Application: Electrical & Electronics, Construction Materials, Transportation Components, Textiles, Packaging End User Industry: Consumer Appliances, Aerospace, Marine Equipment, Industrial Machinery, Telecommunications Form: Powder, Pellet, Granule, Flake, Liquid |
| Companies Covered | BASF SE, Albemarle Corporation, Clariant, Ampacet Corporation, LANXESS, DIC Corporation, Cromex S/A, Tosaf, Nouryon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Flame Retardant Masterbatches Market Shifts & Advancements
Active ingredient dispersion technologies and carrier resin engineering are converging to enable higher loadings with maintained processability, while regulatory pressure on substance toxicity accelerates substitution cycles across all major formulation categories.
Micro-encapsulated red phosphorus is migrating from niche electronics applications toward mainstream appliance housings as Chinese manufacturers seek RoHS-compliant alternatives for export markets. Major white goods producers in Guangdong and Zhejiang provinces now specify encapsulated grades for washing machine and air conditioner plastic components. This technology is migrating from specialty premium positioning into volume commodity supply tiers, compressing margins for conventional ammonium polyphosphate suppliers.
REACH annex XVII restrictions on halogenated flame retardants entered full enforcement phase in 2023, compelling electrical connector and cable manufacturers to validate alternative chemistries through enhanced ECHA notification procedures. German automotive wiring harness producers have accelerated supplier qualification timelines to meet OEM sustainability scorecard requirements. The construction sector across France and Benelux markets exhibits the most acute formulation switching activity, driven by combined regulatory pressure and green building certification point systems.
Compounders now bundle technical service with masterbatch supply, embedding fire testing and regulatory documentation into standard commercial terms rather than charging separately. This service integration disrupts traditional distribution channels where independent testing laboratories previously captured certification value. The shift is most visible in North American wire and cable markets, where integrated suppliers like Ampacet leverage in-house UL witnessing capabilities to compress customer procurement cycles and disintermediate third-party testing relationships.
Global Flame Retardant Masterbatches Market Segmentation
Flame retardant masterbatches fragment across multiple technical dimensions that determine formulation cost, processing behavior, and regulatory compliance pathways. Understanding these segment boundaries reveals where margin pools concentrate and which technology transitions reshape supplier economics.
Product Type:
Formulation chemistry spans legacy halogenated systems through emerging halogen-free alternatives, with each technology carrying distinct cost positions and regulatory risk profiles.
- Brominated:These formulations leverage bromine chemistry to interrupt combustion radical chain reactions, offering cost-effective fire suppression in polyolefin and styrenic resins. Demand concentrates in Chinese appliance exports and Southeast Asian wire and cable production where REACH-equivalent restrictions remain partially unenforced. ECHA substance evaluations and state-level US restrictions on deca-BDE create structural headwinds for volume expansion.
- Phosphorus-Based:Organic and inorganic phosphorus compounds function through char formation and vapor-phase flame inhibition, achieving UL94 V-0 ratings without halogen content. German automotive wiring harness manufacturers and French construction panel producers drive fastest adoption as OEM sustainability scorecards harden requirements. Raw material dependence on Chinese and Moroccan elemental phosphorus creates supply security exposure for Western compounders.
- Nitrogen-Based:Melamine derivatives and guanidine compounds operate through endothermic decomposition and inert gas dilution, typically in synergistic combination with phosphorus.
- Inorganic:Aluminum and magnesium hydroxides provide halogen-free suppression through endothermic water release, dominating volume in cable sheathing where high loadings are process-tolerable.
- Intumescent:Acid source-char former-blowing agent systems expand into insulating foams under fire exposure, commanding specialized positioning in transportation seating and steel coating applications.
Established volume favors brominated grades; emerging adoption favors phosphorus-based alternatives.
Application:
End-use requirements range from thin-wall electronics housings to thick-section construction panels, dictating loading levels, dispersion quality needs, and certification complexity.
- Electrical & Electronics:Connectors, enclosures, and cable insulation demand precise flame retardant dispersion to maintain dielectric properties and surface aesthetics. RoHS compliance mandates in EU and GB standard tightening in China force reformulation cycles among connector manufacturers in Dongguan and Stuttgart industrial clusters.
- Construction Materials:Wall panels, roofing membranes, and insulation boards require intumescent or high-loading inorganic systems that maintain structural integrity during char formation. French and Benelux green building certification schemes accelerate specification switching toward halogen-free alternatives.
- Transportation Components:Aircraft interiors, rail seating, and automotive underhood applications combine flammability with smoke toxicity and heat release rate requirements.
- Textiles:Synthetic fiber treatments and coated fabrics for protective clothing utilize specialized dispersion technologies compatible with melt spinning and coating lines.
- Packaging:E-commerce shipping materials and electronics protective foams face emerging circular economy mandates requiring recycling-compatible formulations.
Electrical and electronics applications anchor current revenue; construction materials offer the steepest expansion trajectory as green building codes proliferate.
End User Industry:
Customer technical sophistication varies from commodity appliance assemblers to aerospace OEMs with multi-year qualification protocols.
- Consumer Appliances:Washing machines, air conditioners, and small electronics housings represent high-volume, price-sensitive demand concentrated in Guangdong and Zhejiang manufacturing clusters. White goods producers now specify encapsulated red phosphorus grades for export-market RoHS compliance.
- Aerospace:FAA flammability protocols for cabin interiors impose rigorous heat release and smoke density testing that favors established brominated systems with extensive airworthiness history.
- Marine Equipment:IMO SOLAS regulations govern fire suppression in vessel interiors and offshore platform components.
- Industrial Machinery:Enclosures, cable chains, and conveyor components in automated manufacturing lines require oil-resistant flame retardant grades.
- Telecommunications:5G infrastructure housings and data center cable management systems combine fire safety with electromagnetic shielding compatibility.
Consumer appliances dominate shipment volume; aerospace and telecommunications concentrate margin capture through technical barriers.
Form:
Physical presentation determines handling characteristics, dust exposure, and integration with customer compounding or direct molding operations.
- Powder:Fine-ground dispersions offer maximum loading flexibility for in-house compounders but require dust control investments and exhibit batch-to-batch dispersion variability.
- Pellet:Extruded cylindrical forms with standardized dimensions enable automated feeding in injection molding and extrusion lines, representing the largest commercial volume.
- Granule:Irregular particle shapes from strand cutting or underwater pelletizing suit bulk handling in construction panel and wire cable compounding.
- Flake:Thin, plate-like particles from sheet slitting serve specialized coating and calendering applications where rapid melt incorporation matters.
- Liquid:Dispersions in plasticizers or reactive carriers enable spray application and thermoset integration for pultrusion and resin transfer molding.
Pellet and granule forms command mainstream volume; liquid dispersions gain share in thermoset composites and battery enclosure applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH substance restrictions and RoHS directives across Europe are accelerating halogen-free transitions, while China's GB standard tightening and MIIT directives on electrical safety reshape procurement patterns in the world's largest manufacturing base.
China
Domestic appliance and automotive wiring production scales up demand for phosphorus-based formulations. MIIT directives on appliance wiring safety mandate enhanced fire suppression in Guangdong and Zhejiang manufacturing clusters. White goods producers in Dongguan now specify encapsulated red phosphorus grades for export-market compliance.
Germany
Automotive wiring harness manufacturers drive fastest adoption of phosphorus-based alternatives as OEM sustainability scorecards harden requirements. ECHA enforcement of persistent organic pollutant limits accelerates halogen-free transitions across electrical manufacturing supply chains. Stuttgart industrial clusters exhibit acute formulation switching activity among connector manufacturers.
United States
FAA flammability protocols for aerospace and consumer appliance applications elevate testing burdens for compounders. EPA maintenance of stringent protocols for cabin interiors favors established systems with extensive airworthiness history. Wire and cable markets show integrated suppliers compressing customer procurement cycles through in-house UL witnessing capabilities.
France
Construction panel producers exhibit the most acute formulation switching activity across Benelux and domestic markets. Combined regulatory pressure and green building certification point systems redirect specification toward halogen-free alternatives. Lyon and Paris industrial basins concentrate demand for intumescent systems in transportation seating applications.
India
Mandatory fire safety certification for electrical infrastructure creates first-mover advantage for halogen-free masterbatch suppliers. BIS standard adoption on appliance and cable safety tightens parallel requirements in the emerging manufacturing base. Maharashtra and Gujarat industrial corridors attract local compounding partnerships seeking to serve domestic appliance assembly growth.
Global Flame Retardant Masterbatches Market Competitive Landscape
On the supply side, the industry is moderately consolidated around integrated chemical conglomerates and specialized compounders with distinct technology positions. Three strategic archetypes dominate: bromine-integrated players leveraging captive raw material access, phosphorus-nitrogen technology specialists serving European regulatory transitions, and toll compounders competing through asset-light service integration. Competitive moves center on backward integration into active ingredient production and geographic expansion through third-party manufacturing partnerships.
Among European-headquartered technology specialists, Clariant anchors the phosphorus-nitrogen synergist tier serving electrical and electronics customers facing REACH compliance deadlines. Albemarle Corporation exemplifies the bromine-integrated archetype, sustaining cost positions in halogenated grades through captive supply chain control. Ampacet Corporation occupies a position within the North American wire and cable specialization tier, competing through integrated color and additive concentrates that bundle fire testing and regulatory documentation into standard commercial terms.
| Leading Market Players |
|---|
| BASF SE |
| Albemarle Corporation |
| Clariant |
| Ampacet Corporation |
| LANXESS |
| DIC Corporation |
| Cromex S/A |
| Tosaf |
| Nouryon |
| Others |
Supply & Pricing Matrix
The Shanghai-Rotterdam maritime corridor carries elemental phosphorus and bromine derivatives that anchor formulation cost structures, with freight rate volatility transmitting directly into margin compression for European compounders and price differentiation between halogenated and halogen-free tiers.
Pricing Analysis
Certification level creates the primary spread across the market, with UL94 V-0 and REACH-compliant grades commanding substantial premiums over uncertified commodity offerings. Three-tier pricing structure separates aerospace-qualified formulations from appliance-grade standards and bulk cable economy tiers. Pricing pressure stems from Chinese domestic production scaling that compresses export margins for Western phosphorus-based suppliers. Appliance assemblers in Guangdong exhibit acute price sensitivity, while aerospace OEMs prioritize qualification history over unit cost.
Supply Chain Analysis
Extended payment terms from German automotive wiring harness producers now stretch to 90-120 days, forcing working capital intensity onto mid-scale compounders. Elemental phosphorus concentrates in Chinese and Moroccan mining operations, while bromine extraction clusters along the US Gulf Coast and Dead Sea. Supply chain risk centers on single-source vulnerability for red phosphorus encapsulation technology held by limited Asian specialists. Distribution runs through integrated compounders with in-house testing capabilities rather than independent distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market tracks the capital goods investment cycle, with formulation demand recovering as electrical infrastructure and appliance manufacturing capex rebounds from recent trough conditions.
For Market Incumbents: Insulate margin positions through backward integration into phosphorus active ingredient production, particularly Moroccan or Chinese mining partnerships that secure input cost stability against elemental phosphorus volatility. Defend European market share by accelerating ECHA pre-registration for next-generation nitrogen-phosphorus synergists before REACH evaluation deadlines tighten further. For New Entrants and Emerging Players: Indian BIS certification requirements for electrical infrastructure create immediate white-space opportunity for halogen-free masterbatch suppliers establishing local compounding partnerships. Battery enclosure applications for electric vehicle thermal runaway protection offer the most penetrable specialized segment, accessible through joint development agreements with lithium-ion pack housing manufacturers rather than direct OEM qualification. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates seeking to divest non-core masterbatch operations amid portfolio rationalization pressures. Long-term viability favors phosphorus-nitrogen technology specialists with established REACH compliance pathways over legacy brominated players facing structural regulatory headwinds. Watch for MIIT enforcement acceleration in China as the inflection signal triggering accelerated halogen-free substitution investment.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phosphorus Mining | Captive Moroccan or Chinese elemental phosphorus supply secures cost positions against raw material volatility. |
| REACH Pre-Registration Investment | Early ECHA notification for nitrogen-phosphorus synergists locks in European electrical supply chain access. |
| Local Compounding Partnership in India | Maharashtra and Gujarat facility investments capture BIS certification-driven demand from domestic appliance growth. |
| Battery Enclosure Formulation Development | Ceramic-forming intumescent systems for lithium-ion pack housings open specialized electric vehicle revenue streams. |
| In-House UL Witnessing Capability | Integrated fire testing compresses customer procurement cycles and displaces third-party laboratory relationships. |
Research Methodology
Desk research of customs trade databases, ECHA substance registration filings, and SEC chemical company disclosures preceded structured interviews with flame retardant formulation chemists, polymer compounding plant managers, and procurement leads at German automotive wiring harness manufacturers. Primary fieldwork captured processing constraints and certification timelines, cross-referenced against secondary validation from GB standard documentation and MIIT directive texts. Bottom-up volume estimates from end-use consumption patterns triangulated with top-down supply-side capacity assessments.
Forecast assumptions held REACH enforcement timelines and Chinese GB standard adoption schedules fixed while varying electric vehicle penetration rates and appliance manufacturing output across the projection horizon. Segmentation modeling spanned formulation chemistry, application thickness requirements, end-user industry technical sophistication, and physical form factors. CAGRs derived from elasticity-adjusted demand projections tied to named regulatory compliance deadlines and OEM sustainability scorecard implementation. Industry-specific inputs included phosphorus raw material contract pricing trends and UL certification queue durations.
Practitioners should monitor ECHA substance evaluation acceleration and MIIT enforcement intensity for early signals of reformulation investment timing. Forecasts reflect assumptions regarding regulatory implementation consistency and raw material supply continuity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Marine Fuel Additives Market
Additives
Asia Pacific Silage Additives Market
Additives
Isobutyl Acetate Market
Additives
Mycotoxin Binders Market
Additives
LAMEA Driveline Additives Market
Additives
Deodorant and Antiperspirant Ingredients Market
Additives
Choline Chloride Market
Additives
Saudi Arabia Feed Additives Market
Additives
Dishwashing Additives Market
Additives
Global Feed Acidulants Market
Additives
Global Performance Additives Market
Additives
Anti-Creasing Agent Market
Additives
Citric Acid Market
Additives
Hydroxypropyl Distarch Phosphate Market
Additives
Antimicrobial Additives Market
Additives
Impact Modifier Market