
 Glyceryl Caprylate Market | 2026-2036
Glyceryl Caprylate Market Size, Share, and Industry Trends Forecast 2026-2036
Glyceryl Caprylate Market Foresight
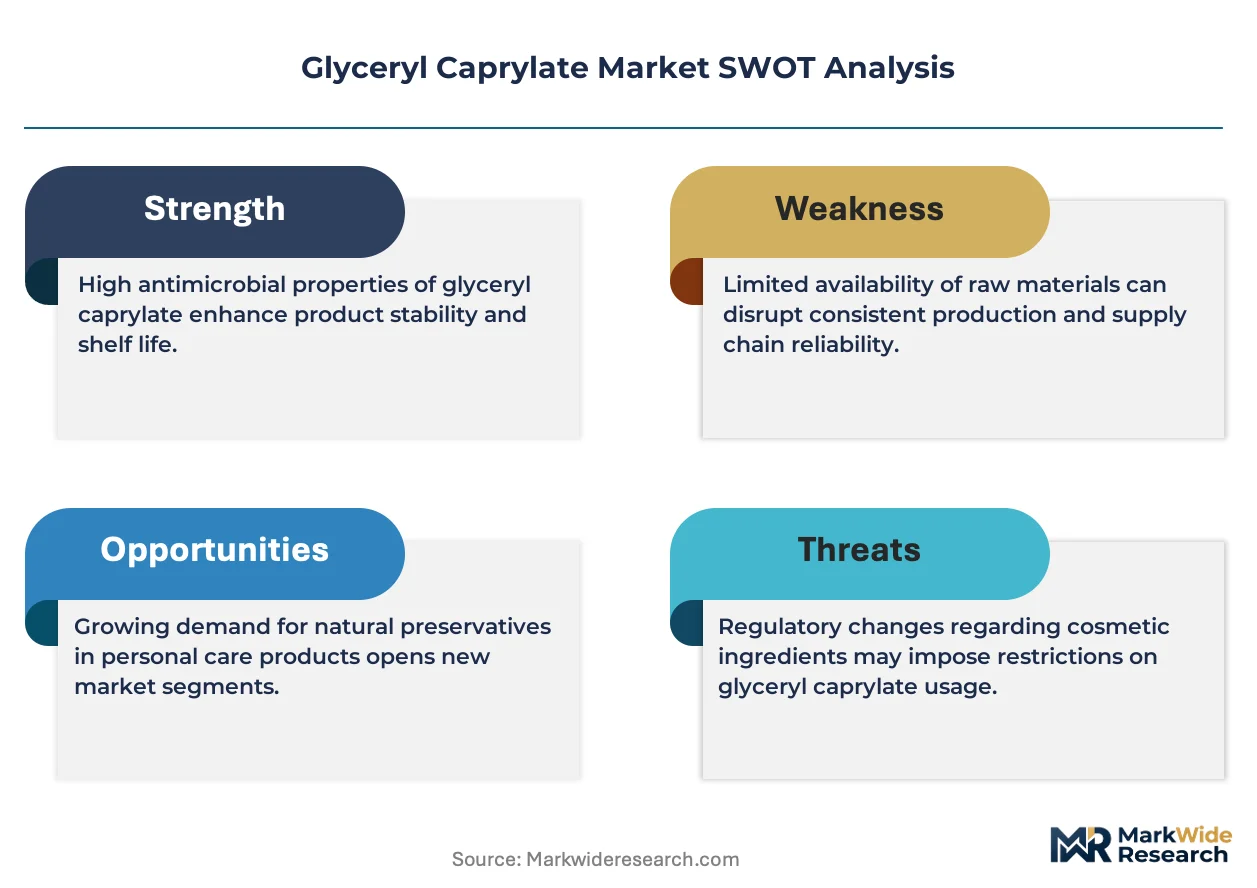
A shift from single-source oleochemical supply toward multi-source vegetable oil feedstock procurement is realigning how glyceryl caprylate producers manage input volatility. Stepan Company leverages backward integration into coconut and palm kernel supply chains to sustain margin stability across cosmetic-grade batches. Evonik Industries competes through specialized esterification technology that dominates pharmaceutical-grade purity thresholds. Kao Corporation anchors its position via integrated fatty acid chemistry operations spanning Japan and Southeast Asia.
Glyceryl caprylate is a monoester of glycerol and caprylic acid, typically produced through enzymatic or chemical esterification of medium-chain triglycerides, functioning as a non-ionic surfactant, emollient, and antimicrobial agent in personal care and food systems. Cosmetic-grade glyceryl caprylate commands the largest volume share due to its dual role as a skin-conditioning agent and mild preservative booster in clean-label formulations. Pharmaceutical-grade material is recording the fastest expansion as parenteral and topical drug delivery systems adopt lipid-based excipients with documented biocompatibility profiles. Food-grade applications occupy a narrower but defensible niche where glyceryl caprylate serves as a mold inhibitor in baked goods and dairy alternatives.
FDA food-contact substance notifications and EPA chemical data reporting requirements shape product registration pathways for U.S.-bound glyceryl caprylate shipments, while REACH registration and ECHA hazard classification protocols govern European market access. Japan's MHLW and METI coordinate standards for quasi-drug and cosmetic ingredient safety that directly influence export specifications from Korean and Chinese manufacturers. Stakeholders must monitor evolving biobased content certification schemes and regional purity mandates to align capital allocation with the segments poised for sustained premium pricing.
Market Dynamics
Feedstock volatility in coconut and palm kernel oil markets is forcing glyceryl caprylate producers to restructure procurement contracts and invest in multi-origin sourcing infrastructure to defend margin stability.
Growth Catalysts
- Clean-label cosmetic mandates:Formulators across Germany, Japan, and the United States are substituting synthetic preservatives with glyceryl caprylate to meet retailer clean beauty specifications.
- REACH purity escalation:ECHA hazard classification protocols for surfactant-grade inputs are compressing supply of sub-standard material and concentrating demand on certified pharmaceutical-grade production.
- Lipid-based drug delivery expansion:Parenteral and topical pharmaceutical systems are adopting glyceryl caprylate as a biocompatible excipient with documented safety profiles.
Market Restraints
- Caprylic acid feedstock concentration:Over 60% of global supply originates from Southeast Asian palm kernel processing, creating geographic concentration risk.
- Enzymatic esterification cost premium:Pharmaceutical-grade production requires specialized lipase catalysts and temperature-controlled reactors that elevate unit economics versus chemical routes.
- Glycerol price volatility:Biodiesel production swings directly impact glycerol availability and pricing for esterification inputs.
Strategic Opportunities
- Indian pharmaceutical compounding:CDSCO regulatory alignment with ICH excipient standards is opening formulation-grade demand from domestic generic injectable manufacturers.
- Biobased certification leverage:USDA BioPreferred and EU Green Deal biobased content schemes enable premium positioning for vegetable-oil-derived material versus petrochemical alternatives.
- Direct-to-formulator digital channels:Specialty chemical marketplaces are disintermediating traditional distributor networks for mid-volume cosmetic batch orders.
Industry Challenges
- Pharmaceutical-grade validation timelines:US FDA Type II drug master file preparation and European Pharmacopoeia certification require 18-24 month documentation cycles.
- Legacy batch record integration:Cosmetic manufacturers with entrenched ERP systems face data mapping complexity when onboarding new glyceryl caprylate suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glyceryl Caprylate Market |
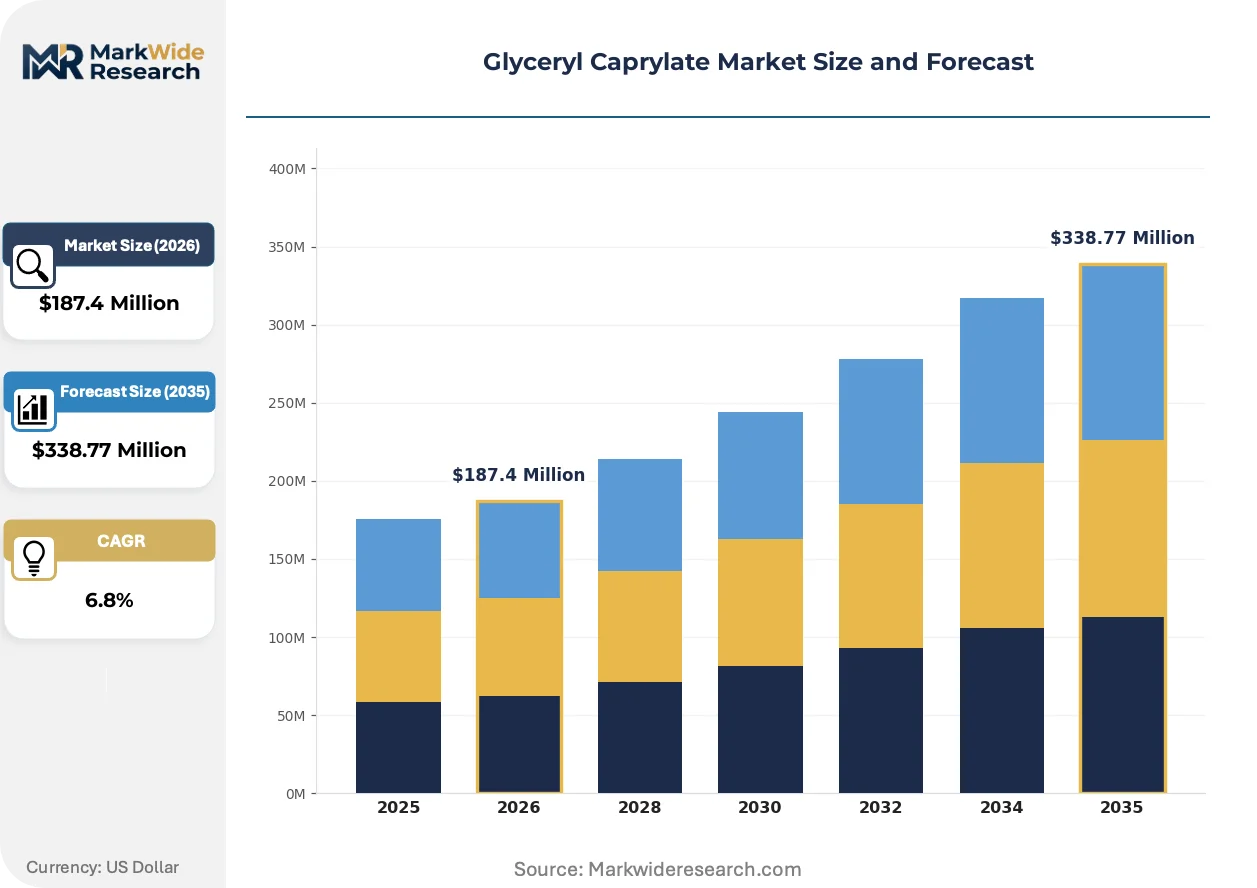
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cosmetic Grade, Pharmaceutical Grade, Food Grade, Industrial Grade Application: Skincare, Haircare, Pharmaceuticals, Food Preservation Distribution Channel: Online Retail, Specialty Stores, Direct Sales, Distributors End User: Cosmetic Manufacturers, Food Producers, Healthcare Providers, Contract Manufacturers |
| Companies Covered | Stepan Company, Evonik Industries, Kao Corporation, ABITEC, INOLEX, Croda International, BASF, Parchem Fine & Specialty Chemicals, Tokyo Chemical Industry, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glyceryl Caprylate Market Shifts & Advancements
Enzymatic process intensification and regulatory harmonization across pharmaceutical excipient standards are compressing the gap between cosmetic-grade commodity supply and premium pharmaceutical-grade production.
Immobilized lipase catalysis for selective monoester production is absorbing capital allocation from chemical esterification routes. Korean and Chinese manufacturers are scaling fixed-bed reactor configurations to serve pharmaceutical compounding demand. This technology is absorbing market share from acid-catalyzed batch processes that generate diester and triester byproducts requiring downstream purification.
REACH registration dossier updates for glyceryl caprylate are tightening purity thresholds for residual caprylic acid and glycerol content. ECHA's 2023-2024 substance evaluation wave is forcing re-registration of legacy cosmetic-grade material. Pharmaceutical-grade producers with pre-validated analytical methods are capturing volume from cosmetic suppliers facing compliance remediation costs.
Formulator procurement teams are consolidating supplier panels from 8-12 vendors to 3-4 strategic partners with integrated fatty acid chemistry capabilities. This concentration is visible most acutely in German and Japanese skincare manufacturing clusters where quality agreement standardization reduces incoming inspection overhead. Direct material qualification programs are replacing distributor-mediated supply relationships for volume-account cosmetic brands.
Glyceryl Caprylate Market Segmentation
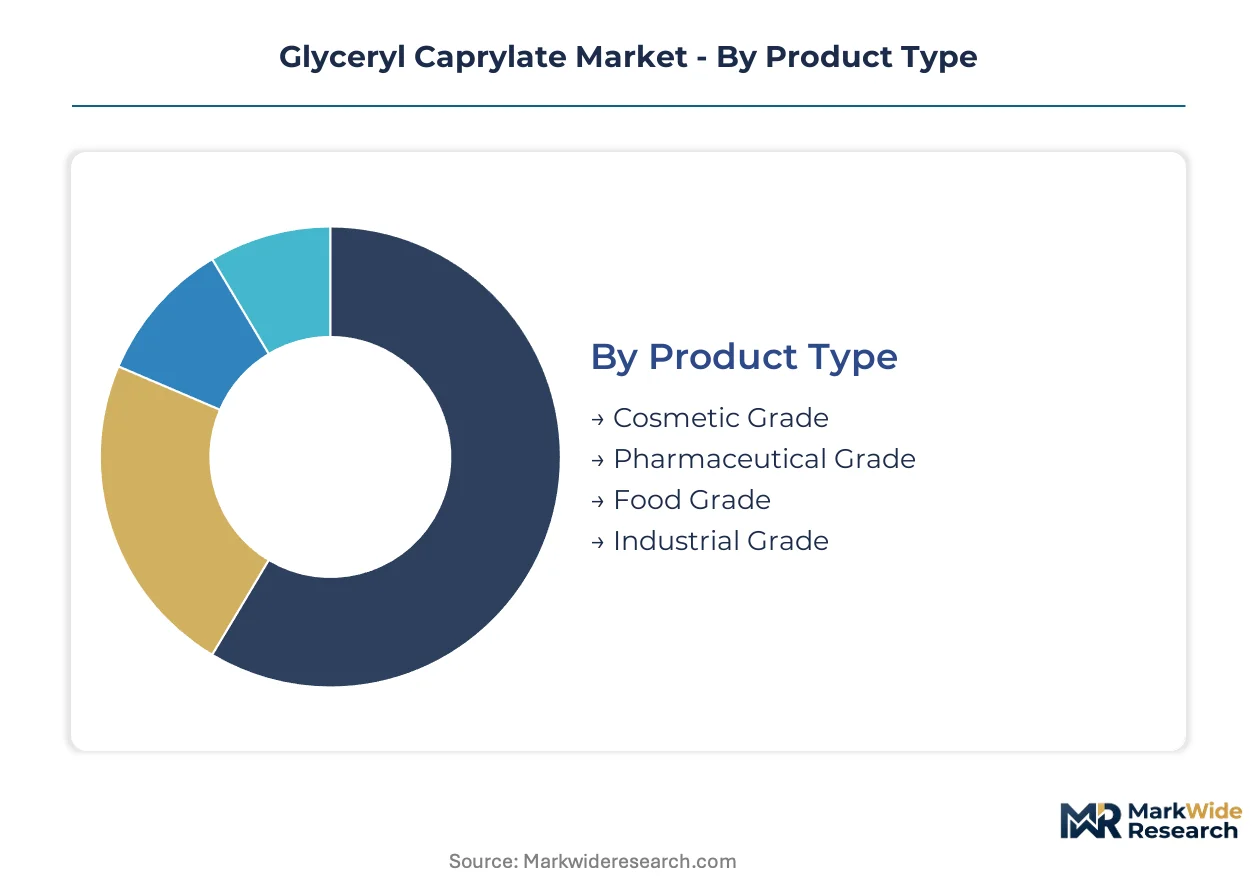
Glyceryl caprylate procurement patterns diverge sharply across purity grades and end-use specifications, with cosmetic and pharmaceutical buyers operating under incompatible technical standards and validation timelines. Understanding these segment boundaries clarifies why producers maintain separate production trains despite shared feedstock origins.
Product Type:
Buyers in this category separate primarily by documentation burden and regulatory filing requirements rather than molecular structure alone.
- Cosmetic Grade:Monoester purity typically ranges 85-95% with controlled residual caprylic acid below 2%, serving formulators seeking dual-function emollients with mild antimicrobial boosting. Demand concentrates in German and Japanese skincare manufacturing clusters where retailer clean beauty specifications are compressing synthetic preservative use.
- Pharmaceutical Grade:Exceeds 98% monoester content with full impurity profiling per ICH Q3C guidelines, qualifying for parenteral and topical drug delivery systems. Steepest expansion trajectory comes from lipid-based excipient adoption in generic injectable manufacturing across India and Southeast Asia.
- Food Grade:Meets FDA food-contact substance notification thresholds for mold inhibition in baked goods and dairy alternatives, with narrower volume concentration in North American and European bakery ingredient supply chains.
- Industrial Grade:Lower purity specifications serve metalworking fluid and lubricant applications where emulsification performance outweighs biocompatibility requirements, with demand anchored in automotive supplier networks.
Volume sits with cosmetic grade; growth tilts toward pharmaceutical grade.
Application:
Formulation complexity and regulatory exposure define how buyers source glyceryl caprylate across these end-uses.
- Skincare:Facial moisturizers, serums, and clean-label creams deploy glyceryl caprylate as a skin-conditioning agent with secondary preservation support, with procurement led by Korean and German formulators integrating multi-functional ingredients.
- Pharmaceuticals:Parenteral emulsions, topical gels, and transdermal patches require excipient-grade material with validated biocompatibility profiles, with CDSCO alignment in India opening compounding demand from domestic generic manufacturers.
- Haircare:Conditioners and scalp treatments leverage emollient properties for sensorial enhancement, with volume concentrated in mass-market brands operating through distributor-mediated supply chains.
- Food Preservation:Mold inhibition in plant-based dairy and extended-shelf-life baked goods operates under narrower regulatory windows, with USDA BioPreferred certification enabling premium positioning.
Skincare commands current volume; pharmaceutical applications are climbing the fastest.
Distribution Channel:
Order scale and technical service requirements determine channel selection, with mid-volume buyers driving structural change.
- Direct Sales:Strategic relationships with cosmetic multinationals and pharmaceutical compounders involve quality agreements, audit rights, and dedicated technical support, capturing the largest revenue share despite lower transaction frequency.
- Distributors:Regional chemical distributors serve fragmented cosmetic manufacturers and food producers requiring smaller batch sizes with inventory buffering, maintaining relevance in secondary markets.
- Online Retail:Specialty chemical marketplaces are disintermediating traditional networks for mid-volume cosmetic batch orders, with platform-based qualification reducing onboarding friction.
- Specialty Stores:Ingredient-focused suppliers serve artisan formulators and independent cosmetic brands seeking technical guidance alongside material procurement.
Direct sales anchor revenue concentration; online channels are gaining share fastest.
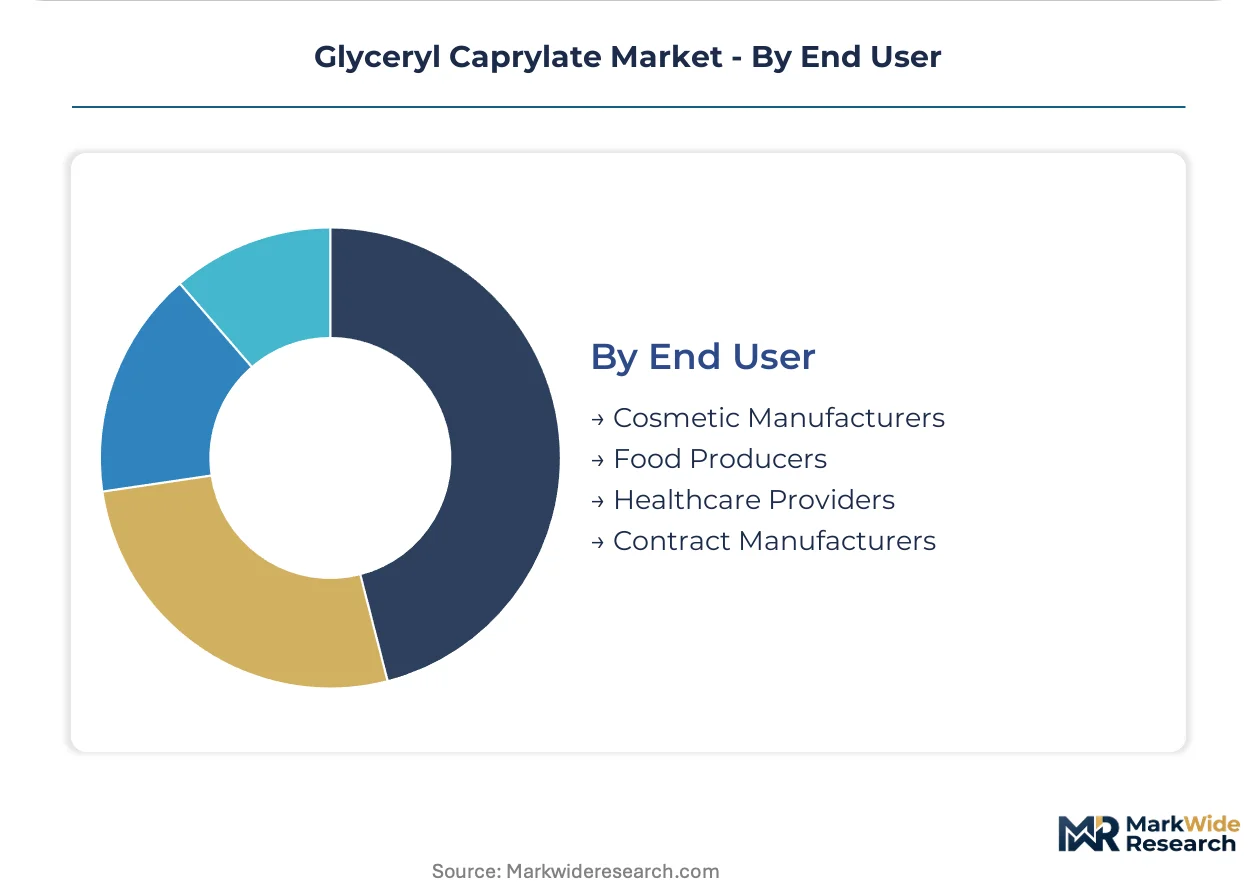
End User:
Integration depth and formulation expertise separate these buyer categories.
- Cosmetic Manufacturers:Integrated skincare and haircare brands with captive R&D capabilities source glyceryl caprylate through direct qualification programs, consolidating supplier panels to reduce incoming inspection overhead.
- Contract Manufacturers:Toll producers serving multiple cosmetic brands require flexible procurement with rapid lot-to-lot consistency, operating under customer-mandated approved supplier lists.
- Food Producers:Bakery and dairy alternative manufacturers prioritize regulatory compliance documentation over technical service intensity, with procurement often channeled through food ingredient distributors.
- Healthcare Providers:Hospital compounding pharmacies and specialty clinics represent emerging demand for pharmaceutical-grade material in extemporaneous preparation, with volume concentrated in institutional procurement frameworks.
Cosmetic manufacturers dominate volume; contract manufacturers show steepest procurement expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cosmetic and pharmaceutical formulators in Germany, Japan, and the United States account for the dominant share of glyceryl caprylate procurement, with clean-label mandates and excipient-grade validation requirements reshaping regional sourcing patterns.
United States
Skincare manufacturers in New Jersey and California are consolidating supplier panels to meet retailer clean beauty specifications. FDA food-contact substance notifications govern mold inhibition applications in plant-based dairy alternatives. The New Jersey pharmaceutical corridor drives excipient-grade demand from generic injectable compounders seeking lipid-based delivery systems.
Germany
REACH registration dossier updates are compressing supply of sub-standard cosmetic-grade material and concentrating demand on certified pharmaceutical-grade production. ECHA hazard classification protocols for surfactant-grade inputs now require re-registration of legacy batches. The Düsseldorf-Cologne chemical cluster hosts formulation-grade producers serving domestic skincare manufacturers.
Japan
METI and MHLW coordinate standards for quasi-drug and cosmetic ingredient safety that directly influence export specifications from Korean and Chinese suppliers. Kao Corporation anchors integrated fatty acid chemistry operations spanning domestic and Southeast Asian facilities. The Osaka-Kobe manufacturing belt concentrates emollient procurement for premium skincare brands.
India
CDSCO regulatory alignment with ICH excipient standards is opening formulation-grade demand from domestic generic injectable manufacturers. Pharmaceutical compounding activity concentrates in Hyderabad and Mumbai, with contract manufacturers qualifying new glyceryl caprylate suppliers under customer-mandated approved vendor lists. The Mumbai-Pune corridor hosts the fastest-expanding excipient validation programs.
South Korea
Cosmetic formulators in Seoul and Incheon are deploying glyceryl caprylate as a dual-function emollient and mild preservative booster in K-beauty export formulations. MFDS cosmetic ingredient safety assessments align with Japanese MHLW standards, streamlining regional supply qualification. The Songdo biocluster attracts pharmaceutical-grade producers scaling immobilized lipase catalysis for selective monoester production.
Glyceryl Caprylate Market Competitive Landscape
Capacity expansion dominates the current landscape as producers invest in multi-origin sourcing infrastructure to defend margin stability against coconut and palm kernel oil volatility. The vendor base separates into integrated oleochemical majors, specialized esterification technology providers, and regional distributors serving fragmented cosmetic manufacturers. Three archetypes define competitive positioning: backward-integrated feedstock controllers, pharmaceutical-grade purity specialists, and platform-integrated direct-to-formulator channels. Geographic expansion and technology licensing represent the dominant competitive moves, with enzymatic process intensification absorbing capital allocation from legacy chemical routes.
Among integrated oleochemical majors, Stepan Company and Kao Corporation exemplify backward-integrated feedstock controllers with captive supply chain positions spanning coconut and palm kernel sourcing. Evonik Industries occupies the pharmaceutical-grade purity specialist tier, competing through specialized esterification technology that dominates excipient-grade thresholds. These three anchors represent distinct strategic vectors: Stepan leverages North American and Southeast Asian supply chain integration, Kao anchors Asia-Pacific manufacturing corridor dominance, and Evonik commands European regulatory compliance positioning.
| Leading Market Players |
|---|
| Stepan Company |
| Evonik Industries |
| Kao Corporation |
| ABITEC |
| INOLEX |
| Croda International |
| BASF |
| Parchem Fine & Specialty Chemicals |
| Tokyo Chemical Industry |
| Others |
Supply & Pricing Matrix
Immobilized lipase catalysis adoption is compressing unit economics for pharmaceutical-grade batches while simultaneously concentrating production capability among Korean and Chinese manufacturers with fixed-bed reactor infrastructure. This technology shift tightens the link between enzymatic process investment and margin defense against chemical-route competitors.
Pricing Analysis
Quality agreement bundling separates pharmaceutical-grade procurement from unbundled cosmetic-grade spot purchasing. Three-tier pricing structure across pharmaceutical, cosmetic, and industrial grades reflects documentation burden divergence, with ICH Q3C validation commanding premium positioning. Cost compression in cosmetic-grade tiers is intensifying because REACH re-registration obligations are forcing sub-standard suppliers into compliance remediation. Contract manufacturers operating under customer-mandated approved vendor lists exhibit lowest price sensitivity; artisan formulators sourcing through specialty stores show highest.
Supply Chain Analysis
Container freight differentials between Southeast Asian palm kernel origins and German pharmaceutical corridors are reshaping procurement contract structures. Supply concentrates in Malaysia, Indonesia, and the Philippines for caprylic acid feedstock, with glycerol sourcing tethered to biodiesel production swings in the United States and Brazil. Single-source vulnerability runs through the 60% palm kernel concentration in Southeast Asian processing. Distribution runs through direct sales relationships with cosmetic multinationals, bypassing traditional distributor networks for volume accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Glyceryl Caprylate Market operates as a cost-of-compliance story where ECHA hazard classification protocols and REACH registration dossier requirements erect documentation barriers that favor incumbent pharmaceutical-grade producers with pre-validated analytical methods.
For Market Incumbents: Anchor market position through backward integration into multi-origin coconut and palm kernel sourcing infrastructure, defending margin stability against feedstock volatility while accelerating pharmaceutical-grade capacity expansion in the Songdo biocluster to capture lipid-based drug delivery demand from Indian generic injectable manufacturers. For New Entrants and Emerging Players: Specialty chemical marketplaces offer the most penetrable route for mid-volume cosmetic batch orders, targeting Korean and German skincare formulators consolidating supplier panels from 8-12 vendors to 3-4 strategic partners, with platform-based qualification reducing 18-24 month onboarding friction versus direct sales channels. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition of enzymatic esterification technology specialists with fixed-bed reactor capabilities and pre-validated European Pharmacopoeia certification, with long-term viability hinging on biobased content certification leverage under USDA BioPreferred and EU Green Deal schemes; the signal to watch is CDSCO regulatory alignment progress opening Indian pharmaceutical compounding demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock | Stepan Company's captive coconut and palm kernel supply chains sustain margin stability across cosmetic-grade batches. |
| Enzymatic Process Intensification | Immobilized lipase catalysis absorbs capital allocation from acid-catalyzed batch processes generating diester byproducts. |
| Pharmaceutical-Grade Validation Investment | US FDA Type II drug master file preparation and European Pharmacopoeia certification capture volume from cosmetic suppliers facing ECHA compliance remediation. |
| Direct-to-Formulator Digital Channels | Specialty chemical marketplaces disintermediate traditional distributor networks for mid-volume cosmetic batch orders. |
| Biobased Certification Leverage | USDA BioPreferred and EU Green Deal content schemes enable premium positioning for vegetable-oil-derived material versus petrochemical alternatives. |
Research Methodology
Trade databases, ECHA registration dossiers, and SEC filings from publicly traded oleochemical majors formed the secondary backbone, supplemented by primary interviews with cosmetic formulators, pharmaceutical excipient procurement managers, and fixed-bed reactor technology providers. Bottom-up and top-down triangulation validated volume estimates across grade tiers and regional production clusters.
Bottom-up modeling anchored the analytical lens, with top-down macroeconomic cross-checks applied across the projection horizon. Segmentation dimensions included purity grade, end-use application, and distribution channel complexity, with CAGRs derived from feedstock price elasticity modeling and regulatory compliance cost escalation curves. Enzymatic versus chemical route capacity expansion timelines and REACH re-registration wave impacts informed trajectory assumptions.
The model holds under stable coconut and palm kernel oil supply conditions; deviation in biodiesel production swings or Southeast Asian logistics disruptions would shift glycerol availability and pricing assumptions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Global Dicalcium Phosphate (Feed Grade) Market
Additives
Surface Modifiers Market
Additives
Piperonyl Butoxide (PBO) Market
Additives
Organic Dispersants Market
Additives
Sodium Potassium Tartrate Market
Additives
Electrolyte Additives for Lithium Ion Battery Market
Additives
Anti-Creasing Agent Market
Additives
Plasticizer Alcohols Market
Additives
Phthalate and Non-Phthalate Plasticizers Market
Additives
Clouding Agents Market
Additives
Ultraviolet Light Stabilizer Market
Additives
Global Caprylhydroxamic Acid Market
Additives
Emulsifiers In Personal Care Market
Additives
Mycotoxin Binders Market
Additives
Tire Additives Market
Additives
Indonesia Feed Additives Market