
 FD and C Lakes Market | 2026-2036
FD and C Lakes Market Size, Share, and Industry Trends Forecast 2026-2036
FD and C Lakes Market Foresight
Consolidation among North American food manufacturers is realigning procurement volumes toward fewer, larger contracts. Sensient Colors leverages its integrated pigment production network to sustain supply security for multinational food brands. IFC Solutions anchors its position through specialized color matching services for confectionery and pharmaceutical clients. Organic Dyes and Pigments competes on custom lake formulations for mid-tier cosmetic companies seeking differentiated shade portfolios.
FD and C Lakes are water-insoluble pigment complexes formed by precipitating certified water-soluble dyes onto aluminum hydrate substrates, yielding particles with controlled particle size distributions between 5 and 30 microns for stable dispersion in oil-based matrices. These complexes serve primarily as colorants where bleeding between product phases must be eliminated, such as in coated confections, compressed tablets, and topical cosmetic preparations. The application dimension shows pharmaceutical additives commanding premium pricing due to USP-grade purity requirements and batch certification costs, while food coloring maintains volume leadership through baked goods and candy applications. Powder form dominates manufacturing throughput, though liquid suspensions are gaining formulation share in automated beverage production lines where dust control and metering precision reduce waste.
FDA color additive regulations under 21 CFR 74 and 21 CFR 82 govern batch certification, labeling, and permitted daily exposure limits for all FD and C Lakes entering interstate commerce. REACH compliance in Europe and EFSA evaluations for food contact applications create parallel compliance obligations for exporters serving multiple jurisdictions. Stakeholders must monitor evolving state-level clean-label legislation in California and New York, where pending restrictions on synthetic colorants could redirect R&D investment toward natural pigment alternatives or reformulation strategies.
Market Dynamics
Pharmaceutical manufacturers are consolidating tablet coating specifications around fewer certified pigment suppliers, compressing qualification timelines and forcing lake producers to maintain redundant FDA batch certification capabilities across multiple production sites.
Growth Catalysts
- 21 CFR 74 batch certification:FDA's mandatory certification protocol for color additives creates durable demand for compliant lake pigments in pharmaceutical and food applications where uncertified alternatives face interstate commerce prohibitions.
- Tablet coating standardization:Contract drug manufacturers are specifying FD and C Lakes for immediate-release coatings to eliminate bleeding between tablet cores and film layers during accelerated stability testing.
- Aluminum hydrate substrate engineering:Advances in precipitated substrate morphology control are extending lake particle size ranges for high-shear confectionery processing without dispersion breakdown.
Market Restraints
- Aluminum raw material concentration:Specialty aluminum hydrate supply concentrates among limited chemical processors, exposing lake manufacturers to input cost volatility and qualification delays for alternative substrate sources.
- Clean-label substitution pressure:Spirulina, beetroot, and turmeric extracts are displacing synthetic lakes in premium confectionery segments where natural positioning commands retail shelf placement advantages.
- REACH authorization complexity:ECHA's evolving requirements for aluminum-containing pigments create parallel compliance burdens for exporters serving European pharmaceutical and cosmetic formulators.
Strategic Opportunities
- Indian pharmaceutical expansion:CDSCO's alignment with ICH quality guidelines is accelerating domestic tablet manufacturing capacity, creating certified lake demand from export-oriented formulation facilities in Hyderabad and Ahmedabad.
- Automated beverage dispensing:Liquid suspension lakes are penetrating high-speed bottling lines where dust-free metering and color consistency reduce waste in carbonated and still beverage production.
- California Proposition 65 alignment:Pending state-level disclosure requirements for synthetic colorants are incentivizing reformulation services that pair lake pigments with compliant labeling strategies for national brand distribution.
Industry Challenges
- Analytical chemistry talent scarcity:Batch certification requires specialized spectrophotometric and chromatographic expertise that competes with broader pharmaceutical quality assurance hiring pools.
- Multi-jurisdiction certification timelines:Simultaneous FDA, EFSA, and Health Canada submissions for new lake variants extend product launch cycles and defer revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | FD and C Lakes Market |
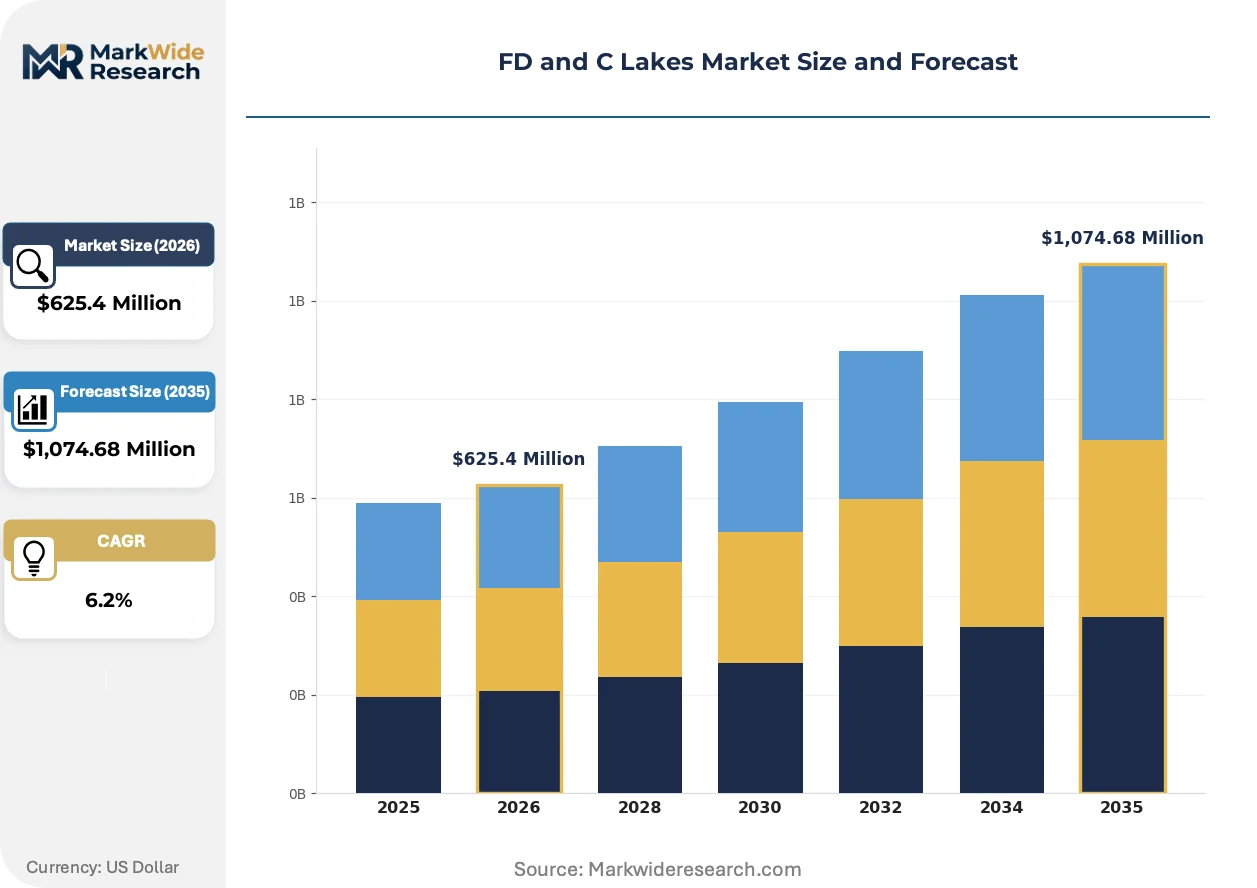
| Market Size in 2026 | $625.4 Million |
| Market Size in 2035 | $1,074.68 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: FD&C Red 40, FD&C Yellow 5, FD&C Blue 1, FD&C Green 3 Application: Food Coloring, Cosmetic Pigments, Pharmaceutical Additives, Beverage Enhancers Form: Powder, Liquid, Gel, Suspension End User: Food Manufacturers, Cosmetic Companies, Pharmaceutical Labs, Beverage Producers |
| Companies Covered | Sensient Colors, IFC Solutions, Organic Dyes and Pigments, Pylam Products Company, ADM, Dynemic Products, Standard Colors, Marcor, Koel Colours, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
FD and C Lakes Market Shifts & Advancements
Microencapsulation technologies and particle engineering are redefining dispersion stability standards across oil-based food and topical pharmaceutical matrices, compressing the performance gap between synthetic and natural colorant platforms.
Surface-modified lake pigments with tailored hydrophobicity gradients are modularizing formulation flexibility for confectionery manufacturers. Mars Wrigley and Ferrero specification teams are qualifying these grades for fat-bloom-resistant chocolate coatings. The technology is modularizing what were previously separate product lines into unified pigment platforms that span panned candy, compound coatings, and compressed tablet applications without reformulation.
EFSA's 2024 re-evaluation of aluminum-containing food additives is tightening acceptable daily intake calculations for lake pigments in children's food categories. The industrial consequence is accelerated migration toward reduced-aluminum substrate alternatives and expanded toxicological dossier preparation for existing certifications. European confectionery exporters are responding by bifurcating formulation strategies—maintaining traditional lakes for adult-targeted products while accelerating natural pigment qualification for pediatric portfolios.
Buyer concentration among North American food manufacturers is compressing supplier negotiation cycles and unbundling technical service components from base pigment pricing. Procurement teams at consolidated baking and candy conglomerates are separating color matching, regulatory documentation, and inventory management into discrete contract line items. This unbundling is most visible in Chicago and Minneapolis procurement offices where three buyers now control specifications previously distributed across fifteen regional formulators.
FD and C Lakes Market Segmentation
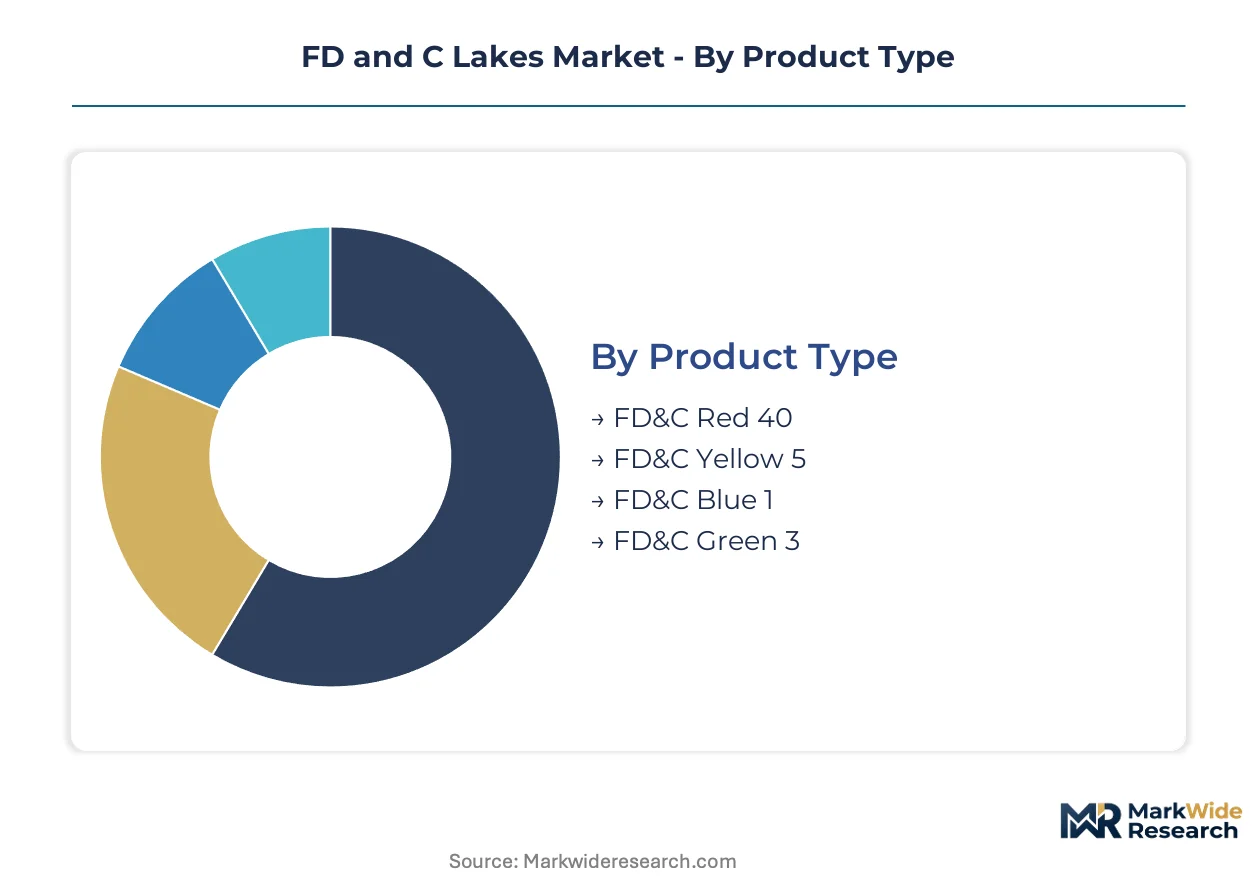
Segmentation in the FD and C Lakes Market reveals distinct performance profiles across pigment chemistry, application requirements, and physical form factors. Each dimension carries specific regulatory, technical, and procurement implications that shape supplier positioning and customer switching costs.
Product Type:
Replacement cycles in certified lake pigments accelerate when FDA batch certification protocols tighten or when substrate engineering advances enable reformulation with fewer pigment variants.
- FD&C Red 40:Aluminum lake complexes of Allura Red AC deliver heat-stable crimson shades for baked goods and compressed tablets. Confectionery manufacturers in the United States specify this pigment for panned candy coatings where bleeding resistance determines shelf appearance.
- FD&C Yellow 5:Tartrazine-derived lakes provide lemon-to-amber coloration with superior lightfastness in oil-based matrices. Pharmaceutical tablet coaters specify this grade for immediate-release formulations where dissolution profile consistency is critical.
- FD&C Blue 1:Brilliant Blue FCF lakes create stable azure tones in sugar-based confections and topical preparations. Demand concentrates in cosmetic applications where shade reproducibility across batches supports brand equity.
- FD&C Green 3:Fast Green FCF lakes blend blue and yellow dye complexes for forest and mint color variants. Beverage producers deploy this pigment in liquid suspension form for carbonated drink coloration.
FD&C Red 40 sits at the top of the volume ranking, with FD&C Blue 1 climbing the fastest as cosmetic formulators expand lake pigment portfolios.
Application:
Cost tier differentiation separates commodity colorant procurement from premium-grade pharmaceutical specifications where batch certification and USP compliance command substantial price premiums.
- Food Coloring:Baked goods and candy applications consume powder-form lakes for dry blend incorporation and fat-based dispersion. FDA 21 CFR 74 compliance remains mandatory for interstate commerce.
- Cosmetic Pigments:Topical preparations require particle size control below 10 microns for skin feel and coverage uniformity. REACH registration obligations in Europe add compliance overhead for exporters.
- Pharmaceutical Additives:USP-grade lakes for tablet coatings and capsule formulations carry the highest purity specifications and certification documentation burdens. CDSCO-aligned facilities in India are expanding qualification of these grades for export markets.
- Beverage Enhancers:Liquid suspension lakes enable dust-free metering in automated bottling lines. Carbonated and still drink producers specify these forms for color consistency and waste reduction.
Food Coloring anchors volume demand, though Pharmaceutical Additives deliver the steepest margin expansion trajectory.
Form:
Customer type preferences diverge sharply between bulk powder procurement by integrated food manufacturers and precision-metered liquid systems adopted by high-speed beverage operations.
- Powder:Standard manufacturing throughput format for dry blending and oil dispersion. Dust control equipment requirements limit adoption in smaller processing facilities.
- Liquid:Pre-dispersed pigment concentrates reduce handling losses in automated production environments. Beverage producers favor this form for closed-system metering.
- Gel:Semi-solid concentrates for specialized confectionery and cosmetic compounding. Limited adoption due to narrower compatibility with standard processing equipment.
- Suspension:Stabilized aqueous or oil-based dispersions for immediate incorporation without pre-dispersion steps. High-shear processing lines specify this form to eliminate dispersion breakdown risks.
Powder maintains volume leadership, with Suspension gaining share fastest in high-throughput processing segments.
End User:
Supply concentration among North American food manufacturers has compressed supplier lists, while pharmaceutical and cosmetic segments retain more fragmented procurement with specialized technical service requirements.
- Food Manufacturers:Consolidated baking and confectionery conglomerates drive large-contract procurement with unbundled technical services. Chicago and Minneapolis procurement offices now control specifications previously distributed across regional formulators.
- Cosmetic Companies:Mid-tier brands seek differentiated shade portfolios through custom lake formulations. Surface-modified pigment grades are qualifying for fat-bloom-resistant chocolate coatings and topical applications.
- Pharmaceutical Labs:Contract drug manufacturers standardize tablet coating specifications around fewer certified suppliers. Redundant FDA batch certification capabilities across multiple production sites are now mandatory for vendor qualification.
- Beverage Producers:High-speed bottling operations prioritize dust-free metering and color consistency. Liquid suspension lakes are penetrating this segment as automation investments reduce tolerance for powder handling variability.
Food Manufacturers represent the largest consumption base, with Pharmaceutical Labs expanding most quickly as CDSCO-aligned manufacturing capacity grows in India.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized analytical chemists and batch certification technicians cluster in regulatory-heavy jurisdictions where FDA and EFSA compliance obligations sustain premium pigment demand.
United States
Pharmaceutical tablet coating standardization and confectionery manufacturing anchor lake pigment consumption. FDA 21 CFR 74 batch certification requirements create durable entry barriers for uncertified competitors. Chicago and Minneapolis procurement offices now control specifications previously distributed across fifteen regional formulators, compressing supplier lists toward fewer certified vendors.
Germany
EFSA's 2024 aluminum-containing additive re-evaluation is tightening daily intake calculations for pediatric food categories. REACH authorization complexity for aluminum-containing pigments creates parallel compliance burdens for exporters serving European pharmaceutical formulators. The Rhine-Ruhr chemical processing corridor hosts specialized aluminum hydrate substrate engineering facilities serving lake manufacturers.
India
CDSCO-aligned pharmaceutical manufacturing capacity in Hyderabad and Ahmedabad is expanding qualification of USP-grade lakes for export markets. The country's national pharmaceutical regulator alignment with ICH quality guidelines accelerates domestic tablet manufacturing capacity. Contract drug manufacturers in these clusters specify certified lakes for immediate-release coatings to eliminate bleeding during stability testing.
Japan
Cosmetic formulators demanding particle size control below 10 microns for skin feel uniformity drive premium lake specifications. METI oversight of chemical substances creates additional registration obligations for aluminum-containing pigments in topical preparations. The Kanto region around Tokyo concentrates formulation R&D for surface-modified pigment grades qualifying for fat-bloom-resistant applications.
Brazil
ANVISA pharmaceutical registration requirements for imported color additives sustain demand for pre-certified lake complexes in generic drug manufacturing. Beverage producers in São Paulo state specify liquid suspension lakes for dust-free metering in automated bottling lines. The Southeast industrial corridor is seeing accelerated natural pigment qualification for pediatric portfolios alongside traditional lake maintenance for adult-targeted products.
FD and C Lakes Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the certification-intensive pigment landscape. The vendor base spans integrated chemical processors maintaining redundant FDA batch certification capabilities alongside specialized color matching service providers. Three archetypes dominate: substrate-engineering specialists controlling aluminum hydrate morphology, regulatory documentation aggregators unbundling technical services from base pigment pricing, and formulation consultants bridging clean-label reformulation pressures with synthetic pigment performance. Consolidation among North American food manufacturers is compressing supplier negotiation cycles, while pharmaceutical qualification timelines force redundant certification investments across multiple production sites.
Within the integrated production tier, Sensient Colors leverages its captive pigment manufacturing network to sustain supply security for multinational food brands. IFC Solutions anchors market position through specialized color matching services for confectionery and pharmaceutical clients. Organic Dyes and Pigments occupies a position serving mid-tier cosmetic companies seeking differentiated shade portfolios through custom lake formulations. These three entities exemplify how regulatory compliance capabilities and technical service bundling separate sustainable competitors from commodity pigment traders.
| Leading Market Players |
|---|
| Sensient Colors |
| IFC Solutions |
| Organic Dyes and Pigments |
| Pylam Products Company |
| ADM |
| Dynemic Products |
| Standard Colors |
| Marcor |
| Koel Colours |
| Others |
Supply & Pricing Matrix
Captive aluminum hydrate production in the United States and Germany anchors both supply security and pricing power for certified lake pigment manufacturers, creating tiered cost structures that separate FDA-batch-certified suppliers from uncertified traders. This integration choice insulates incumbent producers from raw material volatility while forcing qualification investments that compress margins for mid-tier competitors serving price-sensitive confectionery segments.
Pricing Analysis
Capacity additions in India are reshaping price floors for standard-grade lake pigments as CDSCO-aligned pharmaceutical facilities expand USP-grade qualification. Three-tier pricing structure across pharmaceutical-certified, food-grade, and cosmetic-standard levels separates premium batch documentation from commodity pigment offerings. Cost compression in food-grade powders intensifies because consolidated North American buyers unbundle technical services from base pigment contracts. Pharmaceutical labs exhibit the lowest price sensitivity due to qualification timelines and regulatory switching costs, while mid-tier cosmetic companies drive hardest bargain negotiations.
Supply Chain Analysis
Specialized analytical chemists cluster in the United States, Germany, and India where FDA and CDSCO compliance obligations sustain premium workforce premiums. Aluminum hydrate substrate engineering draws from Rhine-Ruhr chemical processors and domestic US specialty chemical manufacturers, with limited alternative qualification sources creating single-source vulnerability for lake precipitation inputs. Tariff exposure on aluminum-containing pigments shipped to Europe compounds cost uncertainty under evolving REACH authorization requirements. Distribution runs through certified pigment distributors maintaining redundant batch certification documentation for pharmaceutical and food manufacturing clients.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in FD and C Lakes rests on pharmaceutical certification premiums widening against food-grade commoditization, with aluminum substrate engineering investments unlocking cost-down trajectories in high-purity production.
For Market Incumbents: Anchor market position through redundant FDA batch certification capabilities across multiple production sites, defending against contract drug manufacturer consolidation that compresses qualified supplier lists. Deepen captive aluminum hydrate substrate engineering to control morphology precision for high-shear confectionery applications, neutralizing clean-label substitution pressure from spirulina and beetroot extracts in premium segments. For New Entrants and Emerging Players: CDSCO alignment with ICH quality guidelines in India opens a window for USP-grade lake qualification serving export-oriented pharmaceutical facilities in Hyderabad and Ahmedabad. Target liquid suspension lake formulation for automated beverage bottling lines where dust-free metering specifications remain underpenetrated by incumbent powder specialists. Enter through specialized color matching services unbundled from base pigment supply, mirroring IFC Solutions' service-led positioning. For Investors and Strategic Acquirers: Consolidation pressure builds where buyer concentration among North American food manufacturers compresses supplier lists toward fewer certified vendors with redundant regulatory capabilities. Five-to-ten-year viability favors substrate-engineering specialists controlling aluminum hydrate morphology and regulatory documentation aggregators serving multinational compliance requirements. Watch EFSA aluminum additive re-evaluation outcomes as inflection indicator for European formulation strategy bifurcation between traditional lakes and natural pigment alternatives.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Hydrate Substrate Engineering | Rhine-Ruhr and US Gulf Coast captive supply secures morphology control for high-shear confectionery grades. |
| FDA Batch Certification Capacity Expansion | Redundant site qualification meets contract drug manufacturer consolidation around fewer certified pigment suppliers. |
| Liquid Suspension Lake Formulation Development | Dust-free metering specifications penetrate automated beverage bottling lines in São Paulo and Chicago manufacturing clusters. |
| Clean-Label Reformulation Service Launch | California Proposition 65 alignment pairs synthetic lake performance with compliant labeling for national brand distribution. |
| CDSCO-Aligned USP-Grade Qualification Investment | Hyderabad and Ahmedabad pharmaceutical manufacturing expansion creates certified lake demand from export-oriented formulation facilities. |
Research Methodology
Multiple input streams — primary interviews with pharmaceutical quality assurance directors, food manufacturer procurement leads, and cosmetic formulation chemists; secondary validation through FDA 21 CFR 74 batch certification records, EFSA additive safety evaluations, and CDSCO pharmaceutical manufacturing registrations; customs trade data and specialty chemical distributor channel assessments — were reconciled through bottom-up demand modeling and top-down market sizing triangulation.
Data-stream reconciliation across pigment chemistry type, application requirement tier, physical form factor, and end-user procurement concentration shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level volume and value trajectories modeled against pharmaceutical tablet coating standardization trends, beverage automation adoption curves, and regional regulatory alignment timelines including EFSA aluminum additive re-evaluation impacts.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated clean-label substitution in pediatric food categories or prolonged REACH authorization complexity for aluminum-containing pigments. Forecasts reflect assumptions regarding CDSCO-ICH guideline implementation pace and consolidated North American food manufacturer procurement behavior. Material deviation in FDA batch certification protocol tightening or EFSA daily intake calculation revisions warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Competitive Inhibitors Market
Additives
Defoaming Coating Additives Market
Additives
Sorbitan Laurate Market
Additives
Iso-Butyric Acid Market
Additives
Refinery Fuel Additives Market
Additives
Monocalcium Phosphate Market
Additives
Cassia Gum Market
Additives
Crosslinking Agents Market
Additives
Anti-Wear Additives Market
Additives
Glyceryl Caprylate Market
Additives
South America Concrete Admixtures Market
Additives
Global Synthetic Tackifier Market
Additives
Anti-Pollution Ingredients Market
Additives
Middle East Feed Additives Market
Additives
PVC Plasticizers and Stabilizers Market
Additives
Low VOC Coating Additives Market